
 Liquid Dispensing Pump Market | 2026-2036
Liquid Dispensing Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Dispensing Pump Market Intelligence
REACH is rebalancing material sourcing costs for European pump manufacturers, forcing substitution of legacy seal compounds. AptarGroup leverages its polymer science capabilities to develop compliant elastomer formulations ahead of enforcement timelines. Silgan Dispensing anchors North American supply through captive injection molding and automated assembly lines. Graco competes in industrial fluid handling with high-pressure piston architectures for chemical transfer.
A liquid dispensing pump is a positive-displacement device engineered to meter controlled volumes of fluid through mechanical, pneumatic, or electric actuation, typically achieving accuracy within one percent of target volume. These systems serve pharmaceutical aseptic filling, food-grade ingredient dosing, and corrosive chemical transfer where contamination or spillage carries significant cost or safety consequences. Peristaltic pumps dominate biopharmaceutical applications because their fluid-path isolation eliminates cross-batch contamination risk and simplifies validation protocols. Diaphragm pumps sustain strong positions in chemical processing where aggressive media degrade other architectures. Digital dispensing technology captures expanding margin pools as manufacturers integrate servo-driven flow control with real-time viscosity compensation.
FDA cGMP guidelines and EU MDR conformity requirements shape product development cycles, mandating traceable materials and validated cleaning procedures for pumps contacting sterile drug products. EPA and OSHA frameworks in the United States impose emissions and worker-exposure limits that drive demand for sealed pumping systems in chemical handling. Stakeholders must monitor evolving pharmaceutical serialization rules and emerging per- and polyfluoroalkyl substance restrictions, as both threaten incumbent seal technologies and create openings for fluoropolymer-free alternatives.
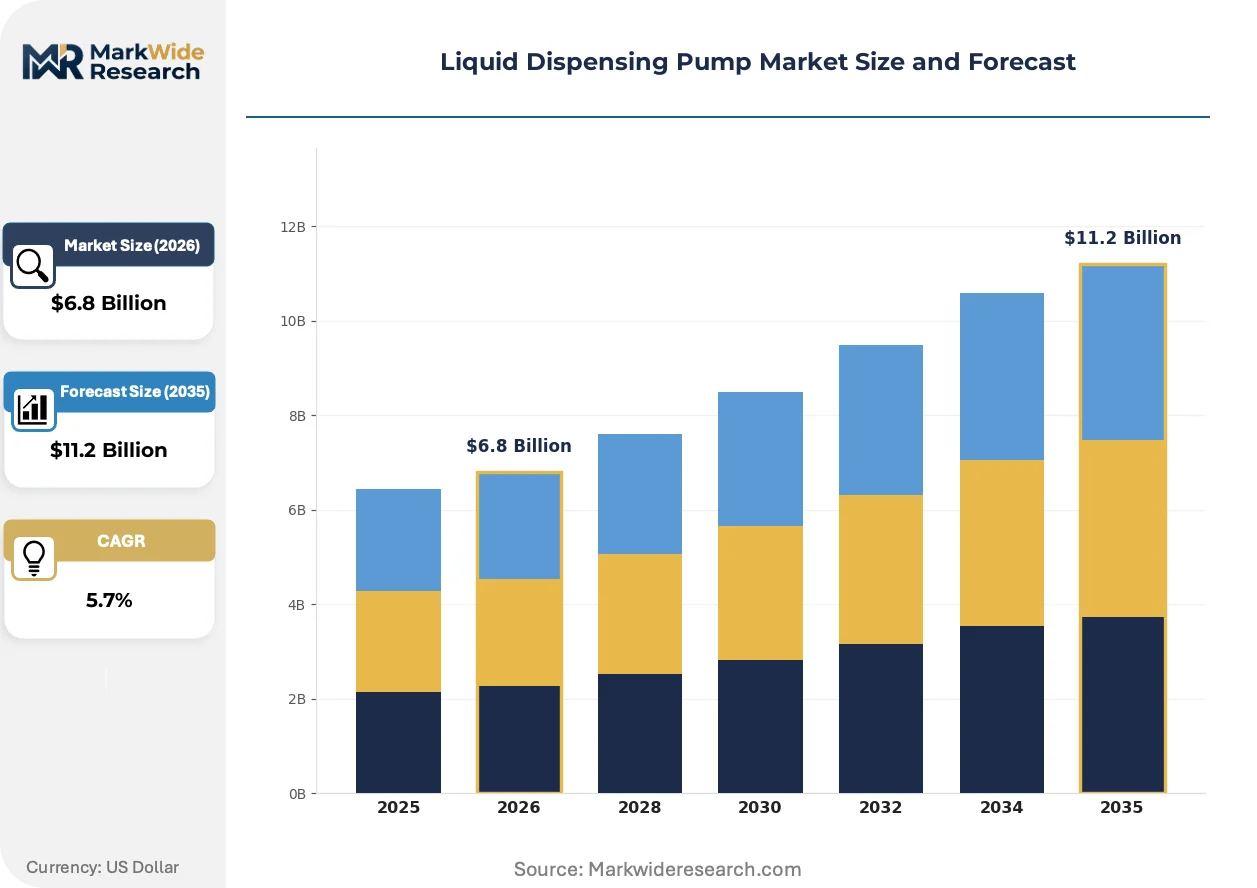
Market Dynamics
Cleanroom-grade dispensing requirements are compressing product development cycles as pharmaceutical manufacturers demand validated systems with traceable material provenance for aseptic filling operations.
Growth Catalysts
- EU MDR compliance mandates:European medical device regulations tighten material specifications for pump housings contacting sterile drug products, creating replacement demand for legacy equipment.
- Biopharmaceutical fluid-path isolation:Peristaltic pump architectures eliminate cross-batch contamination risk in vaccine production, accelerating adoption across fill-finish operations.
- Stuttgart precision engineering cluster:German manufacturers supply high-accuracy filling equipment to global vaccine producers, concentrating technical expertise and component sourcing.
Market Restraints
- Fluoropolymer seal dependency:Incumbent elastomer technologies face substitution pressure as per- and polyfluoroalkyl substance restrictions tighten, forcing costly formulation redevelopment.
- Specialized polymer supply concentration:Medical-grade thermoplastics and compliant elastomers source from limited European and North American compounders, creating input bottlenecks.
- Validation protocol rigidity:FDA cGMP guidelines mandate extensive documentation and cleaning verification, extending qualification timelines for new pump installations.
Strategic Opportunities
- Fluoropolymer-free seal development:Advanced polymer science capabilities enable compliant elastomer formulations ahead of enforcement timelines, capturing premium positioning.
- Digital viscosity compensation integration:Servo-driven flow control converges with real-time fluid property sensing, opening high-margin precision dosing segments.
- Automated assembly scale-up:Captive injection molding and robotic production lines reduce unit costs while tightening quality consistency for high-volume pharmaceutical contracts.
Industry Challenges
- Cleanroom technician scarcity:Qualified personnel for aseptic pump validation and maintenance command premium wages, constraining service expansion.
- Multi-jurisdictional certification burden:Simultaneous FDA, EMA, and national regulator approvals fragment engineering resources and delay market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Dispensing Pump Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Peristaltic Pumps, Diaphragm Pumps, Gear Pumps, Piston Pumps Application: Chemical Processing, Food and Beverage, Pharmaceuticals, Automotive End User: Manufacturing, Healthcare, Agriculture, Laboratories Technology: Electric Pumping, Pneumatic Pumping, Mechanical Pumping, Digital Dispensing |
| Companies Covered | Silgan Dispensing, AptarGroup, Albea, Rieke Packaging Systems, Berry Global, Guala Dispensing, Frapak Packaging, Mitani Valve, Graco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Dispensing Pump Market Strategic Shifts & Innovations
Digital actuation architectures are displacing pneumatic systems across precision dosing applications, while regulatory material restrictions force concurrent redesign of fluid-contact components.
Servo-driven piston pumps with real-time viscosity compensation is overtaking legacy pneumatic architectures in pharmaceutical filling lines. Biologics manufacturers adopt these systems for high-value protein formulations requiring sub-one-percent dosing accuracy. The shift is compressing maintenance intervals and enabling continuous process verification that pneumatic systems cannot support.
REACH substance restrictions are redefining seal material specifications across European pharmaceutical equipment supply chains. ECHA enforcement timelines force substitution of legacy fluoroelastomers in pump housings contacting sterile products. German and Swiss pump manufacturers accelerate polymer science investment to maintain equipment qualification status.
Consolidated procurement by contract manufacturing organizations concentrates purchasing power among fewer buyers. Large fill-finish service providers negotiate multi-year equipment supply agreements that bundle pumps, validation support, and spare parts. This pattern is most pronounced in Ireland and Singapore, where pharmaceutical manufacturing clusters concentrate demand.
Liquid Dispensing Pump Market Segmentation
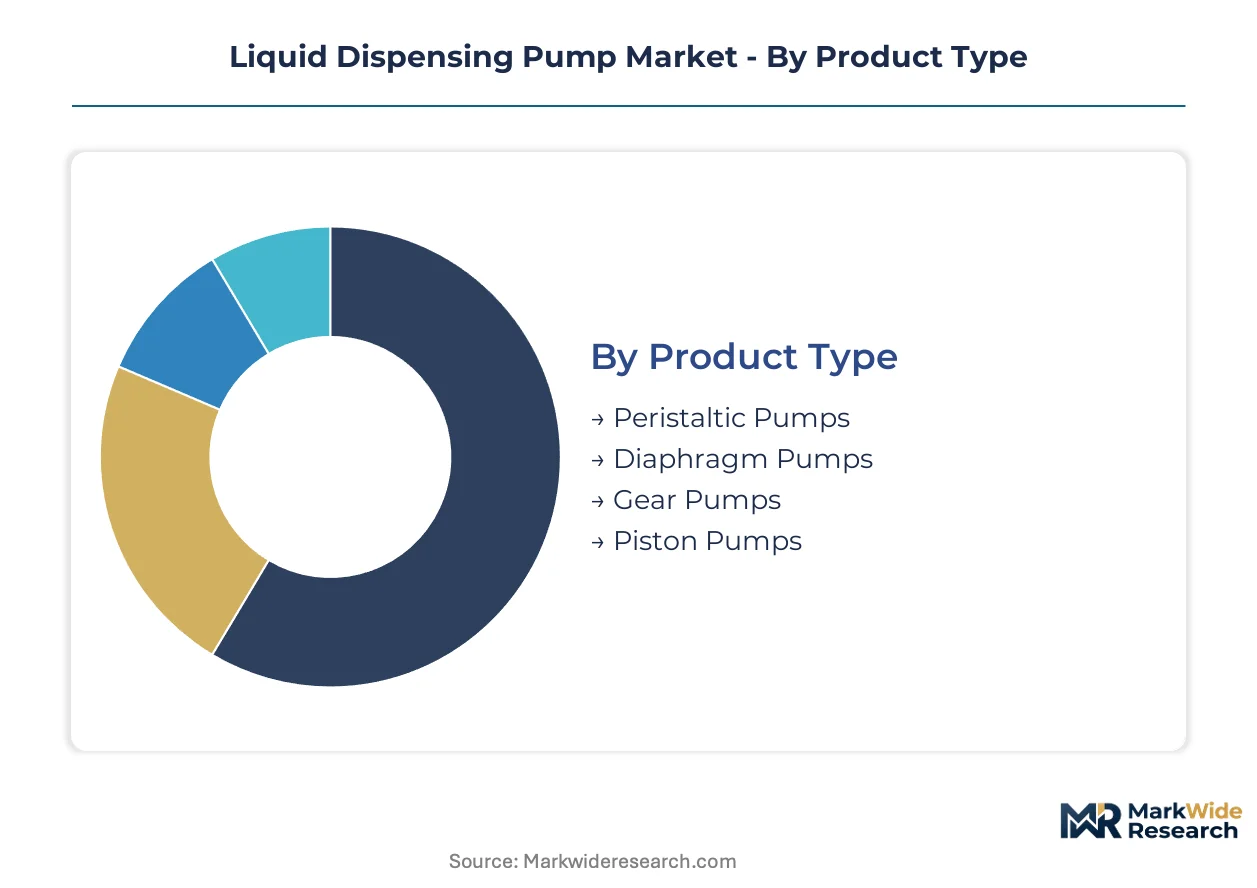
Different pump architectures command radically different capital commitments, from simple mechanical designs to servo-driven digital systems with real-time sensing. Application requirements for sterile biopharmaceutical filling versus corrosive chemical transfer create divergent specification tiers. End-user sophistication ranges from automated manufacturing lines to manual laboratory benches, fragmenting pricing power across the value chain.
Product Type:
Capital intensity varies sharply across architectures, with precision servo-driven systems requiring substantially higher upfront investment than pneumatic or mechanical alternatives.
- Peristaltic Pumps:Fluid-path isolation eliminates cross-batch contamination through disposable tubing sets, making validation protocols straightforward for vaccine fill-finish operations. Biopharmaceutical manufacturers in Germany and Switzerland concentrate demand here as sterile single-use systems become standard for biologics production.
- Piston Pumps:Servo-driven architectures with real-time viscosity compensation achieve sub-one-percent dosing accuracy for high-value protein formulations. Pharmaceutical contract manufacturers in Ireland and Singapore are displacing legacy pneumatic systems with these digital platforms for continuous process verification.
- Diaphragm Pumps:Seal-less designs handle aggressive chemical media in process industries where fluoropolymer restrictions complicate elastomer selection.
- Gear Pumps:Positive-displacement metering suits high-viscosity food-grade ingredients with straightforward cleaning requirements.
Peristaltic pumps absorb the bulk of installed capacity in sterile applications; piston pumps are expanding most quickly through digital upgrade cycles.
Application:
Regulatory burden intensity separates segments, with pharmaceutical and food-grade applications demanding traceable materials and validated cleaning procedures that chemical processing largely avoids.
- Pharmaceuticals:FDA cGMP and EU MDR compliance mandates traceable material provenance for all fluid-contact surfaces, extending qualification timelines. Aseptic filling operations in Germany's Stuttgart precision engineering cluster drive specification intensity for cleanroom-grade systems.
- Chemical Processing:EPA emissions limits and OSHA worker-exposure thresholds favor sealed pumping architectures for hazardous media transfer. REACH substance restrictions are forcing substitution of legacy fluoroelastomer seals in European chemical plants.
- Food and Beverage:FSSAI and EFSA frameworks govern ingredient dosing accuracy and cleanability for consumable products.
- Automotive:Precision lubricant and adhesive dispensing supports electric vehicle battery assembly and powertrain manufacturing.
Pharmaceutical applications command premium positioning through regulatory complexity; chemical processing offers the steepest expansion trajectory as environmental enforcement tightens.
End User:
Procurement sophistication diverges between capital-intensive automated manufacturing and smaller-scale laboratory or agricultural deployments.
- Manufacturing:Automated assembly lines and captive injection molding operations in North America consolidate purchasing power through multi-year equipment supply agreements bundling pumps, validation support, and spare parts.
- Healthcare:Hospital pharmacies and compounding facilities require compact, validated systems for patient-specific medication preparation with stringent contamination controls.
- Laboratories:Research institutions and analytical facilities prioritize flexibility and ease of protocol changeover over maximum throughput.
- Agriculture:Precision crop treatment applications demand corrosion resistance for fertilizer and pesticide handling in field conditions.
Manufacturing captures the dominant share of equipment revenue; healthcare is gaining share fastest through personalized medicine compounding requirements.
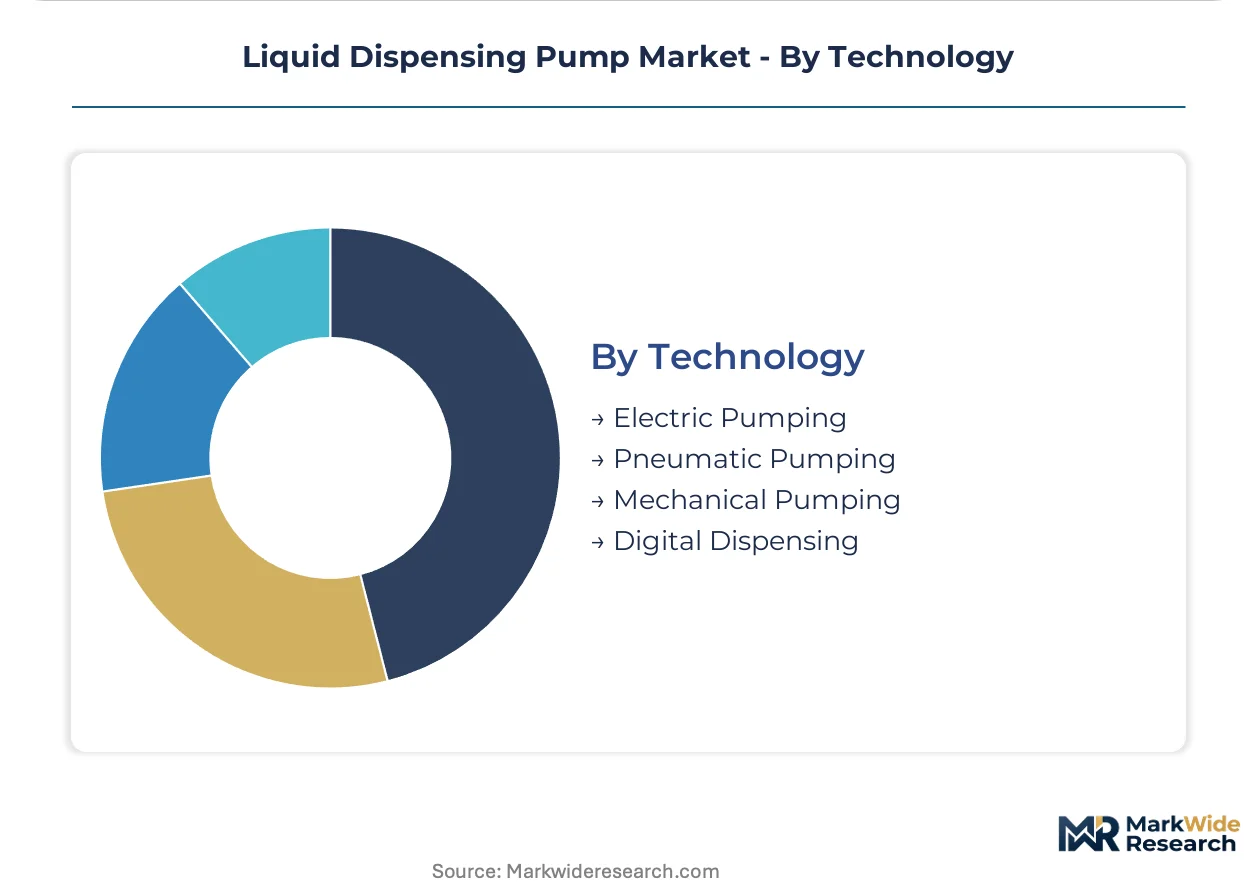
Technology:
Actuation mechanism determines both initial system cost and ongoing operational control capabilities, with digital platforms requiring substantial software and sensor integration investment.
- Digital Dispensing:Servo-driven flow control with real-time viscosity compensation converges precision mechanics with predictive analytics, opening high-margin segments in biologics manufacturing. These systems compress maintenance intervals while enabling continuous verification that pneumatic architectures cannot support.
- Electric Pumping:Brushless DC motor architectures deliver consistent torque profiles for repeatable dosing across varying line pressures.
- Pneumatic Pumping:Compressed air actuation remains cost-effective for simple transfer applications where precision requirements are modest.
- Mechanical Pumping:Hand-operated or spring-driven designs serve low-throughput laboratory and field applications with minimal infrastructure requirements.
Digital dispensing commands the highest capital commitment per installation; electric pumping maintains the broadest installed base across industrial applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Ireland and Singapore concentrate pharmaceutical fill-finish capacity, attracting pump suppliers through tax-efficient manufacturing structures and streamlined regulatory pathways.
Germany
Stuttgart's precision engineering cluster supplies high-accuracy filling equipment to global vaccine producers, with Baden-Württemberg housing specialized suppliers for aseptic pump systems. EU MDR compliance mandates tighten material specifications for pump housings contacting sterile drug products, forcing equipment upgrades across domestic manufacturers. Munich anchors polymer science investment as REACH substance restrictions accelerate fluoropolymer-free seal development.
United States
Contract manufacturing organizations in the Boston-Cambridge corridor consolidate purchasing power through multi-year equipment agreements bundling pumps and validation support. FDA cGMP guidelines mandate traceable materials and documented cleaning verification, extending qualification timelines for new installations. The Pacific Northwest hosts specialized cleanroom equipment fabricators serving biologics manufacturers.
Switzerland
Swissmedic oversight drives specification intensity for sterile drug product contact surfaces, with Basel-area pharmaceutical clusters demanding validated single-use pump systems. The country's medical device regulations align with EU MDR frameworks while maintaining distinct enforcement timelines. Zurich and Geneva concentrate precision mechanics suppliers for high-accuracy dosing equipment.
Ireland
Pharmaceutical manufacturing clusters in Cork and Dublin attract global fill-finish service providers, consolidating demand for cleanroom-grade dispensing systems. The country's corporate tax structure incentivizes capital-intensive automated assembly line investments. Irish contract manufacturers negotiate bundled supply agreements covering pumps, spare parts, and regulatory documentation support.
Singapore
Tuas Biomedical Park and surrounding pharmaceutical zones concentrate biologics manufacturing capacity, driving demand for peristaltic and piston pump architectures with fluid-path isolation. The Economic Development Board's investment incentives support high-value precision equipment sourcing. Local precision engineering capabilities expand to serve regional vaccine production requirements.
Liquid Dispensing Pump Market Key Industry Players
German producers anchor the precision-engineering tier; North American specialists hold positions in high-volume automated assembly systems. The vendor base separates into three distinct strata: integrated packaging conglomerates with captive pump manufacturing, standalone dispensing equipment specialists, and industrial fluid handling diversifiers. Consolidation pressure intensifies as pharmaceutical contract manufacturers concentrate procurement among fewer qualified suppliers. Capacity expansion and fluoropolymer-free material development represent the dominant competitive vectors.
Within the integrated packaging tier, Silgan Dispensing exemplifies North American scale advantages through captive injection molding capabilities. AptarGroup occupies a position emphasizing polymer science specialization for compliant elastomer formulations ahead of enforcement timelines. Graco represents the industrial fluid handling archetype, competing in chemical transfer applications with high-pressure architectures distinct from pharmaceutical-grade systems.
| Leading Market Players |
|---|
| Silgan Dispensing |
| AptarGroup |
| Albea |
| Rieke Packaging Systems |
| Berry Global |
| Guala Dispensing |
| Frapak Packaging |
| Mitani Valve |
| Graco |
| Others |
Cost & Logistics Intelligence
REACH substance restrictions gate qualified supply for European pharmaceutical pump manufacturers while simultaneously compressing premium-tier pricing access for compliant elastomer formulations. Buyers without validated material provenance face extended qualification timelines that translate into substantial cost premiums for cleanroom-grade systems.
Pricing Analysis
Short lead-time availability commands steep premiums as pharmaceutical contract manufacturers in Ireland and Singapore negotiate bundled multi-year agreements covering pumps, spare parts, and validation support. Pricing stratifies across FDA-validated premium tiers, standard CE-marked equipment, and economy-grade industrial transfer pumps. Cost compression in the standard tier intensifies as consolidated procurement by large fill-finish service providers concentrates purchasing power. Small-scale laboratory end users exhibit highest price sensitivity, while automated manufacturing lines prioritize qualification speed over unit cost.
Supply Chain Analysis
Returns and refurbishment flows remain underdeveloped for precision dispensing equipment, with German and Swiss manufacturers beginning pilot remanufacturing programs for servo-driven piston architectures. Component sourcing concentrates in Germany, Switzerland, and the United States, drawing from specialized polymer compounders for medical-grade thermoplastics and compliant elastomers. Supply chain risk hinges on single-source vulnerability for fluoropolymer-free seal formulations as ECHA enforcement timelines accelerate. Distribution runs through direct OEM relationships with pharmaceutical contract manufacturers, supplemented by specialized cleanroom equipment distributors serving smaller healthcare and laboratory accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The liquid dispensing pump market is becoming a vertical-integration race as players pursue captive polymer science capabilities to secure compliant elastomer supply ahead of regulatory enforcement.
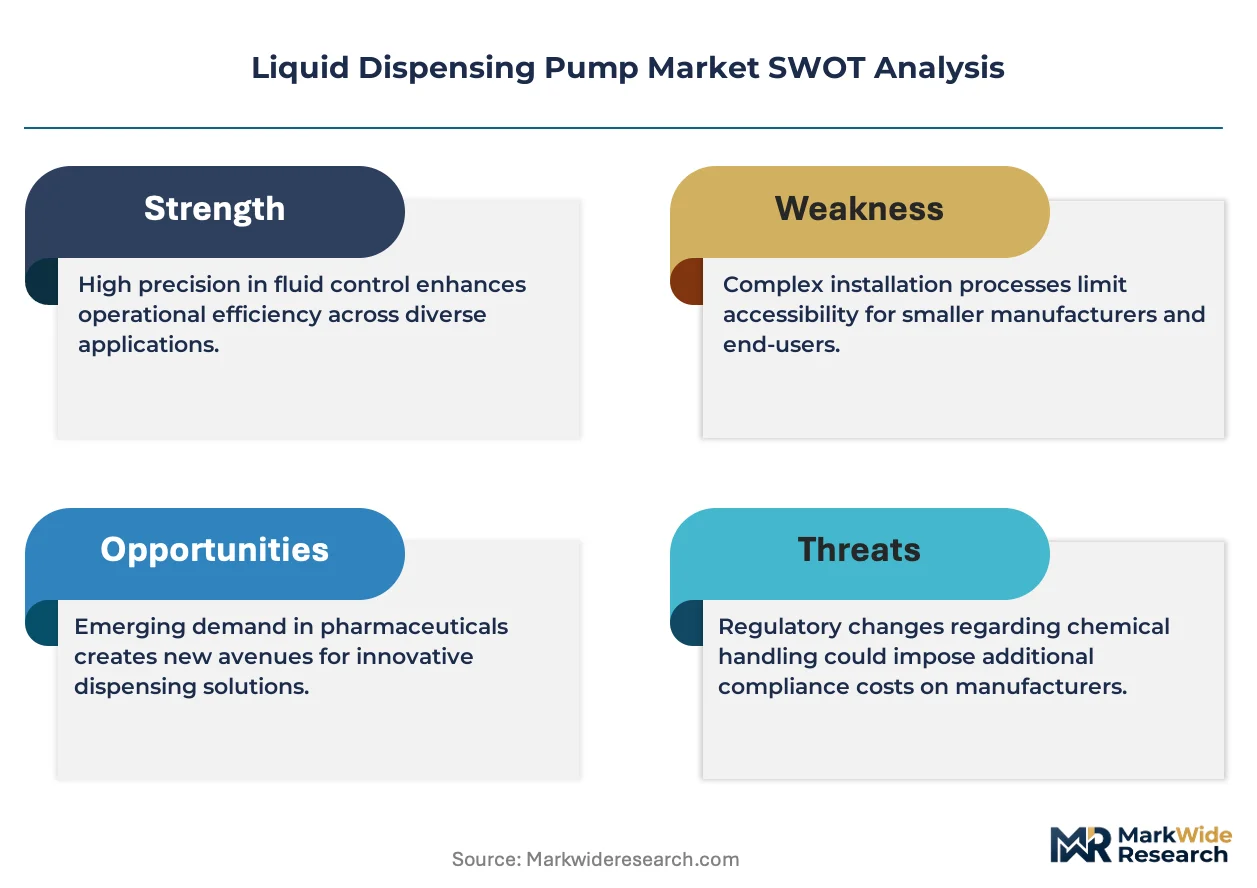
For Market Incumbents: Cement polymer science leadership through accelerated fluoropolymer-free formulation development ahead of REACH enforcement timelines. Acquire specialized cleanroom equipment fabricators in the Pacific Northwest to anchor biologics service capabilities. Threat substitution from digital viscosity compensation platforms demands continuous R&D investment to maintain specification intensity for high-value protein formulations. For New Entrants and Emerging Players: The mid-tier pricing gap between premium servo-driven systems and economy pneumatic architectures offers white-space entry for digitally-enabled electric pumping platforms. Target laboratory and small-scale pharmaceutical compounding facilities in healthcare settings where flexibility requirements outweigh maximum throughput specifications. Go-to-market leverage rests on modular validation protocols that compress installation timelines relative to incumbent documentation burdens. For Investors and Strategic Acquirers: First-mover fluoropolymer-free seal certifications are the leading indicator that material science capabilities will separate viable acquisition targets from stranded asset risks. Long-term viability favors vertically integrated specialists with captive injection molding and automated assembly lines serving pharmaceutical manufacturing clusters. Monitor ECHA substance restriction enforcement timelines as the primary inflection signal for replacement demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Fluoropolymer-Free Seal Development | REACH compliance ahead of ECHA timelines captures premium positioning in European pharmaceutical supply chains. |
| Automated Assembly Scale-Up | Captive robotic production lines reduce unit costs while tightening quality consistency for high-volume contracts. |
| Digital Viscosity Compensation Integration | Servo-driven flow control with real-time sensing opens high-margin precision dosing in biologics manufacturing. |
| Cleanroom Equipment Fabricator Acquisition | Pacific Northwest specialists anchor biologics service capabilities for Boston-Cambridge corridor demand. |
| Multi-Jurisdictional Certification Investment | Simultaneous FDA and EMA pathway preparation reduces fragmented engineering resource allocation delays. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and regulatory affairs leads at pharmaceutical equipment manufacturers. Bottom-up triangulation combined equipment shipment data with top-down validation against EMA submission records and FDA cGMP inspection databases. SEC 10-K disclosures from integrated packaging conglomerates and specialized dispensing equipment specialists provided financial calibration points.
Data-stream reconciliation across unit shipment volumes, average selling price trajectories, and installed base replacement cycles shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include pump architecture type, actuation technology tier, application regulatory intensity, and end-user procurement sophistication. CAGRs were derived from elasticity-adjusted demand curves incorporating pharmaceutical manufacturing capacity expansion schedules and REACH compliance-driven replacement cycles.
Inputs from ECHA substance restriction timelines and FDA inspection databases were available through the study window; gaps in real-time pharmaceutical contract manufacturer capital expenditure disclosures introduce uncertainty bands around equipment demand timing. Practitioners should monitor ECHA enforcement acceleration and pharmaceutical serialization rule evolution for early signals of replacement demand inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Latin America Positive Displacement Pumps Market
Pumps and Control Devices
Twin Screw Pumps Market
Pumps and Control Devices
Screw Pumps Market
Pumps and Control Devices
Package Pumping Station Market
Pumps and Control Devices
Electric Oil Pump Market
Pumps and Control Devices
Cooling Pump Market
Pumps and Control Devices
Global High Pressure Pumps Market
Pumps and Control Devices
Vacuum Pump Stations Market
Pumps and Control Devices
Liquid Ring Vacuum Pump Market
Pumps and Control Devices
Hydraulic Dosing Pump Market
Pumps and Control Devices
Electrostatic Spraying System Market
Pumps and Control Devices
Melt & Gear Pump Market
Pumps and Control Devices
Food and Beverages Industry Pumps Market
Pumps and Control Devices
Air-Operated Double Diaphragm (AODD) Pumps Market
Pumps and Control Devices
Centrifugal Water Pump Market
Pumps and Control Devices
Vertical Immersion Pumps Market