
 Poland Wind Energy Market | 2026-2036
Poland Wind Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Poland Wind Energy Market Analytics
Steel-reinforced concrete foundations in monopile structures is repositioning offshore installation economics toward deeper-water projects. Polenergia leverages its Baltic Sea lease portfolio to anchor early-mover advantage in Polish waters. RWE sustains competitive pressure through integrated development capabilities spanning turbine supply to grid connection. Vestas Wind Systems differentiates via turbine scaling optimized for Baltic wind regimes and Polish grid codes.
Poland wind energy encompasses electricity generation infrastructure converting kinetic wind resource into grid-delivered power through rotating blade assemblies driving synchronous or asynchronous generators, with typical onshore turbines now exceeding 150-meter rotor diameters and 4-6 MW nameplate capacity. The primary commercial purpose centers on bulk power supply to national transmission networks under renewable purchase obligation frameworks. Onshore turbines dominate installed capacity while offshore turbines command premium development attention due to higher capacity factors and Baltic Sea lease availability. Horizontal axis wind turbines lead technology deployment against vertical axis alternatives limited to niche micro-generation applications.
The Polish Energy Regulatory Office administers auction mechanisms and grid connection queues that directly determine project viability timelines. EU Green Deal national binding targets and ECHA offshore environmental assessment requirements shape permitting scope and marine habitat mitigation obligations. The Energy Regulatory Office also enforces distribution system operator technical codes specifying fault-ride-through and reactive power capabilities. Stakeholders must monitor auction price floor adjustments and cross-border transmission capacity expansions linking Poland to Nordic and German balancing markets.
Market Dynamics
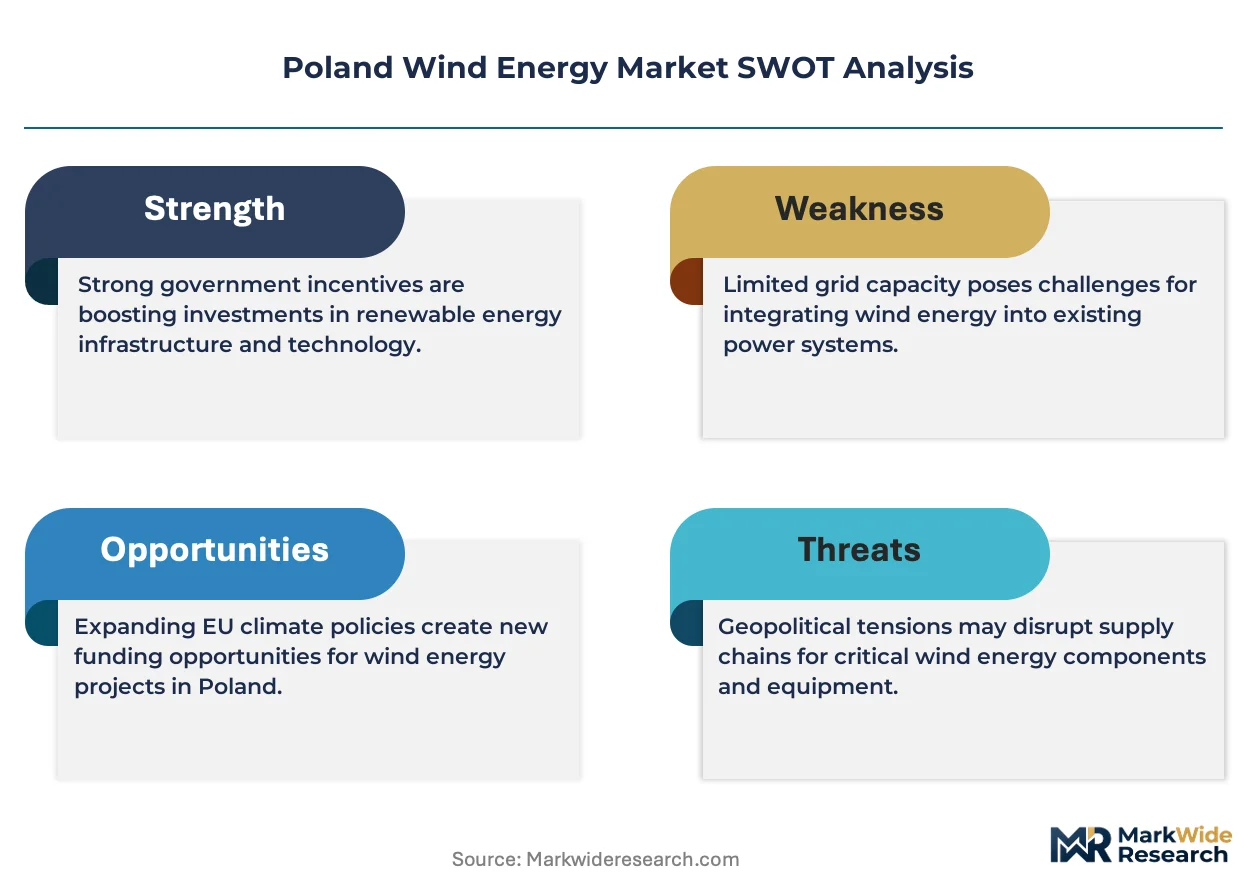
The Polish Energy Regulatory Office's auction mechanism reforms and Baltic Sea lease allocation rules are compressing project development timelines while redistributing capital toward offshore installations. This regulatory recalibration is forcing developers to pre-position grid connection applications and environmental permits in parallel rather than sequence.
Growth Catalysts
- EU Green Deal binding targets:Poland's renewable energy obligation under the EU Green Deal mandates specific capacity additions that utilities must contract through competitive auctions.
- Steel-reinforced concrete monopiles:Foundation engineering advances enable economically viable installations in deeper Baltic waters previously excluded from development.
- Baltic Sea corridor concentration:Lease availability in Polish maritime zones attracts capital from Nordic and German developers seeking capacity expansion.
Market Restraints
- Grid connection queue congestion:Polish transmission system operator interconnection timelines extend 18-24 months beyond turbine delivery schedules.
- Specialized vessel scarcity:Heavy-lift jack-up vessels for monopile installation concentrate among North Sea operators, creating Baltic Sea deployment bottlenecks.
- ECHA marine habitat assessments:Offshore environmental permitting requires seasonal survey windows that compress construction schedules.
Strategic Opportunities
- Pomeranian Voivodeship onshore expansion:Northern Polish regions with established grid infrastructure and land availability offer brownfield repowering potential.
- Hybrid offshore-wind-to-hydrogen:Electrolyzer co-location at Baltic Sea substations creates offtake certainty for merchant power exposure.
- Cross-border Nordic balancing:Planned transmission links to Sweden and Denmark enable capacity factor optimization through geographic diversification.
Industry Challenges
- Marine construction specialist shortage:Polish labor pools lack certified offshore installation crews for foundation and cable laying operations.
- CE marking and grid code compliance:Turbine certification against Polish Energy Regulatory Office technical specifications requires 12-18 month validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poland Wind Energy Market |
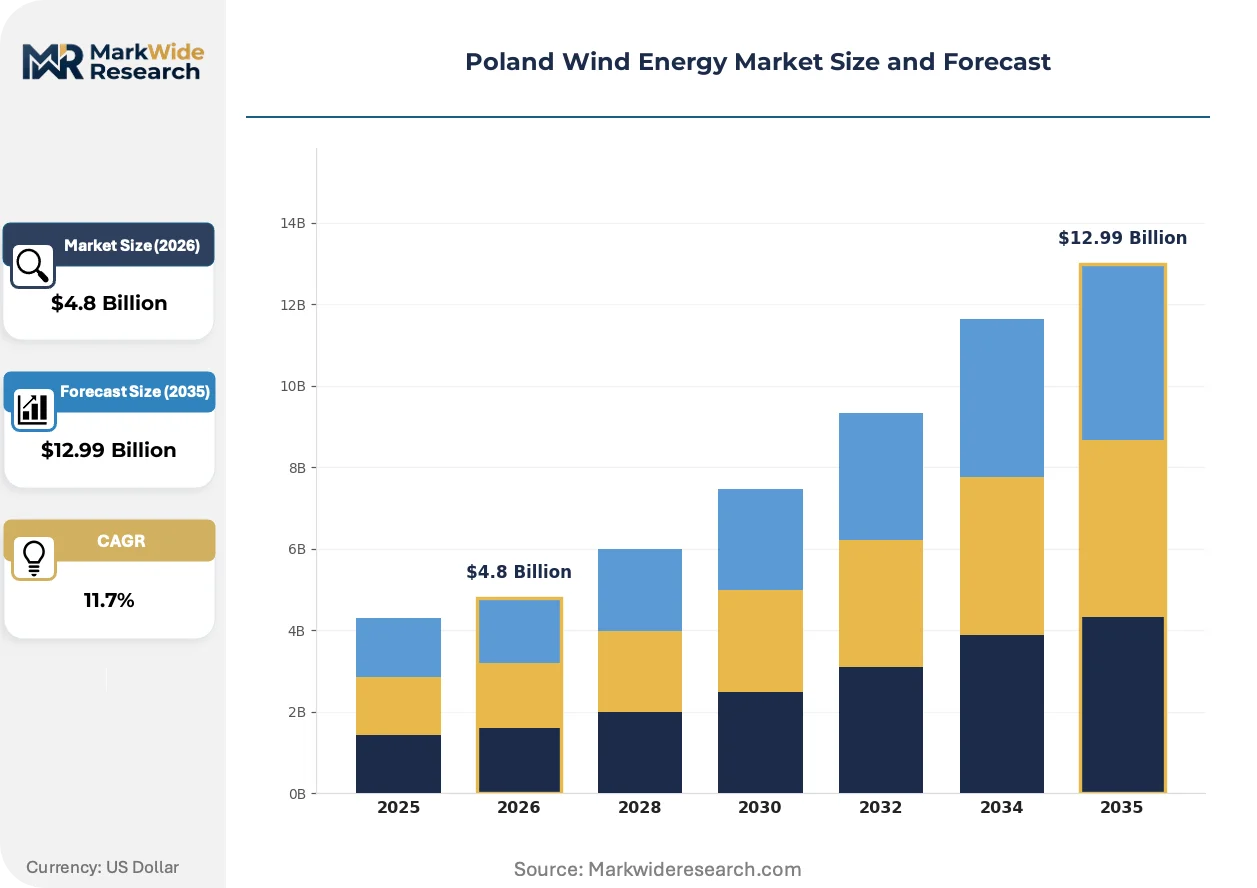
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Onshore Turbines, Offshore Turbines, Hybrid Systems, Small Scale Units Technology: Horizontal Axis Wind Turbines, Vertical Axis Wind Turbines, Floating Platforms, Fixed Platforms End User: Commercial, Residential, Government, Utilities Installation: Ground Mounted, Offshore Mounted, Rooftop, Integrated Systems |
| Companies Covered | Polenergia, RWE, PGE, Orsted, Vestas Wind Systems, Siemens Gamesa Renewable Energy, EDF Renewables, Equinor, Ørsted, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poland Wind Energy Market Evolving Landscape
Turbine scaling and foundation engineering are compressing levelized cost trajectories in Polish waters while regulatory streamlining accelerates project velocity. Three developments warrant particular attention.
Direct-drive permanent magnet generators are eliminating gearbox maintenance burdens in Baltic Sea salt-air environments. Developers in Polish waters specify these systems for 25-year design lives without major drivetrain overhauls. This reliability architecture is converging with larger rotor diameters to expand the economically viable offshore resource envelope.
The EU Green Deal's offshore renewable energy strategy is mandating streamlined environmental permitting across member states. Polish implementation through the Energy Regulatory Office reduces marine survey duplication and compresses consent timelines. Baltic Sea leaseholders benefit most where pre-approved site investigation protocols apply.
Utility procurement departments now require 15-20 year service agreements bundled with turbine supply contracts. Independent service providers lose share to original equipment manufacturer captive service arms. This preference consolidation is most pronounced among Polish state-controlled utilities with limited in-house technical capacity.
Poland Wind Energy Market Segmentation
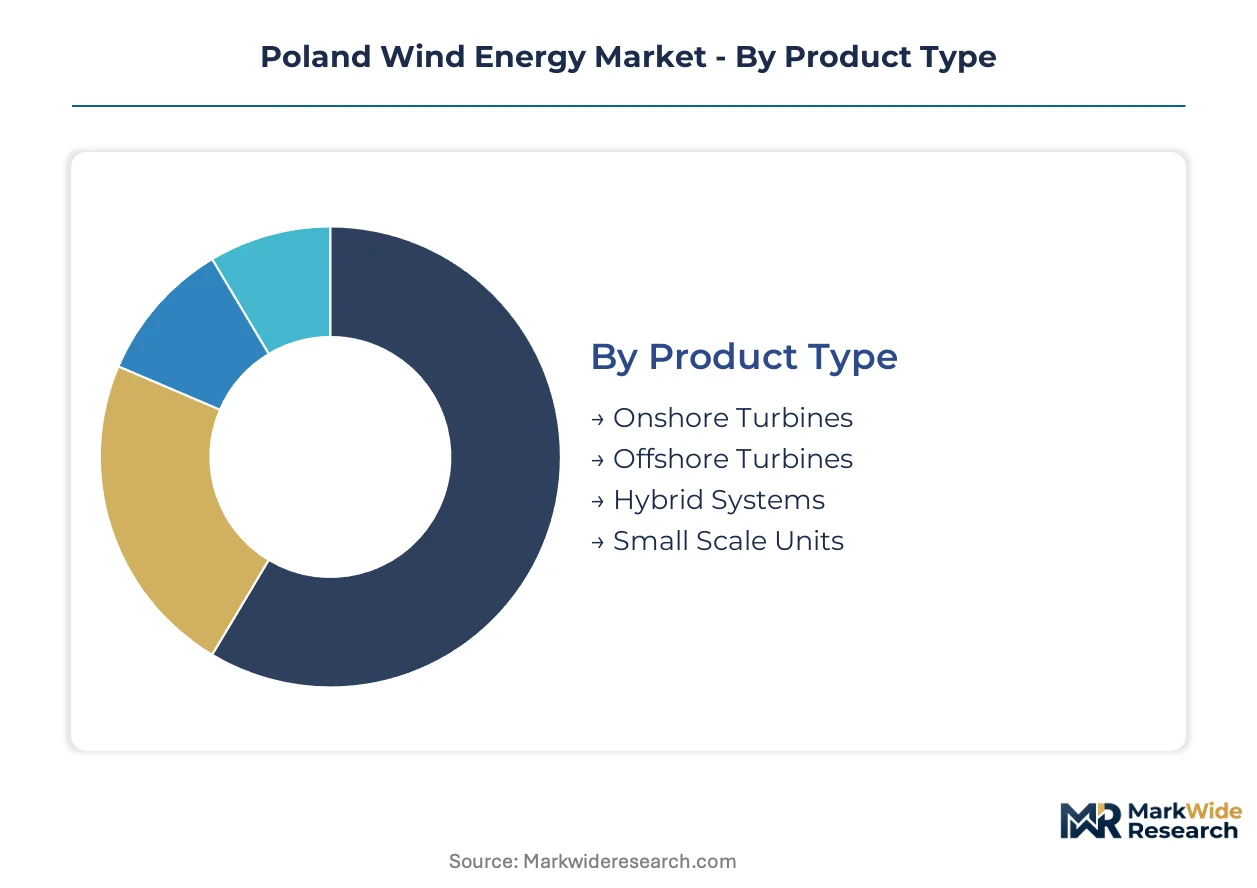
Segmentation in the Poland Wind Energy Market reveals how capital allocation, regulatory incentives, and grid infrastructure constraints differentially shape investment returns across turbine configurations and deployment modes. Developers and utilities use these categories to match technology selection to site-specific wind resource profiles and connection queue positioning.
Product Type:
Capital intensity varies dramatically across product categories, with offshore installations requiring foundation, marine logistics, and subsea cable investments that multiply upfront outlays relative to onshore equivalents.
- Onshore Turbines:These systems deploy steel towers and reinforced concrete foundations on Polish agricultural and forested terrain, with rotor diameters now routinely exceeding 150 meters. Procurement concentrates among state-controlled utilities in Pomeranian and West Pomeranian Voivodeships where transmission infrastructure already exists, though land access negotiations and local permitting create timeline variability.
- Offshore Turbines:Monopile or jacket foundations anchor these units in Baltic Sea waters, demanding specialized heavy-lift vessels and seasonal installation windows. The Polish Energy Regulatory Office's lease auctions in the Baltic Sea corridor attract Danish, Norwegian, and German developers seeking capacity expansion, with grid connection prioritization rules accelerating viable projects.
- Hybrid Systems:Configurations pairing wind generation with battery storage or solar PV co-location.
- Small Scale Units:Distributed turbines below 100 kW capacity serving individual agricultural or industrial sites.
Onshore Turbines absorb the bulk of installed capacity; Offshore Turbines are expanding most quickly.
Technology:
Technology selection in Polish waters hinges on water depth, seabed geology, and the Polish Energy Regulatory Office's technical code requirements for fault-ride-through and reactive power capabilities.
- Horizontal Axis Wind Turbines:The dominant architecture across Polish deployments, with upwind rotor configurations optimized for Baltic wind shear profiles. Direct-drive permanent magnet generators are displacing geared drivetrains in new orders, eliminating salt-air maintenance burdens and aligning with 25-year service agreements now standard in utility procurement.
- Fixed Platforms:Steel-reinforced concrete monopiles or jacket structures anchored to Baltic seabed, with foundation engineering advances enabling economically viable installations in deeper waters previously excluded from development. Polish leaseholders specify these where water depths remain below 50 meters.
- Vertical Axis Wind Turbines:Darrieus or Savonius designs limited to niche micro-generation applications in distributed settings.
- Floating Platforms:Semi-submersible or tension-leg platforms for water depths exceeding 60 meters, still pre-commercial in Polish waters.
Horizontal Axis Wind Turbines dominate current procurement; Fixed Platforms claim the steepest expansion trajectory as deeper-water sites enter development.
End User:
End user segmentation reflects divergent procurement timelines, with utilities operating under renewable purchase obligations that compress decision cycles relative to commercial or residential adopters.
- Utilities:State-controlled and independent power producers contracting capacity through Polish Energy Regulatory Office auctions, with 15-20 year service agreements now bundled into turbine supply contracts. These entities drive volume and anchor manufacturer order books.
- Commercial:Industrial energy consumers pursuing corporate renewable power purchase agreements to hedge electricity price exposure.
- Government:Public sector direct procurement for municipal or national infrastructure.
- Residential:Individual property owners deploying small-scale units, constrained by grid connection queue congestion and distribution system operator technical requirements.
Utilities command the dominant share of megawatt-scale deployment; Commercial offtakers are gaining share fastest as corporate procurement programs expand.
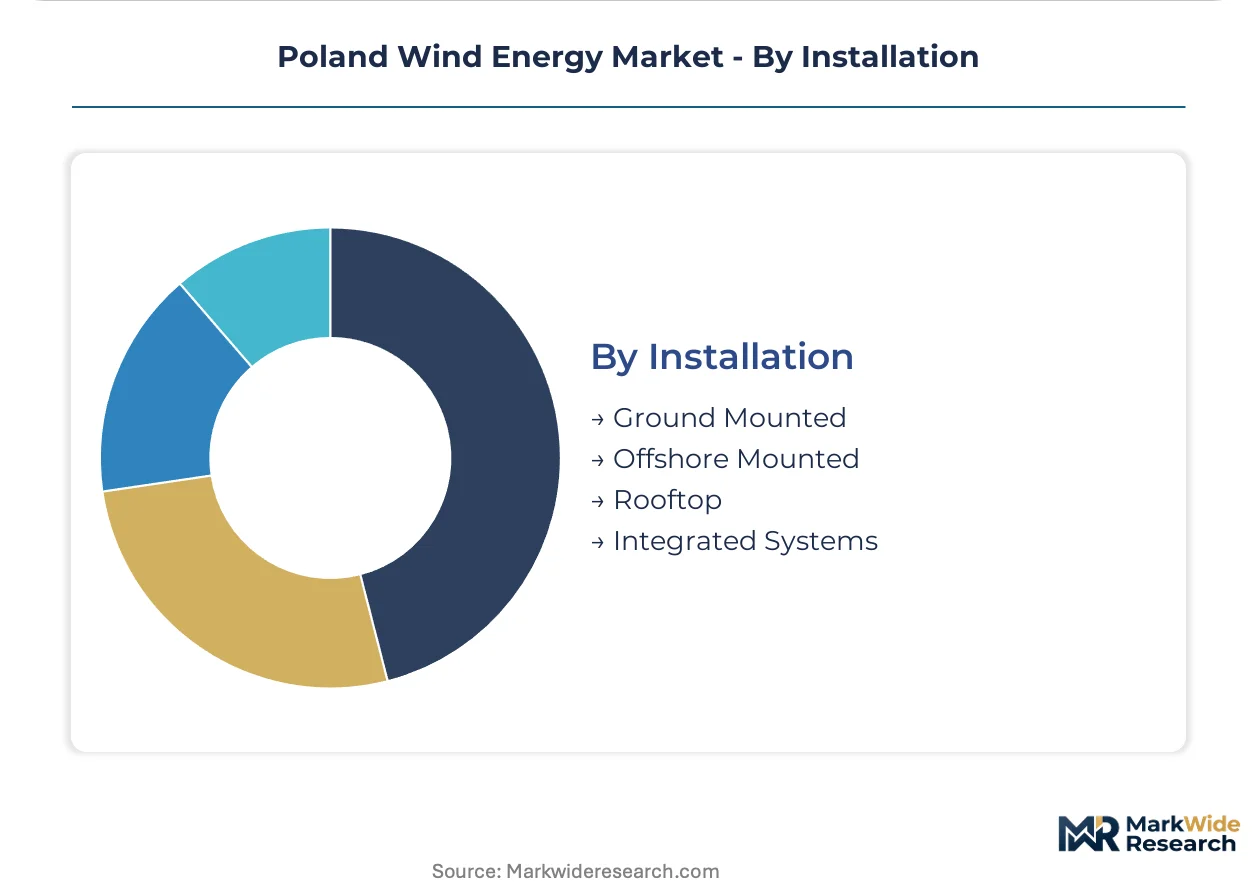
Installation:
Installation modality determines supply chain requirements, with offshore mounted systems facing specialized vessel scarcity that extends timelines 18-24 months beyond turbine delivery schedules.
- Ground Mounted:Conventional onshore deployment on prepared foundations, representing the mature installation base across northern Polish voivodeships. Brownfield repowering of aging turbine fleets in Pomerania offers capital-efficient capacity expansion where grid infrastructure already exists.
- Offshore Mounted:Marine construction requiring heavy-lift jack-up vessels, seasonal weather windows, and ECHA marine habitat assessment compliance. Polish labor pools lack certified offshore installation crews, creating dependence on North Sea specialist contractors.
- Rooftop:Small-scale urban or industrial building-integrated deployment.
- Integrated Systems:Building-embedded or infrastructure-coupled configurations.
Ground Mounted installations retain the largest operational base; Offshore Mounted configurations show the most rapid capacity addition as Baltic Sea lease development accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polish wind energy demand concentrates along the Baltic Sea corridor where lease auctions have attracted Nordic and German developers. The Pomeranian Voivodeship anchors onshore expansion with established grid infrastructure and brownfield repowering potential.
Pomeranian Voivodeship
Onshore turbine procurement dominates in northern Poland where transmission infrastructure already exists. The Polish Energy Regulatory Office administers auction mechanisms that compress decision cycles for utilities in this region. Gdańsk and Gdynia industrial clusters host foundation component fabrication and marine logistics contractors serving Baltic Sea offshore projects.
West Pomeranian Voivodeship
Agricultural and forested terrain offers land availability for ground-mounted installations with rotor diameters exceeding 150 meters. Distribution system operator technical codes specify fault-ride-through requirements that shape turbine selection. Szczecin anchors component supply chains linking German manufacturers to Polish installation sites.
Warmian-Masurian Voivodeship
Grid connection queue congestion extends timelines 18-24 months beyond turbine delivery schedules in this lake-district region. EU Green Deal binding targets mandate specific capacity additions that utilities must contract through competitive auctions. Olsztyn serves as a regional coordination hub for land access negotiations and local permitting.
Masovian Voivodeship
Corporate renewable power purchase agreements from Warsaw-based industrial energy consumers drive commercial segment growth. CE marking and grid code compliance requirements impose 12-18 month validation cycles on turbine certification. The Warsaw metropolitan area concentrates financial services and legal expertise supporting project development across Polish waters.
Łódź Voivodeship
Brownfield industrial sites offer repurposed land for distributed wind generation serving individual agricultural operations. The Energy Regulatory Office enforces reactive power capability standards that filter technology options. Łódź manufacturing heritage supports domestic component fabrication for small-scale units below 100 kW capacity.
Poland Wind Energy Market Competitive Landscape
Lease portfolio accumulation dominates the current landscape as developers pre-position Baltic Sea maritime zones ahead of auction rounds. The vendor base organizes around three strategic archetypes: integrated European utilities with full development-to-grid capabilities, specialized offshore wind developers with marine construction expertise, and turbine original equipment manufacturers with captive service arms. Geographic expansion through cross-border Nordic partnerships and vertical integration into foundation engineering represent the two most visible competitive vectors.
Within the integrated utility tier, Polenergia and RWE exemplify developers leveraging Baltic Sea lease portfolios to anchor early-mover positioning. Vestas Wind Systems occupies the manufacturing tier with turbine scaling optimized for regional wind regimes. Ørsted and Equinor represent Nordic specialists importing North Sea offshore expertise into Polish waters.
| Leading Market Players |
|---|
| Polenergia |
| RWE |
| PGE |
| Orsted |
| Vestas Wind Systems |
| Siemens Gamesa Renewable Energy |
| EDF Renewables |
| Equinor |
| Ørsted |
| Others |
Value Network & Pricing Analysis
Polish state-controlled utilities anchor procurement volume and enforce contract-based long-term offtake pricing bundled with 15-20 year service agreements, compressing margins for turbine original equipment manufacturers while stabilizing revenue visibility for compliant developers.
Pricing Analysis
Volume concentration among state-controlled utilities compresses supplier margins while offshore project premiums sustain higher pricing tiers for Baltic Sea installations. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with CE marking and Polish Energy Regulatory Office grid code compliance filtering access to premium tiers. Cost compression in onshore segments is intensifying because brownfield repowering competition concentrates procurement leverage among incumbent utilities. Commercial offtakers pursuing corporate renewable power purchase agreements exhibit highest price sensitivity, while offshore developers with secured lease positions show least sensitivity due to capacity factor premiums.
Supply Chain Analysis
Steel-reinforced concrete monopile supply rests on German and Danish foundation engineering specialists, with heavy-lift jack-up vessel availability hinging on North Sea operator deployment schedules. Rare earth permanent magnet feedstock draws from Chinese processing facilities, while blade composites source from Spanish and Turkish manufacturing hubs. Single-source vulnerability concentrates in specialized marine construction crews for Baltic Sea cable laying operations. Distribution runs through original equipment manufacturer captive service arms that displace independent providers in utility procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Poland wind energy market reads as a cost-of-compliance story where Polish Energy Regulatory Office technical specifications and ECHA marine habitat assessments erect barrier-to-entry moats favoring developers with pre-positioned permits and validated turbine certifications.
For Market Incumbents: Cement early-mover positioning in Baltic Sea lease zones through parallel environmental permitting and grid connection queue pre-positioning before auction rounds intensify. Acquire certified offshore installation capabilities or captive supply agreements with North Sea marine construction specialists to neutralize vessel scarcity threats. Deepen backward integration into foundation engineering to control critical path timelines. For New Entrants and Emerging Players: Commercial industrial offtakers in Masovian Voivodeship represent an underserved buyer archetype with unmet demand for corporate renewable power purchase agreements outside state-controlled utility channels. Target brownfield repowering opportunities in Pomeranian Voivodeship where existing grid infrastructure reduces connection queue risk. Pursue hybrid offshore-wind-to-hydrogen configurations as a differentiated go-to-market angle with merchant offtake certainty. For Investors and Strategic Acquirers: Distressed-cycle entries favor developers with stalled permitting timelines in Warmian-Masurian Voivodeship where grid connection congestion has compressed valuations. Long-term viability hinges on lease portfolio depth in Polish maritime zones and validated turbine certifications against Polish Energy Regulatory Office codes. Watch cross-border Nordic transmission link progress as the inflection signal for capacity factor optimization plays.| Strategic Initiative | Industry Significance |
|---|---|
| Offshore Lease Portfolio Accumulation | Polish Energy Regulatory Office auction rounds reward pre-positioned maritime zone access with accelerated grid connection timelines. |
| Direct-Drive Permanent Magnet Generator Deployment | Vestas and Siemens Gamesa specifications eliminate salt-air maintenance burdens across 25-year Baltic Sea design lives. |
| Hybrid Wind-to-Hydrogen Electrolyzer Co-location | Baltic Sea substation integration creates merchant offtake certainty for developers exposed to power price volatility. |
| Cross-Border Nordic Balancing Partnership | Planned Sweden and Denmark transmission links enable geographic diversification of capacity factor risk. |
| CE Marking and Grid Code Compliance Investment | Polish Energy Regulatory Office validation cycles filter market access and sustain pricing power for certified suppliers. |
Research Methodology
Document review covered Polish Energy Regulatory Office auction filings, ECHA marine environmental assessments, EU Green Deal national binding target disclosures, and Baltic Sea lease auction records, complemented by interviews with utility planning officers, independent power project developers, EPC contractors, and grid operators. Secondary validation drew from IEA renewable energy databases, FERC-equivalent transmission system operator interconnection queues, and project development tracking services. Bottom-up project pipeline aggregation and top-down national capacity target reconciliation provided cross-verification.
Installed capacity and revenue projections across the analysis window reflect segmentation by turbine configuration, foundation technology, water depth classification, and end-user procurement channel. CAGRs were derived from auction schedule alignment with construction timeline assumptions and vessel availability constraints. Forecast inputs incorporated Polish Energy Regulatory Office permitting velocity trends and seasonal marine construction windows.
Revisions become necessary when Polish Energy Regulatory Office auction price floor adjustments, cross-border transmission capacity expansion delays, or heavy-lift vessel deployment bottlenecks materialize beyond modeled assumptions. Forecasts reflect current regulatory frameworks and technology cost trajectories. A small set of named triggers warrants ongoing watch: EU Green Deal target revisions, ECHA seasonal survey window restrictions, and Nordic balancing market integration progress.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Spain Wind Energy Market
Wind Energy Systems
India Wind Industry Market
Wind Energy Systems
Taiwan Wind Energy Market
Wind Energy Systems
Italy Wind Energy Market
Wind Energy Systems
Chile Wind Energy Market
Wind Energy Systems
Wind Turbine Market
Wind Energy Systems
Portugal Wind Energy Market
Wind Energy Systems
Bladeless Wind Turbines Market
Wind Energy Systems
Europe Direct Drive Wind Turbine Market
Wind Energy Systems
Global Small Wind Market
Wind Energy Systems
Middle-East and Africa Wind Power Market
Wind Energy Systems
Japan Wind Energy Market
Wind Energy Systems
Thailand Wind Energy Market
Wind Energy Systems
Onshore Wind Turbine (above 2.5MW) Market
Wind Energy Systems
Wind Cones Market
Wind Energy Systems
Offshore Wind Tower Market