
 Latin America Wind Turbine Market | 2026-2036
Latin America Wind Turbine Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Wind Turbine Market Foresight
Brazil's Northeast wind corridor is reshaping regional supply chain geography. Nordex SE leverages its regional manufacturing footprint to anchor turbine assembly near port infrastructure. Vestas Wind Systems A/S sustains technology leadership through advanced blade aerodynamics optimized for low-wind sites. Siemens Gamesa Renewable Energy SA competes on drivetrain reliability across complex terrain installations.
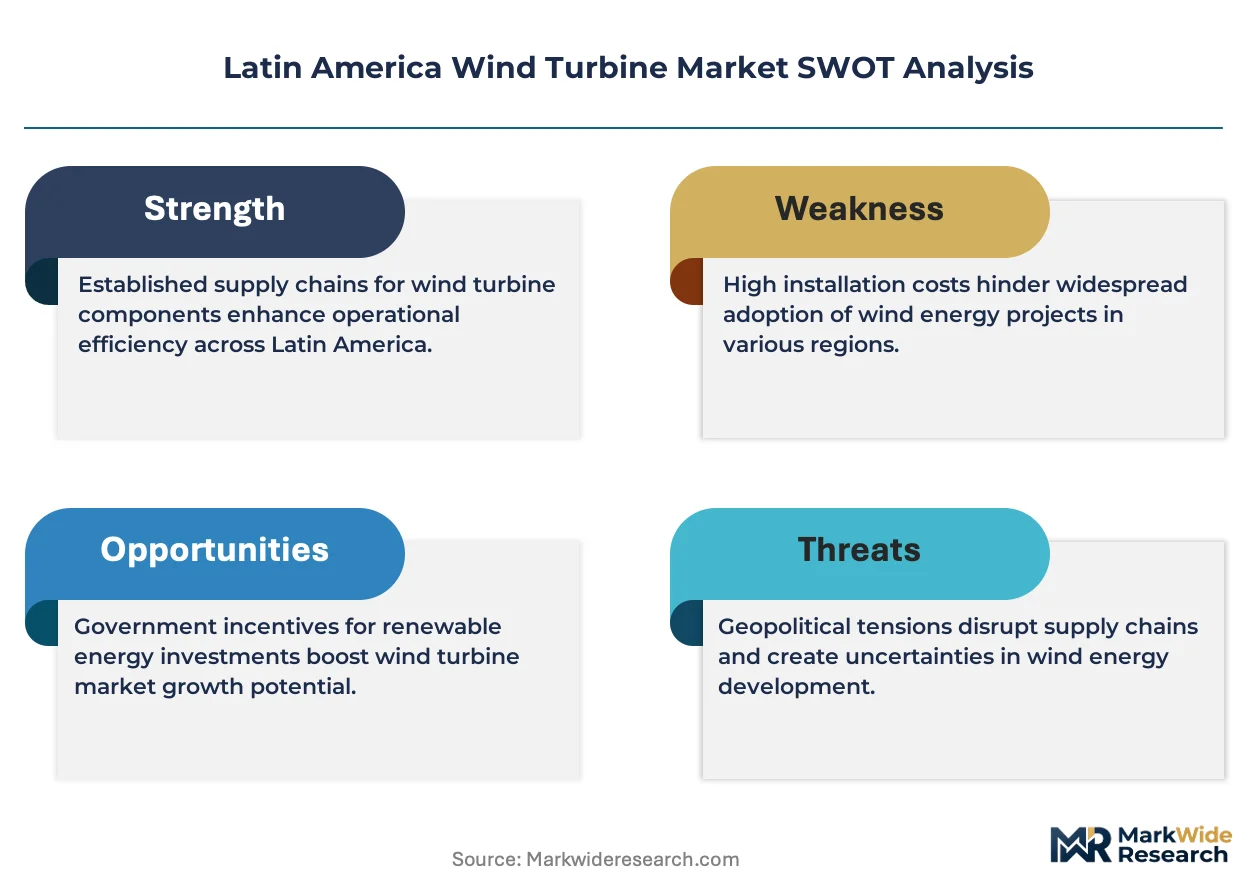
A wind turbine converts kinetic wind energy into electrical power through aerodynamic blades, a drivetrain, and a generator, with modern units rated from 2 MW to 6 MW for utility-scale deployment. Horizontal axis configurations dominate Latin American installations due to mature supply chains and proven capacity factors above 35 percent in coastal zones. Grid-connected technology leads the technology segment, though hybrid systems pairing wind with solar PV gain traction among industrial off-takers seeking dispatchable renewable output. The application segment centers on power generation, with energy storage co-location emerging as a margin pool where developers integrate battery systems to capture price arbitrage.
Brazil's ANEEL auction mechanisms and local content mandates shape procurement standards, while Mexico's CRE interconnection rules and Argentina's renewable energy trust fund framework influence project finance structures. Chile's environmental impact assessment process under SEA authority governs permitting timelines in the Atacama and Magallanes zones. Stakeholders must monitor auction schedule volatility and currency hedging costs as decisive variables for capital allocation.
Market Dynamics
ANEEL's local content mandates are compressing margins for foreign turbine suppliers while forcing rapid domestication of blade and nacelle assembly capacity across Brazil's Northeast corridor.
Growth Catalysts
- ANEEL Auction Mechanisms:Brazil's renewable energy auctions create predictable offtake volumes that de-risk project finance and accelerate developer procurement timelines.
- Industrial Off-Takers:Mining and steel operations in Chile's Atacama region are contracting wind-solar hybrid capacity to secure dispatchable renewable supply and hedge volatile fossil fuel exposure.
- Low-Wind Site Optimization:Advanced blade aerodynamics and taller hub heights are unlocking capacity factors above 35 percent in coastal zones previously deemed marginal for utility-scale deployment.
Market Restraints
- Steel and Rare Earth Input Volatility:Permanent magnet drivetrains depend on neodymium supply chains concentrated in Chinese processing facilities, exposing project economics to export quota fluctuations.
- Port Infrastructure Bottlenecks:Brazil's Northeast corridor lacks heavy-lift crane capacity at shallow-draft ports, forcing turbine component transshipment through Salvador and inflating logistics costs.
- Grid Interconnection Queues:Mexico's CRE interconnection approval timelines stretch 18-24 months, freezing capital deployment and compressing developer IRRs before construction begins.
Strategic Opportunities
- Argentina's RenovAr Trust Fund:The renewable energy trust framework offers dollar-indexed power purchase agreements that mitigate peso devaluation risk for foreign capital providers.
- Energy Storage Co-Location:Battery-wind hybrid configurations capture price arbitrage in Brazil's Northeast, where negative pricing events during high-wind periods create margin pools for dispatchable assets.
- Magallanes Zone Development:Chile's southern Patagonia corridor offers sustained wind regimes exceeding 10 meters per second annual average, with SEA environmental assessments now streamlining for projects below 50 MW.
Industry Challenges
- Tower Erection Specialist Shortage:Brazil lacks certified crane operators for 150-meter hub heights, forcing developers to import Portuguese and Spanish crews at premium rates.
- Grid Code Compliance Testing:ANEEL's revised LVRT and frequency response requirements demand extended factory acceptance testing, delaying COD schedules by 4-6 months.
- Legacy SCADA Integration:Retrofitting older turbine fleets with predictive maintenance sensors requires proprietary protocol gateways that fragment data architecture across multi-vendor wind farms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Wind Turbine Market |
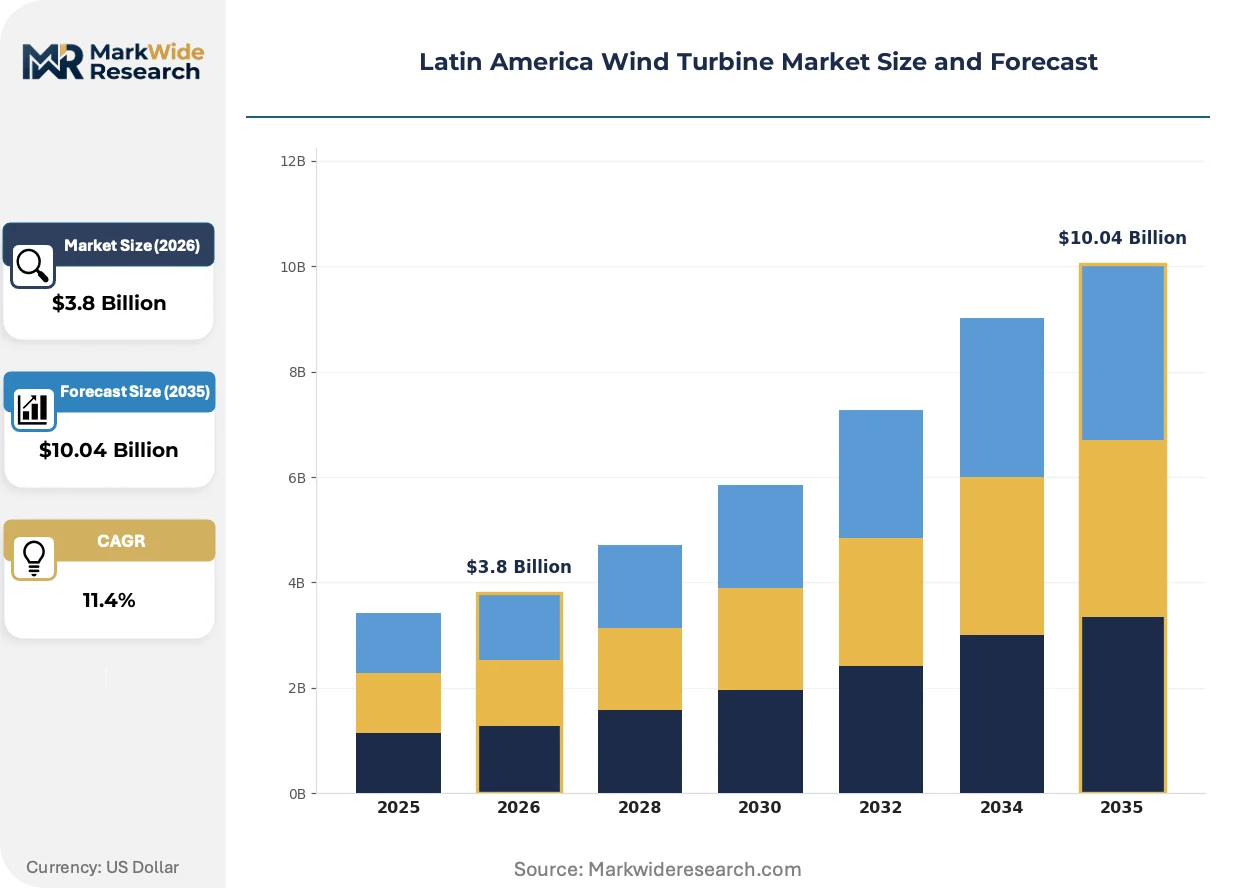
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal Axis, Vertical Axis, Offshore, Onshore Technology: Grid Connected, Off-Grid, Hybrid, Smart Turbines End User: Utilities, Industrial, Commercial, Residential Application: Power Generation, Energy Storage, Direct Use, Microgrids |
| Companies Covered | Nordex SE, Acciona, Vestas Wind Systems A/S, Iberdrola, Enel Spa, Siemens Gamesa Renewable Energy SA, Goldwind, Alstom, GE Vernova, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Wind Turbine Market Shifts & Advancements
Turbine scaling and digitalization are converging to reshape competitive positioning across Latin America's wind corridor, with technology choices increasingly dictating site access and financing terms.
Segmented blade designs using carbon fiber spar caps are rendering obsolete traditional glass-reinforced epoxy construction for rotors exceeding 140 meters in diameter. Developers in Brazil's Ceará state are specifying these platforms for low-wind sites where swept area determines project viability. The shift is compressing supplier margins on conventional blade lines while concentrating assembly contracts with facilities possessing autoclave curing capacity.
Brazil's ANEEL local content mandates now require 65 percent domestic value-add for nacelle assembly and 80 percent for tower fabrication, with penalties disqualifying non-compliant bids from auction participation. Foreign OEMs are responding by licensing blade mold technology to Brazilian joint ventures and converting port-adjacent facilities in Pecém and Suape. The regulation most heavily impacts offshore wind pre-development, where domestic supply chains for transition pieces and substructures remain undeveloped.
Power purchase agreement structures are migrating from 20-year fixed-price contracts toward merchant-exposed tranches with floor-price collars, transferring volume risk to developers while preserving lender coverage ratios. Industrial offtakers in Mexico's Bajío manufacturing belt are driving this evolution, seeking flexibility to curtail when spot prices turn negative. The pattern is most visible in contracts signed since 2023, where 30-40 percent of generation volume now floats against CENACE day-ahead pricing.
Latin America Wind Turbine Market Segmentation
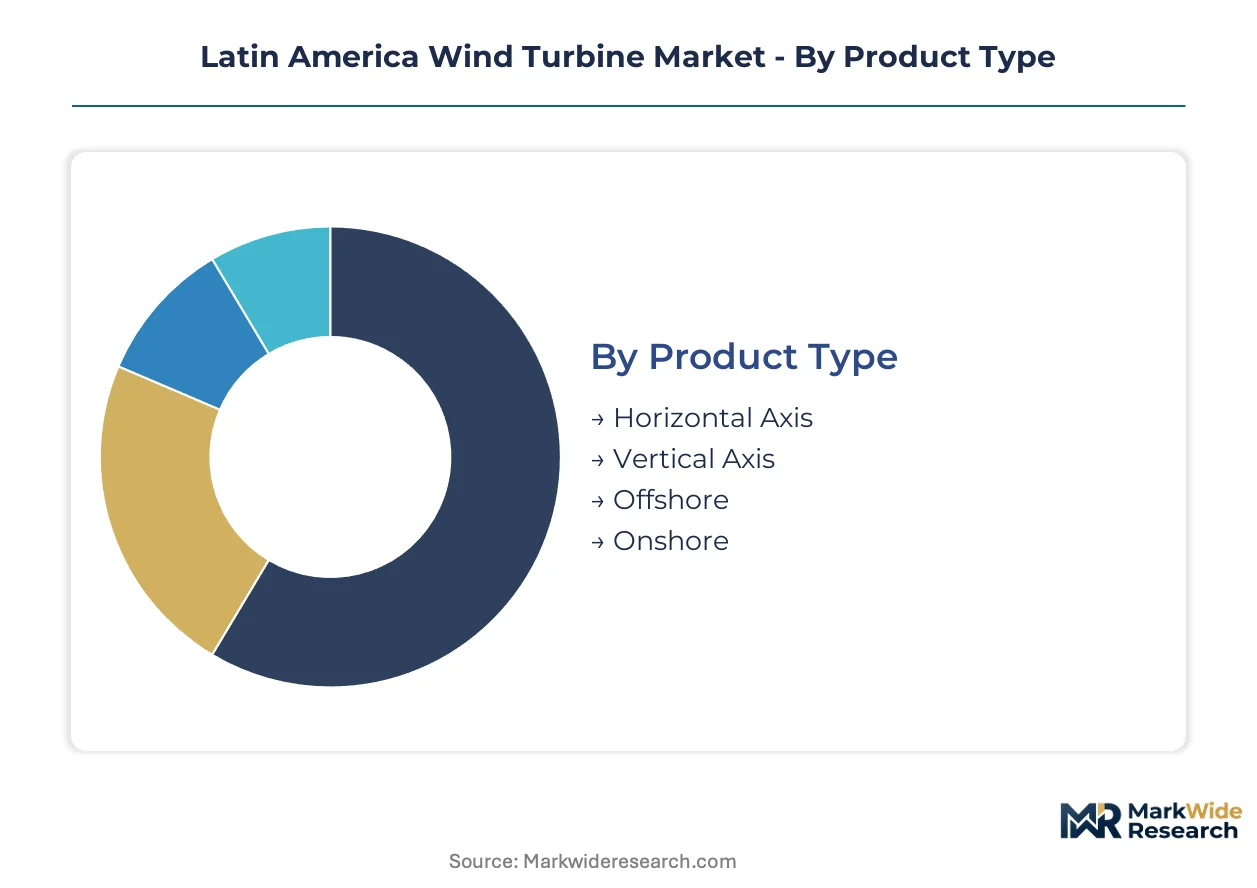
Turbine configuration choices in Latin America hinge on site-specific wind regimes, grid proximity, and ANEEL auction eligibility criteria. Segmentation reveals how technology selection maps to financing structures and local content compliance thresholds across Brazil's Northeast corridor and Chile's Magallanes zone.
Product Type:
Horizontal axis designs anchor utility-scale procurement, while emerging configurations target constrained sites and offshore pre-development.
- Horizontal Axis:Dominant configuration employs three-blade upwind rotors with drivetrains rated 2-6 MW. Brazil's Ceará and Rio Grande do Norte states concentrate demand where capacity factors exceed 35 percent and ANEEL local content mandates favor established supply chains.
- Onshore:Ground-mounted installations account for virtually all operational capacity, with hub heights climbing to 150 meters to capture stronger wind strata. Developers face tower erection specialist shortages that inflate construction timelines by 4-6 months.
- Vertical Axis:Darrieus and H-rotor designs occupy niche applications including urban microgrids and remote telecom towers. Limited swept area constrains utility-scale viability despite omnidirectional wind capture advantages.
- Offshore:Floating platform pre-development accelerates in Brazil's Southeast basin, though domestic supply chains for transition pieces and substructures remain undeveloped under current ANEEL local content rules.
The dominant share belongs to Horizontal Axis, while Onshore is closing the gap fastest through hub height extensions and segmented blade adoption.
Technology:
Grid integration maturity determines financing risk profiles, with hybrid architectures gaining traction among industrial offtakers seeking dispatchable output.
- Grid Connected:Synchronous generators with full-scale converters dominate auction-eligible projects. ANEEL's revised LVRT and frequency response requirements demand extended factory acceptance testing that delays commercial operation dates.
- Hybrid:Wind-solar-battery configurations capture price arbitrage in Brazil's Northeast where negative pricing events cluster during high-wind periods. Mining operations in Chile's Atacama region contract these systems to hedge fossil fuel volatility.
- Off-Grid:Standalone turbines power remote agricultural processing and isolated communities beyond transmission reach. Diesel displacement economics drive adoption in Argentina's Patagonian provinces.
- Smart Turbines:Sensor-embedded platforms with predictive maintenance algorithms reduce unplanned downtime. Legacy SCADA integration challenges fragment data architecture across multi-vendor wind farms.
Grid Connected retains the installed base majority, yet Hybrid configurations are expanding most quickly as battery costs decline and industrial procurement shifts toward merchant-exposed structures.
End User:
Procurement scale and offtake tenure diverge sharply between regulated utilities and private industrial buyers.
- Utilities:State-owned and private distributors anchor volume through ANEEL auction participation. Twenty-year fixed-price contracts with local content riders define procurement standards.
- Industrial:Mining, steel, and cement operations in Mexico's Bajío belt and Chile's Atacama seek hybrid capacity with floor-price collars. These offtakers drive contract evolution toward merchant-exposed tranches with curtailment flexibility.
- Commercial:Corporate renewable energy buyers with sustainability targets contract smaller portfolios through bilateral PPAs. Creditworthiness constraints limit project finance lender participation.
- Residential:Distributed turbines serve rural properties and small agricultural operations. Grid interconnection queues and net metering policy uncertainty suppress scaling.
Utilities command the dominant procurement volume, while Industrial end users are gaining share fastest through direct contracting outside auction mechanisms.
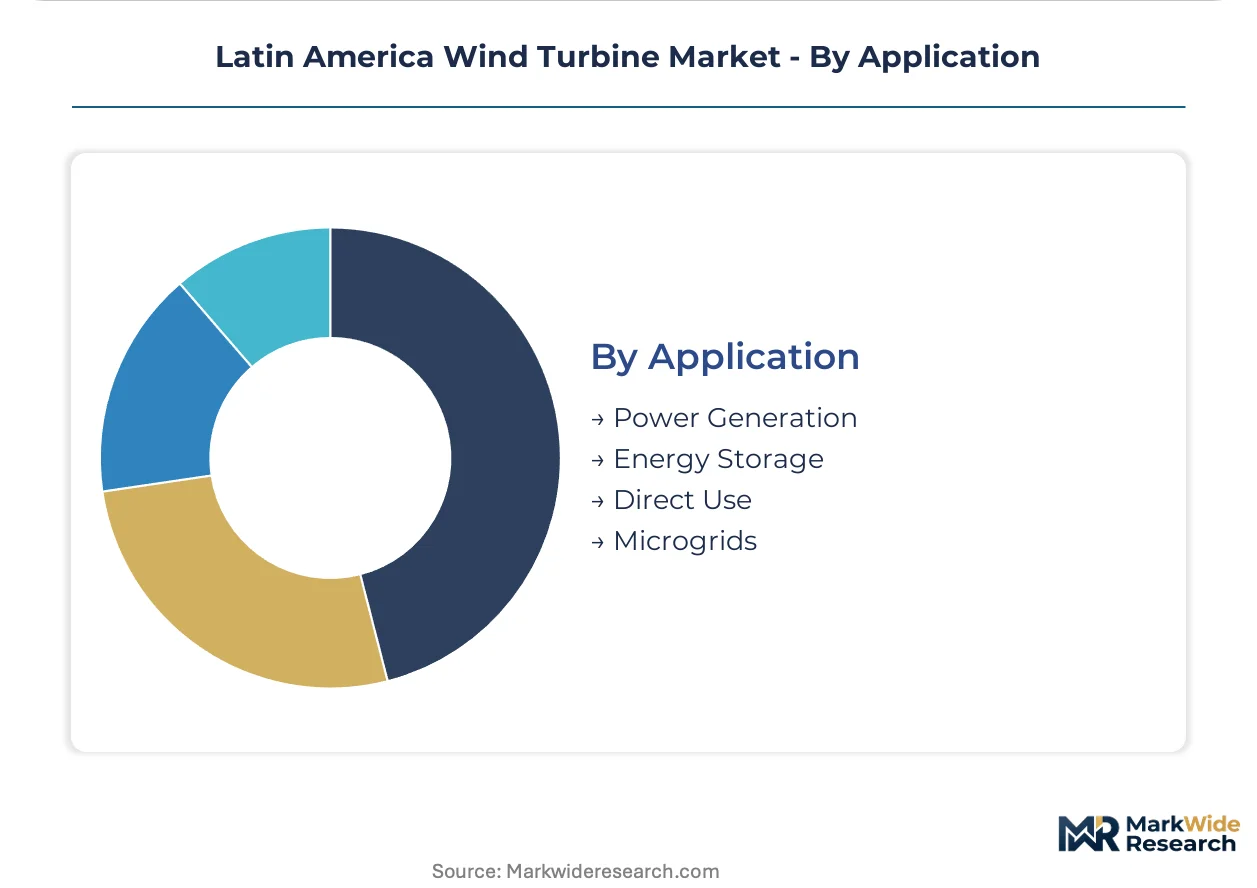
Application:
Revenue model differentiation separates bulk power suppliers from value-stacking developers integrating storage and grid services.
- Power Generation:Wholesale electricity delivery to national grids constitutes the core revenue stream. ANEEL auction mechanisms and CRE interconnection rules shape project economics across Brazil and Mexico.
- Energy Storage:Battery co-location captures price arbitrage and provides ancillary services. Developers in Brazil's Northeast corridor target negative pricing events for margin pool extraction.
- Direct Use:Behind-the-meter supply to industrial facilities bypasses transmission tariffs. Argentina's RenovAr trust framework offers dollar-indexed contracts that mitigate currency risk for foreign capital.
- Microgrids:Islanded systems serve remote mining camps and agricultural processing clusters. Magallanes zone projects below 50 MW benefit from streamlined SEA environmental assessments.
Power Generation holds the dominant application share, though Energy Storage is climbing the fastest as battery-wind hybrid configurations proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil concentrates turbine assembly capacity through port-adjacent facilities in Pecém and Suape, while component sourcing spans Argentina, Chile, and Mexico under divergent regulatory regimes. ANEEL's local content mandates force rapid domestication of nacelle and tower production, reshaping procurement geography across the continent.
Brazil
Utilities in Ceará, Rio Grande do Norte, and Pernambuco states drive procurement through ANEEL renewable energy auctions with 65 percent domestic value-add requirements. The Northeast wind corridor anchors demand where capacity factors exceed 35 percent, though port infrastructure bottlenecks at shallow-draft facilities force costly transshipment through Salvador.
Mexico
Industrial offtakers in the Bajío manufacturing belt contract merchant-exposed wind-solar hybrid capacity to hedge fossil fuel volatility. CRE interconnection approval timelines stretching 18-24 months freeze capital deployment and compress developer IRRs before construction begins.
Chile
Mining operations in the Atacama region seek dispatchable renewable supply through battery-wind hybrid configurations. SEA environmental assessments now streamline for Magallanes zone projects below 50 MW, where sustained wind regimes exceed 10 meters per second annual average.
Argentina
The RenovAr renewable energy trust fund offers dollar-indexed power purchase agreements that mitigate peso devaluation risk for foreign capital providers. Patagonian provinces drive off-grid adoption where diesel displacement economics support standalone turbine deployment.
Colombia
Grid integration challenges and transmission constraints suppress utility-scale development despite substantial wind resource potential in the Guajira Peninsula. Regulatory uncertainty around land tenure and indigenous consultation protocols delays project permitting timelines.
Latin America Wind Turbine Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in blade mold technology and drivetrain subsystems. The market structure consolidates around a handful of full-turbine suppliers with regional manufacturing footprints, while niche players occupy tower fabrication and service contracting segments. Three archetypes dominate: European-headquartered OEMs with licensed local assembly, Chinese manufacturers pursuing direct export strategies, and Latin American joint ventures capturing local content mandates. Competitive intensity centers on technology licensing partnerships and port-adjacent capacity expansion.
Among European-headquartered OEMs, Vestas Wind Systems A/S and Siemens Gamesa Renewable Energy SA exemplify the platform-integrator archetype through established regional assembly presence. Nordex SE occupies a position anchored to Northeast corridor logistics advantages. Chinese manufacturers including Goldwind represent the direct-export vector, competing on capital cost positioning where local content thresholds permit.
| Leading Market Players |
|---|
| Nordex SE |
| Acciona |
| Vestas Wind Systems A/S |
| Iberdrola |
| Enel Spa |
| Siemens Gamesa Renewable Energy SA |
| Goldwind |
| Alstom |
| GE Vernova |
| Others |
Supply & Pricing Matrix
Brazil's Northeast wind corridor logistics routes impose heavy-lift crane surcharges that cascade through turbine component pricing, concentrating supply power among port-adjacent assemblers while forcing tiered price differentiation between auction-compliant and import-dependent developers.
Pricing Analysis
ANEEL's local content mandates dictate the pricing tier structure across Brazil's turbine procurement landscape. Three-tier pricing separates premium domestic-assembly platforms from standard licensed-technology joint ventures and economy direct-import configurations. Price differentiation rests on certification grade for ANEEL auction eligibility and volume scale for tower fabrication contracts. Cost compression in the economy tier is intensifying because Chinese manufacturers compete on capital cost positioning where local content thresholds permit. Industrial offtakers in Chile's Atacama region show least price sensitivity due to fossil fuel hedge premiums, while Argentine developers dependent on RenovAr trust fund access face acute budget constraints.
Supply Chain Analysis
Export controls on permanent magnet rare earth processing limit neodymium flow concentration through Chinese facilities, constraining drivetrain sourcing flexibility for Latin American projects. Component manufacturing draws from China for magnet assemblies, Spain and Denmark for blade mold technology, and Brazil for tower fabrication under ANEEL domestication rules. Raw material dependencies span carbon fiber spar caps, glass-reinforced epoxy, and specialized bearing steel. Single-source vulnerability in rare earth processing exposes project economics to quota fluctuations. Distribution runs through port-adjacent assembly facilities in Pecém and Suape with final-mile heavy-haul to wind corridor sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat arena where ANEEL regulatory entrenchment creates durable competitive positioning for compliant assemblers, with switching costs locking developers into established supply relationships.
For Market Incumbents: Entrench auction eligibility through accelerated licensing of blade mold technology to Brazilian joint ventures, converting port facilities in Ceará and Pernambuco before local content thresholds tighten further. Expand nacelle assembly capacity to capture margin compression from emerging Chinese direct-export entrants. Vertical integration into tower fabrication secures the 80 percent domestic value-add requirement while insulating against steel input volatility.
For New Entrants and Emerging Players: Build out hybrid system integration capabilities targeting Chile's mining sector, where dispatchable renewable demand outstrips established supplier attention. Argentina's dollar-indexed RenovAr contracts offer the most penetrable finance structure for foreign capital providers lacking ANEEL auction track records. A go-to-market angle anchored to battery-wind co-location expertise bypasses direct confrontation with entrenched turbine OEMs.
For Investors and Strategic Acquirers: Regional service contractors with predictive maintenance platforms and legacy SCADA retrofit capabilities represent the priority acquisition archetype. Long-term viability hinges on digitalization moats deepening as turbine fleets age across Brazil's Northeast corridor. The signal to watch is ANEEL auction schedule density as inflection indicator for capital deployment velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Port-Adjacent Capacity Expansion | Pecém and Suape facility conversions secure ANEEL compliance and reduce transshipment costs. |
| Technology Licensing Partnership | Blade mold technology transfers to Brazilian joint ventures satisfy domestic value-add thresholds. |
| Hybrid System Integration | Battery-wind configurations capture price arbitrage in Brazil's negative pricing events. |
| Predictive Maintenance Platform | Sensor-embedded turbines reduce unplanned downtime across aging multi-vendor fleets. |
| Magallanes Zone Development | Streamlined SEA assessments below 50 MW unlock Patagonia's sustained wind regimes. |
Research Methodology
Cross-validation between primary fieldwork with utility planning officers and secondary validation through ANEEL auction databases anchors the qualitative findings. Conversations with IPP project developers, EPC contractors, and grid operators in Brazil's Northeast corridor combined with CRE interconnection filings and Chile's SEA environmental assessment records. Secondary sources include IEA renewable energy reports, EIA generation statistics, and project finance database disclosures. Bottom-up capacity installation tracking and top-down regulatory framework analysis triangulate market sizing.
Calibration against historical auction award volumes and COD realization rates shapes the projection framework across the analysis window. Segmentation dimensions span turbine configuration, grid integration technology, end-user procurement archetype, and application revenue model. CAGRs derive from installed capacity buildout trajectories and capital cost evolution assumptions. Forecast inputs incorporate ANEEL local content threshold schedules and battery cost decline curves.
Stress conditions across currency hedging cost bands, steel price volatility, and interconnection queue durations were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on auction schedule regularity and supply chain domestication pace. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Taiwan Wind Energy Market
Wind Energy Systems
Japan Wind Energy Market
Wind Energy Systems
New Zealand Wind Energy Market
Wind Energy Systems
Wind Power Bolts Market
Wind Energy Systems
Onshore Wind Turbine (above 2.5MW) Market
Wind Energy Systems
Ireland Wind Energy Market
Wind Energy Systems
Wind Turbine Blades Market
Wind Energy Systems
Global Wind Automation Market
Wind Energy Systems
Offshore Wind Anchoring Market
Wind Energy Systems
Airborne Wind Turbines Market
Wind Energy Systems
Wind Turbine Tower Market
Wind Energy Systems
Dual Rotor Wind Turbine Market
Wind Energy Systems
Poland Wind Energy Market
Wind Energy Systems
Wind Power Market
Wind Energy Systems
Norway Wind Energy Market
Wind Energy Systems
Drone Wind Turbine Blade Inspection Market