
 Wide Mouth Jars Market | 2026-2036
Wide Mouth Jars Market Size, Share, and Industry Trends Forecast 2026-2036
Wide Mouth Jars Market Analytics
Glass container manufacturing in China is expanding capacity for wide mouth jar production to serve export and domestic food-packaging buyers. Owens-Illinois Inc. leverages vertical integration across raw-material sourcing and furnace operations to sustain cost leadership in North American glass packaging. Ball Corporation anchors its position in metal closure systems, while Berry Global Inc. competes through plastic jar portfolios targeting lightweight, shatter-resistant applications. Verallia dominates European recycled-glass supply chains, positioning its wide mouth formats for premium food brands.
Wide mouth jars are cylindrical containers with enlarged apertures, typically manufactured from soda-lime glass, PET, or polypropylene, with neck finishes ranging from 70mm to 110mm to enable filling access and consumer scooping. Glass wide mouth jars retain dominance in premium food preservation and home-canning segments where thermal stability and inertness matter. Plastic variants, particularly PET and HDPE formats, represent the fastest-growing product type as food manufacturers seek reduced breakage and lower logistics costs. By closure type, screw cap configurations occupy the largest share of commercial volume, while airtight seal systems command higher margins in specialty and organic food channels.
FDA food-contact notification requirements govern substrate migration limits for plastic wide mouth jars distributed in the United States, while EU REACH and F-Gas Regulation constrain blowing-agent chemistry in European plastic container production. China's SAMR enforces GB standards for food packaging material safety, affecting import and domestic sourcing decisions for glass and polymer substrates. Stakeholders must monitor evolving extended-producer-responsibility frameworks across these jurisdictions, as compliance investments will reshape supplier qualification criteria and substrate selection timelines.
Market Dynamics
Food manufacturers are consolidating SKU portfolios toward wide mouth formats that reduce filling-line changeover times and accommodate thicker viscosity products, while regulatory tightening on food-contact materials forces substrate qualification cycles that favor established glass and certified polymer suppliers.
Growth Catalysts
- EU Packaging Waste Directive amendments:Extended producer responsibility frameworks mandate higher recycled content thresholds, accelerating demand for post-consumer recycled glass wide mouth jars from premium food brands seeking compliance-ready packaging.
- Home-canning resurgence:Consumer stockpiling behaviors and artisanal food entrepreneurship in the United States are expanding retail distribution of wide mouth mason jars through farm-store channels and direct-to-consumer platforms.
- Hot-fill PET technology maturation:Advanced heat-set PET blow molding enables wide mouth jars to withstand pasteurization temperatures previously reserved for glass, opening substitution opportunities in ready-to-eat soup and sauce segments.
Market Restraints
- Soda-lime silica sand supply concentration:High-purity glass sand mining in the United States Midwest faces permitting delays and transport cost inflation, constraining furnace capacity expansion for domestic jar manufacturers.
- FDA food-contact notification timelines:Polymer additive approvals for recycled-content wide mouth jars average 18-24 months, delaying product launches and favoring incumbent suppliers with pre-cleared material libraries.
- Metal closure aluminum tariff exposure:Screw cap and lug lid sourcing from tariff-affected trade corridors elevates total packaging cost structures for mid-size food processors.
Strategic Opportunities
- China SAMR GB standard harmonization:Alignment of domestic food packaging safety standards with Codex Alimentarius frameworks reduces technical barriers for Western jar exporters targeting China's private-label retail expansion.
- Aseptic blow-fill-seal integration:Convergence of sterile blow molding and wide mouth jar forming enables ambient-stable dairy and plant-based yogurt formats without refrigerated distribution infrastructure.
- Direct-store-delivery channel bypass:Foodservice and specialty ingredient suppliers are procuring bulk wide mouth jars through B2B platforms, disintermediating traditional packaging distributor markups.
Industry Challenges
- Color-sorting technician scarcity:Optical glass cullet separation for amber and flint wide mouth jar production requires specialized operators whose training pipelines lag furnace automation investments.
- Legacy ERP integration with track-and-trace mandates:Small-batch artisanal food packagers face capital barriers upgrading inventory systems to meet lot-level serialization requirements under evolving FDA food traceability rules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wide Mouth Jars Market |
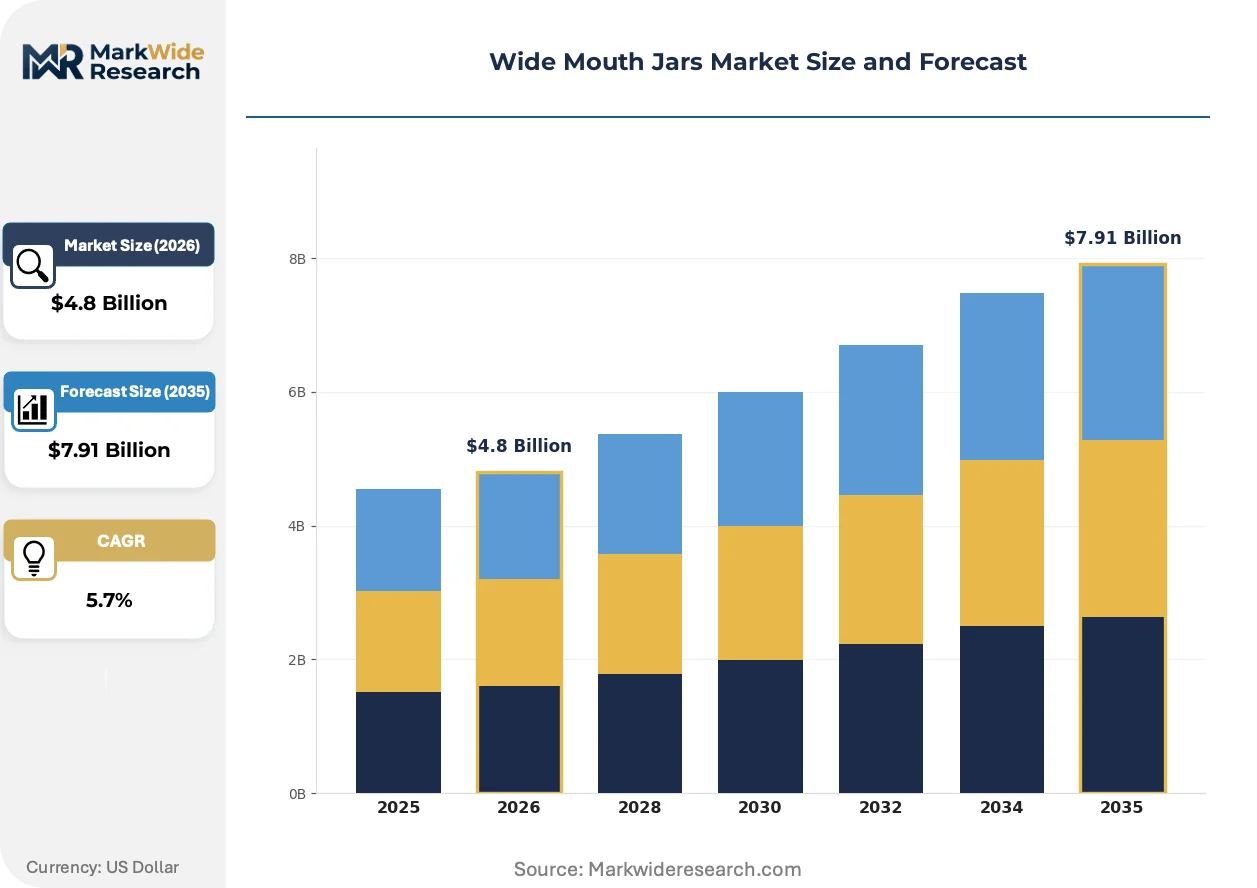
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass, Plastic, Stainless Steel, Ceramic End User: Households, Restaurants, Food Manufacturers, Craft Stores Capacity: 500ml, 1000ml, 2000ml, 3000ml Closure Type: Screw Cap, Airtight Seal, Flip Top, Cork |
| Companies Covered | Ball Corporation, Owens-Illinois Inc., Berry Global Inc., Ardagh Group, Verallia, Berlin Packaging, Anchor Hocking, Libbey, Newell Brands, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wide Mouth Jars Market Evolving Landscape
Material science advances and regulatory precision are compressing development cycles for wide mouth jar formats, while downstream consolidation among food manufacturers concentrates procurement power around suppliers offering certified sustainable substrates and integrated closure systems.
Lightweighting technology is unifying structural performance with material reduction in glass wide mouth jar production. Owens-Illinois and Verallia have deployed proprietary furnace control algorithms that maintain thermal shock resistance while thinning sidewall gauges by 15-20 percent. Premium olive oil and specialty sauce brands in Italy and California are adopting these formats to offset freight cost inflation, and this unifying trend is compressing competitive differentiation around pure weight-based cost claims.
REACH restriction proposals on per- and polyfluoroalkyl substances are forcing reformulation of barrier coatings for plastic wide mouth jars intended for acidic food contact. European compounders are accelerating migration to silicone dioxide plasma barriers and bio-based polyester alternatives. The organic and natural food segment faces the steepest compliance timeline, with German and Dutch retailers already delisting SKUs lacking PFAS-free certifications.
Consolidated procurement desks at North American private-label food manufacturers are compressing supplier panels and demanding lifecycle assessment documentation. Category managers at these entities now require ISO 14040-compliant carbon footprints for wide mouth jar submissions, displacing spot-buying relationships with packaging distributors. This behavioral shift is most visible in the United States, where Kroger and Albertsons consolidation has reduced qualified jar vendor pools by 30 percent in shelf-stable condiment categories.
Wide Mouth Jars Market Segmentation
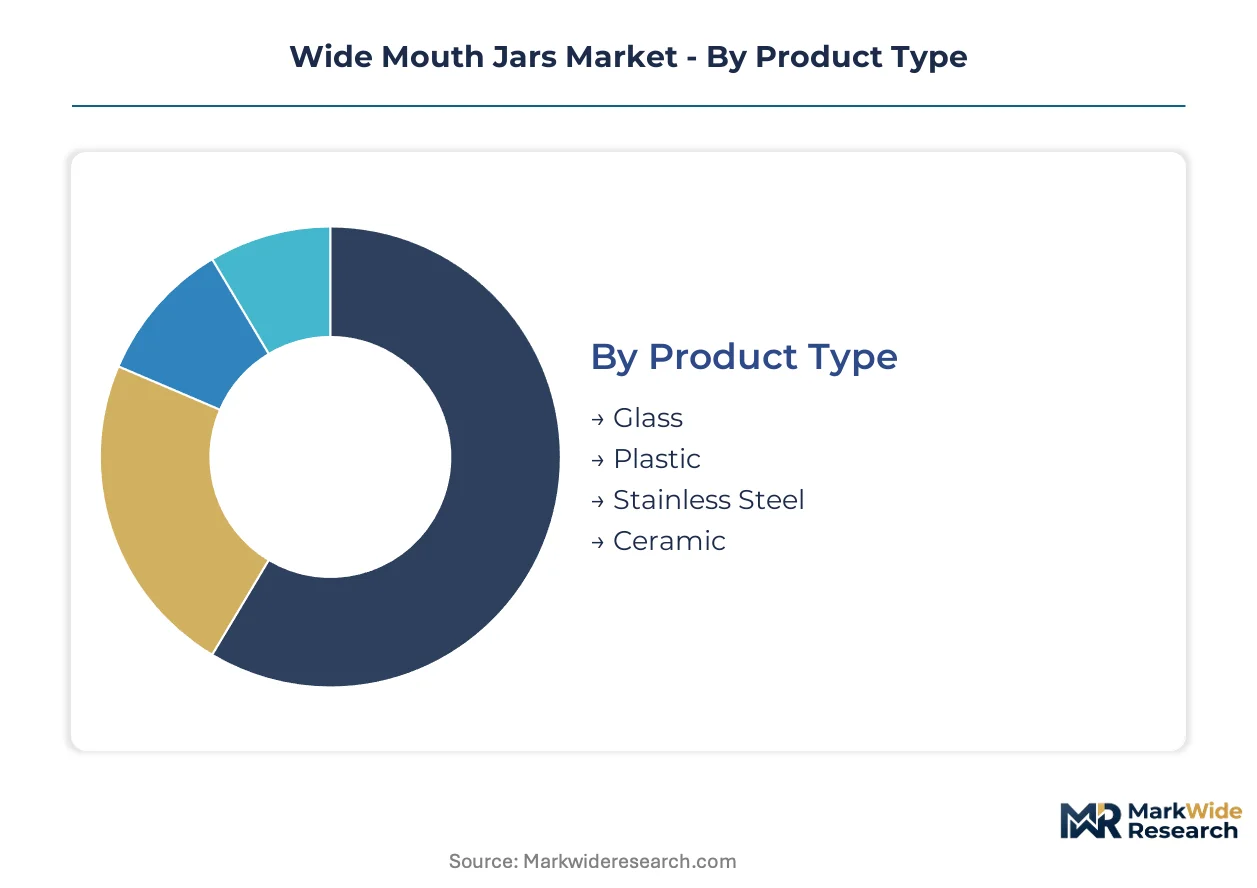
Wide mouth jar procurement decisions hinge on substrate certification status, thermal performance requirements, and filling-line compatibility. Food manufacturers segment their sourcing strategies across material types, end-use applications, and closure systems to balance regulatory compliance with logistics efficiency.
Product Type:
Certification burdens vary sharply by substrate. Glass formats require FDA food-contact material clearance and EU REACH compliance for surface treatments. Plastic variants face SAMR GB standard testing in China and extended migration studies for recycled content. Stainless steel and ceramic formats encounter fewer chemical migration concerns but heavier metal leaching protocols.
- Glass:Soda-lime and borosilicate compositions dominate premium food preservation. Owens-Illinois and Verallia furnace operations in the United States and France supply flint and amber variants to organic sauce brands requiring thermal shock resistance for hot-fill and pasteurization cycles.
- Plastic:PET and HDPE formats with heat-set blow molding capabilities are displacing glass in ready-to-eat soup segments. Berry Global compounds certified polymers for lightweight, shatter-resistant jars that reduce freight damage rates in direct-to-consumer channels.
- Stainless Steel:Airtight food storage applications in camping and outdoor recreation segments favor corrosion-resistant 304-grade containers.
- Ceramic:Artisanal condiment producers in Italy and Spain specify glazed stoneware for premium olive oil and tapenade presentations.
Leading the category by volume: Glass. Growing fastest: Plastic.
End User:
Procurement scale and specification complexity diverge dramatically across buyer types. Household purchasers prioritize retail availability and unit price. Food manufacturers impose lot-level traceability and substrate certification requirements that disqualify spot-market suppliers.
- Food Manufacturers:Consolidated procurement desks at private-label condiment producers in the United States now mandate ISO 14040-compliant carbon footprints and pre-cleared polymer additive libraries, compressing qualified vendor pools by roughly one-third in shelf-stable categories.
- Households:Home-canning resurgence and consumer stockpiling behaviors are expanding retail distribution of mason jars through farm-store channels and direct-to-consumer platforms in Germany and the United States.
- Restaurants:Foodservice operators source bulk wide mouth formats for ingredient storage and batch sauce preparation through B2B platforms that disintermediate traditional packaging distributors.
- Craft Stores:Small-batch artisanal packagers face capital barriers upgrading legacy ERP systems to meet FDA food traceability serialization mandates.
Food manufacturers command the largest procurement volumes. Households are expanding most quickly.
Capacity:
Line speed and filling accuracy requirements shape capacity selection. Smaller formats suit single-serve and sampling applications. Larger containers accommodate foodservice bulk and institutional procurement.
- 500ml:Single-serve condiment and sauce portions for airline and hospitality sampling programs.
- 1000ml:Standard household preservation size for jam and pickle home-canning segments in the United States and Germany.
- 2000ml:Foodservice ingredient storage and restaurant batch preparation formats.
- 3000ml:Industrial-scale food manufacturing and institutional procurement for cafeterias and catering operations.
1000ml formats lead commercial volume. 500ml sizes are gaining share fastest in premium sampling channels.
Closure Type:
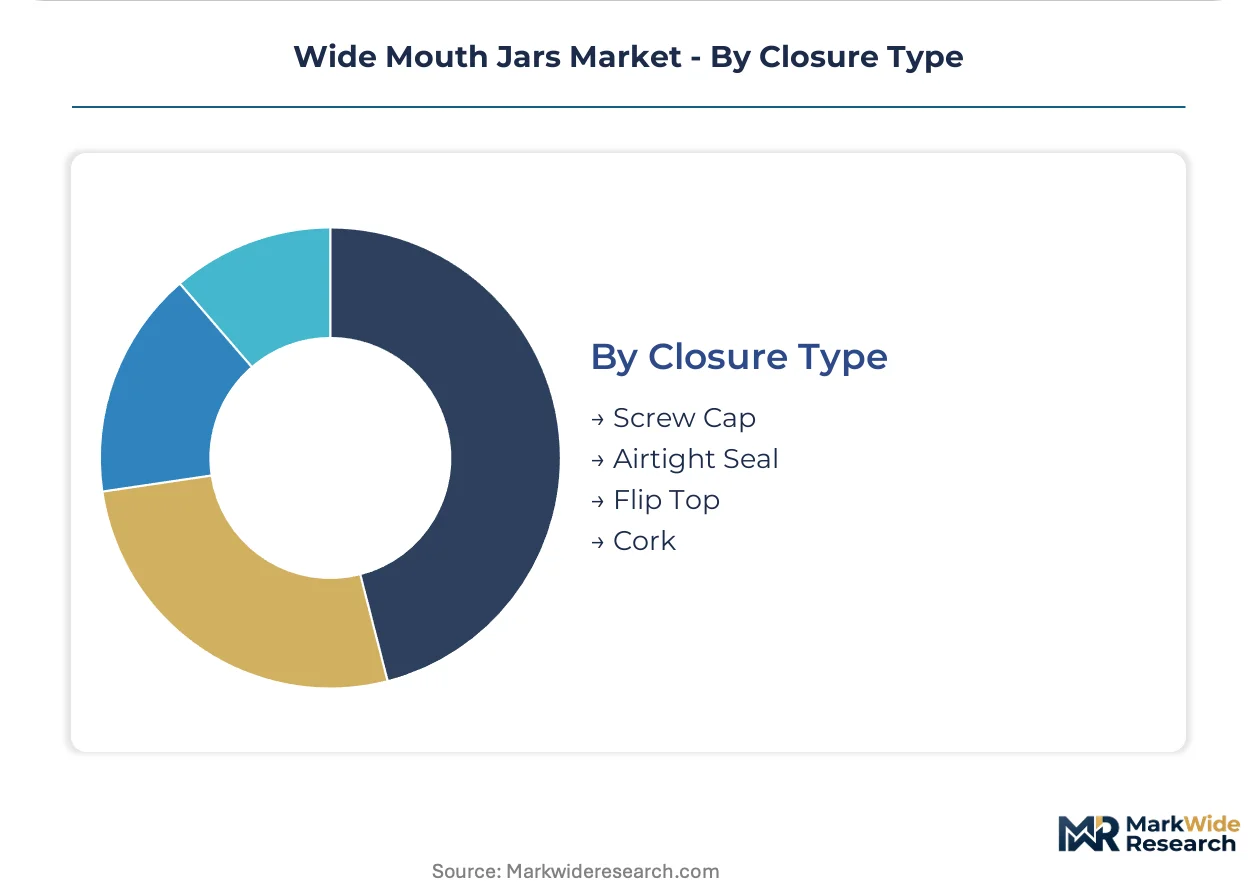
Seal integrity standards and consumer convenience preferences drive closure selection. Screw cap configurations offer resealability and tamper evidence. Airtight systems command margin premiums in organic and natural food channels.
- Screw Cap:Metal lug and continuous thread configurations occupy the largest commercial volume across retail condiment and sauce categories. Aluminum tariff exposure from certain trade corridors is elevating total packaging costs for mid-size processors.
- Airtight Seal:Two-piece lid and gasket systems with vacuum indicators command higher margins in specialty organic channels where oxidation sensitivity affects shelf stability. German and Dutch retailers are already delisting SKUs lacking PFAS-free certifications.
- Flip Top:Hinged polypropylene closures for frequent-access condiment applications in foodservice settings.
- Cork:Natural and synthetic stopper formats for premium olive oil and specialty vinegar presentations in Mediterranean markets.
Screw cap configurations dominate unit volume. Airtight seal systems show the steepest margin expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-purity silica sand deposits in the United States Midwest anchor furnace capacity for soda-lime glass production. Supply chain configurations concentrate jar manufacturing near these feedstock localities and major food-processing clusters.
United States
Private-label retail consolidation at Kroger and Albertsons is compressing qualified vendor pools by roughly one-third in shelf-stable condiment categories. FDA food-contact notification timelines averaging 18-24 months for polymer additives favor incumbent suppliers with pre-cleared material libraries. Owens-Illinois operates furnace capacity in the Midwest sand belt to serve domestic food manufacturers.
Germany
Organic and natural food brands are accelerating procurement of post-consumer recycled glass formats to meet EU Packaging Waste Directive recycled content thresholds. ECHA REACH restriction proposals on PFAS are forcing reformulation of barrier coatings for acidic food contact applications. Verallia maintains furnace operations in the Saarland region to supply premium olive oil and specialty sauce brands.
China
Domestic food packaging demand from private-label retail expansion is driving capacity additions for wide mouth jar production. SAMR enforces GB standards for food packaging material safety, affecting import and domestic sourcing decisions for glass and polymer substrates. Yangtze River Delta manufacturers are scaling output to serve export buyers and domestic food-packaging procurement.
France
Premium food brands specify flint and amber glass formats for thermal shock resistance in hot-fill and pasteurization cycles. EU extended producer responsibility frameworks mandate compliance-ready packaging documentation from suppliers. Verallia's recycled-glass supply chain operations in the Champagne-Ardenne region position formats for organic sauce and preserve segments.
Italy
Artisanal condiment producers in Mediterranean markets specify glazed stoneware and premium glass presentations for olive oil and tapenade packaging. EU F-Gas Regulation constrains blowing-agent chemistry in plastic container production, favoring glass substrate qualification. Emilia-Romagna food manufacturers are consolidating SKU portfolios toward wide mouth formats that reduce filling-line changeover times.
Wide Mouth Jars Market Competitive Landscape
Global majors compete with regional champions across substrate certification and furnace capacity dimensions. The vendor base organizes around three tiers: integrated glass manufacturers with captive sand supply, diversified packaging conglomerates with multi-substrate portfolios, and specialized closure-system suppliers. Strategic moves concentrate on M&A to secure recycled-glass cullet streams and capacity expansion in high-growth food-processing corridors.
Among North American integrated manufacturers, Owens-Illinois Inc. and Ball Corporation occupy positions as archetypes of vertical control over raw-material sourcing and metal closure systems respectively. Berry Global Inc. sits within the diversified packaging tier with plastic jar portfolios. Verallia anchors the European recycled-glass specialist position. These three represent distinct competitive vectors: furnace-scale efficiency, closure-system integration, and sustainability-certified substrate supply.
| Leading Market Players |
|---|
| Ball Corporation |
| Owens-Illinois Inc. |
| Berry Global Inc. |
| Ardagh Group |
| Verallia |
| Berlin Packaging |
| Anchor Hocking |
| Libbey |
| Newell Brands |
| Others |
Value Network & Pricing Analysis
High-purity silica sand futures in the United States Midwest feed directly into furnace capacity planning, cascading through substrate selection decisions that stratify wide mouth jar procurement across premium certified-glass, mid-tier recycled-content polymer, and economy-grade spot-market alternatives.
Pricing Analysis
Warranty-backed substrate certification bundles now separate incumbent suppliers from unbundled spot-market alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects FDA food-contact notification status, ISO 14040 carbon footprint documentation, and volume-scale commitments. Cost compression in mid-tier recycled PET formats is intensifying because polymer additive approval timelines average eighteen to twenty-four months. Private-label food manufacturers exhibit the sharpest price sensitivity, while premium organic brands absorb certification premiums with minimal volume elasticity.
Supply Chain Analysis
Certification gating through FDA, EU REACH, and China SAMR standards concentrates qualified supplier relationships among pre-cleared material libraries. Manufacturing gravity centers on the United States, Germany, and China, with furnace operations in the Midwest sand belt and Yangtze River Delta feeding domestic and export procurement. Raw material dependencies rest on soda-lime silica sand, aluminum closure sheet, and heat-set PET resin. Single-source vulnerability in Midwest high-purity sand mining constrains capacity expansion timelines. Distribution runs through consolidated procurement desks at private-label manufacturers, disintermediating traditional packaging distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EU Packaging Waste Directive recycled content thresholds erect barrier-to-entry moats favoring incumbents with pre-cleared substrate libraries and captive cullet streams.
For Market Incumbents: Deepen backward integration into post-consumer recycled glass cullet streams to secure EU Packaging Waste Directive compliance thresholds before qualification cycles lengthen. Anchor furnace capacity in the United States Midwest sand belt to defend against soda-lime silica sand supply concentration risks. Expand pre-cleared polymer additive libraries to compress FDA food-contact notification timelines for recycled-content formats. For New Entrants and Emerging Players: Aseptic blow-fill-seal integration for ambient-stable dairy and plant-based yogurt formats offers the most penetrable wedge against legacy glass-dependent supply chains. Target craft-store and small-batch artisanal segments where legacy ERP upgrade barriers exclude incumbent distributors. Lead with direct-to-consumer B2B platforms that bypass traditional packaging distributor markups. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap glass manufacturers with stranded furnace capacity in the Saarland and Champagne-Ardenne regions where EU extended producer responsibility frameworks accelerate consolidation. Long-term viability hinges on recycled-glass supply chain control rather than virgin sand access. Watch for China SAMR GB standard harmonization with Codex Alimentarius as the inflection signal opening Western export penetration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled-Glass Cullet Streams | Secures EU Packaging Waste Directive compliance thresholds ahead of competitor qualification cycles. |
| Heat-Set PET Blow Molding Capacity Expansion | Enables pasteurization-temperature substitution for glass in ready-to-eat soup segments. |
| Aseptic Blow-Fill-Seal Technology Deployment | Opens ambient-stable dairy and plant-based yogurt formats without refrigerated distribution. |
| Direct-to-Consumer B2B Platform Launch | Disintermediates traditional packaging distributor markups for foodservice and specialty ingredient buyers. |
| ISO 14040 Carbon Footprint Certification Investment | Meets consolidated procurement desk requirements at Kroger and Albertsons private-label operations. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with glass furnace operations managers, food manufacturer procurement directors, packaging distributor category heads, and SAMR compliance consultants. FDA food-contact notification databases, EU ECHA REACH restriction proposals, China GB standard filings, and SEC 10-K disclosures from integrated packaging manufacturers provided validation anchors. Bottom-up substrate volume modeling and top-down food-processing cluster demand estimation were cross-referenced for triangulation.
Granularity-level modeling distinguished glass, plastic, stainless steel, and ceramic substrates by thermal performance tier and certification status across the projection horizon. Closure type segmentation captured screw cap, airtight seal, flip top, and cork configurations. Capacity modeling addressed 500ml through 3000ml formats. End-user differentiation separated food manufacturer procurement scale from household retail and foodservice channels. CAGRs were derived from substrate-specific volume trajectories weighted by regulatory compliance timelines and furnace capacity expansion announcements.
Forecast precision tightens around the base case; tail outcomes carry wider variance under aluminum tariff regime shifts or Midwest sand mining permit delays. Forecasts reflect assumptions regarding EU Packaging Waste Directive implementation pacing and China private-label retail expansion velocity. A model refresh is warranted upon material change in FDA food-contact notification processing timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Trays Market
Containers
Container Stacking Machine Market
Containers
Stackable Plastic Trays Market
Containers
Foldable Large Containers Market
Containers
Gable Top Container Market
Containers
Kuwait Container Glass Market
Containers
Injection Molding Containers Market
Containers
HDPE Blow Molding and Injection Molding Containers Market
Containers
Canisters Market
Containers
Acrylic Container Market
Containers
Metal Crates Market
Containers
Sample Containers Market
Containers
HDPE Bottles Market
Containers
Middle East and Africa Plastic Bottles and Containers Market
Containers
Stock Clamshell Packaging Market
Containers
PVC Container Market