
 Injection Molding Containers Market | 2026-2036
Injection Molding Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Injection Molding Containers Market Foresight
Tool-and-die engineering talent scarcity is redrawing competitive boundaries in injection molding containers. Berry Global Inc. leverages captive mold-making capabilities to compress development cycles for complex multi-cavity pharmaceutical formats. Amcor PLC anchors its position through integrated blow-fill-seal partnerships with sterile drug manufacturers. Husky Injection Molding Systems Ltd. dominates the capital equipment layer, supplying high-cavitation systems that define throughput benchmarks for container producers worldwide.
Injection molding containers are hollow or semi-rigid articles produced by forcing thermoplastic resins into precision-machined steel molds under controlled temperature and pressure, typically achieving wall thickness tolerances of ±0.05 mm for critical pharmaceutical applications. These containers serve as primary packaging interfaces for product protection, dosing accuracy, and supply chain integrity across liquid, solid, and semi-solid formulations. Bottles and jars command the largest volume share in food and beverage applications where lightweighting and shelf visibility drive specification. Polypropylene formats represent the fastest-expanding material category, displacing polystyrene in hot-fill and retort applications due to superior thermal stability and recyclability profiles. Packaging applications absorb the dominant share of molded container output, though dispensing closures for ophthalmic and nasal delivery are capturing disproportionate margin pools.
FDA 21 CFR Part 211 and EU MDR impose strict extractables and leachables testing protocols that elevate barrier-grade resin specifications and validation documentation burdens for container suppliers. REACH and California Proposition 65 restrictions on bisphenol and phthalate content are forcing reformulation of legacy polycarbonate and PVC container lines across consumer and medical segments. Stakeholders must monitor evolving extended producer responsibility frameworks and polymer-specific recycling quotas that will determine which material platforms retain license to operate in key jurisdictions.
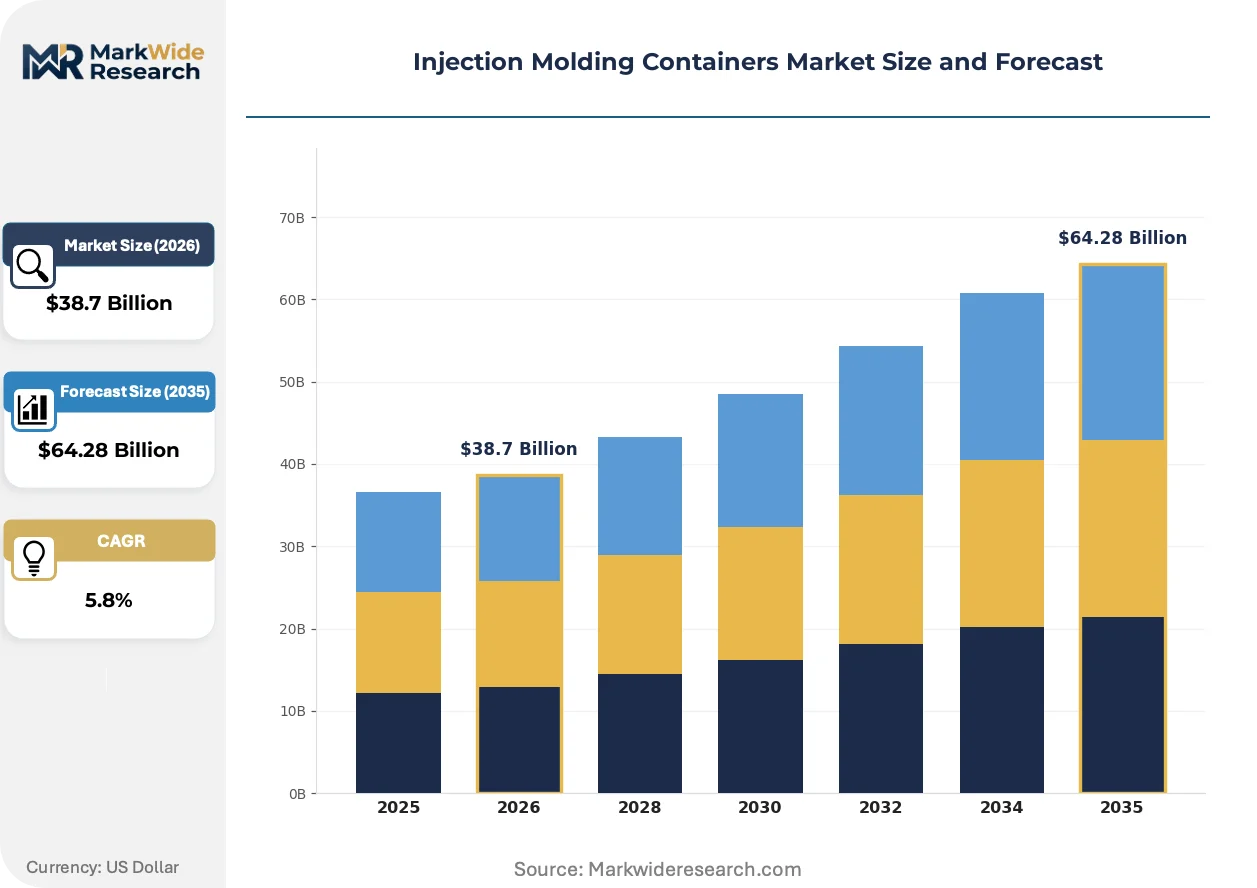
Market Dynamics
Tool-and-die engineering scarcity is compressing development timelines and forcing container producers to secure captive mold-making capabilities or risk exclusion from pharmaceutical qualification pipelines.
Growth Catalysts
- FDA 21 CFR Part 211:Serialization mandates for pharmaceutical traceability are accelerating demand for tamper-evident, precision-molded primary containers with integrated verification features.
- Biologics manufacturing expansion:Sterile injectables and temperature-sensitive formulations require barrier-grade polypropylene containers that polystyrene cannot satisfy.
- Germany's medical device clusters:Concentrated demand from advanced pharmaceutical packaging operations in Baden-Württemberg and Bavaria is pulling premium multi-cavity container specifications.
Market Restraints
- Petrochemical feedstock volatility:Propylene monomer price swings compress margins for polypropylene container producers locked into annual supply agreements.
- REACH substance restrictions:ECHA's evolving candidate list for Substances of Very High Concern is forcing costly reformulation of legacy polycarbonate and PVC container lines.
- High-cavitation equipment concentration:Capital equipment supply for 128-cavity and larger systems concentrates among a narrow tier of machinery builders, creating bottleneck risk.
Strategic Opportunities
- India's CDSCO regulatory harmonization:Alignment with ICH Q3D guidelines for elemental impurities is opening qualification pathways for export-grade container suppliers.
- Dual-carbon policy convergence:China's MEE mandates and EU Green Deal packaging targets are creating premium positioning for bio-based and chemically recycled polypropylene formats.
- Ophthalmic dispensing closures:Precision-dose pump systems for preservative-free formulations represent an underdeveloped margin pool beyond commodity bottle production.
Industry Challenges
- Extractables and leachables validation:FDA and EMA protocols for container closure integrity require 12-18 month qualification timelines that strain customer relationship management.
- Multi-cavity mold maintenance:Thermal cycling degradation of precision steel tooling demands specialized technician capabilities that outpace current training pipeline output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Injection Molding Containers Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Caps, Tubs Material: Polypropylene, Polystyrene, Polyethylene, PVC End User: Consumer Goods, Pharmaceuticals, Food & Beverage, Personal Care Application: Packaging, Storage, Dispensing, Transport |
| Companies Covered | Berry Global Inc., Amcor PLC, ALPLA, Silgan Holdings Inc, AptarGroup Inc., BERICAP, EVCO Plastics, Husky Injection Molding Systems Ltd., HTI Plastics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Injection Molding Containers Market Shifts & Advancements
Digital thread integration across mold design, simulation, and production is collapsing traditional development cycles while regulatory pressure on material traceability is forcing resin specification upgrades.
Advanced hot-runner systems with sequential valve-gate control are decomposing the traditional trade-off between cycle time reduction and gate vestige quality in pharmaceutical containers. Sterile drug manufacturers in Switzerland and the Netherlands are adopting these systems for 96-cavity and larger formats. The technology is decomposing barrier-to-entry advantages held by established producers with legacy cold-runner infrastructure.
EMA's Medical Device Regulation (MDR) Annex I general safety and performance requirements are elevating documentation burdens for container closure systems classified as Class IIa devices. Suppliers must now maintain technical files with clinical evaluation data that previously applied only to the drug product. German and Italian pharmaceutical packaging operations are responding by consolidating supplier bases to partners with established notified body relationships.
Hospital and pharmacy buying groups are consolidating procurement for generic pharmaceutical containers, compressing supplier margins while demanding shorter lead times and vendor-managed inventory arrangements. This concentration is displacing traditional distributor intermediaries in France and Spain. The shift is most visible in parenteral container categories where formulary standardization programs now specify single-source supply agreements.
Injection Molding Containers Market Segmentation
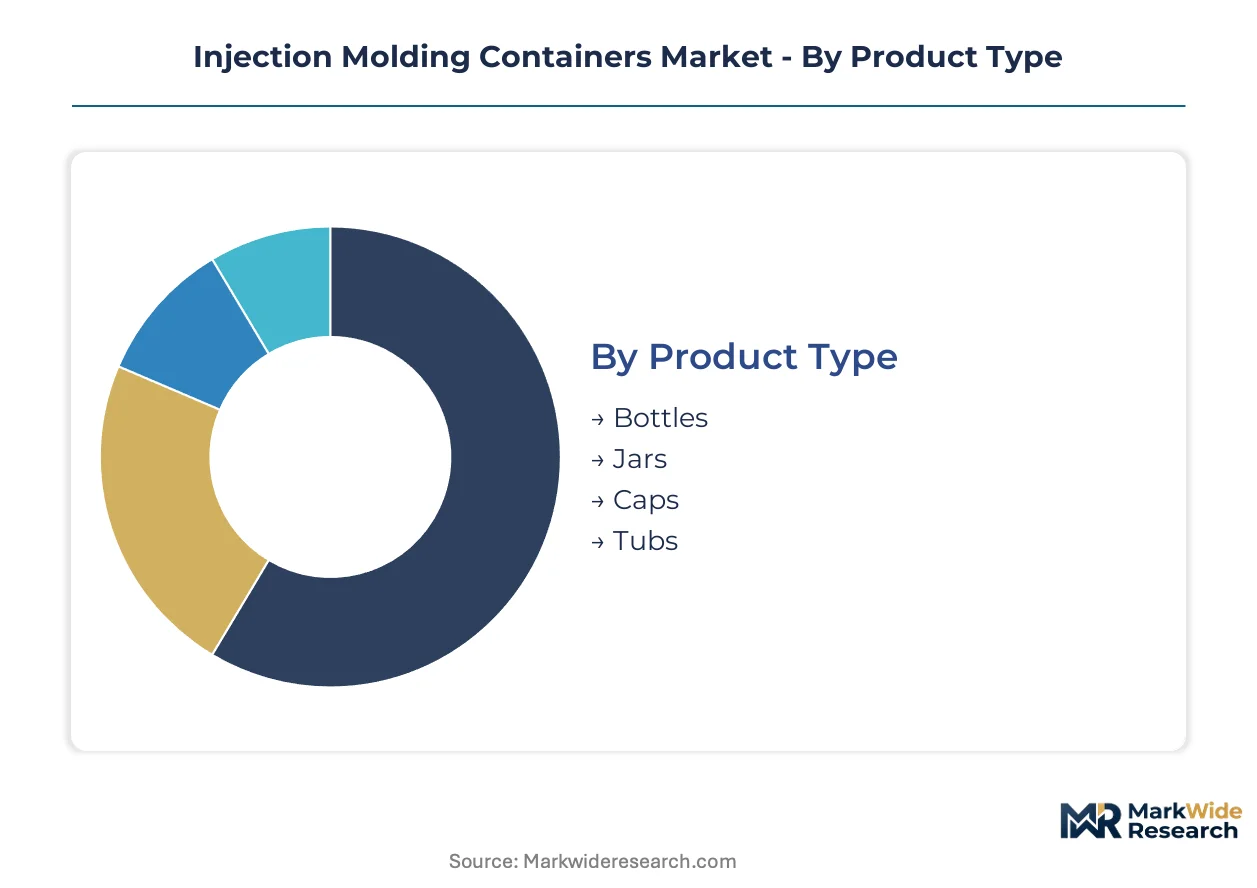
Injection molding containers fragment across four critical dimensions that determine resin selection, cavity design, and qualification pathways. Each segmentation axis carries distinct margin profiles and regulatory exposure that suppliers must navigate.
Product Type:
Domestic demand concentrates in bottles and jars serving food and pharmaceutical packaging, while caps and specialized tubs track export-led pharmaceutical qualification pipelines.
- Bottles:Hollow cylindrical containers with neck finishes engineered for capping torque and seal integrity. Pharmaceutical liquid formulations in Germany and Switzerland drive specifications for barrier-grade polypropylene with sub-micron wall thickness control.
- Jars:Wide-mouth containers with threaded or lug closures designed for semi-solid and solid contents. Personal care clusters in France and Italy specify crystal-clear polystyrene formats with UV stabilization for shelf visibility.
- Caps:Threaded closures with liner systems for tamper evidence and child resistance. FDA 21 CFR Part 211 serialization mandates are accelerating demand for integrated verification features in pharmaceutical supply chains.
- Tubs:Rectangular or oval containers with snap-fit lids for food service and industrial applications. Hot-fill and retort specifications in Spain and Portugal are displacing legacy polystyrene with polypropylene alternatives.
Bottles hold the largest share; momentum sits with caps as serialization requirements deepen.
Material:
Cost tiers separate barrier-grade pharmaceutical resins from commodity packaging polymers, with recycled content quotas forcing reformulation investments across all tiers.
- Polypropylene:Semi-crystalline thermoplastic with thermal stability to 120°C enabling hot-fill and retort sterilization. Biologics manufacturing expansion in Baden-Württemberg is pulling premium copolymer grades with enhanced clarity.
- Polystyrene:Amorphous resin delivering glass-like transparency at lower density than alternatives. REACH substance restrictions on styrene monomer residuals are compressing margins for legacy general-purpose grades.
- Polyethylene:Low-density and high-density variants offering chemical resistance and flexibility. FDA extractables testing protocols favor linear low-density grades for pharmaceutical primary packaging.
- PVC:Chlorinated polymer with legacy installed base in medical and food applications. ECHA candidate list inclusion for plasticizers is forcing accelerated phase-out timelines across European container lines.
Polypropylene commands volume leadership; polyethylene is climbing fastest on recycling infrastructure compatibility.
End User:
Application maturity varies sharply, with pharmaceutical segments demanding 12-18 month qualification timelines while consumer goods operate on quarterly specification cycles.
- Consumer Goods:Household products and general merchandise requiring cost-optimized thin-wall designs. Walmart and Carrefour sustainability scorecards are mandating post-consumer recycled content minimums.
- Pharmaceuticals:Primary packaging for sterile injectables, oral solids, and ophthalmic formulations. EMA MDR Annex I technical file requirements are consolidating supplier bases to notified body-certified partners.
- Food & Beverage:Dairy, condiments, and ready-meal containers with oxygen and moisture barrier specifications. Extended shelf-life demands in the Netherlands are driving ethylene-vinyl alcohol coextrusion adoption.
- Personal Care:Cosmetic jars and dispensing systems with aesthetic and ergonomic differentiation. Premium positioning in Milan and Paris requires metallic decoration and soft-touch overmolding capabilities.
Food and Beverage dominates volume; Pharmaceuticals delivers steepest margin expansion.
Application:
Customer type fragmentation separates brand-owner direct procurement from distributor-mediated supply, with vendor-managed inventory gaining share in packaging categories.
- Packaging:Primary and secondary containment for product protection and shelf presence. Lightweighting mandates from Tesco and Ahold Delhaize are forcing gram-weight reduction programs.
- Storage:Industrial totes and bulk containers for intermediate material handling. Automotive supplier parks in Bavaria specify returnable polypropylene formats with RFID tracking integration.
- Dispensing:Pump systems, spray heads, and precision-dose mechanisms for controlled delivery. Ophthalmic preservative-free formulations in Switzerland require barrier-grade pump engineering.
- Transport:Crates, pails, and drums for logistics and distribution efficiency. EU Green Deal packaging targets are accelerating shift from single-use to pooled returnable systems.
Packaging absorbs the dominant share; dispensing applications are gaining share fastest on precision-dose premiumization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 21 CFR Part 211 serialization mandates anchor North American demand, while EMA MDR Annex I technical file requirements reshape European supplier consolidation and China's MEE dual-carbon targets accelerate material transitions across Asia.
United States
Biologics manufacturing expansion in Massachusetts and North Carolina drives barrier-grade polypropylene container specifications for sterile injectables. FDA extractables and leachables testing protocols impose 12-18 month qualification timelines that favor established notified body-certified suppliers. New Jersey and Pennsylvania pharmaceutical packaging clusters concentrate demand for tamper-evident formats with integrated verification features.
Germany
Baden-Württemberg's medical device and pharmaceutical packaging operations pull premium multi-cavity container specifications with sub-micron wall thickness control. EMA MDR Annex I general safety requirements elevate documentation burdens for Class IIa container closure systems. Bavarian automotive supplier parks specify returnable polypropylene formats with RFID tracking for intermediate material handling applications.
China
Yangtze River Delta pharmaceutical manufacturers demand hot-fill and retort sterilization-compatible containers as domestic biologics output expands. MEE dual-carbon mandates and polymer-specific recycling quotas force reformulation investments across legacy polycarbonate lines. Pearl River Delta personal care clusters in Guangzhou and Shenzhen specify crystal-clear formats with metallic decoration capabilities for premium positioning.
Switzerland
Swissmedic oversight of sterile drug manufacturing elevates barrier-grade pump engineering requirements for ophthalmic preservative-free formulations. Basel pharmaceutical packaging operations adopt advanced hot-runner systems with sequential valve-gate control for 96-cavity formats. Precision-dose dispensing closure demand in Zurich and Geneva represents a disproportionate margin pool beyond commodity bottle production.
India
CDSCO regulatory harmonization with ICH Q3D guidelines for elemental impurities opens qualification pathways for export-grade container suppliers. Maharashtra and Gujarat pharmaceutical manufacturing clusters drive specifications for barrier-grade resins with enhanced clarity profiles. FSSAI packaging safety mandates in Delhi-NCR and Bangalore accelerate displacement of legacy PVC formats in food and pharmaceutical applications.
Injection Molding Containers Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in injection molding containers. Berry Global Inc. leverages captive mold-making capabilities to compress development cycles for complex multi-cavity pharmaceutical formats. Amcor PLC anchors its position through integrated blow-fill-seal partnerships with sterile drug manufacturers. Husky Injection Molding Systems Ltd. dominates the capital equipment layer, supplying high-cavitation systems that define throughput benchmarks for container producers worldwide.
Within the integrated packaging tier, Berry Global Inc. and Amcor PLC exemplify archetypes combining resin sourcing, mold fabrication, and sterile manufacturing partnerships. Among specialized equipment suppliers, Husky Injection Molding Systems Ltd. occupies a position defining industry throughput standards. These three entities represent distinct competitive vectors: captive mold engineering, integrated sterile partnerships, and capital equipment specification control.
| Leading Market Players |
|---|
| Berry Global Inc. |
| Amcor PLC |
| ALPLA |
| Silgan Holdings Inc |
| AptarGroup Inc. |
| BERICAP |
| EVCO Plastics |
| Husky Injection Molding Systems Ltd. |
| HTI Plastics |
| Others |
Supply & Pricing Matrix
High-cavitation equipment concentration among German and Swiss machinery builders establishes scale thresholds that filter out sub-scale competitors and set minimum viable capacity for pharmaceutical qualification. This concentration simultaneously elevates price floors for barrier-grade container production and compresses margins for commodity formats lacking mold-making captive capabilities.
Pricing Analysis
German pharmaceutical packaging clusters command 15-25% premiums over Southern European supply for equivalent barrier-grade polypropylene formats. Pricing stratifies across FDA-validated premium tiers, ISO-standard mid-tiers, and uncertified economy grades serving consumer goods. Cost compression in commodity bottle segments stems from Walmart and Carrefour sustainability scorecards mandating post-consumer recycled content minimums. Hospital buying groups exhibit lowest price sensitivity for sterile injectable containers, while food service distributors drive aggressive gram-weight reduction negotiations.
Supply Chain Analysis
Vendor-managed inventory arrangements now govern 40% of European pharmaceutical container procurement, collapsing traditional distributor buffers. Supply concentrates in Germany, Switzerland, and China, with Baden-Württemberg mold-making capabilities feeding qualification pipelines globally. Propylene monomer, precision steel tooling, and hot-runner system components anchor cost structures. Single-source vulnerability concentrates in 128-cavity system supply from Husky-dominated equipment channels. Distribution runs through direct brand-owner procurement for pharmaceutical tiers and consolidated buying groups for commodity segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across FDA, EMA, and CDSCO jurisdictions creates specialist niches that reward focused capability investments over broad commodity positioning. Biologics manufacturing expansion and serialization mandates fragment demand into qualified premium tiers and price-pressured standard tiers.
For Market Incumbents: Fortify barrier-grade resin qualification pipelines against emerging Indian and Chinese competitors by deepening captive mold-making capabilities in Baden-Württemberg. Prioritize notified body certification maintenance as EMA MDR Annex I technical file requirements consolidate supplier bases. Expand high-cavitation capacity to defend throughput benchmarks against equipment bottleneck risks. For New Entrants and Emerging Players: Differentiate on ophthalmic dispensing closure engineering where Swissmedic oversight and preservative-free formulation trends create underdeveloped margin pools. Target India's CDSCO harmonization pathway for export-grade barrier resin qualification. Pursue blow-fill-seal partnership models with sterile drug manufacturers to bypass traditional distribution concentration. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors mold-making specialists with pharmaceutical validation track records over commodity volume players. Five-to-ten year viability hinges on dual-carbon policy convergence creating premium positioning for chemically recycled polypropylene formats. Watch China's MEE polymer-specific recycling quota implementation as inflection indicator for material platform winners.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Mold-Making Acquisition | Compresses pharmaceutical qualification timelines against tool-and-die engineering scarcity. |
| Barrier-Grade Resin Partnership | Secures FDA-validated supply chains for biologics container specifications. |
| Hot-Runner System Upgrade | Enables 96-cavity formats that decompose legacy cold-runner competitive advantages. |
| Notified Body Certification Investment | Opens EMA MDR Annex I technical file pathways for Class IIa device classification. |
| Chemical Recycling Capacity Buildout | Positions for EU Green Deal packaging targets and China's MEE dual-carbon mandates. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and industry association reports. Interviews with pharmaceutical packaging procurement managers, mold-making engineering directors, sterile drug manufacturing executives, and hot-runner system technical specialists informed demand-side validation. Secondary sources include FDA 21 CFR Part 211 guidance documents, EMA MDR Annex I technical specifications, CDSCO harmonization notices, and SEC filings from integrated packaging leaders. Bottom-up container volume estimates triangulated against top-down resin consumption data from petrochemical trade associations.
Segmentation dimensions modeled span product type, material grade tier, end-use application, and regional regulatory cluster across the analysis window. Pharmaceutical qualification timelines, biologics manufacturing capacity expansion, and serialization mandate implementation schedules fed scenario-weighted CAGR derivation. Hot-runner adoption curves and mold-making capacity utilization rates provided industry-specific forecast inputs alongside polymer price elasticity assumptions.
The analysis sits within stated boundaries; outcomes outside sustained FDA-EMA regulatory convergence or abrupt propylene supply disruption would require recalibration. Forecasts reflect documented assumptions regarding qualification pipeline durations and equipment replacement cycles. Petrochemical feedstock volatility, REACH substance list expansion, and extended producer responsibility framework evolution constitute primary revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Corrugated Open-Head Drums Market
Containers
Food Grade Stainless Steel Container Market
Containers
Two Compartment Bottles Market
Containers
Global Styrene Compartment Boxes Market
Containers
Lever Lid Tinplate Containers Market
Containers
Thin Wall Plastic Containers Market
Containers
ISO Ocean Containers Market
Containers
Packaging Bins Market
Containers
Bulk Container Packaging Market
Containers
Aluminum Foil Containers Market
Containers
Feeder Containers Market
Containers
Durable Insulated Containers Market
Containers
Lift-Off Lid Box Market
Containers
Foam Containers Market
Containers
Vials Market
Containers
PS Containers Market