
 Stackable Plastic Trays Market | 2026-2036
Stackable Plastic Trays Market Size, Share, and Industry Trends Forecast 2026-2036
Stackable Plastic Trays Market Analytics
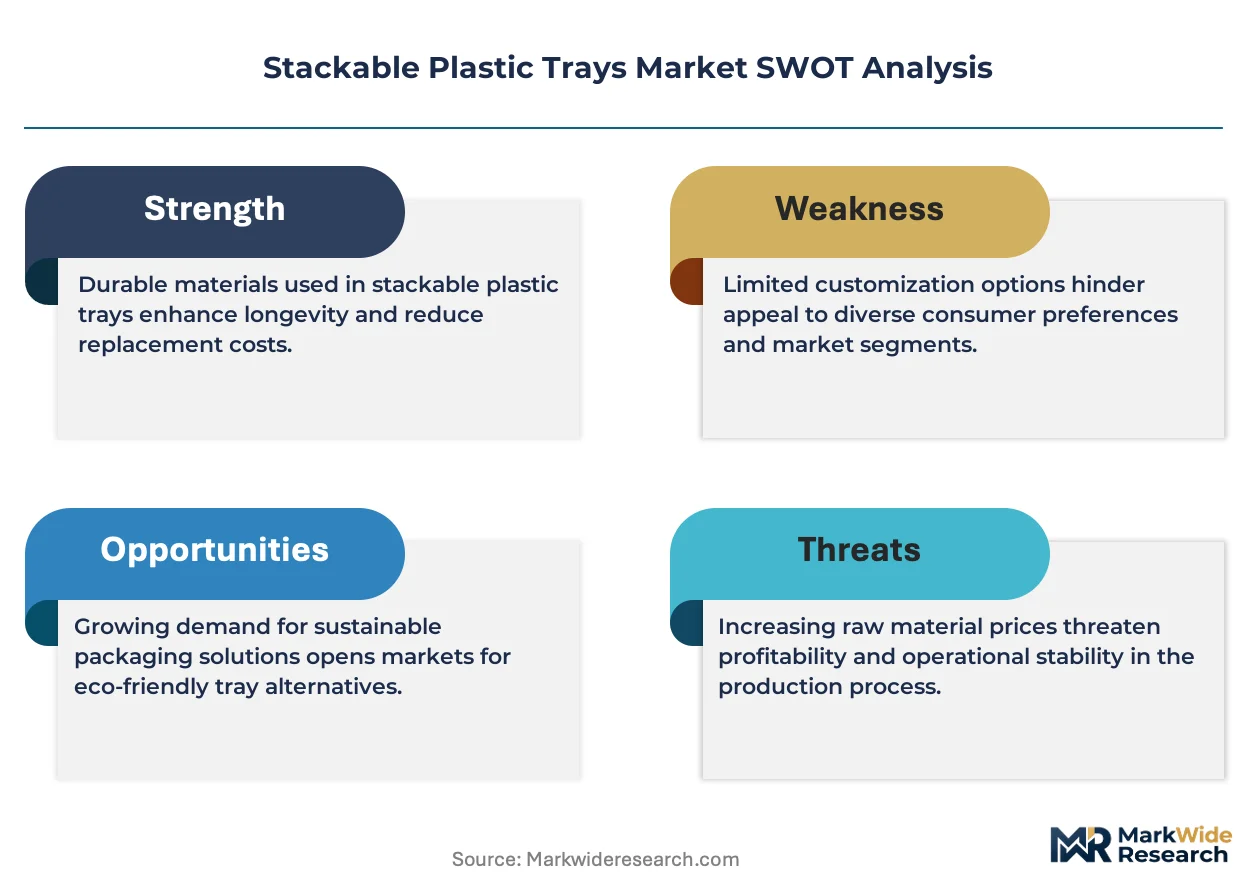
Skilled mold technicians is unwinding capacity expansion across European and North American manufacturing bases. Schoeller Allibert leverages its captive injection-molding network to serve automotive just-in-sequence programs. Rehrig Pacific anchors North American produce distribution through proprietary nestable designs. Berry Global Inc. competes on multi-layer barrier technology for protein packaging applications.
Stackable plastic trays are injection-molded or thermoformed receptacles with standardized footprint dimensions and interlocking features, typically fabricated from polypropylene or high-density polyethylene to withstand repeated sanitization cycles and mechanical stacking loads. Their primary purpose spans unitized goods movement, retail display, and sterile item containment across supply chains. Polypropylene formulations lead material selection for steam-sterilizable medical and food service trays, while polyethylene dominates industrial logistics for its impact resistance at low temperatures. Food service end users represent the deepest margin pool due to compliance-driven replacement cycles, though logistics buyers generate the highest unit volumes in e-commerce fulfillment networks.
FDA food contact substance notifications govern resin approvals for direct-food applications in the United States, while REACH and EU Packaging and Packaging Waste Directive shape material compliance obligations across European markets. California's SB 54 mandates source reduction and recyclability thresholds that filter tray specifications for brands distributing in that state. Stakeholders must monitor evolving extended producer responsibility frameworks and resin recycling infrastructure investments to validate circular-economy claims before procurement committees.
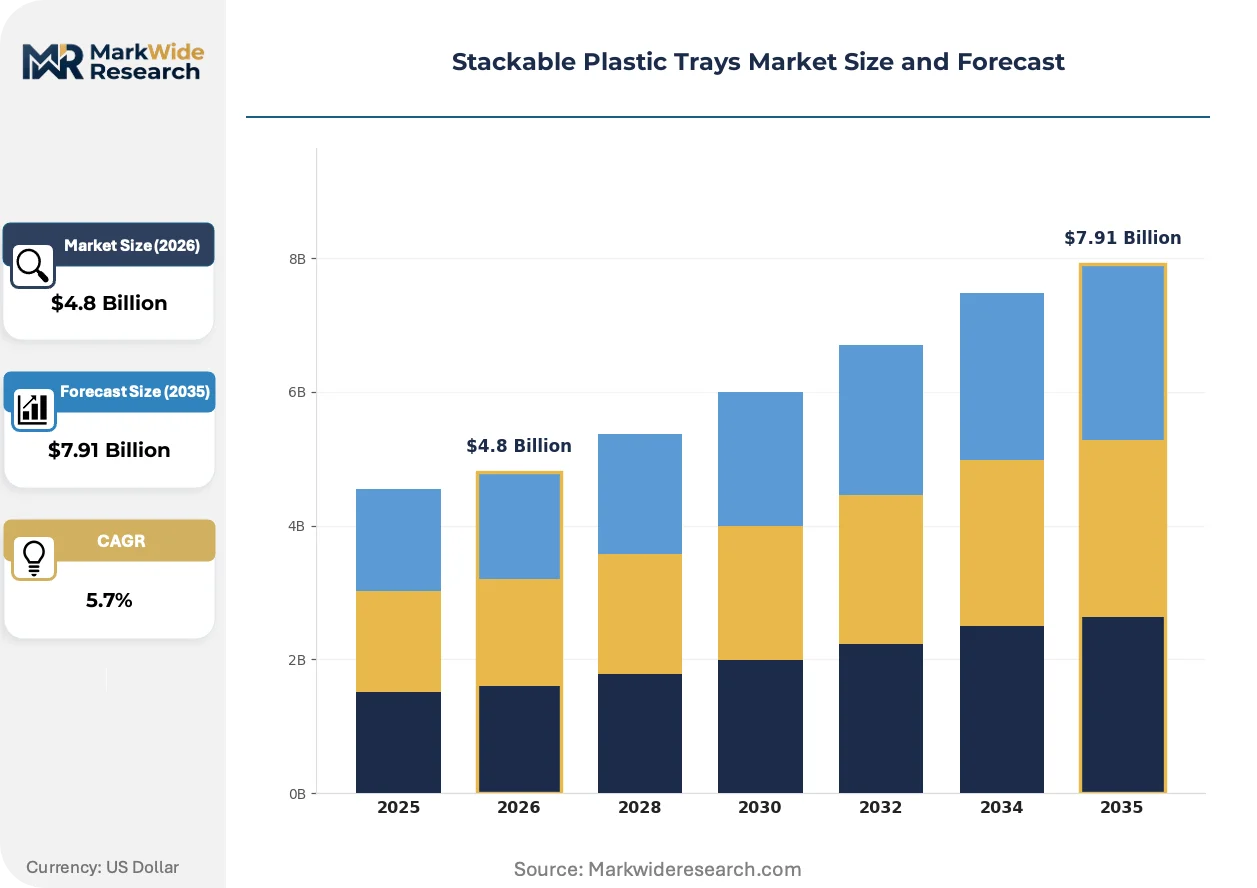
Market Dynamics
EU Single-Use Plastics Directive enforcement is compressing virgin resin demand across food service supply chains while simultaneously opening premium pricing tiers for certified recycled-content trays. Mold technology upgrades and skilled technician scarcity now govern capacity expansion feasibility more than raw capital availability.
Growth Catalysts
- EU Packaging and Packaging Waste Directive:Mandatory recyclability thresholds force brand owners toward reusable tray formats in German automotive logistics corridors and French retail distribution networks.
- Steam-sterilizable polypropylene formulations:Hospital central sterile supply departments in the American Midwest and pharmaceutical hubs replace metal instrument trays with lighter polymer alternatives.
- E-commerce fulfillment density requirements:Third-party logistics providers in the Netherlands and Belgium specify nestable tray footprints to maximize cube utilization in automated storage systems.
Market Restraints
- Propylene feedstock volatility:European crackers tied to naphtha pricing expose tray molders to margin compression when olefin spreads widen.
- Injection mold fabrication concentration:Tooling lead times from specialized Chinese and South Korean die shops extend new product qualification cycles by 8-14 weeks.
- Mechanical recycling contamination limits:FDA food contact substance notification pathways for post-consumer resin remain narrower than brand sustainability commitments require.
Strategic Opportunities
- Underpenetrated Indian pharmaceutical cold chain:Temperature-stable HDPE trays for vaccine distribution remain below 15% penetration versus European benchmarks.
- California SB 54 compliance services:Source reduction auditing and recyclability certification create recurring revenue attachments for tray suppliers serving CPG brands.
- RFID-embedded tray tracking:Convergence of molded-in antennas and cloud-based asset management platforms enables per-use pricing models in closed-loop rental programs.
Industry Challenges
- Skilled mold technician scarcity:European apprenticeship pipelines produce fewer than 400 qualified process engineers annually against replacement demand.
- Multi-jurisdiction certification timelines:Parallel FDA, EFSA, and Health Canada food contact approvals extend product launch windows by 18-24 months.
- Legacy warehouse management system integration:Nestable tray dimensions often conflict with pallet pattern algorithms in older distribution center software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stackable Plastic Trays Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Trays, Industrial Trays, Medical Trays, Storage Trays Material: Polypropylene, Polyethylene, PVC, PET End User: Food Service, Retail, Healthcare, Logistics Size: Small, Medium, Large, Extra Large |
| Companies Covered | Berry Global Inc., Pactiv Evergreen, Schoeller Allibert, Rehrig Pacific, Huhtamaki, Sonoco Products Company, Sealed Air, Genpak, IPL Plastics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stackable Plastic Trays Market Evolving Landscape
Active material science breakthroughs and regulatory compliance automation are compressing product development cycles while simultaneously fragmenting supplier tiers into specialized technology licensors versus volume molders.
Post-consumer recycled polypropylene with melt-flow stabilization is displacing virgin resin in food contact applications across Nordic retail produce programs. ICA Gruppen and S Group specify 30% minimum recycled content thresholds in their 2024-2026 produce tray tenders. This displacement is compressing margins for commodity resin distributors while creating certification-based pricing power for compounders with EFSA-approved recycling process registrations.
California SB 54 mandates source reduction and recyclability thresholds that filter tray specifications for brands distributing in that state. The regulation requires 25% source reduction by weight against 2018 baselines and mandates that all packaging be recyclable or compostable by 2032. Protein packagers in the Central Valley are responding by consolidating SKUs into standardized tray footprints that qualify for mechanical recycling streams rather than multi-material barrier laminates.
Centralized procurement committees now mandate lifecycle cost documentation including washing, repair, and end-of-life recovery fees rather than unit purchase price alone. Food service operators in the Netherlands and Belgium are replacing transactional spot buying with five-year closed-loop rental contracts where tray fleet management transfers to specialized pooling providers. This behavioral shift is most visible in Belgian hospital group purchasing organizations where sterilization service integration now outweighs mold cost in vendor selection criteria.
Stackable Plastic Trays Market Segmentation
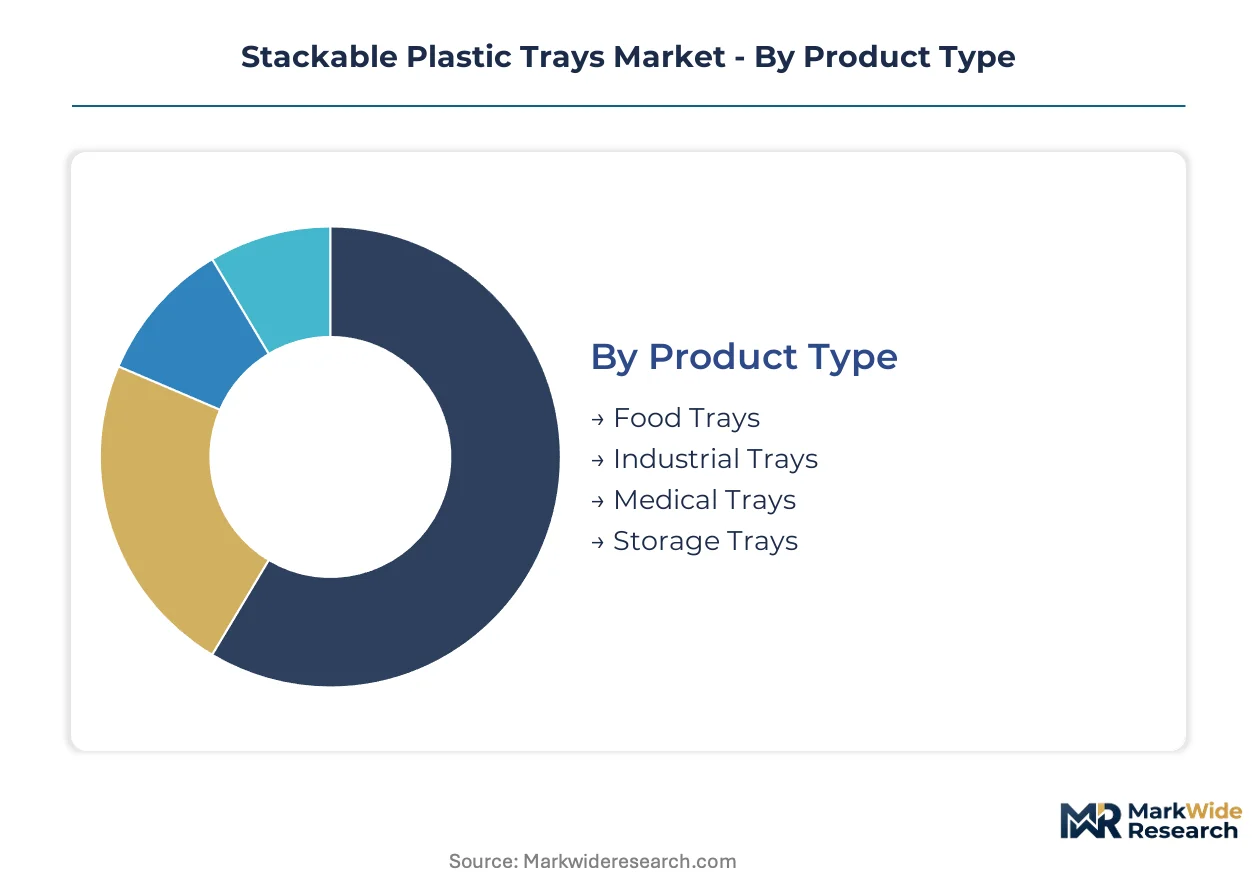
Tray specifications diverge sharply by use environment, with food contact compliance, sterilization protocols, and load-bearing requirements driving incompatible material and design choices. Channel economics favor specialized fabricators over generalists, as certification investments create segment-specific moats.
Product Type:
Food trays and industrial trays move through divergent distribution channels, with food service operators procuring through group purchasing organizations while logistics buyers source direct from molders for fleet standardization.
- Food Trays:Injection-molded polypropylene formats with FDA food contact substance notifications dominate quick-service restaurant chains and institutional catering. Steam-sterilizable variants capture hospital central sterile supply departments across the American Midwest, where metal-to-plastic conversion accelerates.
- Industrial Trays:High-density polyethylene constructions withstand impact at sub-zero temperatures across automotive component logistics corridors in Germany. Nestable designs maximize cube utilization in automated storage systems serving e-commerce fulfillment networks in the Netherlands and Belgium.
- Medical Trays:Validated for steam and ethylene oxide sterilization cycles in pharmaceutical distribution hubs.
- Storage Trays:General-purpose formats for warehouse organization and archival applications.
Industrial trays dominate installed base by unit volume. Food trays are where expansion concentrates as EU Single-Use Plastics Directive enforcement accelerates reusable format adoption.
Material:
Cost tiers separate by thermal performance and regulatory approval burden, with medical-grade polypropylene commanding premium pricing over commodity polyethylene for logistics.
- Polypropylene:Steam-sterilizable formulations lead medical and food service applications, with melt-flow-stabilized post-consumer recycled grades displacing virgin resin in Nordic retail produce programs. EFSA-approved recycling process registrations create certification-based pricing power for compounders serving ICA Gruppen and S Group tenders.
- Polyethylene:HDPE dominates industrial logistics for impact resistance at low temperatures, with temperature-stable formulations penetrating below 15% of Indian pharmaceutical cold chain versus European benchmarks. LDPE variants serve lighter-duty storage applications.
- PVC:Declining share in food contact due to regulatory pressure under REACH and state-level restrictions.
- PET:Emerging in transparent retail display applications requiring visual product verification.
Polypropylene captures the steepest expansion trajectory through sterilization service integration. Polyethylene retains volume leadership in closed-loop rental fleet deployments.
End User:
Customer type determines procurement modality, with healthcare and food service shifting toward outcome-based contracts while retail and logistics favor capital purchase.
- Food Service:Quick-service restaurants and institutional caterers drive compliance-driven replacement cycles, with California SB 54 mandating source reduction and recyclability thresholds. Centralized procurement committees now mandate lifecycle cost documentation including washing, repair, and end-of-life recovery fees.
- Healthcare:Hospital central sterile supply departments and pharmaceutical distribution hubs specify steam-sterilizable formats, with Belgian group purchasing organizations prioritizing sterilization service integration over mold cost in vendor selection.
- Retail:Supermarket produce departments specify minimum recycled content thresholds in tender processes.
- Logistics:Third-party providers prioritize nestable footprints for automated storage density.
Food service generates the deepest margin pool through rental contract attachment. Healthcare is climbing the fastest as metal-to-polymer conversion accelerates.
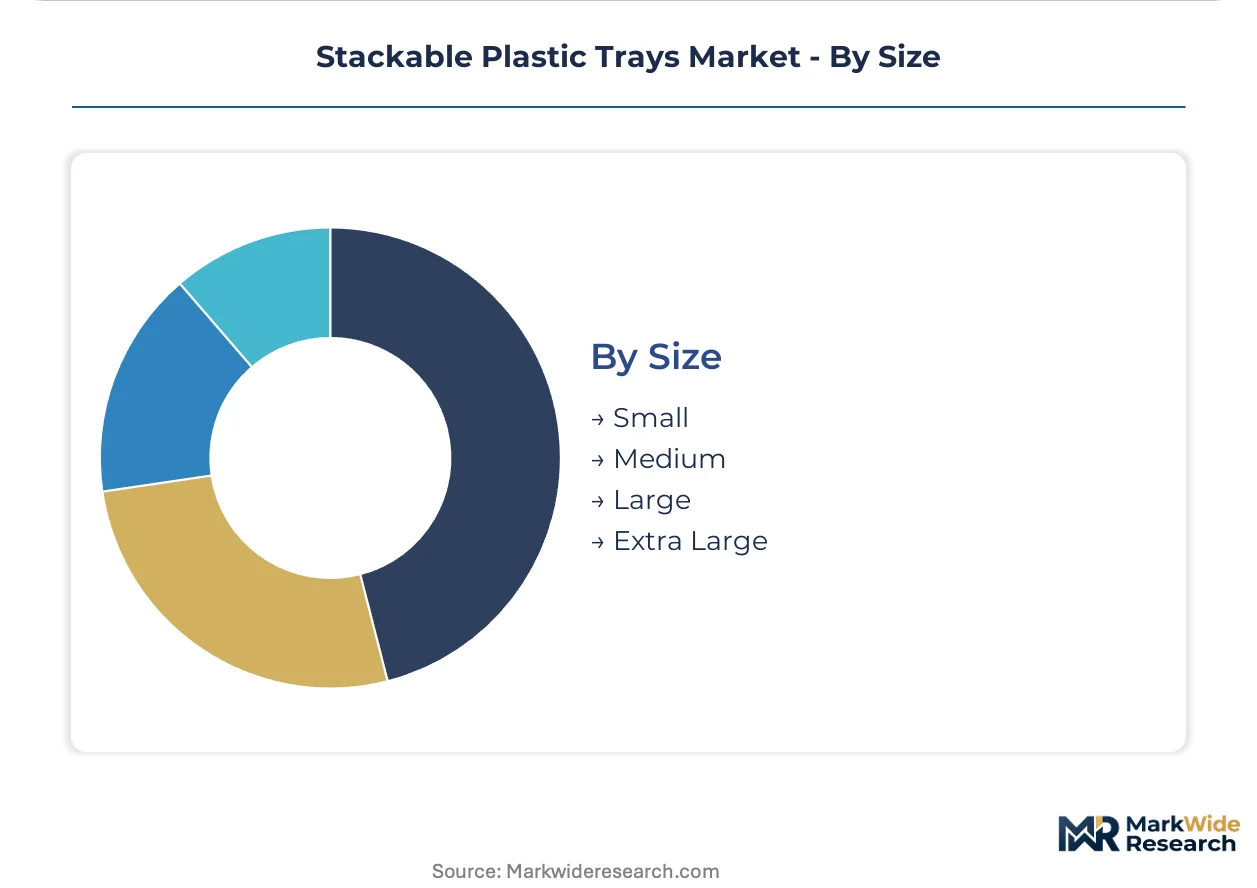
Size:
Volume concentration sits at medium footprints that optimize pallet pattern efficiency across European and North American distribution networks.
- Small:Precision component containment for pharmaceutical and electronics applications.
- Medium:Standardized footprints dominate automotive just-in-sequence programs and retail produce distribution, with Schoeller Allibert leveraging captive injection-molding networks and Rehrig Pacific anchoring North American produce through proprietary nestable designs.
- Large:Bulk material handling in industrial processing and agricultural distribution.
- Extra Large:Specialized applications for oversized component logistics.
Medium formats dominate installed base through pallet pattern standardization. Small sizes are gaining share fastest in pharmaceutical serialization requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive logistics corridors consume industrial-grade polyethylene trays for just-in-sequence component delivery, while American Midwest hospital networks drive medical-grade polypropylene demand through metal-to-plastic conversion programs. This consumption-mix differential separates European logistics density from North American healthcare sterilization requirements.
United States
California's SB 54 mandates source reduction and recyclability thresholds that filter tray specifications for protein packagers in the Central Valley. FDA food contact substance notifications govern resin approvals for direct-food applications nationwide. Hospital central sterile supply departments across Illinois and Ohio accelerate metal-to-polymer tray conversion for steam-sterilizable formats.
Germany
Automotive component logistics corridors in Bavaria and Baden-Württemberg specify nestable HDPE trays for sub-zero temperature impact resistance. REACH and the EU Packaging and Packaging Waste Directive shape material compliance obligations across German manufacturing bases. Schoeller Allibert leverages captive injection-molding networks to serve just-in-sequence programs for OEM suppliers in Stuttgart and Munich.
Netherlands
Third-party logistics providers in Rotterdam and Eindhoven specify standardized tray footprints to maximize cube utilization in automated storage systems. The EU Single-Use Plastics Directive accelerates material transitions toward recyclable resins for food service operators. Belgian hospital group purchasing organizations extend procurement influence across Dutch healthcare networks through sterilization service integration contracts.
India
Temperature-stable HDPE trays for vaccine distribution remain below European penetration benchmarks across Maharashtra and Gujarat pharmaceutical cold chains. The country's national pharmaceutical regulator maintains quality standards for sterile packaging materials. Mumbai and Ahmedabad distribution hubs represent underdeveloped infrastructure for polymer tray standardization in temperature-controlled logistics.
Belgium
Food service operators in Flanders and Wallonia replace transactional spot buying with five-year closed-loop rental contracts where tray fleet management transfers to pooling providers. EU Single-Use Plastics Directive enforcement compresses virgin resin demand across food service supply chains. Brussels-based hospital group purchasing organizations prioritize sterilization service integration over mold cost in vendor selection criteria.
Stackable Plastic Trays Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the stackable plastic trays market, with captive injection-molding networks creating separation from contract fabrication-dependent competitors. The upper tier commands premium positioning through EFSA-approved recycling process registrations and FDA food contact substance notification pathways. Strategic archetypes include captive molders with automotive sequencing expertise, barrier technology compounders serving protein packaging, and pooling operators managing closed-loop rental fleets. Competitive moves concentrate on mold technology upgrades to reduce skilled technician dependency and certification investments to capture EU regulatory premiums.
Among North American fabricators, Berry Global Inc. and Rehrig Pacific occupy distinct positioning vectors within the competitive structure. Berry Global Inc. represents the multi-layer barrier technology archetype serving compliance-intensive food contact applications. Rehrig Pacific exemplifies the nestable design specialist archetype anchoring produce distribution networks through proprietary footprint standardization. Schoeller Allibert sits within the European captive molder tier with automotive logistics sequencing capabilities. These three companies illustrate how certification depth and application-specific design IP create defendable positioning against commodity resin distributors.
| Leading Market Players |
|---|
| Berry Global Inc. |
| Pactiv Evergreen |
| Schoeller Allibert |
| Rehrig Pacific |
| Huhtamaki |
| Sonoco Products Company |
| Sealed Air |
| Genpak |
| IPL Plastics Inc. |
| Others |
Value Network & Pricing Analysis
Captive injection-molding networks in Germany and the United States generate scale economies that compress unit costs while simultaneously erecting price floors for contract-dependent competitors. Automotive sequencing programs and pharmaceutical sterilization contracts anchor utilization rates across these integrated facilities, translating capacity concentration into durable pricing power for molders with in-house tooling capabilities.
Pricing Analysis
Long-term closed-loop rental contracts now dominate food service and healthcare procurement, displacing spot-market transactions across Belgian hospital networks and Dutch produce distribution. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-approved recycled-content compounders from virgin resin molders and uncertified commodity suppliers. Cost compression in standard-grade polyethylene runs through European naphtha-linked crackers when olefin spreads widen. Logistics buyers exhibit highest price sensitivity due to fleet standardization pressures, while pharmaceutical sterilization contracts show lowest sensitivity given regulatory compliance requirements.
Supply Chain Analysis
Strategic stockpiling of injection molds from Chinese and South Korean die shops extends qualification cycles, while just-in-time resin delivery prevails among European automotive molders with pipeline feedstock contracts. Manufacturing concentrates in Germany, the United States, and China, with mold fabrication and compounding capabilities anchoring regional supply clusters. Raw material flows draw from Saudi and U.S. Gulf Coast propylene, Belgian and Dutch mechanical recycling streams, and South Korean specialty additive packages. Single-source vulnerability concentrates in precision mold tooling from East Asian die shops. Distribution runs through captive molder direct sales for automotive sequencing, pooling operators for rental fleets, and distributor networks for spot food service purchases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The stackable plastic trays market tracks automotive production cycles and healthcare capital expenditure waves, with current positioning suggesting recovery-phase entry as hospital sterilization conversion programs accelerate across the American Midwest.
For Market Incumbents: Compound certification depth to defend against recycled-content compounders with EFSA process registrations. Extend captive molding capacity into Indian pharmaceutical cold chain corridors before temperature-stable HDPE penetration rises. Deepen sterilization service integration to lock Belgian and Dutch hospital purchasing committees into five-year renewal cycles. For New Entrants and Emerging Players: Differentiate on RFID-embedded asset tracking to capture per-use pricing models in closed-loop rental programs. Target Indian vaccine distribution networks where tray standardization remains below European benchmarks. Pursue California SB 54 compliance auditing as a recurring revenue attachment to tray supply contracts. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among pooling operators managing sterilization-integrated hospital fleets. Five-to-ten year viability favors compounders with FDA food contact notification pathways and EFSA recycling registrations over commodity resin distributors. Watch for inflection when Indian pharmaceutical regulators mandate polymer tray standards for temperature-controlled distribution.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Recycling Process Registration | Unlocks premium pricing tiers for post-consumer polypropylene in Nordic retail produce tenders. |
| RFID-Embedded Tray Development | Enables per-use pricing models and cloud-based fleet management for rental operators. |
| Indian Cold Chain Footprint Expansion | Captures vaccine distribution growth before regulatory standardization accelerates. |
| Sterilization Service Integration | Locks hospital procurement committees into multi-year contracts beyond mold cost competition. |
| California SB 54 Compliance Certification | Creates recurring audit revenue attachments for protein packagers in Central Valley distribution. |
Research Methodology
Operator-level perspectives from mold technicians, procurement managers at automotive Tier 1 suppliers, hospital central sterile supply directors, and food service group purchasing organization contract managers anchored the qualitative base. Secondary validation drew from FDA food contact substance notification databases, EU Packaging and Packaging Waste Directive implementation reports, SEC filings from disclosed packaging manufacturers, and automotive production sequencing data. Bottom-up tray demand estimates triangulated against top-down resin consumption trends across polypropylene and high-density polyethylene grades.
Sensitivity analysis tested forecast outputs against propylene feedstock volatility scenarios, EU Single-Use Plastics Directive enforcement timelines, and Indian pharmaceutical cold chain infrastructure buildout rates. Segmentation modeling spanned product type, material formulation, end-user procurement modality, and regional regulatory cluster dimensions. CAGR derivation rested on installed base replacement cycles, reusable format adoption curves, and closed-loop rental contract penetration rates across the projection horizon.
The analysis sits within stated boundaries; outcomes outside sustained EU regulatory enforcement or accelerated Indian infrastructure investment would require recalibration. Forecasts reflect documented assumptions regarding resin recycling pathway approvals and mold technician pipeline replenishment. Revision becomes warranted when FDA post-consumer resin notification breadth crosses thresholds enabling brand sustainability commitments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Hinged Lid Compostable Container Market
Containers
2 Piece Cans Market
Containers
USA and Canada Packer Bottle Market
Containers
Container Fixed Fittings Market
Containers
Bulk Container Packaging Market
Containers
Wooden Barrels Market
Containers
Stock Clamshell Packaging Market
Containers
Middle East and Africa Plastic Bottles and Containers Market
Containers
Foam Hinged Take-Out Containers Market
Containers
Water Resistant Packing Cubes Market
Containers
Gable Top Container Market
Containers
Packer Bottle Market
Containers
Slotted Containers Market
Containers
Compartment Take-Out Container Market
Containers
Lever Lid Cans Market
Containers
Sample Containers Market