
 Container Stacking Machine Market | 2026-2036
Container Stacking Machine Market Size, Share, and Industry Trends Forecast 2026-2036
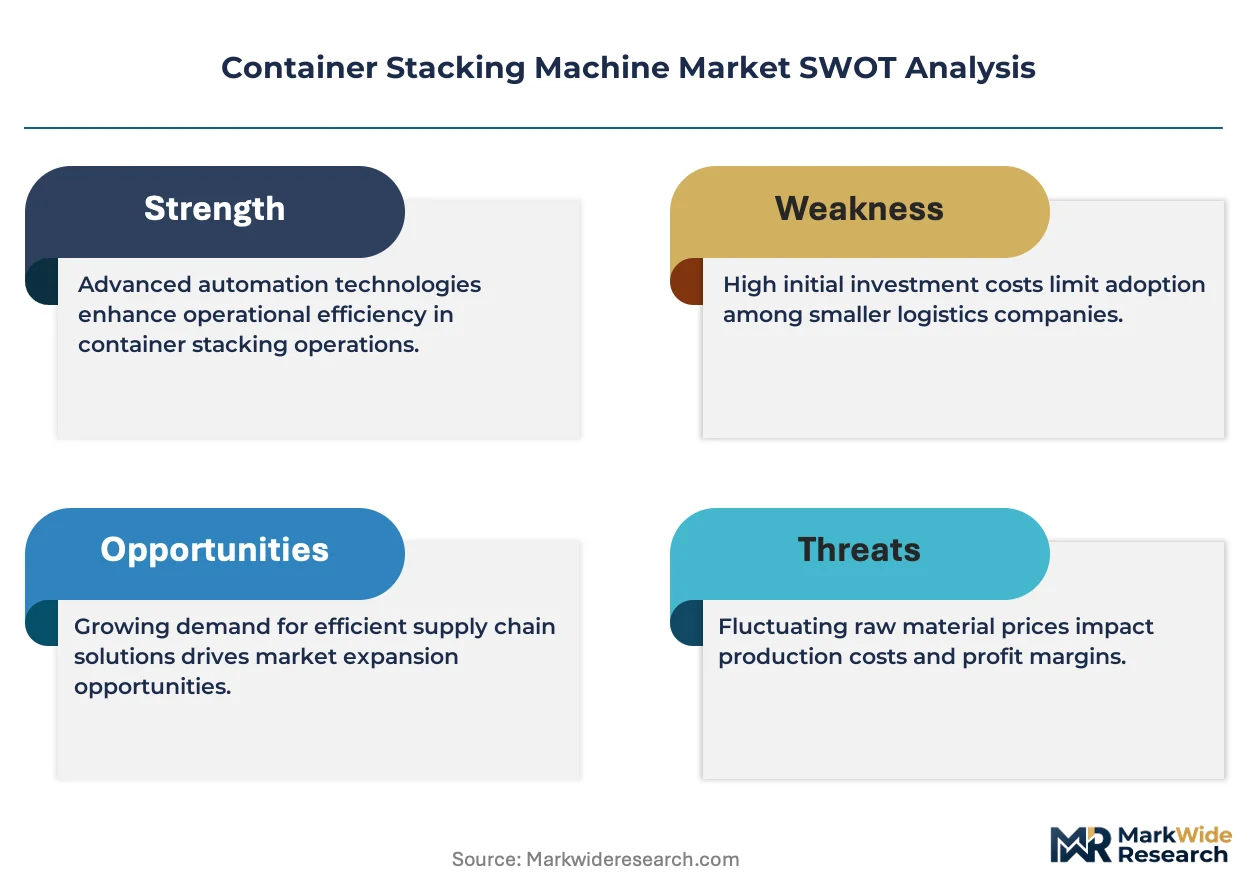
Container Stacking Machine Market Outlook
Software-defined fleet management is hardening as a core revenue layer for equipment suppliers. Konecranes leverages remote monitoring architectures to sustain recurring service contracts across European terminal networks. Kalmar anchors its competitive stance through proprietary automation platforms that integrate with third-party terminal operating systems. ZPMC dominates manufacturing scale, shipping gantry-based stackers from its Shanghai base to emerging port developments across Africa and Latin America.
A container stacking machine is a heavy-lift material handling system engineered to vertically arrange ISO shipping containers in yard blocks, typically achieving stacking heights of one-over-five to one-over-six containers with rated capacities between 40 and 50 tons under spreader. These machines function as the primary interface between vessel cranes and land-side transport, synchronizing yard density with vessel loading velocity. Automatic stacking machines command premium positioning in greenfield terminals where labor arbitrage justifies capital intensity, while semi-automatic configurations retain share in retrofit installations where existing infrastructure constrains full electrification. Hydraulic systems still occupy the majority of installed base due to proven load cycling endurance, though robotic systems are gaining traction in cold-climate ports where precision positioning reduces container damage rates.
ISO 4301 crane classification standards and the EU Machinery Directive (2006/42/EC) govern structural safety and electromagnetic compatibility for machines deployed in European trade lanes, while China's SAMR enforces GB/T 30024 compliance for crane energy consumption metrics. Terminal operators must navigate divergent certification regimes when standardizing fleets across multi-jurisdictional networks. Stakeholders should monitor how port authority decarbonization timelines recalibrate the trade-off between hydraulic reliability and full-electric propulsion architectures.
Market Dynamics
Terminal electrification mandates across China's port network are compressing the operational window for hydraulic stacking architectures while accelerating capital redeployment toward full-electric and hybrid gantry systems. Port authorities in Ningbo-Zhoushan and Qingdao have tied berth access permissions to decarbonization timelines, forcing equipment refresh cycles ahead of natural depreciation schedules.
Growth Catalysts
- China's dual carbon goals:Port electrification mandates in Shanghai and Shenzhen require zero-emission yard equipment by 2030, pulling forward replacement demand for diesel-hydraulic stackers.
- ISO 4301 crane classification:Updated structural safety standards for automated stacking cycles enable European terminal operators to justify premium automation investments with reduced insurance premiums.
- Vietnam's Cai Mep-Thi Vai cluster:Manufacturing relocation from China drives greenfield terminal construction requiring high-density stacking configurations to maximize limited yard footprints.
Market Restraints
- High-grade steel price volatility:Structural steel constitutes 35-40% of stacker manufacturing cost, with European HRC index fluctuations compressing OEM margins on fixed-price contracts.
- ZPMC manufacturing concentration:Single-source dependency for gantry structures among African and Latin American port developments creates supply vulnerability during Chinese holiday shutdowns.
- Battery energy density limitations:Current lithium-ion configurations cannot sustain full-shift operations in high-cycling transshipment terminals without mid-shift charging infrastructure.
Strategic Opportunities
- India's Sagarmala port modernization:Jawaharlal Nehru Port Trust and Visakhapatnam Port Authority tender automation upgrades creating first-mover positioning for integrated stacker-TOS platforms.
- Solid-state battery convergence:Integration with silicon-anode cell architectures promises 40% faster charging cycles, enabling continuous operations in high-velocity transshipment hubs.
- EU Green Deal port funding:Connecting Europe Facility grants cover 30-50% of electrification capital costs for Mediterranean terminal operators replacing legacy diesel fleets.
Industry Challenges
- Mechatronics technician scarcity:Automated stacking systems require specialists fluent in both PLC programming and hydraulic diagnostics, with European and Southeast Asian ports competing for limited talent pools.
- Multi-jurisdictional certification complexity:Terminal operators standardizing fleets across EU, Chinese, and Middle Eastern networks must maintain parallel compliance documentation under divergent structural testing protocols.
- Legacy TOS integration friction:Retrofit automation projects face API incompatibility between proprietary stacker control systems and decade-old terminal operating software architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Container Stacking Machine Market |
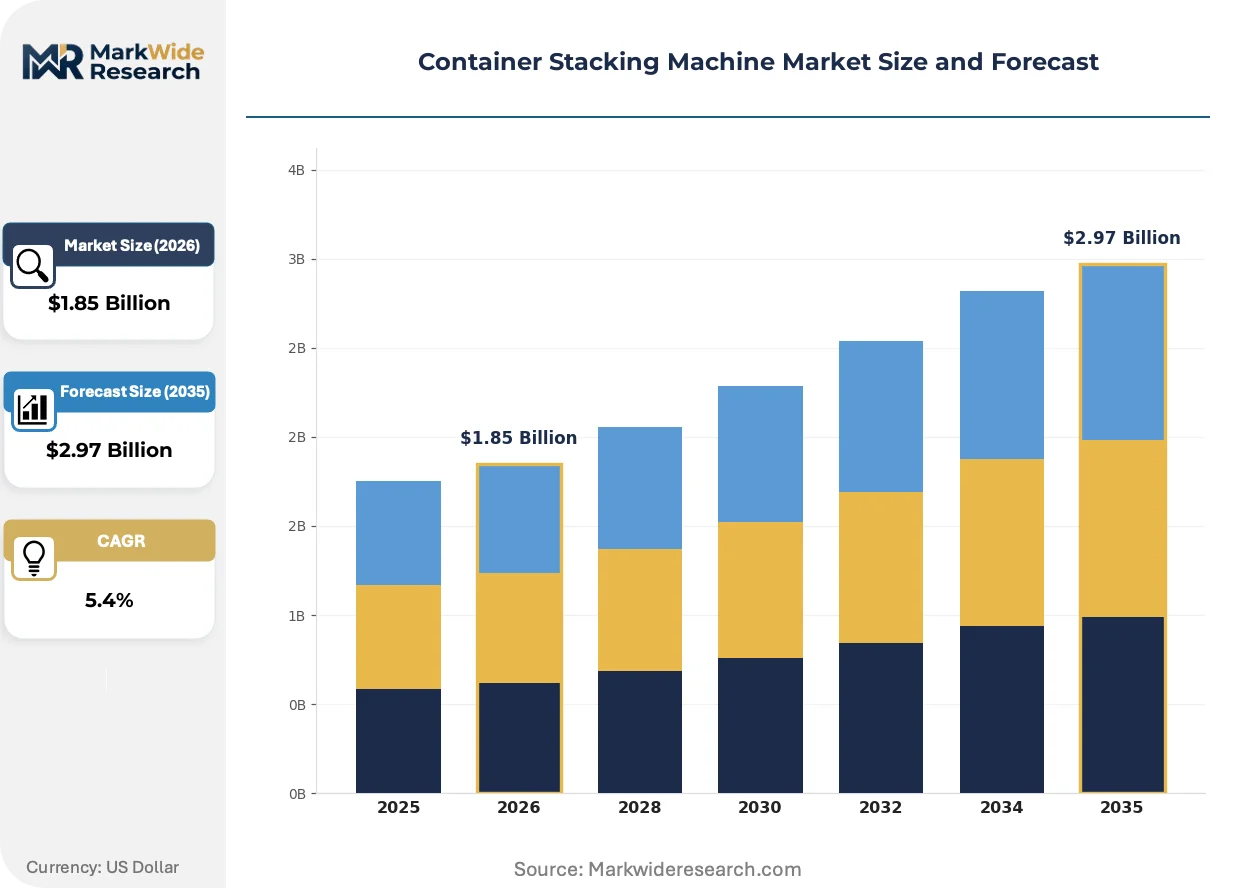
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Stacking Machine, Semi-Automatic Stacking Machine, Manual Stacking Machine, Custom Stacking Solutions Application: Warehouse Operations, Shipping Ports, Distribution Centers, Manufacturing Facilities End User: Logistics Companies, E-commerce Firms, Freight Forwarders, Retail Operations Technology: Robotic Systems, Hydraulic Systems, Conveyor Systems, Mechanical Systems |
| Companies Covered | Konecranes, Kalmar, Hyster-Yale, Toyota Material Handling, Liebherr, SANY, Shanghai Zhenhua Heavy Industries (ZPMC), CVS Ferrari, Cargotec Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Container Stacking Machine Market Strategic Shifts
Autonomous positioning systems are compressing container damage rates while enabling higher yard densities, reshaping how terminal operators evaluate capital equipment lifecycle economics against labor arbitrage calculations.
Robotic spreader alignment systems are expanding into high-latitude port operations where precision positioning reduces container corner casting damage from frost-heaved surfaces. Kalmar and Konecranes have deployed camera-stereo vision hybrids in Rotterdam and Hamburg terminals since 2022, with Finnish and Norwegian port authorities now specifying these configurations in tender documents. The technology is expanding into second-tier Baltic ports where smaller throughput volumes previously justified manual operations.
China's GB/T 30024 energy consumption metrics now govern crane efficiency certification for all port equipment deployed under domestic ownership structures, with SAMR enforcement actions disqualifying non-compliant bids from state-owned terminal operator tenders. The regulation compresses allowable power draw per container move by 15% annually through 2027, forcing OEMs to redesign hoist and trolley drive architectures. European manufacturers serving Chinese joint-venture terminals must maintain dual certification tracks under both GB standards and EU Machinery Directive frameworks.
Service contract unbundling is fragmenting traditional full-maintenance agreements into component-level subscriptions covering predictive analytics, spare parts logistics, and field technician dispatch as separate line items. Large European terminal operators now benchmark these elements individually across Konecranes, Kalmar, and ZPMC service organizations, with Rotterdam World Gateway and APM Terminals Maasvlakte leading this procurement restructuring. The shift is most visible in North European container hubs where scale permits dedicated in-house technical staff for first-line maintenance response.
Container Stacking Machine Market Segmentation
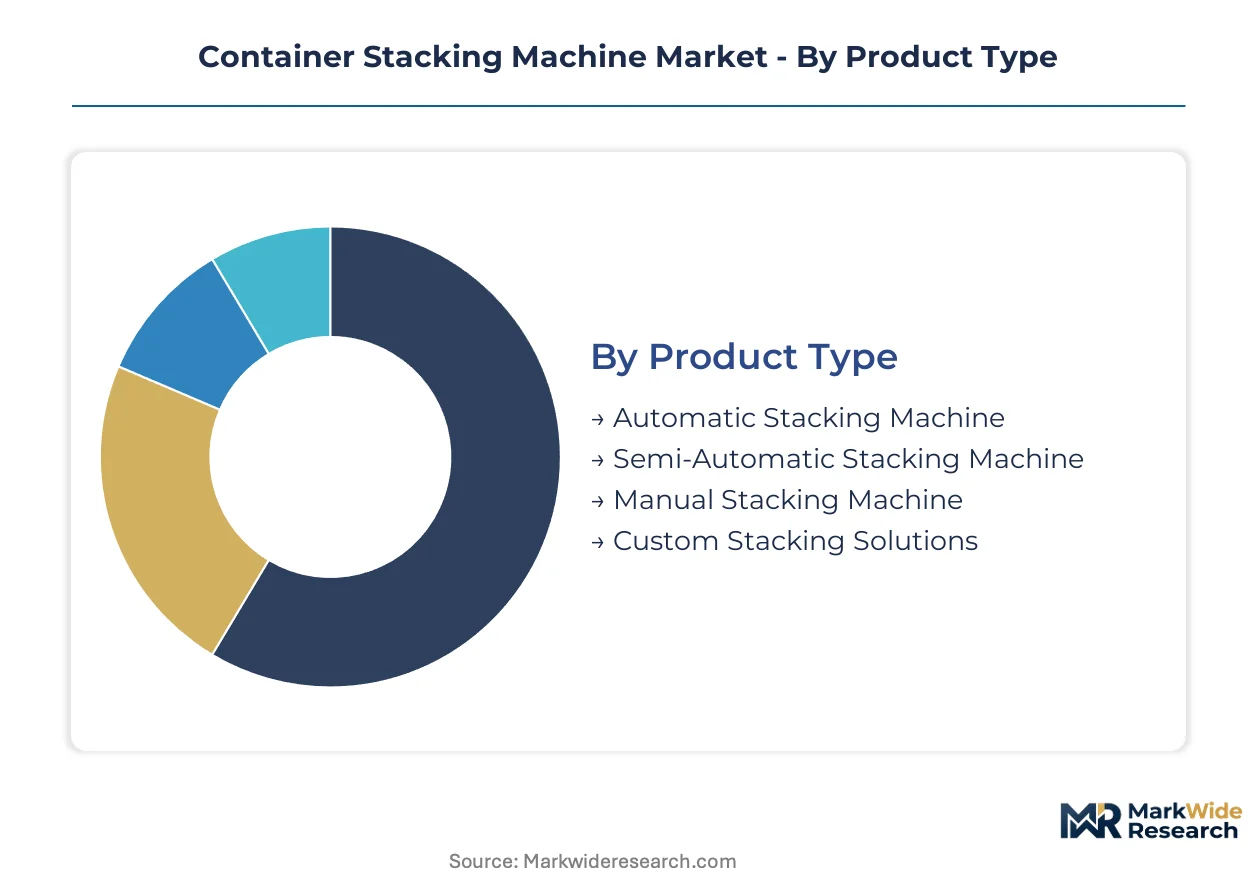
Equipment replacement cycles in container terminals vary dramatically by automation tier, with port operators balancing capital recovery against decarbonization mandates. Segmentation reveals how procurement committees weight technical specifications against total cost of ownership across divergent operational environments.
Product Type:
Upgrade trajectories from manual to semi-automatic configurations dominate procurement budgets in Southeast Asian retrofit markets, while greenfield developments in Vietnam and India skip directly to fully automated architectures.
- Automatic Stacking Machine:These systems integrate gantry-mounted trolley mechanisms with programmable logic controllers achieving one-over-six stacking heights. Demand concentrates in Rotterdam and Singapore transshipment hubs where labor costs justify capital intensity and 24-hour cycling patterns maximize asset utilization.
- Semi-Automatic Stacking Machine:Hybrid architectures retain human operators in cab positions while automating spreader positioning and collision avoidance. European terminal operators at Hamburg and Antwerp deploy these for phased automation of existing yard blocks without full infrastructure rebuilds.
- Manual Stacking Machine:Conventional cab-operated units with hydraulic hoists serving secondary ports in Indonesia and the Philippines where throughput volumes below 500,000 TEU annually cannot amortize automation premiums.
- Custom Stacking Solutions:Purpose-built configurations for narrow-gauge rail interfaces or extreme climate operations at Russian Far East and Canadian Arctic port developments.
Automatic Stacking Machine sits at the top of the volume ranking, with Custom Stacking Solutions climbing the fastest as polar route expansion accelerates specialized demand.
Application:
Application selection tracks yard density requirements and vessel call frequency, with high-velocity transshipment terminals demanding fundamentally different equipment specifications than storage-dominant facilities.
- Warehouse Operations:Indoor container storage at bonded logistics parks in Shenzhen and Dubai Jebel Ali Free Zone, where rubber-tired gantry variants navigate confined aisle widths under roof structures.
- Shipping Ports:Coastal terminal operations at Ningbo-Zhoushan and Los Angeles-Long Beach where quay-to-yard velocity determines equipment specification and electrification mandates compress diesel-hydraulic replacement windows.
- Distribution Centers:Inland container depots serving manufacturing clusters in Mexico's Bajío region and Poland's Silesian logistics corridor, where reach stackers substitute for full gantry systems on limited footprints.
- Manufacturing Facilities:Captive container yards at automotive and electronics plants in Hungary and Thailand, where just-in-sequence delivery patterns require rapid container retrieval capabilities.
Shipping Ports commands the largest installed base, with Distribution Centers expanding most quickly as nearshoring reconfigures supply chain geography.
End User:
End-user procurement authority reflects organizational scale and in-house technical capabilities, with global terminal operators standardizing fleets across multi-port networks while regional players prioritize equipment flexibility.
- Logistics Companies:Integrated 3PL operators like DHL Supply Chain and Kuehne+Nagel operating dedicated container yards at major gateway ports, specifying equipment with API-compatible fleet management architectures.
- E-commerce Firms:Amazon and Alibaba logistics subsidiaries building proprietary container handling capabilities at Los Angeles and Ningbo to bypass congested terminal infrastructure.
- Freight Forwarders:NVOCC operators consolidating cargo at secondary ports in Turkey and Morocco where shared equipment pools reduce individual capital commitments.
- Retail Operations:IKEA and Walmart captive import facilities at Savannah and Rotterdam, where seasonal volume spikes demand equipment with rapid scaling protocols.
Logistics Companies maintains dominant procurement volume, with E-commerce Firms gaining share fastest as vertical integration accelerates.
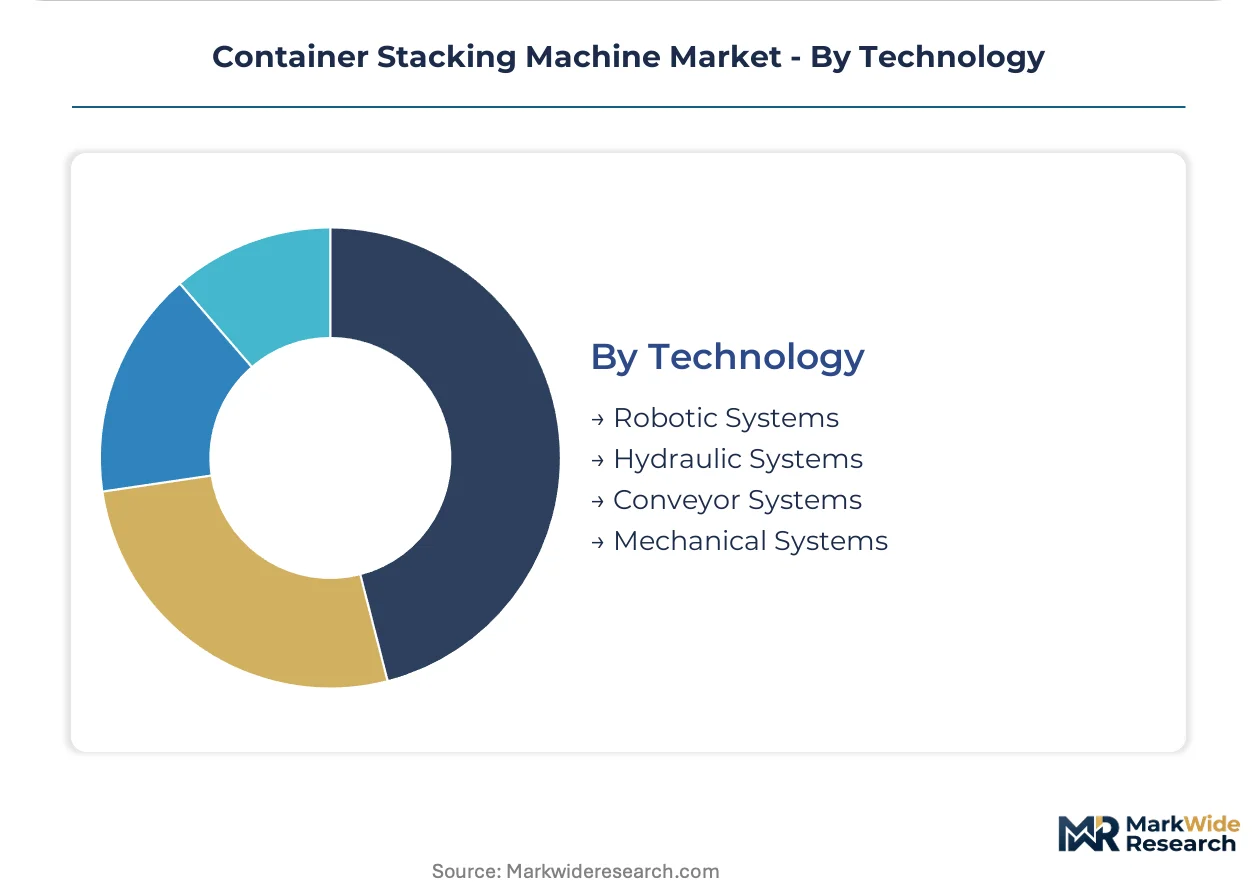
Technology:
Technology selection increasingly bifurcates between proven hydraulic architectures and emerging electric-robotic systems, with port authority decarbonization timelines forcing premature replacement of technically serviceable equipment.
- Robotic Systems:Camera-stereo vision positioning and autonomous trolley navigation enabling sub-50mm spreader alignment precision. Kalmar and Konecranes have deployed these at Rotterdam and Hamburg terminals under EU Green Deal funding protocols.
- Hydraulic Systems:Proven pump-motor configurations dominating the installed base at Chinese and Southeast Asian ports, where SAMR energy consumption regulations now mandate 15% annual efficiency improvements through 2027.
- Conveyor Systems:Automated guided vehicle interfaces for horizontal container transport within yard blocks, specified at greenfield terminals in Vietnam's Cai Mep-Thi Vai cluster.
- Mechanical Systems:Cable-hoist and winch-based architectures retaining niche applications at legacy terminals in Brazil and South Africa with limited electrical infrastructure.
Hydraulic Systems retains the largest installed base despite regulatory pressure, with Robotic Systems showing the steepest expansion trajectory as precision requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting container handling equipment procurement toward jurisdictions where decarbonization mandates align with manufacturing cost structures, compressing replacement windows in high-compliance zones while accelerating greenfield development in emerging port clusters.
China
Shanghai Port Authority's zero-emission yard equipment mandate pulls forward stacker replacement cycles ahead of natural depreciation schedules. SAMR enforces GB/T 30024 energy consumption metrics with 15% annual efficiency improvements required through 2027. Ningbo-Zhoushan and Qingdao port authorities now tie berth access permissions to electrification timelines, forcing terminal operators to retire diesel-hydraulic architectures prematurely.
Vietnam
Manufacturing relocation from China drives demand for high-density stacking configurations at Cai Mep-Thi Vai port cluster where limited yard footprints maximize vertical storage. The Ministry of Transport's terminal automation directives prioritize automated stacking machines in new port developments. Greenfield terminals at Lach Huyen and Cai Mep International skip semi-automatic configurations entirely, deploying full gantry systems from commissioning.
Germany
Hamburg and Bremerhaven terminal operators deploy semi-automatic configurations for phased yard block automation without full infrastructure rebuilds. The EU Machinery Directive (2006/42/EC) and updated ISO 4301 crane classification standards enable reduced insurance premiums for automated stacking cycles. Rotterdam-connected Rhine corridor terminals benchmark equipment specifications against Dutch electrification timelines, compressing procurement decision windows.
India
Jawaharlal Nehru Port Trust and Visakhapatnam Port Authority tender automation upgrades under Sagarmala port modernization programs, creating positioning opportunities for integrated stacker-TOS platforms. The Ministry of Ports, Shipping and Waterways mandates energy efficiency ratings for cargo handling equipment at major ports. JNPT's fourth container terminal and Vizag's outer harbor development specify automatic stacking machines with API-compatible fleet management architectures.
United States
Los Angeles-Long Beach port complex faces CARB emissions regulations compressing diesel equipment operational windows while electrification infrastructure lags deployment schedules. EPA port initiative grants partially cover zero-emission yard equipment capital costs for terminal operators replacing legacy fleets. Savannah and Charleston port authorities specify rapid-scaling equipment protocols to accommodate retail import seasonal volume spikes from IKEA and Walmart captive facilities.
Container Stacking Machine Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with full-system integrators commanding premium positioning in greenfield automation projects while component suppliers capture retrofit upgrade cycles. The vendor structure concentrates around three strategic tiers: European automation platform providers, Chinese manufacturing-scale fabricators, and hybrid hydraulic-electric specialists serving climate-constrained operations. Competitive dynamics center on vertical integration into spreader manufacturing and strategic partnerships with terminal operating system vendors to secure fleet-standardization contracts.
Among European automation platform providers, Konecranes and Kalmar occupy positions exemplifying the software-defined fleet management archetype, with recurring service contract architectures sustaining revenue beyond equipment delivery. Shanghai Zhenhua Heavy Industries anchors the manufacturing-scale tier, shipping gantry-based stackers from its Chinese base to emerging port developments across Africa and Latin America. These three companies represent divergent competitive vectors: automation software integration, manufacturing scale, and hybrid service-contract bundling.
| Leading Market Players |
|---|
| Konecranes |
| Kalmar |
| Hyster-Yale |
| Toyota Material Handling |
| Liebherr |
| SANY |
| Shanghai Zhenhua Heavy Industries (ZPMC) |
| CVS Ferrari |
| Cargotec Corporation |
| Others |
Value Chain & Pricing Dynamics
Port authority electrification mandates in Shanghai and Shenzhen compress procurement timelines for zero-emission yard equipment, forcing OEMs to absorb R&D acceleration costs while terminal operators demand fixed-price contracts that transfer commodity volatility risk upstream.
Pricing Analysis
Distributor margins of 12-18% on European aftermarket parts sustain service revenue for Konecranes and Kalmar while ZPMC's direct-to-port sales eliminate intermediary markups. Three-tier pricing structure across premium automation platforms, standard hydraulic configurations, and economy manual units tracks certification complexity and integration depth. Cost compression in the mid-tier segment is intensifying because Chinese OEMs are qualifying under EU Machinery Directive frameworks. Price-sensitive buyers at Indonesian and Philippine secondary ports prioritize acquisition cost over lifecycle efficiency, while Rotterdam and Singapore transshipment hubs accept automation premiums.
Supply Chain Analysis
Dual-sourcing requirements at European terminal operators mandate qualified suppliers for both gantry structures and automation control systems, preventing single-vendor lock-in. Manufacturing concentrates in China, Germany, and Finland, with high-grade structural steel and lithium-ion battery packs as critical inputs. Single-source vulnerability for gantry fabrication during Chinese holiday shutdowns creates delivery risk for African and Latin American port developments. Distribution runs through OEM direct sales teams for greenfield projects and regional service partners for retrofit installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in container stacking equipment rests on solid-state battery integration reducing energy costs and premium automation tiers capturing decarbonization-linked procurement budgets.
For Market Incumbents: Hedge against ZPMC manufacturing scale by deepening software-defined service contract penetration at European terminals. Prioritize backward integration into spreader manufacturing to defend component margin capture. Accelerate certification under China's GB/T 30024 efficiency tiers to qualify for state-owned terminal tenders. For New Entrants and Emerging Players: Launch via equipment-as-a-service models targeting India's Sagarmala automation upgrades where capital constraints favor operational expenditure structures. Focus on semi-automatic retrofit configurations at Hamburg and Antwerp where phased automation avoids infrastructure rebuild costs. Differentiate through API-native fleet management architectures that bypass legacy TOS integration friction. For Investors and Strategic Acquirers: Asymmetric upside sits with automation software specialists possessing proprietary positioning algorithms and existing Konecranes or Kalmar integration credentials. Long-term viability favors vendors with dual certification tracks under EU Machinery Directive and Chinese GB standards. Monitor solid-state battery pilot deployments at high-cycling transshipment terminals as inflection indicator for electric architecture tipping points.| Strategic Initiative | Industry Significance |
|---|---|
| Automation Platform Integration | Kalmar and Konecranes leverage proprietary TOS compatibility to secure multi-terminal fleet standardization contracts. |
| Backward Integration into Spreader Manufacturing | Captive supply of spreader mechanisms protects margin capture and reduces lead time exposure for European OEMs. |
| Dual Certification Investment | Parallel EU Machinery Directive and GB/T 30024 compliance opens Chinese joint-venture terminal procurement channels. |
| Service Contract Unbundling | Component-level subscriptions for predictive analytics and spare parts logistics match Rotterdam World Gateway procurement restructuring. |
| Solid-State Battery Partnership | Silicon-anode cell integration promises 40% faster charging cycles for continuous transshipment hub operations. |
Study Parameters
Coverage spans China, Vietnam, Germany, India, and the United States, with primary inputs from each jurisdiction combined with secondary validation. Terminal operations directors, OEM procurement teams, port authority planning officers, and aftermarket service heads contributed structured interviews. Secondary sources include customs trade data, SEC filings from listed equipment manufacturers, SAMR regulatory bulletins, and EU Green Deal funding disclosures. Bottom-up equipment shipment tracking and top-down terminal capacity expansion models were triangulated.
Granularity-level modeling disaggregated volume and value across automation tier, propulsion architecture, regional regulatory cluster, and yard block density configuration. CAGRs were derived from regression analysis of historical replacement cycles against electrification mandate timelines. Forecast inputs incorporated berth access permission structures at Ningbo-Zhoushan and Qingdao, EU Connecting Europe Facility grant allocation patterns, and lithium-ion battery energy density improvement curves.
Several conditions sit outside the modeled scope, including unannounced tariff modifications on Chinese steel imports, breakthrough solid-state battery commercialization accelerations, and port authority decarbonization timeline relaxations. Deviation in China's dual carbon goal enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Pails Market
Containers
Disposable Lids Market
Containers
Single Wall Jars Market
Containers
Middle East and Africa Plastic Bottles and Containers Market
Containers
Foldable Container Market
Containers
Essential Oil Containers Market
Containers
Lever Lid Tinplate Containers Market
Containers
Corrugated Open-Head Drums Market
Containers
North America Plastic Bottles and Containers Market
Containers
Dispensing Jug Market
Containers
Gable Top Container Market
Containers
Container Market
Containers
Jug Shipper Market
Containers
Slotted Containers Market
Containers
Pinch Grip Jars Market
Containers
Oblong Tub Lids Market