
 Sample Containers Market | 2026-2036
Sample Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Sample Containers Market Analytics
Buyer concentration in the hospital and diagnostic lab segment is rebalancing as independent reference laboratories and regional health networks diversify procurement beyond legacy distributors. Thermo Fisher Scientific leverages its North American channel density to serve consolidated IDN purchasing coalitions. SARSTEDT AG & Co. KG anchors European supply through specialized logistics for temperature-sensitive specimen transport. Cardinal Health competes on contract breadth, bundling containers with downstream distribution services.
Sample containers are purpose-built receptacles—manufactured from borosilicate glass, polypropylene, or polyethylene—that preserve specimen integrity during collection, transport, and storage through controlled permeability and chemical inertness. Polypropylene containers dominate high-throughput clinical testing due to cost-efficient injection molding and autoclave compatibility, while borosilicate glass vials command premium positioning in pharmaceutical stability studies where extractables control is paramount. Plastic vials and tubes collectively represent the largest product volume pool, though bags are gaining share in environmental monitoring applications requiring large-volume aqueous sampling.
FDA 21 CFR Part 820 quality system regulations and EMA's Medical Device Regulation (MDR) impose biocompatibility and sterility assurance benchmarks that elevate compliance costs for container manufacturers. ISO 10993 biological evaluation standards and REACH substance restrictions further constrain material selection, favoring suppliers with in-house polymer compounding and extractables testing capabilities. Stakeholders must monitor evolving pharmacopeial chapters on plastic packaging systems as regulators tighten leachable thresholds for cell and gene therapy specimens.
Market Dynamics
Container manufacturers face intensifying pressure from FDA and EMA sterilization standards that mandate extractables testing and biocompatibility documentation, compressing margins for suppliers lacking in-house polymer compounding capabilities while rewarding integrated producers with captive testing infrastructure.
Growth Catalysts
- Cell and gene therapy expansion:Advanced therapy medicinal products require specialized primary packaging with ultra-low leachable profiles, pulling demand toward borosilicate glass and fluoropolymer laminates that preserve nucleic acid integrity during cryogenic storage.
- EMA MDR enforcement:Stricter conformity assessment procedures for Class I medical devices are disqualifying commodity suppliers, concentrating procurement among manufacturers with notified body certifications and documented sterilization validation.
- Point-of-care diagnostics:Decentralized testing networks in Germany and the Netherlands are proliferating demand for pre-filled, color-coded specimen tubes that reduce collection error rates in non-laboratory settings.
Market Restraints
- Petrochemical input volatility:Polypropylene and polyethylene resin prices track naphtha and propylene feedstock fluctuations, exposing molders to margin compression when oil markets spike without corresponding container price adjustment mechanisms.
- Supply concentration in borosilicate glass:European pharmaceutical-grade tubing production centers on SCHOTT and Corning facilities in Germany and the United States, creating single-source vulnerability for stability study vials.
- REACH substance restrictions:ECHA candidate list expansions targeting phthalates and bisphenols are forcing reformulation of legacy container seals and closure liners, extending R&D cycles by 18-24 months.
Strategic Opportunities
- Environmental monitoring bags:Large-volume aqueous sampling for PFAS and microplastic detection is displacing rigid containers with flexible fluorinated ethylene propylene bags that enable 10-20 liter field collection without contamination.
- India's CDSCO harmonization:Convergence with ICH Q3D guidelines on elemental impurities is opening import pathways for ISO 15378-certified manufacturers seeking to serve India's expanding contract research organization sector.
- RFID-enabled smart containers:Integration of temperature-logging sensors with unique device identification is creating premium positioning for cold chain specimen transport, particularly in biobanking and clinical trial logistics.
Industry Challenges
- Extractables chemist scarcity:Analytical toxicologists capable of designing ISO 10993-18 study protocols and interpreting mass spectrometry data for polymer qualification are concentrated among a handful of contract laboratories, creating bottlenecks for new product introductions.
- Autoclave validation complexity:Demonstrating sterility assurance levels to FDA 21 CFR Part 820 standards requires substantial capital investment in biological indicator testing infrastructure, particularly for gamma-irradiated plastic alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sample Containers Market |
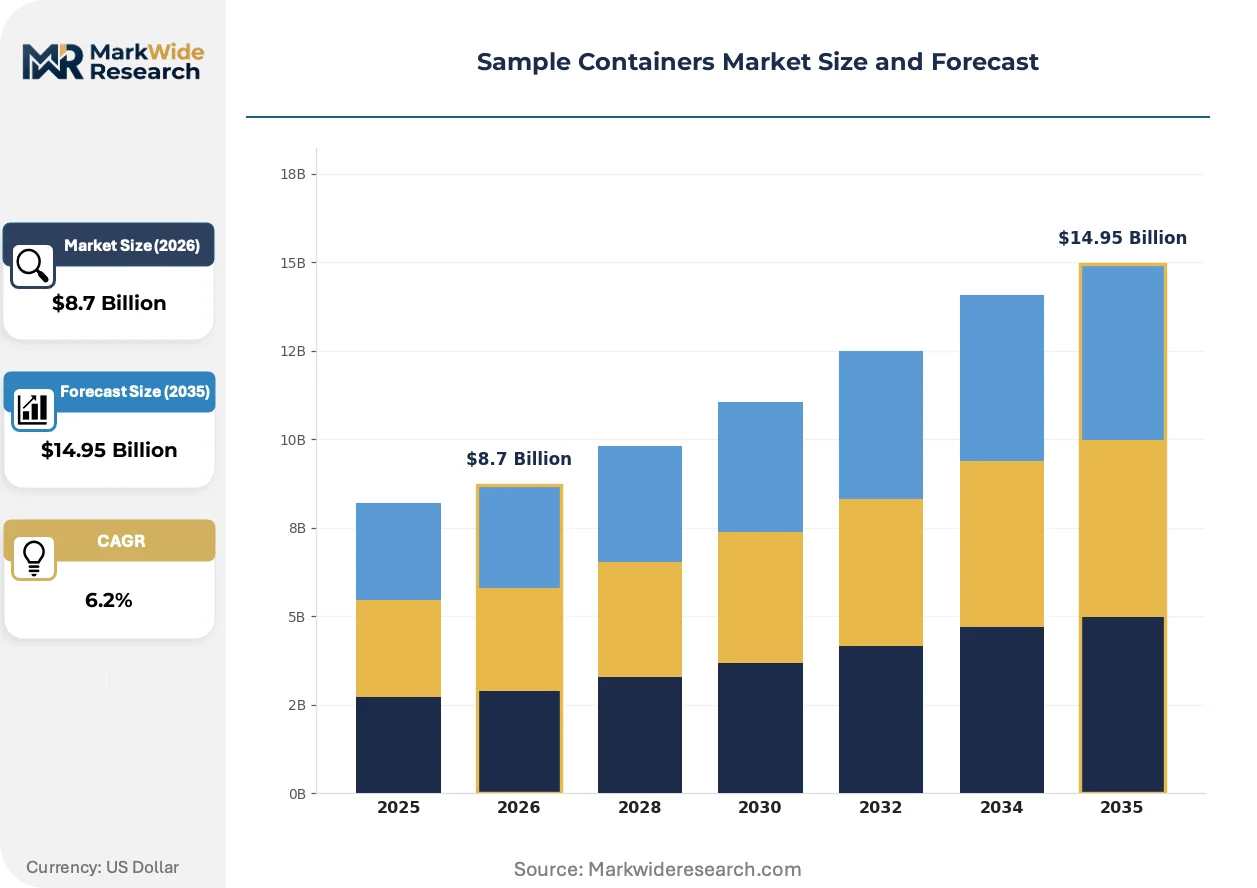
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.95 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Vials, Glass Vials, Tubes, Bags Material: Polyethylene, Polypropylene, Borosilicate Glass, HDPE Application: Clinical Testing, Research Laboratories, Environmental Monitoring, Pharmaceutical Industry End User: Hospitals, Diagnostic Labs, Academic Institutions, Biotech Companies |
| Companies Covered | Thermo Fisher Scientific, Cardinal Health, SARSTEDT AG & Co. KG, FL Medical, Vernacare, Kartell Labware, Leica Biosystems, Bio-Optica, VITLAB GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sample Containers Market Evolving Landscape
Material science breakthroughs and regulatory harmonization pressures are converging to redefine specimen integrity standards, with particular intensity around leachable thresholds and temperature excursion documentation.
Fluoropolymer barrier films are electrifying pharmaceutical stability testing by eliminating silicone oil interference in protein-based therapeutics. Biologics manufacturers in Switzerland and Massachusetts are specifying ethylene tetrafluoroethylene-lined closures for parenteral containers, compressing adoption timelines from decade-long validation cycles to 3-5 year qualification windows as extractables data libraries mature.
REACH Annex XVII expansions are compelling reformulation of polypropylene additives across European supply chains. ECHA restrictions on intentionally added microplastics are forcing container manufacturers to eliminate certain nucleating agents and slip agents, pushing molders toward bio-based alternatives that maintain dimensional stability under autoclave conditions.
Consolidated purchasing coalitions within integrated delivery networks are unbundling container procurement from legacy distributor bundles. Hospital systems in Texas and California are negotiating direct manufacturer contracts for blood collection tubes, bypassing Cardinal Health and McKesson markup structures in favor of volume commitments tied to standardization protocols.
Sample Containers Market Segmentation
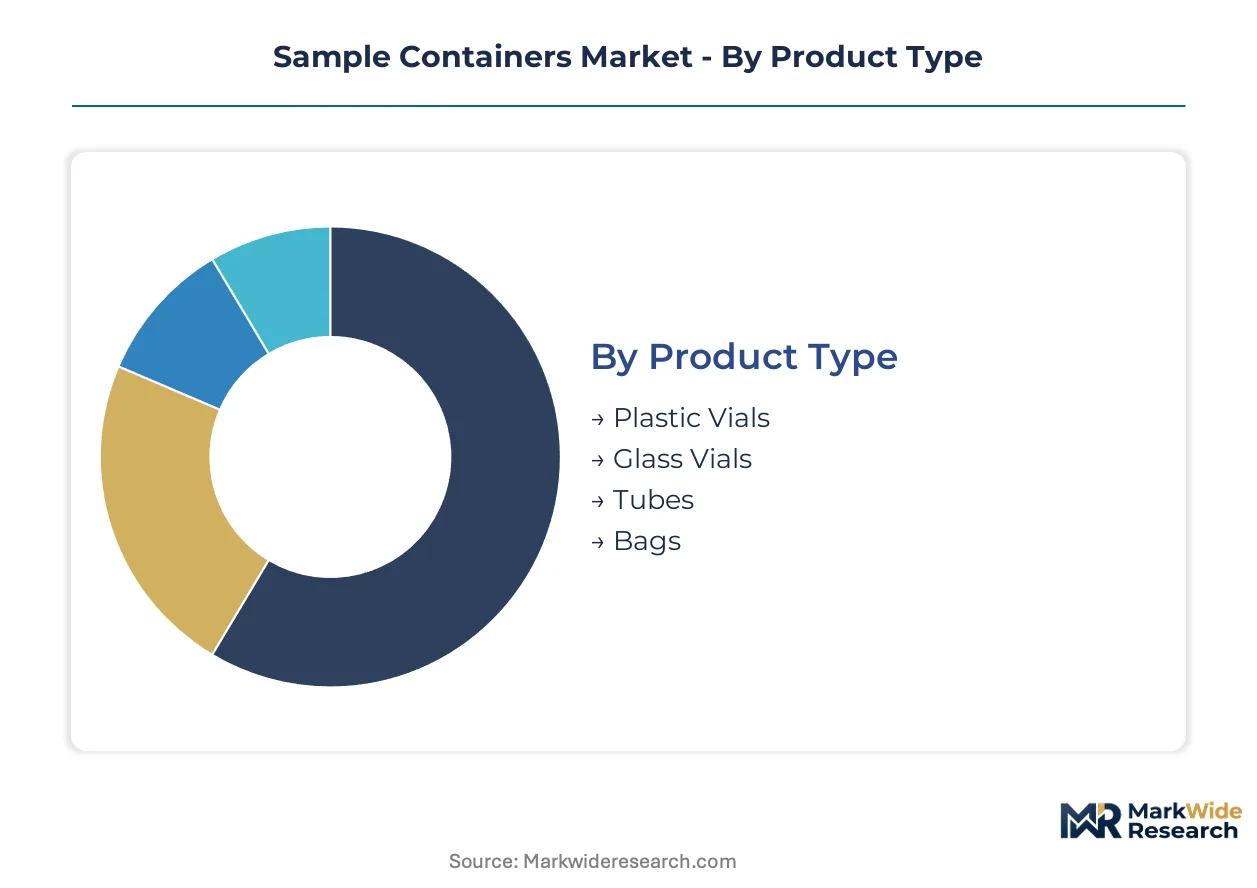
Sample container procurement decisions hinge on sterilization validation requirements, extractables testing burdens, and temperature stability specifications that vary sharply across product categories. Manufacturers must align production capabilities with the certification intensity demanded by each segment's end-use environment.
Product Type:
FDA 21 CFR Part 820 quality system regulations and EMA MDR conformity assessments apply differentially across container formats, with pre-filled and sterile-presenting products triggering Class I medical device obligations that commodity formats escape.
- Plastic Vials:Injection-molded polypropylene or polyethylene vessels designed for high-throughput clinical chemistry and immunoassay workflows. Demand concentrates in hospital central laboratories across Germany and the United States, where autoclave compatibility and cost-efficient disposability drive procurement standardization toward polypropylene formats over glass alternatives.
- Glass Vials:Borosilicate containers specified for pharmaceutical stability studies, cell therapy cryopreservation, and applications demanding ultra-low leachable profiles. Switzerland and Massachusetts biologics manufacturers are pulling volume toward fluoropolymer-lined closures that eliminate silicone oil interference in protein-based therapeutics.
- Tubes:Cylindrical specimen collection vessels with standardized draw volumes and color-coded closures for phlebotomy workflows. Clinical testing networks in the Netherlands specify pre-filled additive tubes that reduce collection error rates in decentralized settings.
- Bags:Flexible fluorinated ethylene propylene containers for large-volume aqueous sampling. Environmental monitoring applications for PFAS and microplastic detection in Germany are displacing rigid containers with 10-20 liter field collection formats.
Plastic vials sit at the top of the volume ranking, with bags climbing the fastest.
Material:
Polymer selection determines regulatory pathway complexity, with borosilicate glass and fluoropolymer laminates commanding premium positioning due to exhaustive extractables documentation requirements that commodity plastics avoid.
- Polypropylene:Dominant material for clinical testing containers due to thermal stability through autoclave cycles and cost-efficient injection molding. REACH Annex XVII restrictions on intentionally added microplastics are forcing reformulation of nucleating agents and slip agents across European supply chains.
- Borosilicate Glass:Pharmaceutical-grade tubing from SCHOTT and Corning facilities commands premium positioning where extractables control is paramount. Single-source vulnerability in Germany and United States production centers creates supply concentration risk for stability study vials.
- Polyethylene:Lower-density alternative for non-sterile environmental sampling and transport containers. Cost positioning suits high-volume disposable applications where thermal cycling demands are minimal.
- HDPE:High-density polyethylene specified for chemical resistance in industrial and environmental monitoring contexts. Rigid formats compete with flexible bags in aqueous sampling applications.
Polypropylene captures the largest volume position, with borosilicate glass expanding most quickly.
Application:
End-use environment dictates sterilization assurance level and documentation burden, with pharmaceutical and cell therapy applications triggering the most intensive biocompatibility validation protocols.
- Clinical Testing:High-throughput diagnostic workflows in hospital and reference laboratory settings. Integrated delivery networks in Texas and California are negotiating direct manufacturer contracts, bypassing distributor markup structures.
- Pharmaceutical Industry:Stability studies, clinical trial logistics, and commercial drug product packaging. EMA MDR enforcement is disqualifying commodity suppliers lacking notified body certifications.
- Research Laboratories:Academic and contract research organization procurement with variable standardization. India's CDSCO harmonization with ICH Q3D guidelines is opening import pathways for ISO 15378-certified manufacturers.
- Environmental Monitoring:PFAS, microplastic, and aqueous contaminant sampling protocols. Large-volume field collection requirements are accelerating adoption of flexible fluoropolymer bags over rigid formats.
Clinical testing holds the volume lead, with environmental monitoring gaining share fastest.
End User:
Purchasing consolidation patterns diverge sharply across customer types, with integrated hospital networks leveraging volume commitments while fragmented academic buyers remain tethered to distributor channels.
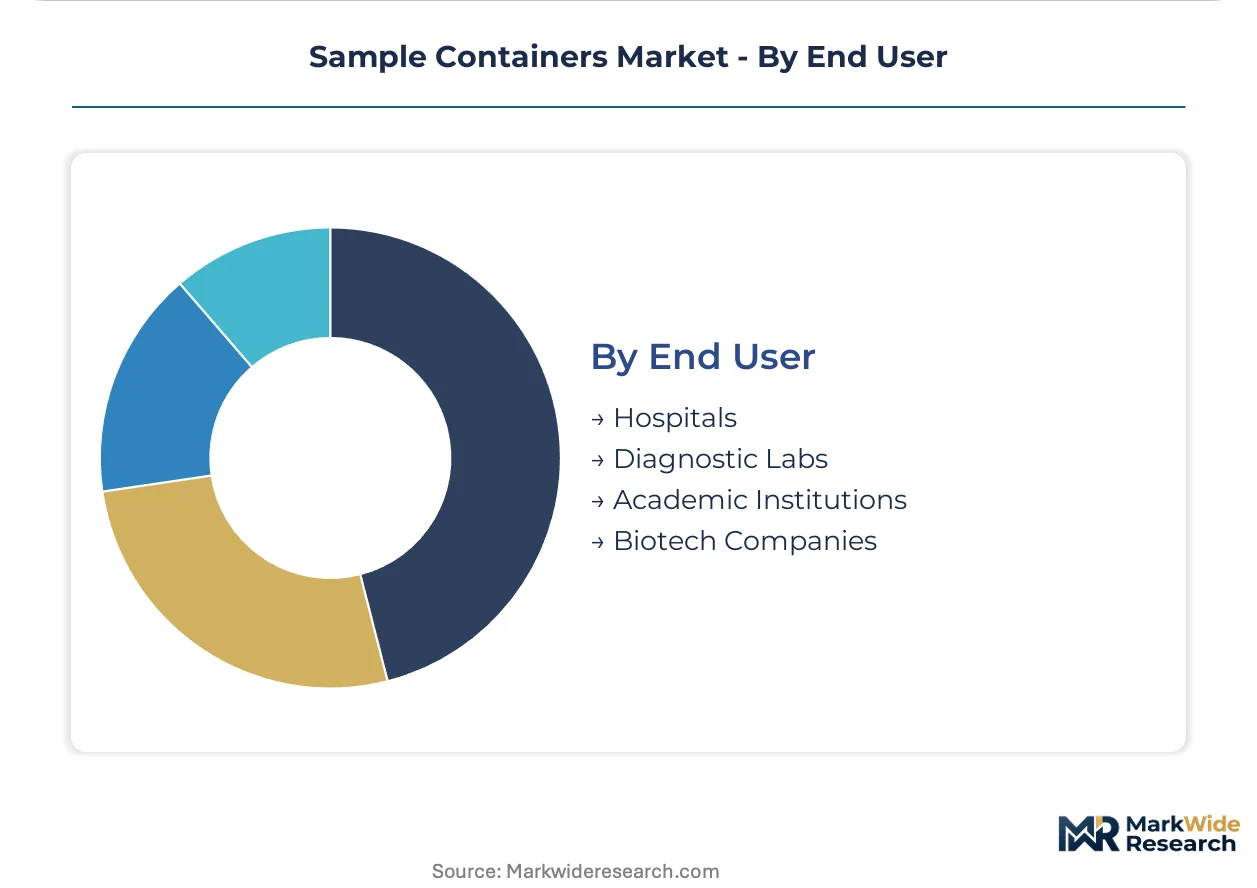
- Hospitals:Consolidated procurement through integrated delivery networks and group purchasing organizations. Standardization protocols favor polypropylene tubes and vials with color-coded closure systems.
- Diagnostic Labs:Independent reference laboratories and regional health networks diversifying beyond legacy distributors. Thermo Fisher Scientific serves this segment through North American channel density.
- Biotech Companies:Cell and gene therapy developers requiring ultra-low leachable profiles and cryogenic stability. Specialized primary packaging demands pull procurement toward borosilicate glass and fluoropolymer laminates.
- Academic Institutions:Fragmented purchasing with reliance on university procurement systems and scientific distributors. Price sensitivity sustains demand for standard polyethylene and polypropylene formats.
Hospitals dominate volume procurement, with biotech companies showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized chemists and polymer scientists concentrate in Germany and Switzerland, anchoring European extractables testing capacity. FDA-regulated clinical testing networks cluster in Texas and California. India's contract research workforce is expanding in Hyderabad and Bangalore.
United States
Integrated delivery networks in Texas and California are negotiating direct manufacturer contracts for blood collection tubes, bypassing traditional distributor markups. FDA 21 CFR Part 820 quality system regulations mandate biocompatibility documentation for Class I medical device classification. Greater Boston hosts biologics manufacturers specifying fluoropolymer-lined closures for parenteral containers.
Germany
SARSTEDT and FL Medical anchor European supply networks for temperature-sensitive specimen transport. EMA Medical Device Regulation enforcement disqualifies commodity suppliers lacking notified body certifications. Baden-Württemberg and North Rhine-Westphalia concentrate pharmaceutical-grade tubing production for stability study vials.
Switzerland
Cell and gene therapy developers require ultra-low leachable profiles and cryogenic stability for nucleic acid preservation. Swissmedic maintains stringent conformity assessment procedures for primary packaging systems. Basel and Zurich biologics clusters are pulling procurement toward borosilicate glass and fluoropolymer laminates.
India
Contract research organizations in Hyderabad and Bangalore are expanding demand for ISO 15378-certified containers. CDSCO harmonization with ICH Q3D guidelines on elemental impurities is opening import pathways for international manufacturers. Maharashtra's pharmaceutical manufacturing belt is standardizing procurement toward pre-filled additive tubes.
Netherlands
Decentralized testing networks are proliferating demand for pre-filled, color-coded specimen tubes that reduce collection error rates. ECHA REACH Annex XVII restrictions on intentionally added microplastics are forcing reformulation of container seals. Amsterdam and Rotterdam serve as logistics hubs for cold chain specimen transport into Northern Europe.
Sample Containers Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across procurement channels. Thermo Fisher Scientific and Cardinal Health leverage North American distribution density to serve consolidated hospital purchasing coalitions. SARSTEDT AG & Co. KG occupies a specialized position in European temperature-controlled logistics. Three archetypes define competitive positioning: integrated life science conglomerates with channel breadth, regional specialists with polymer compounding capabilities, and commodity molders serving price-sensitive environmental monitoring segments. Capacity expansion and strategic partnerships represent the dominant competitive moves, particularly around extractables testing infrastructure and notified body certifications.
Among Germany-based specialists, SARSTEDT AG & Co. KG exemplifies the regional logistics-integrated archetype, while FL Medical occupies a position within Italian medical device manufacturing. Thermo Fisher Scientific represents the diversified conglomerate tier with North American channel density. These three companies anchor distinct strategic positions without overlapping core competencies.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Cardinal Health |
| SARSTEDT AG & Co. KG |
| FL Medical |
| Vernacare |
| Kartell Labware |
| Leica Biosystems |
| Bio-Optica |
| VITLAB GmbH |
| Others |
Value Network & Pricing Analysis
Captive polymer compounding operations in Germany and the United States anchor both supply security and pricing power for container manufacturers serving pharmaceutical and clinical testing segments. Integrated producers with in-house extractables testing infrastructure command premium positioning over molders dependent on third-party validation, compressing margins for commodity suppliers while rewarding backward integration into resin formulation and sterilization assurance.
Pricing Analysis
Capacity additions in India are reshaping price floors for standard polypropylene containers as CDSCO-harmonized manufacturers enter export markets with ISO 15378-certified production. Three-tier pricing structure across premium, standard, and economy levels separates fluoropolymer-lined pharmaceutical vials from autoclave-compatible clinical tubes and non-sterile environmental sampling formats. Cost compression in economy-grade polyethylene containers is intensifying because REACH-driven reformulation of nucleating agents extends R&D cycles without corresponding price recovery mechanisms. Academic institutions and environmental monitoring agencies exhibit highest price sensitivity, while cell and gene therapy developers prioritize leachable profiles over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from integrated delivery networks in Texas and California mandate multi-supplier qualification for blood collection tubes, preventing single-source dependence even where SARSTEDT or Thermo Fisher Scientific hold regional dominance. Pharmaceutical-grade borosilicate glass concentrates in Germany and the United States through SCHOTT and Corning facilities, while polypropylene resin draws from petrochemical complexes in the US Gulf Coast, Western Europe, and Northeast Asia. Single-source vulnerability in borosilicate glass tubing creates structural risk for stability study vial supply. Distribution runs through specialized medical device distributors, direct manufacturer contracts with consolidated hospital networks, and scientific supply channels serving fragmented academic buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sample containers market represents a late-cycle quality story as procurement shifts from commodity disposability toward extractables-assured primary packaging for advanced therapy medicinal products.
For Market Incumbents: Hedge against margin compression in standard polypropylene formats by accelerating captive testing infrastructure investments and securing notified body certifications ahead of EMA MDR enforcement waves. Prioritize polymer compounding capabilities that reduce third-party validation dependence while building direct contracting relationships with integrated delivery networks bypassing distributor markups. For New Entrants and Emerging Players: RFID-enabled temperature-logging sensors offer a technology-first wedge into cold chain specimen transport for biobanking and clinical trial logistics. Target environmental monitoring applications in Germany and the Netherlands where flexible fluoropolymer bags displace rigid containers for PFAS and microplastic field sampling. Pursue ISO 15378 certification as the essential go-to-market credential for India's expanding contract research organization sector. For Investors and Strategic Acquirers: Consolidation pressure builds where extractables testing bottlenecks and regulatory compliance costs outstrip capital access for mid-tier molders. Long-term viability favors vertically integrated specialists with captive polymer science capabilities and established notified body relationships. Monitor CDSCO import pathway expansion as the signal indicating inflection in India's contract research organization procurement standardization.| Strategic Initiative | Industry Significance |
|---|---|
| Notified Body Certification Investment | EMA MDR enforcement disqualifies commodity suppliers lacking conformity assessment documentation. |
| Captive Extractables Testing Infrastructure | In-house ISO 10993-18 capability eliminates third-party bottlenecks for polymer qualification timelines. |
| Direct Manufacturer Contracting | Texas and California hospital systems bypass Cardinal Health and McKesson distributor markups through volume commitments. |
| Fluoropolymer Barrier Film Adoption | Swiss and Massachusetts biologics manufacturers specify ETFE-lined closures eliminating silicone oil interference. |
| RFID-Enabled Smart Container Development | Temperature-logging sensors with unique device identification create premium positioning for cold chain logistics. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation across regulatory filings and trade databases. Interviews with polymer scientists, regulatory affairs specialists at notified bodies, hospital procurement managers, and contract research organization supply chain directors informed material qualification timelines and purchasing consolidation patterns. Secondary sources include FDA 510(k) filings, EMA MDR conformity assessment databases, CDSCO import registration records, and customs trade data for polypropylene and borosilicate glass tubing. Bottom-up volume estimates by product format and material triangulated against top-down market sizing from sterilization equipment capacity and clinical testing laboratory expansion pipelines.
Rate-of-change decomposition across the analysis window separates volume growth from price and mix effects, with CAGRs derived from regression against clinical testing expansion, pharmaceutical pipeline advancement, and environmental monitoring protocol adoption. Segmentation dimensions modeled include product type, material composition, application environment, and end-user purchasing consolidation level. Industry-specific forecast inputs incorporate REACH Annex XVII restriction timelines, EMA MDR transition deadlines, and CDSCO ICH Q3D harmonization progress.
The model holds under steady regulatory enforcement intensity and stable petrochemical feedstock pricing; deviation in oil market volatility or accelerated ECHA substance list expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Compartment Trays Market
Containers
Bulk Containers Market
Containers
Middle East and Africa Plastic Bottles and Containers Market
Containers
Hinged Lid Compostable Container Market
Containers
Safety Bottle Tote Carriers Packaging Market
Containers
Insert Trays Market
Containers
2 Piece Cans Market
Containers
Old Corrugated Containers (OCC) Market
Containers
Wooden Barrels Market
Containers
Foam Hinged Take-Out Containers Market
Containers
PS Containers Market
Containers
Carboy Market
Containers
ISO Ocean Containers Market
Containers
Container Liner Market
Containers
Concentrate Containers Market
Containers
ISO Container Market