
 Gable Top Container Market | 2026-2036
Gable Top Container Market Size, Share, and Industry Trends Forecast 2026-2036
Gable Top Container Market Foresight
Food-grade barrier specification is bifurcating the competitive landscape into premium aseptic tiers and standard fresh-dairy tiers. Tetra Pak Group leverages integrated filling equipment sales to sustain its technology leadership in extended-shelf-life systems. SIG Combibloc Group Ltd. anchors European dairy supply chains through regional manufacturing scale. Elopak ASA differentiates via its Pure-Pak product specialization in renewable and recyclable carton formats.
A gable top container is a paperboard-based carton sealed with heat-applied polyethylene or bio-polymer layers, formed with a peaked closure that enables ergonomic pouring and shelf-stable liquid storage; typical constructions range from 250ml to 5L capacities with liquid-tight spouts or screw caps for controlled dispensing. The material segment splits between fossil-based polyethylene, which still dominates dairy manufacturing volumes, and polylactic acid, which captures premium juice containment contracts as brand owners pursue renewable content claims. Capacity segmentation shows 1L formats leading milk packaging volumes while 500ml SKUs expand fastest in on-the-go beverage production channels where convenience retail formats multiply.
FDA food-contact substance notifications govern polyethylene migration limits in US dairy packaging, while EU REACH and the F-Gas Regulation constrain fluorinated barrier chemistries and redirect R&D toward mineral-coated or PLA-laminated alternatives. China's SAMR enforces GB standards on composite food packaging that importers must meet for market access. Stakeholders must monitor how evolving extended producer responsibility frameworks in the European Union and state-level recycling mandates in California reshape material cost structures and design-for-recyclability requirements.
Market Dynamics
EU REACH constraints on fluorinated barrier chemistries and California's extended producer responsibility mandates are forcing material substitution toward bio-based polyethylene and mineral-coated paperboard across liquid packaging supply chains.
Growth Catalysts
- Aseptic filling technology:Dairy manufacturers in Germany and the United States are retrofitting production lines for extended-shelf-life milk formats, expanding addressable volume for high-barrier carton constructions.
- California's SB 54 mandates:State-level recycled content requirements and producer responsibility frameworks accelerate design-for-recyclability investments in North American liquid packaging.
- Private-label retail contracts:German and Chinese supermarket chains are consolidating beverage packaging procurement around renewable-content gable top specifications, concentrating demand pull.
Market Restraints
- Polylactic acid feedstock volatility:Corn and sugarcane price swings in Brazil and Thailand transmit directly to bio-polymer laminate costs, compressing margin on premium juice containment contracts.
- Concentrated barrier film supply:Three Southeast Asian resin converters control the majority of food-grade polyethylene supply for Asian dairy packaging, creating single-source vulnerability.
- Fluorinated chemistry phase-out:EU F-Gas Regulation and state-level PFAS restrictions in Maine and Washington eliminate proven grease-resistant barriers before mineral-coating alternatives achieve equivalent performance.
Strategic Opportunities
- India's FSSAI compliance gap:Domestic dairy processors face import-dependent aseptic packaging equipment shortages, creating white space for integrated filling-line and carton supply contracts.
- Convenience retail channel expansion:Japanese and South Korean 500ml on-the-go beverage SKUs multiply through unmanned retail formats, demanding compact gable top geometries with resealable spouts.
- EU Green Deal carbon border adjustments:Import tariffs on high-emission packaging materials incentivize regional production of PLA-laminated cartons for European juice and plant-milk brands.
Industry Challenges
- Aseptic validation timelines:FDA food-contact substance notifications for novel bio-polymer barriers require 18-24 month review cycles, delaying product launches and freezing R&D budgets.
- Legacy filling line incompatibility:Mineral-coated paperboard runs at reduced speeds on polyethylene-optimized equipment, forcing capital-intensive retrofits or throughput sacrifices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gable Top Container Market |
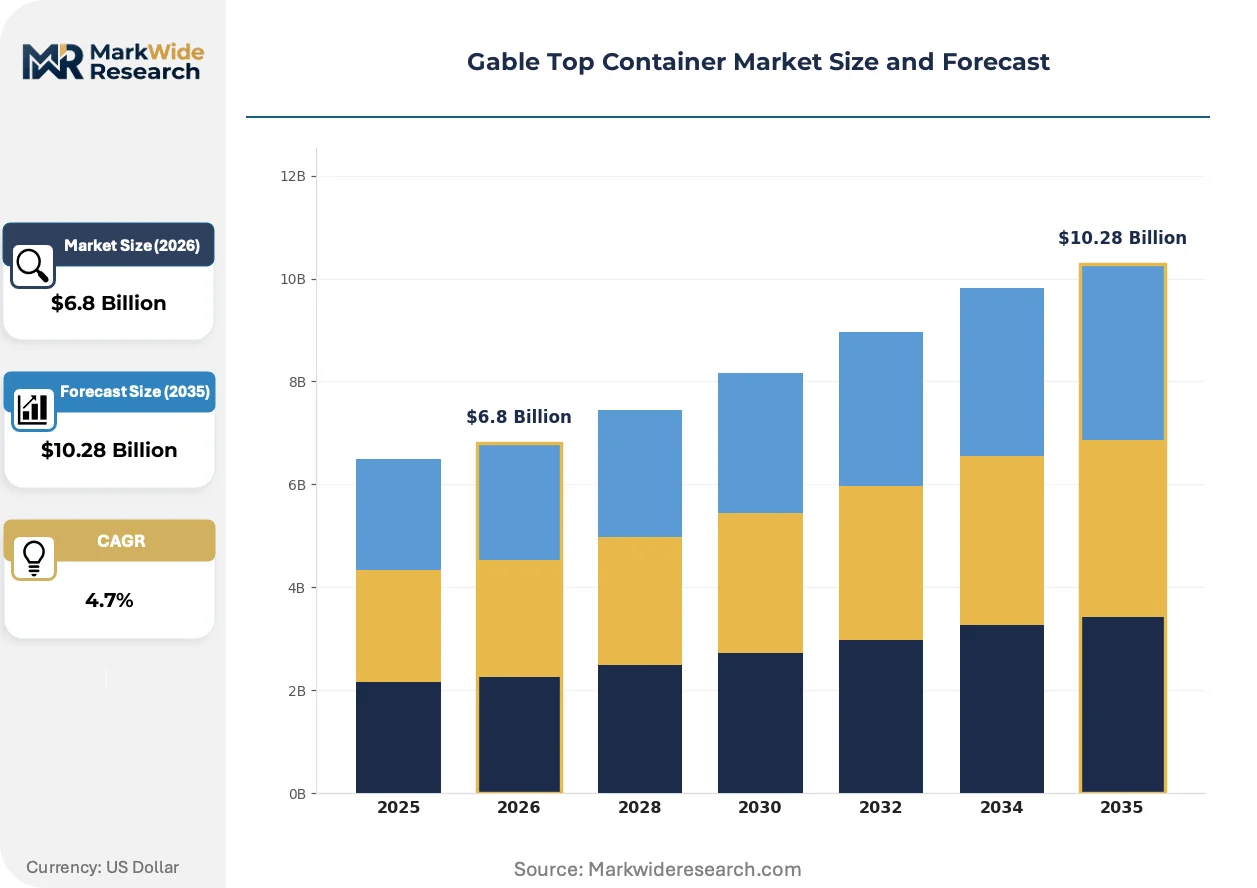
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
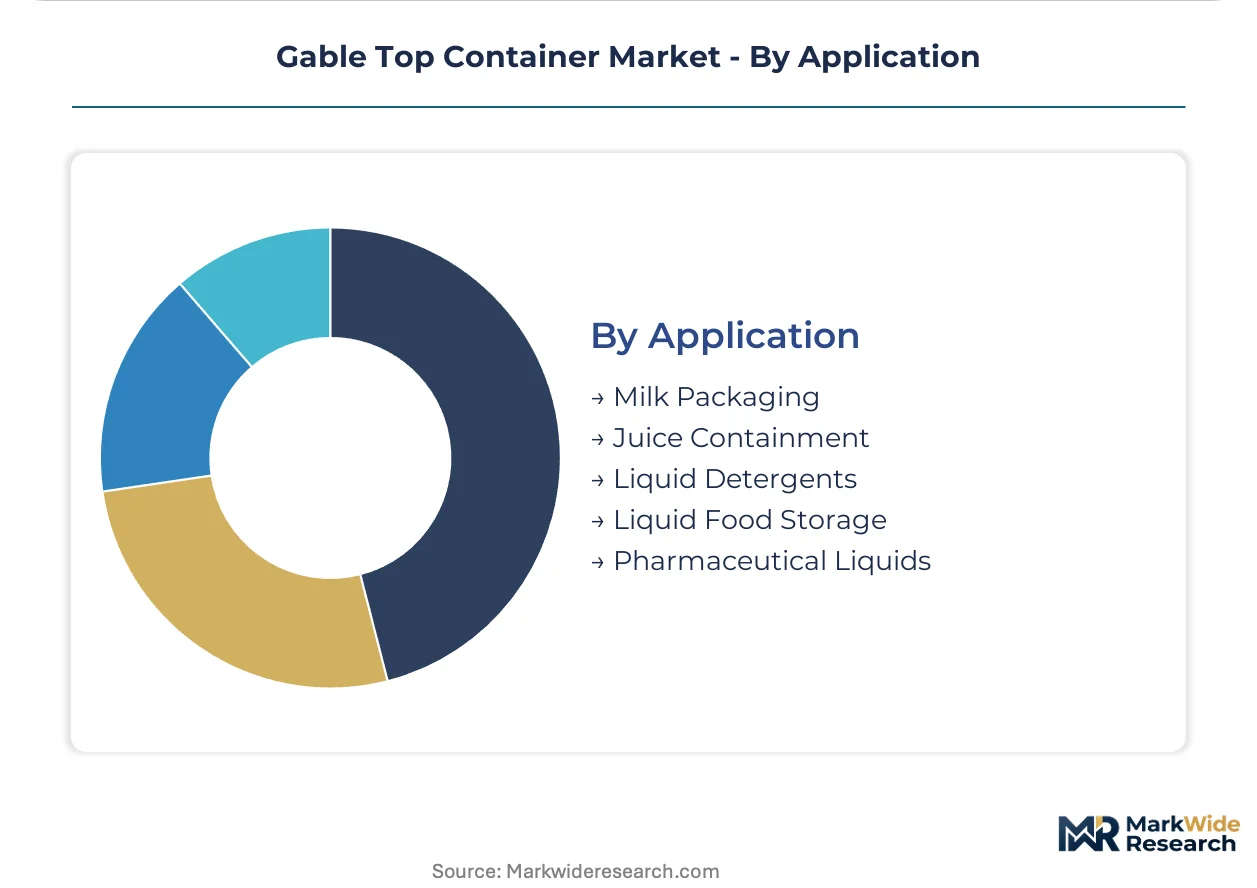
| Segmentation | Material: Polyethylene, Polypropylene, Polylactic Acid, High-Density Polyethylene, Low-Density Polyethylene End User Industry: Dairy Manufacturing, Beverage Production, Household Products, Cosmetic Brands, Chemical Processing Capacity: 250ml, 500ml, 1L, 2L, 5L Application: Milk Packaging, Juice Containment, Liquid Detergents, Liquid Food Storage, Pharmaceutical Liquids |
| Companies Covered | SIG Combibloc Group Ltd., Evergreen Packaging LLC, Tetra Pak Group, Rotopak LLC, Carton Service, Inc., Elopak ASA, Parksons Packaging Ltd, Ital Pack Cartons Srl, Pactiv Evergreen Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gable Top Container Market Shifts & Advancements
Bio-polymer barrier technologies and mineral-coated substrates are displacing conventional fluorinated chemistries across premium liquid packaging segments, while regulatory carbon accounting and retail procurement consolidation reshape competitive requirements.
Polylactic acid laminates are displacing fossil-based polyethylene in 250ml to 1L juice cartons as brand owners pursue renewable content claims for European and North American retail shelves. Organic juice processors and private-label beverage divisions adopt PLA specifications despite 15-20% cost premiums, compressing addressable volume for standard polyethylene constructions and forcing resin suppliers to certify mass-balance supply chains.
EU F-Gas Regulation phase-down schedules and REACH authorization requirements for per- and polyfluoroalkyl substances eliminate grease-resistant fluorinated barriers from dairy and food-service applications by 2027. Carton converters redirect coating R&D toward calcium carbonate and clay mineral dispersions, though these alternatives require thicker application weights and reduce line speeds at German and French manufacturing facilities.
Retail procurement consolidation around sustainability scorecards rotates volume toward integrated packaging suppliers capable of verified carbon footprint disclosure. German and Dutch supermarket chains now require lifecycle assessment documentation for shelf-stable milk cartons, displacing spot-market purchasing relationships and compressing supplier margins on non-certified alternatives.
Gable Top Container Market Segmentation
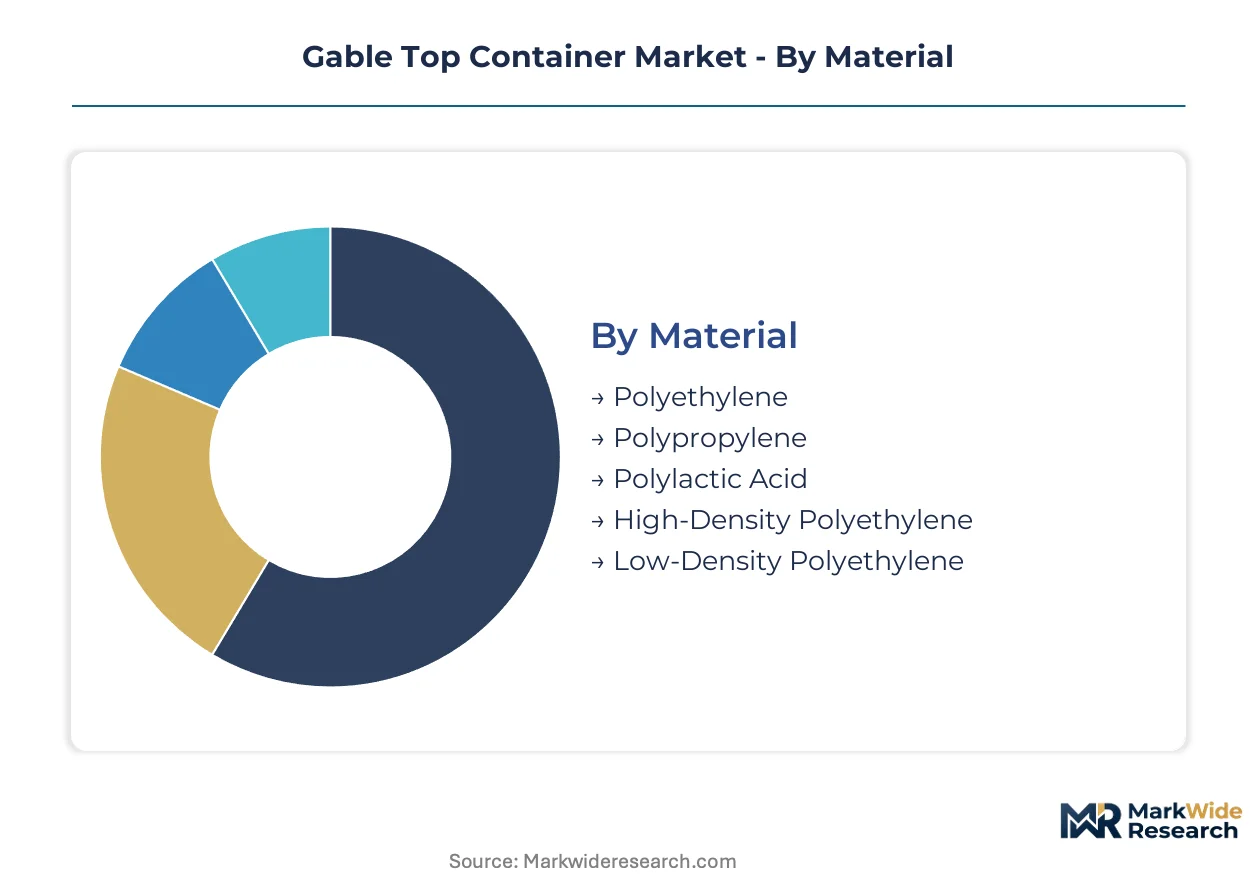
Material substitution pressures and capacity-driven procurement consolidation fragment the gable top container landscape into competing technology tiers. End-use specifications diverge sharply between aseptic dairy requirements and standard fresh-liquid formats, forcing converters to maintain parallel production capabilities.
Material:
Polyethylene faces the most acute substitution threat from bio-based alternatives as EU REACH constraints and California extended producer responsibility mandates accelerate laminate replacement timelines.
- Polyethylene:Fossil-based linear low-density formulations still dominate dairy manufacturing volumes across German and US filling lines. Heat-seal layer specifications require migration testing under FDA food-contact substance notifications, locking in incumbent supply relationships despite sustainability scorecard penalties.
- Polylactic Acid:Corn-derived PLA laminates capture premium juice containment contracts from organic beverage processors seeking renewable content claims. Brazilian and Thai feedstock volatility transmits directly to laminate costs, compressing margins on 250ml to 1L carton formats.
- Polypropylene:Higher melt strength suits hot-fill applications in liquid food storage where thermal resistance exceeds polyethylene capabilities.
- High-Density Polyethylene:Stiffness-optimized grades reinforce screw-cap threads and spout assemblies in 2L to 5L household product containers.
- Low-Density Polyethylene:Flexibility-focused formulations enable ergonomic gable-top creasing in single-serve 250ml beverage SKUs.
Polyethylene retains volume leadership across dairy supply chains; Polylactic Acid holds the steepest expansion curve as retail procurement consolidates around certified renewable content.
End User Industry:
Cost tier stratification separates aseptic-validated dairy processors from standard-format beverage packagers, with equipment amortization schedules determining barrier specification thresholds.
- Dairy Manufacturing:Extended-shelf-life milk producers in Germany and the United States retrofit filling lines for high-barrier carton constructions. Aseptic validation timelines for novel bio-polymer barriers extend 18-24 months, freezing R&D budgets and preserving incumbent polyethylene specifications.
- Beverage Production:On-the-go juice and plant-milk brands multiply 500ml SKU volumes through Japanese and South Korean unmanned retail channels. Convenience retail procurement demands compact geometries with resealable spouts, favoring mineral-coated paperboard over fluorinated barriers.
- Household Products:Liquid detergent packagers specify chemical-resistant polyethylene laminates for 2L to 5L formats.
- Cosmetic Brands:Premium skincare and haircare lines adopt smaller 250ml capacities with enhanced print surfaces for shelf differentiation.
- Chemical Processing:Industrial solvent containment requires specialized barrier films outside standard food-grade specifications.
Dairy Manufacturing commands the highest barrier specification premiums; Beverage Production is expanding most quickly through convenience channel proliferation.
Capacity:
Volume concentration in 1L formats creates margin pressure at scale, while smaller capacities capture per-unit pricing premiums through retail channel fragmentation.
- 1L:Standard milk packaging volumes concentrate in German supermarket private-label contracts and US retail procurement programs. Filling line throughput optimization at this capacity tier locks in polyethylene-optimized equipment, slowing mineral-coated paperboard adoption.
- 500ml:On-the-go beverage SKUs multiply fastest through Japanese convenience stores and South Korean unmanned retail formats. Compact geometries with resealable spouts demand specialized forming equipment, fragmenting converter capacity allocation.
- 250ml:Single-serve juice and dairy portions target airline and hospitality channels.
- 2L:Family-size milk and plant-based alternatives occupy mid-tier retail shelf positioning.
- 5L:Bulk household product and institutional food-service formats require reinforced handle structures.
1L retains volume leadership across liquid dairy; 500ml gains share fastest through convenience retail channel expansion.
Application:
Customer type divergence separates pharmaceutical-grade validation requirements from standard food-contact specifications, with regulatory pathway complexity determining converter market entry barriers.
- Milk Packaging:Aseptic and fresh dairy formats dominate German and US manufacturing volumes with distinct barrier tiers. Extended-shelf-life specifications require integrated filling equipment sales from technology leaders, while fresh dairy tolerates standard polyethylene constructions.
- Juice Containment:Organic and private-label beverage divisions adopt PLA-laminated specifications despite cost premiums. EU Green Deal carbon border adjustments incentivize regional PLA production for European juice brands, displacing imported fossil-based alternatives.
- Liquid Detergents:Chemical compatibility requirements favor high-density polyethylene spout reinforcements.
- Liquid Food Storage:Hot-fill and retort applications demand polypropylene thermal resistance.
- Pharmaceutical Liquids:FDA drug master file validation and EU GMP compliance create specialized converter qualification pathways.
Milk Packaging retains volume leadership; Juice Containment climbs the fastest as renewable content procurement consolidates retail shelf access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converter capacity clusters in Germany, China, and the United States where aseptic filling equipment density and retail procurement consolidation concentrate demand. Regulatory divergence across FDA, EU REACH, and China's SAMR frameworks fragments material specification requirements by geography.
United States
Dairy manufacturers in Wisconsin and California retrofit filling lines for extended-shelf-life formats. FDA food-contact substance notifications govern polyethylene migration limits in milk packaging. The Midwest dairy corridor sustains volume concentration despite California's SB 54 recycled content mandates accelerating design-for-recyclability investments.
Germany
Private-label supermarket chains consolidate beverage procurement around renewable-content specifications. EU REACH constraints on fluorinated barrier chemistries redirect coating R&D toward mineral-dispersion alternatives. The Baden-Württemberg manufacturing belt hosts carton converters adapting production speeds for calcium carbonate-coated substrates.
China
Domestic dairy processors expand aseptic packaging capacity for ambient milk distribution. SAMR enforces GB standards on composite food packaging that importers must meet for market access. The Yangtze River Delta cluster concentrates filling equipment manufacturing and carton converter capacity serving branded dairy customers.
India
Domestic dairy processors face import-dependent aseptic packaging equipment shortages. FSSAI compliance requirements create qualification barriers for imported carton specifications. The Maharashtra-Gujarat dairy belt generates demand pull for integrated filling-line and carton supply contracts from regional cooperatives.
Japan
Convenience retail chains multiply 500ml on-the-go beverage SKUs through unmanned store formats. METI circular economy guidelines incentivize mono-material carton designs for improved recyclability. The Kanto region around Tokyo concentrates demand for compact gable top geometries with resealable spout features.
Gable Top Container Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the gable top container market. Integrated filling equipment suppliers capture premium aseptic tier margins while regional converters compete on standard fresh-dairy specifications. Three archetypes dominate: multinational packaging systems integrators, regional carton converters with dairy supply chain anchoring, and renewable-material specialists pursuing sustainability differentiation. Competitive moves concentrate on strategic partnerships with dairy processors and portfolio diversification into bio-polymer barrier technologies.
Among integrated systems providers, Tetra Pak Group and SIG Combibloc Group Ltd. exemplify the technology leadership archetype through captive filling equipment distribution. Elopak ASA occupies a position within the renewable-material specialist tier, with its corporate structure suggesting Nordic market anchoring. These three companies represent the dominant competitive anchors against which regional converters and private-label suppliers position cost-competitive alternatives.
| Leading Market Players |
|---|
| SIG Combibloc Group Ltd. |
| Evergreen Packaging LLC |
| Tetra Pak Group |
| Rotopak LLC |
| Carton Service, Inc. |
| Elopak ASA |
| Parksons Packaging Ltd |
| Ital Pack Cartons Srl |
| Pactiv Evergreen Inc. |
| Others |
Supply & Pricing Matrix
Polylactic acid displacement of fossil-based polyethylene simultaneously redraws procurement geography toward Brazilian and Thai feedstock zones and compresses margin structures across premium juice containment contracts. This substitution dynamic forces converters to absorb volatile corn and sugarcane price transmission while defending shelf position against mineral-coated paperboard alternatives.
Pricing Analysis
EU REACH and California SB 54 dictate the pricing tier structure across aseptic, standard fresh-dairy, and economy private-label segments. Three-tier pricing separates certified renewable-content specifications from mass-balance alternatives and conventional polyethylene constructions. Price differentiation hinges on FSC chain-of-custody certification and aseptic validation tier, with organic juice processors showing lowest sensitivity and institutional food-service buyers most responsive to per-unit cost. Cost compression in standard dairy tiers intensifies because German supermarket chains now mandate lifecycle assessment documentation for contract renewal.
Supply Chain Analysis
Strategic stockpiling of bio-polymer feedstock dominates converter inventory strategy as Thai and Brazilian sugarcane harvest volatility threatens laminate cost stability. Raw material sourcing draws from Southeast Asian polyethylene resin converters, Nordic pulp suppliers, and South American PLA feedstock growers. Single-source vulnerability concentrates in three Thai resin converters controlling majority food-grade polyethylene supply for Asian dairy packaging. Distribution runs through integrated filling equipment bundling for aseptic tiers and spot-market carton supply for standard fresh-dairy specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gable top container market approaches a platform-economics inflection where integrated filling equipment and carton supply bundling creates winner-take-most dynamics. Interoperability between aseptic validation protocols and retail sustainability scorecards is consolidating procurement around technology-integrated suppliers.
For Market Incumbents: Compound technology leadership in extended-shelf-life systems through captive filling equipment distribution and backward integration into bio-polymer barrier R&D. Defend against mineral-coated paperboard substitution by accelerating FDA food-contact substance notification timelines for novel laminates. Prioritize certification investment in mass-balance supply chain verification to meet German retailer sustainability scorecard requirements. For New Entrants and Emerging Players: Aftermarket retrofit services for legacy polyethylene-optimized filling lines represent the most penetrable service-layer gap as dairy processors face capital-intensive equipment replacement cycles. Target India's Maharashtra-Gujarat dairy belt where FSSAI compliance barriers and import-dependent aseptic equipment shortages create white space for integrated supply contracts. Pursue go-to-market positioning around rapid aseptic validation partnerships with domestic equipment fabricators. For Investors and Strategic Acquirers: Capital is best deployed toward renewable-material specialists with verified PLA laminate supply chains and established European retail relationships. Long-term viability over the next decade rests on carbon border adjustment positioning and mineral-coating technology maturation. Watch for inflection when calcium carbonate-coated substrates achieve line speed parity with polyethylene-optimized equipment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Polymer Feedstock | Brazilian sugarcane supply contracts insulate PLA laminate margins from commodity volatility. |
| Aseptic Validation Partnership | FDA notification pathways for novel barriers accelerate product launch timelines against mineral-coating alternatives. |
| Mass-Balance Certification Program | FSC chain-of-custody documentation secures German supermarket private-label contract renewals. |
| Retrofit Service Network Expansion | Legacy filling line compatibility services capture margin from dairy processors avoiding capital replacement. |
| Regional PLA Production Footprint | EU Green Deal carbon border adjustments favor regional laminate manufacturing over Asian polyethylene imports. |
Research Methodology
Operator-level perspectives from dairy plant managers, carton converter procurement leads, aseptic filling equipment engineers, and retail category buyers anchored the qualitative base. Primary interviews combined with secondary validation from FDA food-contact substance notification databases, EU ECHA REACH authorization registries, and Chinese SAMR GB standard filings. Bottom-up volume modeling triangulated against top-down value estimates using trade flow data from German, US, and Chinese customs authorities.
Sensitivity analysis tested forecast robustness across feedstock price volatility scenarios and regulatory phase-out timelines over the projection horizon. Segmentation dimensions modeled include material laminate type, end-use industry tier, capacity format, and aseptic validation status. CAGRs derived from installed base growth of filling equipment and retail procurement contract renewal patterns. Industry-specific inputs incorporated EU F-Gas Regulation phase-down schedules and California SB 54 recycled content mandate compliance trajectories.
Forecasts assume regulatory continuity in FDA food-contact frameworks, EU REACH authorization requirements, and China's SAMR enforcement posture; material policy shifts would require re-modeling. Specific risks include accelerated PFAS restrictions in US state-level legislation and unforeseen PLA feedstock supply disruptions. Revision becomes warranted when mineral-coated paperboard line speed parity crosses commercial viability thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Global Multi Pack Carriers Market
Containers
Thermoformed Containers Market
Containers
Roll Containers Market
Containers
Pail Lids Market
Containers
Global Container Monitoring Market
Containers
PUR Containers Packaging Market
Containers
Global Food Storage Container Market
Containers
Durable Insulated Containers Market
Containers
Single Wall Jars Market
Containers
Container Coating Market
Containers
Hinged Lid Compostable Container Market
Containers
Metal Cans and Glass Jars Market
Containers
APAC Container Technology Market
Containers
Twist Up Stick Container Market
Containers
Disposable Cups and Lids Market
Containers
Screw Top Jar Market