
 Canisters Market | 2026-2036
Canisters Market Size, Share, and Industry Trends Forecast 2026-2036
Canisters Market Outlook
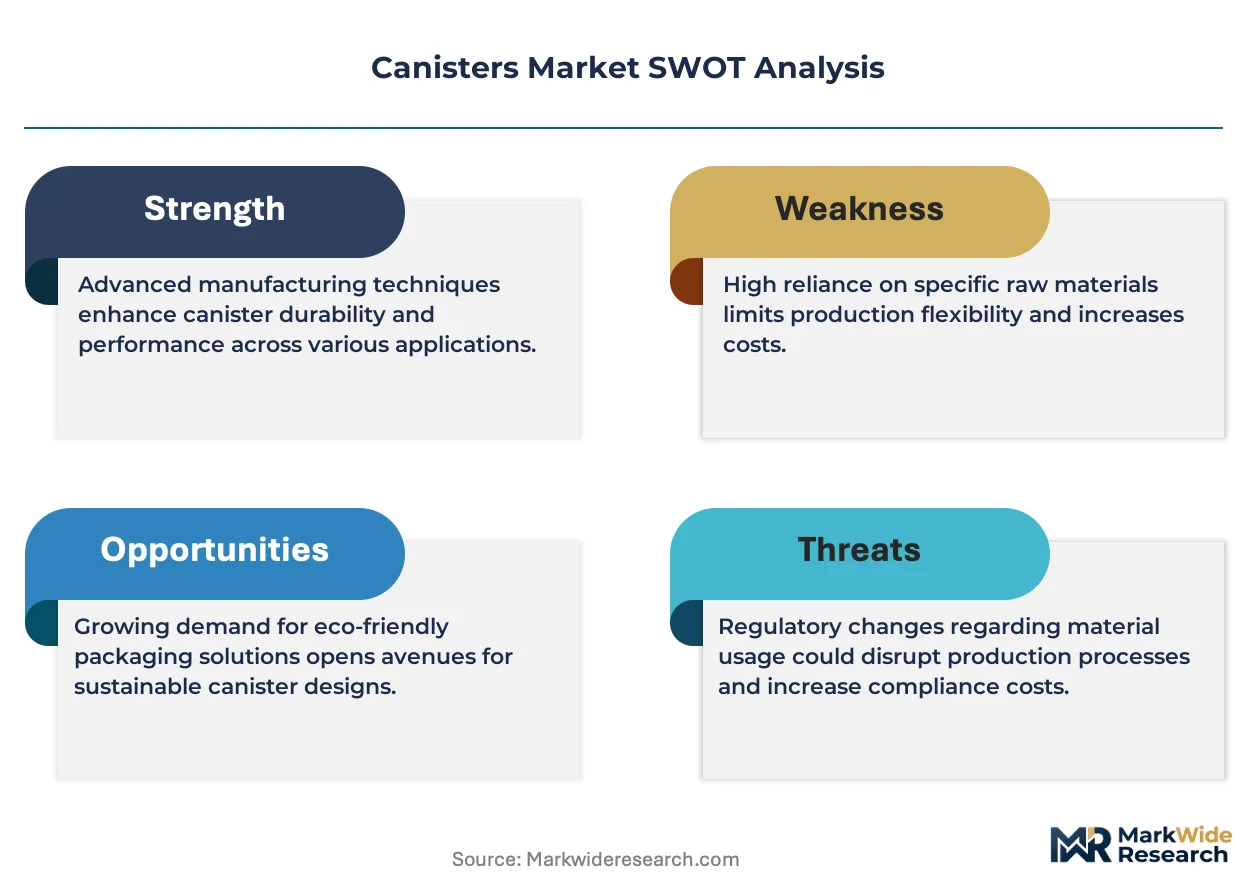
The canisters market is consolidating around a sharp split between premium pharmaceutical-grade aluminum canisters and commodity plastic household containers. Ball Corporation leverages its integrated aluminum supply chain to dominate North American aerosol production. Crown Holdings sustains European leadership through specialized glass and metal pharmaceutical packaging lines. Silgan Holdings competes aggressively in the plastic canister segment with high-volume retail formats.
Canisters are sealed cylindrical containers engineered from aluminum, steel, glass, or polymer resins, typically rated for pressure tolerance between 6 and 15 bar depending on application. They function as protective barriers for sensitive contents against moisture, oxidation, and mechanical damage across food, pharmaceutical, and industrial supply chains. Aerosol canisters lead total volume due to entrenched personal care and household spray applications, though vacuum canisters represent the fastest-expanding category driven by pharmaceutical stability requirements. Plastic canisters anchor the largest margin pool in retail food packaging where lightweighting and barrier coextrusion technologies command premium pricing.
FDA 21 CFR Part 175, EMA Annex 1 sterile manufacturing guidelines, and EU REACH chemical compliance frameworks collectively elevate material certification costs and restrict supplier pools for pharmaceutical and food-contact applications. These regulations force manufacturers to maintain dual quality systems or abandon regulated segments entirely. Stakeholders must monitor evolving PFAS restrictions and aluminum recycling mandates across multiple jurisdictions to anticipate raw material cost shifts and qualification timelines.
Market Dynamics
Pharmaceutical-grade aluminum canister demand is compressing supplier qualification timelines as FDA and EMA tighten extractables testing protocols, forcing dual-certification investments across North American and European supply chains.
Growth Catalysts
- EMA Annex 1 sterile manufacturing:Revised guidelines mandate higher barrier integrity for inhalation drug canisters, accelerating pharmaceutical aluminum adoption across EU manufacturing clusters.
- Barrier coextrusion:Multi-layer polymer technologies enable oxygen transmission rates below 0.1 cc per square meter daily, unlocking extended shelf-life applications in retail food packaging.
- German industrial vacuum canister concentration:Specialized pharmaceutical stability testing infrastructure around Frankfurt and Stuttgart attracts contract manufacturing investment for biologic storage formats.
Market Restraints
- Aluminum ingot cost volatility:LME pricing swings and energy surcharges in European smelting operations compress margin predictability for aerosol canister producers.
- Supplier concentration in pharmaceutical-grade aluminum:Four primary rolling mills control certified 3104-H19 alloy supply, creating qualification bottlenecks for new market entrants.
- PFAS restriction timelines:EU REACH and state-level US prohibitions on fluoropolymer barrier coatings force reformulation investments ahead of compliance deadlines.
Strategic Opportunities
- Indian pharmaceutical packaging expansion:CDSCO alignment with ICH Q3D elemental impurity guidelines creates demand for certified aluminum canister supply as domestic inhaler production scales.
- Connected canister integration:NFC-enabled compliance tracking for dose-counter inhalers merges electronics with primary packaging, opening premium service revenue streams.
- Closed-loop aluminum recovery:EU Green Deal recycling mandates and deposit schemes in Germany and Scandinavia incentivize post-consumer scrap integration into aerosol canister production.
Industry Challenges
- Extractables testing capacity:Pharmaceutical canister qualification requires 18-24 month analytical validation cycles at limited certified laboratories, delaying product launches.
- Legacy steel canister equipment retrofit:Converting tinplate aerosol lines to aluminum-compatible welding and necking tooling demands capital outlays exceeding typical mid-cap maintenance budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canisters Market |
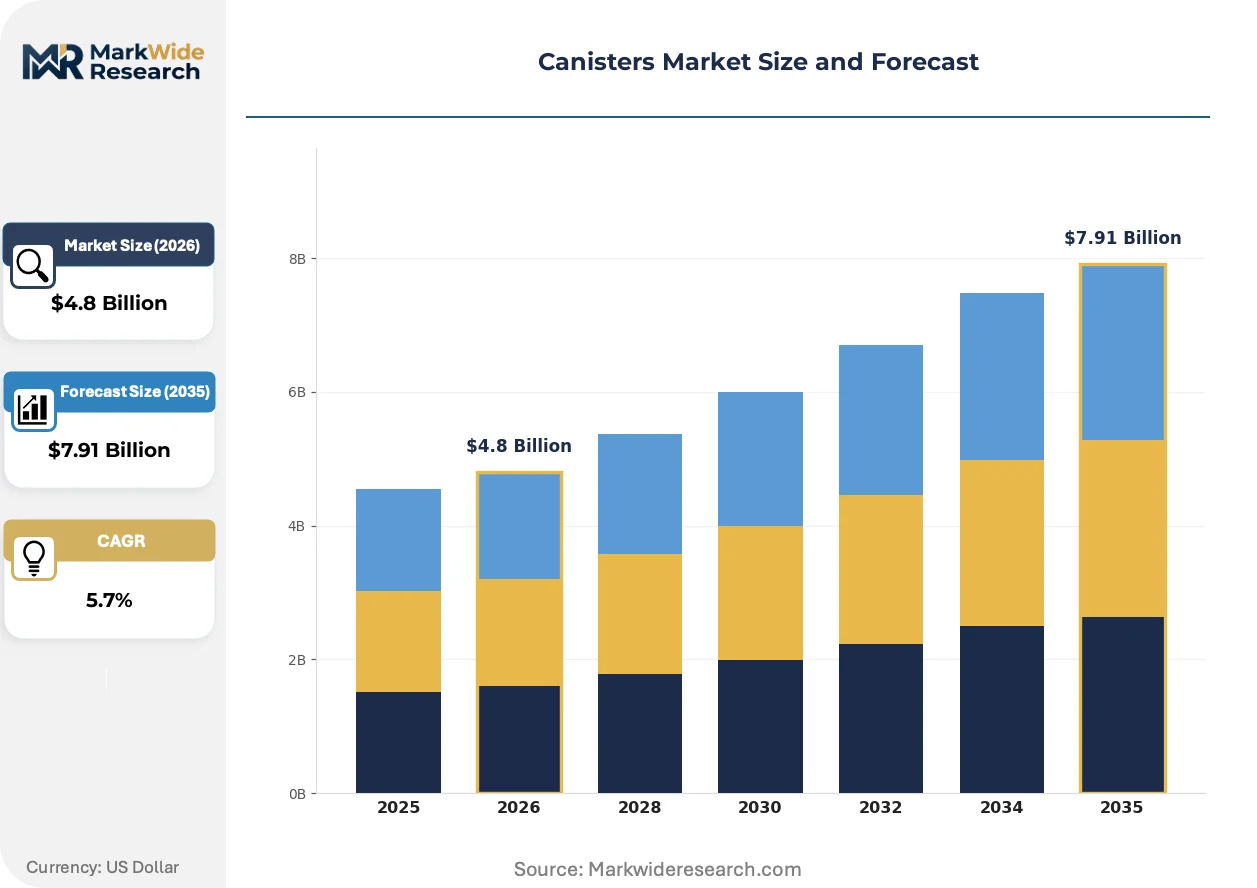
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aerosol Canisters, Vacuum Canisters, Glass Canisters, Plastic Canisters End User: Food & Beverage, Pharmaceuticals, Household, Industrial Material: Aluminum, Glass, Plastic, Steel Packaging Type: Bulk Packaging, Retail Packaging, Custom Packaging, Standard Packaging |
| Companies Covered | Ball Corporation, Berry Global Group, Crown Holdings, Silgan Holdings, Ardagh Group, PMF Industries, Burkle GmbH, Semadeni AG, Thermo Fisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canisters Market Strategic Shifts
Active barrier technologies and regulatory chemistry restrictions are reconfiguring material selection criteria across pharmaceutical and food-contact segments, compressing traditional commodity-specialty boundaries.
High-barrier ethylene vinyl alcohol coextrusion is integrating with polypropylene structural layers to create sub-0.5 gram lightweight canisters for moisture-sensitive nutraceuticals. Contract packagers serving US supplement brands are adopting these formats at accelerated qualification paces. The technology is integrating oxygen scavenger functionality directly into container walls, eliminating secondary sachet requirements and reducing total package mass.
EU REACH restrictions on per- and polyfluoroalkyl substances are eliminating fluoropolymer interior coatings historically used in aluminum pharmaceutical canisters. German and French canister manufacturers are accelerating ceramic-anodized and sol-gel alternative qualification programs with regional pharmaceutical customers. FDA has issued draft guidance requesting additional migration data for replacement coatings, extending approval timelines for US market entry.
Direct-to-pharmacy distribution models are bypassing wholesale consolidation layers for temperature-sensitive biologic canister shipments. Specialty logistics providers in the Netherlands and Belgium are building certified GDP-compliant last-mile networks. This channel restructuring concentrates volume with integrated packaging-distribution specialists and compresses spot-market spot-buying for standard aerosol formats.
Canisters Market Segmentation
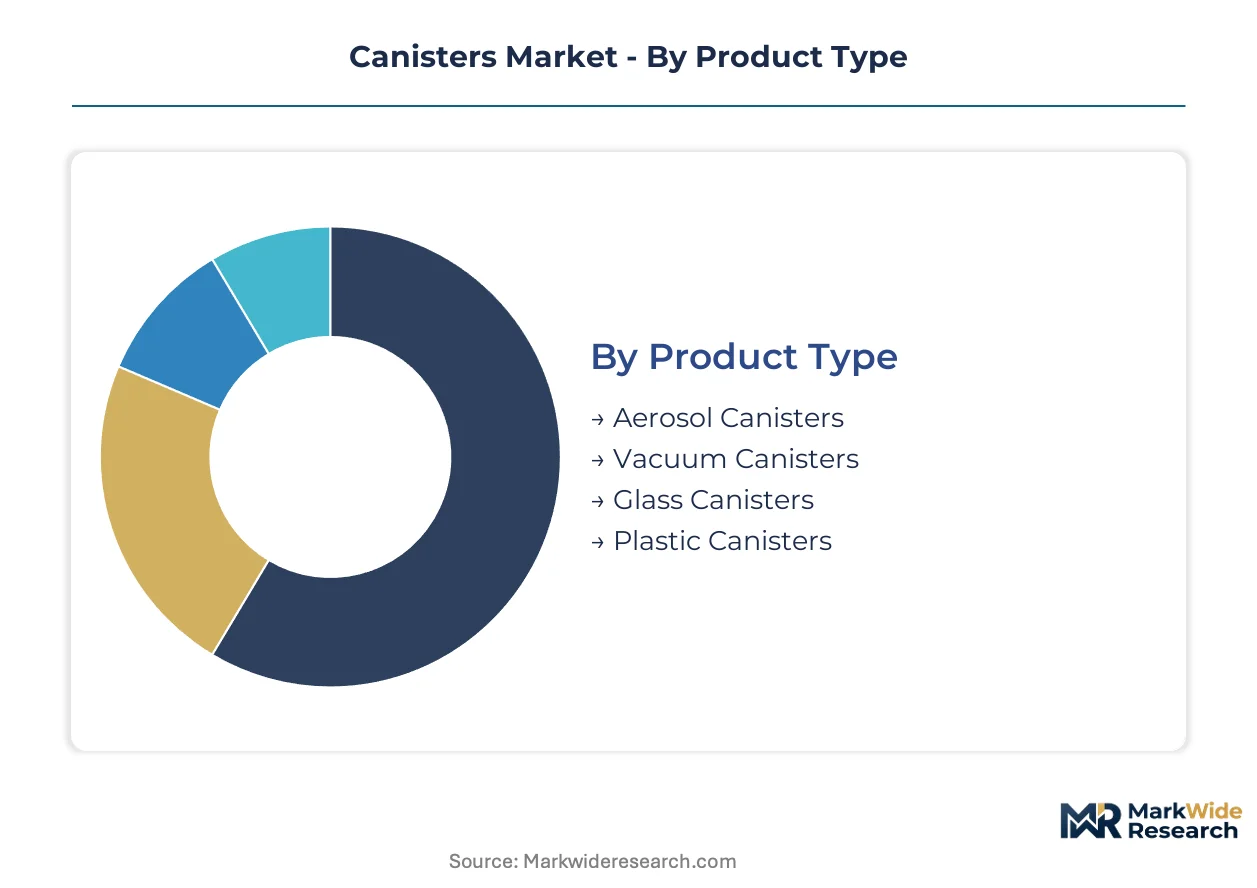
Canister segmentation reveals how capital allocation, regulatory burden, and end-use performance requirements fragment supply chain investment priorities. Material selection and product architecture determine which segments absorb the majority of qualification spending and capacity expansion.
Product Type:
Capital intensity peaks in aluminum aerosol manufacturing where integrated rolling, coating, and necking lines demand nine-figure facility investments. Vacuum canister production requires lower equipment outlays but concentrates validation spending on pharmaceutical extractables testing.
- Aerosol Canisters:Aluminum-dominated pressure vessels rated for 6-15 bar, manufactured through impact extrusion or drawn-and-ironed processes. Demand clusters in US and German personal care manufacturing where EPA and ECHA propel reformulation toward hydrocarbon and compressed gas propellants.
- Vacuum Canisters:Specialized containers engineered for sub-atmospheric pressure stability, typically anodized aluminum or borosilicate glass construction. German pharmaceutical clusters around Frankfurt and Stuttgart concentrate demand as EMA Annex 1 sterile manufacturing guidelines tighten barrier integrity requirements for biologic storage.
- Glass Canisters:Borosilicate or soda-lime silicate vessels with superior chemical inertness for high-purity pharmaceutical applications.
- Plastic Canisters:Polypropylene and polyethylene terephthalate containers dominating retail food packaging through barrier coextrusion and lightweighting technologies.
Most installed capacity flows through Aerosol Canisters. Expansion is steepest in Vacuum Canisters.
End User:
Customer-type segmentation tracks how regulatory stringency and volume scale split procurement patterns between spot-market commodity purchasing and long-term contract manufacturing agreements.
- Food & Beverage:Retail-facing brands drive lightweight plastic canister demand with oxygen transmission specifications below 0.1 cc per square meter daily. US supplement contract packagers accelerate qualification of high-barrier ethylene vinyl alcohol coextrusion formats.
- Pharmaceuticals:Inhalation drug and biologic stability applications command premium aluminum and glass specifications with 18-24 month FDA and EMA extractables validation cycles. CDSCO alignment with ICH Q3D guidelines in India creates incremental certified supply demand.
- Household:Commodity aerosol applications in cleaning and personal care products where aluminum cost volatility compresses margin predictability.
- Industrial:Lubricant, adhesive, and specialty chemical containment with moderate barrier requirements and price-sensitive procurement.
Pharmaceuticals captures the highest margin pool. Food & Beverage generates the largest unit volume.
Material:
Raw material selection determines recycling economics, regulatory compliance pathways, and supplier concentration risk across the value chain.
- Aluminum:3104-H19 alloy dominates aerosol and pharmaceutical vacuum applications through impact extrusion and deep drawing. Four primary rolling mills control certified pharmaceutical-grade supply, creating qualification bottlenecks.
- Glass:Borosilicate and Type I soda-lime compositions for parenteral and high-purity pharmaceutical applications with superior extractables profiles.
- Plastic:Polypropylene structural layers with ethylene vinyl alcohol barrier films achieving sub-0.5 gram lightweight targets for moisture-sensitive nutraceuticals.
- Steel:Tinplate and tin-free steel in legacy aerosol lines facing retrofit pressure toward aluminum-compatible welding and necking tooling.
Aluminum commands the steepest capital commitments. Plastic offers the lowest barrier to capacity entry.
Packaging Type:
Format segmentation distinguishes between standardized high-volume production and customized specifications requiring flexible manufacturing footprints.
- Bulk Packaging:Intermediate containers for business-to-business chemical and ingredient shipment with standardized dimensions and minimal decoration.
- Retail Packaging:Consumer-facing formats with integrated labeling, tamper-evidence, and shelf-display optimization for supermarket and pharmacy channels.
- Custom Packaging:Specification-driven formats for pharmaceutical dose-counter inhalers and connected canister integration with NFC-enabled compliance tracking.
- Standard Packaging:Catalog aerosol and canister specifications serving spot-market procurement with minimal lead times.
Retail Packaging absorbs the majority of decoration and barrier technology investment. Custom Packaging climbs the fastest as direct-to-pharmacy distribution models expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized aluminum rolling mill engineers and pharmaceutical extractables chemists concentrate in German industrial clusters, while aerosol formulation technicians dominate US Gulf Coast manufacturing corridors. These workforce distributions anchor regional competitive advantages in distinct canister sub-segments.
United States
EPA propellant regulations and FDA extractables protocols drive pharmaceutical-grade aluminum demand for inhalation drug delivery. The IRA domestic manufacturing incentives support capital-intensive impact extrusion line investments. Houston and New Jersey pharmaceutical corridors concentrate contract packaging capacity for dose-counter inhalers.
Germany
EMA Annex 1 sterile manufacturing guidelines accelerate vacuum canister adoption for biologic stability applications. EU Green Deal recycling mandates and deposit schemes incentivize closed-loop aluminum recovery integration. Frankfurt and Stuttgart clusters host specialized pharmaceutical stability testing infrastructure attracting contract manufacturing investment.
India
CDSCO alignment with ICH Q3D elemental impurity guidelines creates certified aluminum canister demand as domestic inhaler production scales. PLI scheme incentives for pharmaceutical manufacturing support packaging supply chain localization. Gujarat and Maharashtra pharmaceutical hubs concentrate formulation and packaging investment.
China
NMPA tightened pharmaceutical packaging material safety standards elevate barrier integrity requirements for domestic drug manufacturers. Dual carbon goals and energy efficiency mandates pressure aluminum smelting operations toward renewable power sourcing. Yangtze River Delta manufacturing clusters integrate canister production with downstream aerosol filling capacity.
Japan
PMDA stability testing requirements for inhaled products sustain premium aluminum canister specifications with extended validation cycles. METI circular economy roadmaps promote post-consumer aluminum scrap integration into aerosol production. Osaka pharmaceutical manufacturing corridors maintain specialized barrier coating qualification programs.
Canisters Market Competitive Environment
Top-tier vendors anchor integrated aluminum supply chains, while mid-cap specialists occupy niche pharmaceutical certification segments. The vendor base stratifies between capital-intensive rolling mill operators and flexible contract packaging service providers. Three archetypes dominate: integrated metal packaging conglomerates, pharmaceutical-grade certification specialists, and regional plastic barrier technology firms. Competitive moves concentrate on backward integration into aluminum rolling capacity and strategic partnerships for connected canister electronics integration.
Within the integrated metal packaging tier, Ball Corporation and Crown Holdings occupy positions exemplifying scale-driven supply chain control. Silgan Holdings represents the diversified packaging archetype spanning multiple material substrates. These three entities anchor competitive dynamics through their distinct approaches to capital deployment and customer segment prioritization.
| Leading Market Players |
|---|
| Ball Corporation |
| Berry Global Group |
| Crown Holdings |
| Silgan Holdings |
| Ardagh Group |
| PMF Industries |
| Burkle GmbH |
| Semadeni AG |
| Thermo Fisher Scientific |
| Others |
Value Chain & Pricing Dynamics
EMA Annex 1 sterile manufacturing guidelines are compressing supplier qualification timelines for pharmaceutical-grade aluminum canisters, forcing buyers to absorb premium pricing for dual-certified supply or abandon regulated segments entirely. This specification tightening concentrates procurement power with integrated rolling mill operators while spot-market commodity aerosol buyers face volatile aluminum ingot pass-through costs.
Pricing Analysis
Bundled extractables testing and certification services now command substantial premiums over unbundled canister-only transactions. Three-tier pricing structure across pharmaceutical-grade, food-contact certified, and commodity industrial tiers reflects divergent validation burdens and barrier performance specifications. Cost compression in household aerosol segments is intensifying because LME aluminum volatility and energy surcharges compress margin predictability. Food and beverage contract packagers exhibit highest price sensitivity due to lightweighting mandates and retail margin pressure, while pharmaceutical inhalation drug manufacturers demonstrate lowest sensitivity given regulatory non-substitutability.
Supply Chain Analysis
Freight cost differentials between German pharmaceutical clusters and Asian manufacturing hubs are reshaping regional sourcing patterns for vacuum canister demand. Supply concentrates in Germany, the United States, and China, with certified 3104-H19 alloy rolling capacity anchored in European and North American mill networks. The value chain draws from aluminum ingot, barrier coating chemicals, and precision necking equipment as critical inputs. Single-source vulnerability in pharmaceutical-grade rolling mill certification creates qualification bottlenecks for new market entrants. Distribution runs through direct-to-pharmacy networks for biologic canisters and wholesale consolidation layers for standard aerosol formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through premium-tier pharmaceutical certification as EMA and FDA protocols eliminate commodity competitors, while closed-loop aluminum recovery programs in Germany and Scandinavia unlock input cost reductions.
For Market Incumbents: Anticipate PFAS coating replacement timelines by accelerating ceramic-anodized and sol-gel alternative qualification programs ahead of EU REACH enforcement waves. Deepen captive supply of certified 3104-H19 alloy through backward integration into rolling mill partnerships or long-term offtake agreements with the four primary certified suppliers, defending against new entrant qualification delays. For New Entrants and Emerging Players: CDSCO alignment with ICH Q3D elemental impurity guidelines in India opens a window for certified aluminum canister supply as domestic inhaler production scales and PLI scheme incentives localize pharmaceutical manufacturing. Target Indian pharmaceutical hubs in Gujarat and Maharashtra with contract packaging service models that bundle GDP-compliant distribution with primary packaging supply, bypassing capital-intensive rolling mill investments. For Investors and Strategic Acquirers: Asymmetric upside sits with pharmaceutical-grade certification specialists possessing established FDA and EMA extractables validation cycles and integrated barrier coating technology portfolios. Long-term viability over a multi-year horizon rests on regulatory chemistry restriction compliance capabilities rather than commodity volume scale. Monitor PFAS restriction implementation timelines across EU member states and US state-level jurisdictions as the primary inflection indicator for coating technology replacement demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Rolling Capacity | Captive supply of certified 3104-H19 alloy insulates margin from LME volatility and qualification bottlenecks. |
| Connected Canister Electronics Integration | NFC-enabled dose-counter inhalers merge primary packaging with compliance tracking, opening premium service revenue streams. |
| Ceramic-Anodized Coating Qualification Program | EU REACH PFAS restrictions eliminate fluoropolymer alternatives, creating first-mover advantage with EMA-validated replacements. |
| Closed-Loop Aluminum Recovery Integration | EU Green Deal recycling mandates and German deposit schemes reduce raw material input costs for aerosol production. |
| Direct-to-Pharmacy Distribution Network Buildout | GDP-compliant last-mile infrastructure in the Netherlands and Belgium captures biologic canister volume bypassing wholesale layers. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation across regulatory filings and trade databases. Primary interviews engaged pharmaceutical packaging procurement directors, aluminum rolling mill technical sales leads, contract manufacturing quality assurance managers, and EMA regulatory affairs consultants. Secondary sources incorporated FDA 21 CFR filings, EMA Annex 1 guideline revisions, EU REACH restriction timelines, SEC 10-K packaging segment disclosures, and customs trade flow data. Bottom-up capacity and demand modeling triangulated against top-down market sizing from industry associations.
Rate-of-change decomposition across the analysis window separated volume growth from price and mix effects, with CAGRs derived from segment-level regression against pharmaceutical production indices and aerosol formulation trends. Segmentation dimensions modeled include product type, material substrate, end-use industry, and regional regulatory cluster. Industry-specific forecast inputs incorporated inhalation drug pipeline advancement rates and EU Green Deal recycling mandate implementation schedules.
Revisions become necessary when PFAS restriction timelines accelerate, aluminum smelting energy cost structures shift, or pharmaceutical extractables testing capacity constraints worsen. Forecasts reflect assumptions about regulatory enforcement consistency and raw material supply continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Packaging Bins Market
Containers
Gable Top Container Market
Containers
EPS Container Market
Containers
Cups and Lids Market
Containers
Car Lube Container Market
Containers
Trays Market
Containers
Global Food Storage Container Market
Containers
Cylindrical Cans Market
Containers
Foldable Container Market
Containers
Safety Bottle Tote Carriers Packaging Market
Containers
Food Grade Stainless Steel Container Market
Containers
Collapsible Crate Market
Containers
Hinged Deli Containers Market
Containers
Acrylic Container Market
Containers
Aluminum Foil Containers Market
Containers
Global Flexitanks Market