
 Mason Jars Market | 2026-2036
Mason Jars Market Size, Share, and Industry Trends Forecast 2026-2036
Mason Jars Market Intelligence
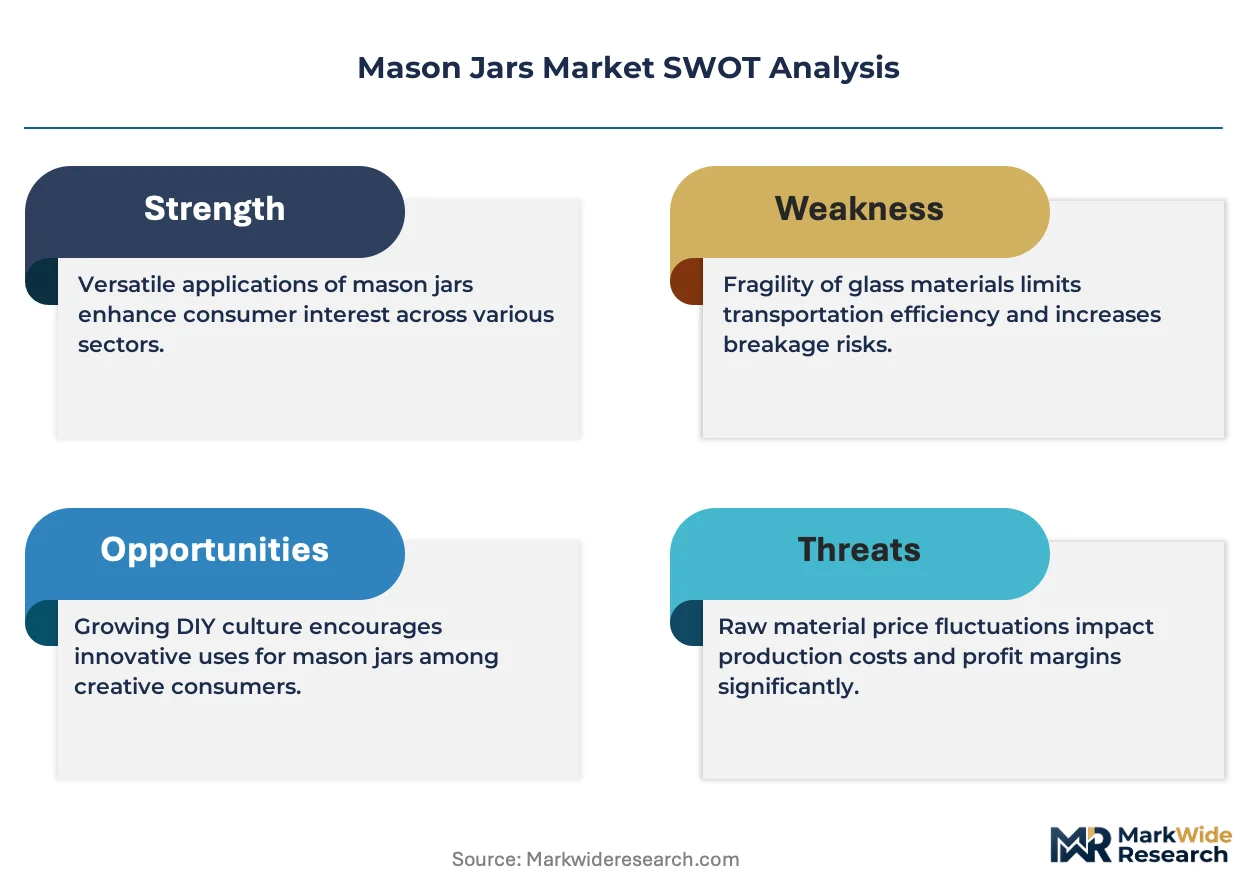
The unbundling of jars from traditional two-piece canning lids is decoupling the product's value from its historical food preservation function. This shift allows for new applications in drinkware, storage, and decor. Ball Corporation sustains its market position through powerful brand equity in the North American home canning sector. Libbey specializes in glassware for the foodservice industry, positioning jars as trendy beverage containers. Meanwhile, global glass manufacturer Verallia competes by supplying bulk jars to large-scale food processing clients for items like jams and sauces.
A mason jar is a molded glass container defined by its threaded neck, which accommodates a screw-on lid. The classic design incorporates a two-part closure system, comprising a flat rubber-ringed steel lid and a separate threaded band, engineered to create a hermetic seal for canning. While standard canning jars for home preservation represent a mature segment, demand from cafes and restaurants for beverage service is expanding rapidly. The 16 oz and 32 oz capacities remain staples for food processing, but smaller 4 oz and 8 oz jars are gaining share for single-portion desserts and craft applications.
The market operates under strict food safety regulations that govern materials in contact with food. In the United States, the FDA sets standards for glass composition and the coatings used on metal lids. Similarly, the European Union's Regulation (EC) No 1935/2004 establishes a legal framework for all food contact materials, ensuring they do not transfer harmful substances to food. These compliance requirements directly influence material sourcing and manufacturing processes. Stakeholders must now balance investments between the high-volume, regulated food preservation market and the more fragmented, design-led consumer goods sector.
Market Dynamics
The central structural force shaping the market is the decoupling of the mason jar from its exclusive food preservation function. This is driven by consumer demand for aesthetic, reusable containers in foodservice and home decor, creating a new value stream separate from traditional canning.
Growth Catalysts
- Regulatory Pressure:The European Union's single-use plastics directives push food vendors toward reusable glass containers for beverages and takeaway items, directly benefiting jar manufacturers.
- Consumer Behavior:The rise of home organization and DIY craft cultures, particularly visible in the United States, creates consistent demand for various jar sizes for non-food storage and decorative projects.
- Foodservice Adoption:The foodservice sector's use of jars for serving signature cocktails, layered desserts, and salads enhances customer experience and provides a durable, washable alternative to disposable drinkware.
Market Restraints
- Input Cost Volatility:Fluctuations in the price of soda ash and energy, key inputs for glass manufacturing, create margin pressure and can lead to price volatility for bulk purchasers.
- Substitution Threat:The availability of lower-cost, lighter-weight plastic and metal containers with screw-top lids presents a significant substitution threat, especially in high-volume, non-canning applications.
- Logistical Costs:Glass jars are heavy and fragile, leading to high transportation costs and breakage rates, which complicates logistics and adds expense for long-distance shipping.
Strategic Opportunities
- Application Expansion:Development of specialized jars for emerging uses like cold brew coffee kits, fermentation systems for kimchi or kombucha, and modular pantry organization systems offers new product lines.
- Geographic Penetration:Expansion into markets in South America and Southeast Asia, where home preserving traditions are present but the commercial "lifestyle" use of jars is underpenetrated, presents a growth vector.
- Product Enhancement:Introducing jars with features like UV-protective coatings for light-sensitive products or integrated measurement markings for culinary use can command premium pricing.
Industry Challenges
- Manufacturing Consistency:Maintaining consistent glass quality and wall thickness across high-speed production lines is a persistent operational challenge, with defects leading to waste and potential safety issues.
- Compliance Complexity:Navigating the fragmented landscape of food contact material regulations, such as differing standards for lid coatings between the FDA and EFSA, requires significant compliance investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mason Jars Market |
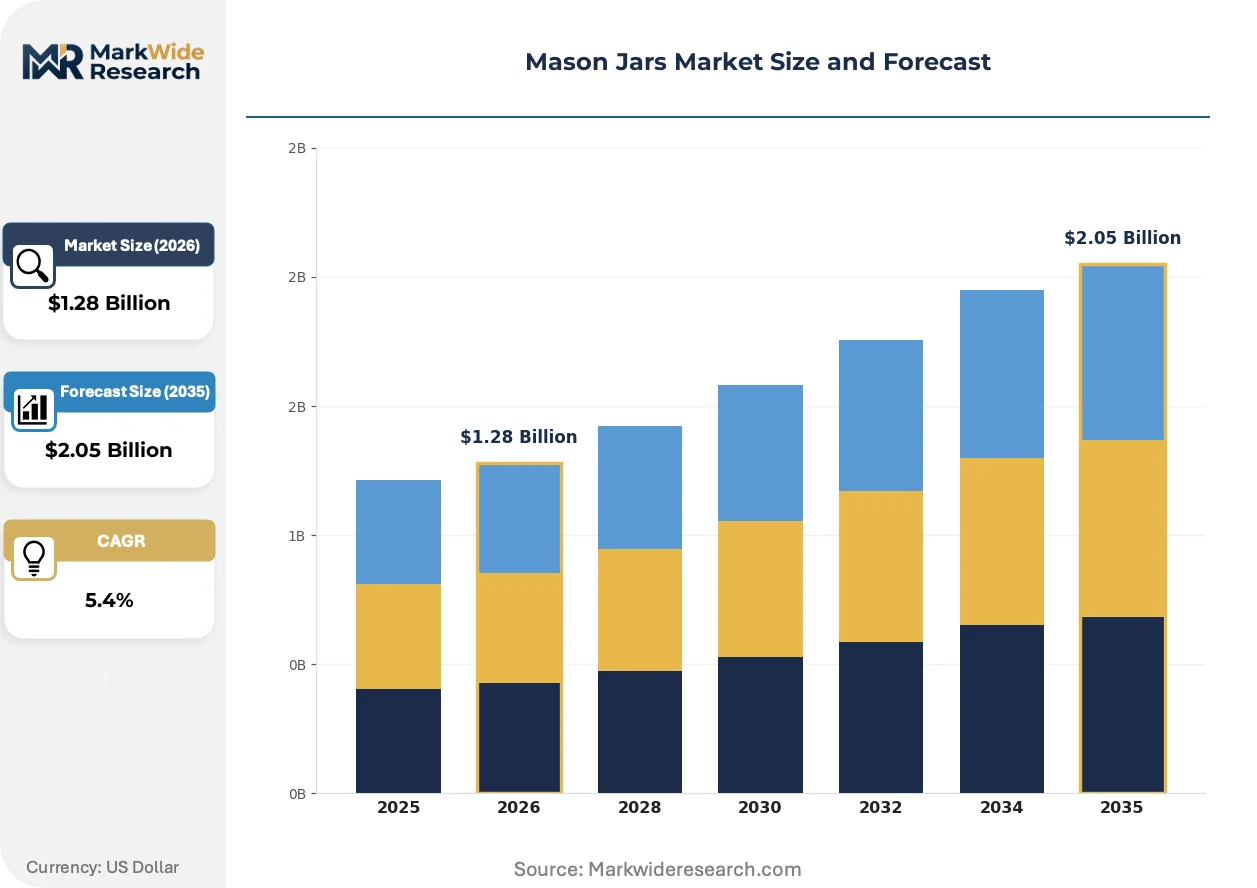
| Market Size in 2026 | $1.28 Billion |
| Market Size in 2035 | $2.05 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Mason Jars, Wide Mouth, Specialty Colored, Canning Jars, Jars with Lids Capacity: 4 oz, 8 oz, 16 oz, 32 oz, 64 oz Distribution Channel: Supermarkets & Hypermarkets, Online Retailers, Specialty Kitchen Stores, Wholesale Distributors End User: Home Kitchen, Food Processing Units, Craft & DIY Enthusiasts, Cafes & Restaurants |
| Companies Covered | Verallia, Libbey, Ball Corporation, Saint-Gobain Glass Packaging, Berlin Packaging, Owens-Illinois, Anchor Hocking, Weck, Ardagh Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mason Jars Market Strategic Shifts & Innovations
The market's evolution is defined by a pivot from a utilitarian preservation tool to a versatile lifestyle product. This transition is influenced by material science advancements and a fundamental shift in consumer perceptions of packaging sustainability and aesthetics.
Lightweighting technology produces glass jars with reduced material without compromising structural integrity. The foodservice industry is a primary adopter, seeking lower shipping weights. This material science innovation is converging with decorative techniques like embossing, enabling brands to create distinctive packaging that doubles as a collectible.
The European Union's Regulation (EC) No 1935/2004 governs food contact materials, ensuring they do not endanger human health. This compels manufacturers to rigorously document all components, from glass composition to lid sealants. The home canning segment is most affected, as producers must guarantee performance while adhering to strict chemical migration limits.
A preference for product transparency drives a "show-the-product" packaging philosophy in the food and beverage sector. This disrupts the dominance of opaque packaging for items like layered sauces, colorful beverages, and artisanal jams. This trend is most pronounced in North American and European organic food markets, where visual appeal reinforces natural product claims.
Mason Jars Market Segmentation
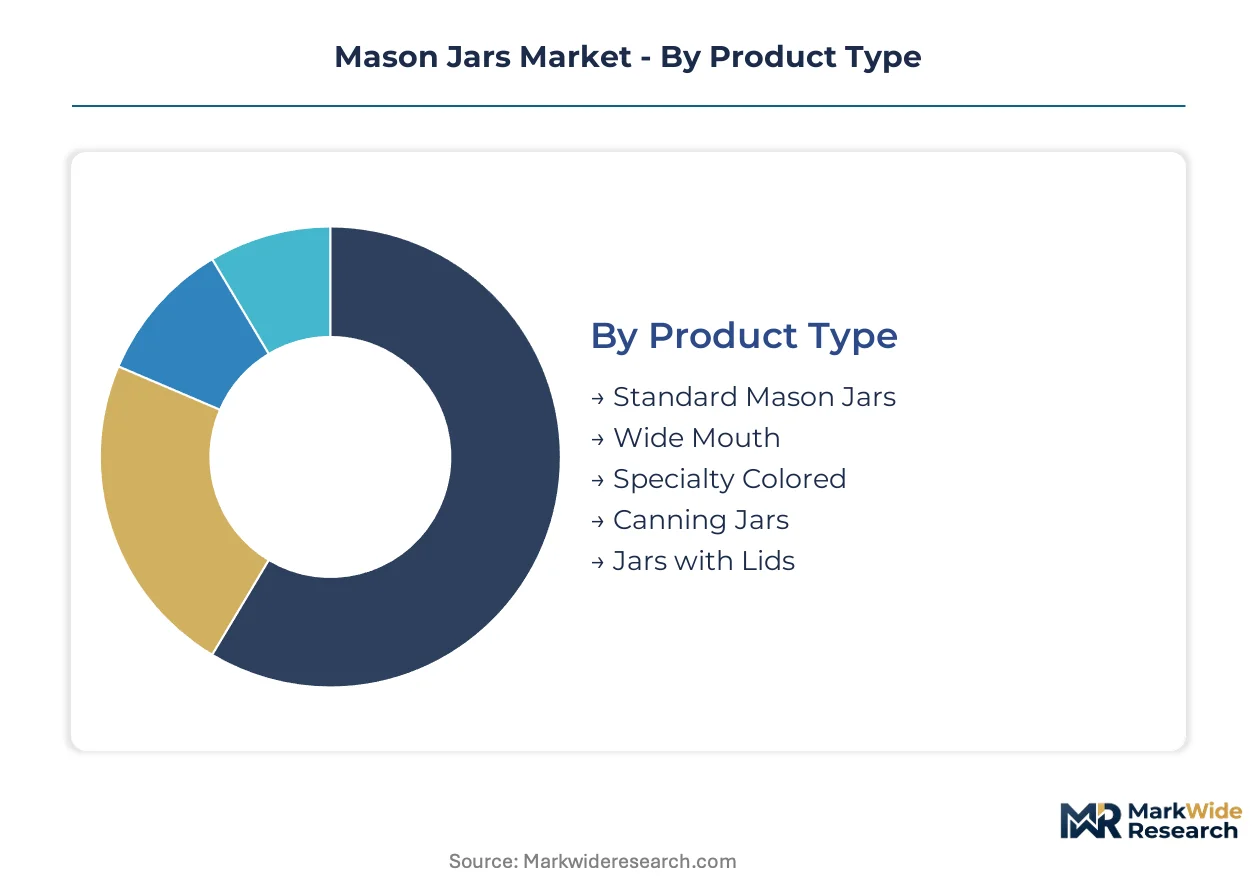
The Mason Jars market structure reflects diverse applications and consumer needs, moving beyond its traditional role. Understanding these segments helps manufacturers allocate resources effectively, from specialized production lines to targeted marketing campaigns. Each segment presents distinct material requirements and distribution logistics.
Product Type:
Certain product types within the Mason Jars market demand substantial upfront capital investment for specialized tooling and manufacturing processes.
- Canning Jars:These glass containers feature specific wall thickness and annealing for thermal shock resistance, crucial for safe home food preservation. Demand concentrates in the United States, driven by established home canning traditions and FDA compliance.
- Specialty Colored:These jars incorporate pigments or coatings for aesthetic effects, appealing to design-conscious consumers and decor applications. Production requires additional processes and quality control, leading to higher unit costs.
- Standard Mason Jars:Clear, unadorned glass jars serve general-purpose storage, craft, and beverage applications.
- Wide Mouth:Jars with a larger opening facilitate easier filling and cleaning, preferred for bulky items.
- Jars with Lids:These complete units include the glass jar and a corresponding two-piece or single-piece lid.
Standard Mason Jars absorbs the bulk of installed capacity; Specialty Colored is expanding most quickly.
Capacity:
Capacity segmentation directly influences the primary use case and logistical considerations for Mason Jars, dictating suitability for various consumer and industrial applications.
- 16 oz:This capacity is a versatile standard for home canning and beverage service in cafes and restaurants. Its balanced size suits single-serve drinks and moderate food portions, driving foodservice demand.
- 32 oz:Often referred to as a quart, this larger capacity is a staple for bulk food preservation and larger beverage servings. Food processing units rely on this size for packaging jams and sauces in European markets.
- 4 oz:Small 4 oz jars are gaining share for single-portion desserts, samples, and craft projects.
- 8 oz:This half-pint capacity is popular for jellies, small batch preserves, and individual yogurt preparations.
- 64 oz:The largest standard capacity, 64 oz jars are typically used for fermenting kombucha or storing dry goods.
The preference for 16 oz and 32 oz capacities remains strong in commercial food applications, while smaller sizes see significant uptake in craft and single-serve markets.
Distribution Channel:
The choice of distribution channel for Mason Jars significantly impacts market reach and customer engagement, catering to different purchasing behaviors and volume requirements.
- Online Retailers:E-commerce platforms offer extensive product variety and direct-to-consumer convenience, reaching craft enthusiasts and home users. This channel benefits from lower overheads and direct shipping capabilities.
- Wholesale Distributors:These channels serve large-volume purchasers like food processing units and foodservice suppliers, handling bulk orders and complex logistics. They supply commercial clients with consistent product volumes.
- Supermarkets & Hypermarkets:These large format stores provide convenient access for general consumers seeking jars for home use.
- Specialty Kitchen Stores:These retailers cater to avid home cooks and canning enthusiasts, offering premium brands and curated selections.
Online Retailers demonstrate the fastest expansion in market penetration, driven by evolving consumer purchasing habits.
End User:
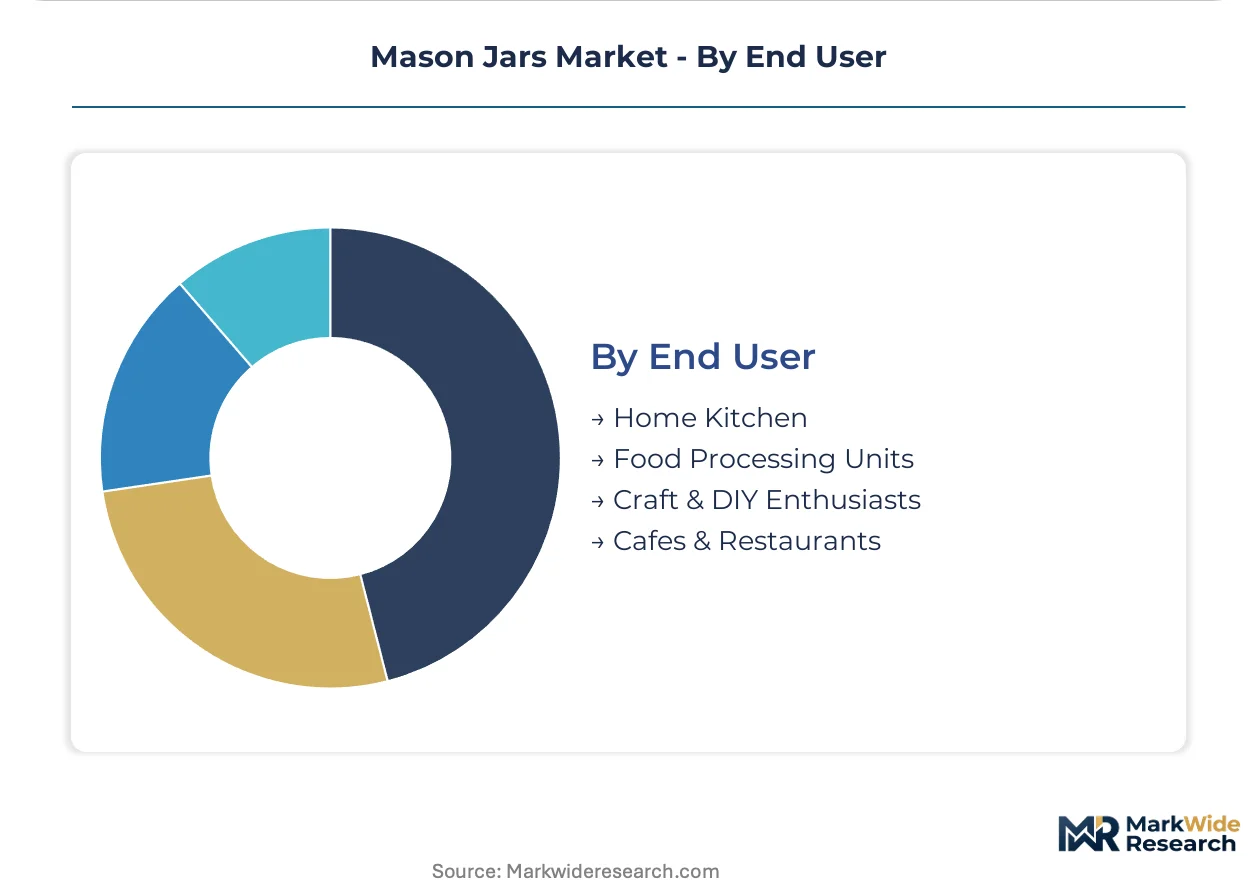
End-user segmentation reveals distinct purchasing motivations and product requirements for Mason Jars, influencing design and marketing strategies across various consumer and commercial sectors.
- Cafes & Restaurants:This segment increasingly adopts Mason Jars for serving beverages and desserts, valuing aesthetic appeal, reusability, and durability. European Union directives against single-use plastics provide a strong tailwind.
- Food Processing Units:Large-scale food manufacturers utilize jars for packaging jams, sauces, and preserves, requiring consistent quality and adherence to stringent food safety regulations. These units demand high volumes and reliable supply chains.
- Home Kitchen:Consumers use jars for traditional home canning, dry food storage, and general organization.
- Craft & DIY Enthusiasts:This segment employs jars for decorative projects, gift packaging, and creative storage solutions.
The Cafes & Restaurants segment is exhibiting the steepest expansion trajectory, while Food Processing Units maintain a consistent demand base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The European Union's comprehensive regulatory framework, particularly directives against single-use plastics, creates a concentrated demand for reusable glass containers across its member states. This policy environment strongly benefits jar manufacturers, driving adoption in commercial and consumer segments. Strong home-canning traditions in other regions also underpin significant market volumes.
United States
Demand in the United States benefits from a robust home canning culture and a strong DIY craft movement. Consumer preference for aesthetic storage solutions fuels demand for various jar sizes. The FDA sets stringent standards for glass composition and lid coatings for food contact materials. Major manufacturers often concentrate production in states like Indiana, benefiting from established logistics networks.
Germany
Germany represents a significant European market, driven by its large food processing industry for jams and sauces. Regulatory compliance under EU Regulation (EC) No 1935/2004 ensures high material quality. The foodservice sector in cities like Berlin increasingly adopts jars for sustainable beverage service. German consumers also value glass for its reusability and environmental benefits.
France
The French market sees demand from large-scale food processors and a growing artisanal food sector. Companies must adhere to EU food contact material regulations, influencing sourcing and manufacturing. Verallia, a global glass manufacturer, operates significant production facilities in France, supplying bulk jars. Parisian cafes increasingly use mason jars for trendy drinks, aligning with sustainability trends.
United Kingdom
The United Kingdom shows consistent demand from home preservers and a vibrant craft community. Post-Brexit, the UK maintains alignment with many EU food contact material standards, such as those governing lid sealants. London's diverse culinary scene heavily utilizes jars for innovative dessert presentations and cocktail service. Retail channels actively promote jars for home organization.
Brazil
Brazil offers significant growth potential as lifestyle applications for mason jars gain traction beyond traditional preservation. Local regulations, often mirroring international food safety guidelines, govern packaging materials. The country's large consumer base in urban centers like São Paulo drives interest in jars for beverages and home decor. Home preserving traditions also contribute to demand.
Mason Jars Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the Mason Jars market, creating a tiered competitive structure. Established glass manufacturers and packaging giants coexist with niche brands targeting specific consumer segments. Strategic archetypes include large-volume industrial suppliers, brand-equity-driven home consumer goods companies, and specialized foodservice providers. Companies actively pursue portfolio diversification into new applications and geographic expansion to capture growth opportunities.
Specialized manufacturers like Ball Corporation anchor the North American home canning sector, leveraging strong brand equity among home preservers. Global glass manufacturer Verallia, operating as a Société Anonyme, exemplifies the large-scale bulk jar supply segment for food processing clients. Libbey, an Inc.-structured company, occupies a position within the foodservice industry, positioning jars as trendy beverage containers. These players collectively shape market dynamics through their distinct operational focuses and distribution networks, addressing varied end-user requirements.
| Leading Market Players |
|---|
| Verallia |
| Libbey |
| Ball Corporation |
| Saint-Gobain Glass Packaging |
| Berlin Packaging |
| Owens-Illinois |
| Anchor Hocking |
| Weck |
| Ardagh Group |
| Others |
Cost & Logistics Intelligence
The European Union's single-use plastics directives gate qualified supply and access to premium-tier pricing for reusable glass containers. These mandates compel manufacturers to meet stringent material and performance standards, influencing production costs and market value. This regulatory environment shapes both the availability of compliant products and their pricing power across various end-use segments.
Pricing Analysis
Margin tightening in the bulk jar segment reflects intense competition and input cost volatility. Per-unit transactional pricing dominates for retail and foodservice, while large food processing units secure contract-based long-term offtake agreements. Price differentiation stems from brand recognition, such as Ball Corporation's equity, and specialized features like UV-protective coatings. Food processing units demonstrate the highest price sensitivity, while craft and DIY enthusiasts often accept premium pricing for aesthetic or unique jars.
Supply Chain Analysis
Single-source vulnerability sits with key raw material suppliers for soda ash and energy, critical inputs for glass manufacturing. Geographic supply concentrates in established glass production hubs like the United States, Germany, and France. Logistical costs represent a significant supply chain risk due to the weight and fragility of glass jars, complicating long-distance shipping. Distribution runs through wholesale distributors for commercial clients and online retailers for direct-to-consumer sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Mason Jars market is undergoing a technology-transition phase, as lightweighting advancements replace traditional, heavier glass formulations. This shift enables new applications and optimizes logistics for various end-users.
For Market Incumbents:Deploy specialized tooling investments to enhance product features like integrated measurement markings or UV-protective coatings. Diversify product lines beyond traditional canning jars to capture emerging lifestyle applications in home decor and specialized storage. This strategy helps mitigate the substitution threat from lighter-weight plastic and metal containers, reinforcing brand relevance in design-led consumer segments.
For New Entrants and Emerging Players:The European Union's single-use plastics directives in Germany open a window for new players offering compliant, reusable glass solutions. Target underpenetrated lifestyle segments in South America and Southeast Asia with design-led jars for beverages and home organization. A direct-to-consumer e-commerce model can facilitate market entry, leveraging social media for brand building among craft and DIY enthusiasts.
For Investors and Strategic Acquirers:Expansion of single-use plastic bans into new geographies is the leading indicator that signals sustained growth in reusable packaging. Long-term viability rests on the continued consumer shift towards sustainable and aesthetic containers across diverse applications. Target niche manufacturers specializing in decorative or functionally enhanced jars, or regional players with established distribution networks in high-growth lifestyle markets. This approach leverages existing infrastructure and specialized product portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Lightweighting R&D | Reduces shipping costs and enhances product appeal for foodservice and e-commerce channels. |
| Expand Specialty Product Lines | Captures demand from craft and decor segments, diversifying revenue beyond traditional canning. |
| Strengthen E-commerce Presence | Reaches individual consumers and small businesses, capitalizing on evolving purchasing habits. |
| Pursue Geographic Penetration | Accesses new consumer bases in emerging markets with growing lifestyle applications. |
| Enhance Compliance Capabilities | Ensures adherence to stringent food contact material regulations, maintaining market access. |
Research Approach
Document review covered trade association reports, regulatory filings from the FDA and EFSA, and company annual reports, complemented by interviews with glass manufacturers, food processing unit procurement leads, foodservice operators, and retail buyers. This approach integrated primary insights with secondary data, enabling bottom-up and top-down triangulation of market figures. Expert opinions validated market trends and segmented demand patterns.
Historical data cross-referenced with panel input formed the basis of the analytical framework applied across the projection horizon. The study modeled segmentation dimensions including product type, capacity, distribution channel, end-user, and regional regulatory compliance. CAGRs were derived by analyzing historical growth trends and factoring in anticipated shifts in consumer behavior and regulatory landscapes. Key inputs included single-use plastic regulation timelines and evolving consumer preference for sustainable packaging.
Caveats apply where raw material price volatility or unforeseen regulatory changes could materially shift the outlook. Forecasts reflect assumptions regarding economic stability and technological progression in glass manufacturing. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Oman Container Glass Market
Glass Packaging
Switzerland Container Glass Market
Glass Packaging
Brazil Container Glass Market
Glass Packaging
Uruguay Container Glass Market
Glass Packaging
Morocco Container Glass Market
Glass Packaging
Glass Frosting for Packaging Market
Glass Packaging
Cameroon Container Glass Market
Glass Packaging
Chile Container Glass Market
Glass Packaging
Germany Container Glass Market
Glass Packaging
Glass Decanters Market
Glass Packaging
Glass Packaging Market
Glass Packaging
Glass Bottles Market
Glass Packaging
Global Glass Packaging Rectifier Diode Market
Glass Packaging
Spain Packaging Market
Glass Packaging
Glass Growlers Market
Glass Packaging
United States Glass Packaging Market