
 United States Hybrid Electric Vehicle Battery Market | 2026-2036
United States Hybrid Electric Vehicle Battery Market Size, Share, and Industry Trends Forecast 2026-2036
United States Hybrid Electric Vehicle Battery Market Insights
Original equipment supply contracts is rewriting how cell manufacturers secure volume commitments in the United States hybrid electric vehicle battery market. Panasonic Holdings Corporation leverages its joint venture structure with domestic automakers to anchor production capacity in Nevada. LG Energy Solution competes through dedicated cylindrical cell lines engineered for North American platform compatibility. Samsung SDI sustains its position via prismatic battery specialization targeting premium sedan and SUV architectures.
A hybrid electric vehicle battery stores electrical energy through electrochemical cells and delivers power to an electric motor assisting an internal combustion engine, typically operating at 200-400 volts with energy densities between 40-100 watt-hours per kilogram for nickel-metal hydride systems and 150-250 watt-hours per kilogram for lithium-ion configurations. Its primary commercial purpose is to enable fuel consumption reduction, capture regenerative braking energy, and provide torque-fill during transient acceleration events. Lithium-ion chemistries dominate value pools due to superior cycle life and packaging efficiency, while nickel-metal hydride retains cost advantages in entry-level sedan segments where thermal stability outweighs energy density priorities. Plug-in charging infrastructure expansion is concentrating demand among fleet end users seeking petroleum displacement through daily grid charging cycles.
The National Highway Traffic Safety Administration enforces battery safety standards under Federal Motor Vehicle Safety Standard 305, while the EPA coordinates with California Air Resources Board to align corporate average fuel economy targets with zero-emission vehicle credit mechanisms. The Inflation Reduction Act's domestic content requirements for clean vehicle tax credits are reshaping where cell assembly and active material processing must occur. Stakeholders must monitor how proposed revisions to NHTSA crash-testing protocols for high-voltage systems interact with state-level fleet electrification mandates to determine optimal timing for capacity expansion decisions.
Market Dynamics
The Inflation Reduction Act's domestic content requirements are compressing cell assembly timelines as manufacturers race to qualify for clean vehicle tax credits before qualification windows narrow. This regulatory pressure is forcing immediate capital allocation decisions across the value chain.
Growth Catalysts
- California Air Resources Board fleet mandates:Commercial operators in zero-emission vehicle zones face binding procurement quotas that pull hybrid powertrains into service ahead of full electrification timelines.
- Lithium-ion nickel-manganese-cobalt chemistries:Research pipelines prioritize these cathode formulations for their superior energy density in premium sedan and SUV architectures.
- Michigan automotive corridor concentration:Proximity to Detroit Three engineering centers accelerates validation cycles and reduces logistics friction for cell-to-pack integration.
Market Restraints
- Cobalt supply concentration:Active material processing dependence on Central African feedstock creates price volatility exposure for cathode manufacturers.
- Nickel-metal hydride technical ceiling:Energy density limitations below 100 watt-hours per kilogram constrain these systems to entry-level segments where thermal stability is paramount.
- NHTSA Federal Motor Vehicle Safety Standard 305 compliance costs:Crash-testing protocols for high-voltage systems extend development timelines and raise barrier-to-entry for new cell suppliers.
Strategic Opportunities
- Texas fleet electrification corridors:Underpenetrated commercial vehicle demand in Dallas-Fort Worth and Houston logistics hubs offers volume expansion outside coastal saturation zones.
- Regenerative braking optimization software:Convergence of power electronics with predictive route mapping enables torque-fill efficiency gains in stop-and-go urban delivery cycles.
- EPA-CARB credit stacking mechanisms:Corporate average fuel economy alignment with zero-emission vehicle credits creates dual-revenue streams for qualifying powertrain configurations.
Industry Challenges
- Battery management systems engineering talent:Scarce firmware developers capable of cell balancing algorithms and thermal runaway detection strain hiring pipelines.
- Pack-level certification timelines:NHTSA validation sequences for 200-400 volt architectures extend product launch windows beyond traditional powertrain development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Hybrid Electric Vehicle Battery Market |
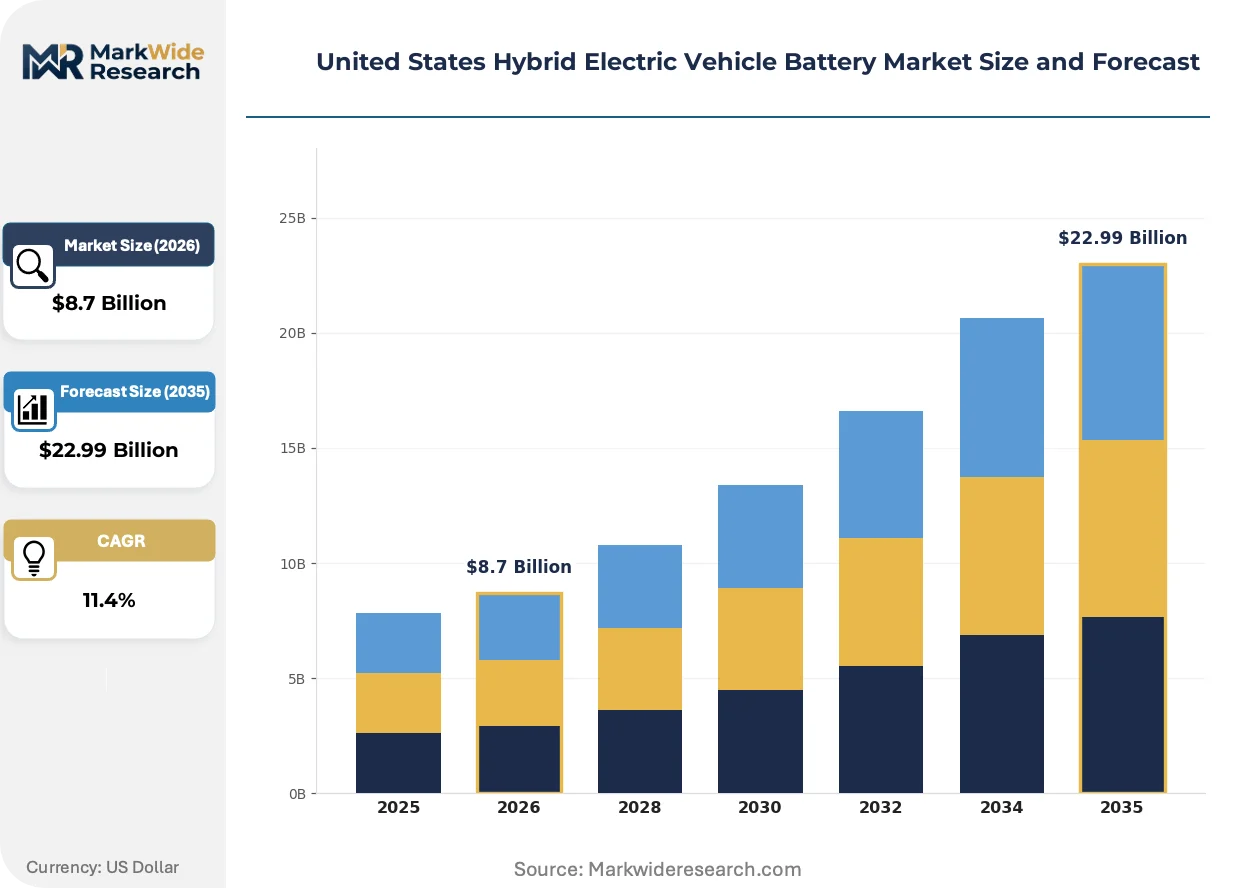
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lithium-ion, Nickel-Metal Hydride, Lead-Acid, Sodium-Ion Vehicle Model: Sedan, SUV, Truck, Hatchback Charging Method: Plug-in, Regenerative Braking, Fast Charging, Wireless End User: Individual Consumers, Fleets, Rental Services, Corporate |
| Companies Covered | Panasonic Holdings Corporation, EnerSys, BYD Company, LG Energy Solution, Samsung SDI, Duracell Inc., Exide Industries Ltd, Contemporary Amperex Technology, Prime Planet Energy & Solutions, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Hybrid Electric Vehicle Battery Market Trends and Innovations
Cell form factors and thermal management architectures are undergoing rapid specification changes as platform engineers optimize for range-extended hybrid duty cycles rather than pure electric range.
Solid-state electrolyte research is migrating from laboratory demonstration to pilot-scale production trials. Tier 1 suppliers in Michigan and California are validating sulfide-based ceramic separators for 2028 platform integration. This chemistry is migrating from niche aerospace applications toward mass-market hybrid architectures by promising 30% energy density gains over liquid electrolyte predecessors.
The Inflation Reduction Act's domestic assembly requirements are compressing supplier qualification timelines. Cell manufacturers must demonstrate North American active material processing to maintain tax credit eligibility for their automotive customers. Michigan and Nevada production facilities face the steepest compliance ramps as foreign-owned suppliers reconfigure supply chains.
Fleet procurement departments are consolidating vendor relationships around vertically integrated cell-to-pack suppliers capable of warranty-backed performance guarantees. Municipal transit authorities in California and commercial logistics operators in Illinois are bypassing traditional distributor networks for direct OEM contracting. This concentration is most visible in California's zero-emission vehicle zones where procurement officers prioritize single-source accountability over multi-vendor price competition.
United States Hybrid Electric Vehicle Battery Market Segmentation
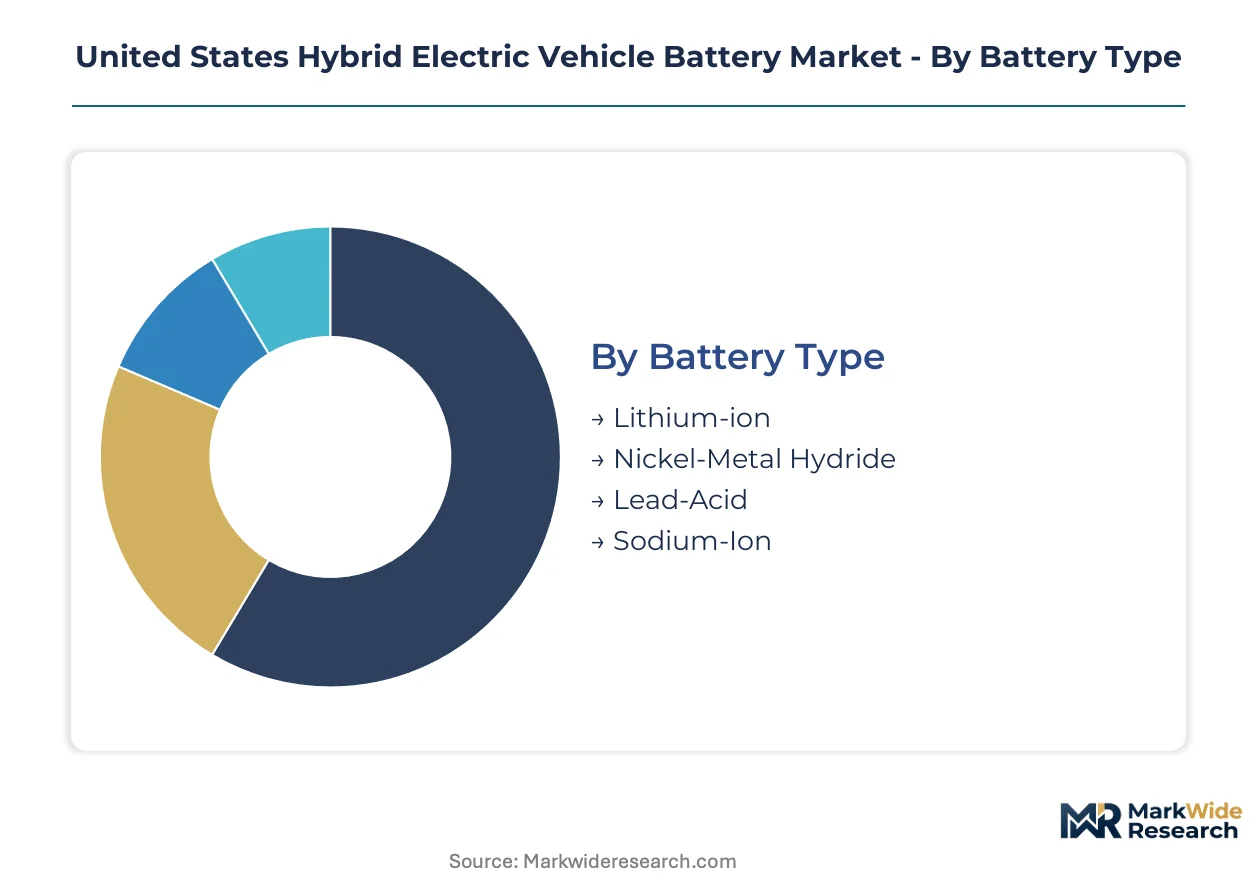
Segmentation in the United States hybrid electric vehicle battery market reveals how procurement cycles, technical specifications, and regulatory exposure vary across customer types and vehicle architectures. Understanding these fault lines helps manufacturers align production capacity with the segments turning over fastest.
Battery Type:
Cycle times diverge sharply: lithium-ion cells refresh every 3-4 years with chemistry iterations, while nickel-metal hydride platforms persist 7-10 years in cost-sensitive applications.
- Lithium-ion:Nickel-manganese-cobalt cathodes deliver 150-250 watt-hours per kilogram, enabling compact pack designs for Michigan-engineered SUV platforms where CARB compliance deadlines accelerate replacement schedules.
- Nickel-Metal Hydride:Thermal stability above 60°C suits entry-level sedan architectures in Texas and Florida markets where battery thermal management costs must stay minimal.
- Lead-Acid:Auxiliary power unit applications in commercial truck stop-start systems retain share where 12-volt electrical architectures persist.
- Sodium-Ion:Emerging chemistry from Nevada pilot lines targets grid-storage adjacent applications with domestic mineral sourcing advantages under IRA content rules.
Lithium-ion anchors the volume base while sodium-ion gains share at the steepest rate.
Vehicle Model:
Margin structures stratify by platform engineering complexity, with truck architectures commanding premium pricing for thermal management and vibration hardening.
- SUV:Three-row configurations dominate California fleet procurement with 400-volt architectures enabling all-electric range sufficient for daily urban delivery cycles without range anxiety.
- Sedan:Compact and mid-size segments concentrate in Illinois and Ohio manufacturing corridors where Detroit Three engineering centers optimize hybrid powertrain packaging for fuel economy certification.
- Truck:Full-size hybrid powertrains from Detroit and Dearborn facilities target contractor and rural owner-operators seeking towing capacity without pure-electric charging infrastructure dependence.
- Hatchback:Subcompact platforms retain nickel-metal hydride dominance in price-sensitive coastal urban markets where parking constraints favor smaller footprints.
Sedan platforms retain the widest installed base while SUV configurations expand most quickly.
Charging Method:
Customer acquisition costs scale inversely with infrastructure dependence, shaping how OEMs bundle hardware with software services.
- Plug-in:Daily grid charging enables 40-mile electric range in California zero-emission vehicle zones where fleet operators maximize petroleum displacement through overnight depot charging.
- Regenerative Braking:Kinetic energy recovery systems dominate non-plug-in architectures across Michigan and Ohio manufacturing, capturing deceleration events in stop-and-go traffic corridors.
- Fast Charging:150-kilowatt DC capability remains rare in hybrid applications but emerging in range-extended truck platforms targeting interstate logistics routes.
- Wireless:Inductive pad systems pilot in Seattle and San Francisco municipal transit depots where automated fleet charging reduces labor costs.
Regenerative braking underpins the broadest deployment while plug-in systems climb the fastest.
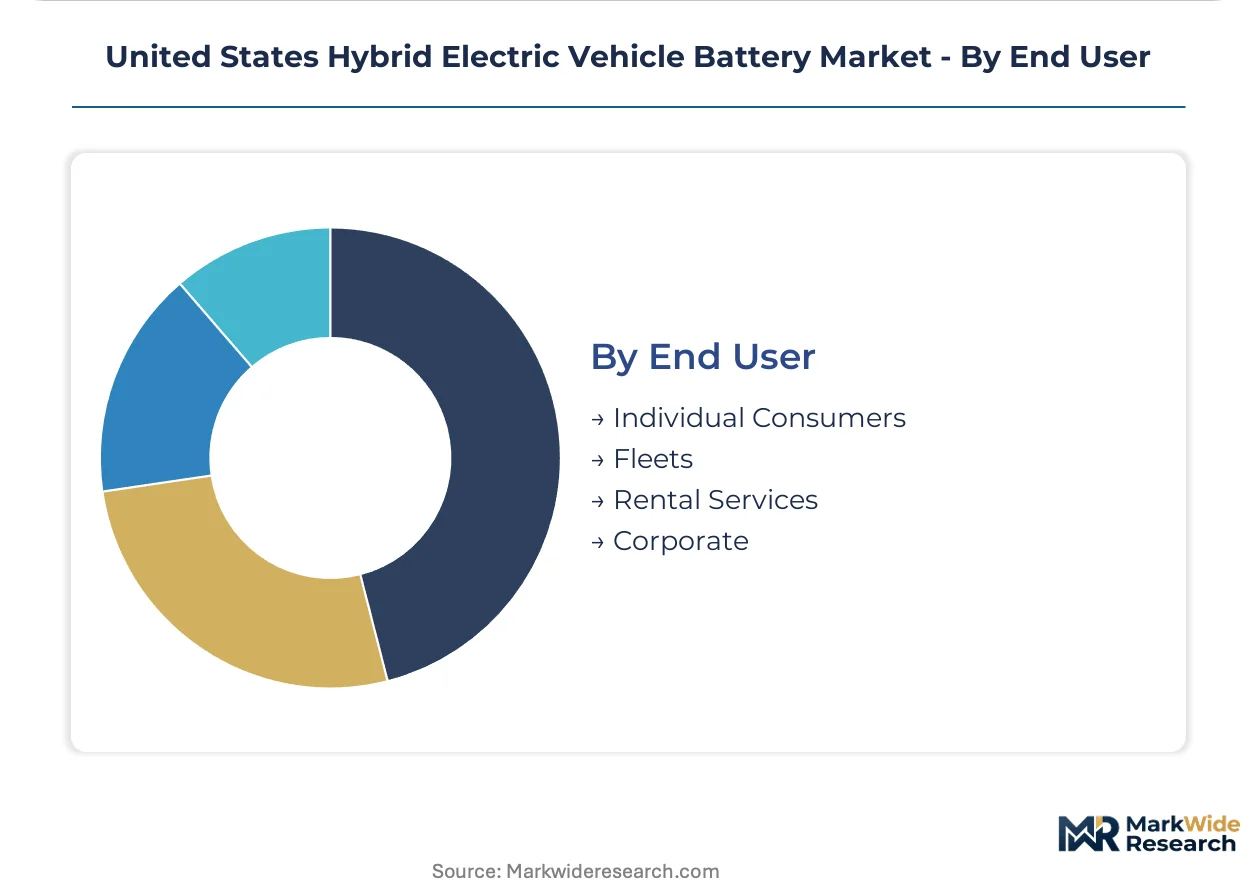
End User:
Purchasing authority concentration determines contract structure, with fleet procurement departments consolidating around performance guarantees rather than per-unit pricing.
- Fleets:Commercial operators in California and Texas negotiate direct OEM contracts for 500-plus unit commitments with warranty-backed cycle life minimums.
- Individual Consumers:Retail buyers in suburban Michigan and Pennsylvania markets respond to IRA tax credit visibility with 6-8 year ownership horizons.
- Rental Services:Airport and urban car-share operators in Florida and Arizona prioritize rapid charge acceptance over maximum range for high-turnover utilization.
- Corporate:Sustainability-mandated procurement from Illinois and New York headquarters drives lease structuring around carbon accounting disclosure requirements.
Individual consumers provide the deepest volume base while fleet segments scale fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Interstate 80 freight corridor anchors battery logistics across the industrial Midwest, while West Coast port infrastructure at Long Beach and Oakland channels Asian cell imports into domestic assembly plants.
Michigan
Detroit Three engineering centers in Warren and Dearborn drive hybrid validation cycles for next-generation SUV platforms. The state's Department of Environment, Great Lakes, and Energy coordinates with EPA on fleet electrification grants. Michigan State University's Battery Labs in East Lansing host cathode material characterization for nickel-manganese-cobalt formulations.
California
Los Angeles municipal transit authorities negotiate 500-unit fleet contracts for zero-emission vehicle zone compliance. California Air Resources Board mandates bind commercial operators in the San Joaquin Valley to hybrid procurement quotas. Tesla's Fremont facility and emerging suppliers in the Central Valley concentrate cell-to-pack integration capacity.
Texas
Dallas-Fort Worth logistics hubs generate underpenetrated commercial vehicle demand outside coastal saturation zones. The Texas Commission on Environmental Quality administers diesel emission reduction incentives that pull hybrid powertrains into service. Houston's petrochemical corridor repurposes industrial sites for electrolyte material processing under IRA domestic content rules.
Nevada
Gigafactory-scale production facilities outside Reno anchor lithium-ion cell assembly for North American platform compatibility. The Governor's Office of Economic Development structures tax abatements around clean vehicle credit qualification timelines. Northern Nevada's lithium clay deposits feed emerging domestic active material supply chains.
Illinois
Chicago corporate headquarters drive sustainability-mandated procurement with carbon accounting disclosure requirements. The Illinois Environmental Protection Agency aligns state fleet standards with federal corporate average fuel economy targets. Manufacturing corridors in Rockford and Peoria specialize in battery management systems firmware development.
United States Hybrid Electric Vehicle Battery Market Competitive Landscape
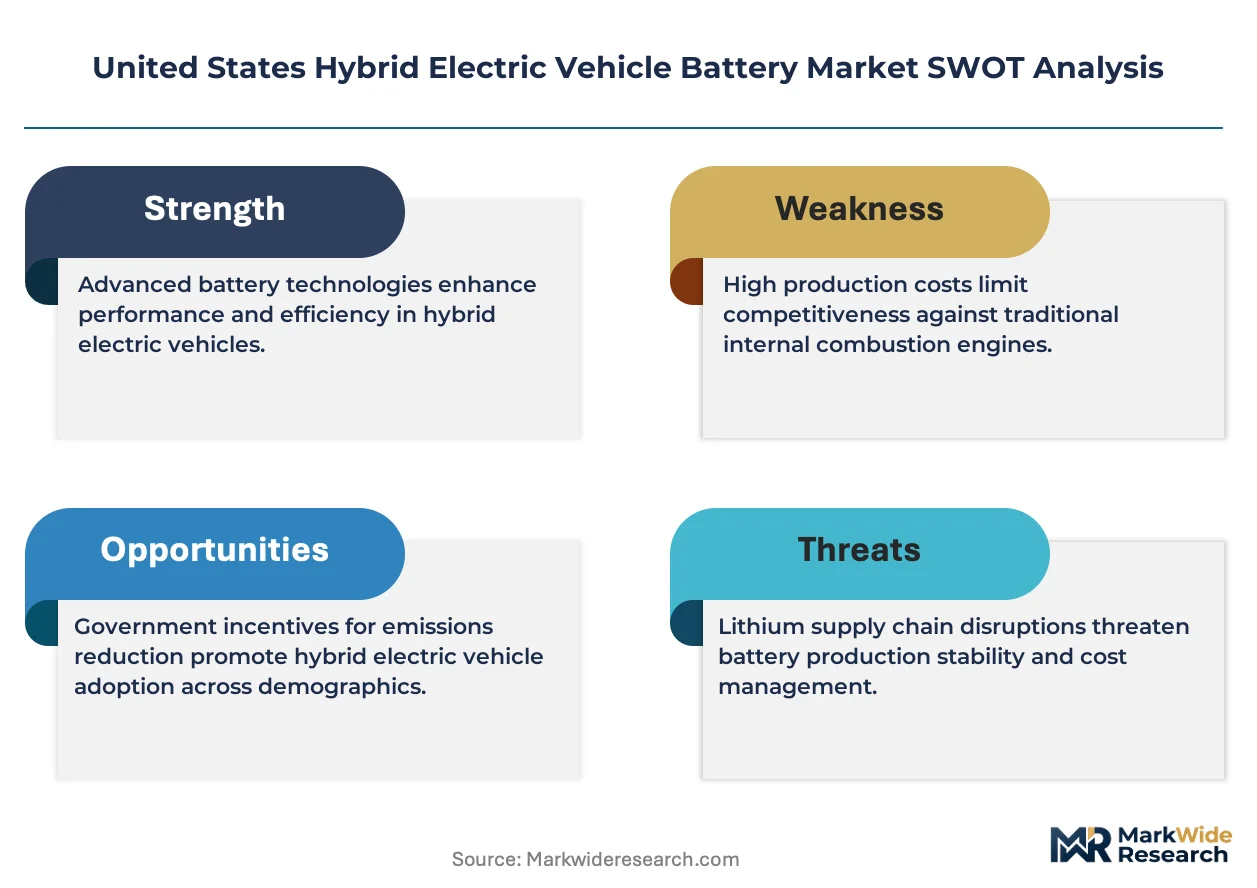
Platform integrators command the system tier; component specialists sit upstream on cathode powders and separator films. The United States hybrid electric vehicle battery market structures around three tiers: joint-venture cell producers with dedicated OEM lines, independent pack assemblers sourcing cells on spot markets, and materials processors feeding active material into qualification pipelines. Consolidation pressures concentrate among cell manufacturers racing to meet Inflation Reduction Act domestic assembly deadlines. Capacity expansion and backward integration into precursor refining represent the dominant competitive moves reshaping supplier positioning.
Among Asian-headquartered joint-venture specialists, Panasonic Holdings Corporation and LG Energy Solution anchor the tier-one cell supply tier, while Samsung SDI occupies a position within prismatic battery specialization. These entities exemplify the platform-integrated archetype where production capacity ties directly to Detroit Three and California-based OEM validation programs. Their Nevada and Michigan-adjacent facilities represent the geographic concentration pattern dominating qualification timelines for clean vehicle tax credit eligibility.
| Leading Market Players |
|---|
| Panasonic Holdings Corporation |
| EnerSys |
| BYD Company |
| LG Energy Solution |
| Samsung SDI |
| Duracell Inc. |
| Exide Industries Ltd |
| Contemporary Amperex Technology |
| Prime Planet Energy & Solutions |
| Others |
Pricing and Supply Chain Analysis
Central African cobalt feedstock concentration hands cathode manufacturers asymmetric pricing power over Detroit Three procurement officers negotiating annual cell supply agreements. This upstream chokepoint compresses margin pools at the pack assembly tier while amplifying volatility exposure for nickel-manganese-cobalt formulations.
Pricing Analysis
Volume-discount tiering structures dominate fleet procurement contracts, with 500-unit commitments commanding 12-15 point spreads over spot-market spot purchases. Price differentiation rests on IRA domestic content certification grade and warranty-backed cycle life guarantees rather than raw chemistry specifications. Cost compression in entry-level nickel-metal hydride segments is intensifying because thermal stability requirements constrain pack design flexibility. Municipal transit authorities exhibit the sharpest price sensitivity, while premium SUV fleet operators prioritize performance guarantees over per-kilowatt-hour economics.
Supply Chain Analysis
Upstream feedstock angles reveal lithium carbonate processing dependence on Chilean and Australian hard-rock spodumene, with cathode active material production concentrated in China and South Korea. Cell assembly draws from Japanese separator films and German electrolyte additives, creating multi-jurisdictional qualification burdens. Single-source vulnerability in cobalt hydroxide refining exposes margin structures to Central African supply disruptions. Distribution runs through Michigan-adjacent pack integration facilities serving Detroit Three platform engineering centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where cell-to-pack modularity standards are consolidating around Detroit Three interoperability protocols, rewarding suppliers who validate early against unified battery management system architectures.
For Market Incumbents: Entrench position through captive cobalt offtake agreements with Central African processors and accelerated Nevada cell line qualification against IRA domestic assembly deadlines. Sodium-ion chemistry entrants from Chinese suppliers threaten cost positions in grid-adjacent applications; backward integration into lithium clay refining secures feedstock optionality. For New Entrants and Emerging Players: Pursue Texas commercial fleet corridors where diesel emission reduction incentives create procurement pull without coastal supplier saturation. Battery management systems firmware development in Illinois offers the most penetrable white-space, with direct contracting to Rockford engineering shops bypassing established pack assembler relationships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed cathode material processors holding EPA environmental permits but lacking OEM validation relationships. Five-to-ten year viability hinges on IRA credit qualification durability; watch for NHTSA crash-testing protocol revisions as inflection signal for capacity write-down risk.| Strategic Initiative | Industry Significance |
|---|---|
| IRA Domestic Content Compliance | Nevada and Michigan facilities must demonstrate North American active material processing to maintain clean vehicle tax credit eligibility. |
| Cobalt Supply Agreement Restructuring | Long-term offtake contracts with Central African processors reduce price volatility exposure for nickel-manganese-cobalt cathode production. |
| Battery Management Systems Acquisition | Illinois firmware development shops provide scarce cell balancing algorithm talent pools for platform-integrated pack architectures. |
| Sodium-Ion Pilot Line Investment | Nevada clay deposits enable domestic mineral sourcing advantages under IRA content rules for grid-storage adjacent applications. |
| Fleet Direct Contracting Infrastructure | California municipal transit authorities consolidate vendor relationships around single-source accountability for zero-emission vehicle zone compliance. |
Research Methodology
The analysis maps lithium-ion, nickel-metal hydride, and emerging sodium-ion chemistries, each validated through Tier 1 supplier procurement leads, OEM platform engineers, fleet operations directors, and cathode material R&D heads. Primary interviews with Nevada production facility managers and Michigan pack integration specialists combined with EPA regulatory filings, NHTSA safety standard documentation, CARB mandate tracking databases, and SEC automotive OEM disclosure triangulation. Bottom-up cell shipment data and top-down vehicle production estimates converge across the analysis window.
Assumption sets held IRA domestic content thresholds and NHTSA crash-testing protocols fixed while varying cobalt price volatility scenarios and fleet electrification mandate acceleration rates. Segmentation dimensions span battery chemistry, vehicle architecture, charging method, and end-user procurement authority. CAGRs derive from installed base turnover modeling and replacement cycle compression across SUV, sedan, and truck platforms. Forecast inputs incorporate Michigan engineering center validation timelines and California zero-emission vehicle zone enforcement intensity.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated Chinese cell manufacturers would shift outcomes beyond modeled ranges. Material shifts in Inflation Reduction Act credit qualification windows or NHTSA high-voltage safety standard revisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hybrid Vehicles
Canada Hybrid Electric Vehicle Battery Market
Hybrid Vehicles
Hypercar Market
Hybrid Vehicles
Hybrid Cars Market
Hybrid Vehicles
Hybrid Vehicle Market
Hybrid Vehicles
Global Hybrid Vehicle Transmission Market
Hybrid Vehicles
Hybrid Electric Vehicle Market
Hybrid Vehicles
Middle East and Africa Hybrid Electric Vehicle Battery Market
Hybrid Vehicles
Plug-In Hybrid Electric Vehicles (PHEV) Market
Hybrid Vehicles
Global Hybrid-Electric Vehicle Insulation Market
Hybrid Vehicles
Hybrid Powertrain Systems Market
Hybrid Vehicles
Hybrid Drivetrain Market
Hybrid Vehicles
Hybrid Train Market
Hybrid Vehicles
Asia-Pacific Micro-Hybrid Vehicles Market
Hybrid Vehicles
Hybrid Electric Self-Driving Car Market
Hybrid Vehicles
United Arab Emirates Hybrid and Electric Vehicles Market
Hybrid Vehicles
Electric and Hybrid Vehicles Driveline Market