
 Automotive Whiplash Protection Equipment Market | 2026-2036
Automotive Whiplash Protection Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Whiplash Protection Equipment Market Analysis
FMVSS 202a is rebalancing the cost-of-entry calculus for whiplash protection equipment, forcing suppliers to absorb higher validation costs while demonstrating measurable neck injury criterion reductions. Autoliv Inc. anchors its position through deep vertical integration into crash sensor and pyrotechnic actuator production. Continental AG differentiates via active head restraint systems that integrate with pre-crash radar architectures. Lear Corporation specializes in seat-integrated solutions that merge foam engineering with structural frame design.
Automotive whiplash protection equipment encompasses active and passive occupant safety systems engineered to mitigate cervical spine trauma during rear-impact collisions, typically incorporating energy-absorbing foams, pyrotechnic actuators, and biomechanically optimized head restraint geometries measured against NICmax and Nkm injury metrics. Head restraints dominate value capture due to regulatory mandates across major automotive markets, while airbag-integrated neck protection represents the fastest-growing product category as OEMs pursue multi-point restraint strategies. Thermoplastic materials sustain margin advantages through recyclability compliance and weight reduction relative to metal-reinforced alternatives, with composite material adoption accelerating in motorsport and luxury applications where cost sensitivity diminishes.
NHTSA enforces FMVSS 202a minimum backset and height requirements in the United States, while Euro NCAP's dynamic whiplash assessment protocol shapes product development priorities for European-bound vehicles. Japan's Ministry of Land, Infrastructure, Transport and Tourism incorporates whiplash performance into its safety rating framework, creating a triad of influential testing regimes. Stakeholders must monitor the divergence between passive foam-based systems and active pyrotechnic solutions, as the technology choice carries irreversible platform engineering commitments and supplier lock-in effects.
Market Dynamics
Active head restraint systems are displacing passive foam-based designs as Euro NCAP protocols tighten dynamic whiplash performance thresholds, forcing platform-level engineering commitments that lock OEMs into specific supplier ecosystems for entire vehicle generations.
Growth Catalysts
- Euro NCAP Dynamic Testing:The protocol's 2023 revision elevated whiplash protection to a weighted scoring category, compelling OEMs to prioritize NICmax-compliant head restraints in vehicle development cycles.
- Pyrotechnic Actuator Maturation:Crash sensor response times below 20 milliseconds now enable predictive deployment algorithms that reduce cervical spine trauma incidence in rear-impact scenarios.
- German OEM Integration Rates:Premium manufacturers in Stuttgart and Munich have standardized active systems across mid-tier nameplates, creating specification cascades into mass-market platforms.
Market Restraints
- Polymer Feedstock Volatility:Engineering-grade thermoplastics for energy-absorbing foams face price instability tied to propylene supply chain disruptions in Gulf Coast petrochemical clusters.
- Validation Cost Burden:FMVSS 202a compliance requires extensive sled testing and biomechanical dummy certification, concentrating development resources among suppliers with captive crash-test facilities.
- Passive System Lock-In:Existing seat-frame architectures in economy vehicle segments resist retrofit compatibility with active pyrotechnic mechanisms without comprehensive redesign.
Strategic Opportunities
- Indian Safety Rating Integration:Bharat NCAP's planned whiplash assessment protocol creates first-mover positioning for suppliers establishing localized testing partnerships with Chennai and Pune manufacturing clusters.
- Pre-Crash Radar Convergence:Integration of head restraint deployment algorithms with forward-facing sensor suites enables multi-vector collision anticipation beyond rear-impact scenarios alone.
- Recyclability Compliance:EU End-of-Life Vehicle Directive revisions favor mono-material foam constructions that simplify disassembly and thermal reprocessing versus metal-reinforced alternatives.
Industry Challenges
- Biomechanical Simulation Talent Scarcity:Finite element modeling expertise for cervical spine kinematics remains concentrated among a limited pool of specialized engineering consultancies in Detroit and Gothenburg.
- Cross-Platform Integration Complexity:Active head restraint electronics must synchronize with disparate OEM restraint control modules, requiring extensive software validation cycles that extend program timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Whiplash Protection Equipment Market |
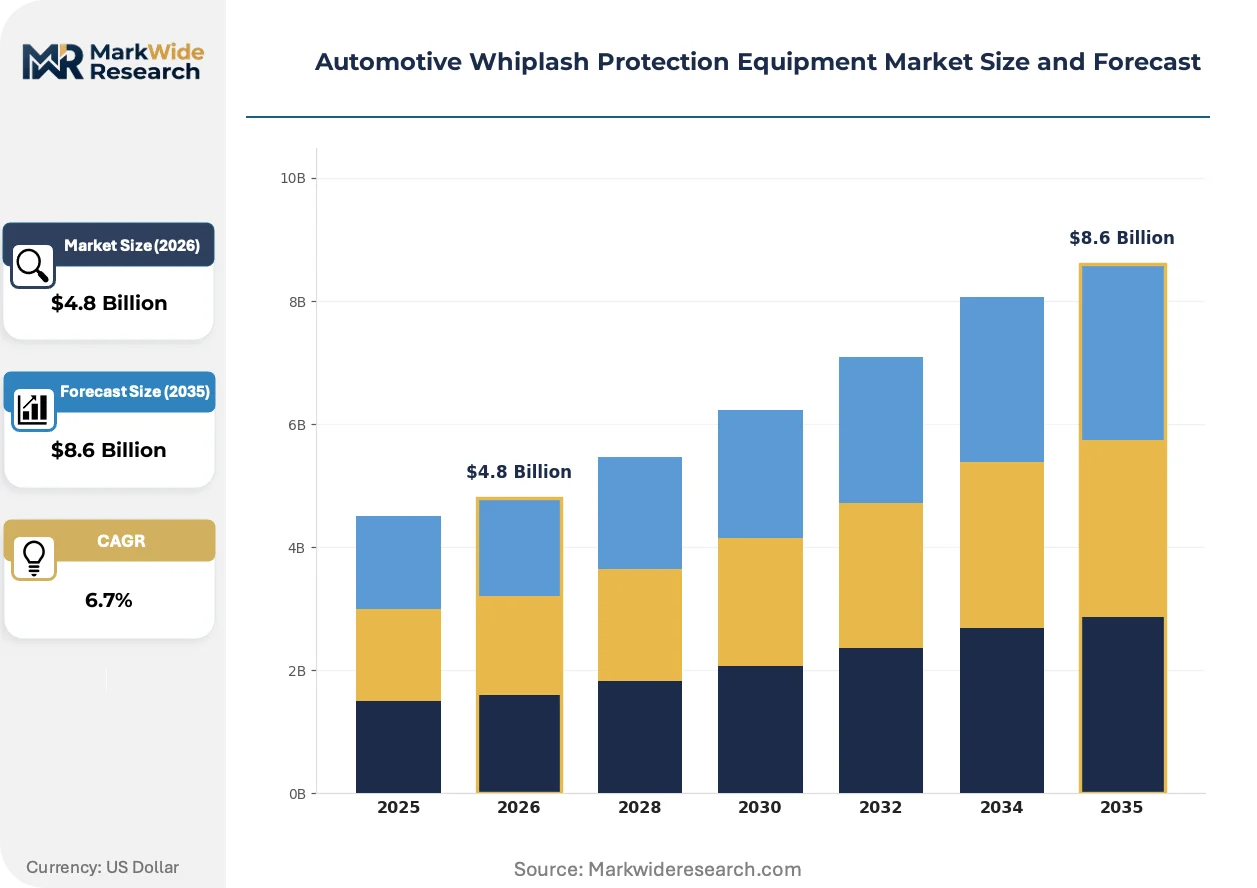
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Head Restraints, Seat Cushions, Neck Braces, Airbags Installation Type: Original Equipment Manufacturer, Aftermarket, Custom Installation, Retrofit End User: Automakers, Fleet Operators, Insurance Companies, Vehicle Owners Material: Foam, Thermoplastics, Composite Materials, Textiles |
| Companies Covered | Robert Bosch GmbH, Continental AG, Autoliv Inc., Lear Corporation, ZF Friedrichshafen AG, Hyundai Mobis, Denso Corporation, Grammer AG, Takata Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Whiplash Protection Equipment Market Emerging Trajectories
Sensor fusion architectures are rewriting the competitive terrain for whiplash protection, as predictive collision detection migrates from standalone rear-impact sensors to networked vehicle safety systems with multi-directional threat assessment capabilities.
Electro-mechanical active head restraints are integrating pyrotechnic deployment with reversible electric actuators, enabling luxury vehicle manufacturers to offer adjustable comfort positioning that automatically transitions to crash-ready geometry when radar signatures indicate imminent rear impact. This dual-mode functionality compresses the traditional trade-off between occupant ergonomics and safety performance that has constrained passive head restraint design for decades.
FMVSS 202a amendments under NHTSA review are tightening backset distance tolerances and introducing dynamic performance requirements that mirror Euro NCAP testing methodologies. The proposed rulemaking would eliminate the static geometry compliance pathway that has allowed economy segment vehicles to meet standards with minimal engineering investment, forcing structural redesigns across the US-bound product portfolio.
Fleet procurement specifications for rental and corporate vehicle operators now mandate active whiplash protection as a standard inclusion rather than optional equipment, compressing the specification gap between retail and commercial channels that previously sustained two-tier product strategies. This specification convergence is most visible in German and Japanese fleet management contracts, where total cost of ownership calculations now incorporate insurance premium reductions tied to Euro NCAP star ratings.
Automotive Whiplash Protection Equipment Market Segmentation
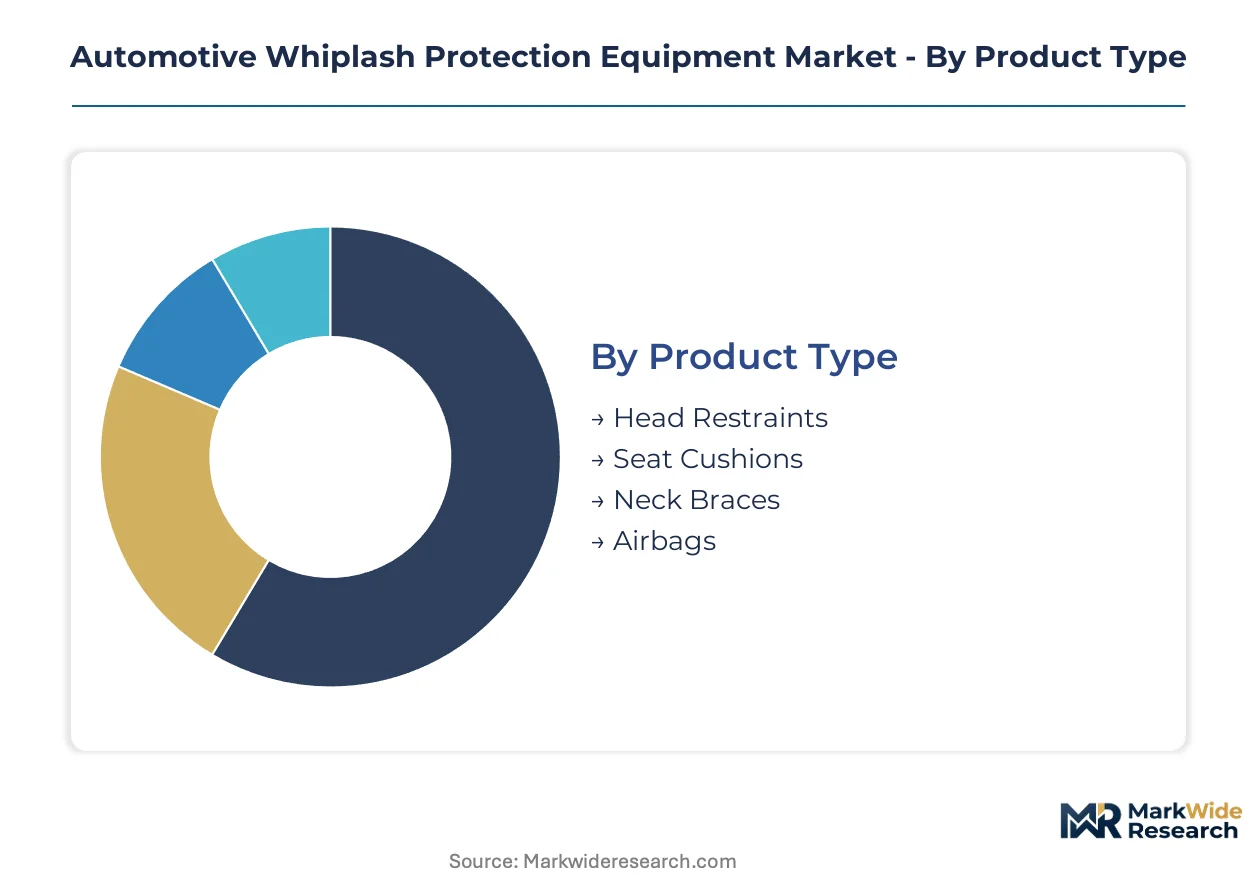
Whiplash protection equipment segments diverge sharply by integration depth, with seat-embedded systems demanding multi-year platform commitments while standalone retrofit products serve immediate compliance needs. Material choices and installation pathways determine supplier margin structures and regulatory validation burdens.
Product Type:
Integration depth varies from fully embedded seat architectures to deployable supplemental systems, with embedded solutions locking OEMs into supplier ecosystems across vehicle generations.
- Head Restraints:Biomechanically optimized geometries incorporating energy-absorbing foams and adjustable backset mechanisms dominate OEM specifications. German and Japanese automakers in Stuttgart, Munich, and Toyota City anchor demand as Euro NCAP protocols tighten NICmax performance thresholds.
- Airbags:Deployable curtain and seat-mounted systems integrate with pyrotechnic actuator networks for predictive deployment. Fleet procurement specifications in German and Japanese corporate contracts are accelerating adoption beyond luxury nameplates into mid-tier platforms.
- Seat Cushions:Energy-dissipating foam constructions address lumbar-pelvic kinematics in rear-impact scenarios.
- Neck Braces:Post-collision medical devices serve rehabilitation and insurance claim contexts outside vehicle-integrated supply chains.
Volume placements concentrate in Head Restraints; the faster expansion belongs to Airbags.
Installation Type:
Cost tier stratification separates captive OEM supply from fragmented aftermarket channels, with validation intensity determining viable participant pools.
- Original Equipment Manufacturer:Factory-integrated systems require FMVSS 202a and Euro NCAP compliance testing with biomechanical dummy certification. Stuttgart and Munich manufacturing clusters sustain highest specification rates for active pyrotechnic mechanisms.
- Aftermarket:Post-sale installations serve vehicle owners and fleet operators seeking insurance premium reductions through safety rating improvements. Chennai and Pune service networks are expanding as Bharat NCAP protocols elevate awareness.
- Custom Installation:Specialist fitters address motorsport and disability-access vehicle modifications with non-standard geometries.
- Retrofit:Economy segment compatibility constraints limit viable applications to passive foam-based designs.
Revenue margins peak in OEM channels; aftermarket volume is climbing fastest in Indian urban clusters.
End User:
Customer type dictates procurement cadence, with fleet operators compressing specification cycles relative to retail automaker development timelines.
- Automakers:Platform engineering decisions commit suppliers for 5-7 year production runs. German premium manufacturers have standardized active systems across mid-tier nameplates, creating specification cascades.
- Fleet Operators:Rental and corporate vehicle managers now mandate active whiplash protection as standard equipment. Total cost of ownership calculations in German and Japanese fleet contracts incorporate insurance reductions tied to Euro NCAP ratings.
- Insurance Companies:Claims cost reduction drives specification influence through premium incentive structures.
- Vehicle Owners:Retail replacement demand concentrates in post-collision repair contexts and safety-conscious upgrade segments.
Contract security favors automaker relationships; fleet operator specification authority is expanding most rapidly.
Material:
Supply concentration and recyclability compliance are reshaping material selection priorities across regulatory jurisdictions.
- Thermoplastics:Engineering-grade polymers deliver weight reduction and end-of-life vehicle directive compliance for EU-bound production. Recyclability advantages sustain margin premiums over metal-reinforced alternatives in German manufacturing.
- Foam:Energy-absorbing polyurethane and expanded polypropylene constructions dominate passive system economics. Gulf Coast propylene supply disruptions are injecting price volatility into validation-dependent development programs.
- Composite Materials:Carbon fiber and aramid reinforcements serve motorsport and luxury applications where cost sensitivity diminishes.
- Textiles:Cover materials and comfort layers complete system assemblies without primary energy management functions.
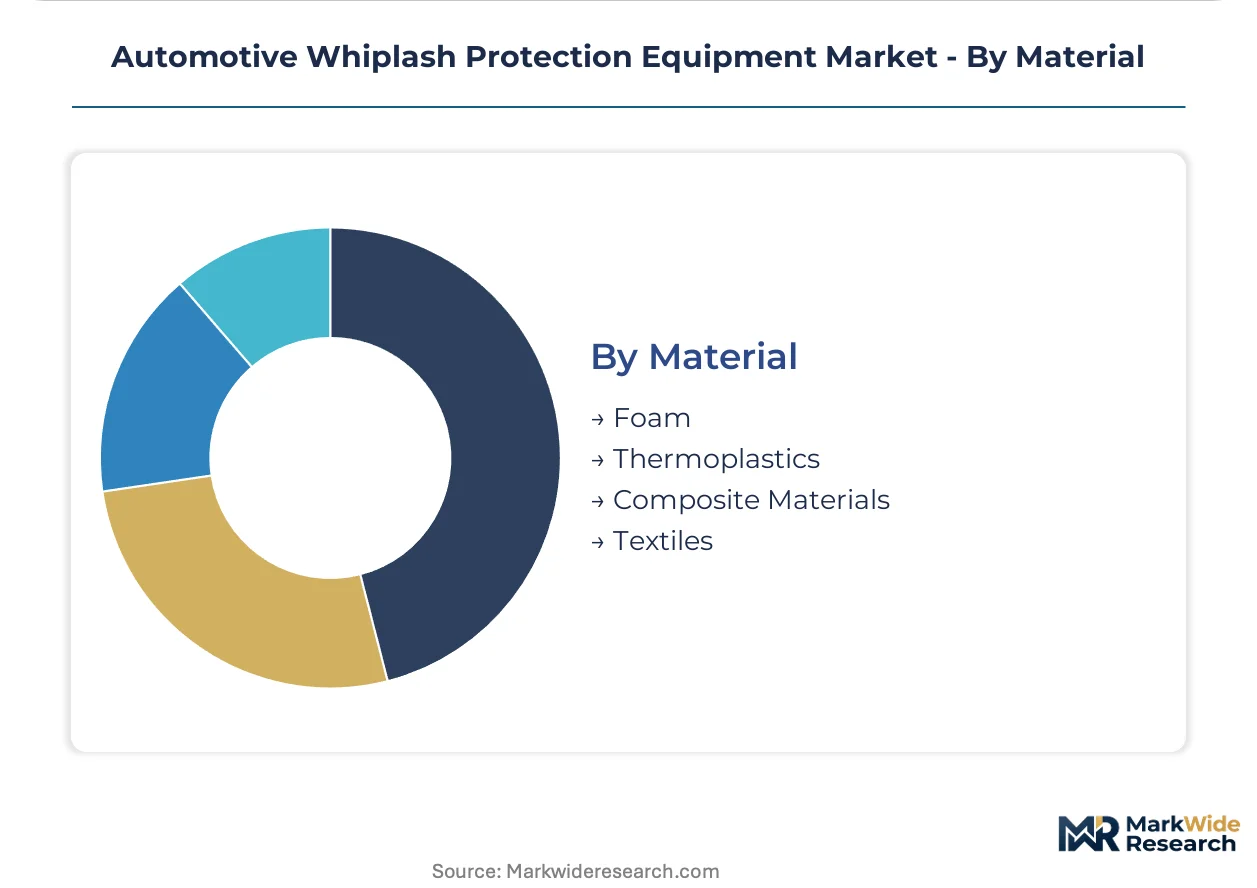
Procurement scale centers on Foam formulations; Thermoplastics are gaining share fastest on regulatory tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Japanese automakers concentrate specification authority for whiplash protection systems, while United States regulatory enforcement shapes validation requirements. Indian safety rating evolution and South Korean supplier integration complete the demand map.
United States
NHTSA's FMVSS 202a amendments under review would eliminate static compliance pathways, forcing structural redesigns across Detroit Three product portfolios. Insurance premium incentives tied to safety ratings now influence fleet procurement specifications. Michigan's automotive engineering corridor sustains captive crash-test facility investments from major Tier 1 suppliers.
Germany
Premium manufacturers in Stuttgart and Munich have standardized active head restraint systems across mid-tier nameplates, creating specification cascades into mass-market platforms. Euro NCAP's 2023 protocol revision elevated whiplash protection to a weighted scoring category. Baden-Württemberg's supplier cluster maintains deep integration into pyrotechnic actuator and sensor production.
Japan
Ministry of Land, Infrastructure, Transport and Tourism incorporates whiplash performance into national safety rating frameworks, aligning domestic requirements with Euro NCAP methodologies. Toyota City and Nagoya manufacturing clusters anchor OEM integration rates for active systems. Domestic suppliers leverage pre-crash radar convergence with forward-facing sensor architectures.
India
Bharat NCAP's planned whiplash assessment protocol creates first-mover positioning for suppliers establishing localized testing partnerships. Chennai and Pune manufacturing clusters are expanding aftermarket service networks as safety awareness elevates. Central government vehicle safety mandates are compressing adoption timelines from luxury into mass-market segments.
South Korea
Seoul Capital Area suppliers integrate whiplash protection electronics with broader restraint control module portfolios, leveraging scale in passenger vehicle safety systems. Domestic OEMs are accelerating active system adoption to maintain export competitiveness in European markets. Busan-Ulsan manufacturing corridors concentrate foam and thermoplastic component production.
Automotive Whiplash Protection Equipment Market Vendor Landscape
German producers anchor one tier; Swedish and American specialists hold differentiated positions in sensor integration and seat-embedded architectures. The supplier base concentrates among vertically integrated safety system conglomerates and seat-structure specialists with captive foam engineering capabilities. Three archetypes dominate: full-system integrators controlling pyrotechnic and sensor supply; seat-frame engineers merging structural and energy-absorbing design; and electronics specialists converging radar and deployment algorithms. M&A activity targets biomechanical simulation capabilities, while capacity expansion concentrates in Indian and Mexican manufacturing corridors to serve regional OEM integration.
Among the full-system integrators, Autoliv Inc., Continental AG, and ZF Friedrichshafen AG exemplify the tier-one safety conglomerate archetype, each representing distinct geographic origins and structural approaches to vertical integration. These entities occupy positions where crash sensor production, pyrotechnic actuator manufacturing, and deployment algorithm development converge under unified engineering organizations. Lear Corporation and Grammer AG sit within the seat-structure specialist tier, anchoring their competitive positions through foam-to-frame design integration rather than distributed electronics architectures. Hyundai Mobis and Denso Corporation represent the Asia-Pacific supplier model, leveraging domestic OEM relationships to scale active system adoption across export-bound vehicle programs.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| Autoliv Inc. |
| Lear Corporation |
| ZF Friedrichshafen AG |
| Hyundai Mobis |
| Denso Corporation |
| Grammer AG |
| Takata Corporation |
| Others |
Supply Flow & Price Mechanics
Propylene price indices cascading through Gulf Coast petrochemical clusters compress margin structures for energy-absorbing foam producers, forcing tiered pricing stratification across active pyrotechnic and passive foam-based systems. NHTSA FMVSS 202a validation costs concentrate pricing power among suppliers with captive crash-test facilities, while polymer feedstock volatility injects quarterly recalibration pressure into contract negotiations.
Pricing Analysis
Volume placements concentrate in passive foam-based head restraints where price differentiation rests on energy-absorption certification grade and backset adjustability range. Premium active pyrotechnic systems command structural premiums tied to NICmax performance thresholds and pre-crash radar integration depth. Pricing pressure stems from polymer feedstock volatility in Gulf Coast supply corridors, compressing margins for thermoplastic-dependent suppliers. Fleet operators exhibit highest price sensitivity due to total cost of ownership calculations, while German premium OEMs prioritize performance tier over unit economics.
Supply Chain Analysis
FMVSS 202a biomechanical dummy certification and Euro NCAP protocol compliance create gating barriers that concentrate qualified supply among German, Japanese, and United States manufacturing clusters. Pyrotechnic actuator production draws from specialty chemical feedstocks and precision-machined metal components, with crash sensor electronics anchored in South Korean and Taiwanese semiconductor corridors. Single-source vulnerability runs through Gulf Coast propylene supply chains disrupted by petrochemical cluster outages. Distribution runs through Tier 1 supplier direct-to-OEM channels, with aftermarket service networks expanding through Chennai and Pune urban clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FMVSS 202a amendments under NHTSA review are elevating cost-of-entry barriers for whiplash protection equipment, creating compliance moats that favor incumbent suppliers with established validation infrastructure and captive crash-test facilities.
For Market Incumbents: Lock in platform-level engineering commitments with Stuttgart and Munich OEMs before specification cycles finalize for next-generation vehicle architectures. Deepen backward integration into pyrotechnic actuator production to defend margin position against polymer feedstock volatility. Prioritize biomechanical simulation talent acquisition in Detroit and Gothenburg corridors where finite element modeling expertise for cervical spine kinematics concentrates. For New Entrants and Emerging Players: Bharat NCAP's planned whiplash assessment protocol in India opens a window for localized testing partnerships with Chennai and Pune manufacturing clusters. Target aftermarket service networks in Indian urban centers where safety awareness elevation outpaces domestic supply capacity. Pursue fleet operator procurement specifications in German and Japanese corporate contracts where insurance premium reductions now mandate active system inclusion. For Investors and Strategic Acquirers: Distressed-cycle entries favor seat-structure specialists with captive foam engineering capabilities in Baden-Württemberg supplier corridors. Long-term viability over the projection horizon rests on pre-crash radar convergence and sensor fusion architecture integration. Watch for FMVSS 202a final rule publication as inflection indicator accelerating structural redesign requirements across Detroit Three portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Pre-Crash Radar Integration | Sensor fusion architectures enable predictive head restraint deployment beyond rear-impact scenarios alone. |
| Biomechanical Simulation Acquisition | Finite element modeling expertise for cervical spine kinematics remains concentrated in Detroit and Gothenburg. |
| Indian Testing Partnership Establishment | Bharat NCAP protocol development creates first-mover positioning in Chennai and Pune manufacturing clusters. |
| Mono-Material Foam Transition | EU End-of-Life Vehicle Directive revisions favor recyclable thermoplastic constructions over metal-reinforced alternatives. |
| Fleet Procurement Specification Capture | German and Japanese corporate contracts now mandate active whiplash protection as standard equipment inclusion. |
Methodological Framework
Document review covered NHTSA FMVSS 202a regulatory filings, Euro NCAP dynamic whiplash assessment protocols, and vehicle production databases, complemented by interviews with Tier 1 supplier procurement leads, OEM platform engineers, aftermarket distributors, and fleet operator safety managers. Secondary validation drew from SEC 10-K disclosures, customs trade data for polymer feedstocks, and IHS Markit vehicle registration statistics. Bottom-up unit economics and top-down market sizing triangulated volume and value estimates across the analysis window.
Segment-level outputs reflect vehicle class stratification, propulsion architecture differentiation, content-per-vehicle trajectories, OEM tier positioning, and regional production cluster concentration. CAGRs were derived from regression analysis against macro vehicle production forecasts and regulatory mandate implementation timelines. Industry-specific inputs incorporated Euro NCAP scoring weight evolution, FMVSS 202a amendment probability, and fleet procurement specification convergence rates.
The model assumes a particular technology adoption path favoring active pyrotechnic systems over passive foam-based designs; alternative pathways for electro-mechanical reversible actuators would alter the outlook for supplier margin structures and platform engineering commitments. Forecasts reflect assumptions regarding regulatory implementation timing, polymer feedstock price stabilization, and OEM specification cascade velocity. A model refresh is warranted upon material change in NHTSA rulemaking finalization or Bharat NCAP protocol publication.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Forklift Camera Systems Market
Automotive Safety and Security Systems
ABS Sensors Market
Automotive Safety and Security Systems
Global Car Radar Detectors Market
Automotive Safety and Security Systems
Automotive Brake Override System Market
Automotive Safety and Security Systems
Automotive Vacuumless Braking Market
Automotive Safety and Security Systems
Forward Collision Warning System for Automotive Market
Automotive Safety and Security Systems
Active Spoiler Market
Automotive Safety and Security Systems
Collision Mitigation Technology Market
Automotive Safety and Security Systems
Automotive Black Boxes Market
Automotive Safety and Security Systems
Automotive Perimeter Lighting System Market
Automotive Safety and Security Systems
Airbag Sensor Market
Automotive Safety and Security Systems
Automotive Fire Suppression System Market
Automotive Safety and Security Systems
Car Camera Cleaning Systems Market
Automotive Safety and Security Systems
Automatic Brake Pad Inspection System Market
Automotive Safety and Security Systems
Video Event Data Recorder Market
Automotive Safety and Security Systems
Middle East and Africa Automotive Adaptive Lighting System Market