
 Automotive Surge Absorber Market | 2026-2036
Automotive Surge Absorber Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Surge Absorber Market Analytics
Electric vehicle OEMs are redrawing procurement priorities for surge protection components as high-voltage architectures proliferate across passenger and commercial platforms. Panasonic Industry Co., Ltd. leverages its ceramic varistor heritage to anchor positions in Japanese EV supply chains. Littelfuse, Inc. competes through fuse-integrated surge suppression modules that reduce component count in tight engine-bay layouts. Infineon Technologies AG differentiates via semiconductor-based active clamping circuits that respond faster than passive alternatives during load-dump events.
An automotive surge absorber is a protective device that limits transient voltage spikes in vehicle electrical systems, typically employing metal oxide varistors or transient voltage suppression diodes rated for 12V to 800V operating envelopes depending on application severity. The device shields ECUs, battery management systems, and infotainment modules from damage caused by alternator load dumps, inductive switching, and electrostatic discharge. Passive absorbers still dominate unit volume in internal combustion platforms where cost sensitivity runs highest, while hybrid absorbers combining metal and polymer substrates represent the fastest-growing material configuration as OEMs seek thermal stability in electrified powertrains. Composite-based solutions command margin premiums in heavy-duty vehicles facing sustained vibration exposure across mining and construction duty cycles.
The US NHTSA and EPA jointly shape surge absorber specifications through electromagnetic interference limits and fuel-economy-driven weight reduction mandates that favor compact polymer housings. Europe's ECE R10 regulation and REACH chemical restrictions force reformulation of zinc oxide disc compositions to eliminate restricted stabilizer compounds. China's GB/T standards for new energy vehicles mandate surge immunity testing at levels exceeding conventional automotive thresholds. Stakeholders must monitor how battery-electric platform voltages climb toward 800V architectures and whether existing absorber technologies can maintain clamping precision without sacrificing energy dissipation capacity.
Market Dynamics
High-voltage platform migration across electric vehicle architectures is compressing absorber design cycles and forcing simultaneous upgrades in thermal tolerance, clamping precision, and form-factor miniaturization.
Growth Catalysts
- China's NMPA vehicle safety mandates:New energy vehicle testing protocols now exceed conventional automotive surge immunity thresholds, compelling absorber specification upgrades across domestic and foreign OEM supply chains.
- 800V powertrain proliferation:Battery-electric architectures climbing toward higher operating voltages demand absorbers with expanded clamping ranges and faster response characteristics.
- Germany's automotive manufacturing belt:Concentrated EV production in Bavaria and Baden-Württemberg generates localized procurement pull for Tier-1 surge protection component suppliers.
Market Restraints
- Zinc oxide raw material volatility:Metal oxide varistor production depends on zinc concentrate pricing subject to mining supply disruptions and energy-intensive smelting cost swings.
- Japan's component supplier corridor concentration:Ceramic varistor expertise clusters among a narrow set of heritage manufacturers, creating single-source vulnerability for global OEMs.
- REACH chemical restrictions:Europe's ban on specific stabilizer compounds forces reformulation of established disc compositions, extending qualification timelines.
Strategic Opportunities
- India's nascent EV manufacturing base:Domestic production incentives under the PLI scheme create first-mover positioning for absorber suppliers establishing local technical support.
- Fuse-integrated suppression modules:Convergence of overcurrent and overvoltage protection into single housings addresses space constraints in compact engine-bay layouts.
- US NHTSA electromagnetic interference limits:Tightening radiated emission standards drive replacement demand in legacy fleet retrofits and commercial vehicle upfitting.
Industry Challenges
- Multiphysics simulation expertise gap:Thermal-electrical-mechanical co-design for 800V architectures requires specialized CAE talent scarce among traditional passive component engineers.
- ECE R10 certification timeline compression:Electromagnetic compatibility testing for new absorber variants faces laboratory capacity constraints across European notified bodies.
- Legacy 12V system integration friction:Dual-voltage vehicle architectures demand absorber portfolios spanning incompatible specification ranges without cross-contamination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Surge Absorber Market |
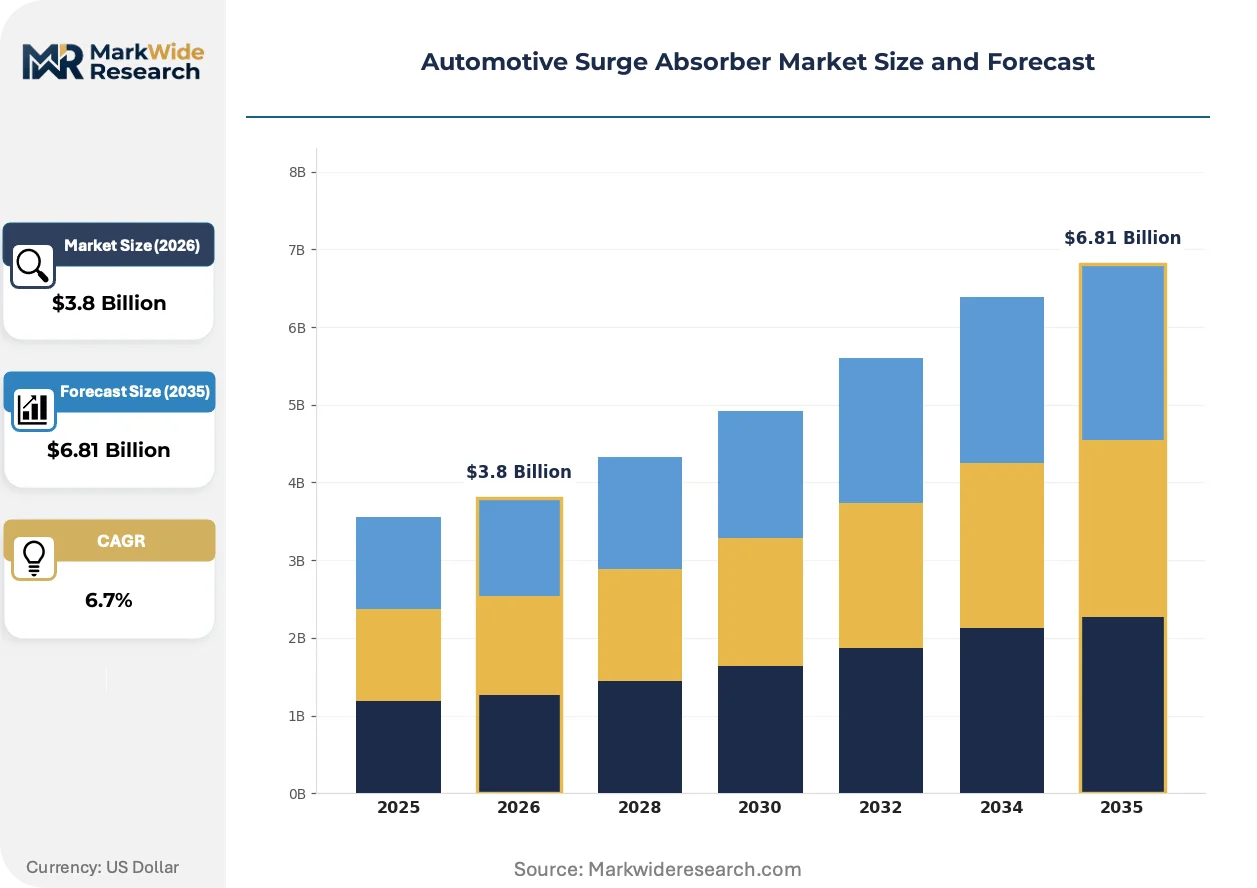
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passive Absorbers, Active Absorbers, Hybrid Absorbers, Vibration Dampers Material: Rubber, Polymer, Metal, Composite Application: Lightweight Vehicles, Heavy-Duty Vehicles, Electric Vehicles, Commercial Vehicles End User: Tier-1 Suppliers, OEMs, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | Panasonic Industry Co., Ltd., Littelfuse, Inc., Infineon Technologies AG, Mitsubishi Materials Corporation, Bourns, Inc., TDK Corporation, Murata Manufacturing, Nippon Chemi-Con Corporation, TE Connectivity Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Surge Absorber Market Evolving Landscape
Component architecture is pivoting toward multifunctional integration as space and thermal budgets tighten across electrified platforms. Three developments are restructuring competitive requirements.
Polymer-housed metal oxide varistors are miniaturizing through advanced ceramic sintering techniques that maintain energy dissipation capacity while shrinking disc diameters. Tier-1 suppliers serving German premium EV platforms are adopting these compact variants to meet fuel-economy-driven weight reduction mandates. The technology is miniaturizing protection footprints sufficiently to embed absorbers directly within battery module housings rather than external junction boxes.
Europe's ECE R10 electromagnetic compatibility regulation is tightening conducted and radiated emission limits for vehicle electrical subsystems. The standard forces absorber manufacturers to characterize high-frequency response beyond traditional clamping voltage specifications. Heavy-duty commercial vehicle segments face the steepest compliance burden due to extended cable harness lengths amplifying transient propagation.
Buyer consolidation among EV-focused Tier-1 integrators is compressing supplier qualification cycles and consolidating purchase volumes with technically differentiated sources. Direct OEM engineering relationships are displacing traditional distributor-centric procurement in high-voltage protection categories. This concentration is most visible in Japan's automotive component corridors where keiretsu structures favor incumbent technical partners.
Automotive Surge Absorber Market Segmentation
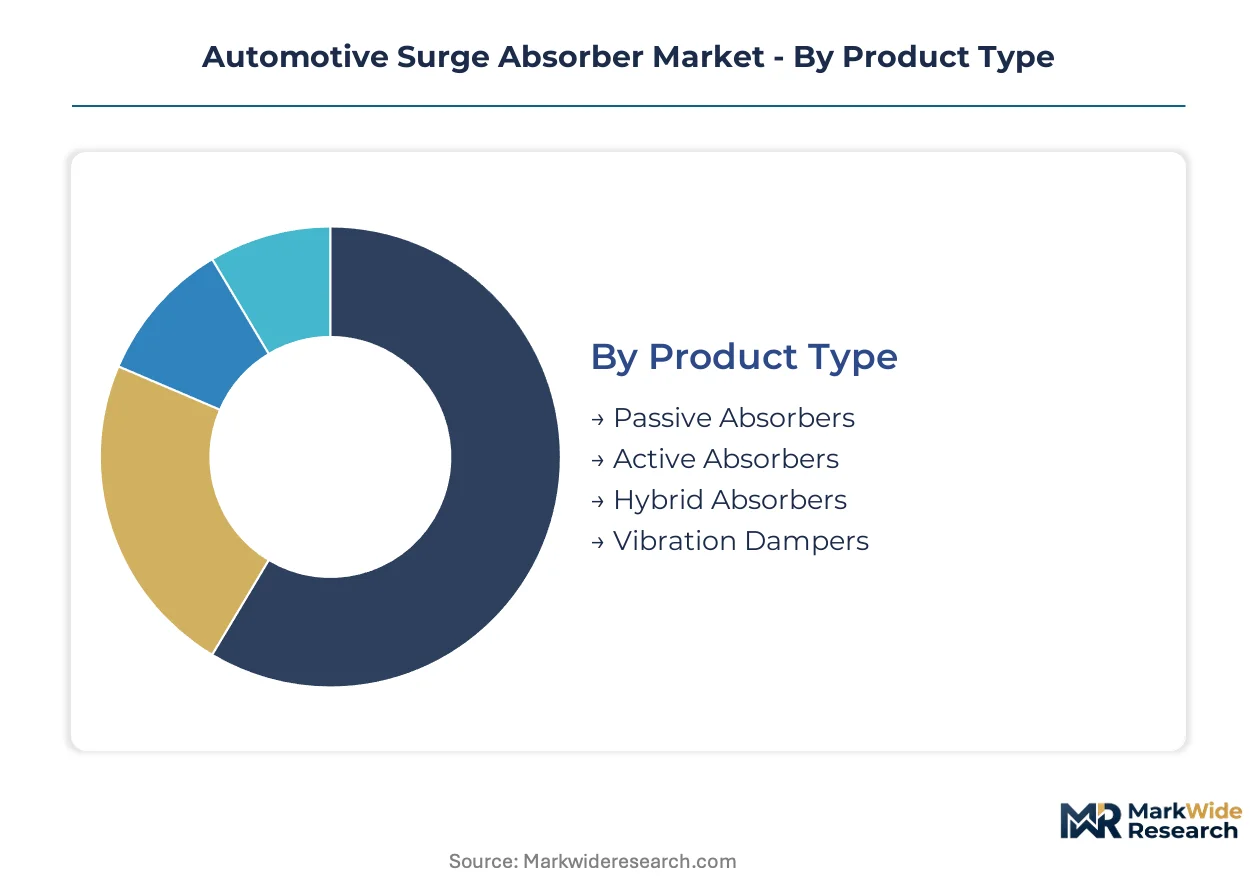
Segmentation in the automotive surge absorber market reveals how protection technologies stratify across voltage tiers, material science capabilities, and procurement channels. Understanding these divisions exposes where specification premiums concentrate and where cost engineering dominates purchasing decisions.
Product Type:
Regulatory differentiation across electromagnetic compatibility regimes is fragmenting product architectures, with ECE R10 in Europe, GB/T standards in China, and NHTSA interference limits in the US each favoring distinct response speed and clamping precision profiles.
- Passive Absorbers:Metal oxide varistors and transient voltage suppression diodes operate without external control circuits, relying on material breakdown characteristics to limit voltage spikes. Internal combustion platforms in cost-sensitive segments continue specifying these devices, though 800V electrification is compressing their addressable market.
- Active Absorbers:Semiconductor-based clamping circuits from suppliers like Infineon Technologies AG monitor line conditions and trigger suppression responses within nanoseconds. Battery-electric vehicle powertrains in Germany's manufacturing belt are pulling procurement toward these faster-acting alternatives as load-dump events intensify with higher system voltages.
- Hybrid Absorbers:Combining passive ceramic cores with active monitoring elements, these devices balance cost and performance for 48V mild-hybrid architectures. China's NMPA new energy vehicle protocols are accelerating qualification timelines for hybrid configurations.
- Vibration Dampers:Mechanical absorption elements address physical shock transmission rather than electrical transients, finding application in heavy-duty mining and construction vehicles facing sustained vibration exposure.
Passive absorbers handle the majority of throughput; active absorbers are gaining share fastest as electrification climbs voltage curves.
Material:
Cost tier stratification separates commodity rubber formulations from engineered composites commanding specification premiums in severe-duty applications.
- Rubber:Conventional elastomer compounds dominate legacy 12V system production where thermal cycling tolerance requirements remain modest. Suppliers serving India's nascent EV manufacturing base under PLI incentives are qualifying rubber-housed variants for cost-competitive domestic platforms.
- Polymer:Advanced thermoplastic formulations enable miniaturization through injection-molded housings that maintain dielectric strength. EPA weight reduction mandates in the US are accelerating polymer adoption as fuel-economy regulations tighten.
- Metal:Zinc oxide ceramic discs sintered into metal-oxide varistors remain the workhorse for high-energy dissipation. Japan's component supplier corridors concentrate heritage expertise in ceramic-metal interfaces, creating sourcing concentration risk for global OEMs.
- Composite:Metal-polymer laminates and fiber-reinforced structures deliver thermal stability under multiphysics stress. Heavy-duty commercial segments facing ECE R10 compliance burdens for extended cable harnesses specify composites for margin-critical protection.
Metal configurations anchor volume production; composites are expanding most quickly in premium electrified platforms.
Application:
Customer type divergence separates fleet procurement patterns from individual vehicle engineering specifications across voltage architectures.
- Lightweight Vehicles:Passenger car platforms prioritize compact form factors and weight minimization. Germany's automotive belt specifications for premium EVs are driving polymer-housed miniaturization to embed absorbers directly within battery module housings.
- Heavy-Duty Vehicles:Mining and construction equipment demands vibration-hardened protection with extended temperature envelopes. REACH chemical restrictions are forcing reformulation of zinc oxide stabilizer compounds for these severe-duty cycles.
- Electric Vehicles:High-voltage architectures from 400V to 800V require absorbers with expanded clamping ranges and faster response characteristics. China's GB/T standards mandate surge immunity testing exceeding conventional automotive thresholds.
- Commercial Vehicles:Fleet operators balance retrofit compatibility with forward-specification durability. NHTSA electromagnetic interference limits are driving replacement demand in legacy fleet upfitting across North American logistics corridors.
Lightweight vehicles generate the dominant order flow; electric vehicles are climbing the fastest on specification intensity.
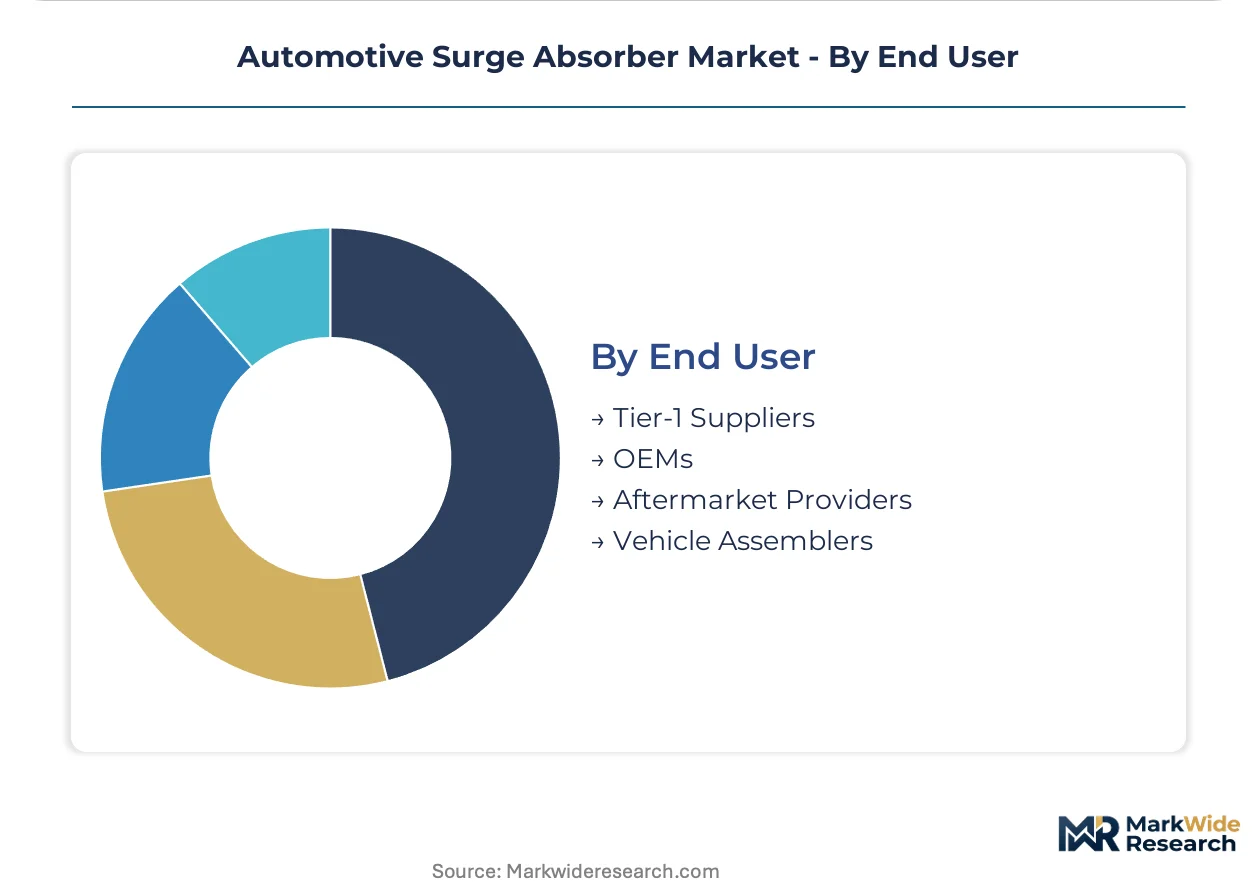
End User:
Supply concentration patterns concentrate technical differentiation among integrated Tier-1 suppliers while aftermarket channels compete on availability and interchangeability.
- Tier-1 Suppliers:Integrated component houses like Panasonic Industry and Littelfuse bundle surge protection with adjacent power distribution functions. Keiretsu structures in Japan favor incumbent technical partners with direct OEM engineering relationships.
- OEMs:Vehicle manufacturers with captive electronics divisions are insourcing high-voltage protection design for 800V platform differentiation. Direct OEM procurement is displacing distributor-centric channels in these categories.
- Aftermarket Providers:Independent distributors and service networks focus on legacy fleet maintenance and regional vehicle populations. Inventory breadth and cross-reference compatibility determine competitive position.
- Vehicle Assemblers:Contract manufacturers and regional assembly operations procure to customer specifications with limited design autonomy. Price sensitivity runs highest in this channel.
Tier-1 suppliers command the deepest technical engagement; OEM direct sourcing is expanding most quickly in high-voltage categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese component manufacturers export surge protection devices to German EV powertrain integrators, while Chinese domestic suppliers feed local battery-electric vehicle assembly lines under NMPA certification requirements.
China
Domestic EV production scales and 800V platform deployment drive absorber procurement volumes. NMPA vehicle safety mandates for new energy vehicles enforce surge immunity testing above conventional automotive thresholds. Yangtze River Delta manufacturing clusters host battery module integrators embedding protection components directly into pack architectures.
Germany
Premium EV platform engineering in Bavaria and Baden-Württemberg concentrates Tier-1 supplier technical engagement. ECE R10 electromagnetic compatibility rules tighten conducted and radiated emission limits for vehicle electrical subsystems. Stuttgart-area engineering centers co-develop absorber specifications with powertrain divisions for next-generation architectures.
United States
Commercial vehicle fleet retrofits and legacy upfitting generate aftermarket replacement demand. NHTSA electromagnetic interference limits and EPA weight reduction mandates shape specification priorities. Michigan-based automotive electronics corridors source compact polymer-housed variants for fuel-economy compliance.
Japan
Ceramic varistor heritage manufacturing anchors positions in domestic and export supply chains. METI industrial standards and keiretsu procurement structures favor incumbent technical partners. Nagoya-area component corridors concentrate expertise in metal-oxide disc sintering for high-energy dissipation applications.
India
Nascent EV manufacturing incentives under the PLI scheme attract first-mover supplier technical support investments. BIS certification requirements and CEA electrical safety regulations establish compliance baselines for domestic platforms. Tamil Nadu and Gujarat automotive corridors host contract manufacturers qualifying localized absorber supply.
Automotive Surge Absorber Market Competitive Landscape
Player mix skews toward diversified electronics conglomerates with passive component heritage, creating a tiered structure where ceramic expertise clusters geographically and fuse-integration capabilities separate premium positioning. Three archetypes dominate: semiconductor-based active protection specialists, metal-oxide varistor heritage manufacturers, and fuse-integrated module integrators. Competitive moves concentrate on strategic partnerships for 800V co-development and geographic expansion into Indian PLI-eligible manufacturing zones.
Within the heritage ceramic tier, Panasonic Industry Co., Ltd. and TDK Corporation occupy positions shaped by decades of metal-oxide formulation expertise. Semiconductor-based alternatives are represented by Infineon Technologies AG, whose active clamping architectures exemplify the response-speed differentiation pulling procurement in high-voltage electrified platforms. These three anchors illustrate how technical specialization maps to voltage-tier segmentation across passenger and commercial vehicle applications.
| Leading Market Players |
|---|
| Panasonic Industry Co., Ltd. |
| Littelfuse, Inc. |
| Infineon Technologies AG |
| Mitsubishi Materials Corporation |
| Bourns, Inc. |
| TDK Corporation |
| Murata Manufacturing |
| Nippon Chemi-Con Corporation |
| TE Connectivity Ltd. |
| Others |
Value Network & Pricing Analysis
Capacity utilization at Japanese ceramic varistor foundries shapes both supply concentration and price floors across the automotive surge absorber market. High-volume metal-oxide disc production in Nagoya-area corridors generates scale economies that passive component suppliers leverage against emerging polymer-housed alternatives, compressing margins for mid-tier competitors while anchoring premium pricing for heritage manufacturers with proven 800V qualification records.
Pricing Analysis
Current-generation active absorbers command 40-60% premiums over prior-generation passive metal-oxide varistors, while next-generation hybrid configurations with integrated monitoring circuits occupy an intermediate tier. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under ECE R10 and China's GB/T protocols, with UL-recognized variants capturing specification premiums. Cost compression in standard-tier rubber-housed units is intensifying because India's PLI-eligible domestic manufacturers are qualifying lower-cost formulations. Fleet operators in commercial vehicle segments exhibit highest price sensitivity, while German premium EV platform engineers demonstrate lowest sensitivity due to thermal-performance tradeoffs.
Supply Chain Analysis
Zinc concentrate refining capacity in Australia, Peru, and China constitutes the critical upstream chokepoint for metal-oxide varistor feedstock. Ceramic disc production draws from zinc oxide powder, silver electrode paste, and polymer housing resins, with sintering furnaces representing the most capital-intensive processing stage. Single-source vulnerability concentrates in Japan's component supplier corridors, where keiretsu structures limit alternative sourcing for OEMs requiring heritage technical partnerships. Distribution runs through Tier-1 integrators like Panasonic Industry and Littelfuse for OEM direct procurement, while aftermarket channels rely on independent distributors with cross-reference compatibility databases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive surge absorber demand tracks the capital expenditure cycle of electric vehicle platform development, with 800V architecture rollouts constituting the current cyclical upswing. Tier-1 supplier consolidation and OEM direct sourcing patterns favor technically differentiated incumbents with established electromagnetic compatibility qualification records.
For Market Incumbents: Consolidate ceramic varistor heritage positions through backward integration into zinc oxide powder processing, securing supply continuity against mining concentrate volatility. Acquire or partner with multiphysics simulation specialists to close CAE talent gaps for 800V thermal-electrical-mechanical co-design, defending against semiconductor-based active clamping substitutes from Infineon Technologies AG. For New Entrants and Emerging Players: Anchor in India's nascent EV manufacturing corridors under PLI scheme incentives, where localized technical support investments create first-mover positioning before keiretsu structures solidify. Target 48V mild-hybrid absorber configurations as the most penetrable segment, leveraging hybrid passive-active architectures that balance cost and performance without requiring full 800V qualification cycles. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors fuse-integrated suppression module specialists with proven engine-bay miniaturization capabilities and direct OEM engineering relationships. Long-term viability hinges on 800V platform penetration rates and whether polymer-housed variants can displace ceramic-metal configurations in high-energy dissipation applications. Watch NMPA and ECE R10 regulatory timeline compression as the inflection indicator for qualification capacity constraints and laboratory bottlenecks.| Strategic Initiative | Industry Significance |
|---|---|
| 800V Co-Development Partnership | Direct OEM engineering relationships displace distributor-centric procurement in high-voltage protection categories. |
| Polymer Housing Miniaturization | Advanced ceramic sintering enables battery module embedding, meeting EPA weight reduction mandates. |
| India PLI Zone Technical Support | Localized qualification accelerates domestic platform integration before supply structures mature. |
| Multiphysics Simulation Capability Buildout | CAE talent acquisition addresses 800V thermal-electrical-mechanical co-design expertise gaps. |
| REACH-Compliant Stabilizer Reformulation | Zinc oxide disc composition changes maintain European market access despite chemical restrictions. |
Research Methodology
A standing panel of Tier-1 supplier procurement directors, OEM platform engineers, aftermarket distribution managers, and electromagnetic compatibility testing laboratory directors provided ongoing calibration throughout the study period. Primary fieldwork combined structured interviews with secondary validation against vehicle production databases, IHS Markit registration data, NMPA certification filings, and ECE R10 test reports. Bottom-up segment sizing across product type, material, application, and voltage tier triangulated against top-down market envelope estimates derived from automotive electronics content-per-vehicle analysis.
Consistency checks validated volume and value outputs against external benchmarks including customs trade data for zinc oxide varistor imports, SEC filings from diversified electronics conglomerates with passive component divisions, and regional automotive production statistics from Germany's VDA and China's CAAM. The analytical framework modeled segmentation dimensions spanning propulsion architecture, voltage tier, vehicle class, and regional regulatory cluster across the projection horizon. CAGRs were derived from regression analysis of historical qualification cycle lengths, platform rollout schedules, and supplier contract tenors, with 800V penetration rates and NMPA certification velocity as automotive-specific forecast inputs.
Material uncertainties — raw material price volatility, regulatory timeline compression, and technology substitution rates — sit outside the modeled envelope. Forecasts reflect assumptions regarding sustained OEM electrification commitments and stable trade flows for zinc concentrate processing. Practitioners should keep alternative scenarios live as battery-electric platform voltage trajectories and REACH chemical restriction enforcement evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Motorcycle E-Call Market
Automotive Safety and Security Systems
Automotive Seat Belt Sensor Market
Automotive Safety and Security Systems
Global Motorcycle Advanced Driver Assistance System (ADAS) Market
Automotive Safety and Security Systems
Automotive Airbag and Seat Belt Market
Automotive Safety and Security Systems
Collision Mitigation Technology Market
Automotive Safety and Security Systems
Safety Restraint Systems Market
Automotive Safety and Security Systems
Global Automotive Curtain Airbags Market
Automotive Safety and Security Systems
China Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Forward Collision Warning System for Automotive Market
Automotive Safety and Security Systems
Vehicle Speed Monitoring System Market
Automotive Safety and Security Systems
Engine Braking System Market
Automotive Safety and Security Systems
United States Automotive Airbag Systems Market
Automotive Safety and Security Systems
Automotive Brake System Market
Automotive Safety and Security Systems
Automotive Occupant Sensing System Market
Automotive Safety and Security Systems
Anti-Lock Braking System (ABS) Market
Automotive Safety and Security Systems
United States Automotive Collision Avoidance Systems Market