
 Russia Automotive Electric Actuators Market | 2026-2036
Russia Automotive Electric Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Automotive Electric Actuators Market Analytics
Aftermarket service revenue is narrowing toward OEM-anchored supply contracts as vehicle assemblers seek tighter lifecycle control. Continental dominates electromechanical actuator integration for powertrain applications across Russian OEM lines. Robert Bosch GmbH leverages its Tier-1 supplier relationships to sustain channel control in chassis control segments. Nidec Corporation specializes in compact rotary actuator designs for HVAC systems in domestically assembled passenger vehicles.
Russia automotive electric actuators are precision electromechanical devices converting electrical signals into mechanical motion, typically operating at 12-48V with position feedback resolution below 0.1 millimeters, primarily enabling automated control of engine throttles, brake calipers, and climate vents. Linear actuators lead product type demand due to their penetration in throttle body and seat adjustment applications where stroke precision determines system reliability. Electromechanical technology anchors the technology split, displacing hydraulic alternatives in powertrain modules as OEMs target weight reduction and energy efficiency gains. Smart actuators represent the fastest-growing product category, integrating local processing capability for real-time diagnostic feedback in steering and chassis control systems.
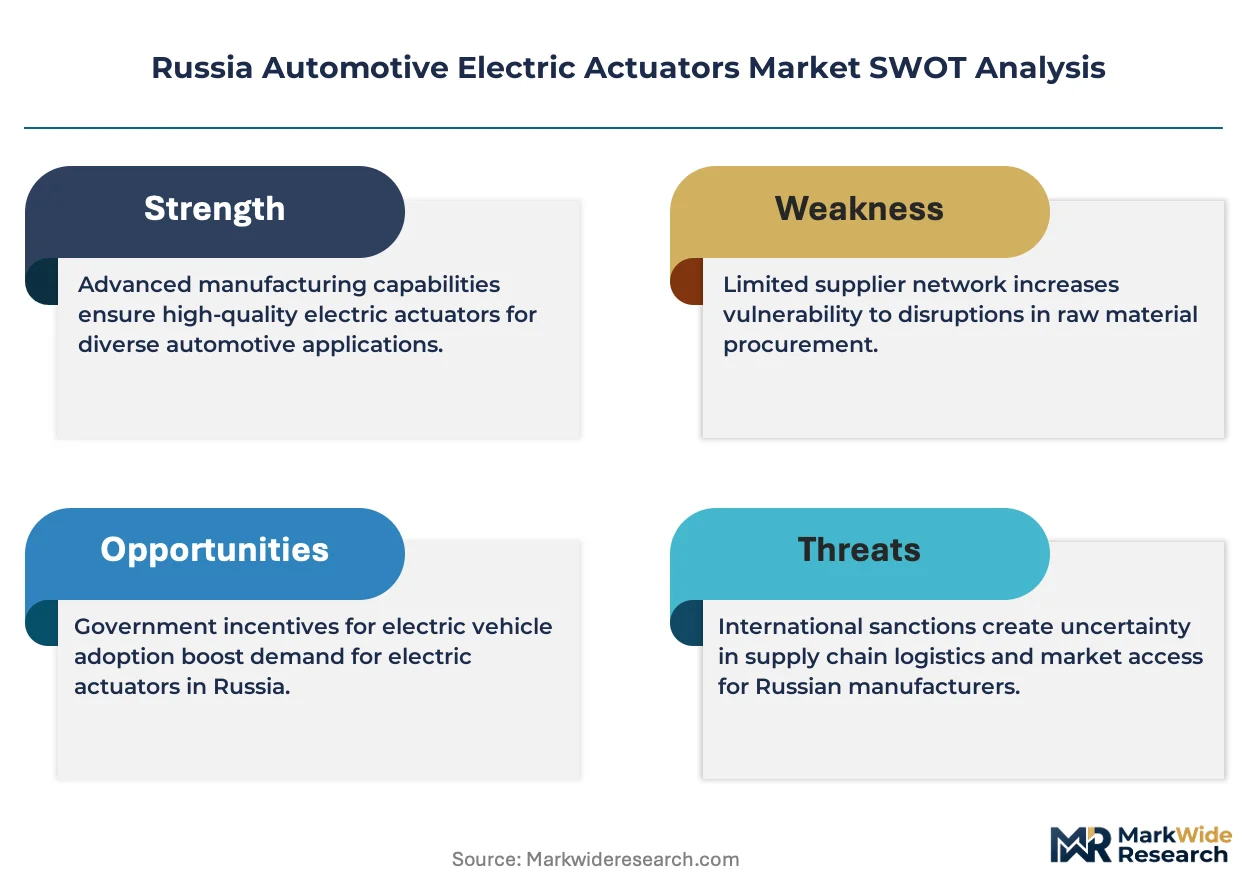
Russia's national technical regulator enforces GOST-R certification and UNECE harmonized vehicle standards that mandate fail-safe actuator performance in brake-by-wire and steer-by-wire architectures. The country's environmental regulator applies emission thresholds that push powertrain actuator electrification to enable precise fuel injection and exhaust gas recirculation control. Stakeholders must monitor how import substitution policies reshape component sourcing rules for foreign-owned Tier-1 suppliers operating domestic assembly plants.
Market Dynamics
Domestic vehicle production modernization is compressing supplier lead times while GOST-R certification mandates are forcing electromechanical architecture redesigns across Russian OEM assembly lines.
Growth Catalysts
- UNECE Harmonized Standards:Brake-by-wire and steer-by-wire mandates under Russia's national technical regulation framework are accelerating electromechanical actuator penetration in chassis control modules.
- Central Federal District Manufacturing:Moscow-region automotive clusters are concentrating precision actuator demand as domestic OEMs localize powertrain component sourcing.
- Smart Actuator Integration:Local processing capability for real-time diagnostic feedback is displacing conventional position-feedback designs in steering and suspension systems.
Market Restraints
- Import Substitution Policy Friction:Foreign-owned Tier-1 suppliers face component sourcing rule changes that disrupt established supply relationships for electromechanical subassemblies.
- Semiconductor Input Volatility:Position feedback sensor chips and motor driver ICs expose actuator manufacturers to global electronics supply fluctuations.
- Hydraulic System Inertia:Established brake and steering hydraulic architectures in legacy vehicle platforms resist full electromechanical replacement during model refresh cycles.
Strategic Opportunities
- Volga Region Expansion:Tolyatti and Nizhny Novgorod automotive manufacturing corridors present underpenetrated demand for HVAC rotary actuators in expanded passenger vehicle output.
- Emission Threshold Compliance:Russia's environmental regulator applies exhaust gas recirculation control mandates that create actuator demand for precise throttle body and EGR valve positioning.
- Sensor-Actuator Convergence:Integration of torque sensing with electromechanical drive units enables consolidated module designs that reduce wiring complexity and assembly labor.
Industry Challenges
- Embedded Systems Engineering Talent:Firmware development for 12-48V motor control algorithms and position feedback loops faces acute shortage in Russian technical labor markets.
- GOST-R Certification Timelines:Fail-safe performance validation for safety-critical brake and steering actuators extends product qualification cycles before production release.
- Legacy Platform Integration:Electromechanical actuator retrofit into existing vehicle electrical architectures requires voltage level translation and signal protocol adaptation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Automotive Electric Actuators Market |
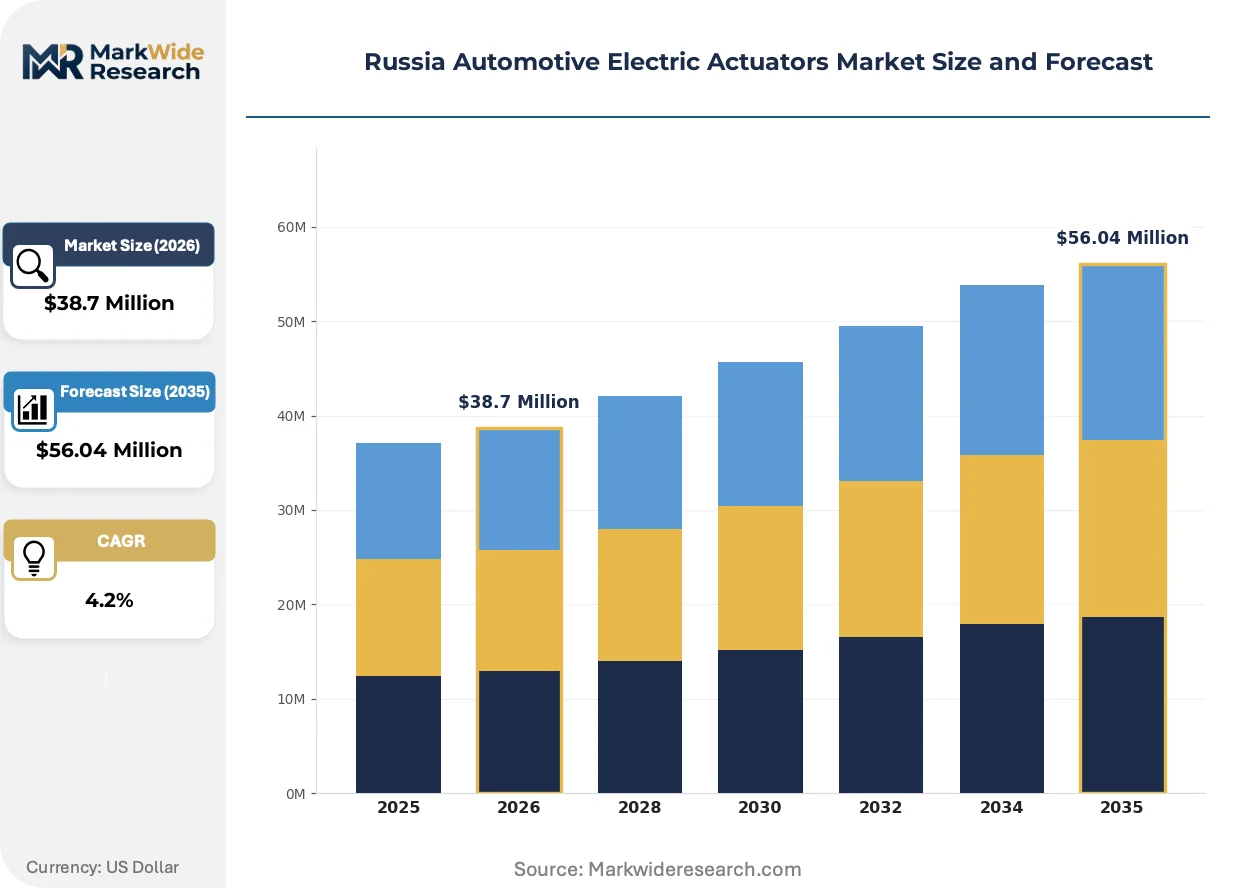
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $56.04 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Actuators, Rotary Actuators, Smart Actuators, Pneumatic Actuators End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Technology: Electromechanical, Piezoelectric, Hydraulic, Magnetic Application: Powertrain, Chassis Control, HVAC, Steering Systems |
| Companies Covered | Denso Corporation, Mitsubishi Electric Corporation, Nidec Corporation, Hitachi Ltd, Continental, Robert Bosch GmbH, Johnson Electric, Valeo, ZF Friedrichshafen, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Automotive Electric Actuators Market Evolving Landscape
Electromechanical architectures are displacing hydraulic systems across powertrain and chassis modules while local processing capability migrates into actuator housings.
Digital twin technology is virtualizing actuator development workflows. Russian OEM engineering teams are adopting physics-based simulation for throttle body and brake caliper electromechanical designs prior to physical prototyping. This compression of validation cycles is reducing GOST-R certification preparation timelines while improving first-pass yield in production ramp phases.
Russia's national technical regulator enforces UNECE harmonized vehicle standards that mandate redundant position sensing in steer-by-wire architectures. Tier-1 suppliers must demonstrate fail-safe actuator performance through documented fault-tree analysis before receiving type approval. The chassis control segment bears the heaviest compliance burden as steer-by-wire adoption accelerates in premium domestic vehicle lines.
Fleet operators and vehicle assemblers are consolidating actuator procurement under long-term supply agreements with embedded technical support clauses. Discrete spot purchasing of replacement units is yielding to lifecycle service contracts that bundle predictive maintenance analytics with hardware supply. This behavioral shift concentrates most visibly in the Central Federal District where Moscow-based fleet managers negotiate consolidated agreements covering multiple vehicle platforms.
Russia Automotive Electric Actuators Market Segmentation
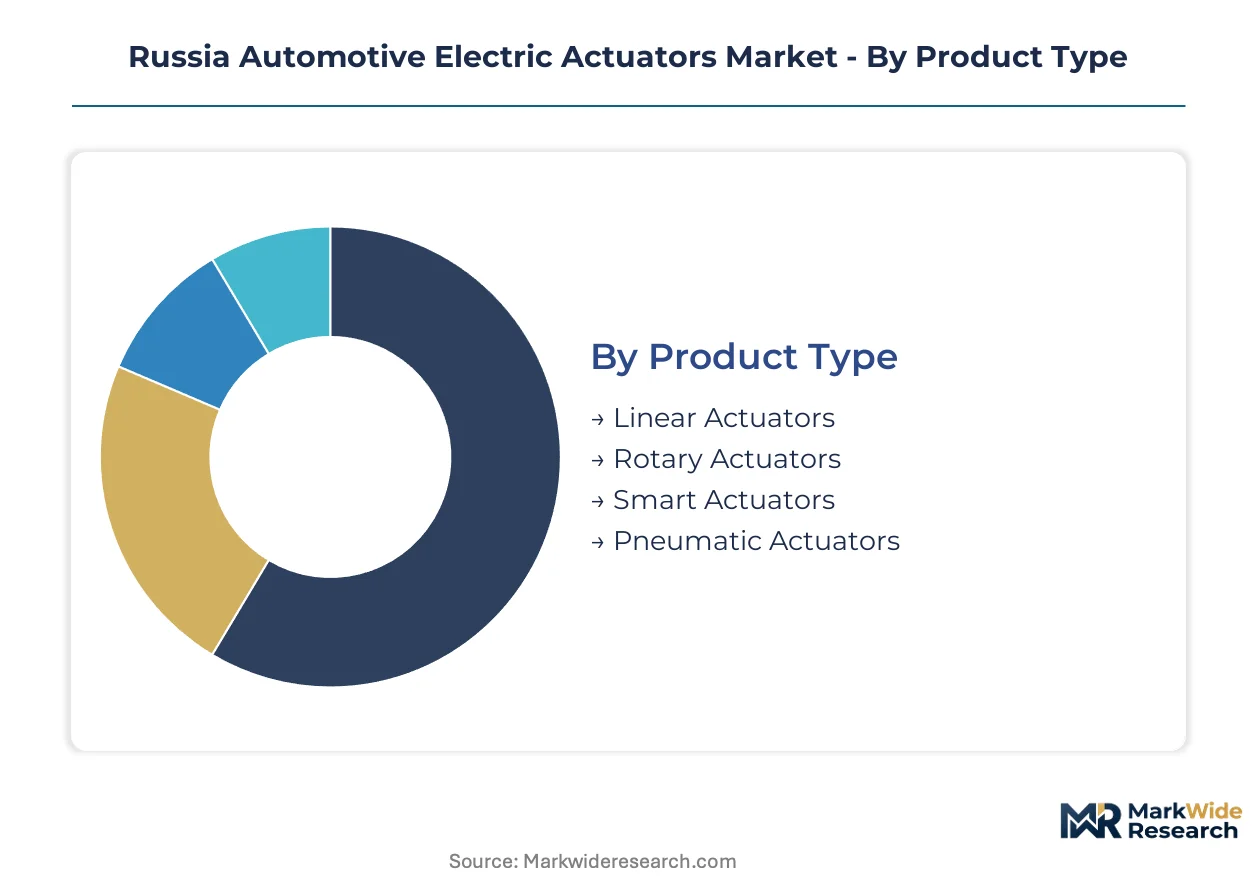
Segmentation in the Russia automotive electric actuators market reveals how component sourcing decisions diverge across the vehicle lifecycle. After-sales service intensity varies dramatically between OEM-anchored supply contracts and independent aftermarket channels, reshaping inventory positioning and technical support requirements for suppliers operating in the Central Federal District and Volga manufacturing corridors.
Product Type:
After-sales service intensity concentrates most heavily in smart actuator deployments where embedded diagnostics require specialized technician training and software-enabled fault resolution.
- Linear Actuators:These devices convert rotational motor motion into precise linear displacement through ball screw or belt drive mechanisms, typically achieving stroke lengths of 50-300mm with positional accuracy below 0.1mm. Demand clusters in throttle body applications across Moscow-region OEM assembly lines where GOST-R certification mandates fail-safe return-to-home functionality. The Central Federal District's powertrain component localization drives specification standardization among domestic vehicle assemblers.
- Smart Actuators:Integrated local processing units enable real-time diagnostic feedback and predictive maintenance signaling through CAN bus communication protocols. Chassis control modules in premium domestic vehicle lines are absorbing these units fastest as steer-by-wire architectures proliferate under UNECE harmonized standards enforcement by Russia's national technical regulator.
- Rotary Actuators:Compact brushless DC motor designs with harmonic gear reduction serve HVAC damper control in Tolyatti-assembled passenger vehicles.
- Pneumatic Actuators:Compressed air-driven mechanisms persist in legacy commercial vehicle brake systems where electromechanical retrofit costs exceed replacement economics.
Linear actuators hold the largest share; momentum sits with smart actuators.
End User:
Cost tier stratification separates long-term supply agreements from spot procurement, with OEM-anchored contracts commanding premium pricing for embedded technical support and lifecycle warranty coverage.
- OEMs:Domestic vehicle manufacturers in the Volga region negotiate multi-year actuator supply contracts with localized production requirements under import substitution policy frameworks. These agreements bundle predictive maintenance analytics and dedicated engineering support, compressing supplier margins while securing volume commitments for electromechanical chassis control modules.
- Tier-1 Suppliers:Foreign-owned component integrators face component sourcing rule disruptions as GOST-R certification timelines extend for safety-critical brake and steering actuator designs. Their established channel control in chassis control segments depends on demonstrating fail-safe performance through documented fault-tree analysis before type approval.
- Aftermarket Providers:Discrete replacement unit distribution yields to consolidated procurement under fleet operator agreements in Moscow-based vehicle management operations.
- Vehicle Assemblers:Nizhny Novgorod corridor manufacturers source actuator subassemblies for final integration into domestically produced platforms.
OEMs dominate volume; Tier-1 suppliers are gaining share fastest through technical specification influence.
Technology:
Application requirements in powertrain and chassis modules determine technology selection, with energy efficiency and weight reduction targets displacing legacy hydraulic alternatives.
- Electromechanical:Brushless DC motor architectures with integrated position feedback sensors operate at 12-48V with resolution below 0.1 millimeters. Russia's environmental regulator applies emission thresholds that push powertrain actuator electrification for precise fuel injection and exhaust gas recirculation valve positioning in domestically assembled vehicles.
- Piezoelectric:Ceramic element expansion enables nanometer-scale positioning precision for fuel injector control in high-pressure direct injection systems. The Central Federal District's precision manufacturing base supports ceramic element fabrication, though piezoelectric driver electronics remain import-dependent.
- Hydraulic:Pressurized fluid power persists in legacy brake and steering architectures resistant to full electromechanical replacement during model refresh cycles.
- Magnetic:Voice coil and solenoid mechanisms serve fast-response applications in transmission shift control modules.
Electromechanical technology commands the largest share; piezoelectric exhibits the steepest expansion trajectory in fuel system applications.
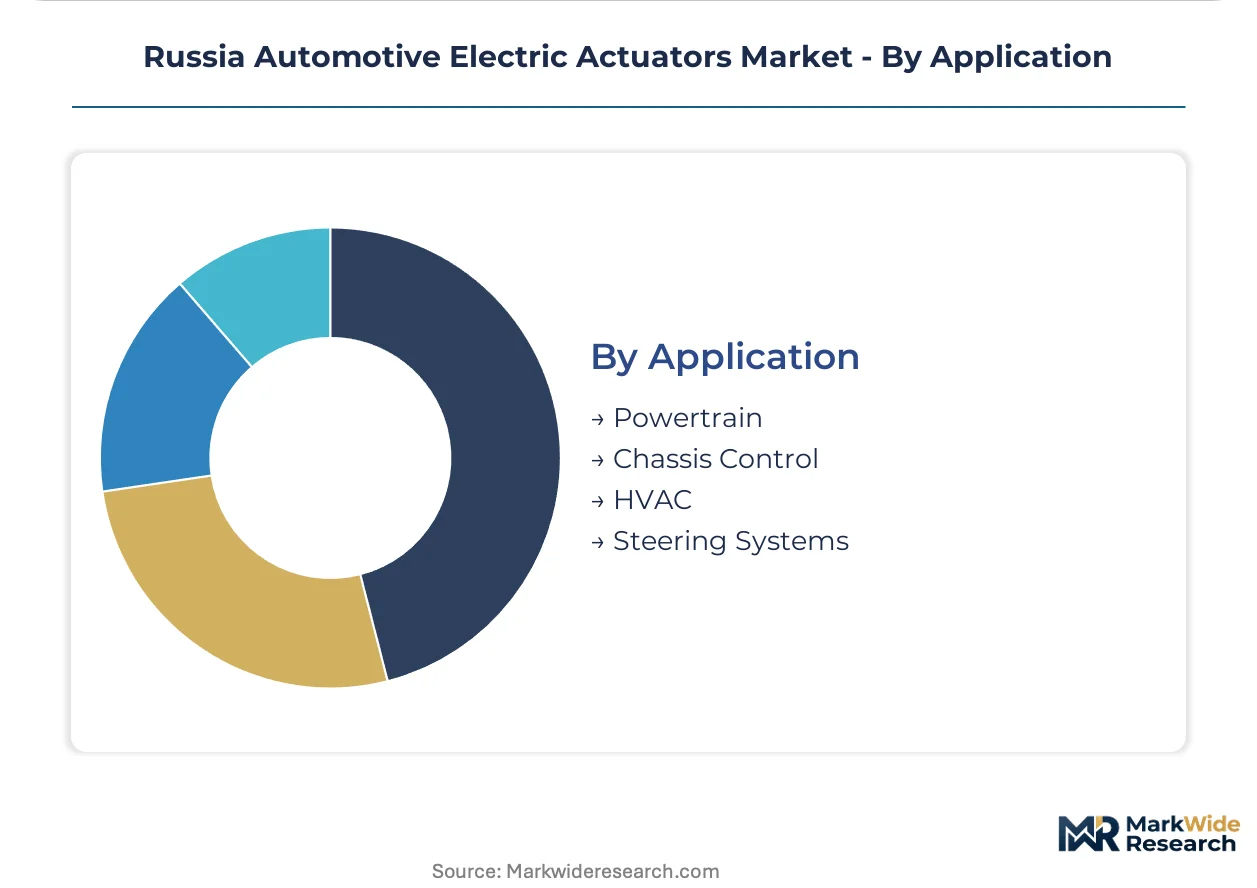
Application:
Customer type differentiation separates safety-critical chassis systems from comfort-oriented HVAC modules, with certification burden and technical support intensity varying accordingly.
- Chassis Control:Brake-by-wire and steer-by-wire architectures mandate redundant position sensing and documented fail-safe performance validation under Russia's national technical regulation framework. UNECE harmonized standards enforcement concentrates compliance burden in this segment as premium domestic vehicle lines accelerate electromechanical adoption.
- Powertrain:Throttle body, variable valve timing, and exhaust gas recirculation actuators enable precise combustion control for emission threshold compliance. The Volga region's automotive manufacturing clusters generate concentrated demand as Tolyatti and Nizhny Novgorod facilities localize component sourcing.
- HVAC:Damper and blend door actuators prioritize cost optimization over precision in mass-market passenger vehicle climate control systems.
- Steering Systems:Electromechanical power steering motors integrate torque sensing with drive units for consolidated module designs reducing wiring complexity.
Powertrain applications hold the largest share; chassis control is climbing the fastest as steer-by-wire mandates expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Central Federal District and Volga region concentrate Russia's automotive electric actuator consumption through distinct pathways: Moscow-area OEMs prioritize chassis control precision for premium vehicle lines, while Tolyatti and Nizhny Novgorod facilities emphasize powertrain component localization for mass-market output.
Central Federal District
Brake-by-wire and steer-by-wire mandates from Russia's national technical regulator are accelerating smart actuator deployment in Moscow-region vehicle assembly plants. GOST-R certification requirements for fail-safe performance extend product qualification timelines for Tier-1 suppliers establishing domestic engineering centers. The district's precision manufacturing base supports position feedback sensor integration for throttle body applications across localized powertrain platforms.
Volga Region
Exhaust gas recirculation control mandates from Russia's environmental regulator are driving electromechanical actuator demand in Tolyatti-assembled passenger vehicles. Import substitution policies are forcing foreign-owned suppliers to reconfigure component sourcing rules for electromechanical subassemblies. Nizhny Novgorod manufacturing corridors present underpenetrated demand for HVAC rotary actuators as domestic OEMs expand climate system electrification.
Siberian Federal District
Commercial vehicle fleet operators in Novosibirsk and Krasnoyarsk are consolidating actuator procurement under lifecycle service contracts with predictive maintenance analytics. Regional logistics infrastructure constraints compress supplier lead times for replacement units in remote mining and timber transport applications. Local vehicle modification shops retrofit legacy hydraulic brake architectures with electromechanical alternatives for heavy-duty platform modernization.
Southern Federal District
Port logistics and agricultural machinery assembly in Rostov-on-Don generate specialized demand for pneumatic-to-electromechanical actuator conversion in commercial vehicle brake systems. The district's vehicle import flows from neighboring countries create aftermarket service intensity for non-domestic actuator calibration and diagnostic tooling. Krasnodar-based fleet managers negotiate consolidated supply agreements covering mixed-platform vehicle populations.
Northwestern Federal District
St. Petersburg automotive component manufacturing is attracting Tier-1 supplier technical support facilities to serve Baltic-region export-oriented assembly lines. The city's engineering talent pool supports firmware development for 12-48V motor control algorithms in smart actuator designs. Regional industrial policy incentives are drawing electromechanical subassembly localization investments from foreign-owned suppliers seeking GOST-R certification efficiency.
Russia Automotive Electric Actuators Market Competitive Landscape
Capability concentration sits with electromechanical integration specialists; scale advantage sits with diversified automotive component conglomerates. The market structure tiers between precision actuator designers with embedded systems expertise and volume manufacturers leveraging established OEM channel relationships. Three archetypes dominate: Japanese motor-control specialists, German chassis-system integrators, and diversified European automotive suppliers. Competitive moves center on strategic partnerships for firmware development and backward integration into position feedback sensor supply.
Within the Japanese specialist tier, Denso Corporation and Mitsubishi Electric Corporation represent the precision motor-control archetype with embedded diagnostic capability. Nidec Corporation occupies a distinct position in compact rotary actuator designs. Among German-anchored system integrators, Continental and Robert Bosch GmbH exemplify chassis control module consolidation. Johnson Electric anchors the diversified supplier category with electromechanical actuator breadth across vehicle platforms.
| Leading Market Players |
|---|
| Denso Corporation |
| Mitsubishi Electric Corporation |
| Nidec Corporation |
| Hitachi Ltd |
| Continental |
| Robert Bosch GmbH |
| Johnson Electric |
| Valeo |
| ZF Friedrichshafen |
| Others |
Value Network & Pricing Analysis
The Moscow-Kazan freight corridor's volatile fuel surcharges compress supplier margins while amplifying price differentiation between OEM-anchored long-term contracts and spot aftermarket procurement. Electromechanical actuator manufacturers absorb logistics cost swings through tiered pricing structures that separate GOST-R certified safety-critical chassis modules from standard HVAC rotary units.
Pricing Analysis
Long-term offtake agreements dominate OEM procurement, locking in volume commitments for brake-by-wire and steer-by-wire actuators across Moscow-region assembly plants. Price differentiation hinges on GOST-R certification tier and embedded diagnostic capability, with smart actuators commanding premium positioning over conventional position-feedback designs. Cost compression in mass-market HVAC applications intensifies as import substitution policies force foreign Tier-1 suppliers to localize subassembly production. Fleet operators in the Central Federal District exhibit lowest price sensitivity due to lifecycle service bundling, while independent aftermarket channels face acute margin pressure from consolidated procurement trends.
Supply Chain Analysis
Rare-earth magnet feedstock from China and position feedback sensor chips from Taiwan and South Korea anchor electromechanical actuator manufacturing cost structures. Brushless DC motor laminations, Hall-effect sensors, and CAN bus controller ICs draw from concentrated Asian supply bases. Single-source vulnerability in semiconductor motor driver ICs exposes Russian assembly plants to global electronics allocation disruptions. Distribution runs through Tier-1 supplier technical support facilities clustered in St. Petersburg and Nizhny Novgorod, with final integration occurring at domestic OEM lines in Tolyatti and Moscow-region corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hydraulic brake and steering architectures in legacy commercial vehicle fleets present a persistent substitution threat that electromechanical incumbents must actively displace through total-cost-of-ownership demonstration and retrofit program development.
For Market Incumbents: Pre-empt hydraulic system retention in heavy-duty platforms by deploying field engineering teams to quantify fuel efficiency gains from electromechanical chassis modules. Lock in backward integration into position feedback sensor supply to insulate margins from semiconductor allocation volatility. Cement GOST-R certification capabilities as a competitive moat against emerging Asian suppliers lacking fail-safe validation expertise. For New Entrants and Emerging Players: Establish a beachhead in HVAC rotary actuators for the Nizhny Novgorod manufacturing corridor, where climate system electrification lags powertrain and chassis adoption. Target fleet operator lifecycle service contracts in the Siberian Federal District's commercial vehicle segments, where predictive maintenance analytics remain underdeveloped. Lead with software-enabled diagnostic capability to differentiate from commodity pneumatic-to-electromechanical conversion offerings. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified European automotive suppliers seeking to divest non-core electromechanical actuator divisions amid Russia's import substitution policy friction. Long-term viability rests on embedded systems firmware capabilities rather than pure manufacturing scale. Watch for GOST-R certification timeline compression as the signal indicating regulatory environment stabilization and acquisition multiple expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces GOST-R certification burden across multiple domestic OEM vehicle lines simultaneously. |
| Backward Integration into Sensors | Captures position feedback IC supply currently exposed to Taiwan semiconductor allocation cycles. |
| Software-Defined Actuator Investment | Enables predictive maintenance revenue streams through CAN bus diagnostic protocol deployment. |
| Geographic Manufacturing Footprint | St. Petersburg engineering centers accelerate firmware development for smart actuator designs. |
| Long-term Supply Agreement | Locks in Volga region OEM volume commitments ahead of import substitution policy enforcement. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with OEM platform engineers, Tier-1 supplier procurement directors, aftermarket distributors in Moscow and Nizhny Novgorod, and GOST-R certification technical auditors. Secondary validation drew from UNECE regulatory harmonization documents, Russia's national technical regulation framework updates, vehicle production databases, and customs records tracking electromechanical subassembly import flows. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the Russian automotive sector.
Calibration against historical GOST-R certification timelines and OEM localization announcements refined projection parameters across the modeling period. Segmentation dimensions included product type, application module, technology architecture, end-user contract structure, and regional manufacturing cluster. CAGRs were derived from elasticity-adjusted volume trajectories incorporating import substitution policy implementation pace and semiconductor supply recovery assumptions.
Stress conditions across GOST-R certification timeline extension, rare-earth magnet price volatility, and steer-by-wire mandate acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement consistency and Tier-1 supplier localization commitment durability. Cross-checking against vehicle registration data and OEM production schedule disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
France Automotive Market
Automotive Components
Mexico Automotive Pneumatic Actuators Market
Automotive Components
Automotive Sensor Cleaning System Market
Automotive Components
MEMS Automobile Sensors Market
Automotive Components
Japan Automotive Electric Actuators Market
Automotive Components
Automotive Polycarbonate Glazing Market
Automotive Components
Europe Automotive Electric Actuators Market
Automotive Components
Automotive Dynamic Spotlight Market
Automotive Components
Automotive Evaporative Emission Control (EVAP) System Market
Automotive Components
Automotive Radiator Fan Market
Automotive Components
Global Automotive Damper Control Unit Market
Automotive Components
Automotive Sunroof Glass Market
Automotive Components
Automotive Tailgate Market
Automotive Components
Global Automatic Lubrication System Market
Automotive Components
Automotive V-Belts Market
Automotive Components
France Automotive Electric Actuators Market