
 Crane Collision Avoidance Devices Market | 2026-2036
Crane Collision Avoidance Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Crane Collision Avoidance Devices Market Insights
Chinese crane OEM manufacturing capacity is consolidating around integrated safety electronics as a factory-standard offering. Sany leverages its domestic supply chain to bundle radar and ultrasonic sensor packages at the point of crane assembly. Konecranes anchors its competitive position through R&D intensity in port automation, where collision avoidance merges with remote operator systems. Liebherr differentiates through specialized sensor calibration for heavy-lift crawler cranes operating in confined construction sites.
Crane collision avoidance devices comprise integrated sensor arrays, processing units, and alarm or intervention mechanisms designed to detect proximity hazards and prevent contact between crane structures, loads, and personnel or equipment. These systems typically operate through electromagnetic wave emission and echo detection within defined safety perimeters, triggering audible warnings or automatic motion cessation when thresholds are breached. Radar systems dominate current installations in port and maritime applications where atmospheric conditions degrade optical sensor performance, while lidar systems represent the fastest-growing product category as price curves flatten and point-cloud resolution improves for precision construction environments. Active technology systems capture the largest share of new procurement, though hybrid architectures combining redundant sensor modalities are gaining preference among European contractors seeking compliance with machinery safety directives.
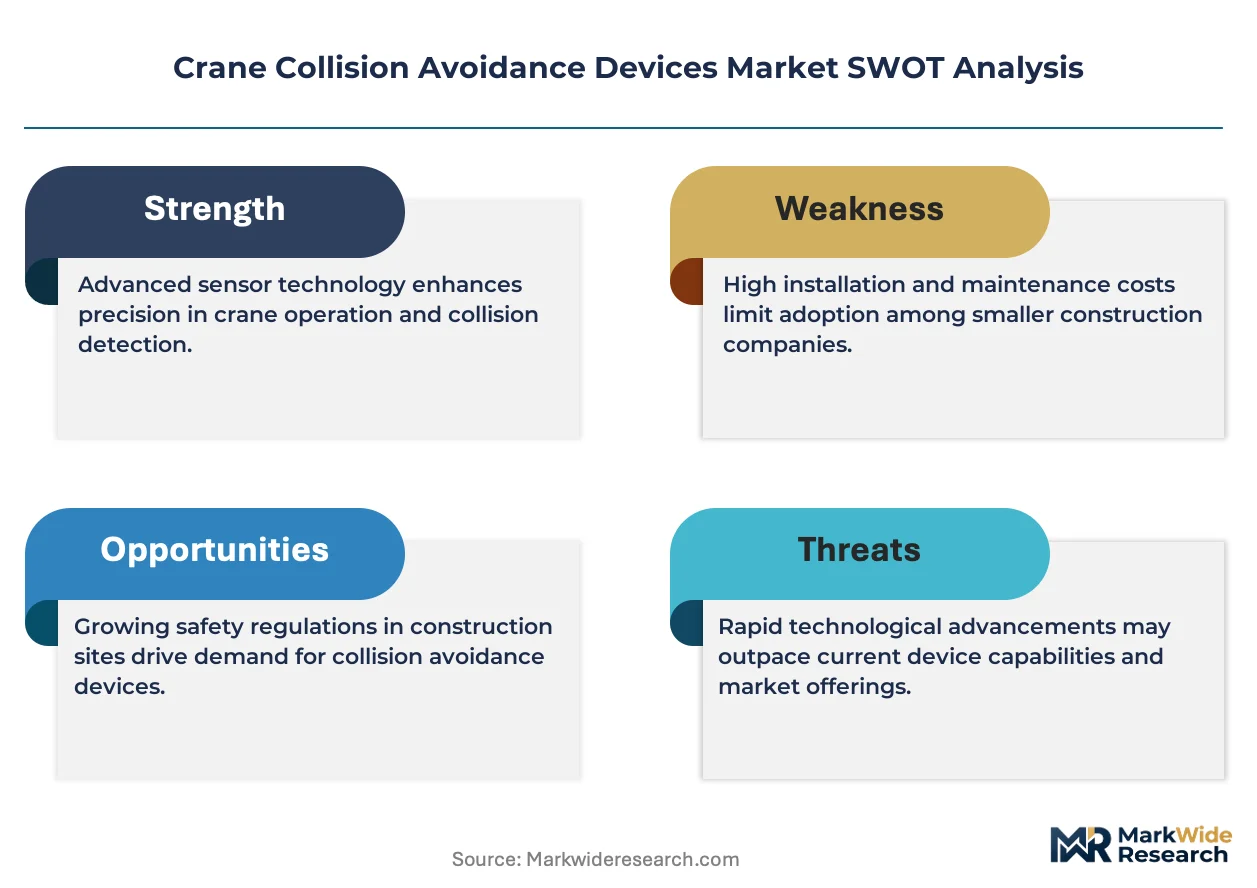
OSHA crane safety standards and EU machinery directives under CE marking frameworks mandate operator visibility and hazard detection capabilities that directly shape product certification requirements and market access conditions. China's SAMR enforces GB standards for construction machinery safety that increasingly reference anti-collision functionality as a design prerequisite. Stakeholders must monitor how regulatory convergence between North American and European safety standards influences sensor interoperability specifications and supplier qualification protocols.
Market Dynamics
Factory-fit integration of anti-collision electronics is compressing the aftermarket retrofit window as Chinese and European crane OEMs embed sensor suites during original assembly, shifting procurement power toward equipment manufacturers and away from standalone device vendors.
Growth Catalysts
- OSHA visibility mandates:US construction safety directives now require enhanced operator sight-line assistance for cranes exceeding specified load thresholds, directly stimulating sensor procurement from general contractors and rental fleet operators.
- Port automation in Singapore and Rotterdam:Container terminal operators are specifying collision-avoidance-to-remote-control integration as a single procurement package, bundling hardware with software control layers.
- Radar reliability in maritime atmospheres:Salt-laden, high-humidity port environments degrade optical sensors, positioning electromagnetic wave systems as the default specification for coastal crane installations.
Market Restraints
- Semiconductor input volatility:Processing units and sensor chipsets face supply concentration risk from Taiwan and South Korean foundries, creating lead time unpredictability for device assemblers.
- Calibration complexity:Multi-sensor fusion architectures require site-specific parameter tuning that extends commissioning timelines and demands specialized field engineering capacity.
- Substitute automation pathways:Fully autonomous crane systems with embedded perception eliminate discrete collision avoidance as a separate procurement category, threatening standalone device vendors.
Strategic Opportunities
- India infrastructure buildout:National highway and metro construction projects are specifying tower cranes with anti-collision functionality for the first time, creating virgin demand in a historically price-sensitive market.
- Lidar-construction management convergence:Point-cloud data from crane-mounted sensors is converging with building information modeling workflows, enabling new revenue streams through data licensing.
- EU machinery safety directive updates:Pending CE marking revisions will mandate redundant sensing modalities, forcing retrofit upgrades across existing European crane fleets.
Industry Challenges
- Field calibration expertise scarcity:Technicians capable of integrating radar, ultrasonic, and optical inputs into unified alarm logic remain concentrated in Germany and Japan, constraining deployment velocity elsewhere.
- Legacy crane integration friction:Pre-digital control systems lack standardized communication protocols, requiring custom interface development for each retrofit installation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crane Collision Avoidance Devices Market |
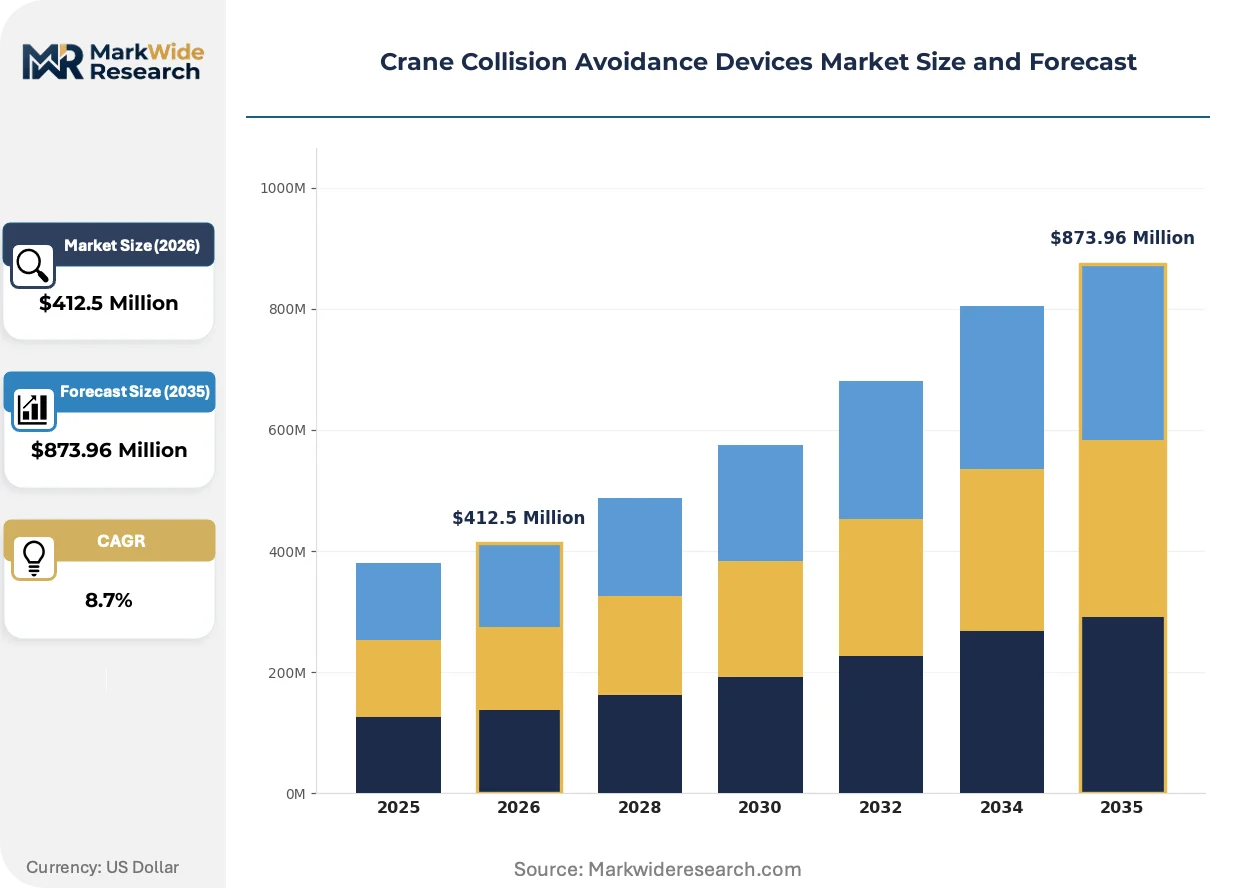
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $873.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radar Systems, Camera Systems, Ultrasonic Sensors, Lidar Systems Technology: Active Systems, Passive Systems, Hybrid Systems, Wireless Systems Application: Construction, Manufacturing, Shipping, Mining End User: OEMs, Contractors, Shipping Companies, Equipment Rentals |
| Companies Covered | Sany, Konecranes, Terex Corporation, Hyster-Yale, Cargotec (Kalmar), Liebherr, Zoomlion, Manitex, XCMG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crane Collision Avoidance Devices Market Trends and Innovations
Sensor modality fusion is displacing single-technology reliance as port operators and construction firms demand fail-operational hazard detection. This shift compresses vendor specialization advantages and rewards systems integrators with multi-physics competency.
Radar-based proximity detection is converging with ultrasonic ranging in hybrid architectures that layer electromagnetic wave reliability with short-range precision. Port operators in Hamburg and Los Angeles are specifying these dual-modality packages for rubber-tired gantry cranes. The convergence is compressing single-technology vendor margins while elevating systems houses with calibration expertise across sensor types.
EU machinery safety directives under CE marking frameworks are tightening operator visibility requirements through pending amendments to the machinery regulation. Crane OEMs in Finland and Germany are pre-certifying integrated sensor suites to accelerate customer compliance timelines. Tower crane installations across France and Spain are experiencing procurement delays as contractors await clarified certification pathways.
Buying committees are consolidating sensor procurement decisions within fleet management departments rather than delegating to site supervisors. Equipment rental chains in Texas and Alberta are centralizing collision avoidance specification across their crane portfolios. This concentration is visible most acutely in North American oilfield services, where standardized fleet configurations reduce training and maintenance complexity.
Crane Collision Avoidance Devices Market Segmentation
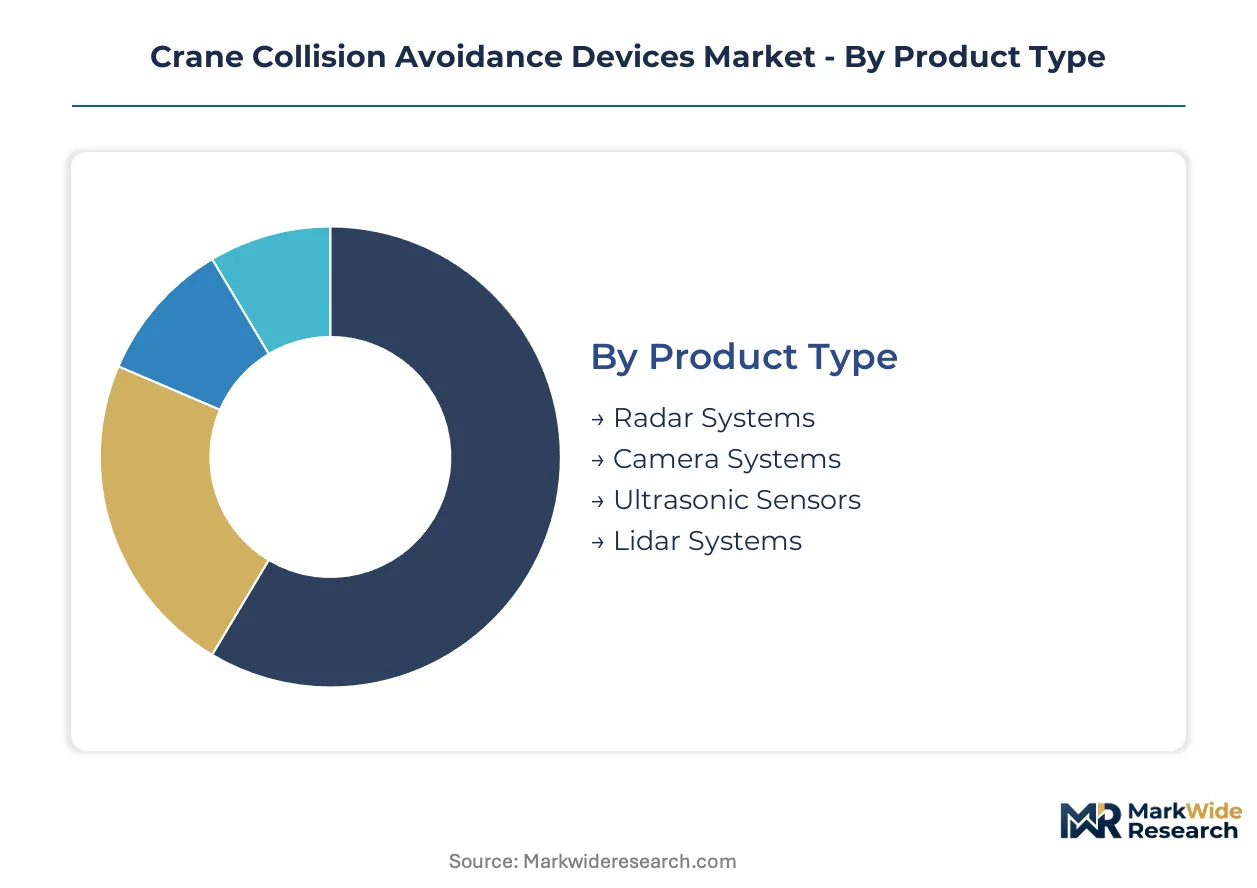
Crane collision avoidance devices fragment across sensor modalities, system architectures, and procurement channels. Each axis carries distinct margin profiles and regulatory compliance requirements that shape supplier strategy.
Product Type:
Sensor modality determines performance envelope in atmospheric conditions and installation cost structure.
- Radar Systems:Electromagnetic wave emission and echo detection operate reliably through salt spray, dust, and precipitation. Port operators in Singapore and Rotterdam specify radar as default for rubber-tired gantry cranes where optical degradation is constant.
- Lidar Systems:Point-cloud generation delivers millimeter-scale spatial resolution for precision load positioning. Construction firms in Germany and Japan are specifying lidar for tower crane installations in dense urban envelopes where margin for error is minimal.
- Camera Systems:Optical imaging with machine vision processing requires clear sight lines and supplemental lighting. Demand concentrates in indoor manufacturing environments.
- Ultrasonic Sensors:High-frequency acoustic ranging provides short-range precision at lower unit cost. Frequently bundled as secondary confirmation layer in hybrid architectures.
Radar Systems leads on scale; Lidar Systems leads on momentum.
Technology:
System architecture determines intervention depth from warning to automatic motion cessation.
- Active Systems:Sensor arrays trigger automatic braking or boom arrest when thresholds breach, eliminating operator response latency. EU machinery safety directives under CE marking frameworks are mandating active intervention for cranes above specified load thresholds.
- Hybrid Systems:Redundant sensor modalities with failover logic satisfy fail-operational requirements in port automation. Terminal operators in Hamburg and Los Angeles specify hybrid packages for autonomous crane retrofits.
- Passive Systems:Audible and visual alarms depend on operator response without automatic intervention. Retains share in legacy fleet retrofits where control system integration is cost-prohibitive.
- Wireless Systems:Radio-frequency proximity detection between crane structures and personnel tags. Emerging specification for construction sites with high transient worker density.
Active Systems dominates procurement volume; Hybrid Systems is climbing the fastest as redundancy mandates spread.
Application:
Operating environment dictates sensor specification and maintenance regime intensity.
- Construction:Tower and mobile cranes in urban sites require 360-degree coverage with high spatial resolution. China's SAMR enforcement of GB standards for construction machinery safety is embedding anti-collision as design prerequisite.
- Shipping:Maritime container handling demands corrosion-resistant electromagnetic systems. Port automation investments in Singapore and Rotterdam bundle collision avoidance with remote operator platforms.
- Manufacturing:Indoor overhead cranes operate in controlled atmospheres favoring optical and ultrasonic modalities. Automotive and aerospace plants specify integration with facility safety management systems.
- Mining:Extreme dust and vibration environments degrade sensor reliability. Australian and Chilean open-pit operators prioritize ruggedized radar with extended calibration intervals.
Construction leads on scale; Shipping leads on momentum through port automation acceleration.
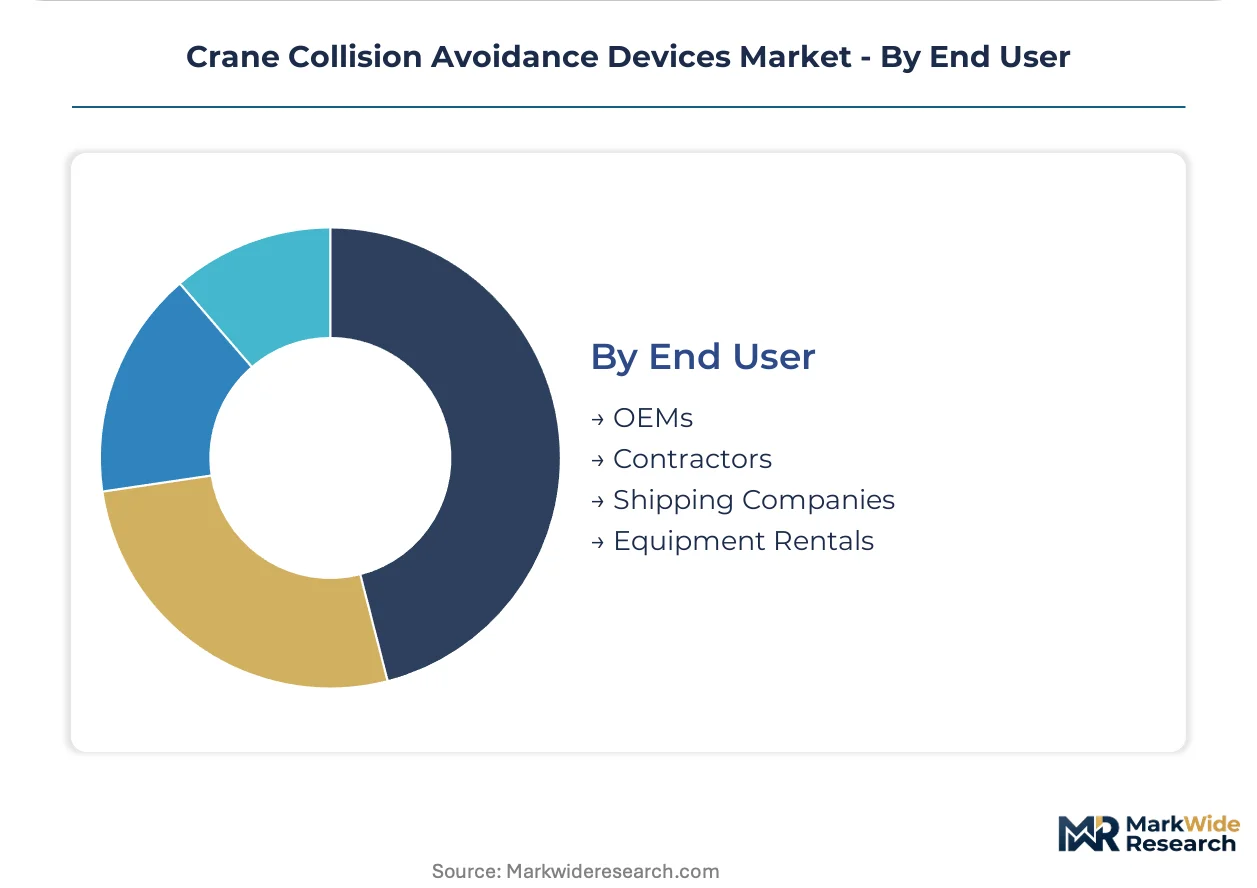
End User:
Procurement authority is shifting from site-level discretion to fleet-wide standardization.
- OEMs:Factory-fit integration during crane assembly compresses aftermarket retrofit opportunity. Sany and Konecranes embed sensor suites as standard configuration, capturing procurement margin previously available to standalone vendors.
- Contractors:General contractors face OSHA visibility mandates for cranes exceeding load thresholds. US construction firms in Texas and Alberta are centralizing specification across project portfolios.
- Shipping Companies:Container terminal operators specify collision-avoidance-to-remote-control integration as unified procurement package. Buying committees consolidate decisions within fleet management departments.
- Equipment Rentals:Rental chains standardize configurations to reduce training and maintenance complexity. North American oilfield services firms drive fleet harmonization across crane categories.
OEMs leads on scale; Equipment Rentals leads on momentum as rental penetration rises in emerging markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is shifting collision avoidance device production toward jurisdictions with streamlined machinery certification pathways. Chinese and South Korean foundries supply processing chipsets at lower compliance cost than European analogs, drawing final assembly capacity eastward despite end-market concentration in Western construction and port automation.
China
Domestic crane OEMs embed anti-collision sensor suites as factory-standard configuration on tower and mobile crane models. SAMR enforcement of GB standards for construction machinery safety mandates anti-collision functionality as a design prerequisite. Manufacturing clusters in Changsha and Xuzhou integrate radar and ultrasonic packages during original assembly, compressing aftermarket retrofit opportunity.
Germany
CE marking frameworks under pending machinery regulation amendments mandate redundant sensing modalities for cranes above specified load thresholds. Tower crane installations across Bavaria and North Rhine-Westphalia experience procurement delays as contractors await clarified certification pathways. German systems integrators concentrate calibration expertise for multi-sensor fusion architectures.
United States
OSHA visibility mandates for cranes exceeding load thresholds stimulate sensor procurement from general contractors and rental fleet operators. Equipment rental chains in Texas and Alberta centralize collision avoidance specification across crane portfolios. Oilfield services firms drive fleet harmonization to reduce training complexity.
Singapore
Container terminal operators specify collision-avoidance-to-remote-control integration as unified procurement package. Port automation investments bundle hardware with software control layers for rubber-tired gantry cranes. Maritime atmospheric conditions position electromagnetic wave systems as default specification.
India
National highway and metro construction projects specify tower cranes with anti-collision functionality for the first time. Central Public Works Department guidelines reference operator visibility assistance for urban infrastructure sites. Demand concentrates in Maharashtra and Gujarat where contractor fleets modernize.
Crane Collision Avoidance Devices Market Competitive Landscape
Chinese producers anchor the factory-integration tier; European specialists hold the calibration-intensive retrofit segment. Market structure bifurcates between OEM-embedded systems houses and standalone device vendors serving legacy fleets. Three archetypes dominate: integrated safety electronics suppliers, multi-sensor systems integrators, and port automation technology bundlers. Competitive moves concentrate on strategic partnerships with crane OEMs and geographic expansion through distributor networks.
Among Chinese fabricators, Sany and XCMG represent the factory-standard integration archetype, embedding sensor suites during crane assembly to capture procurement margin. Konecranes occupies a position exemplifying the port automation bundler model, where collision avoidance merges with remote operator platforms. Liebherr anchors the specialized calibration tier, serving heavy-lift crawler cranes in confined construction environments.
| Leading Market Players |
|---|
| Sany |
| Konecranes |
| Terex Corporation |
| Hyster-Yale |
| Cargotec (Kalmar) |
| Liebherr |
| Zoomlion |
| Manitex |
| XCMG |
| Others |
Pricing and Supply Chain Analysis
Captive sensor production by Chinese crane OEMs anchors both supply security and pricing power in the collision avoidance devices market. Sany and XCMG leverage in-house radar and ultrasonic assembly lines in Changsha and Xuzhou to compress procurement costs for factory-fit integration, while European systems integrators absorb premium pricing for calibration-intensive retrofit installations.
Pricing Analysis
Distributor margins in the aftermarket retrofit channel range from 15 to 25 percent, whereas direct-to-OEM supply agreements carry volume-scaled discounts that eliminate intermediary markups. Three-tier pricing structure across premium, standard, and economy levels separates CE-certified multi-sensor fusion systems from basic ultrasonic alarm units. Cost compression in the standard tier is intensifying because Chinese fabricators are bundling safety electronics as factory-standard configuration. Equipment rental chains in Texas and Alberta demonstrate the least price sensitivity due to fleet harmonization mandates, while independent contractors in India exhibit acute cost consciousness on first-time anti-collision procurements.
Supply Chain Analysis
Semiconductor processing units draw from Taiwan and South Korean foundries, with radar chipsets and lidar photodetectors resting on Japanese specialty component producers. Raw material dependencies span gallium arsenide substrates, MEMS acoustic transducers, and automotive-grade microcontroller units. Single-source vulnerability concentrates in Taiwan's advanced node fabrication capacity, where geopolitical friction threatens lead time predictability for device assemblers. Distribution runs through crane OEM captive supply agreements in China, systems integrator direct sales in Germany, and rental fleet procurement consortia in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on the shift from discrete device sales to integrated software-hardware bundles, where recurring calibration service contracts offset upfront sensor commoditization.
For Market Incumbents: To counter factory-fit integration by Chinese crane OEMs, European specialists must deepen calibration service revenue streams and secure exclusive port automation partnerships in Singapore and Rotterdam. Capacity addition in Germany for multi-sensor fusion field engineering preserves premium positioning against commoditized radar packages. Certification investment in pending CE marking amendments accelerates compliance timelines for contractor customers awaiting clarified pathways. For New Entrants and Emerging Players: Lidar point-cloud analytics software represents the most penetrable white-space target, enabling convergence with building information modeling workflows for construction firms in Germany and Japan. India's virgin infrastructure procurement offers geographic entry through tower crane anti-collision specifications on national highway and metro projects. A technology-first go-to-market angle positions sensor-data licensing as a recurring revenue layer distinct from hardware margins. For Investors and Strategic Acquirers: Roll-up economics work for multi-sensor systems integrators because calibration expertise scarcity in Germany and Japan creates defendable local moats. The five-to-ten year viability window favors acquisition targets with established port automation bundler relationships and proprietary sensor fusion algorithms. Watch for OSHA enforcement intensity on visibility mandates as the inflection indicator signaling aftermarket retrofit demand durability.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Sensor Fusion Platform Development | CE marking amendments in Germany mandate redundant sensing modalities for crane safety compliance. |
| Port Automation Technology Bundling | Singapore terminal operators specify collision avoidance integrated with remote operator control systems. |
| Calibration Service Network Expansion | Scarcity of field technicians in India and China constrains deployment velocity for hybrid architectures. |
| Backward Integration into Radar Chipsets | Taiwan foundry concentration risk incentivizes captive semiconductor supply for Chinese OEMs. |
| Building Information Modeling Data Licensing | German construction firms leverage crane-mounted lidar point-clouds for project management workflows. |
Research Methodology
Coverage spans China, Germany, the United States, Singapore, and India, with primary inputs from each market informing demand calibration. The research combines structured interviews with crane OEM procurement directors, port terminal operations managers, construction fleet supervisors, and aftermarket service technicians with secondary validation through SAMR GB standard filings, OSHA directive documentation, EU machinery regulation amendment drafts, and customs trade data on sensor component flows. Bottom-up equipment installation tracking and top-down regulatory mandate sizing were triangulated to anchor volume estimates.
Granularity-level modeling disaggregated the market across sensor modality, system architecture, application environment, and procurement channel dimensions. Deployment patterns across the projection horizon were projected using equipment replacement cycles, regulatory compliance deadlines, and port automation investment pipelines. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Industry-specific forecast inputs included crane OEM factory-fit penetration rates and rental fleet standardization timelines.
The model holds under stable regulatory enforcement trajectories; deviation in OSHA inspection intensity or EU CE marking implementation delays would shift aftermarket retrofit timing. Semiconductor supply normalization assumptions underpin sensor cost curves; persistent Taiwan foundry constraints would compress margin structures. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive Intelligent Headlight System Market
Automotive Safety and Security Systems
Automotive ABS and ESC Market
Automotive Safety and Security Systems
Automatic Emergency Braking Market
Automotive Safety and Security Systems
Emergency Vehicle Lights Market
Automotive Safety and Security Systems
Driving Armor Market
Automotive Safety and Security Systems
Highway Crash Cushion Market
Automotive Safety and Security Systems
Adaptive Front Lighting Market
Automotive Safety and Security Systems
Automotive Speed Alert System Market
Automotive Safety and Security Systems
Automotive Brake Actuation Systems Market
Automotive Safety and Security Systems
Automotive Anti Lock Braking System and Electronic Stability Control Market
Automotive Safety and Security Systems
Automotive Seat Belt System Market
Automotive Safety and Security Systems
Automatic Emergency Braking System (AEBS) Market
Automotive Safety and Security Systems
Smart Motorcycle Helmet Market
Automotive Safety and Security Systems
Automotive Perimeter Lighting System Market
Automotive Safety and Security Systems
Automotive Driver Drowsiness Detection System Market
Automotive Safety and Security Systems
Automotive Adaptive Lighting System Market