
 Start Stop System Market | 2026-2036
Start Stop System Market Size, Share, and Industry Trends Forecast 2026-2036
Start Stop System Market Analytics
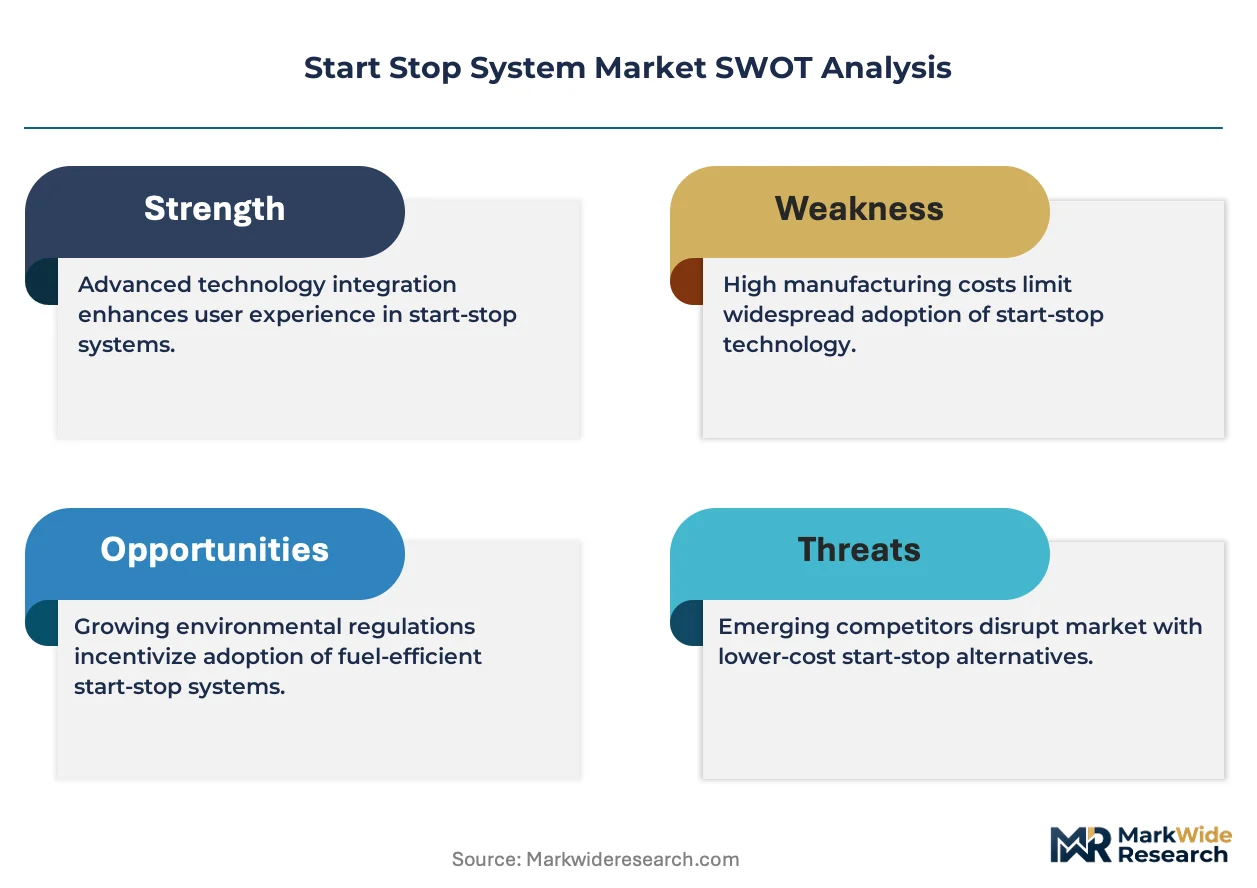
Enhanced cycle durability specifications for starter motors and battery management modules is redrawing competitive requirements across the supply base. Robert Bosch GmbH leverages its integrated powertrain electronics portfolio to anchor intelligent system deployments for European OEM platforms. Continental AG competes through specialized 48-volt mild-hybrid architectures that extend start-stop functionality into higher vehicle segments. Denso Corporation dominates thermal-integrated control strategies for gasoline direct-injection engines across Japanese and North American assembly lines.
A start-stop system automatically shuts down and restarts a vehicle's internal combustion engine to eliminate idle fuel consumption and exhaust emissions, typically employing reinforced starter motors, absorbent glass mat batteries, and crankshaft position sensors with sub-400 millisecond restart latency. The technology serves primarily to reduce urban driving cycle emissions and comply with fleet-average CO2 mandates without full powertrain electrification. Intelligent systems lead product type segmentation by value due to integrated predictive algorithms and navigation-linked engine-off timing, while micro hybrid systems represent the fastest-expanding category as automakers embed 48-volt electrical architectures into mainstream vehicle lines. OEM end users capture the dominant share of volume through platform-level integration at the design phase, though aftermarket providers are gaining ground in retrofit programs for aging commercial fleets across emission-restricted urban zones.
The EPA Corporate Average Fuel Economy standards and NHTSA safety protocols shape US market access requirements for start-stop system durability and restart reliability under varying thermal conditions. EMA and ECHA frameworks in Europe enforce chemical substance restrictions in battery components while the EU Green Deal's fleet CO2 targets directly mandate technology penetration rates across new vehicle registrations. China's MIIT and SAMR coordinate GB standards for electromagnetic compatibility and dual carbon implementation timelines that determine product certification pathways. Stakeholders must monitor regulatory calibration between emission reduction mandates and battery recycling accountability rules as the primary determinant of technology configuration choices and geographic manufacturing placement.
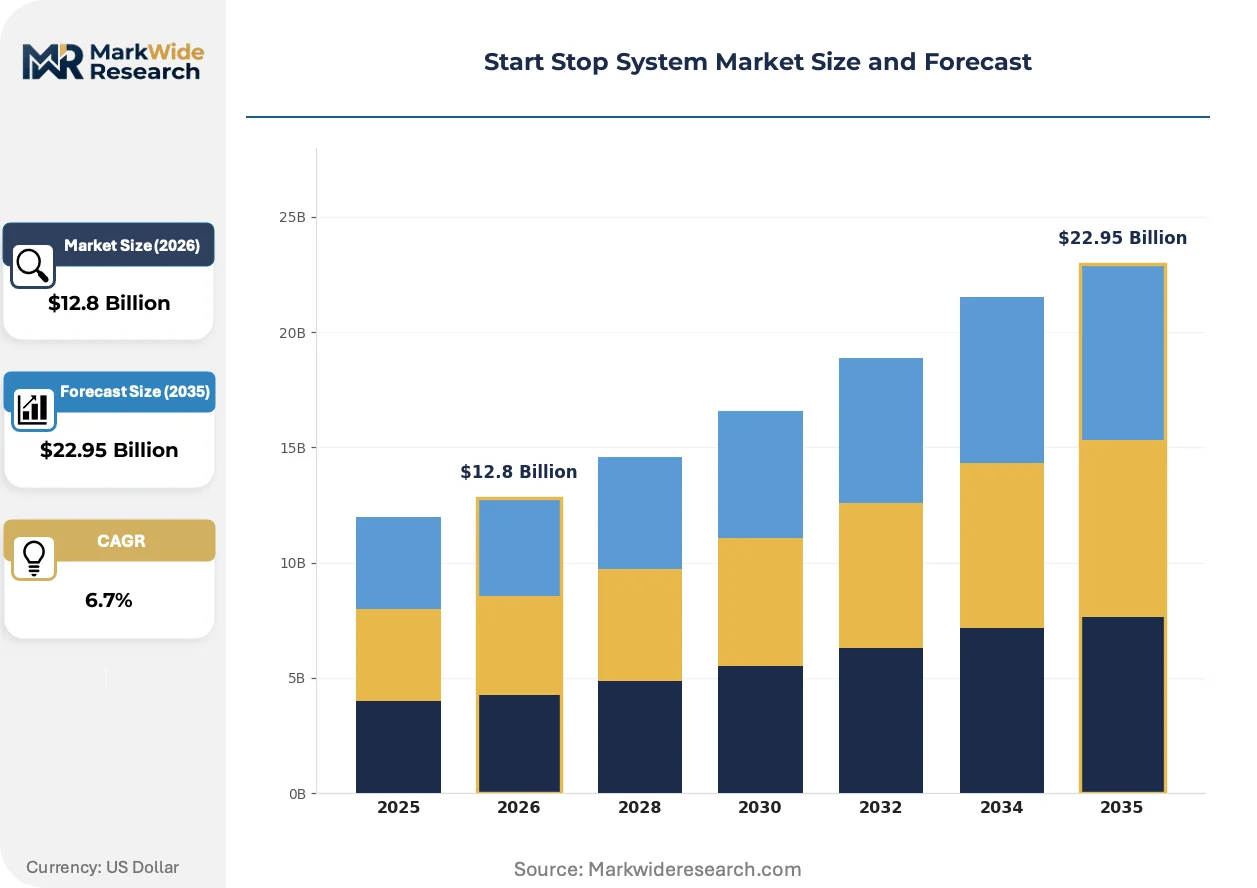
Market Dynamics
CO2 fleet emission mandates across Germany, Japan, and China are forcing powertrain electrification strategies that embed start-stop architectures as compliance baselines before full hybridization. OEM engineering budgets are rebalancing toward 48-volt electrical systems that extend idle-stop functionality into premium vehicle segments.
Growth Catalysts
- EU Green Deal protocols:Fleet CO2 reduction targets for 2030 are mandating technology penetration rates that push start-stop systems from optional equipment to standard fitment across German OEM platforms.
- China's dual carbon goals:MIIT implementation timelines for GB standards on electromagnetic compatibility are accelerating domestic certification of intelligent start-stop modules for gasoline direct-injection engines.
- Urban emission-restricted zones:Municipal access rules in Tokyo, London, and Paris are creating retrofit demand from aging commercial fleets seeking compliance without full powertrain replacement.
Market Restraints
- Absorbent glass mat battery cost volatility:Lead price fluctuations and sulfuric acid supply constraints are compressing margins for battery management module suppliers serving volume OEM contracts.
- Starter motor supply concentration:Precision component manufacturing for reinforced starter motors remains concentrated in Japan's Aichi and Shizuoka prefectures, exposing buyers to single-source risk.
- Technical limitation in restart latency:Sub-400 millisecond restart specifications for crankshaft position sensors face thermal degradation thresholds that limit deployment in extreme climate zones.
Strategic Opportunities
- India's BIS certification pathway:PLI scheme incentives for automotive component manufacturing are opening local production opportunities for 48-volt mild-hybrid architectures previously imported from European suppliers.
- Navigation-linked predictive algorithms:Convergence of GPS traffic data with engine-off timing logic is creating intelligent system differentiation in German premium vehicle segments.
- Brazil's ANVISA-aligned commercial fleet renewal:Urban emission enforcement in São Paulo and Rio de Janeiro is generating aftermarket retrofit channel growth for aging delivery vehicle populations.
Industry Challenges
- Power electronics integration complexity:Combining 48-volt architectures with legacy 12-volt electrical systems requires specialized calibration expertise scarce in mainstream Tier-2 supplier engineering teams.
- EMA chemical substance compliance timelines:Battery component restrictions under evolving ECHA frameworks are extending product recertification cycles and freezing platform approvals during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Start Stop System Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional Systems, Intelligent Systems, Hybrid Systems, Micro Hybrid Systems End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Technology: Automatic Start Stop, Manual Start Stop, Advanced Start Stop, Eco Start Stop Fuel Type: Gasoline, Diesel, Electric, Hybrid |
| Companies Covered | Robert Bosch GmbH, Continental AG, Denso Corporation, BorgWarner Inc., Valeo, Hitachi Automotive, Johnson Controls Inc., Schaeffler Technologies AG & Co. KG, Marelli Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Start Stop System Market Evolving Landscape
Predictive engine management algorithms are reshaping competitive differentiation by shifting value from hardware durability to software-defined restart timing. Thermal-integrated control strategies are converging with powertrain electronics in ways that redefine supplier capability requirements.
Silicon carbide power semiconductors are replacing traditional silicon MOSFETs in 48-volt DC-DC converters, enabling higher switching frequencies that reduce converter size and weight. German OEMs are adopting these modules for next-generation mild-hybrid platforms launching across C-segment and D-segment vehicle lines. This semiconductor transition is displacing incumbent converter suppliers lacking wide-bandgap fabrication partnerships or thermal packaging expertise.
EPA Corporate Average Fuel Economy standards are tightening durability testing protocols for start-stop systems under varying thermal cycling conditions, forcing suppliers to redesign validation procedures. NHTSA safety protocols now mandate restart reliability demonstrations across temperature extremes from -40°C to 85°C ambient. US-based OEM engineering teams are responding by extending platform development timelines and increasing prototype testing budgets for thermal stress validation.
Fleet procurement managers are unbundling after-sales service contracts from initial system supply agreements, creating separate competitive arenas for hardware supply versus predictive maintenance software subscriptions. This purchasing pattern change is disrupting traditional Tier-1 supplier relationships that bundled both elements. The shift is most visible in North American commercial fleet segments where total cost of ownership modeling now separates capital expenditure from operational technology management spend.
Start Stop System Market Segmentation
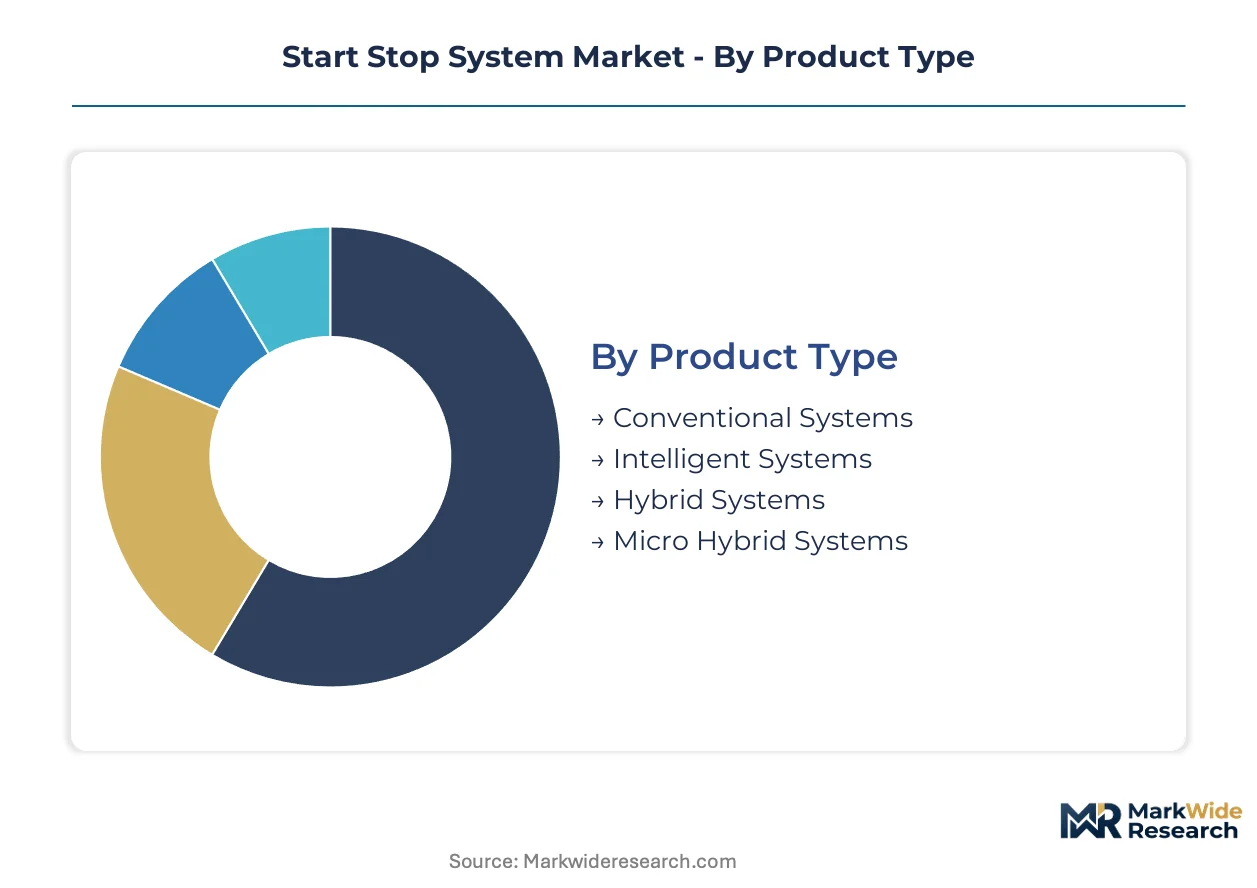
Start-stop system configuration varies sharply across deployment contexts. Regulatory pressure on CO2 emissions and restart latency specifications create divergent technology requirements between mass-market platforms and premium vehicle architectures.
Product Type:
EU Green Deal fleet mandates and China's GB standards on electromagnetic compatibility differentiate certification pathways by system intelligence level, with predictive algorithms facing stricter validation protocols than conventional idle-stop modules.
- Intelligent Systems:Integrated predictive algorithms and navigation-linked engine-off timing define these configurations. German OEM platforms in Stuttgart and Munich anchor demand as premium vehicle segments pursue CO2 compliance without full electrification. EU Green Deal protocols mandate these systems for fleet-average calculations.
- Micro Hybrid Systems:These 48-volt electrical architectures embed start-stop functionality into mainstream vehicle lines. Japanese precision component manufacturers in Aichi Prefecture supply reinforced starter motors and DC-DC converters. China's MIIT certification timelines accelerate domestic adoption for gasoline direct-injection engines.
- Conventional Systems:Basic idle-stop modules with reinforced starter motors and absorbent glass mat batteries serve entry vehicle segments in emission-restricted urban zones.
- Hybrid Systems:Integrated configurations combining start-stop with mild-hybrid energy recovery appear in C-segment and D-segment platforms from German and Japanese OEMs.
Intelligent Systems handle the majority of throughput; Micro Hybrid Systems are expanding most quickly on share.
End User:
Cost tier differentiation separates platform-level integration from retrofit deployment, with capital expenditure requirements varying by order magnitude between factory-fit programs and aftermarket channel provisioning.
- OEMs:Platform-level integration at the design phase captures dominant volume. Engineering budgets for 48-volt electrical systems flow through German and Japanese passenger vehicle manufacturers. EPA Corporate Average Fuel Economy standards and NHTSA safety protocols govern US market access requirements.
- Aftermarket Providers:Retrofit programs for aging commercial fleets concentrate in emission-restricted urban zones including Tokyo, London, and Paris. Municipal access rules drive demand without full powertrain replacement.
- Tier-1 Suppliers:Specialized component manufacturing for battery management modules and crankshaft position sensors serves volume OEM contracts.
- Vehicle Assemblers:Contract manufacturing arrangements integrate start-stop modules during final assembly for regional market variants.
OEMs capture the dominant revenue position; Aftermarket Providers are climbing the fastest on volume contribution.
Technology:
Application context determines restart latency specifications, with automatic configurations facing stricter thermal cycling validation than manual alternatives under EPA durability testing protocols.
- Automatic Start Stop:Sub-400 millisecond restart latency specifications employ crankshaft position sensors with thermal degradation thresholds. NHTSA protocols mandate reliability demonstrations from -40°C to 85°C ambient across US market deployments.
- Advanced Start Stop:Predictive algorithms converge GPS traffic data with engine-off timing logic. German premium vehicle segments differentiate through software-defined restart timing rather than hardware durability alone.
- Manual Start Stop:Driver-activated systems serve cost-sensitive vehicle segments with simplified electrical architectures.
- Eco Start Stop:Optimized configurations for urban driving cycles prioritize emission reduction in stop-and-go traffic conditions.
Automatic Start Stop anchors current deployment volumes; Advanced Start Stop shows the steepest expansion trajectory.
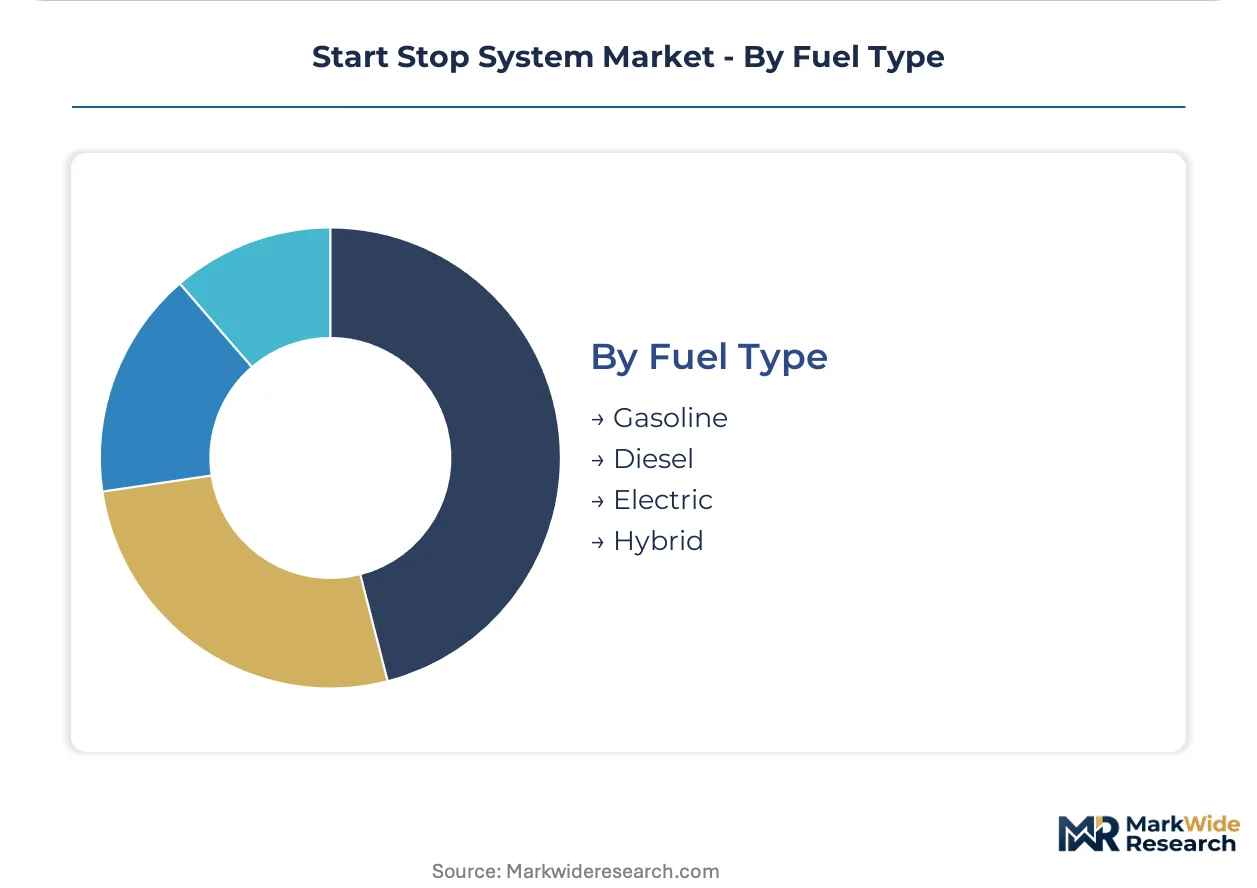
Fuel Type:
Supply concentration for gasoline direct-injection engines in Japan's manufacturing corridors contrasts with diesel system deployment in German commercial vehicle platforms.
- Gasoline:Thermal-integrated control strategies from Denso Corporation dominate Japanese and North American assembly lines. China's dual carbon goals accelerate domestic certification of intelligent start-stop modules for this fuel category.
- Hybrid:Dual-powertrain configurations embed start-stop as baseline compliance architecture before full electrification. 48-volt mild-hybrid systems from Continental AG extend functionality into premium segments.
- Diesel:Heavy-duty commercial applications in Germany's automotive engineering corridor face tightening CO2 fleet emission rules under EU Green Deal protocols.
- Electric:Start-stop functionality integrates with range-extender architectures in transitional powertrain configurations.
Gasoline handles the majority of current installations; Hybrid is gaining share fastest as electrification strategies mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German OEM engineering corridors export 48-volt mild-hybrid architectures to Japanese precision component manufacturers, creating a transcontinental supply loop that concentrates advanced start-stop system deployment across three continents.
Germany
Stuttgart and Munich anchor OEM platform engineering for intelligent start-stop modules with predictive algorithms. EU Green Deal fleet CO2 mandates under KBA enforcement push technology from optional equipment to standard fitment. The Baden-Württemberg automotive corridor concentrates Continental AG's specialized 48-volt architecture production for premium C-segment and D-segment vehicles.
Japan
Aichi and Shizuoka prefectures host precision manufacturing clusters for reinforced starter motors and crankshaft position sensors. METI coordinates JIS standards validation for sub-400 millisecond restart latency specifications. Denso Corporation dominates thermal-integrated control strategies for gasoline direct-injection engines across Nagoya-area assembly lines serving North American export markets.
China
MIIT implementation timelines for GB standards on electromagnetic compatibility accelerate domestic certification of intelligent start-stop modules. Dual carbon goals under SAMR coordination mandate technology penetration across gasoline direct-injection engine platforms. Yangtze River Delta manufacturing zones concentrate battery management module production for volume OEM contracts.
United States
EPA Corporate Average Fuel Economy standards and NHTSA safety protocols govern market access requirements for thermal cycling durability. Detroit-area OEM engineering teams extend platform development timelines for restart reliability demonstrations from -40°C to 85°C ambient. Midwest automotive corridors integrate start-stop modules during final assembly for regional market variants.
India
PLI scheme incentives for automotive component manufacturing open local production opportunities for 48-volt mild-hybrid architectures. BIS certification pathways streamline domestic validation previously requiring European import dependency. Maharashtra and Gujarat industrial corridors attract tier-1 suppliers establishing battery management module fabrication for domestic OEM platform integration.
Start Stop System Market Competitive Landscape
Listed leaders compete with private specialists across technology integration depth, creating a tiered structure where scale-driven conglomerates face focused component architects. The vendor base clusters around three strategic archetypes: integrated powertrain electronics generalists, 48-volt mild-hybrid specialists, and thermal-integrated control strategists. Dominant competitive moves include backward integration into semiconductor sourcing and geographic expansion through regional certification partnerships.
Within the integrated powertrain tier, Robert Bosch GmbH and Continental AG exemplify divergent approaches to system intelligence. Denso Corporation anchors the thermal-integrated specialist position. These three entities occupy distinct competitive spaces defined by their geographic origins and organizational structures rather than convergent product strategies.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| Denso Corporation |
| BorgWarner Inc. |
| Valeo |
| Hitachi Automotive |
| Johnson Controls Inc. |
| Schaeffler Technologies AG & Co. KG |
| Marelli Corporation |
| Others |
Value Network & Pricing Analysis
Silicon carbide power semiconductors displacing traditional silicon MOSFETs in 48-volt DC-DC converters simultaneously redraws supply geography toward wide-bandgap fabrication centers in Germany and Japan while compressing converter pricing economics through higher switching frequency efficiency gains. This substitution dynamic concentrates pricing power with semiconductor suppliers possessing thermal packaging expertise while forcing incumbent converter vendors into cost restructuring or partnership arrangements.
Pricing Analysis
The technology-generation pricing gap separating conventional 12-volt idle-stop modules from 48-volt mild-hybrid architectures and emerging intelligent predictive systems structures market transactions. Contract-based long-term offtake agreements dominate volume OEM procurement, with price differentiation anchored in certification grade under EPA thermal cycling protocols and volume scale commitments. Cost compression in conventional AGM battery tiers intensifies because lead price volatility and sulfuric acid supply constraints squeeze Tier-2 supplier margins. Aftermarket retrofit providers exhibit highest price sensitivity due to municipal fleet budget constraints, while German premium OEM platforms demonstrate lowest sensitivity when pursuing CO2 compliance without full electrification.
Supply Chain Analysis
Just-in-time inventory strategies prevail among Japanese precision component manufacturers in Aichi and Shizuoka prefectures, while European OEMs maintain strategic stockpiles of wide-bandgap semiconductors to mitigate fabrication lead time exposure. Geographic supply concentration centers on Germany for 48-volt system integration, Japan for reinforced starter motors and crankshaft position sensors, and China for battery management module production. Raw material dependencies encompass lead for AGM batteries, silicon carbide substrates for next-generation converters, and precision-machined steel for starter motor components. Single-source vulnerability in Japanese starter motor manufacturing creates structural risk for buyers lacking qualified secondary suppliers. Distribution runs through Tier-1 supplier direct-to-OEM channels for factory fitment and specialized aftermarket distributors for commercial fleet retrofit programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Start Stop System Market sits in a cyclical recovery phase driven by EU Green Deal fleet CO2 mandates forcing technology penetration from optional equipment to standard fitment across German OEM platforms.
For Market Incumbents: Secure backward integration into silicon carbide semiconductor sourcing to defend converter margins against wide-bandgap fabrication specialists. Anchor platform engineering relationships with Stuttgart and Munich OEM teams through predictive algorithm development investments that raise switching costs for substitute suppliers. For New Entrants and Emerging Players: BIS certification fast-tracks under India's PLI scheme open white-space opportunities for 48-volt mild-hybrid architectures previously import-dependent on European suppliers. Target Maharashtra and Gujarat industrial corridors for battery management module fabrication serving domestic OEM platform integration. Pursue joint venture structures with established Tier-2 suppliers to bypass OEM qualification timeline barriers. For Investors and Strategic Acquirers: The market sits at a technology substitution phase that favors semiconductor-thermal packaging specialists over legacy converter vendors. Long-term viability over the next decade rests on positioning upstream of 48-volt architecture proliferation in gasoline direct-injection platforms. Monitor EPA thermal cycling durability test protocol revisions as the primary inflection signal for validation cost escalation favoring scaled testing infrastructure holders.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | German OEMs consolidate 48-volt architectures across C-segment and D-segment vehicle lines to amortize development costs. |
| Battery Supply Agreement | Long-term AGM and lithium-ion cell contracts secure volume pricing for Tier-1 suppliers serving EPA thermal cycling requirements. |
| Software-Defined Vehicle Investment | Predictive algorithm development converges GPS traffic data with engine-off timing logic for premium differentiation. |
| Geographic Manufacturing Footprint | Yangtze River Delta and Maharashtra industrial corridors concentrate production for MIIT and BIS certification compliance. |
| Charging Infrastructure Partnership | 48-volt mild-hybrid system suppliers coordinate with charging network operators on grid-integration standards for transitional electrification architectures. |
Research Methodology
A spread of perspectives from OEM platform engineers, Tier-1 supplier procurement leads, aftermarket fleet managers, and semiconductor fabrication specialists converged on the working assumptions anchoring this analysis. Primary fieldwork combined structured interviews with secondary validation against vehicle production databases, IHS Markit registration data, EPA Corporate Average Fuel Economy filings, and MIIT electromagnetic compatibility certification records. Bottom-up triangulation across component shipment volumes and top-down reconciliation with OEM platform deployment schedules ensured analytical consistency.
Segmentation dimensions modeled encompass product type across intelligent, micro hybrid, conventional, and hybrid system configurations; end user categories spanning OEM factory fitment and aftermarket retrofit channels; technology tiers from automatic to advanced predictive algorithms; and fuel type differentiation between gasoline, hybrid, diesel, and electric range-extender architectures. CAGRs were derived through regression analysis of historical penetration rates against regulatory mandate timelines, with forecast inputs incorporating EU Green Deal fleet CO2 trajectory assumptions and China's dual carbon implementation pace.
Decision-makers should treat outputs as directional under base assumptions of sustained regulatory emission mandate tightening and stable lead price environments; material deviation would warrant model refresh. Revision becomes warranted when EPA thermal cycling protocol amendments or ECHA battery substance restrictions cross implementation thresholds that freeze platform approvals or extend recertification cycles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
LAMEA Hill-Start Assist System Market
Automotive Safety and Security Systems
Vehicle Barrier System Market
Automotive Safety and Security Systems
Automotive Inspection Tunnels Market
Automotive Safety and Security Systems
Automotive Occupant Sensing System Market
Automotive Safety and Security Systems
Automotive Passive Safety System Market
Automotive Safety and Security Systems
Automotive Side Guard Door Beam Market
Automotive Safety and Security Systems
Collision Mitigation Technology Market
Automotive Safety and Security Systems
Automotive Mirror System Market
Automotive Safety and Security Systems
Automotive Pedestrian Protection System Market
Automotive Safety and Security Systems
Automotive Biometric Access System Market
Automotive Safety and Security Systems
Global Automotive Fog Lights Market
Automotive Safety and Security Systems
Global Motorcycle Advanced Driver Assistance System (ADAS) Market
Automotive Safety and Security Systems
Automotive HD/Imaging Radar Market
Automotive Safety and Security Systems
Global Automotive Knee Airbags Market
Automotive Safety and Security Systems
China Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Hill-Start Assist System Market