
 Wearable Motorcycle Airbags Market | 2026-2036
Wearable Motorcycle Airbags Market Size, Share, and Industry Trends Forecast 2026-2036
Wearable Motorcycle Airbags Market Insights
Direct-to-rider digital channels and specialty motorsport retail networks are reshaping how wearable motorcycle airbags reach end users. Alpinestars leverages its racing heritage and technical partnerships with MotoGP teams to sustain premium positioning across European markets. Dainese competes through integrated D-air technology platforms that extend from consumer vests to factory racing suits. In&Motion differentiates by offering subscription-based algorithm updates that improve crash-detection accuracy over time.
Wearable motorcycle airbags are personal protective garments incorporating gas-inflatable bladders, accelerometer-gyroscope sensor arrays, and tethered or wireless trigger mechanisms designed to deploy cushioning around the torso, neck, and spine milliseconds before impact. These systems rely on proprietary crash-detection algorithms and cold-gas inflator technology to reduce traumatic injury severity during high-speed incidents. Inflatable vests lead volume sales among product types due to lower price points and universal fit compatibility, while sensor-based wireless systems capture the fastest growth trajectory as riders abandon mechanical tether systems. Professional riders and racing teams represent the highest-margin end-user segment, with deployment concentrated in track racing applications where FIM and national federation mandates increasingly require airbag integration.
CE marking under the EU Personal Protective Equipment Regulation and France's ANSM oversight of medical-adjacent trauma devices shape certification pathways and market access across Europe. Germany's KBA and Italy's Ministry of Transport enforce type-approval standards that influence product design requirements for road-legal systems. Stakeholders must monitor evolving algorithm liability frameworks and the shift from voluntary adoption to circuit-specific mandates as the primary demand catalysts.
Market Dynamics
The transition from tether-triggered to wireless sensor-based deployment systems is compressing replacement cycles and reshaping supplier value capture across the protective gear value chain.
Growth Catalysts
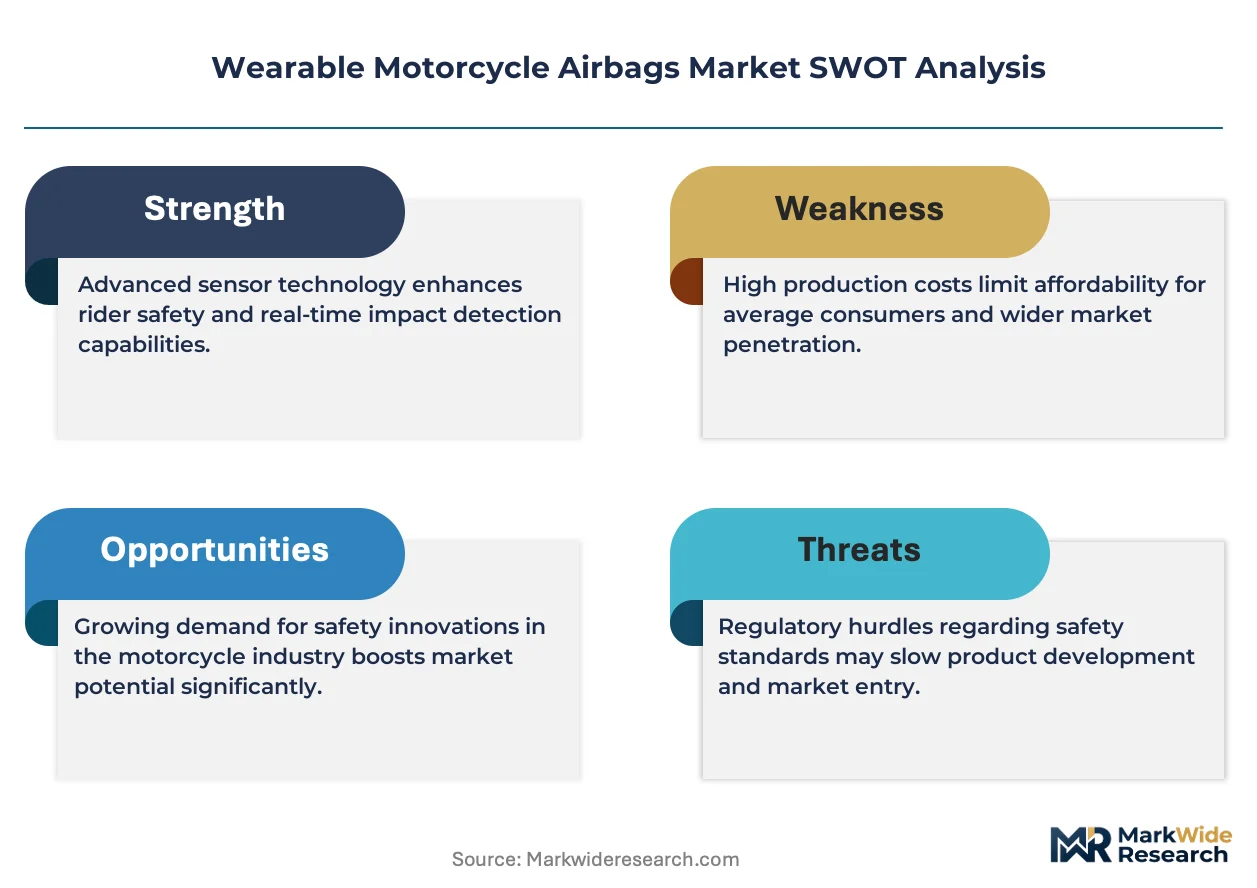
- FIM circuit mandates:International racing federation requirements for airbag integration in premier championships are forcing team procurement upgrades across European tracks.
- CE marking evolution:The EU Personal Protective Equipment Regulation's updated certification pathways are accelerating product standardization and reducing cross-border friction.
- Track-day participation:Germany, France, and Italy are registering sustained growth in amateur racing events where circuit-specific gear rules apply.
Market Restraints
- Helium supply concentration:Cold-gas inflator production depends on concentrated noble gas sourcing from limited geographic suppliers, creating input cost volatility.
- Algorithm liability exposure:Proprietary crash-detection software carries unresolved legal frameworks around false-deployment incidents and injury claims.
- Mechanical tether persistence:Lower-cost mechanical systems retain installed base among price-sensitive touring riders, slowing full wireless transition.
Strategic Opportunities
- Urban commuting expansion:Daily motorcycle commuters in Paris, Milan, and Barcelona represent an underpenetrated segment beyond racing applications.
- Subscription algorithm services:Continuous firmware updates improving crash-detection accuracy are creating recurring revenue models alongside hardware sales.
- Integration with connected vehicles:V2X communication protocols are enabling pre-impact data sharing between motorcycles and infrastructure.
Industry Challenges
- Embedded systems engineering talent:The intersection of garment manufacturing and real-time sensor fusion requires scarce cross-functional expertise.
- Multi-jurisdiction certification timelines:Separate KBA, ANSM, and Ministry of Transport approvals extend product launch schedules across European markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wearable Motorcycle Airbags Market |
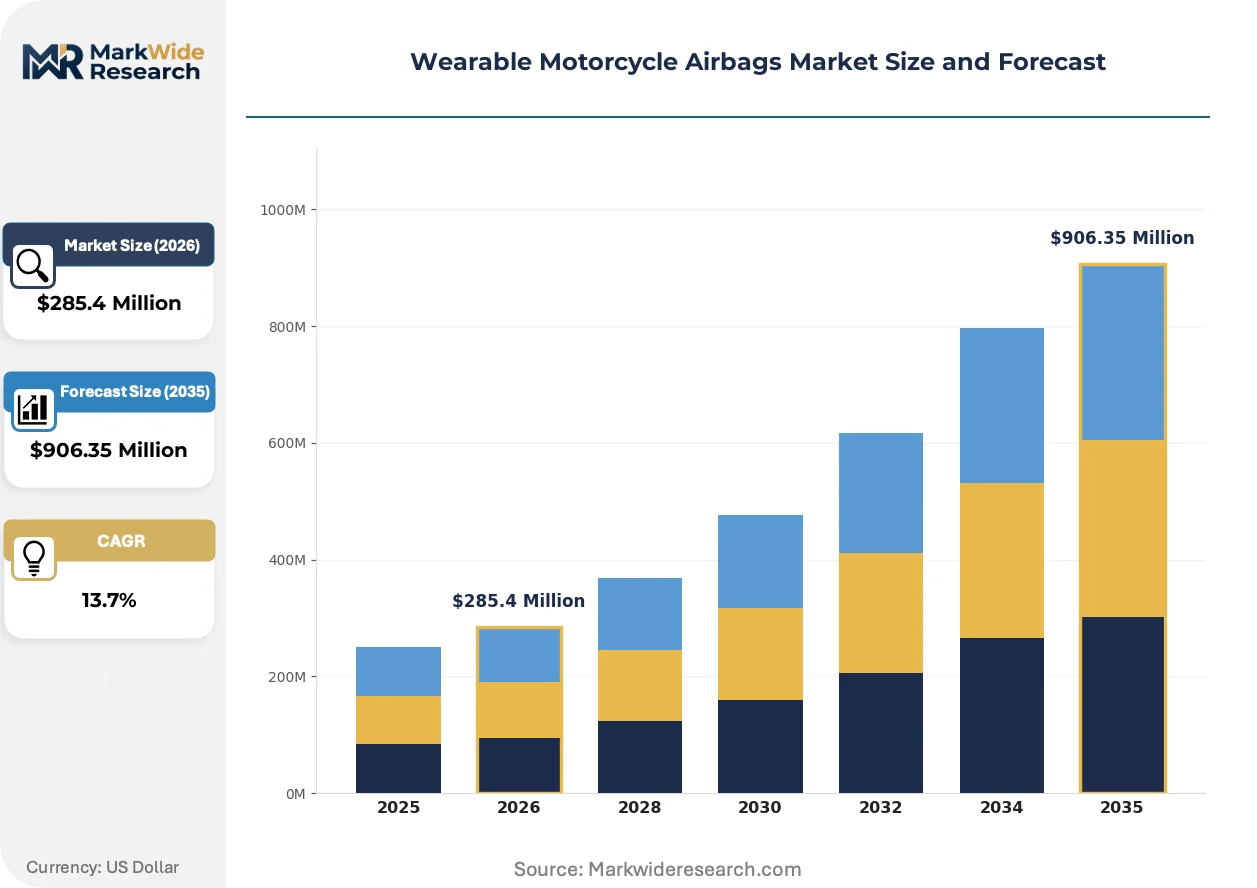
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $906.35 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inflatable Vests, Jackets, Harnesses, Trousers Technology: Wireless Systems, Sensor-Based, Manual Activation, Automated Deployment End User: Professional Riders, Casual Riders, Racing Teams, Riding Schools Deployment Type: On-Road, Off-Road, Track Racing, Urban Commuting |
| Companies Covered | Hit-Air, MotoAirBag, Alpinestars, Bering, OMNIOF, Dainese, In&Motion, Ixon, Helite, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wearable Motorcycle Airbags Market Trends and Innovations
Sensor fusion architectures and algorithmic refinement are compressing deployment latency while expanding addressable rider segments beyond traditional racing applications.
Multi-axis inertial measurement units combined with machine-learning classification are hybridizing crash-detection capabilities. Professional racing teams are adopting these systems fastest, with factory squads replacing legacy tether configurations between seasons. This convergence is hybridizing supplier competencies, forcing textile manufacturers to acquire embedded systems capabilities or cede margin to technology specialists.
France's ANSM oversight of medical-adjacent trauma devices is tightening documentation requirements for injury-mitigation claims. Manufacturers must now submit clinical validation data alongside mechanical testing. Racing suit suppliers targeting the French market are restructuring quality assurance departments to manage parallel technical and medical dossiers.
Direct-to-rider digital channels are fragmenting traditional specialty retail dominance. Younger track-day participants in Germany and Italy are purchasing through manufacturer apps and configuring fit remotely. This disintermediation is compressing distributor margins and shifting service responsibilities to brand-owned logistics networks.
Wearable Motorcycle Airbags Market Segmentation
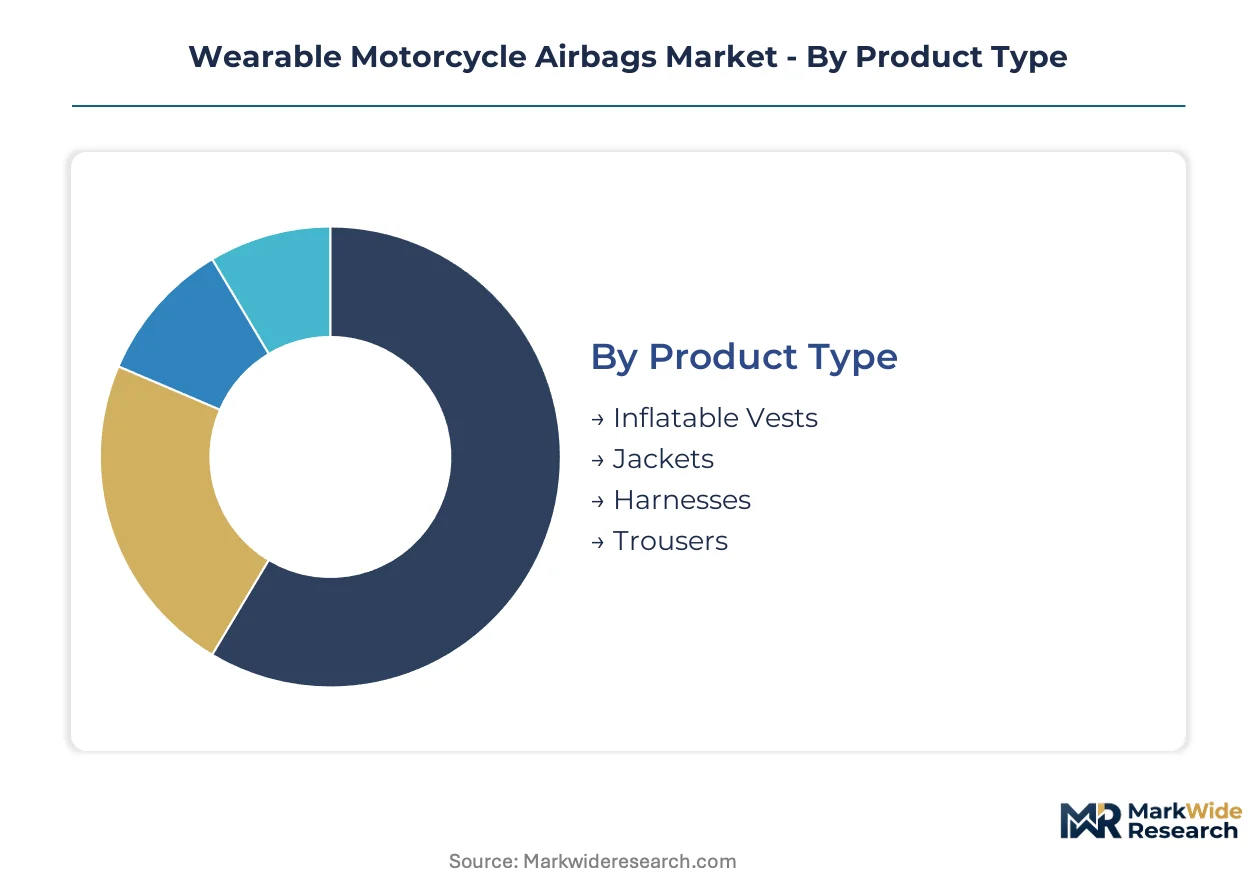
Wearable motorcycle airbags fragment across four critical dimensions: garment configuration, trigger mechanism sophistication, rider risk profile, and operational environment. Each axis reveals distinct margin structures and certification requirements that reshape supplier priorities across European markets.
Product Type:
The use-case spectrum spans daily commuting protection to full-body racing coverage, with garment architecture dictating both sensor integration complexity and replacement economics.
- Inflatable Vests:Sleeveless designs incorporating torso-focused airbag bladders with universal fit systems. Demand concentrates among amateur track-day participants in Germany and Italy where circuit mandates require airbag coverage without full-suit investment.
- Jackets:Integrated outerwear combining abrasion-resistant textiles with embedded inflation systems and shoulder-elbow armor. Professional riders and racing teams in France drive premium procurement as ANSM documentation requirements favor medically-validated trauma mitigation systems.
- Harnesses:Modular torso-only systems worn over existing riding gear. Touring riders across Alpine regions favor these for multi-day flexibility.
- Trousers:Lower-body protection with hip and thigh airbag deployment. Niche adoption centers on high-speed road racing where leg injury severity drives specialized procurement.
The dominant share belongs to inflatable vests, while jackets are closing the gap fastest as integrated designs satisfy tightening circuit certification standards.
Technology:
Cost tier stratification separates legacy mechanical systems from algorithm-driven wireless platforms, with firmware subscription models reshaping lifetime value capture.
- Wireless Systems:Radio-frequency linked vests communicating with motorcycle ECUs or standalone trigger modules. Racing teams across MotoGP feeder championships mandate these for telemetry integration and post-crash data analysis.
- Sensor-Based:Self-contained accelerometer-gyroscope arrays executing crash detection without vehicle tethering. Urban commuters in Paris and Milan drive volume expansion as standalone convenience outweighs premium pricing.
- Manual Activation:Rider-triggered mechanical systems with physical pull-cords. Budget-conscious touring segments in Eastern Europe retain this installed base.
- Automated Deployment:Machine-learning classification engines with predictive impact timing. Factory racing programs pilot these for sub-50-millisecond deployment latency.
Wireless systems command the revenue concentration, yet sensor-based configurations are expanding most quickly as algorithm accuracy improvements justify hardware refresh cycles.
End User:
Customer type determines certification tier requirements and service intensity, with institutional procurement carrying parallel technical and medical documentation obligations.
- Professional Riders:Contracted athletes with federation-mandated airbag integration and factory technical support. FIM World Championship participation rules force seasonal equipment upgrades across European circuits.
- Casual Riders:Weekend enthusiasts and touring motorcyclists with voluntary adoption patterns. French and German insurance incentive programs accelerate penetration in this price-sensitive tier.
- Racing Teams:Organized squads with fleet procurement and centralized maintenance protocols. Track-day organizers in Italy increasingly require team-level airbag compliance for event insurance.
- Riding Schools:Training institutions with standardized student gear and liability-focused specifications. ANSM oversight in France drives these toward medically-documented trauma mitigation systems.
Professional riders anchor margin contribution, though racing teams are gaining share fastest as circuit mandates cascade from premier championships to national series.
Deployment Type:
Operational environment dictates sensor calibration requirements and deployment algorithm tuning, with high-speed track applications demanding the most sophisticated crash classification.
- On-Road:Highway and arterial street riding with variable traffic interaction patterns. Germany's KBA type-approval framework shapes product design for road-legal system certification.
- Off-Road:Trail and enduro applications with low-speed high-impact scenarios. Specialized algorithms distinguish rider falls from terrain-induced jolts.
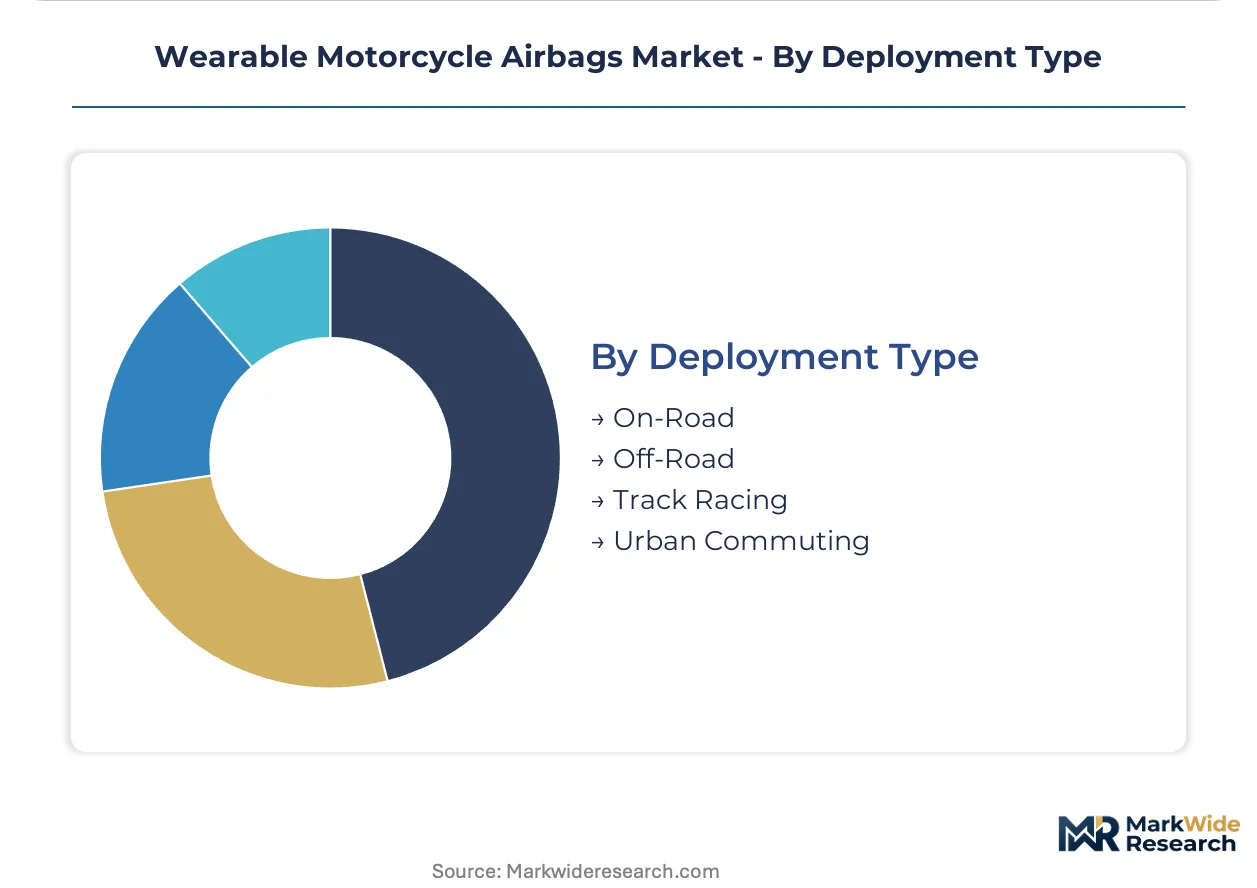
- Track Racing:Controlled circuit environments with predictable impact surfaces and medical response infrastructure. FIM mandates and national federation rules concentrate demand in Italy, France, and Spain.
- Urban Commuting:Stop-and-go traffic with intersection conflict exposure. Barcelona and Paris municipal safety initiatives pilot subsidy programs for daily rider protection.
Track racing dominates procurement value, while urban commuting is climbing the fastest as metropolitan safety programs expand addressable ridership beyond traditional racing segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government subsidy programs and circuit-mandated safety standards are redirecting procurement flows toward certified airbag systems across major motorcycle markets. National regulators are tightening personal protective equipment frameworks while metropolitan authorities pilot commuter protection initiatives. Industrial clusters concentrate where racing infrastructure and technical textile manufacturing overlap.
Germany
Track-day participation growth and KBA type-approval requirements for road-legal systems are expanding the addressable rider base. The country's federal motor transport authority enforces stringent certification timelines that favor established suppliers with embedded systems expertise. Bavaria's motorsport engineering corridor around Munich anchors technical development and team procurement decisions.
France
ANSM oversight of medical-adjacent trauma devices is elevating documentation requirements for injury-mitigation claims in racing applications. The national medicines safety agency now requires clinical validation data alongside mechanical testing for market authorization. Paris municipal safety initiatives subsidize daily commuter protection, creating volume demand beyond traditional racing segments.
Italy
FIM circuit mandates and national federation rules are forcing seasonal equipment upgrades across premier and feeder championships. The Ministry of Transport enforces parallel type-approval standards that influence product design for road-legal deployment. Emilia-Romagna's motorsport manufacturing belt around Modena concentrates supplier technical facilities and racing team headquarters.
United States
AMA Pro Racing adoption standards and state-level helmet law expansions are creating regulatory momentum for supplemental protection systems. The NHTSA maintains advisory jurisdiction over motorcycle safety equipment while stopping short of federal airbag mandates. California's track-day culture and Arizona's winter training circuits concentrate early wireless system adoption among amateur racers.
Japan
METI industrial standards for protective equipment and domestic manufacturer R&D concentration are shaping regional product specifications. The Ministry of Economy, Trade and Industry coordinates with JIS standard bodies on sensor calibration protocols. The Kanto region around Tokyo hosts integrated textile-electronics development clusters serving both domestic and export markets.
Wearable Motorcycle Airbags Market Competitive Landscape
On the supply side, the industry is consolidating around technology specialists with embedded systems capabilities and heritage protective gear manufacturers acquiring sensor fusion competencies. Three archetypes dominate: racing-heritage brands leveraging technical partnerships, standalone airbag specialists with algorithm subscription models, and diversified textile suppliers integrating inflation systems into existing garment lines. Competitive moves center on firmware-as-a-service transitions and backward integration into cold-gas inflator production.
Within the racing-heritage tier, Alpinestars and Dainese exemplify positioning built on premier championship technical partnerships and integrated technology platforms. In&Motion occupies a distinct archetype as a standalone specialist emphasizing recurring revenue through algorithm update subscriptions. Helite represents the diversified protective equipment fabricator segment with cross-application inflation system expertise spanning equestrian and motorcycling verticals.
| Leading Market Players |
|---|
| Hit-Air |
| MotoAirBag |
| Alpinestars |
| Bering |
| OMNIOF |
| Dainese |
| In&Motion |
| Ixon |
| Helite |
| Others |
Pricing and Supply Chain Analysis
Emilia-Romagna's motorsport manufacturing belt around Modena anchors European production capacity for cold-gas inflators and sensor-integrated textiles, concentrating supplier pricing power among heritage racing brands while compressing margins for peripheral component vendors.
Pricing Analysis
Certification level creates the primary spread between CE-marked road-legal systems and track-only configurations, with ANSM medical-validation tiers commanding premium positioning in France. Three-tier pricing structure across premium racing, standard consumer, and economy tether-based levels reflects firmware sophistication and telemetry integration depth. Cost compression in the economy tier intensifies as Eastern European touring riders retain mechanical systems, while professional racing teams show minimal price sensitivity due to FIM mandate compliance requirements.
Supply Chain Analysis
Helium and argon feedstock for cold-gas inflators draws from concentrated noble gas extraction in Qatar, Russia, and the United States, creating input cost volatility that ripples through finished vest pricing. Sensor arrays and accelerometer- gyroscope modules hinge on semiconductor fabrication in Taiwan, South Korea, and Japan. Single-source vulnerability around European helium refining capacity exposes manufacturers to supply disruption. Distribution runs through direct-to-rider digital channels and specialty motorsport retail networks with increasing disintermediation of traditional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from pandemic-suppressed track-day participation, with FIM circuit mandates and EU regulatory tightening providing cyclical uplift through forced equipment refresh cycles.
For Market Incumbents: Insulate algorithm subscription revenue by deepening firmware-as-a-service capabilities against standalone hardware competitors, while securing captive supply of cold-gas inflators through backward integration or long-term offtake agreements with Qatari noble gas processors to neutralize input volatility. For New Entrants and Emerging Players: Urban commuter protection in Barcelona, Paris, and Milan represents the most penetrable white-space segment, where municipal subsidy programs reduce price sensitivity and standalone sensor-based systems bypass racing certification barriers; target direct-to-rider app-based distribution to bypass entrenched specialty retail gatekeepers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors embedded systems specialists with proven crash-detection algorithm IP over pure textile manufacturers, as the convergence of garment and electronics competencies creates durable competitive moats; long-term viability hinges on V2X integration readiness and clinical validation dossiers for medical-adjacent trauma claims.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithm Subscription Migration | Recurring firmware revenue from In&Motion's model displaces one-time hardware margins across European racing teams. |
| Cold-Gas Inflator Backward Integration | Alpinestars and Dainese secure captive helium supply chains against Qatari export volatility. |
| ANSM Clinical Validation Investment | French market access now requires trauma-mitigation dossiers parallel to CE mechanical testing. |
| Urban Commuter Direct Channel Buildout | Manufacturer-owned apps in Germany and Italy fragment specialty retail distribution control. |
| V2X Communication Protocol Development | Pre-impact data sharing with infrastructure enables sub-50-millisecond deployment latency for factory racing programs. |
Research Methodology
A spread of perspectives from racing team technical directors, protective gear procurement officers at riding schools, CE certification consultants, and cold-gas inflator supply managers converged on the working assumptions around algorithm liability exposure and replacement cycle compression. Primary fieldwork combined structured interviews with secondary validation against FIM technical regulations, KBA type-approval documentation, ANSM medical device filings, and customs trade data for noble gas imports. Bottom-up segment sizing triangulated against top-down motorsport participation statistics and protective equipment spend patterns.
Demand-supply balance modeling across the projection horizon incorporated garment configuration, trigger mechanism sophistication, rider risk profile, and operational environment as core segmentation dimensions. CAGRs derived from fitted growth curves applied to track-day participation trends, regulatory mandate rollout schedules, and urban commuter subsidy program expansion trajectories. Forecast inputs included FIM championship rule evolution, KBA road-legal certification timelines, and municipal safety initiative budget commitments in Paris, Milan, and Barcelona.
Practitioners should monitor helium supply contract renegotiations and FIM feeder championship mandate extensions for early signals of margin pressure or demand acceleration. Forecasts reflect assumptions around algorithm liability framework stabilization and sustained track-day participation recovery. Cross-checking against motorcycle registration data and motorsport federation participation statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive Rear View Mirror Market
Automotive Safety and Security Systems
Driver Monitoring System (DMS) Market
Automotive Safety and Security Systems
Trailer Assist System Market
Automotive Safety and Security Systems
Global Automotive Curtain Airbags Market
Automotive Safety and Security Systems
Automotive Battery Pack Fire Barrier Pad Market
Automotive Safety and Security Systems
AI in-Vehicle Surveillance Market
Automotive Safety and Security Systems
Car Safety Market
Automotive Safety and Security Systems
Automatic Emergency Braking System (AEBS) Market
Automotive Safety and Security Systems
Driver Assistance System Market
Automotive Safety and Security Systems
Automotive Lane Warning System Market
Automotive Safety and Security Systems
Global Electronic Brake Force Distribution System Market
Automotive Safety and Security Systems
Asia-Pacific Automotive Anti-Lock Braking System Market
Automotive Safety and Security Systems
Global Automotive Terrain Response System Market
Automotive Safety and Security Systems
United States Automotive Airbag Systems Market
Automotive Safety and Security Systems
Global Automotive Lidar Sensor Market
Automotive Safety and Security Systems
Smart Airbag Coats Market