
 Anti-Fog Lights Market | 2026-2036
Anti-Fog Lights Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Fog Lights Market Analysis
EU Green Deal automotive lighting efficiency targets is hardening compliance timelines for auxiliary lamp manufacturers serving European OEMs. OSRAM GmbH leverages its vertical integration in LED chip fabrication to sustain cost advantages across German automotive supply chains. HELLA GmbH & Co. KGaA anchors its position through specialized optical design capabilities for adaptive front-lighting systems. Stanley Electric Co. Ltd. competes on manufacturing scale in Japan while extending its aftermarket distribution across Southeast Asian markets.
Anti-fog lights are auxiliary forward-illumination devices engineered to project a wide, low beam pattern below the optical cutoff of standard headlamps, typically operating at color temperatures between 3000K and 4300K to minimize backscatter in condensed moisture conditions. Their primary purpose is to enhance driver visibility during fog, heavy rain, or snow events without reflecting light off suspended water droplets back into the driver's eyes. LED product types now dominate factory-installed applications due to superior luminous efficacy and thermal management, while halogen retains share in price-sensitive aftermarket channels. Automotive applications generate the largest revenue pool, though marine and safety gear segments are expanding fastest as regulatory mandates broaden visibility requirements for commercial vessels and industrial protective equipment.
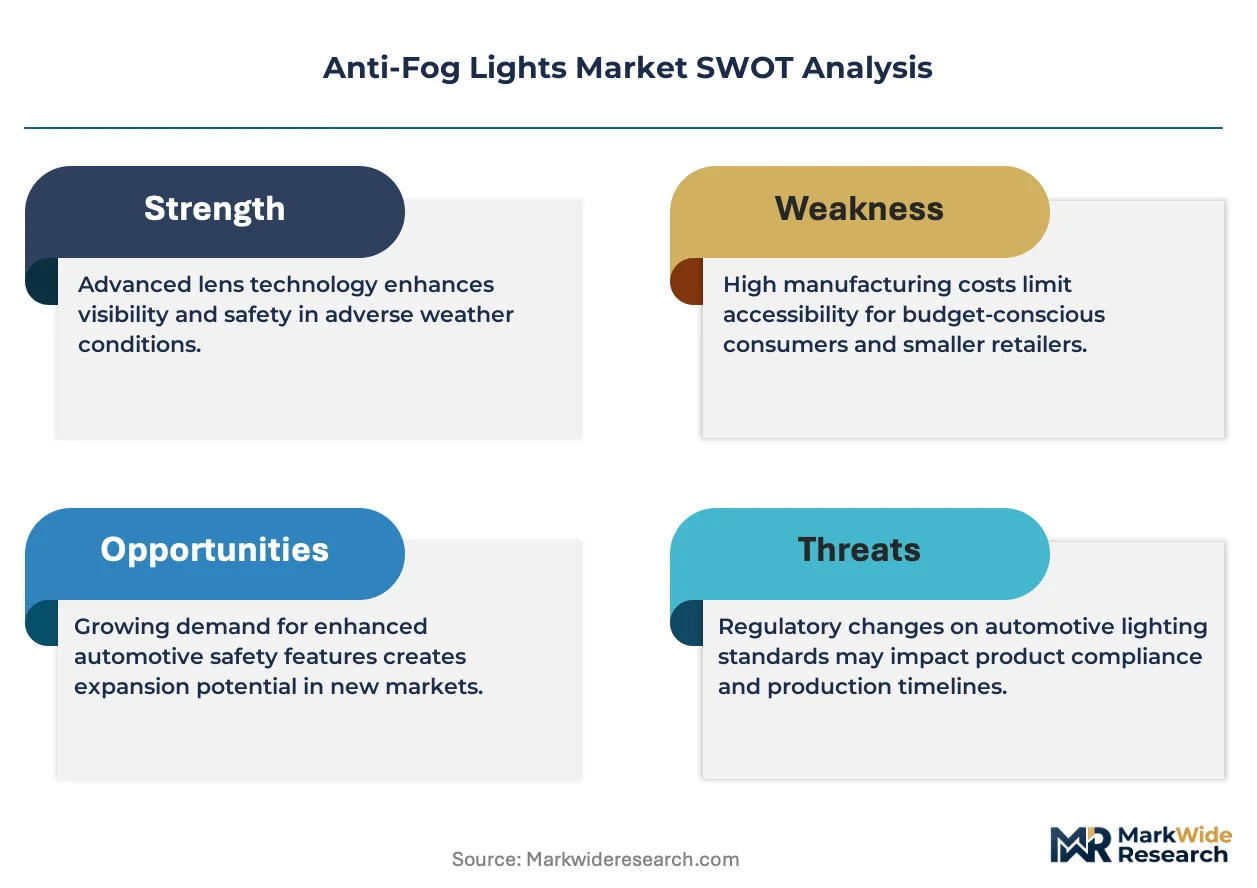
NHTSA Federal Motor Vehicle Safety Standard 108 shapes US market access by specifying beam pattern geometry and intensity limits for auxiliary driving lamps. ECE Regulation 19 governs European type approval for fog lamps, while China's GB 4785 standard mandates installation requirements and performance testing protocols for domestic vehicle certification. REACH substance restrictions and RoHS compliance further constrain material selection for lens polymers and driver electronics. Stakeholders must monitor divergence between US self-certification and European type-approval pathways as regulatory fragmentation risks complicate platform standardization strategies.
Market Dynamics
LED luminous efficacy gains and thermal management advances are compressing halogen's residual foothold in automotive auxiliary lighting, while regulatory divergence between NHTSA self-certification and ECE type-approval pathways fragments platform standardization strategies for multinational suppliers.
Growth Catalysts
- ECE Regulation 19 photometric tightening:Revised beam pattern geometry requirements are forcing OEM specification upgrades across German, French, and Italian vehicle platforms, accelerating LED fog lamp penetration in factory-installed applications.
- Marine regulatory expansion:Commercial vessel visibility mandates from the International Maritime Organization are extending anti-fog lighting requirements to cargo ships and passenger ferries, opening adjacent revenue pools beyond automotive.
- Color temperature optimization:3000K-4300K LED architectures minimize backscatter in condensed moisture, delivering measurable visibility advantages that specification engineers at Stuttgart and Munich tier-one clusters actively prioritize.
Market Restraints
- LED driver electronics cost structure:Semiconductor content in intelligent thermal management circuits maintains 40-60% cost premiums over halogen assemblies, constraining aftermarket price-sensitive segments.
- Lens polymer supply concentration:High-temperature polycarbonate and PMMA formulations for optical-grade fog lamp housings concentrate among Japanese and German specialty chemical suppliers, creating input vulnerability.
- REACH substance restrictions:ECHA limitations on brominated flame retardants and specific phthalates constrain material selection for housing assemblies, complicating European type-approval pathways.
Strategic Opportunities
- Industrial protective equipment:Safety gear mandates for mining, construction, and logistics workforces are extending anti-fog visibility requirements to helmet-mounted and wearable illumination systems.
- EU Green Deal efficiency targets:Automotive lighting energy consumption benchmarks create regulatory tailwinds for LED auxiliary lamp specification across European OEM procurement cycles.
- Adaptive beam convergence:Integration of fog lighting with camera-based road condition sensing and dynamic leveling systems enables premium pricing in advanced driver-assistance system architectures.
Industry Challenges
- Photometric calibration expertise scarcity:Precision optical design capabilities for cutoff beam engineering concentrate among aging specialist workforces in German and Japanese lighting clusters, constraining supplier expansion.
- Dual certification timeline compression:Simultaneous NHTSA FMVSS 108 self-certification and ECE Regulation 19 type-approval processes extend product development cycles by 8-14 months for platform-global programs.
- Legacy vehicle integration complexity:Retrofit LED fog lamp installations on pre-2015 vehicle electrical architectures require CAN bus adapter modules and load resistor solutions, fragmenting aftermarket product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Fog Lights Market |
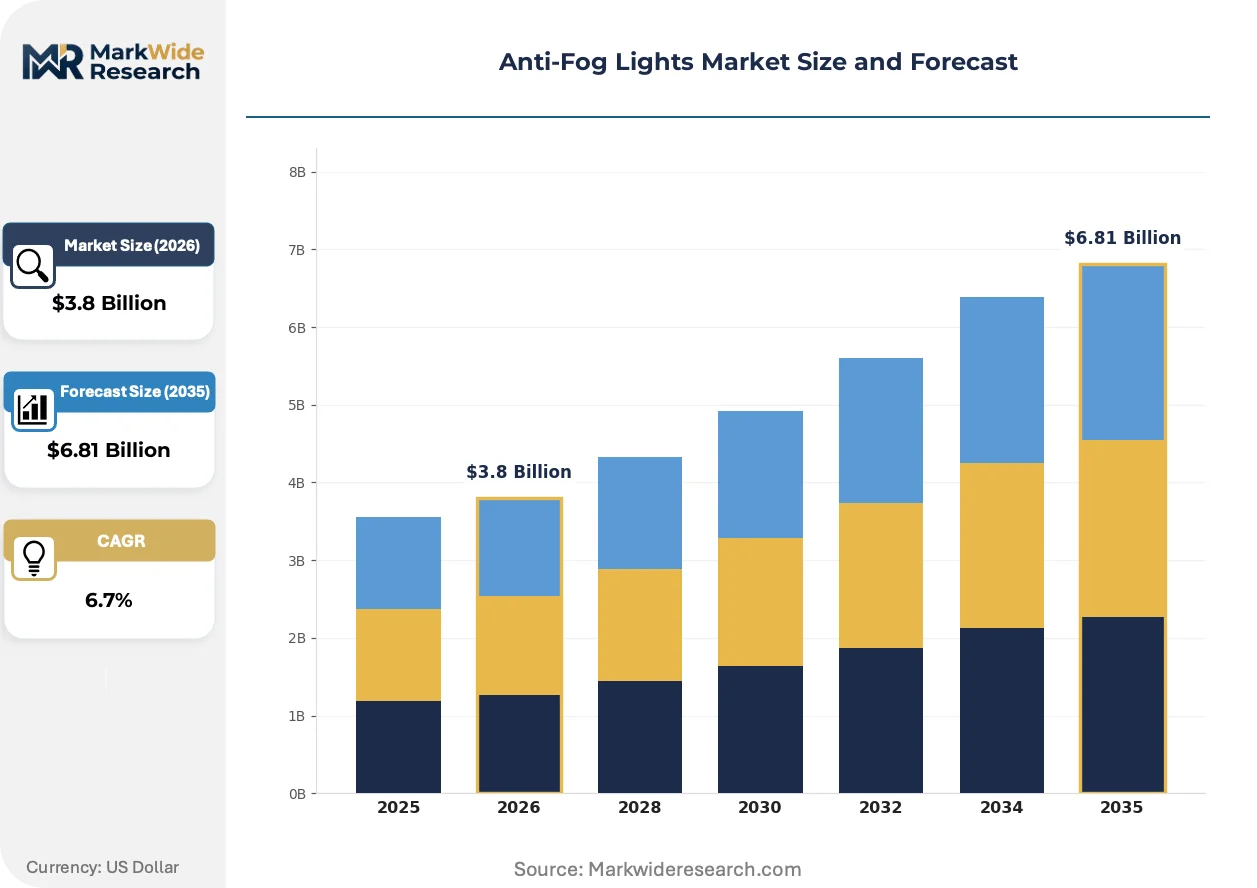
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Xenon, Halogen, Fluorescent Application: Automotive, Marine, Motorcycle, Safety Gear Installation Type: Factory-Installed, Aftermarket, Portable, Integrated End User: Consumers, Fleet Operators, OEMs, Retailers |
| Companies Covered | OSRAM GmbH, HELLA GmbH & Co. KGaA, Stanley Electric Co. Ltd., PIAA Corporation, Marelli Holdings Co., Ltd., Cree LED, General Electric, J.W. Speaker Corporation, Seoul Semiconductor Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Fog Lights Market Emerging Trajectories
Digital light processing and intelligent thermal architectures are rewriting how auxiliary illumination integrates with vehicle sensing systems, compressing the gap between standalone fog lamps and unified front-lighting domains.
Micro-LED array technology is rewriting fog lamp beam adaptability by enabling pixel-level intensity modulation without mechanical shutters. Premium German OEMs now specify these assemblies for adaptive cutoff control in variable weather conditions. The technology is rewriting supplier competitive positions by favoring semiconductor fabrication capabilities over traditional optical molding expertise.
EU Green Deal automotive efficiency targets are tightening auxiliary lamp energy consumption benchmarks ahead of 2030 fleet averages. ECE Regulation 19 revision timelines are compressing to align with these broader decarbonization frameworks. European tier-one suppliers near Stuttgart and Munich are responding by accelerating LED-only platform commitments and phasing halogen auxiliary options.
Fleet procurement centralization at commercial vehicle operators is consolidating fog lamp specification authority away from individual maintenance managers. Large German logistics and construction fleet buyers now mandate standardized LED auxiliary lighting across entire vehicle classes, displacing fragmented aftermarket purchasing. This concentration is most visible in Rhine-Ruhr industrial corridor fleet renewal programs.
Anti-Fog Lights Market Segmentation
Anti-fog light procurement splits across four structural axes that determine specification intensity and margin capture. Technology choice dictates thermal architecture and photometric performance. Installation channel governs certification burden and price sensitivity. End-user concentration shapes volume contracting and aftermarket fragmentation.
Product Type:
LED luminous efficacy gains and thermal management advances are compressing legacy technologies in automotive auxiliary lighting.
- LED:Solid-state emitters operating at 3000K-4300K color temperatures deliver superior luminous efficacy and intelligent thermal management. Specification engineers at Stuttgart and Munich tier-one clusters prioritize these assemblies for premium vehicle platforms under ECE Regulation 19 photometric tightening.
- Xenon:High-intensity discharge lamps produce intense white output through xenon gas excitation, retaining niche presence in marine applications where raw lumen output outweighs energy efficiency mandates.
- Halogen:Tungsten-halogen filaments maintain residual foothold in price-sensitive aftermarket channels where semiconductor driver costs constrain LED adoption.
- Fluorescent:Gas-discharge tubes with phosphor coatings occupy minimal share, limited to industrial safety gear applications requiring diffuse, low-glare illumination.
Mature deployment sits with Halogen. Newer deployment is concentrated in LED.
Application:
End-use concentration determines regulatory exposure and beam pattern engineering requirements.
- Automotive:Factory-installed fog lamps for passenger vehicles and commercial trucks generate the largest revenue pool. NHTSA FMVSS 108 and ECE Regulation 19 govern beam geometry and intensity limits across US and European OEM procurement cycles.
- Marine:Commercial vessel visibility mandates from the International Maritime Organization extend anti-fog requirements to cargo ships and passenger ferries. This segment is climbing the fastest as regulatory mandates broaden beyond automotive.
- Motorcycle:Compact auxiliary lighting for two-wheelers emphasizes weight reduction and vibration resistance. Japanese manufacturers dominate specification for premium motorcycle platforms.
- Safety Gear:Helmet-mounted and wearable illumination systems for mining, construction, and logistics workforces are gaining share fastest as occupational visibility mandates proliferate.
Volume concentration rests with Automotive. Specification innovation is migrating toward Safety Gear.
Installation Type:
Channel structure determines certification pathway and margin architecture.
- Factory-Installed:OEM-integrated assemblies undergo ECE type-approval or NHTSA self-certification before vehicle platform launch. LED architectures dominate as European tier-one suppliers phase halogen auxiliary options.
- Aftermarket:Retrofit installations on legacy vehicle electrical architectures require CAN bus adapter modules and load resistor solutions. Price sensitivity constrains semiconductor content in this channel.
- Portable:Battery-powered standalone units serve emergency and recreational applications with minimal regulatory burden.
- Integrated:Unified front-lighting domain controllers merge fog functions with adaptive headlamp systems, commanding premium pricing in ADAS architectures.
Certification burden is heaviest for Factory-Installed. Margin compression is most severe in Aftermarket.
End User:
Buyer concentration shapes contracting scale and specification authority.
- OEMs:Vehicle manufacturers consolidate fog lamp procurement through tier-one lighting suppliers near Stuttgart, Munich, and Tokyo. Fleet procurement centralization at commercial vehicle operators is consolidating specification authority away from fragmented aftermarket purchasing.
- Fleet Operators:Large German logistics and construction fleet buyers now mandate standardized LED auxiliary lighting across entire vehicle classes, displacing individual maintenance manager discretion.
- Consumers:Individual vehicle owners drive aftermarket replacement demand with high price elasticity and brand fragmentation.
- Retailers:Distributors and e-commerce platforms intermediate between manufacturers and end users, capturing margin through inventory aggregation and technical support services.
Contracting scale favors Fleet Operators. Fragmentation persists with Consumers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors specification intensity for premium fog light assemblies, with tier-one automotive clusters around Munich reinforcing German procurement concentration for LED-based auxiliary lighting systems.
Germany
Stuttgart and Munich tier-one clusters drive factory-installed LED fog lamp penetration under ECE Regulation 19 photometric tightening. EU Green Deal automotive efficiency targets compress compliance timelines for auxiliary lamp manufacturers. Baden-Württemberg suppliers leverage specialized optical design capabilities to capture premium vehicle platform contracts.
United States
NHTSA FMVSS 108 self-certification shapes market access for auxiliary driving lamps across passenger and commercial vehicle segments. Michigan and Ohio automotive manufacturing corridors concentrate OEM procurement authority. Detroit-based tier-one suppliers navigate divergent certification timelines for platform-global programs.
Japan
Tokyo and Nagoya manufacturing bases sustain LED chip fabrication and optical-grade polymer supply for fog lamp housings. METI industrial standards govern component quality benchmarks for domestic and export markets. Kanto region suppliers extend aftermarket distribution networks across Southeast Asian markets.
China
GB 4785 standard mandates installation requirements and performance testing protocols for domestic vehicle certification. Yangtze River Delta automotive electronics clusters scale manufacturing output for LED driver electronics. Shanghai-based suppliers address cost premiums constraining aftermarket price-sensitive segments.
South Korea
Seoul Capital Area semiconductor fabrication capabilities support LED luminous efficacy gains for auxiliary lighting applications. MFDS-equivalent automotive component regulations align with international type-approval frameworks. Busan-Ulsan industrial corridor suppliers concentrate on thermal management circuit integration.
Anti-Fog Lights Market Vendor Landscape
The competitive structure tilts toward vertically integrated lighting specialists with captive LED chip production and established tier-one automotive relationships. Market concentration reflects high barriers in precision optical design and dual-certification expertise. Two strategic archetypes dominate: German-Japanese specialists with deep OEM integration and Asian scale manufacturers leveraging semiconductor fabrication advantages. Competitive moves center on adaptive beam technology licensing and thermal architecture partnerships.
Among German lighting specialists, OSRAM GmbH and HELLA GmbH & Co. KGaA exemplify the vertically integrated archetype with Stuttgart and Munich regional anchoring. Stanley Electric Co. Ltd. represents the Japanese manufacturing scale model. These three occupy positions defined by regulatory compliance depth rather than price competition.
| Leading Market Players |
|---|
| OSRAM GmbH |
| HELLA GmbH & Co. KGaA |
| Stanley Electric Co. Ltd. |
| PIAA Corporation |
| Marelli Holdings Co., Ltd. |
| Cree LED |
| General Electric |
| J.W. Speaker Corporation |
| Seoul Semiconductor Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
LED driver semiconductor costs cascade from foundry capacity constraints in South Korea and Taiwan through three distinct pricing tiers for automotive auxiliary lighting assemblies. This input concentration amplifies margin pressure at the standard tier while premium OEM channels absorb thermal management circuit premiums through value-based contracting.
Pricing Analysis
Photometric performance outcomes anchor value-based pricing for anti-fog lamp assemblies, with ECE Regulation 19 certification tier separating premium factory-installed LED systems from economy aftermarket halogen replacements. Price differentiation hinges on optical-grade polymer lens quality and dual-certification compliance burden, with NHTSA FMVSS 108 self-certification adding cost layers for US-bound production. Cost compression in the aftermarket channel intensifies as CAN bus adapter requirements fragment retrofit product lines. Fleet operators exhibit lowest price sensitivity through centralized procurement, while individual consumers drive margin erosion in price-elastic replacement demand.
Supply Chain Analysis
EU Green Deal local-content benchmarks and emerging domestic-manufacturing mandates in China and South Korea are reshaping sourcing patterns for LED fog lamp assemblies. High-temperature polycarbonate and PMMA optical-grade polymers concentrate among German and Japanese specialty chemical suppliers, while LED chip fabrication centers on Taiwan, South Korea, and Japan. Single-source vulnerability in precision optical molding equipment constrains capacity expansion for adaptive beam architectures. Distribution runs through tier-one automotive supplier clusters near Stuttgart, Munich, and Tokyo before final OEM integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Photometric calibration expertise scarcity functions as the binding capacity constraint, propping pricing power for incumbent specialists with established German and Japanese optical engineering workforces.
For Market Incumbents: Deepen backward integration into LED driver semiconductor design to capture thermal management circuit margins currently flowing to foundry partners. Anchor certification investment in simultaneous NHTSA and ECE approval capabilities to compress timeline advantages over multinational platform programs. Defend against Asian scale manufacturers by locking Stuttgart and Munich tier-one relationships through adaptive beam technology licensing partnerships. For New Entrants and Emerging Players: Enter via industrial safety gear applications where occupational visibility mandates are proliferating fastest and specification intensity remains nascent. Target mining and construction helmet-mounted illumination systems where certification barriers sit lower than automotive type-approval pathways. Pursue direct contracting with fleet operators in the Rhine-Ruhr corridor as centralized procurement displaces fragmented aftermarket purchasing. For Investors and Strategic Acquirers: ECE Regulation 19 revision timelines compressing toward EU Green Deal alignment is the leading indicator that LED-only platform commitments will harden across European OEM procurement cycles, favoring semiconductor-fabrication-capable suppliers over traditional optical molders. Position acquisition screening around captive LED chip production and established tier-one automotive relationships with 5-10 year viability windows. Monitor marine regulatory expansion signals from the International Maritime Organization as adjacent revenue pool validation.| Strategic Initiative | Industry Significance |
|---|---|
| Adaptive Beam Technology Licensing | Micro-LED array partnerships with Stuttgart OEMs rewrite supplier competitive positions around semiconductor fabrication. |
| Dual-Certification Capability Buildout | Simultaneous NHTSA FMVSS 108 and ECE Regulation 19 approval slashes platform-global program timelines. |
| Marine Segment Regulatory Positioning | IMO commercial vessel mandates extend anti-fog requirements to cargo ships and passenger ferries beyond automotive. |
| Industrial Safety Gear Market Entry | Helmet-mounted illumination systems for mining and construction workforces open specification innovation pathways. |
| Optical Polymer Backward Integration | Captive high-temperature polycarbonate supply mitigates Japanese and German specialty chemical supplier concentration risk. |
Methodological Framework
Trade databases, regulatory filing repositories, and automotive production statistics formed the secondary backbone for this analysis. Primary interviews with tier-one supplier procurement managers, OEM platform engineers, aftermarket distributors, and optical design specialists combined with secondary validation across ECE Regulation 19 type-approval records and NHTSA FMVSS 108 self-certification filings. Bottom-up and top-down triangulation anchored volume and value estimates.
Bottom-up modeling traced LED and halogen unit shipments through installation channels and end-user segments, while top-down approaches cross-referenced automotive production volumes and auxiliary lamp content-per-vehicle assumptions. Segmentation dimensions spanned technology type, application vertical, installation channel, and regional regulatory cluster. CAGRs derived from fitted growth curves calibrated to ECE photometric tightening timelines and EU Green Deal efficiency mandate implementation.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt regulatory divergence between NHTSA and ECE pathways or sustained semiconductor foundry capacity constraints. Forecasts embed assumptions around LED luminous efficacy improvement trajectories and thermal management cost compression. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Motorcycle E-Call Market
Automotive Safety and Security Systems
Asia-Pacific Automotive Anti-Lock Braking System Market
Automotive Safety and Security Systems
Automotive Brake Override System Market
Automotive Safety and Security Systems
Germany Traffic Sign Recognition Market
Automotive Safety and Security Systems
Automotive Surge Absorber Market
Automotive Safety and Security Systems
Global Automotive Defogger System Market
Automotive Safety and Security Systems
Automotive Pedestrian Protection System Market
Automotive Safety and Security Systems
Africa and Middle East Airbag Systems Market
Automotive Safety and Security Systems
Mexico Airbag Systems Market
Automotive Safety and Security Systems
Driving Armor Market
Automotive Safety and Security Systems
Adaptive Headlights Market
Automotive Safety and Security Systems
Global Car Radar Detectors Market
Automotive Safety and Security Systems
Automotive Blind Spot Monitors Market
Automotive Safety and Security Systems
Global Automotive Terrain Response System Market
Automotive Safety and Security Systems
Lane Departure Warning (LDW) Market
Automotive Safety and Security Systems
Latin America Airbag Systems Market