
 Wheelchair Accessible Vehicle Market | 2026-2036
Wheelchair Accessible Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Wheelchair Accessible Vehicle Market Outlook
Software-defined ramp calibration and remote diagnostics is shifting how fleet operators manage uptime across converted vehicle pools. BraunAbility leverages its dedicated manufacturing footprint to sustain high-volume output of side-entry minivan conversions. Toyota anchors North American supply through its certified mobility dealer program and factory-authorized upfitter relationships. Ford competes with proprietary chassis modifications that streamline third-party conversion integration.
A wheelchair accessible vehicle is a passenger transport unit engineered with structural floor lowering, reinforced anchoring systems, and deployed access mechanisms to accommodate occupied wheelchairs, typically achieving interior door heights exceeding 56 inches and ramp load capacities above 1,000 pounds. Its primary purpose is to enable independent or assisted mobility for individuals with permanent or temporary ambulatory limitations. Minivan conversions occupy the dominant volume position due to lower center-of-gravity engineering and garage-compatible parking profiles, while electric powertrains represent the fastest-growing fuel category as conversion houses adapt battery placement around floor-pan modifications. Ramp systems command the largest installed base among modification types, though lift mechanisms capture premium pricing in commercial paratransit applications where vertical platform entry is mandated.
The National Highway Traffic Safety Administration enforces Federal Motor Vehicle Safety Standards that govern post-manufacture structural alterations, while the Rehabilitation Engineering and Assistive Technology Society of North America publishes voluntary conversion quality protocols that influence insurer reimbursement rates. State-level Medicaid waiver programs create patchwork funding availability that shapes regional demand intensity and dealer network profitability. Stakeholders must monitor how EPA emissions standards for light-duty trucks interact with conversion weight penalties that reduce electric range and alter total cost of ownership calculations for fleet buyers.
Market Dynamics
Medicaid-funded fleet procurement is concentrating demand around converted minivans with software-defined diagnostics, while the ADA's tightened compliance timelines force conversion houses to accelerate certification cycles and compress delivery windows.
Growth Catalysts
- Medicaid waiver expansion:State-level non-emergency medical transportation programs are widening eligibility criteria and increasing per-member vehicle allocations, directly lifting fleet procurement volumes.
- Floor-pan battery integration:Electric powertrain adaptation for wheelchair-accessible minivans is expanding addressable range for conversion houses previously constrained by internal combustion chassis supply.
- Aging demographic concentration:The United States is experiencing accelerated growth in mobility-limited populations over 65, creating sustained replacement demand for personal-use accessible vehicles.
Market Restraints
- Steel and aluminum input volatility:Reinforced ramp and anchoring system fabrication faces margin pressure from fluctuating structural metal prices, particularly affecting smaller conversion operations without long-term supplier contracts.
- Conversion house geographic concentration:Certified upfitter capacity clusters in the Midwest and Southeast United States, creating regional supply bottlenecks and extended delivery timelines for coastal markets.
- Electric range compression:Floor-lowering modifications add substantial weight that reduces battery efficiency, limiting electric wheelchair accessible vehicle viability for rural paratransit routes exceeding 150 miles.
Strategic Opportunities
- Telematics-integrated service contracts:Fleet operators are purchasing remote diagnostics bundled with preventive maintenance, opening recurring revenue streams for conversion houses with connected vehicle capabilities.
- Suburban dealer network gaps:Exurban counties around Dallas, Phoenix, and Atlanta show certified mobility dealer penetration below 30 percent, representing whitespace for territory expansion.
- IRA commercial vehicle incentives:Federal tax credits for electric light-duty trucks are offsetting conversion cost premiums, accelerating electric powertrain adoption in municipal paratransit procurement.
Industry Challenges
- FMVSS 403/404 certification backlog:NHTSA testing queue delays for powered ramp systems are stretching product launch timelines by four to six months, freezing capital in work-in-progress inventory.
- Conversion technician skill scarcity:Structural welding and automotive electronics integration expertise is concentrating among aging specialists, constraining output scaling at high-volume conversion facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wheelchair Accessible Vehicle Market |
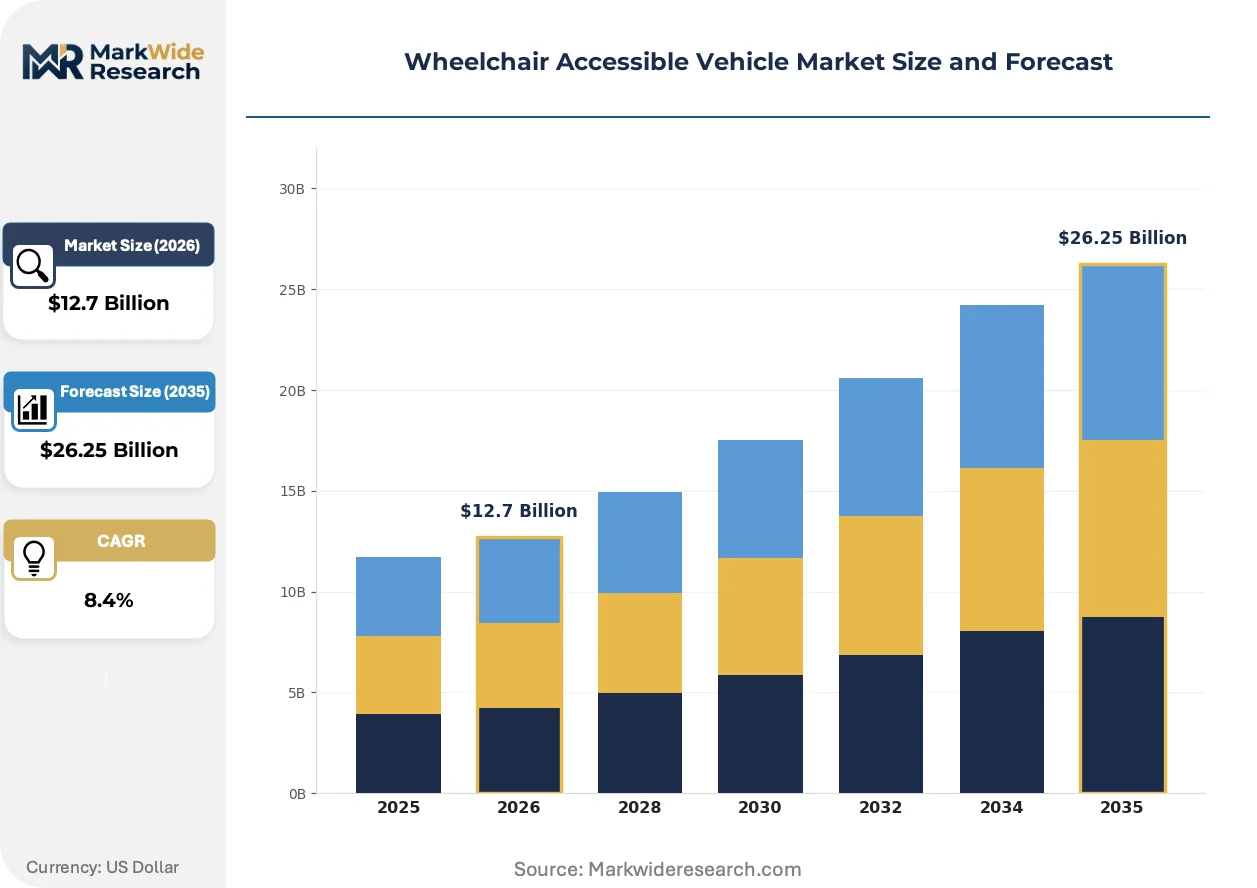
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $26.25 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Minivans, SUVs, Vans, Trucks Modification Type: Ramp, Lift, Conversion, Hand Controls End User: Individuals, Healthcare Providers, Organizations, Care Facilities Fuel Type: Gasoline, Diesel, Electric, Hybrid |
| Companies Covered | MobilityWorks, Freedom Motors USA, BraunAbility, Toyota, United Access, Vantage Mobility International, ATC Mobility, Ford, Rollx Vans, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wheelchair Accessible Vehicle Market Strategic Shifts
Software-defined vehicle architectures are penetrating wheelchair accessible conversions, enabling predictive maintenance and remote calibration that reshape how fleet operators manage vehicle uptime and total cost of ownership.
Lightweight carbon fiber composite ramp systems are expanding into side-entry minivan configurations, reducing deployed weight by 40 percent compared to aluminum alternatives. Municipal paratransit fleets in California and Washington are specifying these ramps for electric chassis to preserve battery range. The technology is expanding into premium personal-use segments as conversion houses market range preservation to suburban buyers.
ADA Title III updated accessibility standards are mandating faster deployment mechanisms and enhanced slip resistance for public accommodation vehicles. Commercial operators must retrofit existing fleets or accelerate replacement cycles to meet compliance deadlines. Transit agencies in Illinois, Pennsylvania, and Ohio are consolidating procurement to secure volume pricing ahead of enforcement phase-in.
Fleet buyers are consolidating vendor relationships around conversion houses offering integrated telematics and nationwide service networks. Large Medicaid transportation brokers are dropping small regional upfitters in favor of national contracts with standardized reporting and single-point accountability. This consolidation is most visible in Texas and Florida, where managed care organizations control substantial non-emergency medical transportation spending.
Wheelchair Accessible Vehicle Market Segmentation
Wheelchair accessible vehicle procurement varies sharply by use case, with fleet operators prioritizing durability metrics and individual buyers emphasizing garage compatibility and ride quality. Conversion houses calibrate engineering specifications and pricing tiers around these divergent decision frameworks.
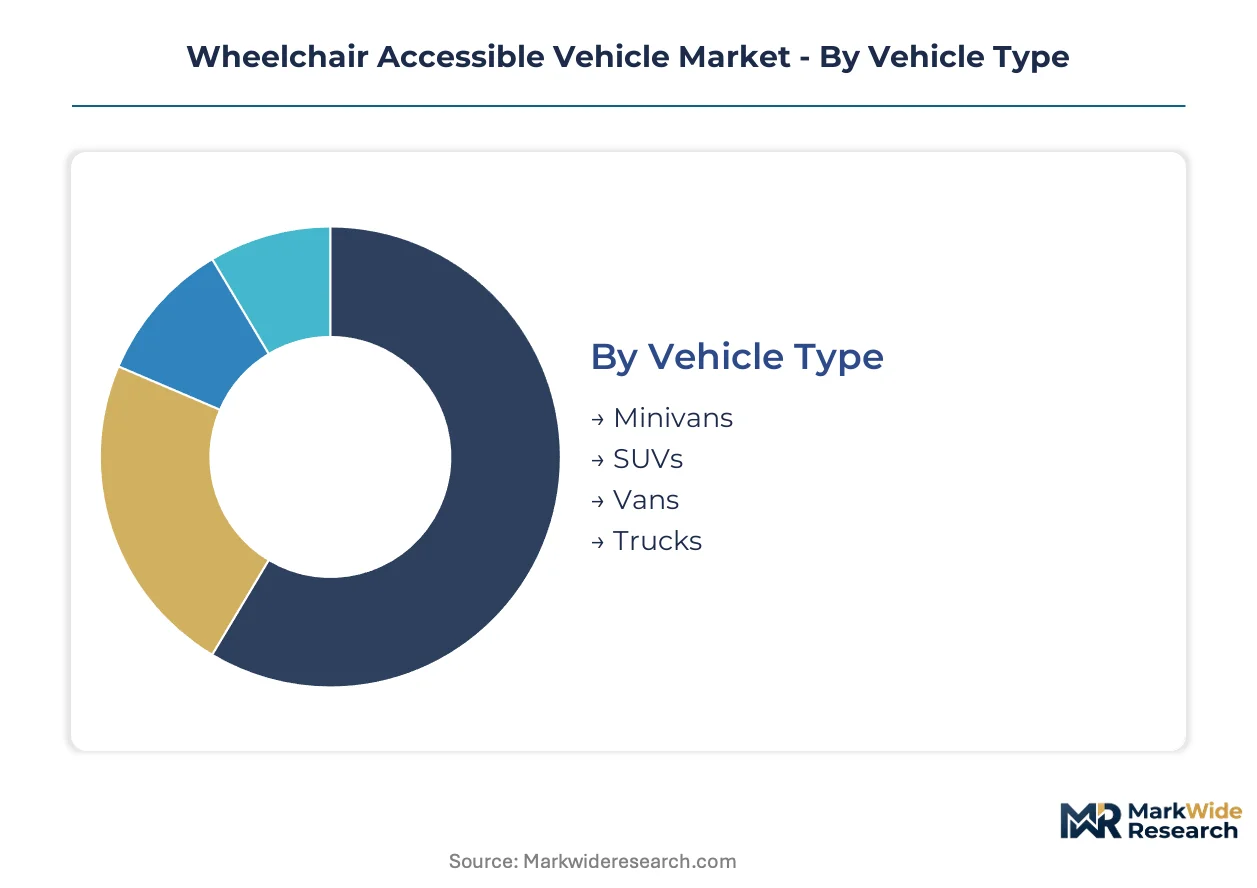
Vehicle Type:
Fleet density and parking infrastructure constraints determine volume distribution across chassis formats.
- Minivans:Floor-lowering modifications achieve center-of-gravity stability below 24 inches while maintaining standard garage clearance. Medicaid-funded non-emergency medical transportation programs in Texas and Florida concentrate procurement here due to lower per-unit capital requirements and established service networks.
- SUVs:Higher ground clearance necessitates steeper ramp angles or powered lift integration, adding $8,000-$15,000 to conversion cost. Personal-use buyers in suburban Atlanta and Dallas-Forth Worth metro areas favor SUVs for all-weather capability and perceived safety advantages in multi-vehicle households.
- Vans:Full-size commercial configurations dominate paratransit and care facility shuttle applications where multiple wheelchair positions are required.
- Trucks:Factory-authorized upfitter programs from Ford and Toyota anchor supply for rural healthcare providers needing off-pavement durability.
Minivans lead on scale; electric powertrain adaptation is gaining share fastest among SUVs as battery placement engineering matures.
Modification Type:
Compliance mandates and entry geometry requirements shape specification patterns across customer segments.
- Ramp:Side-entry aluminum deployments handle 1,000-pound dynamic loads and deploy in under 30 seconds. California and Washington municipal fleets specify carbon fiber alternatives to preserve electric vehicle range.
- Lift:Vertical platform mechanisms command premium positioning in commercial paratransit where ADA Title III mandates level entry. Transit agencies in Illinois and Pennsylvania accelerate replacement cycles ahead of enforcement deadlines.
- Conversion:Structural floor pan lowering and reinforced anchoring systems form the foundational modification across all vehicle types.
- Hand Controls:Secondary mobility adaptations for drivers with upper-body function preservation represent a specialized aftermarket segment.
Ramp systems dominate installed base; lift mechanisms capture the steepest margin expansion trajectory as compliance deadlines tighten.
End User:
Funding source and utilization intensity create distinct service and warranty requirements.
- Individuals:Personal-use buyers prioritize ride quality and aesthetic integration, often financing through specialized mobility lenders with extended depreciation schedules.
- Healthcare Providers:Hospital-affiliated transportation services demand telematics integration and nationwide service networks to minimize downtime across dispersed vehicle pools.
- Organizations:Non-profit disability service agencies balance acquisition cost against expected utilization hours and donor reporting requirements.
- Care Facilities:Nursing home and assisted living shuttle operations emphasize door-to-door cycle time and liability mitigation through automated restraint systems.
Healthcare providers drive fleet standardization; individuals represent the most fragmented demand profile with highest price sensitivity variance.
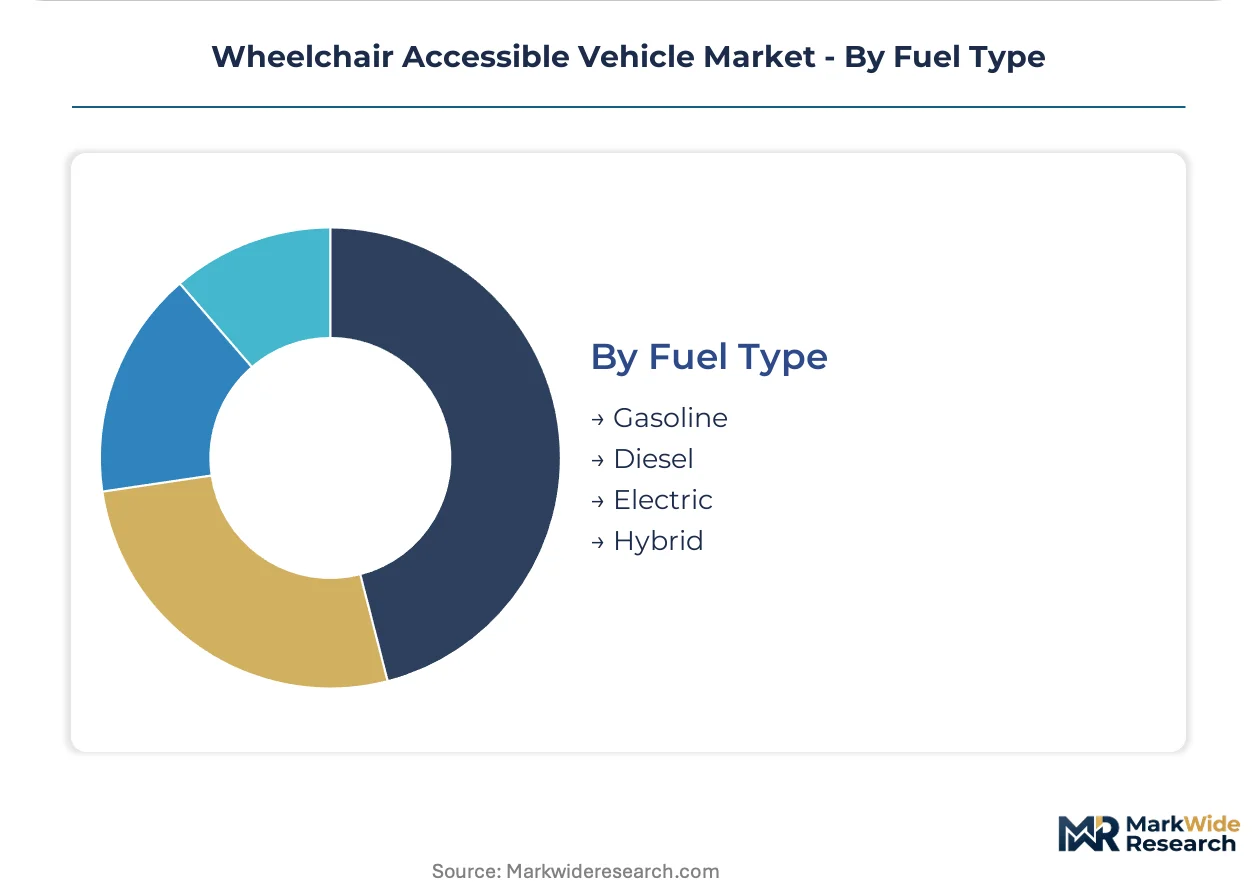
Fuel Type:
Total cost of ownership calculations increasingly incorporate conversion weight penalties and available federal incentives.
- Gasoline:Established internal combustion supply chains and conversion house familiarity sustain dominant procurement share among personal-use buyers in the Midwest and Southeast.
- Electric:IRA commercial vehicle tax credits offset conversion premiums for municipal paratransit fleets. Floor-lowering weight penalties reduce range by 15-25 percent, constraining rural route viability.
- Diesel:Heavy-duty van applications in commercial paratransit retain diesel preference for torque characteristics and refueling infrastructure density.
- Hybrid:Transitional powertrains attract buyers seeking fuel cost reduction without electric range anxiety or charging infrastructure dependency.
Gasoline retains volume leadership; electric configurations are expanding most quickly in California and Washington state fleets where incentives stack with local mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates conversion house capacity and Medicaid-funded fleet procurement, while Germany anchors European engineering standards through its KBA certification protocols for structural vehicle modifications.
United States
Texas and Florida Medicaid transportation brokers drive consolidated fleet procurement around standardized minivan conversions. NHTSA enforces FMVSS 403/404 certification timelines that stretch product launches by four to six months. Indiana and Michigan host the densest clusters of certified upfitter facilities, with BraunAbility sustaining high-volume output from dedicated manufacturing footprints in these states.
Germany
KBA type-approval requirements for post-manufacture structural alterations shape conversion house investment priorities across the federal states. EU Green Deal emissions targets accelerate electric powertrain adaptation for municipal paratransit fleets in Bavaria and North Rhine-Westphalia. Stuttgart-based engineering consultancies specialize in floor-pan battery integration for wheelchair-accessible van platforms.
Japan
METI subsidies for barrier-free transportation infrastructure expand addressable demand among aging rural populations in Shikoku and Kyushu. JIS standards for vehicle modification quality influence insurer reimbursement protocols nationwide. Toyota's certified mobility dealer program anchors supply chain coordination through factory-authorized upfitter relationships concentrated in the Kanto region.
United Kingdom
Motability Scheme lease volumes concentrate demand around side-entry minivan configurations for personal-use buyers in Greater London and the Southeast. DVSA inspection protocols for wheelchair accessible vehicle safety create compliance layering that favors established conversion houses over new market entrants. Birmingham and Manchester host regional distribution hubs for national fleet service networks.
Canada
Provincial disability transportation funding programs in Ontario and Quebec generate patchwork procurement intensity that shapes dealer network profitability. Transport Canada CMVSS alignment with NHTSA standards reduces certification duplication for US-sourced conversion platforms. Toronto and Vancouver metropolitan areas show certified mobility dealer penetration gaps below national averages, representing whitespace for territory expansion.
Wheelchair Accessible Vehicle Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with fleet procurement consolidating around national providers while personal-use demand fragments across regional dealerships. The vendor base organizes into three tiers: OEM-authorized upfitters with factory engineering relationships, independent conversion houses with proprietary ramp systems, and regional installers serving local Medicaid transportation brokers. Consolidation pressure intensifies as large healthcare transportation brokers drop small regional upfitters in favor of standardized reporting and single-point accountability. Geographic expansion through suburban dealer network gaps and telematics-integrated service contracts represent the dominant competitive vectors.
Among OEM-authorized fabricators, Toyota and Ford exemplify divergent strategic positioning through certified mobility dealer programs versus proprietary chassis modifications. BraunAbility occupies a dedicated manufacturing position within the independent conversion house tier. These three entities anchor distinct supply chain configurations: factory-authorized upfitter relationships, streamlined third-party integration protocols, and high-volume side-entry minivan output respectively.
| Leading Market Players |
|---|
| MobilityWorks |
| Freedom Motors USA |
| BraunAbility |
| Toyota |
| United Access |
| Vantage Mobility International |
| ATC Mobility |
| Ford |
| Rollx Vans |
| Others |
Value Chain & Pricing Dynamics
Captive manufacturing footprints in Indiana and Michigan anchor supply positions for BraunAbility and Ford's certified upfitter networks, concentrating conversion capacity within four-hour trucking radius of Detroit chassis supply while insulating these operators from spot-market aluminum volatility that compresses margins at smaller regional houses.
Pricing Analysis
Capacity additions in Michigan and Indiana are reshaping price floors for side-entry minivan conversions as BraunAbility's dedicated output expands fleet procurement negotiating leverage. Three-tier pricing structure across premium carbon-fiber ramps, standard aluminum deployments, and economy steel alternatives differentiates offerings, with certification grade under FMVSS 403/404 creating additional stratification. Cost compression in economy-tier steel conversions is intensifying because Medicaid brokers consolidate procurement around standardized specifications. Individual personal-use buyers in suburban Dallas and Atlanta show highest price sensitivity, while municipal paratransit fleets prioritize total cost of ownership over upfront capital.
Supply Chain Analysis
Regional distribution centers in Indianapolis and Orlando feed hub-and-spoke patterns that extend certified upfitter reach into dealer-penetration gaps across exurban Texas and Florida. Supply concentrates in the United States, with secondary component sourcing from Mexico for chassis platforms and Canada for structural steel inputs. Reinforced ramp fabrication draws from aluminum sheet and carbon fiber composite feedstocks, while battery pack integration for electric chassis rests on South Korean cell supply. Single-source vulnerability in NHTSA certification testing creates four-to-six-month launch delays that freeze working capital. Distribution runs through factory-authorized dealer networks for Toyota and Ford, independent conversion house direct sales for BraunAbility, and regional Medicaid broker contracts for smaller upfitters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Arbitrage opportunities emerge between Texas and California procurement environments, where IRA commercial vehicle incentives in the latter offset conversion premiums that Medicaid rate structures in the former cannot absorb.
For Market Incumbents: Deploy telematics-integrated service contracts as the primary lever to lock in fleet retention against emerging software-defined vehicle entrants. Deepen backward integration into carbon fiber composite ramp manufacturing to capture margin from lightweighting demand in California and Washington electric fleets. Fortify certification investment ahead of ADA Title III enforcement deadlines to freeze out smaller competitors lacking NHTSA testing queue priority. For New Entrants and Emerging Players: Begin with suburban dealer territory expansion in Phoenix, Dallas, and Atlanta where certified mobility penetration sits below 30 percent. Target healthcare provider segments demanding nationwide service networks, as large Medicaid transportation brokers drop regional upfitters for single-point accountability. Pursue go-to-market partnerships with managed care organizations controlling non-emergency medical transportation spending in Texas and Florida. For Investors and Strategic Acquirers: Consolidation pressure builds where conversion technician skill scarcity constrains output scaling at high-volume facilities. Five-to-ten-year viability favors acquisition targets with captive NHTSA certification capacity and established telematics platforms over undifferentiated regional installers. Monitor FMVSS 403/404 testing queue lengths as inflection indicator for which conversion houses can sustain product launch velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Remote diagnostics bundled with preventive maintenance opens recurring revenue streams for conversion houses. |
| Carbon Fiber Ramp Manufacturing Scale-Up | Lightweighting preserves electric vehicle range for California and Washington municipal paratransit procurement. |
| Suburban Dealer Network Expansion | Territory gaps in Dallas-Forth Worth and Atlanta exurbs represent whitespace for certified mobility penetration. |
| FMVSS Certification Investment | NHTSA testing queue priority determines product launch velocity and capital efficiency across conversion portfolios. |
| IRA Incentive Stacking Strategy | Federal tax credits for electric light-duty trucks offset conversion cost premiums in municipal procurement cycles. |
Study Parameters
Coverage spans the United States, Germany, Japan, the United Kingdom, and Canada, with primary inputs from each market's regulatory and procurement stakeholders. Conversion house operations directors, Medicaid transportation program administrators, certified mobility dealer principals, NHTSA compliance officers, and fleet procurement managers at healthcare providers contributed structured interviews. Secondary validation drew from NHTSA FMVSS certification databases, state Medicaid waiver program filings, EPA emissions standards documentation, and vehicle production registration data. Bottom-up unit economics triangulated against top-down spending flow analysis.
Granularity-level modeling disaggregated volume and value across vehicle type, modification type, end user, and fuel type dimensions, with additional segmentation by state-level Medicaid program structure. CAGRs derived from logistic adoption curves for electric powertrain penetration and replacement cycle dynamics for aging demographic cohorts. Forecast inputs incorporated IRA incentive phase-out assumptions and ADA Title III compliance deadline enforcement patterns.
Several conditions sit outside the modeled scope, including abrupt NHTSA regulatory reinterpretation, steel and aluminum commodity price spikes exceeding historical volatility bands, and Medicaid program eligibility contraction at state level. Forecasts reflect documented assumptions around technician labor supply and electric vehicle charging infrastructure buildout pace. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passenger Vehicles
Indonesia Passenger Car Market
Passenger Vehicles
Convertible Vehicles Market
Passenger Vehicles
India Automotive Market
Passenger Vehicles
Family Car Market
Passenger Vehicles
Lightweight Cars Market
Passenger Vehicles
Microcars Market
Passenger Vehicles
Minivans Market
Passenger Vehicles
Luxury Vehicles Market
Passenger Vehicles
Train Market
Passenger Vehicles
Limousines Market
Passenger Vehicles
Automotive Passenger Vehicle Sensor Market
Passenger Vehicles
Electric Passenger Car MRO Market
Passenger Vehicles
Solar Passenger Car Market
Passenger Vehicles
Electric Sports Car Market
Passenger Vehicles
Quadricycle and Tricycle Market
Passenger Vehicles
Large Suvs Market