
 Family Car Market | 2026-2036
Family Car Market Size, Share, and Industry Trends Forecast 2026-2036
Family Car Market Analysis
Japanese automaker production networks is rebalancing toward hybrid-dedicated platforms after years of pure-ICE dominance. Toyota anchors the hybrid segment through its Prius-derived architecture across multiple nameplates. Honda competes with integrated powertrain manufacturing that sustains cost discipline in mid-size SUVs. Subaru differentiates through standard all-wheel-drive configurations that occupy a defensible niche in northern-climate markets.
A family car denotes a passenger vehicle engineered to transport four or more occupants with emphasis on cabin volume, crashworthiness, and child-accommodation features such as LATCH anchor systems and multi-zone climate control. Structural segmentation reveals SUV variants lead volume due to elevated seating positions and perceived safety advantages, while electric powertrains represent the fastest-growing fuel category as battery costs decline and charging density improves. Five-star safety ratings command margin premiums in Europe and North America where consumer awareness of NCAP protocols has matured.
EPA fuel-economy standards and Euro 7 emissions limits are forcing powertrain portfolio redesigns across all major manufacturers. NHTSA crash-test protocols and the EU's General Safety Regulation mandate automatic emergency braking and lane-keeping systems as baseline equipment, reshaping technology feature bundling. Stakeholders must monitor how software-defined vehicle architectures alter safety system upgradability and long-term residual value calculations.
Market Dynamics
Powertrain electrification is compressing development cycles across the family car segment as manufacturers retool from pure-ICE architectures toward hybrid-dedicated platforms and battery-electric variants. This structural shift is forcing simultaneous compliance with tightening emissions protocols and recalibration of residual value models.
Growth Catalysts
- Euro 7 Emissions Standards:The European Union's incoming pollutant caps are mandating widespread hybridization and electrification, creating engineered demand for compliant powertrains across mid-size vehicle classes.
- Suburban Household Formation:Multiple-child families in outer metropolitan zones are prioritizing cabin volume and crashworthiness, concentrating purchases in SUV segments with elevated seating positions.
- Charging Infrastructure Buildout:Dense fast-charging networks in Germany, China, and the United States are reducing range anxiety and enabling battery-electric adoption among family buyers previously limited to ICE options.
Market Restraints
- Battery Mineral Concentration:Cobalt and lithium processing capacity concentrates in limited jurisdictions, exposing OEMs to supply disruption and price volatility in critical cell inputs.
- Semiconductor Fab Bottlenecks:Advanced node production for vehicle control systems remains concentrated among Taiwan-based foundries, constraining output scaling for safety-critical electronics.
- ICE Residual Value Collapse Risk:Accelerating electrification mandates in European cities are compressing secondary-market demand for pure-combustion family vehicles, threatening lease-end valuations.
Strategic Opportunities
- Software-Defined Vehicle Architectures:Over-the-air update capability for safety systems creates recurring revenue streams and extends vehicle functional lifecycles beyond traditional hardware cycles.
- Vehicle-to-Grid Integration:Bidirectional charging protocols enable family cars to serve as distributed storage assets, unlocking utility revenue participation for suburban households with solar installations.
- India's PLI Scheme for Auto:Production-linked incentives for advanced automotive technology manufacturing are attracting component localization investments targeting price-sensitive family segments.
Industry Challenges
- Functional Safety Certification:ISO 26262 compliance for automated driving systems requires specialized embedded software engineering talent that remains scarce across Tier-1 suppliers.
- Legacy Platform Integration:Hybrid powertrain packaging within existing vehicle architectures demands thermal management redesigns that compress engineering timelines and strain supplier coordination.
- Homologation Timeline Compression:Simultaneous validation against diverging NHTSA, Euro NCAP, and China-NCAP protocols is extending pre-launch certification cycles and delaying regional market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Family Car Market |
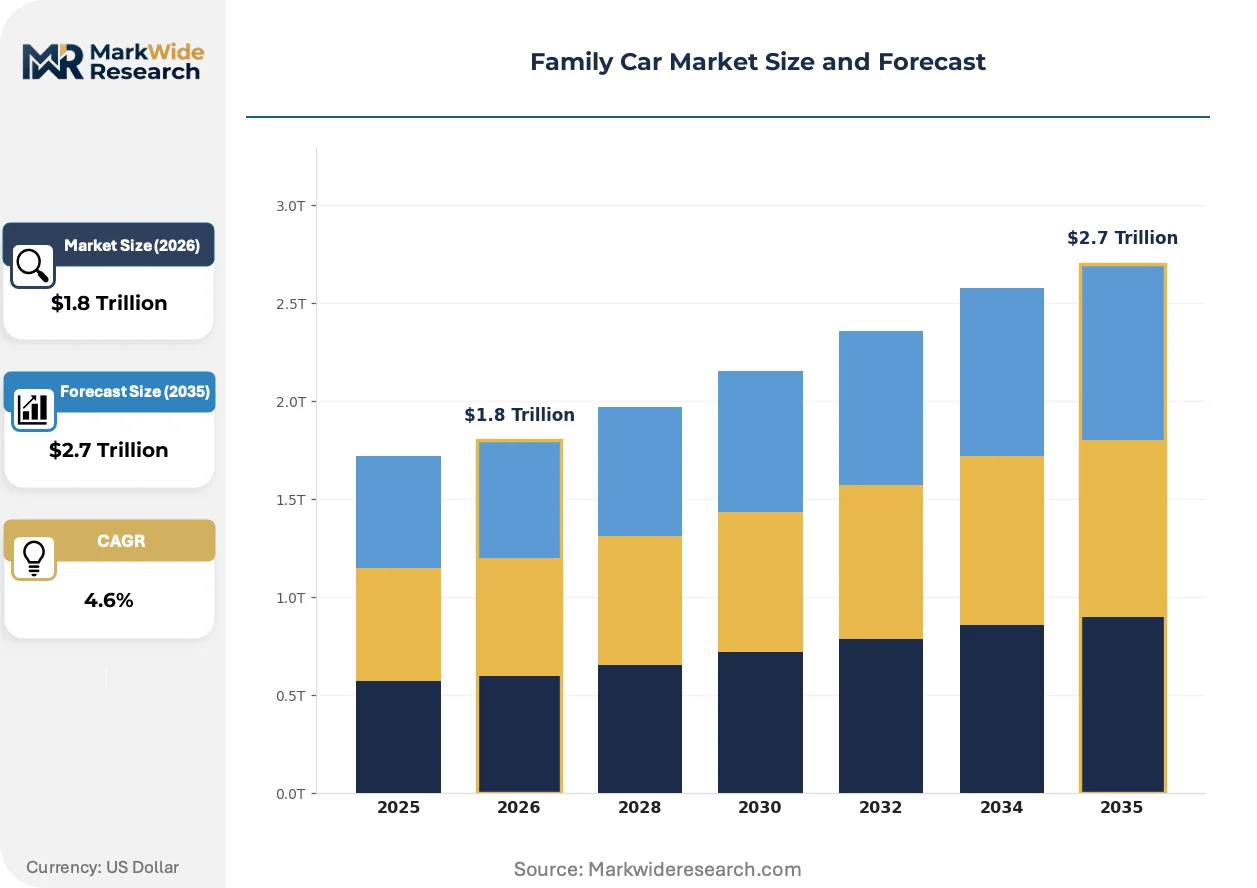
| Market Size in 2026 | $1.8 Trillion |
| Market Size in 2035 | $2.7 Trillion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: SUV, Minivan, Hatchback, Station Wagon Fuel Type: Petrol, Diesel, Electric, Hybrid Safety Rating: 5-Star, 4-Star, 3-Star, 2-Star Technology Features: Adaptive Cruise Control, Lane Assist, Infotainment System, Parking Assistance |
| Companies Covered | Volvo, Nissan, Honda, Subaru, Ford, Hyundai, Kia, Chevrolet, Toyota, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Family Car Market Emerging Trajectories
Intelligent cabin systems are redefining family vehicle value propositions as occupant monitoring and predictive safety features migrate from premium segments to mass-market nameplates. These technologies are compressing traditional equipment-grade hierarchies.
Advanced driver-assistance systems (ADAS) are automating longitudinal and lateral vehicle control in highway environments, reducing driver workload during family road trips. Mid-size SUV buyers in North America and Europe are specifying these features at penetration rates previously seen only in luxury segments. The technology is automating the standard equipment list across price tiers and compressing the premium commanded by early-mover brands.
EPA Tier 3 and Euro 7 tailpipe regulations are forcing powertrain portfolio diversification toward PHEV and BEV architectures with multi-hundred-mile electric ranges. Manufacturers are consolidating engineering resources onto dedicated electrified platforms rather than adapting legacy ICE underpinnings. The United States and Germany are experiencing the most acute compliance-driven product cycle acceleration as both jurisdictions phase in stringent fleet-average standards.
Subscription-based feature activation is displacing traditional trim-level bundling as buyers seek post-purchase flexibility for heated seats, advanced navigation, and driver-assistance upgrades. Direct-to-consumer digital sales channels in China and select European markets are enabling this unbundling by establishing persistent vehicle connectivity. Younger family buyers in urban China are demonstrating highest willingness to pay recurring fees for software-enabled convenience features versus upfront hardware purchases.
Family Car Market Segmentation
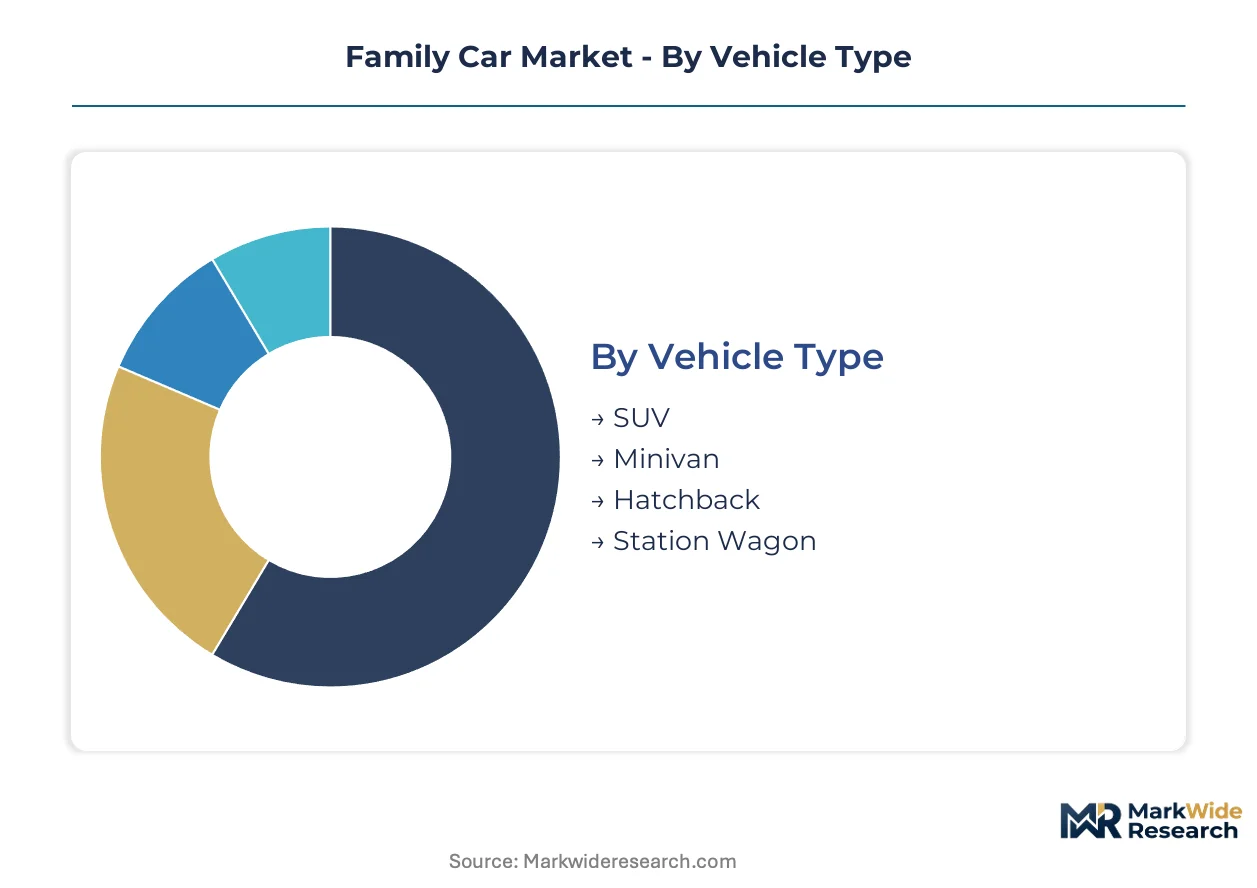
Structural segmentation in the family car market determines homologation pathways, feature bundling strategies, and regional market entry sequencing. Each dimension carries distinct certification burdens that reshape manufacturer portfolio priorities and pricing architecture.
Vehicle Type:
SUV variants face the most demanding Euro NCAP and NHTSA structural integrity protocols due to elevated mass and rollover risk profiles, while minivans must satisfy specialized child-occupant protection standards.
- SUV:Elevated seating positions and reinforced cabin structures dominate suburban household purchases across the United States, China, and Germany. Five-star safety ratings command margin premiums in these markets where NCAP protocol awareness has matured among buyers with multiple children.
- Minivan:Sliding door configurations and flat-load floors optimize child-accommodation features including LATCH anchor density and third-row accessibility. Demand concentrates in North American outer metropolitan zones where three-child families prioritize cabin volume over driving dynamics.
- Hatchback:Compact footprints suit European urban centers with congestion charging and restricted parking.
- Station Wagon:Extended rooflines retain cargo utility in markets where SUV taxation disadvantages apply.
SUV sits at the top of the volume ranking, with electric powertrains climbing the fastest across all vehicle type categories.
Fuel Type:
Powertrain selection dictates emissions compliance trajectories under EPA Tier 3 and Euro 7 frameworks, with each fuel category requiring distinct validation cycles and supplier ecosystems.
- Electric:Battery-electric architectures with multi-hundred-mile ranges are gaining share fastest in Germany, China, and the United States as charging density improves and cobalt-lithium cell costs decline. NHTSA and Euro NCAP protocols now include specialized high-voltage safety assessments for thermal runaway protection.
- Hybrid:Toyota's Prius-derived architecture and Honda's integrated powertrain manufacturing anchor mid-size SUV offerings with cost discipline. These systems satisfy Euro 7 interim targets without full infrastructure dependency.
- Petrol:Pure-combustion variants face residual value compression risk in European cities with electrification mandates.
- Diesel:Compression-ignition powertrains retain niche utility in high-torque towing applications.
Hybrid systems capture the largest installed base, while battery-electric variants show the steepest expansion trajectory among family buyer cohorts.
Safety Rating:
Star classification under NCAP protocols directly determines market access eligibility and insurance premium differentials across developed automotive markets.
- 5-Star:Maximum structural integrity and active safety system performance mandatory for premium positioning in Europe and North America. Automatic emergency braking and lane-keeping systems are baseline equipment requirements under EU General Safety Regulation and NHTSA protocols.
- 4-Star:Acceptable occupant protection with minor penalty point deductions in specific test modes. Volume manufacturers target this threshold for price-sensitive segments while reserving 5-star engineering for flagship nameplates.
- 3-Star:Marginal protection levels acceptable only in emerging markets without mature NCAP adoption.
- 2-Star:Minimal compliance with baseline regulatory requirements.
5-Star ratings dominate revenue concentration, with 4-Star variants retaining volume significance in emerging market entry strategies.
Technology Features:
Software-defined vehicle architectures are unbundling traditional trim hierarchies, with over-the-air update capability extending functional lifecycles beyond hardware replacement cycles.
- Adaptive Cruise Control:Longitudinal automation reduces driver workload during extended family road trips. Penetration rates in North American mid-size SUVs now match luxury segment adoption curves from prior product cycles.
- Lane Assist:Lateral control automation mandatory under EU General Safety Regulation for new type approvals. ISO 26262 functional safety certification requirements constrain supplier base concentration.
- Infotainment System:Persistent connectivity enables subscription-based feature activation in China and select European markets.
- Parking Assistance:Automated maneuvering addresses urban space constraints in dense metropolitan environments.
Infotainment systems generate the highest recurring revenue attachment, with adaptive cruise control expanding most quickly into standard equipment lists.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's suburban household formation outpaces Germany's electrification infrastructure buildout, while the United States combines both dynamics with distinct regulatory pressures. Each geography shapes family car demand through divergent policy instruments and demographic concentrations.
United States
Three-child families in outer metropolitan zones prioritize cabin volume and crashworthiness, concentrating purchases in SUV segments. NHTSA mandates automatic emergency braking and lane-keeping systems as baseline equipment under updated crash-test protocols. Detroit-Warren-Dearborn anchors domestic production networks retooled toward hybrid-dedicated platforms.
China
Urban households with multiple children drive demand for intelligent cabin systems and predictive safety features in mid-size vehicles. MIIT dual carbon goals accelerate battery-electric adoption through charging density improvements in coastal provinces. Yangtze River Delta manufacturing clusters specialize in cobalt-lithium cell integration for export-qualified nameplates.
Germany
Five-star NCAP ratings command margin premiums among safety-conscious buyers with elevated electrification expectations. KBA enforces Euro 7 interim targets that mandate widespread hybridization across mid-size classes. Bavaria hosts engineering centers consolidating resources onto dedicated electrified platforms rather than legacy ICE adaptations.
Japan
Integrated powertrain manufacturing sustains cost discipline in hybrid SUV offerings for northern-climate markets. METI standards guide thermal management redesigns for legacy platform integration. Nagoya-Toyota industrial corridor concentrates supplier coordination for functional safety certification under ISO 26262 protocols.
India
Price-sensitive family segments attract component localization investments under PLI scheme incentives for advanced automotive technology. BIS homologation requirements extend pre-launch certification cycles for multi-market nameplates. Tamil Nadu and Gujarat clusters target export manufacturing for emerging market entry strategies.
Family Car Market Vendor Landscape
Japanese producers anchor the hybrid-dedicated tier; European specialists hold positions in electrified safety systems. The vendor base concentrates around consolidated platform architectures with limited pure-play entrants. Three archetypes dominate: integrated powertrain manufacturers, software-defined vehicle architects, and standard all-wheel-drive configurators. Capacity expansion and strategic partnerships constitute the dominant competitive moves as engineering timelines compress.
Within the integrated powertrain tier, Toyota Motor Corporation and Honda Motor Co., Ltd. exemplify cost discipline through captive hybrid architecture deployment. Hyundai Motor Company occupies a position bridging scale manufacturing with rapid electrification transitions. Each represents distinct geographic production gravity—Japanese operational heritage versus Korean platform flexibility—without asserting specific market share claims.
| Leading Market Players |
|---|
| Volvo |
| Nissan |
| Honda |
| Subaru |
| Ford |
| Hyundai |
| Kia |
| Chevrolet |
| Toyota |
| Others |
Supply Flow & Price Mechanics
Suburban households with multiple children concentrate purchasing power in SUV segments with five-star safety ratings, anchoring a three-tier pricing structure across premium, standard, and economy levels where certification grades and electrification content drive differentiation.
Pricing Analysis
Capacity additions in South Korea and China are reshaping price floors for battery-electric family vehicles as cell manufacturing scales. Pricing stratifies across premium, standard, and economy tiers based on NCAP certification level and powertrain architecture, with hybrid systems commanding mid-tier positioning. Cost compression in pure-combustion variants is intensifying because Euro 7 compliance investments erode margins. Fleet buyers exhibit highest price sensitivity, while safety-conscious suburban households show lowest elasticity for five-star rated electrified SUVs.
Supply Chain Analysis
End-of-life battery refurbishment flows and powertrain remanufacturing networks are emerging as critical reverse-logistics capabilities for electrified family vehicles. Cobalt and lithium processing concentrates in the Democratic Republic of Congo, Chile, and Australia, while semiconductor fabrication for safety-critical systems draws from Taiwan, South Korea, and the United States. Single-source vulnerability in advanced-node chip supply threatens production scaling for automated driving features. Distribution runs through OEM captive networks and authorized dealer channels with increasing direct-to-consumer digital penetration in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where Euro 7 emissions caps and NHTSA safety mandates are accelerating powertrain portfolio redesigns and reshaping competitive positioning across all manufacturer tiers.
For Market Incumbents: Hedge against ICE residual value collapse by accelerating hybrid-dedicated platform deployment and securing long-term cobalt-lithium offtake agreements. Consolidate engineering resources onto scalable electrified architectures rather than adapting legacy ICE underpinnings. Channel control through subscription-based feature activation creates recurring revenue streams that offset hardware margin pressure.
For New Entrants and Emerging Players: The price-point gap between premium five-star electrified SUVs and economy-tier pure-combustion hatchbacks offers white-space opportunity in mid-market hybrid SUVs with standard safety equipment. Target India's price-sensitive family segments through component localization under PLI scheme incentives. Pursue direct-to-consumer digital sales channels with persistent vehicle connectivity to enable post-purchase feature monetization.
For Investors and Strategic Acquirers: Integrated powertrain manufacturers with captive hybrid architecture capabilities are the most active acquirer in this space, seeking software-defined vehicle competencies to extend functional lifecycles. Long-term viability favors platform-agnostic engineering houses with ISO 26262 functional safety certification and bidirectional charging protocol expertise. Monitor homologation timeline compression across diverging NCAP protocols as an inflection indicator for regional market entry sequencing.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Consolidated electrified architectures reduce engineering timelines and supplier coordination burdens under Euro 7. |
| Battery Supply Agreement | Long-term cobalt-lithium offtakes insulate OEMs from mineral price volatility and processing concentration risk. |
| Software-Defined Vehicle Investment | Over-the-air update capability for safety systems extends functional lifecycles beyond traditional hardware replacement cycles. |
| Geographic Manufacturing Footprint | Tamil Nadu and Gujarat clusters in India enable export manufacturing for emerging market entry strategies under PLI incentives. |
| Charging Infrastructure Partnership | Bidirectional charging protocols unlock vehicle-to-grid revenue participation for suburban households with solar installations. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with OEM platform engineers, Tier 1 supplier procurement leads, dealership operations heads, and charging infrastructure developers with secondary validation against vehicle production databases, IHS Markit registration data, EPA fuel-economy filings, and Euro NCAP test protocols. Bottom-up segment sizing and top-down macroeconomic triangulation cross-checked volume and value estimates.
Segment-weighting approaches modeled vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster dimensions across the projection horizon. CAGRs were derived from regression analysis of historical adoption curves and policy-driven demand inflections, incorporating battery cost decline trajectories and charging density buildout schedules as key forecast inputs.
Caveats apply where semiconductor fab bottlenecks, battery mineral supply disruptions, or divergent homologation timeline extensions could materially shift the outlook. Practitioners should monitor NHTSA and KBA regulatory announcements, Taiwan foundry utilization rates, and cobalt-lithium spot price movements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passenger Vehicles
Solar Passenger Car Market
Passenger Vehicles
Inland Water Passenger Transport Market
Passenger Vehicles
Medium Cars Market
Passenger Vehicles
North America Automotive Market
Passenger Vehicles
Electric Passenger Car MRO Market
Passenger Vehicles
Europe Luxury Car Market
Passenger Vehicles
Luxury Vehicles Market
Passenger Vehicles
Passenger Vehicle Market
Passenger Vehicles
Three-Wheeler Vehicle Market
Passenger Vehicles
Sports Utility Vehicles (Suvs) Market
Passenger Vehicles
North America MUV Rental Market
Passenger Vehicles
India Luxury Car Market
Passenger Vehicles
Train Seat Market
Passenger Vehicles
Small Suvs Market
Passenger Vehicles
Wheelchair Accessible Vehicle Market
Passenger Vehicles
Train Market