
 Large Suvs Market | 2026-2036
Large Suvs Market Size, Share, and Industry Trends Forecast 2026-2036
Large Suvs Market Intelligence
The gap between premium and commodity tiers is expanding in concrete terms. Chevrolet leverages its manufacturing scale to dominate the full-size truck-based SUV segment, while Cadillac differentiates through advanced cabin technology and bespoke powertrain options. Toyota anchors its position with hybrid reliability, and Ford competes by extending its electric architecture into three-row platforms.
Large SUVs are passenger vehicles exceeding 5,100 mm in length with body-on-frame or unibody construction, three-row seating capacity, and towing ratings above 3,500 kg, designed primarily for family transportation, commercial fleet duty, and recreational hauling. Luxury SUVs command the highest margin pools as buyers prioritize premium materials and advanced driver-assistance systems, while electric powertrains represent the fastest-growing fuel type segment as battery costs decline and charging infrastructure proliferates. Adventure Seekers and Corporate Users drive divergent demand patterns, with the former emphasizing off-road capability and the latter prioritizing total cost of ownership and connectivity integration.
NHTSA crashworthiness standards and EPA Corporate Average Fuel Economy rules shape product engineering timelines and powertrain portfolios for US-market manufacturers, while the EU's CO2 fleet targets and China's dual carbon goals restrict pure combustion engine offerings in those jurisdictions. Stakeholders must monitor how battery supply constraints and raw material cost volatility affect electric large SUV profitability and production scheduling across multiple regulatory environments.
Market Dynamics
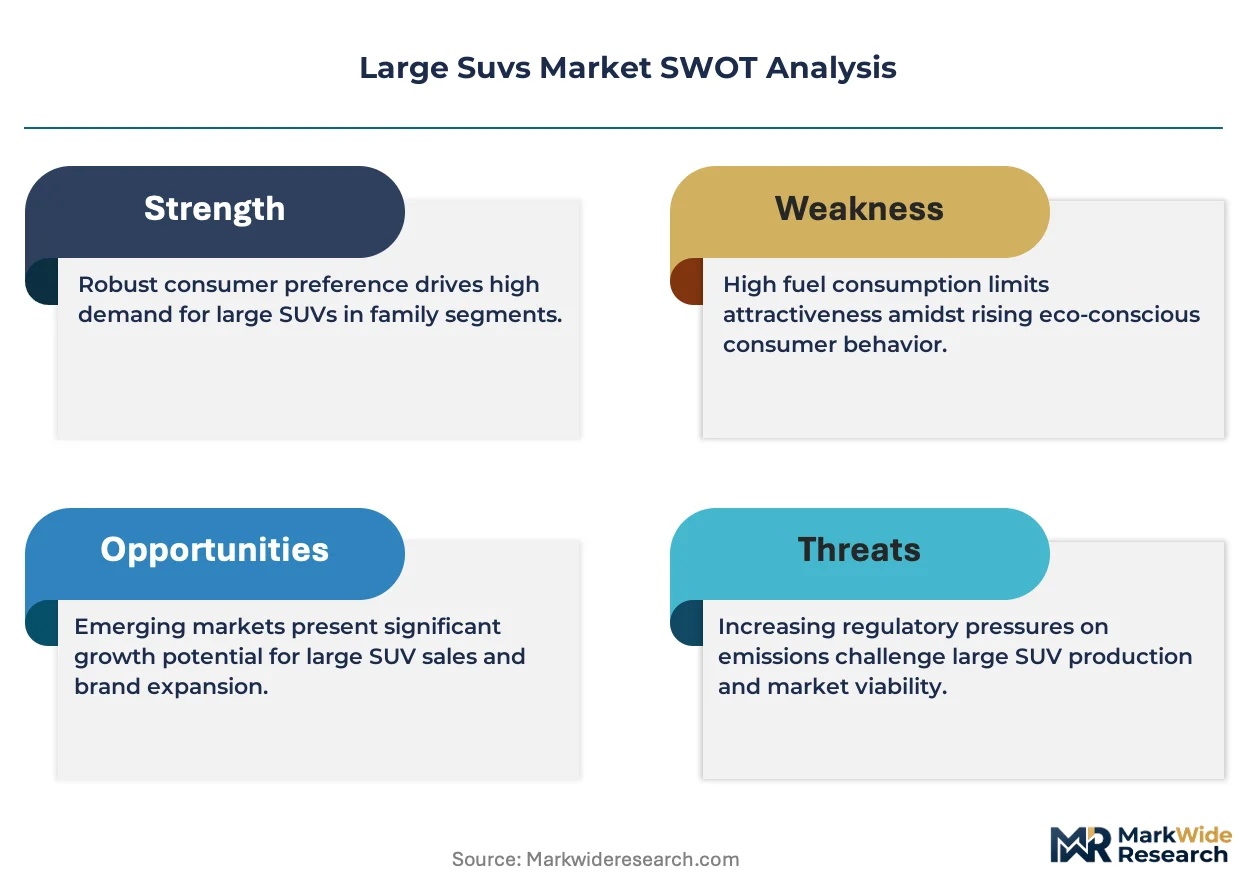
The US EPA Corporate Average Fuel Economy standards and the EU's CO2 fleet targets are forcing powertrain diversification across the Large SUVs Market, compressing engineering timelines while expanding R&D budgets for hybrid and electric architectures.
Growth Catalysts
- EPA Fuel-Economy Standards:US manufacturers accelerate hybrid powertrain development to meet fleet-wide efficiency mandates, expanding three-row SUV electrification portfolios.
- Adventure Seeker Segment:Recreational buyers prioritize towing capacity and off-road capability, sustaining demand for body-on-frame platforms with advanced four-wheel-drive systems.
- Battery Cost Decline:Lithium-ion pack prices drop below threshold levels, enabling electric large SUV production at competitive manufacturing cost structures.
Market Restraints
- Lithium Supply Concentration:Raw material processing concentrates in China and Chile, exposing battery supply chains to geopolitical friction and export restriction risk.
- Charging Infrastructure Gaps:Rural and ex-urban corridors in the United States and Australia lack high-capacity DC fast-charging networks, limiting electric large SUV adoption outside metropolitan clusters.
- Body-on-Frame Weight Penalty:Traditional truck architectures impose mass disadvantages that degrade electric range performance, constraining platform choices for zero-emission variants.
Strategic Opportunities
- India Fleet Electrification:Corporate mobility providers in Mumbai and Delhi expand procurement of hybrid large SUVs under tightening BIS efficiency norms and ESG disclosure requirements.
- Vehicle-to-Load Integration:Bidirectional charging technology converges with camping and worksite power needs, creating new value propositions for adventure and commercial buyers.
- EU Green Deal Incentives:Member state purchase subsidies and fleet electrification mandates accelerate zero-emission large SUV adoption in Germany, France, and the Netherlands.
Industry Challenges
- Software-Hardware Integration Complexity:Advanced driver-assistance systems require seamless coordination between sensor arrays and legacy chassis electronics, extending validation cycles.
- Battery Thermal Management Certification:UN ECE R100 and FMVSS 305 compliance testing for large-format packs demands specialized facilities and extended timeline resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Large Suvs Market |
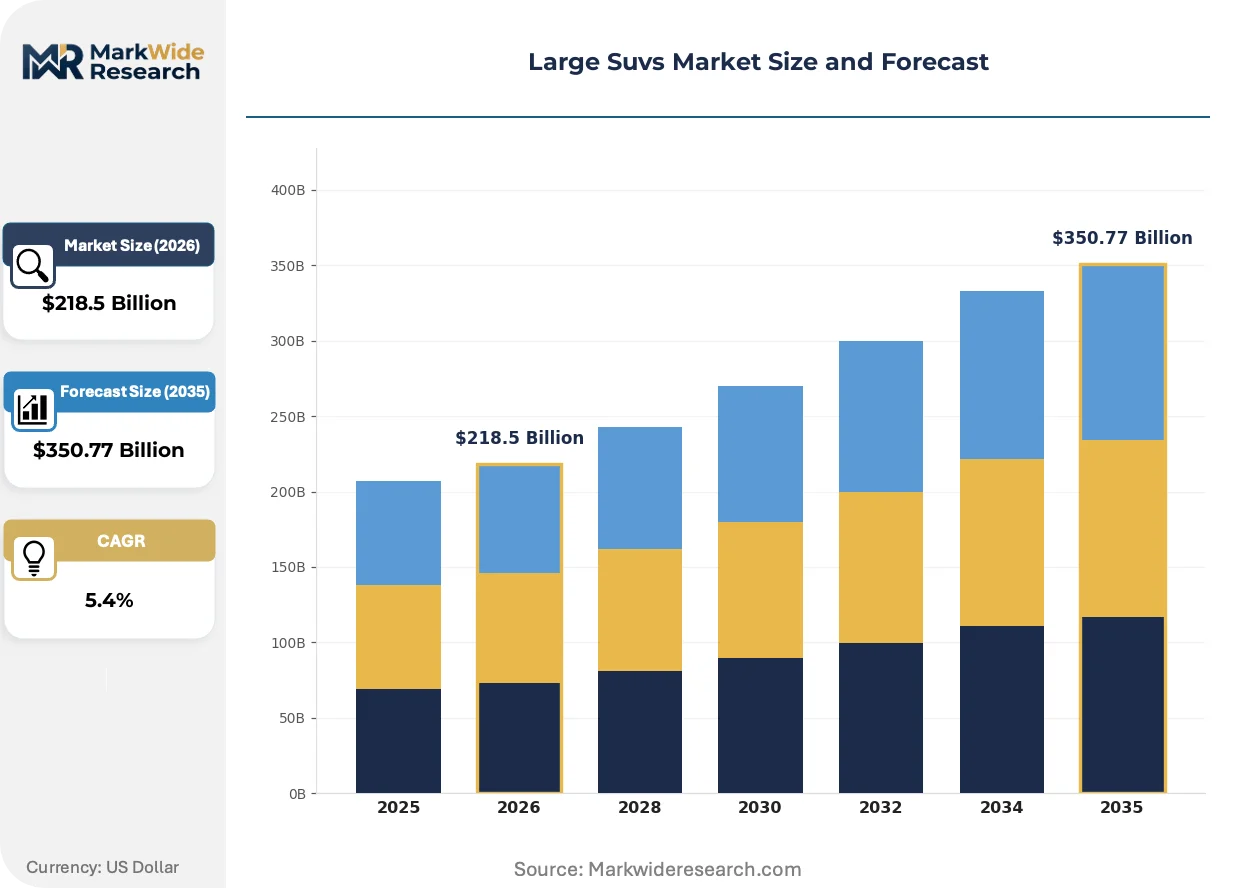
| Market Size in 2026 | $218.5 Billion |
| Market Size in 2035 | $350.77 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Luxury Suvs, Performance Suvs, Compact Suvs, Crossover Suvs End User: Families, Adventure Seekers, Corporate Users, Rental Services Fuel Type: Petrol, Diesel, Hybrid, Electric Technology: Infotainment Systems, Safety Features, Connectivity Options, Autonomous Driving |
| Companies Covered | Chevrolet, GMC, Ford, Jeep, Toyota, Nissan, Cadillac, Lincoln, Hyundai, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Large Suvs Market Strategic Shifts & Innovations
Powertrain electrification is fragmenting competitive advantage away from traditional engine manufacturing scale toward battery chemistry control and software-defined vehicle architectures.
Cell-to-pack battery architecture is decentralizing thermal management responsibility from module-level to pack-level systems, reducing component count and assembly complexity. Tier 1 suppliers in South Korea and Japan adopt this approach for North American OEM programs. The technology is decentralizing manufacturing location flexibility, enabling pack assembly closer to final vehicle plants.
The EU's F-Gas Regulation restricts refrigerant global warming potential in automotive climate systems, mandating transition to CO2-based heat pumps. European manufacturers redesign HVAC architectures for large SUVs to accommodate transcritical cycle operation. German and Swedish premium brands face compressed certification timelines for 2027 model year compliance.
Fleet procurement managers now specify total cost of ownership metrics over upfront vehicle price, embedding residual value forecasting and charging infrastructure access into acquisition decisions. Rental and corporate fleet channels in the United States and United Kingdom rewrite supplier scorecards around these parameters. This behavioral shift favors manufacturers with demonstrated battery durability data and expansive service networks.
Large Suvs Market Segmentation
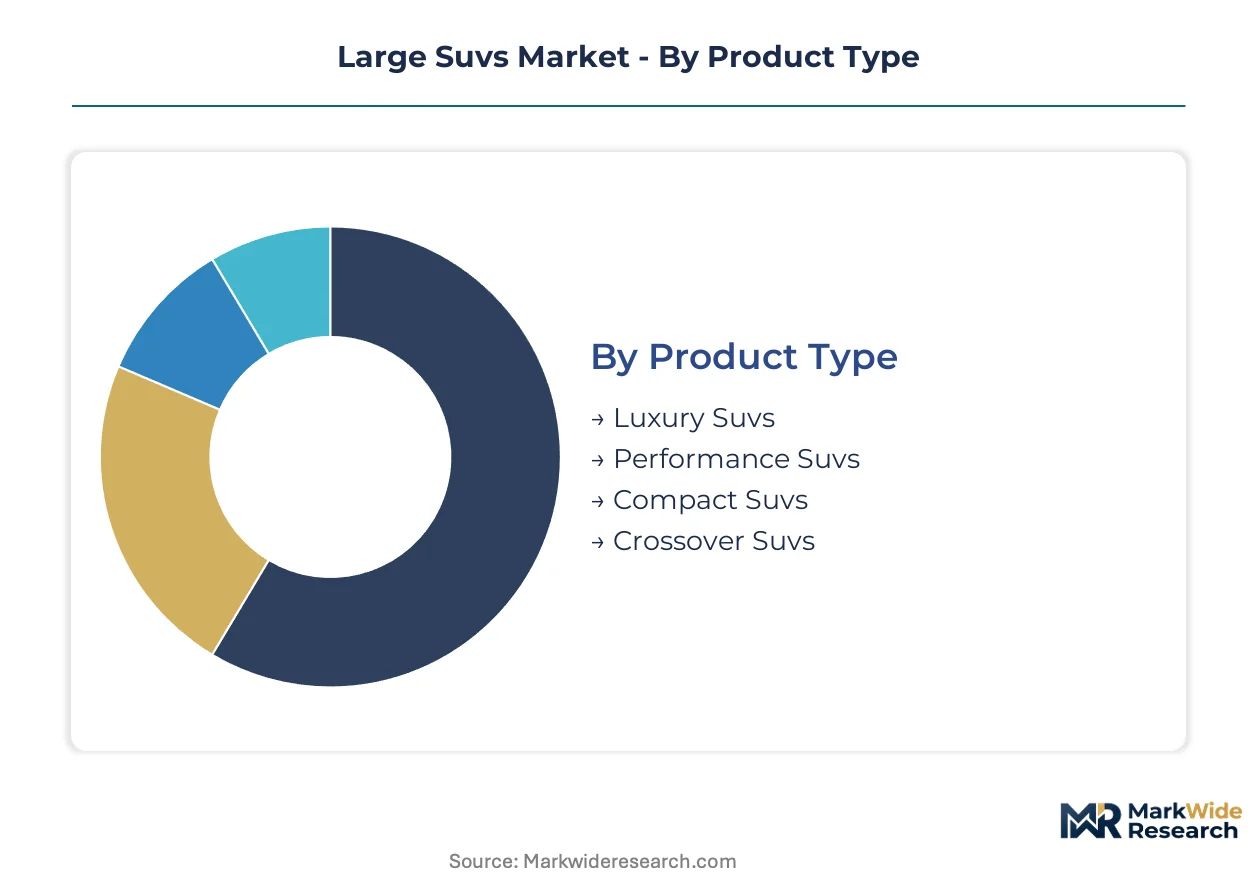
Large SUVs serve divergent user profiles that demand fundamentally different engineering priorities. Segmentation reveals how powertrain choices, cabin configurations, and technology stacks must align with distinct buyer economics and use patterns.
Product Type:
Volume concentration sits in accessible tiers while premium segments extract disproportionate margin through specification differentiation.
- Luxury SUVs:These vehicles integrate bespoke interior materials, adaptive air suspension, and configurable ambient environments. Demand clusters in Germany and the United Arab Emirates where buyers prioritize craftsmanship and advanced driver-assistance suites.
- Performance SUVs:High-output powertrains and track-capable chassis tuning define this segment. The category climbs fastest as affluent buyers in South Korea and Switzerland seek sports-car acceleration with three-row practicality.
- Compact SUVs:Smaller footprints with five-seat configurations serve urban mobility needs.
- Crossover SUVs:Unibody construction blends car-like handling with elevated seating positions for suburban buyers.
Today's leader: Luxury SUVs. Tomorrow's challenger: Performance SUVs.
End User:
Application context determines whether towing capacity or total cost of ownership dominates the purchase calculus.
- Families:Safety ratings and third-row accessibility drive selection. This segment concentrates in the United States and Australia where school-run distances and extracurricular logistics require maximum interior flexibility.
- Adventure Seekers:Off-road hardware and roof-load ratings matter most. Demand strengthens in Colorado and Queensland as recreational buyers prioritize trail-rated four-wheel-drive systems and integrated recovery points.
- Corporate Users:Fleet managers emphasize depreciation curves and connectivity integration.
- Rental Services:Turnaround speed and standardized maintenance protocols shape procurement.
The installed base favors family configurations. The growth edge belongs to adventure positioning.
Fuel Type:
Regulatory pressure is fragmenting the combustion-dominant past into a diversified powertrain present.
- Hybrid:Dual-powertrain architectures deliver efficiency without range anxiety. Toyota's reliability data and EPA compliance credits sustain expansion across California and Texas fleet channels.
- Electric:Battery-electric platforms eliminate tailpipe emissions entirely. Norway and the Netherlands accelerate adoption through purchase-tax elimination and lane-access privileges.
- Petrol:Conventional internal combustion remains prevalent in price-sensitive markets.
- Diesel:Torque-rich powertrains retain towing customers despite emissions scrutiny.
Hybrid holds current volume. Electric captures the steepest expansion trajectory.
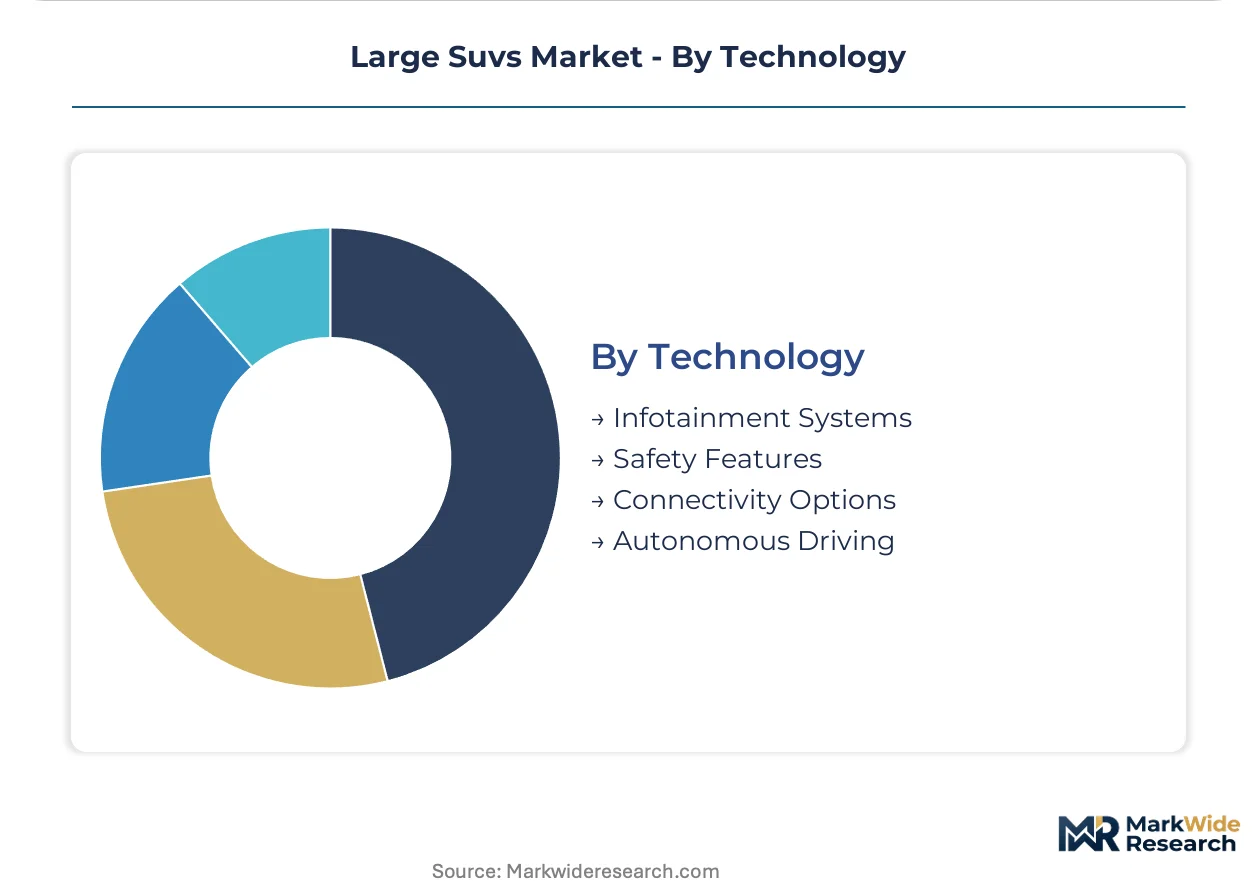
Technology:
Software-defined features are displacing hardware differentiation as the primary value lever.
- Infotainment Systems:Large-format touchscreens and over-the-air update capability define cabin experience. German premium brands and South Korean suppliers compete on processor speed and voice-recognition accuracy.
- Safety Features:Automatic emergency braking and blind-spot monitoring approach standard equipment. NHTSA and Euro NCAP testing protocols accelerate mandate timelines across US and EU markets.
- Connectivity Options:5G modems and Wi-Fi hotspot functionality enable fleet telematics.
- Autonomous Driving:Highway-assist features reduce driver workload on long-distance routes.
Safety features dominate current specification sheets. Autonomous capability shapes tomorrow's competitive frontier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent clusters in Detroit, Stuttgart, and Seoul anchor the Large SUVs Market's product development pipelines. These concentrations shape powertrain portfolios and platform architectures across distinct regulatory environments.
United States
Three-row family configurations dominate suburban and ex-urban demand across Texas and Florida. NHTSA crashworthiness standards and EPA Corporate Average Fuel Economy rules compress engineering timelines for Detroit-based manufacturers. Michigan's automotive corridor concentrates hybrid powertrain development programs for full-size truck platforms.
China
Affluent buyers in Shanghai and Beijing prioritize premium electric large SUVs with advanced driver-assistance suites. MIIT new-energy vehicle mandates and dual carbon goals accelerate zero-emission powertrain adoption. Yangtze River Delta manufacturing clusters scale battery pack assembly for domestic OEM programs.
Germany
Performance-oriented buyers in Munich and Stuttgart seek high-output powertrains with track-capable chassis tuning. KBA type-approval processes and EU CO2 fleet targets force powertrain diversification across Baden-Württemberg engineering centers. Bavarian premium brands redesign HVAC architectures for F-Gas Regulation compliance.
South Korea
Technology-focused consumers in Seoul and Busan demand configurable cabin environments with over-the-air update capability. MFDS automotive safety standards and national hydrogen economy roadmaps influence powertrain investment priorities. Ulsan manufacturing complexes integrate cell-to-pack battery architectures for export programs.
India
Corporate fleet operators in Mumbai and Delhi expand hybrid large SUV procurement under tightening mobility mandates. BIS efficiency norms and SEBI ESG disclosure requirements reshape acquisition scorecards for rental services. Tamil Nadu automotive clusters assemble three-row platforms for domestic and export markets.
Large Suvs Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the Large SUVs Market's tiered structure. Full-line manufacturers with captive powertrain foundries dominate volume segments while premium specialists extract margin through specification differentiation. Three archetypes anchor competitive positioning: Detroit-based truck-platform scale players, Japanese hybrid reliability specialists, and German premium technology integrators. Dominant competitive moves include portfolio electrification and platform architecture licensing to spread R&D costs.
Within the scale-driven tier, Chevrolet and Ford occupy positions anchored by manufacturing breadth and truck-platform heritage. Toyota exemplifies the hybrid reliability archetype with powertrain durability data sustaining fleet channel penetration. Cadillac represents the premium technology vector through advanced cabin differentiation and bespoke powertrain configurations.
| Leading Market Players |
|---|
| Chevrolet |
| GMC |
| Ford |
| Jeep |
| Toyota |
| Nissan |
| Cadillac |
| Lincoln |
| Hyundai |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap suppliers in Michigan and Ontario anchor the tiered supplier base for body-on-frame platforms, concentrating procurement leverage among Detroit-based OEMs while compressing margin pools for independent stamping and casting specialists.
Pricing Analysis
The bundled-vs-unbundled service split separates fleet procurement from retail transactions. Three-tier pricing structure across premium, standard, and economy levels reflects powertrain complexity and after-sales service bundling. Price differentiation rests on EPA compliance credits and residual value guarantees. Pricing pressure stems from lithium cost volatility in battery-electric variants. Corporate fleet buyers exhibit highest price sensitivity due to total cost of ownership mandates, while adventure-seeking retail customers prioritize capability over sticker price.
Supply Chain Analysis
Reverse-logistics flows for battery pack refurbishment and powertrain remanufacturing are concentrating in South Korea and Japan as cell-to-pack architectures enable modular replacement programs. Geographic supply concentration centers on China for lithium processing, South Korea for cathode materials, and Germany for precision chassis components. Raw material dependencies include lithium carbonate, high-strength steel, and semiconductor-grade silicon. Single-source vulnerability in Chinese lithium refining exposes margin stability to export restriction risk. Distribution runs through captive OEM logistics networks for fleet channels and franchised dealership systems for retail buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Large SUVs Market functions as a stable compounder where regulatory tailwinds for electrification sustain replacement demand across fleet and retail channels.
For Market Incumbents: Deploy platform standardization across ICE and electric architectures to spread R&D costs. Incumbent manufacturers must consolidate battery supply agreements with South Korean and Chinese cell producers to secure capacity ahead of fleet electrification mandates. Channel control through certified pre-owned programs defends residual value positioning against emerging direct-to-consumer entrants. For New Entrants and Emerging Players: The price-point gap between premium electric large SUVs and economy hybrid variants offers white-space entry. New entrants should target adventure-seeking retail segments in Colorado and Queensland where off-road capability commands brand loyalty. A software-defined vehicle architecture with over-the-air update capability enables feature monetization without hardware redesign. For Investors and Strategic Acquirers: Battery technology specialists are the most active acquirer in this space as OEMs seek vertical integration into cell chemistry control. Long-term viability favors manufacturers with demonstrated thermal management certification and expansive service networks. Acquisition targets should demonstrate cell-to-pack assembly expertise and UN ECE R100 compliance capability. Monitor EPA Corporate Average Fuel Economy credit pricing as an inflection indicator for hybrid versus electric investment allocation.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures lithium-ion cell capacity from South Korean producers for electric platform rollout. |
| Platform Standardization | Reduces engineering overhead by unifying body-on-frame architectures across powertrain variants. |
| Software-Defined Vehicle Investment | Enables over-the-air feature updates and subscription revenue streams through cabin technology. |
| Charging Infrastructure Partnership | Addresses rural DC fast-charging gaps limiting electric large SUV adoption outside metropolitan clusters. |
| Geographic Manufacturing Footprint | Localizes pack assembly near final vehicle plants to mitigate logistics cost and tariff exposure. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary research included conversations with OEM platform engineers, Tier 1 supplier procurement directors, fleet acquisition managers, and dealership operations heads. Secondary validation drew from EPA fuel-economy certification databases, NHTSA crashworthiness filings, vehicle production registries, and IHS Markit registration data. Bottom-up segment sizing and top-down macroeconomic triangulation converged on volume and value estimates.
Comparable historical periods anchored the projection framework across the analysis window. The analytical model segmented by vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs were derived from trend extrapolation moderated by regulatory phase-in schedules and battery cost decline curves. Forecast inputs included EPA compliance credit pricing trajectories and EU CO2 fleet target stringency paths.
Caveats apply where battery raw material export restrictions or charging infrastructure deployment delays could materially shift the outlook. Forecasts reflect assumptions about lithium supply chain stability and regulatory enforcement continuity. Practitioners should monitor EPA rulemaking timelines and EU F-Gas Regulation compliance deadlines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passenger Vehicles
Compact Cars Market
Passenger Vehicles
Solar Passenger Car Market
Passenger Vehicles
Asia Pacific Luxury Cars Market
Passenger Vehicles
Wheelchair Accessible Vehicle Market
Passenger Vehicles
Electric Passenger Car MRO Market
Passenger Vehicles
North America Automotive Market
Passenger Vehicles
Luxury Vehicles Market
Passenger Vehicles
North American Lightweight Car Market
Passenger Vehicles
Three-Wheeler Vehicle Market
Passenger Vehicles
Lightweight Cars Market
Passenger Vehicles
Global SUV Market
Passenger Vehicles
Limousines Market
Passenger Vehicles
Latin America Passenger Car Market
Passenger Vehicles
Global Luxury SUV Market
Passenger Vehicles
Microcars Market
Passenger Vehicles
India Passenger Car Market