
 Microcars Market | 2026-2036
Microcars Market Size, Share, and Industry Trends Forecast 2026-2036
Microcars Market Outlook
Urban commuters is collapsing as the dominant buyer archetype while small families gain share in multi-vehicle households seeking secondary runabouts. SAIC GM Wuling Automobile Co., Ltd. leverages its battery supply chain integration to dominate China's low-cost electric microcar tier. Suzuki Motor Corporation anchors the kei car tradition through dedicated R&D platforms optimized for Japan's unique regulatory envelope. Microlino AG specializes in retro-styled urban runabouts that differentiate on design rather than spec-sheet competition.
Microcars are motorized vehicles typically under 3.4 meters in length with engine displacements capped at 660cc in regulated markets, purpose-built for short-distance urban mobility and parking-constrained environments. Electric variants command the fastest expansion as lithium iron phosphate battery packs slash per-unit costs below internal-combustion equivalents. Gasoline microcars retain residual demand across Southeast Asian markets where charging infrastructure remains sparse. The four-seater configuration captures the broadest end-user base by accommodating small-family utility without sacrificing the parking advantages that define the category.
Japan's Ministry of Economy, Trade and Industry (METI) enforces kei car dimension and power caps that create a protected domestic segment insulated from standard vehicle competition. The European Union's F-Gas Regulation and CO2 fleet targets pressure OEMs toward zero-emission microcar portfolios for urban compliance credits. India's PLI scheme for automotive manufacturing incentivizes localized electric microcar assembly for price-sensitive entry buyers. Stakeholders must monitor how China's MIIT adjusts new energy vehicle subsidy thresholds as these rules determine which microcar formats remain economically viable at mass-market price points.
Market Dynamics
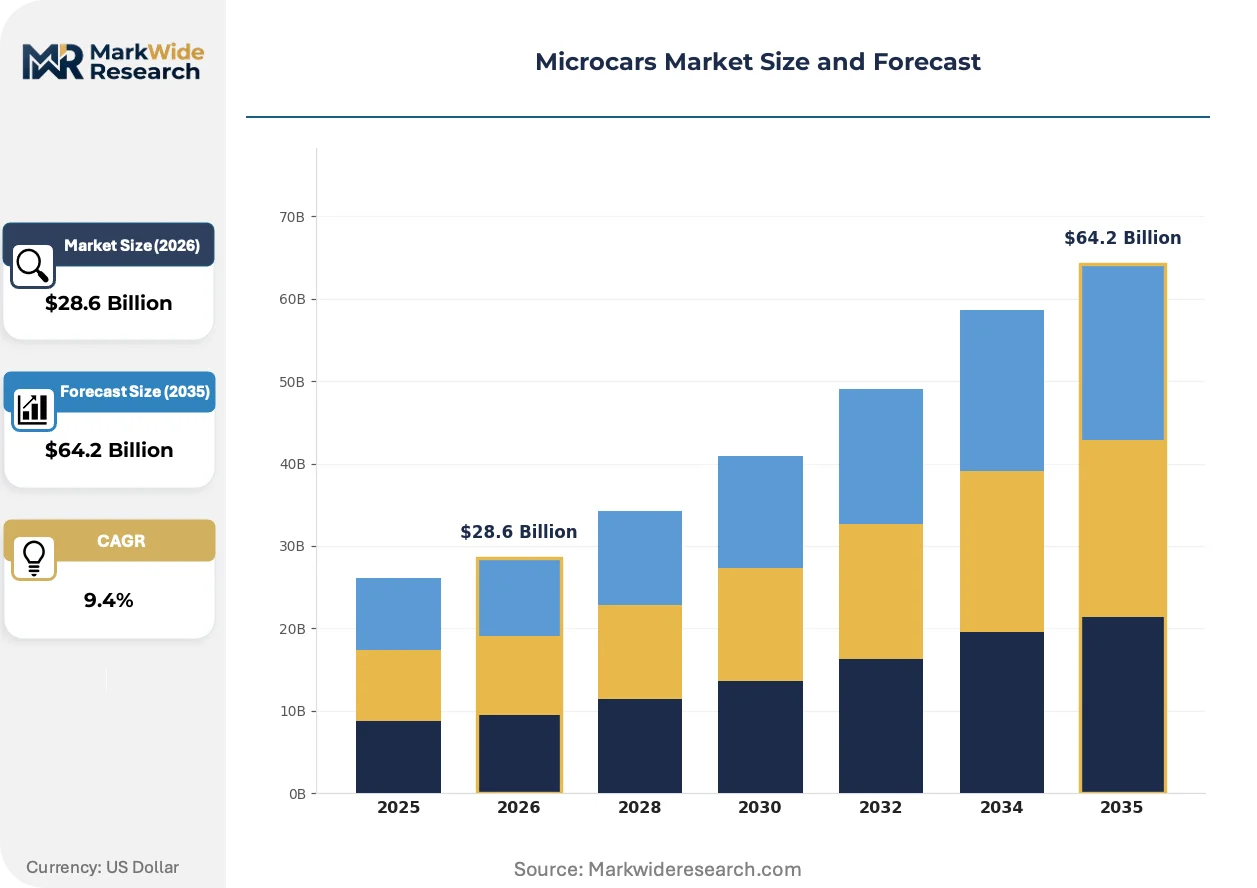
Battery platform standardization is compressing development costs while congestion charges in dense metropolitan zones accelerate electric microcar adoption among urban commuters seeking parking-constrained mobility solutions.
Growth Catalysts
- EU F-Gas Regulation:Fleet CO2 targets pressure OEMs toward zero-emission microcar portfolios for urban compliance credits.
- India PLI scheme:Localized electric microcar assembly receives manufacturing incentives for price-sensitive entry buyers.
- Lithium iron phosphate chemistry:Battery pack costs have fallen below internal-combustion equivalents, accelerating electric variant expansion.
Market Restraints
- Lithium supply concentration:Raw material processing clusters in limited geographies create input cost volatility for battery-dependent manufacturers.
- Southeast Asian infrastructure gap:Sparse charging networks preserve residual gasoline microcar demand, fragmenting platform investment returns.
- Kei car regulatory envelope:Japan's METI dimension caps insulate domestic producers but prevent scale economies from cross-border standardization.
Strategic Opportunities
- China MIIT subsidy adjustments:Threshold revisions will determine which microcar formats retain economic viability at mass-market price points.
- Multi-vehicle household penetration:Small families in dense cities seek secondary runabouts, displacing single-vehicle commuter archetypes.
- Retro-styled urban runabouts:Design differentiation commands premium positioning outside spec-sheet competition in European city centers.
Industry Challenges
- Kei car R&D platform specialization:Dedicated engineering for Japan's unique regulatory envelope consumes capital without transferable IP to other markets.
- Supply chain reconfiguration:Battery supply chain integration demands upstream control over cell production, squeezing capital-light assemblers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microcars Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $64.2 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Hybrid, Gasoline, Diesel End User: Urban Commuters, Students, Retirees, Small Families Vehicle Size: Two-Seater, Four-Seater, Compact, Lightweight Distribution Channel: Direct Sales, Online Retail, Dealerships, Rental Services |
| Companies Covered | SAIC GM Wuling Automobile Co., Ltd., Suzuki Motor Corporation, Ligier Group, Microlino AG, Honda Motor Co., Ltd., Aixam-Mega, BYD Auto Co., Ltd., Eli Electric Vehicles, Stellantis N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microcars Market Strategic Shifts
Urban mobility electrification is fragmenting along battery chemistry lines while regulatory pressure and household vehicle economics reshape competitive positioning across metropolitan clusters.
Lithium iron phosphate battery technology is bifurcating the powertrain landscape. Urban fleet operators and multi-vehicle households are adopting LFP packs for their thermal stability and cycle longevity. The chemistry divide is compressing cobalt-dependent supply chains while enabling sub-3-meter vehicle formats previously uneconomical at mass-market price points.
Japan's METI enforces kei car dimension and power caps that create a protected domestic segment. This regulatory insulation preserves dedicated R&D platforms optimized for 660cc displacement limits. Domestic producers respond by deepening kei-specific engineering rather than pursuing exportable architectures.
Secondary runabout purchasing is displacing primary commuter vehicle decisions in dense European and Japanese metropolitan zones. Small families in multi-car households now evaluate microcars against public transit season tickets and ride-hailing subscriptions. This behavioral pivot concentrates demand in four-seater configurations that preserve parking advantages while accommodating intermittent family utility.
Microcars Market Segmentation
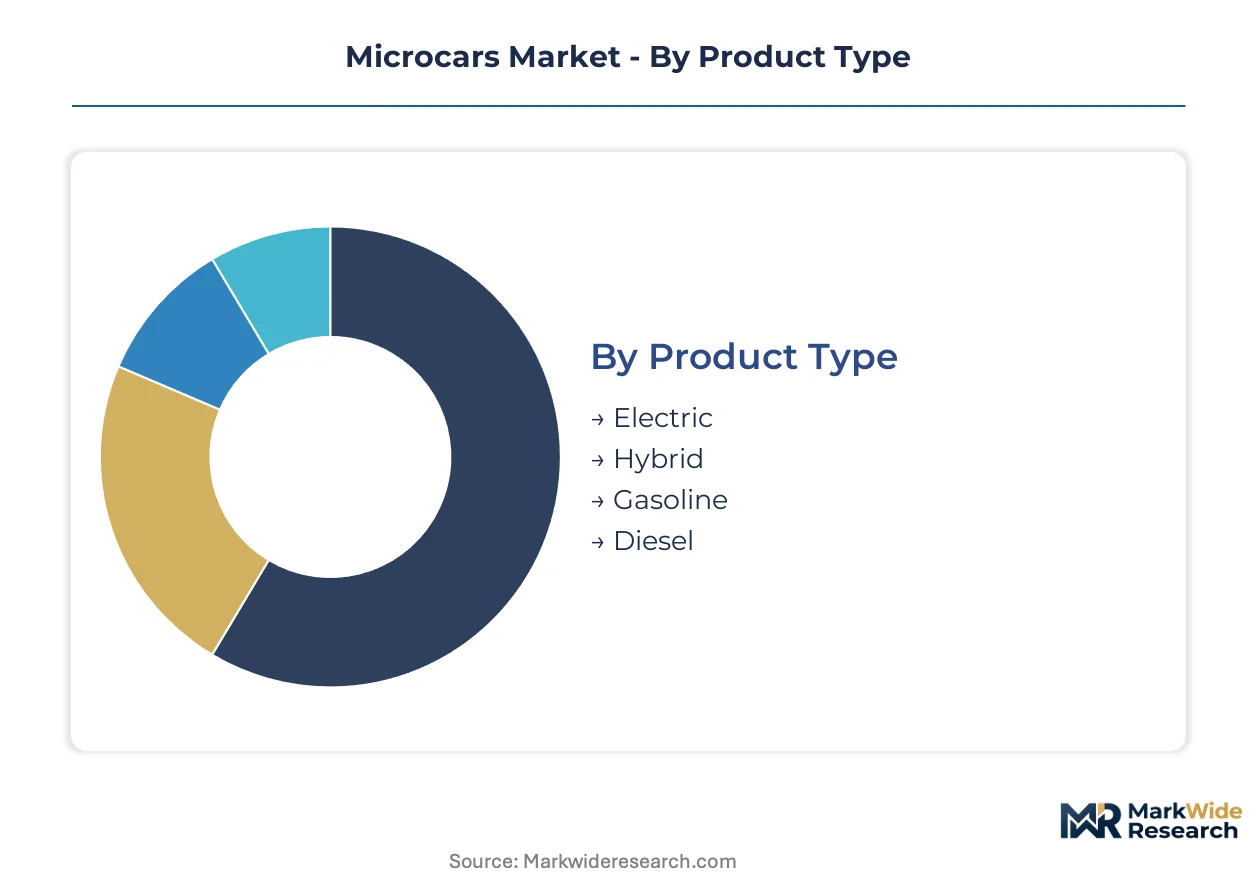
Microcar segmentation reveals divergent substitution pressures across powertrain technologies and household use cases. Category boundaries are blurring as electric variants undercut gasoline on total cost of ownership while urban congestion policies reshape who buys and how they purchase.
Product Type:
Electric powertrains face the most intense substitution pressure from next-generation battery chemistries and shared mobility services, while fossil fuel variants confront regulatory phase-out timelines.
- Electric:Lithium iron phosphate battery packs deliver thermal stability and cycle longevity that cobalt-dependent chemistries cannot match. Urban fleet operators in dense European city centers are consolidating procurement around LFP-equipped two-seaters as congestion charges tighten and parking premiums escalate.
- Hybrid:Small-battery series-hybrid architectures bridge infrastructure gaps in Southeast Asian markets where charging networks remain sparse. Thailand's metropolitan zones and Indonesia's secondary cities concentrate residual demand for this transitional format.
- Gasoline:Kei car regulations in Japan preserve a protected 660cc segment insulated from electrification mandates.
- Diesel:Compression-ignition microcars retain niche utility in rural European applications requiring torque for light commercial tasks.
Electric retains volume leadership; hybrid holds the steepest expansion curve as infrastructure laggards bridge toward full electrification.
End User:
Cost tier stratification separates premium design-conscious buyers from price-sensitive entry segments across metropolitan household structures.
- Urban Commuters:Single-occupant professionals in London, Paris, and Tokyo evaluate microcars against public transit season tickets and ride-hailing subscriptions. This archetype is losing share as remote work patterns persist and congestion charging shifts cost calculations.
- Small Families:Multi-vehicle households in dense European and Japanese cities seek secondary runabouts that preserve parking advantages while accommodating intermittent family utility. Four-seater configurations dominate this segment's procurement criteria.
- Students:Campus-adjacent municipalities with restricted parking supply create concentrated demand for sub-3-meter formats.
- Retirees:Fixed-income households in Japan's aging prefectures prioritize kei car tax advantages and maintenance simplicity.
Small families command the premium price tier; students anchor the entry-cost segment with highest price elasticity.
Vehicle Size:
Volume concentration in four-seater formats reflects the tension between parking constraints and intermittent utility requirements.
- Four-Seater:Accommodates small-family transport without sacrificing the category-defining parking advantages. This configuration captures the broadest end-user base across European and Japanese metropolitan zones where multi-vehicle households dominate.
- Two-Seater:Sub-2.5-meter lengths unlock parking exemptions in Amsterdam, Milan, and Barcelona regulatory schemes. Design-focused entrants differentiate through retro styling rather than spec-sheet competition.
- Compact:Three-meter envelope balances urban maneuverability with highway capability for peri-urban commuters.
- Lightweight:Sub-500kg formats exploit regulatory exemptions for unlicensed operation in select European jurisdictions.
Four-seater configurations dominate absolute unit volumes; two-seater formats expand most quickly through parking exemption arbitrage.
Distribution Channel:
Supply concentration in legacy dealership networks is fragmenting as direct-to-consumer entrants and subscription models capture urban early adopters.
- Direct Sales:Manufacturer-owned channels bypass margin-stacking intermediaries for price-transparent electric variants. Chinese producers leverage this model to undercut European incumbents on delivered cost.
- Dealerships:Franchise networks retain residual strength in gasoline microcar markets requiring service infrastructure and trade-in handling. Southeast Asian markets with sparse digital payment penetration depend on this channel.
- Online Retail:Configurator-based purchasing with home delivery is gaining traction among design-focused European urban buyers.
- Rental Services:Short-term subscription models compete with car-sharing platforms for intermittent-use households in dense city centers.
Dealerships retain volume leadership in fossil fuel segments; direct sales channels gain share fastest among electric-first urban adopters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai anchors Asia-Pacific microcar export capacity while Rotterdam's Maasvlakte terminals handle European battery component inflows that sustain Dutch and German assembly operations.
China
MIIT subsidy thresholds determine which electric microcar formats retain mass-market viability. Yangtze River Delta manufacturers exploit captive lithium iron phosphate cell production to compress delivered costs below internal-combustion equivalents. Shenzhen and Shanghai metropolitan zones concentrate procurement for secondary runabouts in multi-vehicle households.
Japan
METI's kei car dimension caps preserve a protected 660cc segment insulated from electrification mandates. Kanto manufacturers maintain dedicated R&D platforms optimized for domestic regulatory envelopes rather than exportable architectures. Tokyo and Osaka urban commuters anchor residual demand for gasoline-powered formats.
Germany
EU F-Gas Regulation fleet CO2 targets pressure OEMs toward zero-emission microcar portfolios for urban compliance credits. Bavarian engineering clusters specialize in compact electric powertrains for sub-3-meter vehicle formats. Berlin and Munich congestion charging schemes accelerate electric variant adoption among parking-constrained professionals.
India
PLI scheme manufacturing incentives attract localized electric microcar assembly for price-sensitive entry buyers. Tamil Nadu and Gujarat industrial corridors concentrate component sourcing for sub-500kg urban formats. Delhi-NCR and Bangalore municipal parking restrictions concentrate demand among campus-adjacent and metropolitan commuters.
France
ECHA chemical registration requirements shape battery pack material sourcing for European-market electric variants. Auvergne-Rhône-Alpes clusters specialize in lightweight composite chassis for retro-styled urban runabouts. Paris congestion charging and parking exemption policies concentrate two-seater procurement among design-focused metropolitan buyers.
Microcars Market Competitive Environment
Listed leaders compete with private specialists across battery supply chain integration and regulatory platform specialization. The vendor base splits between scale-driven volume manufacturers and design-focused niche entrants. Three archetypes dominate: integrated battery producers, kei car traditionalists, and retro-styled urban specialists. Capacity expansion and strategic partnerships constitute the primary competitive moves as firms secure lithium iron phosphate cell supply.
Within the integrated supply chain tier, SAIC GM Wuling Automobile Co., Ltd. and BYD Auto Co., Ltd. exemplify Chinese producers leveraging captive battery production to compress delivered costs. Suzuki Motor Corporation anchors the kei car traditionalist position through dedicated domestic R&D platforms. Microlino AG occupies a design-differentiation niche among European urban specialists.
| Leading Market Players |
|---|
| SAIC GM Wuling Automobile Co., Ltd. |
| Suzuki Motor Corporation |
| Ligier Group |
| Microlino AG |
| Honda Motor Co., Ltd. |
| Aixam-Mega |
| BYD Auto Co., Ltd. |
| Eli Electric Vehicles |
| Stellantis N.V. |
| Others |
Value Chain & Pricing Dynamics
Lithium iron phosphate chemistry substitution for cobalt-dependent alternatives simultaneously redistributes cell production toward China's Yangtze River Delta and collapses battery pack costs below internal-combustion equivalents. This chemistry pivot concentrates pricing power among vertically integrated producers while squeezing capital-light assemblers dependent on spot-market cell procurement.
Pricing Analysis
Volume-discount tiering structures separate captive-battery producers from module-assemblers across procurement contracts. Three-tier pricing stratifies across premium retro-styled European entrants, standard kei car traditionalists, and economy Chinese volume manufacturers. Cost compression in the economy tier intensifies as MIIT subsidy thresholds tighten eligibility for mass-market formats. Students and first-time buyers in India and Southeast Asia exhibit highest price elasticity, while design-focused metropolitan households in Paris and Milan accept premium positioning.
Supply Chain Analysis
Inventory lead times for lithium iron phosphate cells have compressed from quarterly to monthly cadence as Yangtze River Delta capacity scales. Cell production concentrates in China, South Korea, and Japan, with cathode active material processing anchored in Sichuan and Qinghai provinces. Raw material dependencies span lithium carbonate, iron phosphate precursor, and electrolyte formulations. Single-source vulnerability in lithium hydroxide refining creates input cost volatility. Distribution runs through manufacturer-direct channels for electric variants and legacy dealership networks for gasoline segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Microcar penetration sits at early-cycle expansion as congestion charging schemes in dense metropolitan zones accelerate electric variant adoption beyond replacement demand alone.
For Market Incumbents: Secure captive lithium iron phosphate cell supply through backward integration or long-term offtake agreements with Yangtze River Delta producers. Deepen kei-specific R&D platforms against regulatory insulation erosion. Defend margin position by controlling battery supply chain integration rather than competing on spec-sheet differentiation. For New Entrants and Emerging Players: Anchor in Southeast Asian hybrid microcar demand where charging infrastructure gaps preserve transitional format viability. Target Thailand's metropolitan zones and Indonesia's secondary cities with small-battery series-hybrid architectures. Pursue direct-to-consumer distribution with home delivery configurators to bypass margin-stacking dealership networks. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European retro-styled urban specialists lacking battery supply chain integration. Long-term viability favors manufacturers with upstream cell production control or kei car regulatory moats. Monitor China MIIT subsidy threshold adjustments as the inflection signal determining which microcar formats retain mass-market economic viability.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Platform Standardization | Compresses development costs for manufacturers across multiple vehicle formats. |
| Lithium Iron Phosphate Supply Agreement | Locks in thermal-stable cell chemistry below cobalt-dependent pricing tiers. |
| Kei Car R&D Platform Deepening | Preserves METI regulatory insulation against cross-border electrification mandates. |
| Direct-to-Consumer Channel Launch | Bypasses margin-stacking intermediaries for price-transparent electric variants. |
| Congestion Zone Compliance Certification | Unlocks urban parking exemptions and zero-emission credits in European city centers. |
Study Parameters
Operator-level perspectives from OEM platform engineers, Tier 1 battery procurement leads, dealership operations heads, and urban fleet managers anchored the qualitative base. Primary fieldwork combined with secondary validation from vehicle production databases, IHS Markit registration data, MIIT subsidy filings, and METI regulatory disclosures. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Sensitivity analysis tested forecast outputs against alternative battery chemistry adoption curves and subsidy phase-out scenarios. Segmentation dimensions modeled include propulsion architecture, vehicle size class, end-user household structure, and regional regulatory cluster. CAGRs derived from iterative convergence of historical trajectory analysis and forward-looking adoption elasticity estimates. Industry-specific inputs incorporated congestion charging policy implementation timelines and lithium iron phosphate cost curves.
Decision-makers should treat outputs as directional under base assumptions of sustained MIIT subsidy thresholds and EU F-Gas Regulation enforcement; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passenger Vehicles
Luxury Vehicles Market
Passenger Vehicles
Limousines Market
Passenger Vehicles
Quadricycle and Tricycle Market
Passenger Vehicles
Family Car Market
Passenger Vehicles
Convertible Vehicles Market
Passenger Vehicles
Russia Light Vehicle Market
Passenger Vehicles
Asia Pacific Luxury Cars Market
Passenger Vehicles
India Luxury Car Market
Passenger Vehicles
Passenger Vehicle Market
Passenger Vehicles
China Luxury Car Market
Passenger Vehicles
Small Suvs Market
Passenger Vehicles
India Passenger Car Market
Passenger Vehicles
North American Lightweight Car Market
Passenger Vehicles
Train Seat Market
Passenger Vehicles
Inland Water Passenger Transport Market
Passenger Vehicles
Sports Utility Vehicles (Suvs) Market