
 Limousines Market | 2026-2036
Limousines Market Size, Share, and Industry Trends Forecast 2026-2036
Limousines Market Foresight
Subscription-based fleet access is rebalancing how operators monetize vehicle utilization, shifting capital burden from ownership to recurring revenue. Uber Technologies Inc. leverages its global driver network to sustain density in premium ride categories. Blacklane GmbH differentiates through fixed-rate corporate contracts that anchor predictable yield per vehicle. Carey International Inc. specializes in white-label chauffeur services that extend hotel and airline brand consistency.
A limousine is a luxury passenger vehicle, typically stretched or factory-elongated beyond standard sedan dimensions, designed for premium ground transport with enhanced interior amenities and professional chauffeur operation. Stretch configurations employ reinforced chassis extensions and partition systems to accommodate elevated occupant capacity while maintaining structural integrity. Sedan and SUV categories dominate current fleet composition due to lower operating costs and broader airport transfer suitability, while stretch and super stretch variants concentrate margin pools in event and hospitality segments. Corporate transport and airport transfer service types absorb the majority of structured booking volume, whereas subscription pricing models remain underdeveloped relative to hourly and flat rate alternatives.
The National Highway Traffic Safety Administration enforces modified vehicle safety standards that govern limousine structural modifications and occupant protection systems. The EPA and California Air Resources Board impose emissions thresholds that filter powertrain eligibility for commercial luxury fleets. The EU Green Deal and F-Gas Regulation tighten carbon intensity benchmarks for vehicles operating across European metropolitan zones. Fleet operators and platform intermediaries must monitor regulatory divergence between zero-emission mandates and charging infrastructure readiness.
Market Dynamics
Fleet electrification mandates from California's Air Resources Board and the EU Green Deal are forcing capital reallocation across limousine operators, compressing payback periods for internal combustion assets while charging infrastructure lags deployment timelines.
Growth Catalysts
- Corporate travel budget normalization:Executive ground transport spending across North American financial services and professional services verticals is recovering to pre-pandemic run rates, restoring hourly chauffeur service utilization.
- Zero-emission procurement mandates:California's Advanced Clean Cars II regulation and the EU Green Deal's 2035 ICE phase-out are accelerating battery-electric limousine fleet turnover in premium ground transport segments.
- Airport transfer density:Concentrated demand in New York, Los Angeles, and Chicago sustains premium pricing power for sedan and SUV categories serving business aviation terminals.
Market Restraints
- Battery cost volatility:Lithium-ion cell pricing uncertainty compresses fleet operator margins on electric vehicle conversions, extending total cost of ownership breakeven timelines.
- Modified vehicle certification friction:NHTSA structural modification standards impose extended compliance timelines for stretch limousine conversions, limiting supply responsiveness.
- Ride-hailing platform substitution:Uber Black and premium platform categories capture price-sensitive corporate transport demand, pressuring dedicated fleet utilization rates.
Strategic Opportunities
- Subscription fleet access models:Underdeveloped recurring revenue structures in hourly and flat-rate dominant markets create white space for utilization-optimized membership pricing.
- Hotel and airline white-label partnerships:Brand-consistent chauffeur services for hospitality chains remain fragmented, offering margin capture through operational integration.
- EU F-Gas Regulation compliance services:Refrigerant management for climate-controlled premium interiors creates aftermarket service revenue streams as environmental enforcement tightens.
Industry Challenges
- Chauffeur talent pipeline constriction:Commercial driver licensing requirements and wage competition from logistics sectors limit qualified operator availability in dense metropolitan markets.
- Charging infrastructure deployment lag:Fleet-dedicated high-speed charging capacity in urban core and airport-adjacent locations trails electric vehicle procurement timelines, stranding asset utilization.
- Partition system safety recertification:NHTSA occupant protection standards for modified vehicles require ongoing structural engineering validation, extending vehicle modification cycle times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Limousines Market |
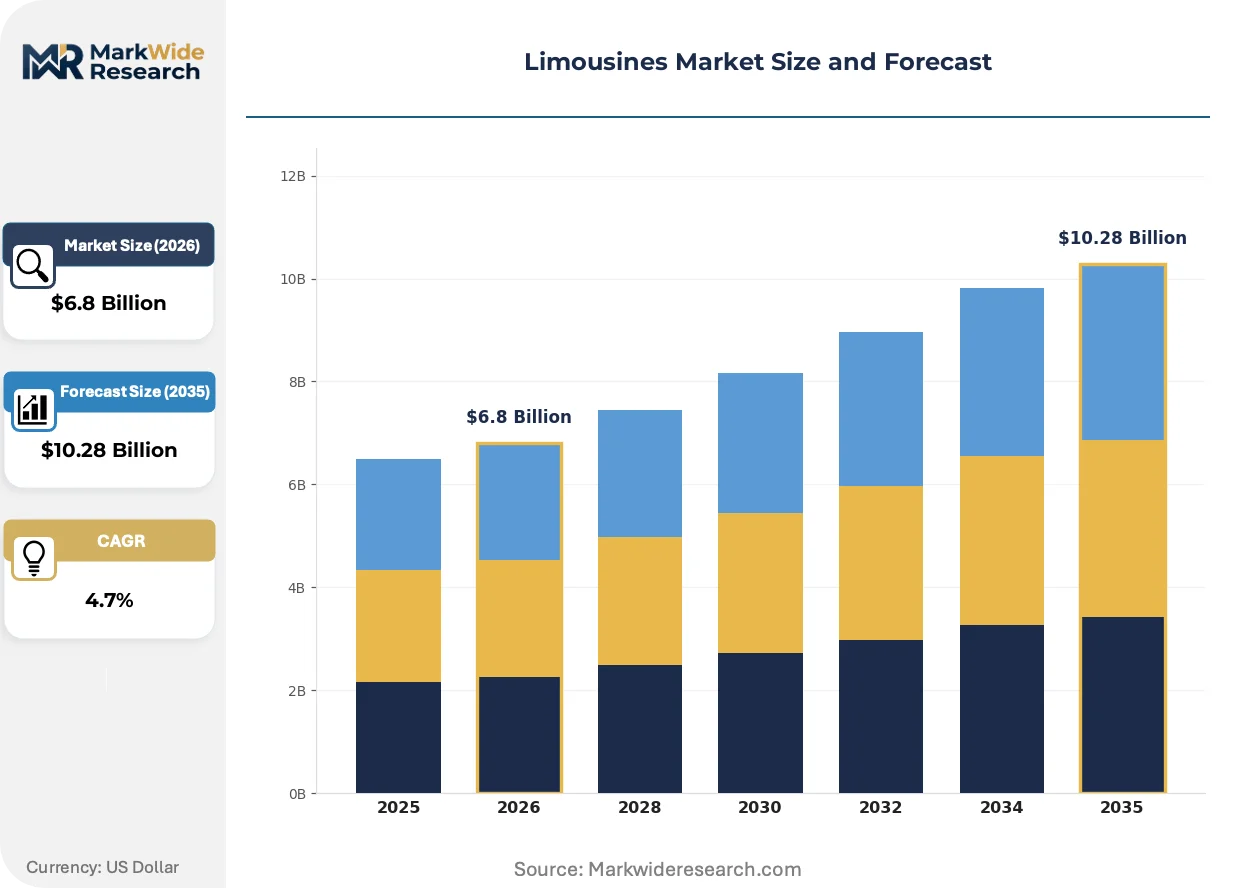
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedan, SUV, Stretch, Super Stretch Service Type: Chauffeur Service, Rental Service, Corporate Transport, Airport Transfer End User: Individuals, Corporations, Event Planners, Hotels Pricing Model: Hourly Rate, Flat Rate, Package Deal, Subscription |
| Companies Covered | Uber Technologies Inc., Lyft Inc., DiDi Global Inc., Grab Holdings Ltd., Blacklane GmbH, Carey International Inc., Addison Lee Ltd., EmpireCLS Worldwide Services, Gett Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Limousines Market Shifts & Advancements
Electrification is compressing powertrain procurement cycles while connectivity platforms reshape how fleet operators manage utilization and customer interface. These shifts are redefining asset-light operational models.
Battery-electric drivetrains are absorbing the capital allocation previously directed to internal combustion engine maintenance and fuel hedging. Fleet operators in California and EU metropolitan zones are accelerating zero-emission procurement ahead of mandate deadlines. The technology is absorbing margin pressure from volatile petroleum inputs while creating new stranded asset risk for ICE-heavy legacy fleets.
The EU Green Deal's carbon intensity benchmarks are tightening eligibility for vehicles operating across European metropolitan zones. Commercial luxury fleets face exclusion from low-emission zones without powertrain conversion or replacement. Stretch and super stretch variants concentrated in event hospitality segments face disproportionate compliance cost exposure due to modification complexity.
Corporate transport buyers are consolidating preferred vendor relationships around fixed-rate contract structures that transfer utilization risk to fleet operators. Hourly and flat-rate alternatives face compression as procurement functions prioritize budget predictability. This pattern concentrates most visibly in financial services and professional services verticals across New York and London corporate travel programs.
Limousines Market Segmentation
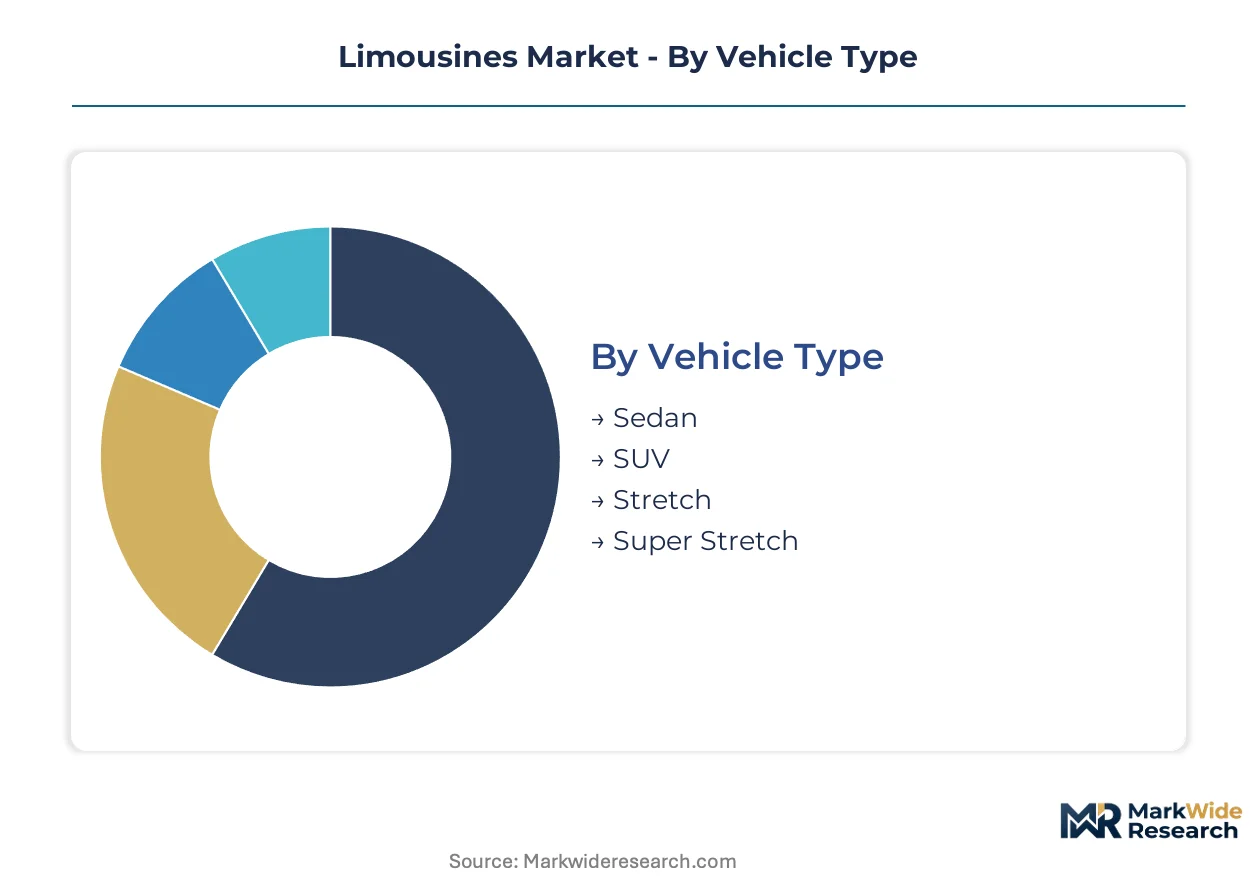
Limousine fleet operators segment offerings to match vehicle configuration with trip economics and client procurement patterns. Each segmentation axis reflects distinct margin structures and capital intensity requirements that shape operator investment decisions.
Vehicle Type:
Customization intensity spans factory-standard sedans at one extreme to coachbuilt super-stretch configurations requiring structural engineering validation at the other.
- Sedan:Factory-elongated luxury sedans with reinforced chassis maintain the lowest per-mile operating costs in premium ground transport. Corporate transport departments in New York and Los Angeles concentrate procurement here for airport transfers and hourly executive service, prioritizing reliability over spectacle.
- SUV:Extended-wheelbase sport utility vehicles combine elevated occupant capacity with all-weather capability and luggage volume suited to business aviation terminals. Fleet operators allocate expanding capital share to SUV categories as corporate travel policies emphasize passenger safety and ground clearance.
- Stretch:Aftermarket chassis extensions with partition systems accommodate hospitality and event segments requiring elevated occupant capacity. NHTSA structural modification standards extend compliance timelines for these conversions.
- Super Stretch:Multi-door coachbuilt configurations exceeding standard stretch dimensions serve wedding and celebration markets with premium per-trip pricing. Electrification mandates from California's Air Resources Board impose disproportionate compliance cost exposure due to modification complexity.
Most installed capacity flows through Sedan. Expansion is steepest in SUV.
Service Type:
Contract structure determines utilization risk allocation between fleet operator and client, from spot-market rentals to multi-year corporate commitments.
- Chauffeur Service:Professional driver provision with vehicle includes uniform standards, route optimization, and real-time tracking platforms. Hourly billing structures dominate this segment, with demand concentrating in financial services verticals across Chicago and London.
- Rental Service:Self-drive luxury vehicle access for specified durations without professional operator. This segment captures price-sensitive demand from individuals seeking occasion-specific vehicle access without ownership burden.
- Corporate Transport:Structured ground transport programs with fixed-rate contracts, dedicated account management, and consolidated billing. Procurement functions prioritize budget predictability, compressing hourly alternatives.
- Airport Transfer:Point-to-point service connecting business aviation terminals, commercial airports, and urban destinations. Density in New York, Los Angeles, and Chicago sustains premium pricing power for sedan and SUV categories.
Corporate Transport absorbs the majority of contracted revenue. Airport Transfer is expanding most quickly as business aviation activity normalizes.
End User:
Buyer sophistication and procurement scale separate individual occasion-based demand from institutional volume commitments with negotiated rate structures.
- Individuals:Occasion-driven consumers booking weddings, celebrations, and personal travel through direct reservation channels. Price sensitivity varies sharply by event type and geographic market.
- Corporations:Procurement departments managing executive ground transport programs with preferred vendor relationships and consolidated expense management. Financial services and professional services verticals drive structured demand in major metropolitan zones.
- Event Planners:Intermediaries coordinating transportation logistics for conferences, weddings, and entertainment productions. This segment demands fleet flexibility and last-minute availability guarantees.
- Hotels:Hospitality properties sourcing white-label chauffeur services to extend brand consistency across guest touchpoints. Operational integration with property management systems creates switching costs.
Corporations anchor contracted volume. Hotels are gaining share fastest as hospitality chains consolidate vendor relationships.
Pricing Model:
Revenue predictability increases across the spectrum from variable hourly exposure to fixed subscription commitments.
- Hourly Rate:Time-based billing with minimum duration requirements and vehicle-category surcharges. This model transfers utilization risk to clients but creates revenue volatility for operators.
- Flat Rate:Fixed pricing for defined routes or service types, common in airport transfer and point-to-point corporate transport. Procurement functions prioritize this structure for budget predictability.
- Package Deal:Bundled service offerings combining multiple trips, vehicle categories, or duration blocks at discounted rates. Wedding and event segments concentrate demand here.
- Subscription:Recurring membership access to fleet capacity with monthly or annual commitments. This underdeveloped structure shifts capital burden from ownership to recurring revenue.
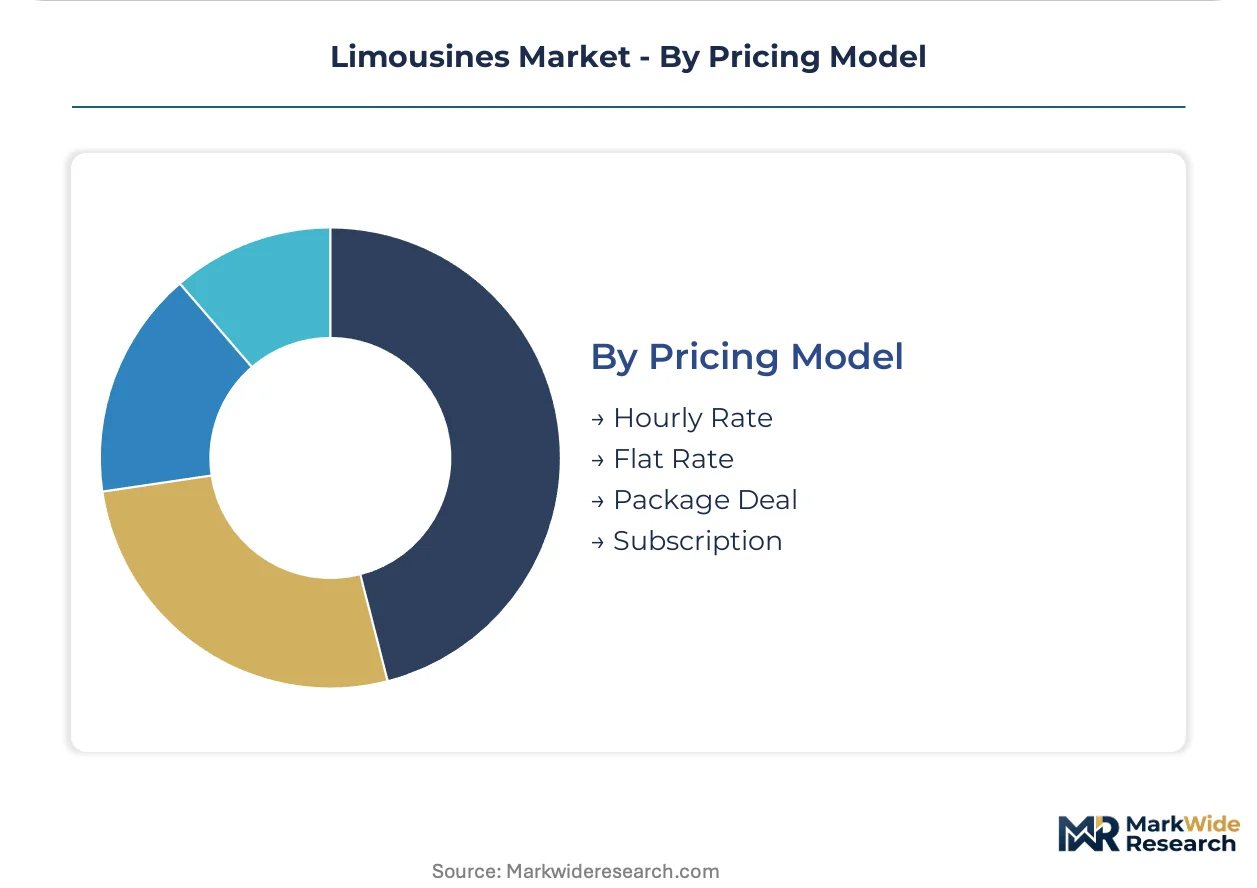
Hourly Rate and Flat Rate dominate transaction volume. Subscription is climbing the fastest as operators experiment with utilization-optimized membership pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands premium pricing power through concentrated corporate travel demand, while Germany's regulatory framework accelerates zero-emission fleet turnover at a faster pace than most European peers.
United States
Corporate travel budgets in financial services and professional services verticals drive executive ground transport spending across New York, Los Angeles, and Chicago. California's Air Resources Board enforces Advanced Clean Cars II regulations that mandate battery-electric procurement timelines for commercial luxury fleets. Fleet operators in Manhattan and Beverly Hills expand sedan and SUV allocations for business aviation terminal transfers.
Germany
Frankfurt and Munich anchor corporate transport demand from banking and automotive headquarters seeking fixed-rate contract structures. The EU Green Deal's carbon intensity benchmarks tighten eligibility for vehicles operating across metropolitan zones. Berlin-based fleet operators face compressed payback periods for internal combustion assets as the 2035 ICE phase-out approaches.
United Kingdom
London's financial district sustains hourly chauffeur service utilization from investment banking and legal services procurement functions. The F-Gas Regulation imposes refrigerant management requirements for climate-controlled premium interiors. Blacklane GmbH and Addison Lee Ltd. concentrate operational density in the City and Canary Wharf corporate travel corridors.
China
Beijing and Shanghai metropolitan zones generate demand for premium airport transfers from multinational executive travel programs. Dual carbon goals and MIIT emissions standards filter powertrain eligibility for commercial luxury vehicle registrations. DiDi Global Inc. leverages platform density to capture corporate transport volume in tier-one city business districts.
United Arab Emirates
Dubai's hospitality and events sectors sustain super-stretch limousine deployment for wedding and celebration markets. Federal transport regulations govern commercial driver licensing and vehicle modification standards across the emirates. Carey International Inc. and EmpireCLS Worldwide Services maintain white-label partnerships with luxury hotel properties along Sheikh Zayed Road.
Limousines Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with platform intermediaries capturing price-sensitive corporate volume while dedicated fleet operators defend premium positioning through service consistency. The vendor base concentrates around three strategic archetypes: global ride-hailing platforms extending into premium categories, specialized chauffeur service providers with fixed-rate corporate contracts, and hospitality-integrated white-label operators. Competitive moves center on geographic expansion through platform density and strategic partnerships with hotel and airline loyalty programs.
Within the platform-intermediary tier, Uber Technologies Inc. and Lyft Inc. occupy positions that leverage driver network scale to sustain utilization across premium ride categories. Blacklane GmbH exemplifies the specialized chauffeur archetype through fixed-rate corporate contract structures that anchor predictable yield per vehicle, while Carey International Inc. represents hospitality-integrated positioning via white-label services extending hotel and airline brand consistency.
| Leading Market Players |
|---|
| Uber Technologies Inc. |
| Lyft Inc. |
| DiDi Global Inc. |
| Grab Holdings Ltd. |
| Blacklane GmbH |
| Carey International Inc. |
| Addison Lee Ltd. |
| EmpireCLS Worldwide Services |
| Gett Co. |
| Others |
Supply & Pricing Matrix
Chauffeur talent concentration in New York and Los Angeles widens pricing spreads between premium white-label services and hourly rate alternatives, as labor cost differentials across metropolitan markets stratify fleet access tiers.
Pricing Analysis
Capacity additions in Germany and the United Kingdom are reshaping price floors for corporate transport contracts as fleet operators compete for fixed-rate commitments. Three-tier pricing structure across premium, standard, and economy levels separates white-label hotel partnerships from direct hourly bookings and platform-mediated rides. Price differentiation hinges on brand consistency guarantees and volume scale commitments. Pricing pressure stems from ride-hailing platform substitution in airport transfer corridors. Individual occasion-based buyers exhibit highest price sensitivity; hospitality chains with operational integration requirements show lowest.
Supply Chain Analysis
Refurbishment flows for stretched chassis configurations create secondary parts markets extending vehicle modification cycle economics. Manufacturing concentrates in the United States, Germany, and China for factory-elongated sedan and SUV platforms. Battery-electric powertrain procurement draws from South Korean and Chinese cell suppliers, while partition systems and climate control components source from German and Japanese Tier 1 suppliers. Single-source vulnerability in lithium-ion cell supply creates fleet operator exposure. Distribution runs through direct fleet procurement channels and platform intermediary networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Limousines Market compounds steadily as corporate travel budget normalization restores hourly chauffeur utilization across financial services verticals.
For Market Incumbents: Deploy subscription fleet access models to capture recurring revenue streams and reduce utilization volatility from spot-market dependence. Consolidate white-label partnerships with hospitality chains to create operational switching costs against platform intermediaries. Defend against ride-hailing substitution by anchoring fixed-rate corporate contracts with dedicated account management infrastructure. For New Entrants and Emerging Players: Battery-electric fleet specialization offers technology-first wedge into California and EU metropolitan markets ahead of mandate deadlines. Target underdeveloped subscription pricing structures in hourly-dominant corporate transport segments. Pursue hotel and airline loyalty program integrations as primary go-to-market channel. For Investors and Strategic Acquirers: Hospitality conglomerates are the most active acquirer in this space, seeking operational control over guest touchpoint consistency. Five-to-ten year viability rests on electrification capex efficiency and charging infrastructure deployment timing. Monitor California Air Resources Board enforcement acceleration and EU Green Deal carbon intensity benchmark tightening as inflection indicators for asset stranding risk.| Strategic Initiative | Industry Significance |
|---|---|
| Electrification Fleet Conversion | California Air Resources Board mandates force battery-electric procurement timelines for commercial luxury operators. |
| White-Label Partnership Expansion | Hotel chain operational integration creates vendor switching costs and margin protection. |
| Subscription Pricing Launch | Recurring revenue structures shift capital burden from ownership to membership economics. |
| Charging Infrastructure Partnership | Airport-adjacent high-speed capacity deployment reduces stranded asset risk for electric fleets. |
| Corporate Contract Consolidation | Fixed-rate structures transfer utilization risk from procurement functions to fleet operators. |
Research Methodology
Bottom-up corporate transport demand modeling reconciled against top-down fleet operator capacity tracking forms the analytical core. Primary interviews with fleet procurement directors, hospitality chain operations executives, chauffeur service platform managers, and regulatory compliance officers combine with secondary validation from NHTSA modified vehicle safety filings, EPA emissions certification databases, EU Green Deal implementation reports, and California Air Resources Board regulatory notices. Triangulation across stakeholder perspectives and documentary sources anchors segment-level estimates.
Input-output matrices map vehicle type, service category, and end-user demand against powertrain procurement cycles and charging infrastructure deployment timelines across the projection horizon. Segmentation dimensions span vehicle configuration, contract structure, buyer sophistication, and pricing model commitment. CAGRs derive from regression analysis of fleet turnover rates, corporate travel spending patterns, and regulatory mandate phase-in schedules. Battery cost trajectories and commercial driver wage inflation feed industry-specific forecast sensitivity.
The model holds under steady corporate travel budget recovery and regulatory enforcement continuity; deviation in battery cell pricing volatility or charging infrastructure deployment delays would shift fleet operator investment timing. Forecasts reflect documented assumptions about mandate compliance deadlines and technology cost curves. Practitioners should monitor California ZEV credit market dynamics and EU low-emission zone expansion schedules for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passenger Vehicles
North America Automotive Market
Passenger Vehicles
Electric Passenger Car MRO Market
Passenger Vehicles
Electric Sports Car Market
Passenger Vehicles
China Luxury Car Market
Passenger Vehicles
Family Car Market
Passenger Vehicles
Minivans Market
Passenger Vehicles
Luxury Vehicles Market
Passenger Vehicles
Convertible Vehicles Market
Passenger Vehicles
Passenger Vehicle Market
Passenger Vehicles
Lightweight Cars Market
Passenger Vehicles
Train Seat Market
Passenger Vehicles
Global Passenger Cars Market
Passenger Vehicles
Russia Light Vehicle Market
Passenger Vehicles
Latin America Passenger Car Market
Passenger Vehicles
Compact Cars Market
Passenger Vehicles
Europe Luxury Car Market