
 Luxury Vehicles Market | 2026-2036
Luxury Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Luxury Vehicles Market Analysis
Subscription-based ownership bundling is pivoting how luxury buyers access vehicles. Mercedes-Benz leverages its captive finance arm to sustain recurring revenue through lease-to-own hybrids. BMW anchors its urban mobility strategy with flexible monthly plans that compete against traditional purchase cycles. Lexus differentiates through concierge service tiers that extend brand loyalty beyond the initial transaction.
Luxury vehicles are passenger automobiles engineered with premium materials, advanced powertrains exceeding 300 horsepower, and precision-manufactured interiors using hand-finished leather and real wood veneer, designed to deliver superior comfort, status signaling, and driving dynamics for discerning buyers. SUVs dominate volume as affluent families prioritize cabin space and commanding road position across multiple terrains. Electric variants within the fuel type category represent the fastest-expanding margin pool as battery technology matures and charging infrastructure proliferates. Sedans remain a mature profit center in executive fleet channels where chauffeur-driven configurations sustain residual values.
The European Union enforces CO2 fleet-average mandates through EMA oversight while the EPA regulates tailpipe emissions in the United States, compelling powertrain diversification across manufacturer lineups. China's MIIT imposes NEV credit quotas that force joint-venture partners to localize electric luxury production or sacrifice market access. Stakeholders must monitor regulatory fragmentation between jurisdictions that threatens platform standardization and capital allocation efficiency.
Market Dynamics
Powertrain electrification is restructuring capital allocation across manufacturing footprints as battery chemistry costs compress and platform architectures consolidate around scalable electric skateboards.
Growth Catalysts
- EU Fleet CO2 Mandates:EMA-enforced emission ceilings are compelling luxury marques to phase out combustion engines ahead of consumer-driven demand curves.
- Affluent Urbanization:Dense metropolitan clusters in China and India are generating concentrated demand for compact electric luxury crossovers with sub-5-meter footprints.
- Solid-State Battery Maturation:Next-generation cell architectures are extending range thresholds that eliminate remaining consumer hesitation around long-distance electric touring.
Market Restraints
- Lithium Supply Concentration:Chilean and Australian spodumene deposits dominate cathode material sourcing, creating geopolitical chokepoints for European and North American assembly plants.
- Semiconductor Node Scarcity:Advanced driver-assistance systems require 7nm and below fabrication capacity that remains concentrated at TSMC and Samsung foundries.
- Charging Infrastructure Asymmetry:Rural and ex-urban corridors in the United States and Southern Europe lack DC fast-charging density sufficient for luxury buyer expectations.
Strategic Opportunities
- Southeast Asia Premiumization:Indonesia, Thailand, and Vietnam present underpenetrated markets where first-generation wealth creation outpaces established luxury vehicle penetration rates.
- Battery-as-a-Service Models:Decoupled battery ownership from vehicle purchase is lowering entry price points while securing recurring revenue streams through monthly subscription frameworks.
- EU Green Deal Industrial Policy:Battery gigafactory subsidies and critical raw materials processing incentives are reshoring European supply chain control.
Industry Challenges
- Software-Defined Vehicle Talent Gap:Embedded systems engineers with automotive safety integrity level expertise command premiums that strain legacy workforce compensation structures.
- Homologation Timeline Compression:Divergent type-approval requirements between EPA, EMA, and MIIT regimes are extending development cycles for unified global platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Luxury Vehicles Market |
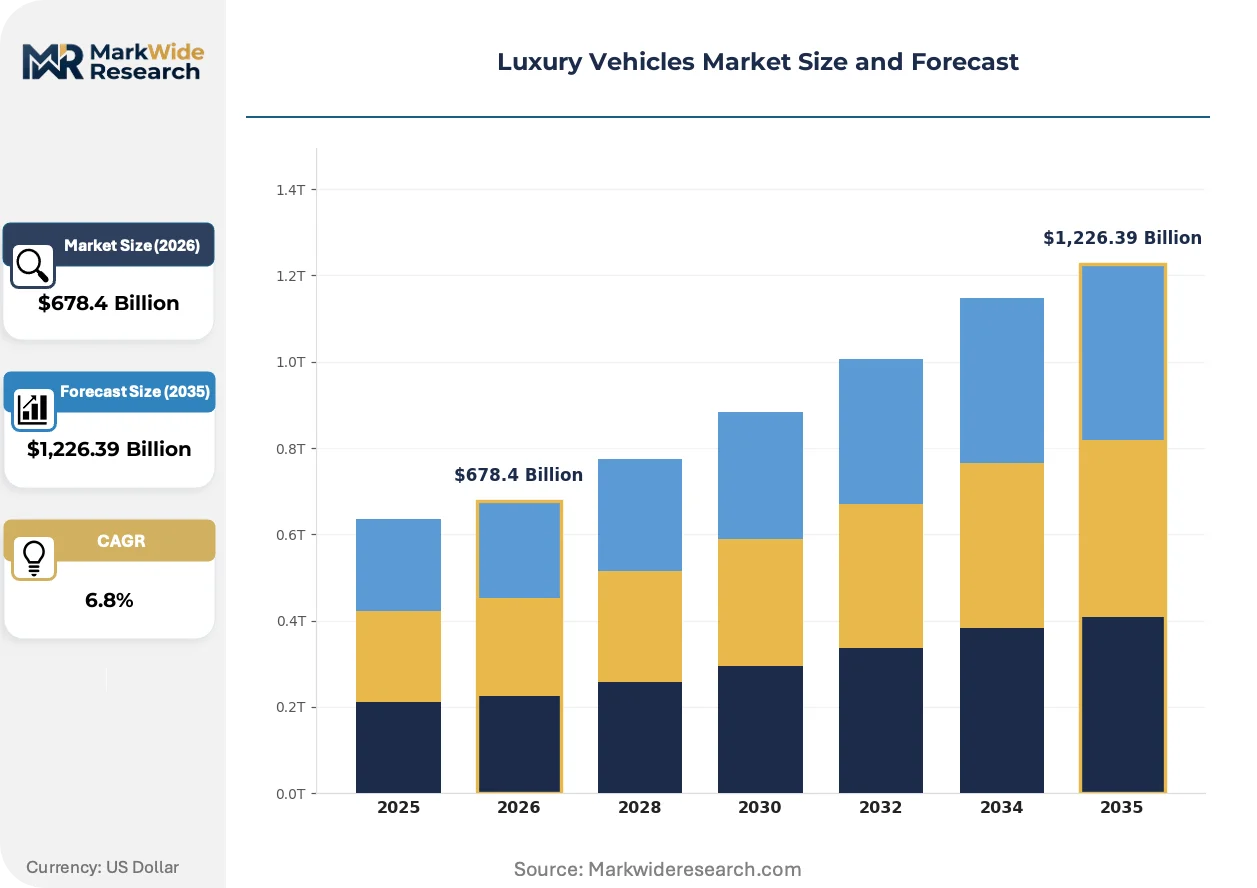
| Market Size in 2026 | $678.4 Billion |
| Market Size in 2035 | $1,226.39 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SUV, Sedan, Coupe, Convertible Fuel Type: Petrol, Diesel, Electric, Hybrid End User: Affluent Consumers, Executives, Fleet Operators, Dealerships Market Channel: Direct Sales, Online Sales, Showrooms, Leasing |
| Companies Covered | Genesis, Cadillac, Lexus, Acura, Porsche, Mercedes-Benz, Audi, Volvo, BMW, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Luxury Vehicles Market Emerging Trajectories
Digital architecture convergence is collapsing the boundary between powertrain and infotainment domains, enabling over-the-air feature monetization that extends revenue capture across vehicle lifecycles.
Cell-to-pack battery engineering is modularizing energy storage subsystems by eliminating module housings and integrating thermal management directly into pack structures. Luxury electric vehicle programs at Mercedes-Benz and BMW are adopting these architectures to reclaim interior volume and reduce assembly complexity. This compression of the battery hierarchy is modularizing supplier relationships as tier-one integrators assume direct cell sourcing responsibilities previously managed by module specialists.
The EU AI Act's risk-based classification system is imposing documentation and transparency obligations on automated driving functions above SAE Level 2. Manufacturers must now maintain technical files demonstrating conformity with fundamental rights impact assessments for biometric identification and emotion recognition systems. German KBA type-approval processes are extending by four to six months as agencies develop evaluation protocols for these algorithmic accountability requirements.
Corporate fleet procurement is fragmenting across mobility-as-a-service platforms that unbundle vehicle access from ownership. Executive transportation managers at financial services and technology firms are replacing three-year lease commitments with flexible monthly subscriptions covering insurance, maintenance, and charging infrastructure. This shift is most pronounced in London, Singapore, and Dubai where parking scarcity and congestion pricing amplify total cost of ownership sensitivity.
Luxury Vehicles Market Segmentation
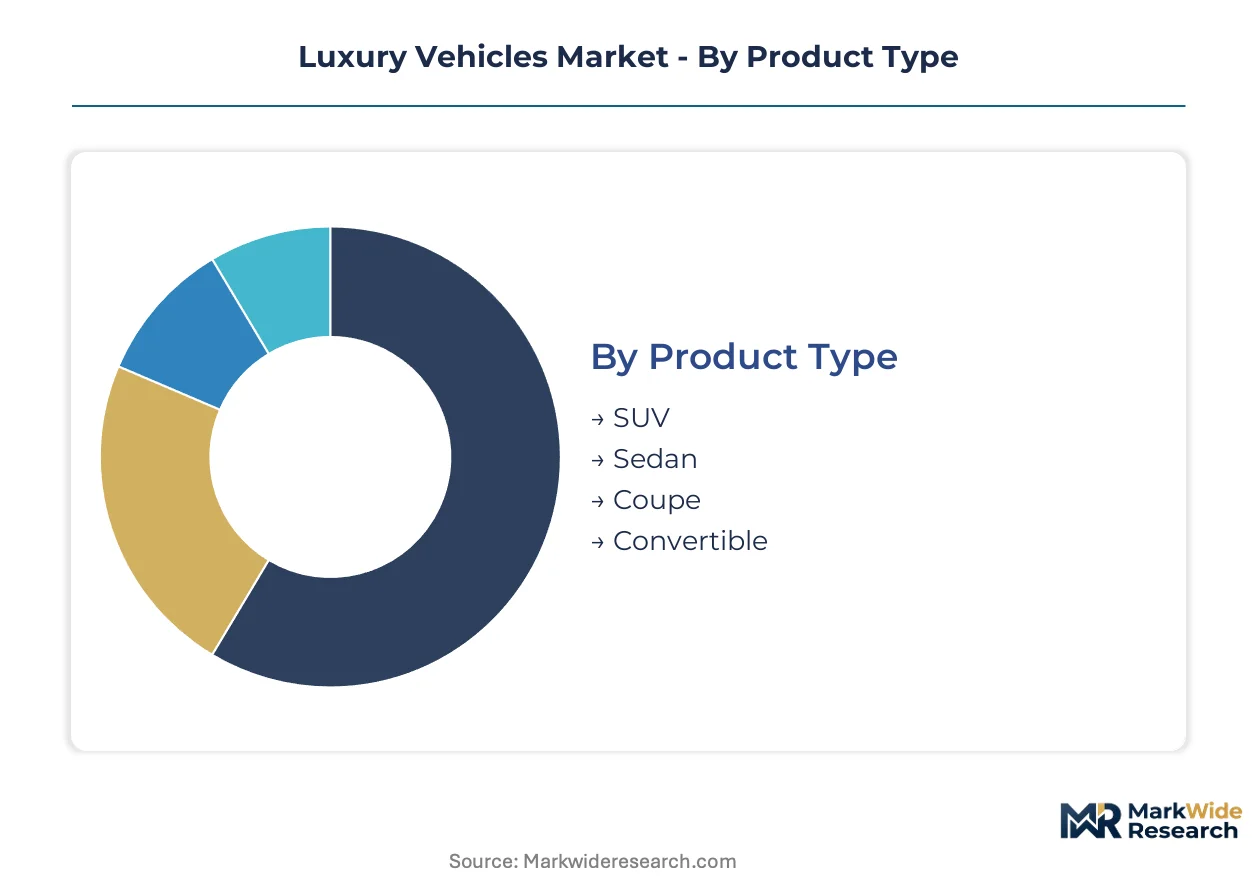
Segmentation in luxury vehicles determines capital allocation priorities across divergent buyer expectations and regulatory constraints. Manufacturers must balance platform development costs against margin profiles that vary sharply by body style and powertrain architecture.
Product Type:
SUV platforms demand the heaviest upfront engineering investment due to structural reinforcement requirements and multi-terrain capability integration.
- SUV:Architectures prioritize elevated seating positions, all-wheel-drive configurations, and reinforced unibodies capable of towing and off-road duty cycles. Affluent families in China's tier-one cities concentrate demand for extended-wheelbase variants with third-row seating, driven by multi-generational household mobility needs and chauffeur utilization. SUVs absorb the bulk of installed capacity; Electric variants within SUVs are expanding most quickly.
- Sedan:Low-slung profiles emphasize aerodynamic efficiency and rear-seat comfort for executive transport. Corporate fleet channels in Germany and Japan sustain residual values through chauffeur-driven configurations where legroom and cabin isolation outweigh cargo versatility.
- Coupe:Two-door silhouettes sacrifice rear accessibility for stylistic distinction and structural rigidity. Buyers in the United Arab Emirates and Switzerland favor these configurations as secondary vehicles for personal use rather than family transport.
- Convertible:Retractable roof mechanisms add weight and complexity while delivering open-air driving experiences. Mediterranean coastal markets and California's urban corridors generate concentrated seasonal demand sensitive to weather patterns and parking security.
Platform consolidation favors scalable SUV architectures that accommodate sedan and coupe derivatives through shared underpinnings.
Fuel Type:
Powertrain selection dictates battery supply chain commitments and regulatory compliance trajectories across manufacturing footprints.
- Petrol:Turbocharged inline-six and V8 configurations deliver immediate throttle response and established service infrastructure. Demand concentrates in Middle Eastern markets where fuel subsidies persist and charging infrastructure remains sparse.
- Diesel:Compression-ignition efficiency suits long-distance touring with superior thermal efficiency at highway speeds. European executive fleets and Indian luxury buyers favor these powertrains for intercity travel where refueling speed outweighs electrification benefits.
- Electric:Skateboard architectures integrate battery packs beneath cabin floors, lowering center of gravity and maximizing interior volume. China's MIIT credit quotas and the EU's EMA fleet-average mandates are forcing accelerated localization of luxury electric assembly.
- Hybrid:Parallel and series-hybrid configurations bridge infrastructure gaps while preserving range flexibility. Japanese metropolitan buyers and London congestion-zone operators prioritize these systems where pure-electric range anxiety persists but emissions regulations tighten.
Hybrid systems retain the largest installed production base; pure electric architectures are climbing the fastest as battery costs compress and charging density improves.
End User:
Buyer category determines service integration depth and pricing architecture flexibility across ownership models.
- Affluent Consumers:Individual purchasers prioritize badge prestige, customization programs, and concierge delivery experiences. These buyers in Southeast Asia's first-generation wealth centers are expanding faster than replacement demand in mature markets.
- Executives:Corporate procurement managers negotiate fleet discounts against residual value guarantees and maintenance bundling. German financial services firms and technology companies in Singapore are shifting from three-year leases toward flexible monthly subscriptions.
- Fleet Operators:Rental and mobility-service providers optimize for depreciation curves and standardization across vehicle pools. Airport-based premium rental channels in Dubai and Miami concentrate demand for recognizable luxury marques with proven durability records.
- Dealerships:Franchise networks absorb inventory risk against manufacturer floorplan financing and volume incentives. Inventory financing structures determine regional availability patterns and trim-level allocation priorities.
Affluent consumers drive the majority of unit volume; fleet operators are gaining share fastest as mobility-as-a-service platforms proliferate.
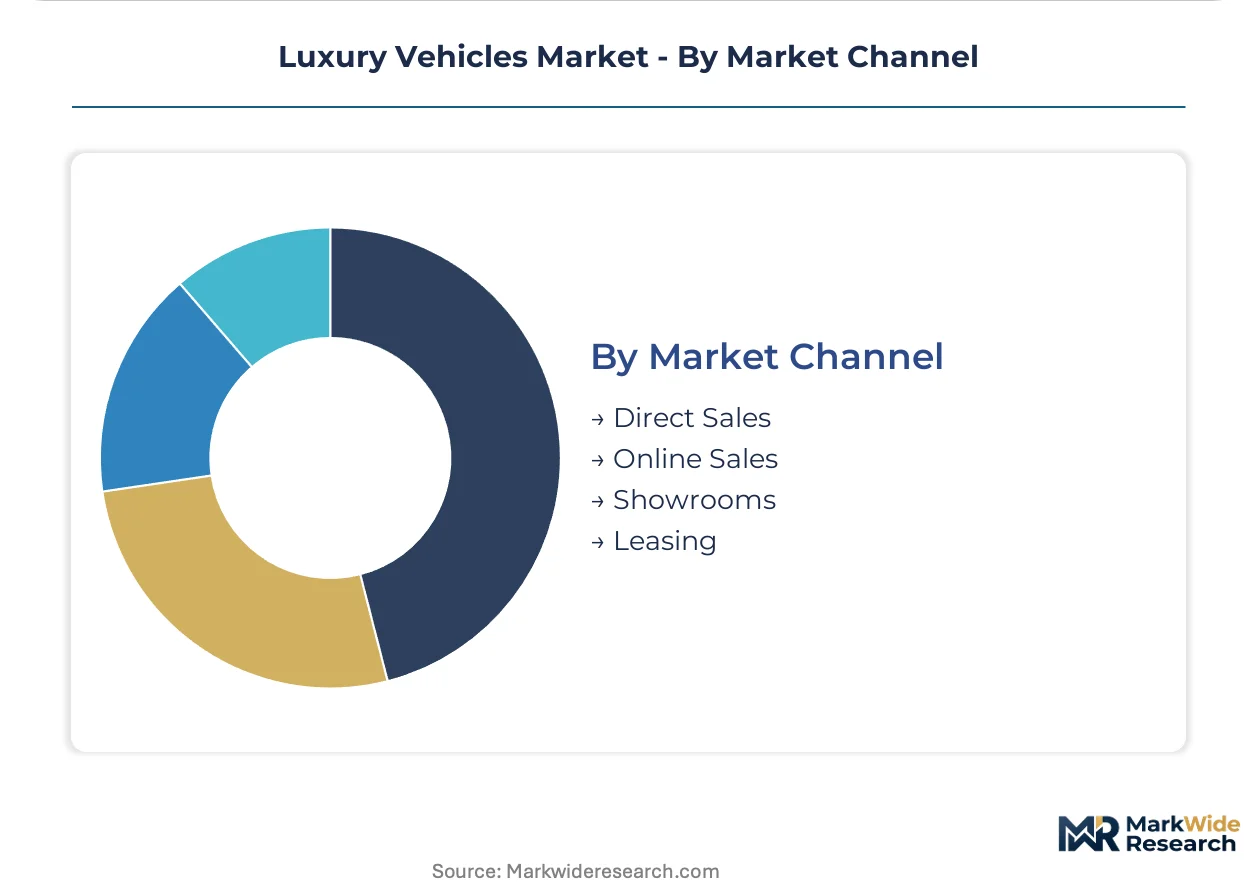
Market Channel:
Distribution architecture selection affects customer acquisition costs and lifetime value capture through recurring revenue streams.
- Direct Sales:Manufacturer-owned stores eliminate franchise margins while controlling pricing and brand presentation. Tesla's company-owned network in the United States and NIO's user centers in Shanghai demonstrate this model's capital intensity and customer data advantages.
- Online Sales:Configurator-based purchasing with home delivery reduces physical footprint requirements while expanding geographic reach. COVID-accelerated adoption in the United Kingdom and South Korea has normalized remote luxury vehicle acquisition.
- Showrooms:Traditional retail environments enable tactile material evaluation and test drive experiences. High-rent district locations in Paris, Milan, and Tokyo sustain foot traffic through experiential marketing investments.
- Leasing:Captive finance arms bundle depreciation risk with maintenance and insurance into predictable monthly outflows. Mercedes-Benz's lease-to-own hybrids and BMW's flexible monthly plans demonstrate how this channel extends customer relationships beyond initial transactions.
Showrooms retain the dominant share of transaction volume; online sales are expanding most quickly as digital-native buyers enter the luxury segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentration in Germany and China contrasts with consumption growth in emerging wealth centers. Assembly plants in Stuttgart and Shanghai supply vehicles to buyers across divergent regulatory environments. Regional demand patterns reflect infrastructure maturity, emissions policy stringency, and generational wealth formation timelines.
China
MIIT credit quotas force joint-venture partners to localize electric luxury production or sacrifice market access. Tier-one cities concentrate demand for extended-wheelbase SUVs with third-row seating driven by multi-generational household mobility. Shanghai's Pudong district hosts NIO user centers demonstrating direct-sales capital intensity.
Germany
EMA-enforced CO2 fleet-average mandates compel Stuttgart and Munich marques to phase out combustion engines ahead of consumer-driven demand curves. KBA type-approval processes extend development cycles for automated driving functions above SAE Level 2. Baden-Württemberg's engineering clusters specialize in powertrain electrification and precision manufacturing.
United States
EPA tailpipe regulations and California's ZEV program create bifurcated compliance obligations for premium manufacturers. Texas and Florida sustain demand for large-displacement internal combustion configurations where charging infrastructure remains sparse. Detroit's captive finance arms bundle lease-to-own hybrids into recurring revenue frameworks.
United Kingdom
London congestion pricing and ULEZ boundaries amplify total cost of ownership sensitivity among executive fleet managers. Financial services firms shift from three-year lease commitments toward flexible monthly subscriptions covering insurance and maintenance. The Midlands retain specialist coachbuilding capabilities for chauffeur-driven configurations.
United Arab Emirates
Fuel subsidies and sparse charging infrastructure sustain demand for turbocharged V8 configurations in Dubai and Abu Dhabi. Secondary vehicle purchases favor two-door coupes for personal use rather than family transport. Airport-based premium rental channels concentrate demand for recognizable marques with proven durability records.
Luxury Vehicles Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Consolidation around heritage marques with century-long brand equity creates high barriers for new entrants. Three archetypes dominate: full-line manufacturers spanning mass-market to ultra-luxury, dedicated premium specialists, and captive luxury divisions of volume producers. Strategic moves center on platform consolidation for electric skateboard architectures and captive finance arm expansion into subscription-based ownership models.
Among heritage German manufacturers, Mercedes-Benz, BMW, and Audi occupy positions exemplifying full-line diversification across powertrain architectures and body styles. Stuttgart-based Mercedes-Benz anchors the premium tier through its captive finance integration. Munich-based BMW represents flexible mobility strategy execution. Ingolstadt-based Audi sits within the Volkswagen Group structure, illustrating conglomerate-backed premium positioning. These three exemplify how engineering heritage and manufacturing scale interact with electrification mandates.
| Leading Market Players |
|---|
| Genesis |
| Cadillac |
| Lexus |
| Acura |
| Porsche |
| Mercedes-Benz |
| Audi |
| Volvo |
| BMW |
| Others |
Supply Flow & Price Mechanics
Captive finance integration through manufacturer-owned leasing arms anchors pricing power by decoupling sticker price from monthly accessibility, while simultaneously securing supply chain visibility through fleet renewal predictability. This vertical control over both capital allocation and procurement timing lets Stuttgart and Munich marques smooth raw material volatility across multi-year contract structures.
Pricing Analysis
Margin tightening in electric powertrains reflects lithium carbonate volatility and cathode material spot-market swings. Three-tier pricing structure across ultra-luxury, premium, and entry-luxury levels segments buyers by concierge service depth and customization granularity. Cost-down pressure on base electric variants accelerates because MIIT credit quotas force localization subsidies that compress export margins. Fleet operators exhibit highest price sensitivity due to depreciation curve optimization, while individual affluent consumers absorb badge premiums with minimal elasticity.
Supply Chain Analysis
Qualification gating through automotive safety integrity level certification restricts cell-to-pack engineering partnerships to tier-one integrators with proven thermal management track records. Battery supply concentrates in China, South Korea, and Japan, with European gigafactory buildouts attempting reshoring. Cathode chemistry draws from Chilean and Australian spodumene deposits, creating geographic chokepoints. Single-source vulnerability in 7nm semiconductor fabrication at TSMC and Samsung foundries threatens advanced driver-assistance system rollout timelines. Distribution runs through captive finance arms and direct-sales flagships in tier-one urban clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
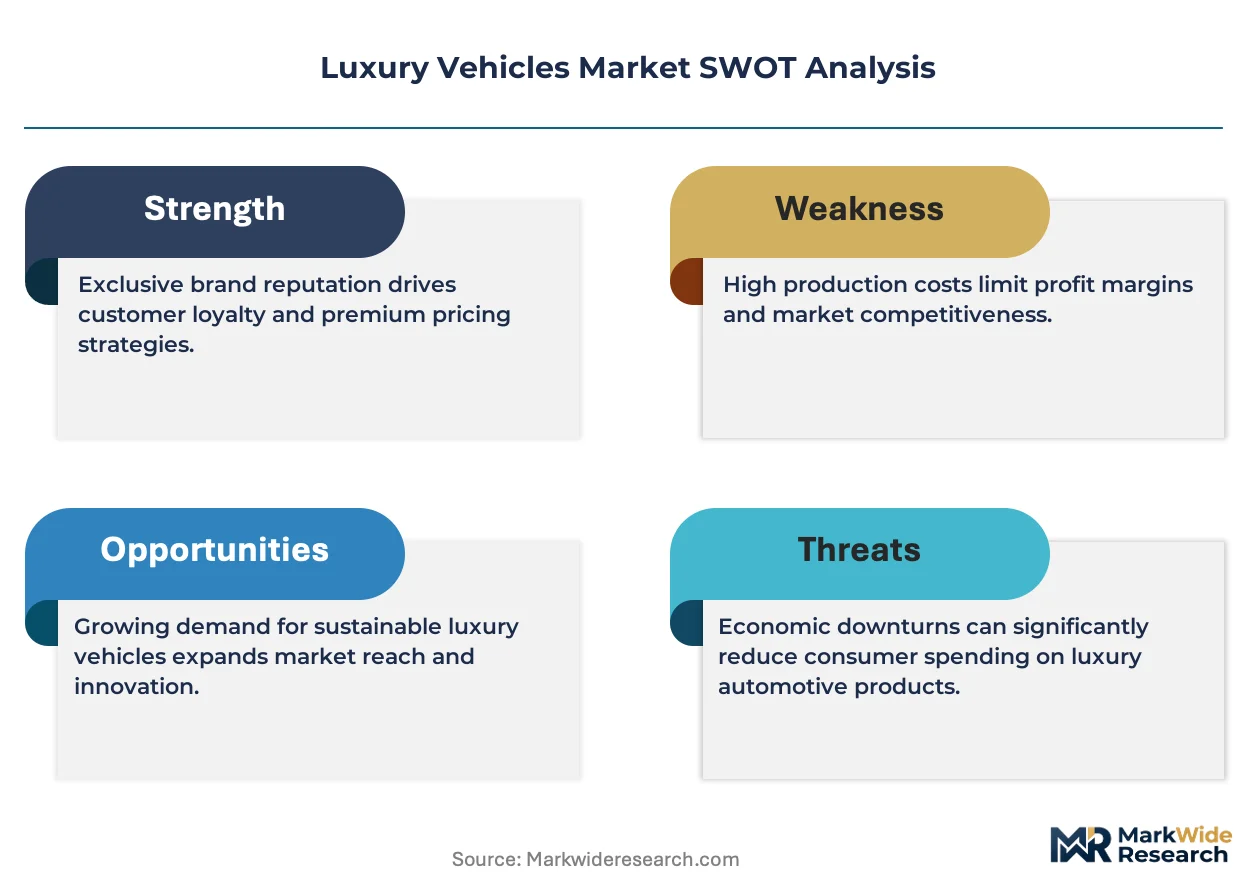
Solid-state battery manufacturing capacity constitutes the binding constraint propping pricing power across electric luxury platforms, as cell qualification timelines extend development cycles beyond demand curves.
For Market Incumbents: Deploy platform consolidation across scalable skateboard architectures to amortize electrification R&D across SUV, sedan, and coupe derivatives. Deepen backward integration into cathode material processing through EU Green Deal subsidy capture. Defensive moves must counter emerging pure-play electric entrants from China with localized joint-venture assembly and MIIT credit banking. For New Entrants and Emerging Players: The price-point gap between established German marques and volume-brand premium divisions creates white-space for software-defined vehicle specialists. Southeast Asian first-generation wealth centers in Indonesia and Vietnam present underpenetrated demand for compact electric crossovers. Battery-as-a-service subscription models lower entry barriers while securing recurring revenue without full manufacturing footprint investment. For Investors and Strategic Acquirers: Exit pathways concentrate in platform technology acquisitions by conglomerates seeking electrification acceleration. Five-to-ten year viability hinges on solid-state battery patent portfolios and automated driving algorithmic accountability documentation. Target tier-one integrators with direct cell sourcing relationships and thermal management IP. Watch KBA type-approval timeline extensions as inflection signals for European market access friction.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Skateboard architectures amortize development costs across SUV, sedan, and coupe derivatives at Mercedes-Benz and BMW. |
| Battery Supply Agreement | Direct cathode material offtake from Chilean and Australian deposits secures European gigafactory feedstock. |
| Software-Defined Vehicle Investment | Over-the-air feature monetization extends revenue capture across vehicle lifecycles beyond initial transaction. |
| Geographic Manufacturing Footprint | MIIT-mandated joint-venture localization preserves market access against NEV credit quota penalties. |
| Charging Infrastructure Partnership | DC fast-charging density expansion in rural United States corridors addresses luxury buyer range anxiety. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs combining with primary interviews across OEM platform engineers, Tier 1 supplier procurement leads, captive finance operations directors, and dealership network managers. Vehicle production databases from IHS Markit, EMA fleet-average compliance disclosures, MIIT NEV credit filings, and EPA tailpipe certification records provided demand-side triangulation. Bottom-up segmentation modeling and top-down macroeconomic reconciliation validated volume and value estimates.
Data-stream reconciliation across powertrain architecture adoption curves, regional regulatory compliance timelines, and content-per-vehicle material cost indices generated consistent projections across the analysis window. Segmentation dimensions modeled include vehicle class, propulsion architecture, OEM tier, and regional production cluster. CAGRs derived from regression against battery chemistry cost compression trajectories and charging infrastructure density buildout schedules, with solid-state battery commercialization timelines and EU AI Act algorithmic accountability protocols as scenario-weighting inputs.
Inputs from KBA type-approval databases and NMPA homologation registries were available through the study window; gaps in solid-state battery manufacturing yield data introduce uncertainty bands around electric vehicle cost parity assumptions. Forecasts reflect documented assumptions regarding lithium supply concentration and semiconductor fabrication capacity expansion. A model refresh is warranted upon material change in EU EMA fleet-average mandate stringency or MIIT NEV credit quota recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passenger Vehicles
Europe Luxury Car Market
Passenger Vehicles
Train Seat Market
Passenger Vehicles
Solar Passenger Car Market
Passenger Vehicles
Electric Passenger Car MRO Market
Passenger Vehicles
Russia Light Vehicle Market
Passenger Vehicles
Small Suvs Market
Passenger Vehicles
Ghana Automobile Market
Passenger Vehicles
India Automotive Market
Passenger Vehicles
Family Car Market
Passenger Vehicles
North American Lightweight Car Market
Passenger Vehicles
Quadricycle and Tricycle Market
Passenger Vehicles
Latin America Passenger Car Market
Passenger Vehicles
Microcars Market
Passenger Vehicles
Large Suvs Market
Passenger Vehicles
Global Passenger Cars Market
Passenger Vehicles
Compact Cars Market