
 Electric Passenger Car MRO Market | 2026-2036
Electric Passenger Car MRO Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Passenger Car MRO Market Foresight
China is narrowing the gap between OEM-authorized and independent repair capacity through aggressive technician certification programs. Robert Bosch GmbH leverages its diagnostic tool ecosystem to anchor aftermarket service workflows across multiple voltage platforms. Tesla, Inc. sustains tight control over battery system repairs through proprietary software locks and restricted parts distribution. Continental AG competes on brake-by-wire and thermal management component replacement for multi-brand fleets.
Electric Passenger Car MRO encompasses the technical servicing, repair, component refurbishment, and software recalibration of battery-electric passenger vehicles, requiring specialized high-voltage safety protocols above 60V DC and isolation testing equipment. The primary commercial purpose is to extend vehicle operational life while ensuring electrochemical system integrity and occupant safety. Battery system services command the deepest margin pools due to cell-level diagnostics and thermal runaway prevention requirements, while telematics solutions represent the fastest-expanding segment as predictive maintenance algorithms reduce unscheduled downtime. Fleet operators generate the most concentrated demand volume, though individual owners drive higher per-visit revenue through upgrade-oriented spending.
The EU Battery Directive and China's MIIT GB standards mandate traceable cell replacement and state-of-health documentation, forcing MRO providers to invest in blockchain-enabled lifecycle tracking. India's BIS certification requirements for high-voltage equipment create market access barriers for uncertified independent shops. The US EPA and NHTSA coordinate on end-of-life battery handling rules that affect reverse logistics economics. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded service investments.
Market Dynamics
Battery safety certification requirements above 60V DC are forcing MRO providers to restructure technician training programs and capital deployment, concentrating service capability among OEM-affiliated networks and certified independent operators.
Growth Catalysts
- EU Battery Directive traceability mandates:Lifecycle documentation requirements for cell replacement are expanding the addressable market for blockchain-enabled service platforms across Germany, France, and the Netherlands.
- Fleet electrification in urban logistics:Commercial operators operating delivery and ride-hailing vehicles are consolidating service contracts to minimize downtime through predictive maintenance scheduling.
- High-voltage diagnostic tooling:Isolation testing equipment and thermal imaging systems are enabling independent shops to access previously OEM-captive battery system repairs.
Market Restraints
- Lithium-ion cell supply concentration:Cathode material processing capacity clusters in China, exposing European and North American MRO providers to input cost volatility and geopolitical supply disruptions.
- Proprietary software lock architectures:Vehicle manufacturers restrict battery management system access through encrypted controller networks, limiting third-party diagnostic capabilities.
- Specialized facility capex requirements:Thermal runaway containment infrastructure and high-voltage safety bays demand capital investments that exclude small independent operators from premium service segments.
Strategic Opportunities
- India's BIS high-voltage certification gap:The country's nascent EV fleet and limited certified service infrastructure create first-mover positioning for training program providers and equipment distributors.
- Second-life battery refurbishment:Stationary energy storage applications for degraded automotive packs are extending value capture beyond vehicle service into grid-scale asset management.
- Telematics-platform integration:Fleet management software convergence with predictive maintenance algorithms is enabling subscription-based revenue models for component replacement timing optimization.
Industry Challenges
- High-voltage technician scarcity:Electrochemical system safety training programs produce insufficient certified personnel relative to fleet expansion rates, inflating labor costs and service backlogs.
- Multi-voltage platform complexity:Service bays must maintain competency across 400V, 800V, and emerging 1200V architectures simultaneously, fragmenting tooling investment and technician specialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Passenger Car MRO Market |
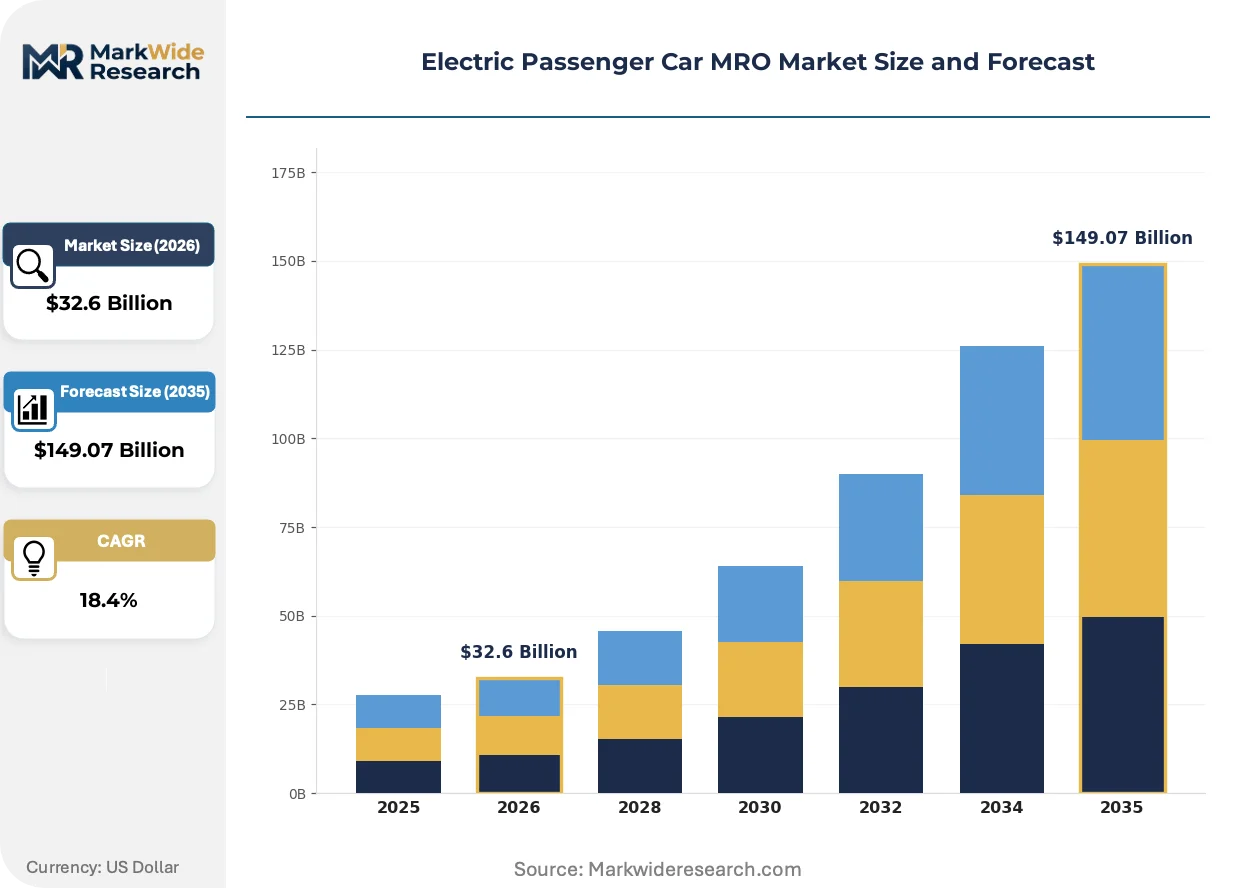
| Market Size in 2026 | $32.6 Billion |
| Market Size in 2035 | $149.07 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Routine Maintenance, Repair Services, Parts Replacement, Upgrades Component: Battery System, Electric Drive Unit, Suspension System, Braking System End User: Fleet Operators, Individual Owners, Rental Companies, Repair Shops Technology: Telematics Solutions, Diagnostic Tools, Software Platforms, Battery Management Systems |
| Companies Covered | Robert Bosch GmbH, Tesla, Inc., Continental AG, ZF Friedrichshafen AG, Hyundai Motor Company, General Motors, ST Engineering, LKC Corporation, The Hybrid Shop, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Passenger Car MRO Market Shifts & Advancements
Telematics integration and predictive algorithms are compressing maintenance scheduling from reactive breakdown response to continuous health monitoring, restructuring how fleet operators contract for service capacity and how providers price risk.
Cloud-connected battery management systems are digitizing cell-level performance tracking across distributed vehicle populations. Fleet operators in Germany and California are adopting these platforms fastest, enabling condition-based replacement rather than calendar-based intervals. This capability is digitizing warranty risk transfer from vehicle owners to MRO providers through outcome-guaranteed service contracts.
China's MIIT GB standards for thermal runaway propagation testing are mandating redesigned battery pack architectures with enhanced cell-to-cell isolation. Domestic manufacturers must redesign service protocols for disassembly and reassembly. European MRO providers importing Chinese EV platforms face certification lag as they adapt to these structural battery changes.
Commercial fleet procurement is consolidating around multi-year service agreements bundling predictive software, component replacement, and residual value guarantees. Leasing companies and logistics operators in the Netherlands and Norway are displacing transactional repair relationships with integrated mobility-service contracts. This restructuring concentrates volume among providers capable of underwriting battery performance risk.
Electric Passenger Car MRO Market Segmentation
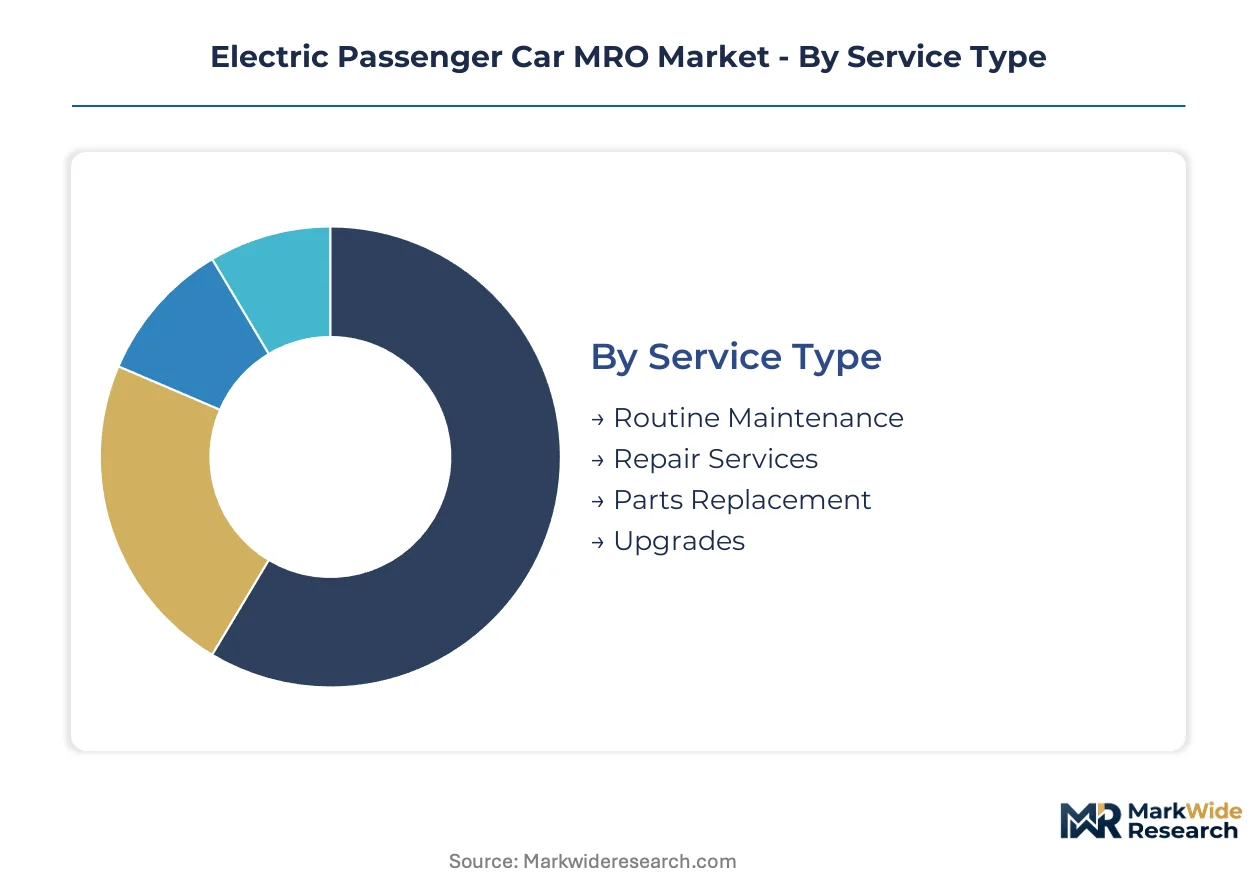
Segmentation in electric passenger car MRO reveals divergent margin structures and capability requirements across service modalities. Each dimension—service type, component focus, end user, and technology stack—commands distinct capital deployment and technician specialization profiles.
Service Type:
Mature revenue streams coexist with emerging high-margin categories as electrification redefines maintenance protocols.
- Routine Maintenance:Scheduled inspections of thermal management systems, cabin climate control, and high-voltage cable integrity. Fleet operators in Germany and California consolidate these contracts into multi-year agreements to minimize vehicle downtime.
- Repair Services:Corrective interventions addressing powertrain faults, charging system failures, and collision-related electrical damage. Individual owners generate premium pricing through urgent demand and limited certified provider availability.
- Parts Replacement:Component-level substitution of degraded modules rather than full system overhaul. China's MIIT traceability mandates are extending documentation requirements across cell replacement workflows.
- Upgrades:Performance enhancement and range extension through software recalibration and hardware retrofits. Early adopters in Norway and the Netherlands drive concentrated demand for battery capacity augmentation.
Routine Maintenance handles the majority of throughput; Upgrades is gaining share fastest as residual value optimization becomes central to fleet economics.
Component:
Cost tier differentiation separates capital-intensive battery services from mechanical systems with established aftermarket infrastructure.
- Battery System:Cell-level diagnostics, thermal runaway prevention, and state-of-health recalibration requiring isolation testing equipment above 60V DC. OEM-affiliated networks dominate in Germany due to proprietary software access restrictions.
- Electric Drive Unit:Motor, inverter, and gearbox servicing across 400V to 800V architectures. Independent shops in North America are acquiring competency through Bosch-certified training programs.
- Suspension System:Weight-distribution adjustments and regenerative braking integration calibration. Standard tooling requirements enable broad independent shop participation.
- Braking System:Brake-by-wire maintenance and friction material replacement for blended regenerative-mechanical systems. Continental AG anchors aftermarket supply for multi-brand fleet operators.
Battery System commands the deepest margin pools; Electric Drive Unit is expanding most quickly as powertrain diversity increases.
End User:
Volume concentration versus per-transaction value creates divergent go-to-market structures across customer types.
- Fleet Operators:Commercial logistics and ride-hailing platforms operating centralized vehicle pools. Predictive maintenance subscriptions are displacing transactional repair relationships in the Netherlands.
- Individual Owners:Private vehicle users with sporadic service needs and upgrade-oriented spending patterns. Higher per-visit revenue offsets lower frequency compared to fleet contracts.
- Rental Companies:Short-term mobility providers prioritizing rapid turnaround and residual value preservation. Standardized service protocols across vehicle classes reduce operational complexity.
- Repair Shops:Independent and OEM-affiliated service providers purchasing diagnostic equipment and technical training. India's BIS certification requirements are constraining uncertified market entry.
Fleet Operators drive the largest contract volumes; Repair Shops as a customer segment for equipment and training is climbing the fastest.
Technology:
Application focus determines whether providers capture recurring software revenue or one-time hardware sales.
- Telematics Solutions:Cloud-connected vehicle monitoring enabling predictive component replacement. California-based fleet operators are adopting these platforms fastest for warranty risk transfer.
- Diagnostic Tools:Isolation testers, thermal imagers, and high-voltage measurement equipment. Bosch's ecosystem anchors aftermarket workflows across multiple voltage platforms.
- Software Platforms:Battery management system interfaces and over-the-air update infrastructure. Tesla's proprietary locks restrict third-party access to critical calibration functions.
- Battery Management Systems:Cell balancing algorithms and thermal runaway detection firmware. EU Battery Directive traceability mandates are expanding addressable market for lifecycle documentation providers.
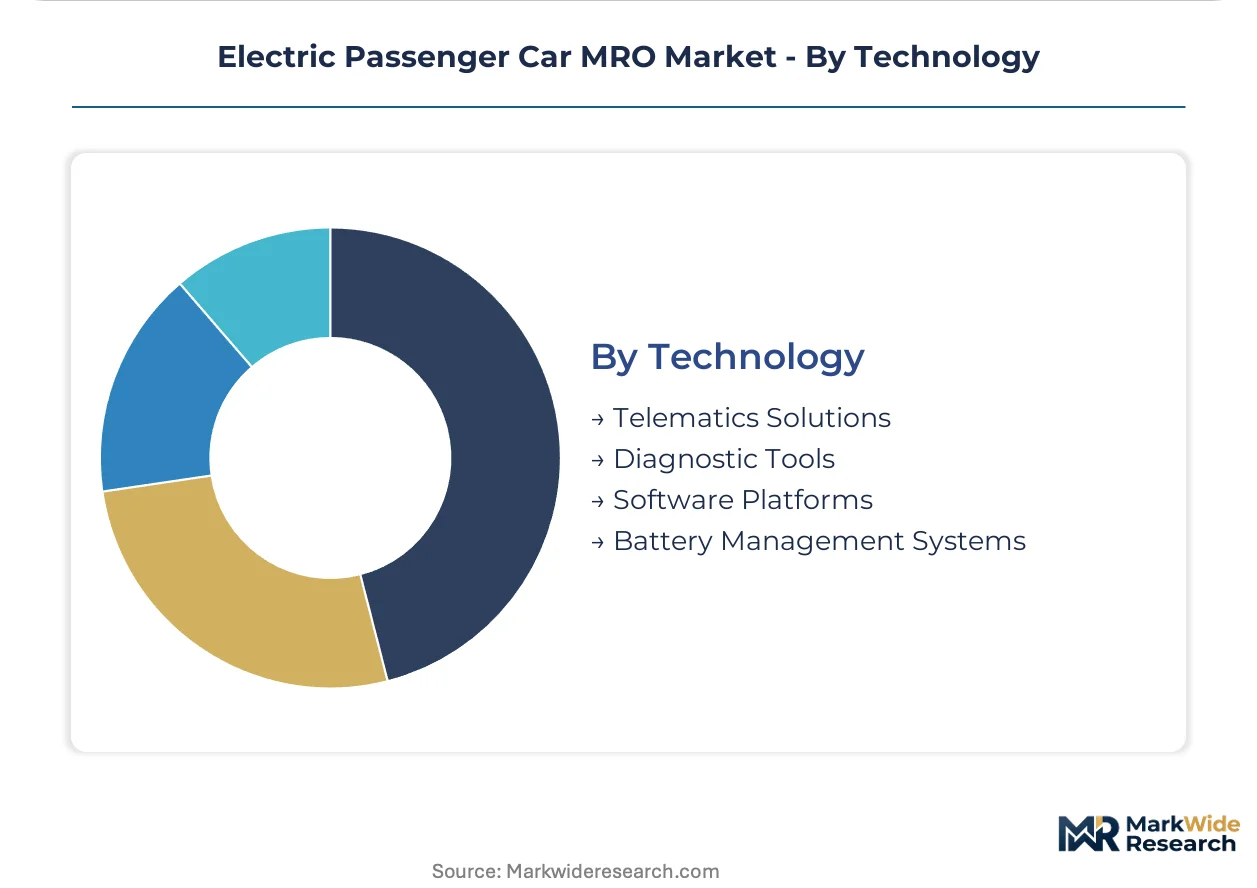
Diagnostic Tools handle the majority of equipment shipments; Telematics Solutions shows the steepest expansion trajectory as fleet digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT's GB standards for thermal runaway testing anchor China's regulatory framework, while Germany's KBA enforces strict high-voltage certification protocols. Fleet electrification concentrates service demand across distinct national clusters with divergent compliance requirements.
Germany
OEM-affiliated networks dominate battery system repairs through proprietary software access and KBA-mandated technician certification. The EU Battery Directive's traceability mandates force blockchain-enabled lifecycle documentation across cell replacement workflows. Stuttgart and Munich anchor the densest concentration of high-voltage service bays serving commercial fleet operators.
United States
California-based fleet operators adopt telematics platforms fastest for warranty risk transfer through predictive maintenance algorithms. NHTSA coordinates with EPA on end-of-life battery handling rules affecting reverse logistics economics. The San Francisco Bay Area and Los Angeles metro cluster independent shops acquiring Bosch-certified diagnostic competencies.
China
Domestic manufacturers redesign service protocols for disassembly under MIIT GB thermal runaway propagation testing standards. Aggressive technician certification programs narrow the gap between OEM-authorized and independent repair capacity. Shenzhen and Shanghai concentrate the largest pools of certified high-voltage technicians serving ride-hailing electrification.
India
BIS certification requirements for high-voltage equipment create market access barriers for uncertified independent shops. The country's nascent EV fleet and limited certified service infrastructure attract first-mover training program providers. Maharashtra and Karnataka host emerging equipment distribution hubs targeting fleet electrification in urban logistics.
Netherlands
Leasing companies and logistics operators displace transactional repair relationships with integrated mobility-service contracts. Predictive maintenance subscriptions consolidate volume among providers capable of underwriting battery performance risk. Amsterdam and Rotterdam anchor multi-brand fleet service agreements bundling software and component replacement.
Electric Passenger Car MRO Market Competitive Landscape
OEM-captive service networks and independent aftermarket specialists split the market along software access fault lines. Tier-one automotive suppliers leverage diagnostic tool ecosystems to anchor multi-brand workflows. Two strategic archetypes dominate: integrated mobility-service providers bundling predictive software with risk-bearing contracts, and equipment-certification platforms enabling independent shop competency acquisition. Competitive moves concentrate on technician training program scaling and telematics-platform integration for subscription revenue capture.
Within the equipment-certification tier, Robert Bosch GmbH exemplifies the diagnostic ecosystem archetype across voltage platforms. Tesla, Inc. occupies a position representing OEM-captive control through proprietary software architectures. Continental AG anchors the component-replacement specialist archetype for brake-by-wire and thermal management systems serving multi-brand fleets.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Tesla, Inc. |
| Continental AG |
| ZF Friedrichshafen AG |
| Hyundai Motor Company |
| General Motors |
| ST Engineering |
| LKC Corporation |
| The Hybrid Shop |
| Others |
Supply & Pricing Matrix
Cathode material processing capacity clusters in China, concentrating pricing power among cell manufacturers and compressing margin capture for European and North American MRO providers dependent on imported battery modules.
Pricing Analysis
German OEM-affiliated service bays command 40-60% premiums over independent shops for battery system repairs, reflecting KBA certification requirements and proprietary software access restrictions. Three-tier pricing structure across premium-certified, standard-compliant, and economy-basic levels separates fleet contract rates from individual owner walk-in pricing. Cost compression in the independent tier is intensifying because Bosch-certified diagnostic tools democratize high-voltage competency. Fleet operators exhibit lowest price sensitivity due to warranty risk transfer demands, while individual owners in India and Southeast Asia drive aggressive negotiation on routine maintenance.
Supply Chain Analysis
Extended payment terms from 60 to 90 days dominate supplier-finance arrangements for isolation testing equipment and thermal imaging systems, straining working capital for independent shop equipment distributors. Lithium carbonate and nickel sulfate draw from Chilean mining operations and Indonesian processing facilities, with cell assembly concentrating in China, South Korea, and Japan. Single-source vulnerability runs through Chinese cathode active material suppliers subject to export license uncertainty. Distribution runs through Bosch-authorized equipment distributors and OEM-captive parts networks serving multi-brand fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat arena where KBA and MIIT certification requirements create switching costs that protect incumbent service networks from price erosion.
For Market Incumbents: Harden proprietary software control over battery management system calibration to defend against Bosch-enabled independent competitors. Expand backward integration into second-life battery refurbishment to capture grid-storage value streams beyond vehicle service. Prioritize technician training program scaling in India before BIS certification requirements mature. For New Entrants and Emerging Players: Pursue India's uncertified independent shop segment through BIS-aligned training program partnerships with equipment distributors. Target telematics-platform integration for Dutch and Norwegian fleet operators displacing transactional repair relationships. Lead with subscription-based predictive maintenance offerings rather than per-service pricing. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed diagnostic equipment distributors consolidating regional training networks. Five-to-ten year viability hinges on regulatory divergence between EU Battery Directive traceability mandates and China's MIIT GB standards creating dual-certification overhead. Watch for MIIT export restriction signals on battery management system firmware as inflection indicator for captive-versus-independent repair balance.| Strategic Initiative | Industry Significance |
|---|---|
| Technician Certification Program Scaling | BIS-aligned training investments capture India's nascent EV fleet before regulatory barriers mature. |
| Telematics Platform Integration | Predictive maintenance subscriptions displace transactional repair relationships among Dutch fleet operators. |
| Second-Life Battery Refurbishment | Grid-storage applications extend value capture beyond vehicle service into stationary energy asset management. |
| Proprietary Software Lock Reinforcement | Encrypted controller networks defend OEM-captive battery system repairs against independent diagnostic competition. |
| Multi-Voltage Diagnostic Tool Development | 400V-to-800V competency expansion enables independent shops to service powertrain diversity across fleet populations. |
Research Methodology
A standing panel of aftermarket service directors, high-voltage technician training leads, fleet procurement managers, and OEM platform engineers provided ongoing calibration against secondary validation from MIIT GB standard filings, EU Battery Directive implementation guidelines, KBA certification databases, and IHS Markit vehicle registration data. Bottom-up service bay capacity modeling triangulated against top-down fleet electrification projections.
Scenario-bracketing around MIIT thermal runaway testing evolution and EU traceability mandate enforcement timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include service type modality, component system focus, end-user archetype, and voltage platform architecture. CAGRs derived from technician supply-demand gap analysis and fleet contract pricing elasticity. Forecast inputs incorporated BIS certification rollout pace and lithium carbonate price volatility assumptions.
Sensitivities concentrate around MIIT export license restrictions on battery management system firmware and EU Battery Directive enforcement variance across member states. Forecasts reflect documented assumptions on fleet electrification cadence and high-voltage technician training completion rates. Macroeconomic contraction, regulatory acceleration, or solid-state battery commercialization would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passenger Vehicles
India Automotive Market
Passenger Vehicles
South America Passenger Cars Market
Passenger Vehicles
Limousines Market
Passenger Vehicles
Sports Utility Vehicles (Suvs) Market
Passenger Vehicles
Large Suvs Market
Passenger Vehicles
Compact Cars Market
Passenger Vehicles
Electric Sports Car Market
Passenger Vehicles
North America Automotive Market
Passenger Vehicles
Microcars Market
Passenger Vehicles
Asia Pacific Luxury Cars Market
Passenger Vehicles
Automotive Passenger Vehicle Sensor Market
Passenger Vehicles
Latin America Passenger Car Market
Passenger Vehicles
Family Car Market
Passenger Vehicles
Global Luxury SUV Market
Passenger Vehicles
Quadricycle and Tricycle Market
Passenger Vehicles
Minivans Market