
 Indonesia Passenger Car Market | 2026-2036
Indonesia Passenger Car Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Passenger Car Market Insights
Modular feature bundling is hardening as the dominant configuration pattern in Indonesia's passenger car market, with buyers increasingly expecting advanced safety and connectivity packages even in entry-level trims. Toyota Motor Manufacturing Indonesia leverages its extensive local supplier network to sustain cost advantages across the LCGC segment. Honda Manufacturing Indonesia differentiates through hybrid technology leadership, while Hyundai Motor Manufacturing Indonesia competes aggressively on electric vehicle readiness and dedicated EV platform localization.
An Indonesia passenger car is a wheeled motor vehicle designed to transport up to eight passengers, typically featuring unibody construction, front-engine layout, and compliance with local fuel efficiency standards measured in kilometers per liter. Its primary commercial purpose is personal mobility, fleet services, and ride-hailing operations across Indonesia's archipelagic geography. The SUV segment dominates volume as Indonesian buyers prioritize ground clearance and cabin flexibility for varied road conditions. The hybrid engine category represents the fastest-growing technology trajectory, driven by government tax incentives and fuel price sensitivity among middle-class consumers.
Indonesia's Ministry of Industry enforces LCGC regulations that mandate minimum domestic content and fuel consumption thresholds, directly shaping which powertrains manufacturers can profitably offer. BIS-equivalent national standards and the country's energy ministry directives on biofuel blending further constrain product planning and import dependencies. Stakeholders must monitor regulatory adjustments to electric vehicle incentives and local content requirements as these will determine competitive positioning in the next product cycle.
Market Dynamics
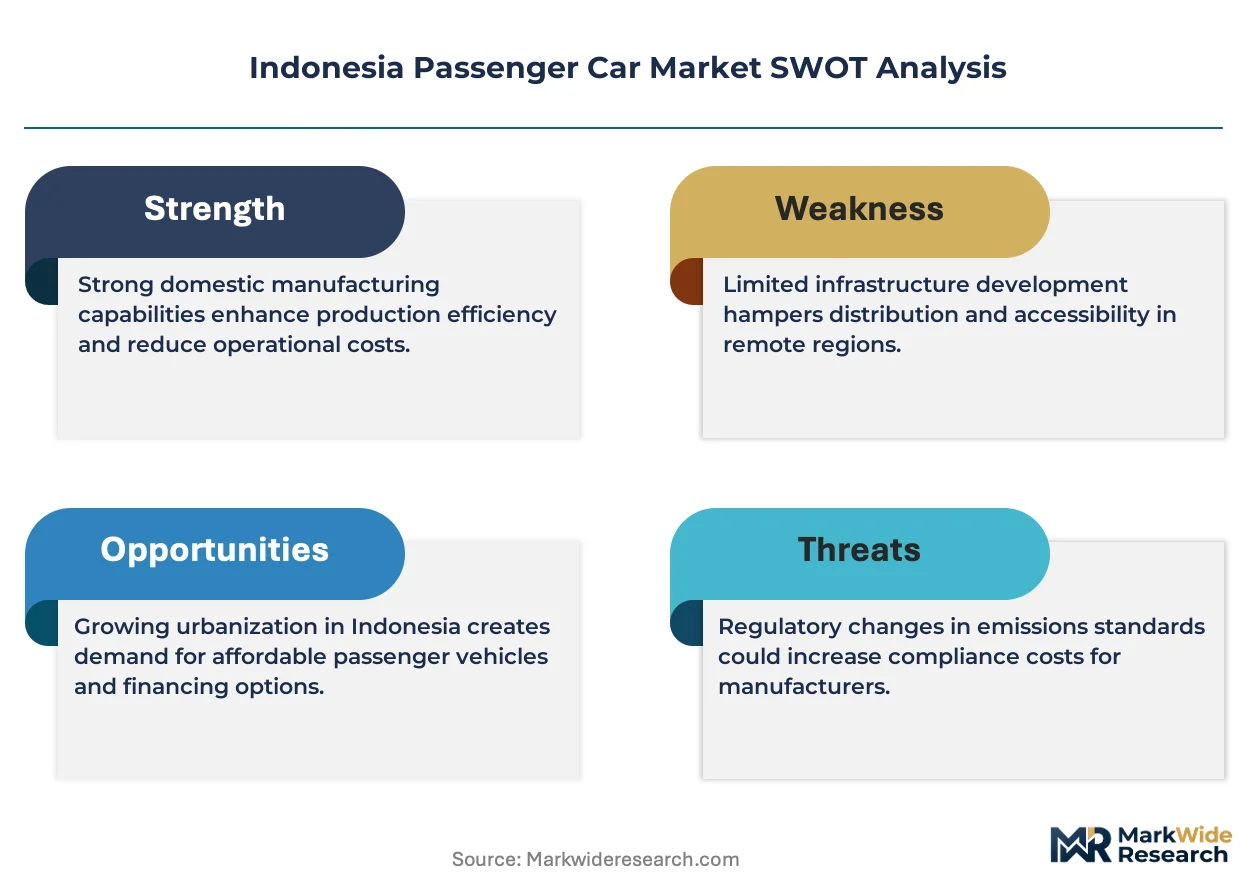
Indonesia's LCGC regulatory framework is compressing engine displacement allowances while simultaneously mandating higher local content thresholds, forcing manufacturers to reconfigure powertrain portfolios and supplier networks simultaneously.
Growth Catalysts
- Hybrid powertrain adoption:Indonesia's Ministry of Industry tax incentives for electrified vehicles are accelerating fleet operator procurement of full-hybrid systems for ride-hailing services in Jakarta and Surabaya.
- LCGC compliance pathways:The Low Cost Green Car program's fuel efficiency thresholds are channeling R&D investment toward lightweight materials and downsized turbocharged engines.
- Java corridor demand density:Greater Jakarta's urban agglomeration concentrates passenger car volume, enabling scale economies in distribution and after-sales service infrastructure.
Market Restraints
- Domestic content mandates:LCGC rules requiring minimum local sourcing create supplier qualification bottlenecks for new entrants lacking established Indonesian manufacturing partnerships.
- Biofuel blending mandates:The energy ministry's B30 and advancing B40 directives constrain gasoline engine calibration flexibility and import dependency for compatible fuel injection systems.
- Archipelagic logistics costs:Inter-island shipping from Java-based assembly plants to outer island markets inflates delivered vehicle costs versus competitors with distributed regional production.
Strategic Opportunities
- Electric vehicle incentive capture:Pending adjustments to Indonesia's EV tax holiday and import duty exemptions for battery electric vehicles present first-mover positioning advantages for dedicated platform localization.
- Surabaya fleet hub development:East Java's second-city status and expanding ride-hailing operator bases offer underpenetrated volume relative to Jakarta saturation.
- Digital retail channel integration:Direct-to-consumer online configuration and financing platforms are bypassing traditional dealer networks for tech-savvy middle-class buyers.
Industry Challenges
- Powertrain engineering talent scarcity:Indonesia's technical universities produce insufficient hybrid and electric vehicle calibration specialists, forcing manufacturers to import engineering capacity or fund extended training programs.
- Supplier certification timelines:BIS-equivalent national standards validation for new local component sources extends product launch schedules by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Passenger Car Market |
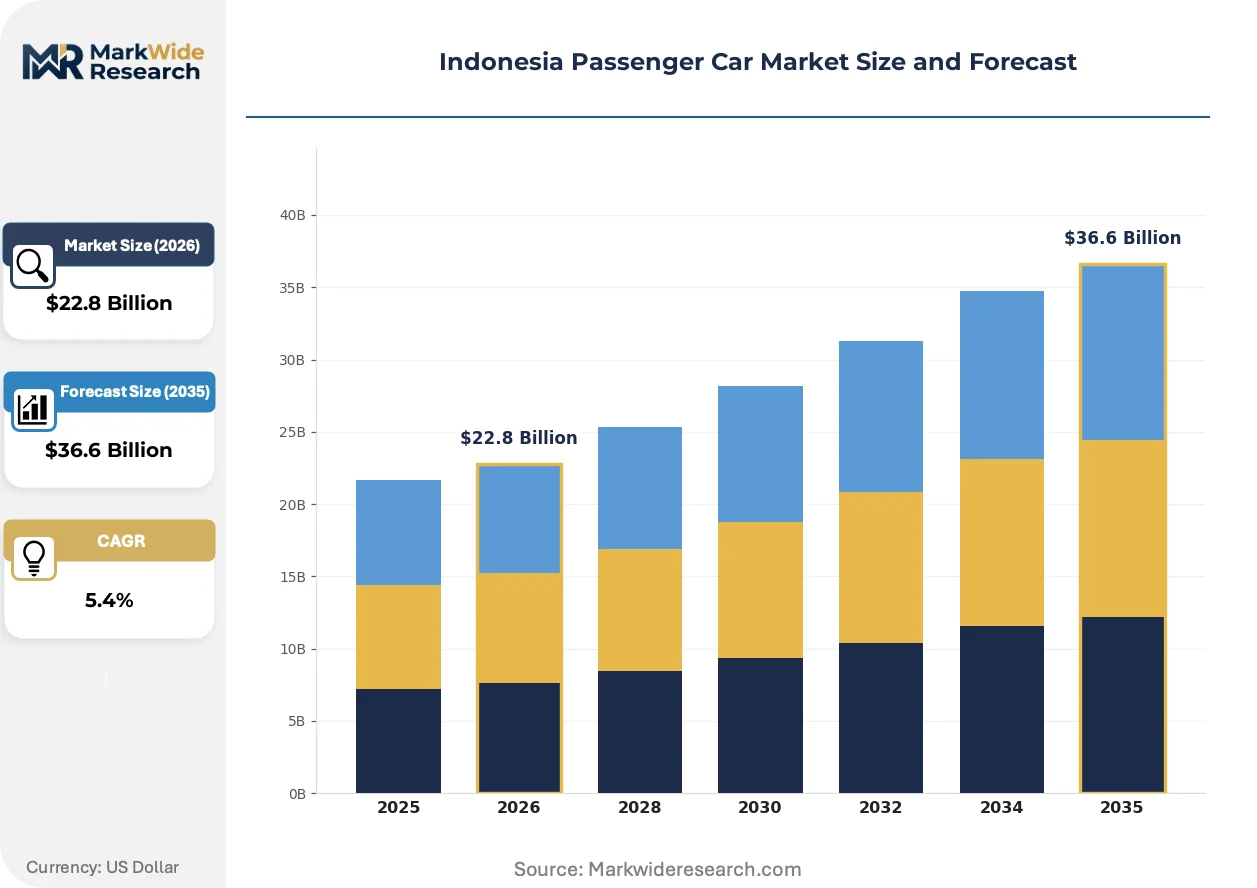
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $36.6 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedan, SUV, Hatchback, Coupe Engine Type: Petrol, Diesel, Electric, Hybrid Transmission: Manual, Automatic, Semi-Automatic, Continuously Variable Fuel Efficiency: Low, Moderate, High, Very High |
| Companies Covered | Suzuki Indomobil Motor, Honda Manufacturing Indonesia, Toyota Motor Manufacturing Indonesia, Wuling Motors Indonesia, SGMW Motor Indonesia, Mitsubishi Motors Krama Yudha Indonesia, Hyundai Motor Manufacturing Indonesia, Sokonindo Automobile, Astra Daihatsu Motor, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Passenger Car Market Trends and Innovations
Digital service integration is redefining ownership expectations across Indonesia's passenger car market, with buyers now evaluating vehicles as connected mobility platforms rather than standalone hardware assets.
Hybrid-electric powertrains are converging with downsized turbocharged gasoline engines to deliver LCGC-compliant fuel efficiency without sacrificing cabin size or ground clearance. Fleet operators in Jakarta's ride-hailing sector are adopting these systems fastest, compressing payback periods through fuel cost savings. The convergence is enabling manufacturers to bridge regulatory thresholds while preserving the SUV body styles Indonesian buyers prioritize for varied road conditions.
Indonesia's Ministry of Industry is tightening local content verification protocols for LCGC qualification, requiring auditable domestic value-add documentation across engine, transmission, and electronics sourcing. The industrial consequence is accelerated supplier park development near existing assembly clusters in Bekasi and Karawang. Entry-level trim manufacturers are responding by deepening captive sourcing relationships to defend program eligibility.
Subscription-based vehicle access models are displacing traditional ownership among urban professionals in Greater Jakarta, with monthly fees bundling insurance, maintenance, and connectivity services. Digital-native fleet aggregators are capturing this demand shift through app-based procurement interfaces. The behavioral pivot is most visible among ride-hailing drivers and young middle-class households prioritizing liquidity over asset accumulation.
Indonesia Passenger Car Market Segmentation
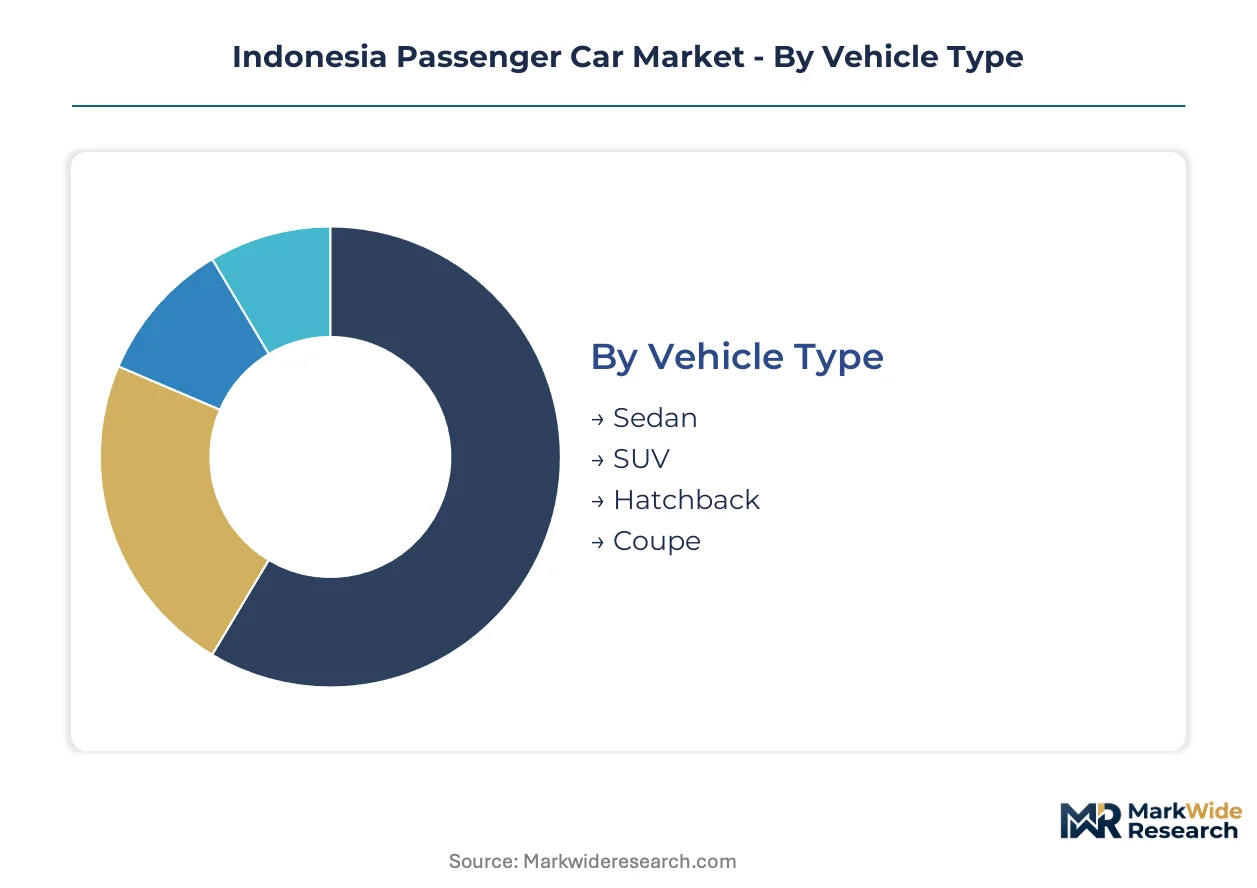
Indonesia's passenger car segmentation reflects divergent upgrade cycles across vehicle architectures and powertrain technologies. Fleet operators and private buyers follow distinct replacement timelines shaped by LCGC compliance windows and ride-hailing depreciation schedules.
Vehicle Type:
Replacement cycles vary sharply by body style, with commercial fleets compressing SUV turnover while sedan ownership extends toward decade-long horizons.
- SUV:Unibody construction with elevated ground clearance dominates Indonesian procurement for varied road conditions across Java and outer islands. Greater Jakarta fleet operators prioritize cabin flexibility and resale liquidity, driving compressed replacement cycles among ride-hailing contractors.
- Sedan:Three-box configuration with dedicated trunk volume retains preference among established middle-class households in Surabaya and Bandung. Private ownership patterns stretch replacement intervals as buyers prioritize fuel efficiency certification over styling updates.
- Hatchback:Two-box compact dimensions align with LCGC dimensional regulations and urban parking constraints in Jakarta's dense core. Young professionals favor this architecture for first-vehicle entry.
- Coupe:Fixed-roof two-door body style occupies niche positioning among enthusiast segments in Indonesia's premium corridors. Limited volume concentrates in Jakarta's affluent districts.
Volume placements concentrate in SUV; the faster expansion belongs to Hatchback.
Engine Type:
Powertrain selection directly determines LCGC program eligibility and tax treatment, creating tiered cost structures across ownership economics.
- Hybrid:Combined internal combustion and electric motor architecture delivers LCGC-compliant efficiency thresholds without range limitations. Jakarta-based ride-hailing fleets adopt this technology fastest as fuel cost sensitivity compresses payback calculations.
- Petrol:Spark-ignition gasoline engines remain the baseline powertrain across Indonesia's entry-level segment, calibrated for B30 biofuel compatibility under energy ministry directives. Surabaya's expanding fleet hubs sustain steady procurement despite efficiency disadvantages.
- Electric:Battery-electric powertrains with zero tailpipe emissions qualify for pending import duty exemptions and tax holidays under Ministry of Industry adjustments. Charging infrastructure gaps in outer islands constrain geographic deployment.
- Diesel:Compression-ignition engines retain commercial utility for high-torque applications but face declining passenger car relevance as LCGC displacement ceilings tighten.
Petrol retains volume dominance; hybrid systems are climbing the fastest.
Transmission:
Transmission architecture influences manufacturing cost structures and local content qualification under LCGC supplier verification protocols.
- Automatic:Torque converter or dual-clutch configurations dominate urban buyer preference for Jakarta's stop-and-go traffic density. Fleet operators specify automatic variants to reduce driver fatigue and training costs.
- Continuously Variable:Pulley-based stepless ratio systems optimize fuel efficiency measurements for LCGC certification thresholds. Toyota Motor Manufacturing Indonesia leverages local CVT sourcing to defend program eligibility.
- Manual:Synchronized mesh gearboxes retain cost advantage in entry-level trims and rural markets where repair accessibility outweighs convenience factors.
- Semi-Automatic:Automated manual transmissions bridge cost and efficiency positioning but occupy narrowing market space between full automatic and CVT alternatives.
Automatic variants capture Jakarta-Surabaya volume; CVT systems gain share fastest on regulatory alignment.
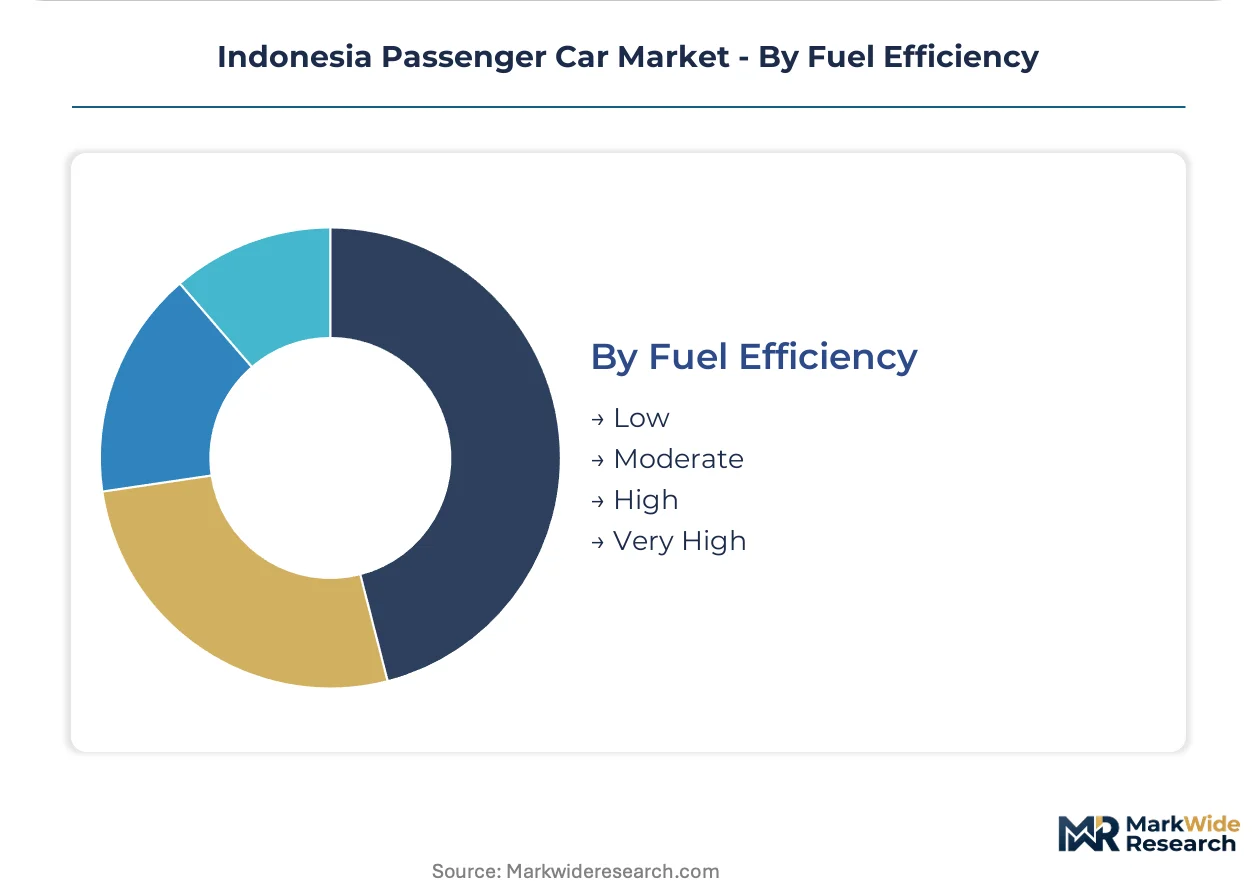
Fuel Efficiency:
Efficiency tiering maps directly to LCGC compliance bands and resulting excise tax differentials, structuring manufacturer portfolio priorities.
- Very High:Exceeds 25 km/liter certification thresholds qualifying for maximum LCGC tax relief and priority fleet procurement. Hybrid-electric architectures and lightweight materials enable this tier.
- High:Delivers 20-25 km/liter performance meeting baseline LCGC requirements for domestic content benefits. Downsized turbocharged engines populate this band.
- Moderate:15-20 km/liter range occupies non-LCGC positioning with higher tax incidence, limiting volume to specific use cases or premium segments.
- Low:Below 15 km/liter classification faces regulatory pressure and shrinking commercial viability outside specialized applications.
High-efficiency tiers dominate Java corridor placements; Very High certification is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's passenger car production concentrates on Java while consumption spreads across an archipelago of 17,000 islands. This geographic mismatch shapes logistics costs and regional market development priorities.
Greater Jakarta
Fleet operators and ride-hailing contractors drive replacement demand in Indonesia's capital corridor. The Ministry of Industry's LCGC fuel efficiency thresholds channel procurement toward hybrid powertrains for taxi services. Assembly clusters in Bekasi and Karawang feed this dense urban market with localized supplier networks.
East Java
Surabaya's expanding middle class sustains private ownership growth outside the capital saturation zone. The provincial government's infrastructure investments improve last-mile connectivity to outer island shipping routes. Local fleet hubs are capturing underpenetrated volume relative to Jakarta's mature ride-hailing density.
West Java
Bandung's established manufacturing base supports component supplier parks serving LCGC certification requirements. The region's technical universities feed engineering talent into hybrid powertrain calibration programs. Domestic content verification protocols accelerate captive sourcing relationships near existing assembly infrastructure.
Central Java
Semarang's port facilities handle inter-island distribution to eastern Indonesia markets. Higher logistics costs from Java-based plants inflate delivered vehicle prices versus regional competitors. Biofuel blending mandates from the energy ministry constrain gasoline engine calibration flexibility for vehicles shipped through this corridor.
Sumatra
Medan anchors passenger car demand in Indonesia's westernmost major island. Infrastructure gaps and shipping dependencies from Java create pricing premiums that slow adoption relative to the main island. Charging infrastructure scarcity constrains battery electric vehicle deployment despite pending tax incentive adjustments.
Indonesia Passenger Car Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Indonesia's LCGC-regulated passenger car market. Toyota Motor Manufacturing Indonesia leverages extensive local supplier networks to sustain cost advantages, while Honda Manufacturing Indonesia differentiates through hybrid technology positioning. Hyundai Motor Manufacturing Indonesia competes aggressively on electric vehicle readiness. Strategic moves center on supplier park deepening and dedicated EV platform localization to capture pending incentive adjustments.
Among Japanese-anchored manufacturers, Toyota Motor Manufacturing Indonesia, Honda Manufacturing Indonesia, and Mitsubishi Motors Krama Yudha Indonesia occupy positions reflecting long-established LCGC program participation. These entities exemplify the incumbent archetype defending market presence through captive sourcing relationships and entrenched distribution infrastructure. Chinese-affiliated entrants including Wuling Motors Indonesia and SGMW Motor Indonesia represent the challenger archetype, competing on price positioning and EV platform localization speed.
| Leading Market Players |
|---|
| Suzuki Indomobil Motor |
| Honda Manufacturing Indonesia |
| Toyota Motor Manufacturing Indonesia |
| Wuling Motors Indonesia |
| SGMW Motor Indonesia |
| Mitsubishi Motors Krama Yudha Indonesia |
| Hyundai Motor Manufacturing Indonesia |
| Sokonindo Automobile |
| Astra Daihatsu Motor |
| Others |
Pricing and Supply Chain Analysis
Hybrid powertrain calibration specialists concentrated in West Java's technical corridor command wage premiums that widen pricing-tier spreads between LCGC-certified economy vehicles and hybrid-equipped fleet configurations. Labor-cost differentials between captive engineering programs and third-party supplier development directly feed into manufacturer tiering strategies across Jakarta's ride-hailing procurement channels.
Pricing Analysis
Margin tightening in entry-level LCGC trims reflects compressed domestic content qualification timelines as manufacturers absorb extended supplier certification costs. Three-tier pricing structure across premium hybrid, standard petrol, and economy LCGC levels separates buyers by fuel efficiency certification grade and after-sales service bundling. Pricing pressure intensifies in the standard petrol tier as biofuel blending mandates from Indonesia's energy ministry constrain engine calibration flexibility. Fleet operators in Greater Jakarta exhibit highest price sensitivity due to volume procurement and depreciation schedules, while private buyers in Surabaya prioritize efficiency certification over upfront cost.
Supply Chain Analysis
Indonesia's LCGC domestic content mandates are reshaping sourcing patterns toward captive supplier parks in Bekasi and Karawang. Component supply concentrates in Japan, Thailand, and China for hybrid powertrain electronics, turbocharged engine subsystems, and CVT transmission assemblies. Raw material dependencies span lithium carbonate for battery cells, high-grade steel for lightweight chassis structures, and semiconductor chips for powertrain control modules. Single-source vulnerability in hybrid system controllers creates supply chain risk given BIS-equivalent validation timelines. Distribution runs through Java-based assembly clusters to inter-island shipping networks serving outer island markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's passenger car market sits in a technology-transition phase as hybrid-electric powertrains displace conventional petrol engines across LCGC-compliant fleet procurement. This shift restructures competitive positioning around electrification readiness rather than displacement-based cost optimization.
For Market Incumbents: Deepen captive sourcing relationships within Bekasi-Karawang supplier parks to defend LCGC program eligibility against emerging EV-platform entrants. Accelerate hybrid powertrain localization to offset margin pressure from biofuel calibration complexity and extended BIS-equivalent certification timelines. For New Entrants and Emerging Players: Battery-electric platform localization offers the most penetrable wedge into Indonesia's pending EV incentive adjustments, particularly for dedicated fleet operators in Surabaya's underpenetrated ride-hailing corridors. Target digital-native procurement interfaces and subscription-based ownership models to bypass entrenched dealer networks in Greater Jakarta. For Investors and Strategic Acquirers: Re-rating potential sits with hybrid powertrain engineering specialists given Indonesia's Ministry of Industry tax incentive trajectory and fleet operator fuel cost sensitivity. Acquisition targets should demonstrate auditable domestic value-add documentation and established BIS-equivalent certification pathways. Watch for EV import duty exemption finalization as the inflection signal for platform localization viability.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Powertrain Localization | Captures LCGC tax incentives while meeting fleet operator fuel efficiency requirements in Jakarta. |
| Supplier Park Deepening | Accelerates domestic content verification for LCGC eligibility near existing Bekasi assembly infrastructure. |
| Digital Retail Channel Integration | Bypasses traditional dealer networks for tech-savvy middle-class buyers seeking subscription ownership models. |
| EV Platform Dedicated Localization | Positions for pending Ministry of Industry import duty exemptions and tax holiday adjustments. |
| Surabaya Fleet Hub Development | Captures underpenetrated East Java volume relative to saturated Greater Jakarta ride-hailing density. |
Research Methodology
Multi-period observation of vehicle registration flows, LCGC certification approvals, and fleet procurement patterns anchored the trend analysis, supplemented by interviews with OEM platform engineers, Tier 1 supplier procurement leads, ride-hailing fleet operators, and Ministry of Industry regulatory officials. Secondary validation drew from IHS Markit vehicle production databases, Indonesia's automotive industry association statistics, energy ministry biofuel blending directives, and customs import records for hybrid powertrain components. Bottom-up segment sizing triangulated against top-down macroeconomic consumption models.
Input-output matrices mapped powertrain technology adoption, vehicle class preferences, and regional demand density across the projection horizon. Segmentation dimensions modeled included vehicle architecture, propulsion system, transmission type, and fuel efficiency tier alongside OEM supply chain localization depth. CAGRs derived from regression analysis of historical penetration curves adjusted for regulatory incentive phase-ins. Forecast inputs incorporated LCGC domestic content threshold evolution and charging infrastructure deployment timelines for battery-electric vehicles.
Several conditions sit outside the modeled scope, including abrupt regulatory reversals on EV incentives, geopolitical disruptions to semiconductor supply chains, and currency volatility effects on imported component costs. Forecasts reflect documented assumptions regarding policy continuity and supplier certification timeline stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passenger Vehicles
Wheelchair Accessible Vehicle Market
Passenger Vehicles
India Passenger Car Market
Passenger Vehicles
India Automotive Market
Passenger Vehicles
Electric Passenger Car MRO Market
Passenger Vehicles
North American Lightweight Car Market
Passenger Vehicles
Luxury Car Market
Passenger Vehicles
China Luxury Car Market
Passenger Vehicles
Luxury Vehicles Market
Passenger Vehicles
Europe Luxury Car Market
Passenger Vehicles
Electric Sports Car Market
Passenger Vehicles
South America Passenger Cars Market
Passenger Vehicles
North America Automotive Market
Passenger Vehicles
Automotive Luxury Vehicle Market
Passenger Vehicles
North America MUV Rental Market
Passenger Vehicles
Lightweight Cars Market
Passenger Vehicles
Passenger Vehicle Market