
 Tannin Market | 2026-2036
Tannin Market Size, Share, and Industry Trends Forecast 2026-2036
Tannin Market Intelligence
Synthetic phenolic alternatives is repositioning cost structures across leather finishing and wood adhesive segments. Silvateam S.p.A. leverages backward integration into chestnut and quebracho forestry to secure raw material continuity. Tanac S.A. anchors South American supply through controlled extraction from mimosa bark. Laffort specializes in enological tannin formulations for premium wine producers across Bordeaux and Napa Valley.
Tannins comprise water-soluble polyphenolic compounds with molecular weights ranging from 500 to 3,000 daltons, derived from plant bark, wood, and fruit skins through aqueous or solvent extraction. These compounds precipitate proteins, bind metal ions, and scavenge free radicals, serving as essential inputs in leather tanning, wine stabilization, and natural preservative systems. Condensed tannins dominate volume throughput due to their superior reactivity in chrome-free leather processing. Hydrolyzable tannins command premium pricing in pharmaceutical and nutraceutical applications where gallic acid content determines bioactive potency. Synthetic tannins occupy standard-grade leather segments where cost minimization overrides natural-origin specifications.
REACH in Europe and FDA GRAS determinations in the United States govern food-contact and pharmaceutical-grade tannin certifications, with EFSA evaluating novel extract safety profiles for dietary supplement inclusion. China's SAMR enforces GB standards on imported tannin additives for domestic food manufacturing. Stakeholders must monitor regulatory divergence between natural-extract purity thresholds and synthetic-tolerance limits as classification decisions reshape formulation choices across end-use categories.
Market Dynamics
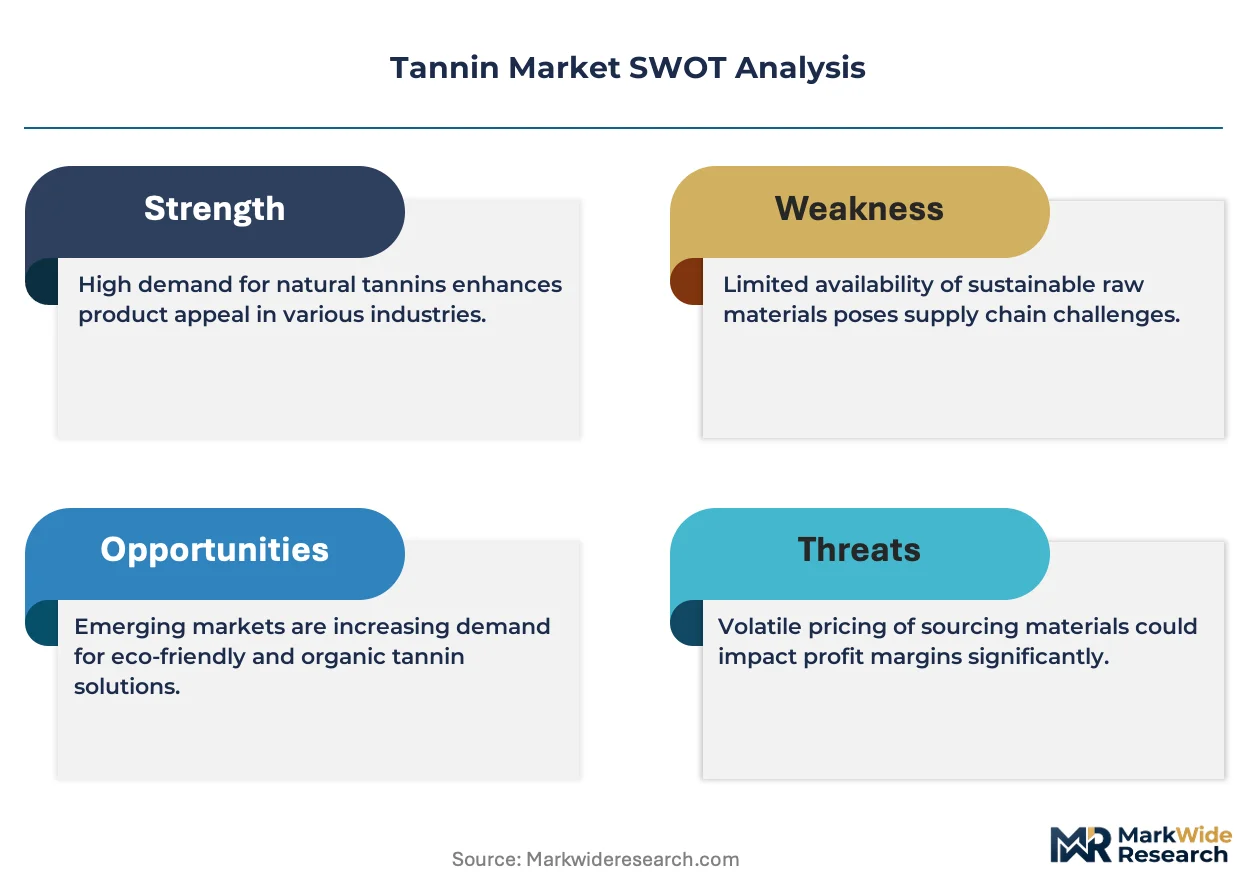
REACH regulation in Europe is compressing formulation flexibility for food-grade tannin suppliers while simultaneously opening premium pricing tiers for compliant natural extracts. This regulatory pivot is forcing simultaneous investment in purification infrastructure and backward forestry integration across the value chain.
Growth Catalysts
- Chrome-free leather mandates:REACH and similar frameworks in multiple jurisdictions are accelerating substitution of chromium salts with condensed tannins in tanning operations.
- Enological mouthfeel demand:Bordeaux and Napa Valley winemakers are expanding tannin procurement for color stabilization and textural complexity in premium bottlings.
- Quebracho forestry control:Backward integration into South American bark supply is securing raw material continuity for hydrolyzable tannin producers.
Market Restraints
- Mimosa bark concentration:Brazilian and Argentine supply clusters create geographic vulnerability for condensed tannin feedstock.
- Synthetic phenolic substitution:Cost-driven leather finishers in standard-grade segments are displacing natural tannins with petroleum-derived alternatives.
- Extraction energy intensity:Aqueous and solvent processing requires sustained thermal input, compressing margins during energy price volatility.
Strategic Opportunities
- Pharmaceutical-grade gallic acid:Hydrolyzable tannin derivatives with verified bioactive potency are penetrating nutraceutical formulations.
- SAMR compliance arbitrage:GB standards enforcement in China is creating first-mover advantage for certified exporters to domestic food manufacturing.
- Supercritical CO2 extraction:This converging technology with precision fractionation is enabling solvent-free pharmaceutical-grade output.
Industry Challenges
- Analytical chemist scarcity:Polyphenolic characterization and EFSA novel food dossier preparation require specialized expertise in short supply.
- Multi-jurisdiction certification lag:Sequential FDA GRAS, EFSA safety evaluation, and SAMR registration timelines extend commercialization by 18-36 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tannin Market |
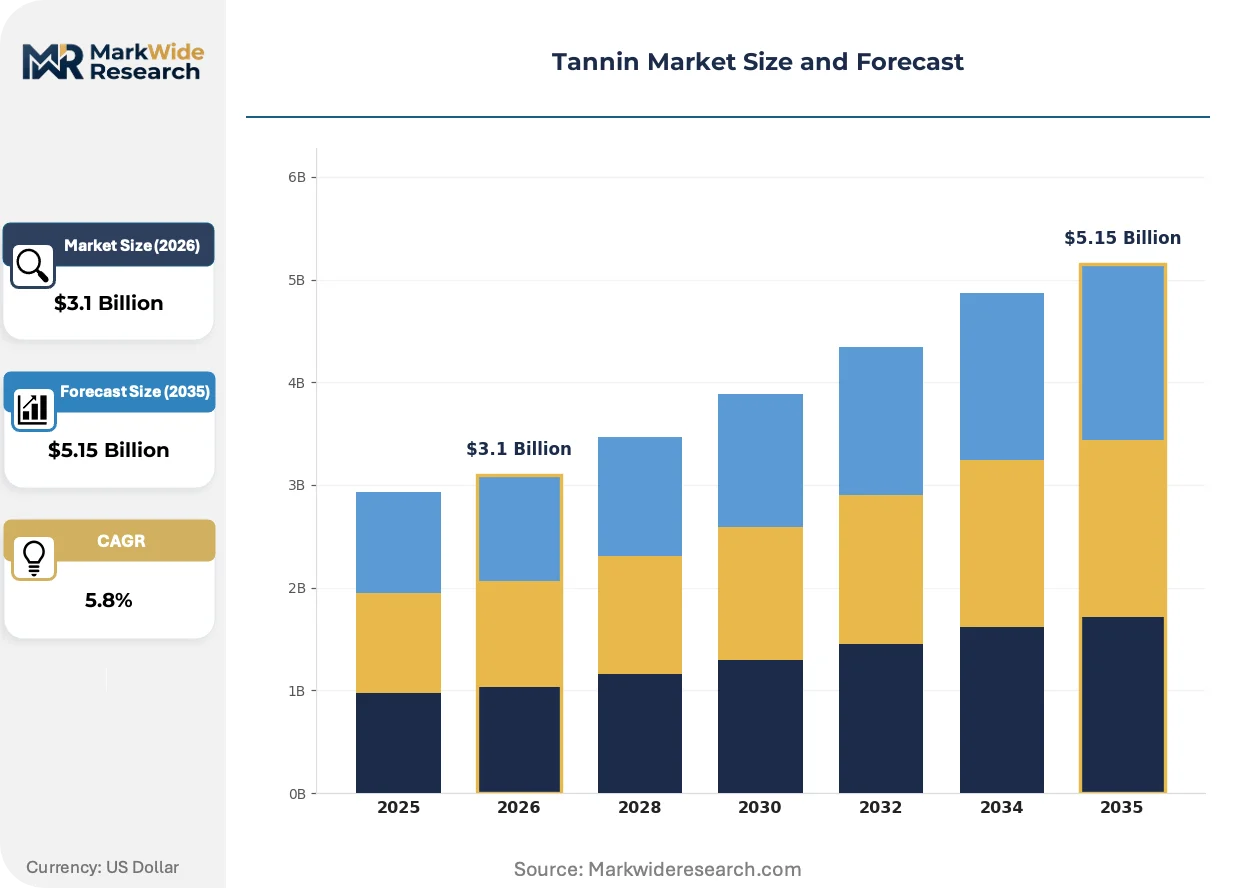
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.15 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrolyzable Tannins, Condensed Tannins, Synthetic Tannins, Others End User: Food & Beverage, Pharmaceuticals, Cosmetics, Leather Industry Application: Food Preservation, Dyeing, Tanning, Additives Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | Silvateam S.p.A., Tanin Sevnica Ltd., Laffort, Tanac S.A., Polson Ltd., UCL Company (Pty) Ltd., Tannin Corporation, S.A. Ajinomoto OmniChem N.V., Ever s.r.l., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tannin Market Strategic Shifts & Innovations
Extraction technology and regulatory classification systems are simultaneously evolving, creating divergence between premium natural-origin positioning and cost-optimized synthetic alternatives. Suppliers must now engineer for dual certification pathways.
Membrane filtration systems for tannin fractionation by molecular weight are modularizing production economics for mid-scale processors. Italian and French enological specialists are adopting these units to customize galloyl content for specific wine styles. This modularizing capability is compressing minimum efficient scale and enabling regional craft suppliers to compete with integrated forestry operations.
EFSA's expanded novel food evaluation framework is extending safety dossier requirements for dietary supplement applications. Hydrolyzable tannin extracts with uncharacterized gallic acid ester profiles face prolonged assessment timelines. Pharmaceutical-grade suppliers in Switzerland and Germany are responding by investing in full constituent mapping ahead of submission.
Direct contracting between Bordeaux châteaux and chestnut forestry cooperatives is displacing spot-market tannin procurement. This relationship model transfers quality verification upstream and locks volume commitments through harvest cycles. The shift is most visible in France's Dordogne basin, where controlled-origin designations now command 15-20% premia over commodity grades.
Tannin Market Segmentation
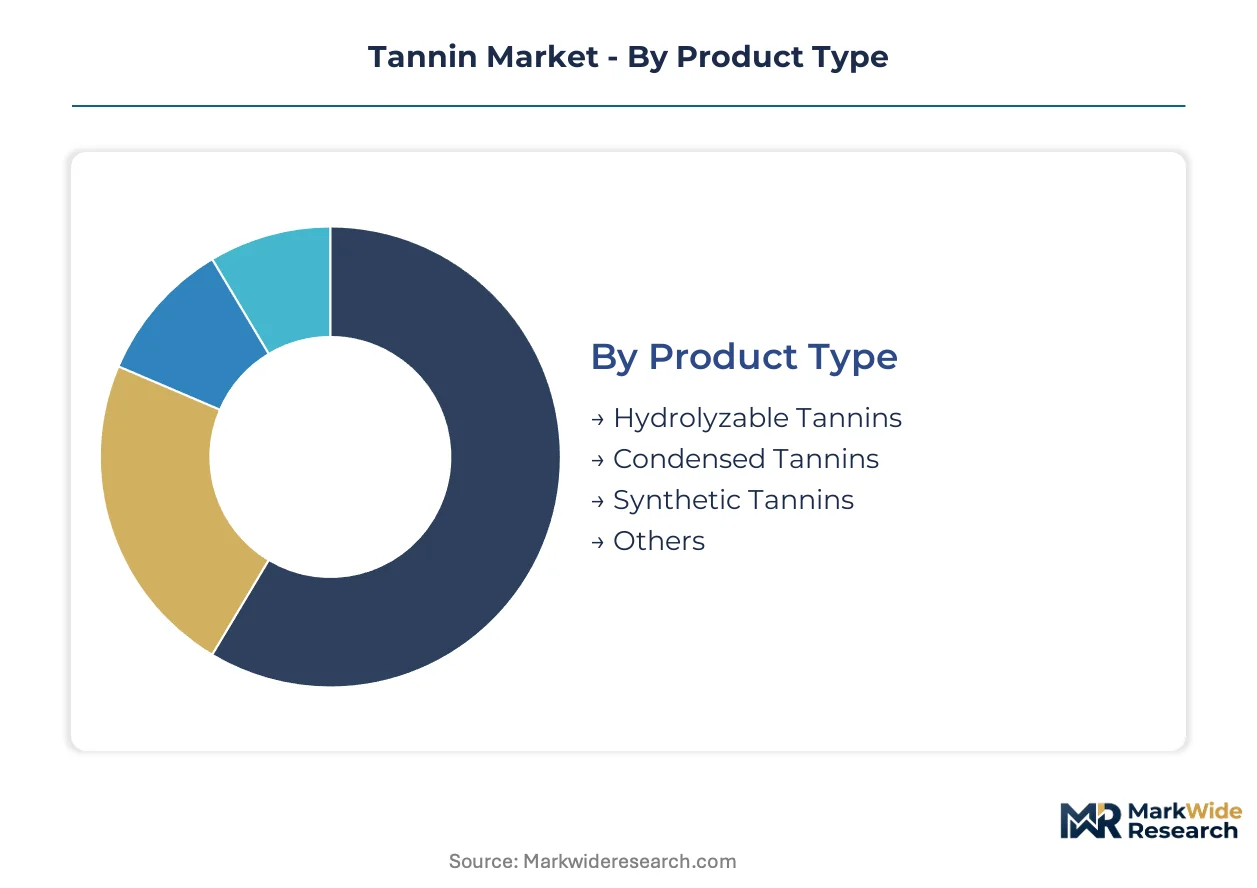
Tannin procurement patterns diverge sharply across end-use specifications, with wine stabilization demanding enological purity while leather processing tolerates broader compositional variance. Pharmaceutical and nutraceutical buyers impose the strictest molecular characterization requirements, creating tiered certification barriers that reshape supplier economics.
Product Type:
Cost tier differentiates buyers most acutely, with natural-origin premiums widening against petroleum-derived substitutes.
- Hydrolyzable Tannins:These polyphenolic compounds feature ester-linked gallic acid units that hydrolyze under acidic or enzymatic conditions. Demand concentrates in Swiss and German pharmaceutical corridors where verified bioactive potency commands certification premia. EFSA novel food dossier requirements compress formulation flexibility for dietary supplement entrants.
- Condensed Tannins:Flavan-3-ol polymers with superior protein-binding affinity dominate chrome-free leather substitution mandates. Italian and Spanish tannery clusters in Tuscany and Igualada sustain concentrated offtake as REACH chromium restrictions harden. Quebracho and mimosa bark supply concentration in South America creates geographic vulnerability.
- Synthetic Tannins:Petroleum-derived phenolic condensates serve standard-grade leather segments where cost minimization overrides natural-origin specifications.
- Others:Phlorotannins from brown algae and specialized bark extracts occupy niche nutraceutical and cosmetic preservative applications.
Volume sits with Condensed Tannins; growth tilts toward Hydrolyzable Tannins.
End User:
Application maturity separates segments, with leather tanning representing century-old demand against pharmaceutical expansion.
- Food & Beverage:Enological mouthfeel enhancement and natural preservative systems drive Bordeaux and Napa Valley procurement. FDA GRAS determinations and EFSA safety evaluations govern additive inclusion thresholds.
- Pharmaceuticals:Gallic acid derivatives with verified antioxidant and antimicrobial properties penetrate nutraceutical formulations. Full constituent mapping requirements extend commercialization timelines.
- Cosmetics:Skin-conditioning and UV-protective applications leverage tannin-metal chelation properties in French and Korean formulation houses.
- Leather Industry:Vegetable tanning operations in Italy, Spain, and Argentina sustain bulk demand as chrome substitution accelerates under REACH and similar frameworks.
Leather Industry anchors current volume; Pharmaceuticals exhibits the steepest expansion trajectory.
Application:
Customer type dictates specification stringency, with food-contact applications facing the tightest purity benchmarks.
- Food Preservation:Natural antioxidant systems in meat, fish, and oil-based products require SAMR GB compliance in China and FDA GRAS status in the United States. Extraction solvent residues face tightening analytical thresholds.
- Tanning:Protein cross-linking for leather durability dominates volume throughput. Condensed tannin reactivity profiles determine processing efficiency in chrome-free operations.
- Additives:Enological formulations for color stabilization and astringency modulation serve premium wine producers.
- Dyeing:Natural colorant applications in textile and ink manufacturing leverage tannin-metal complexation chemistry.
Tanning commands installed capacity; Food Preservation gains share fastest on clean-label substitution.
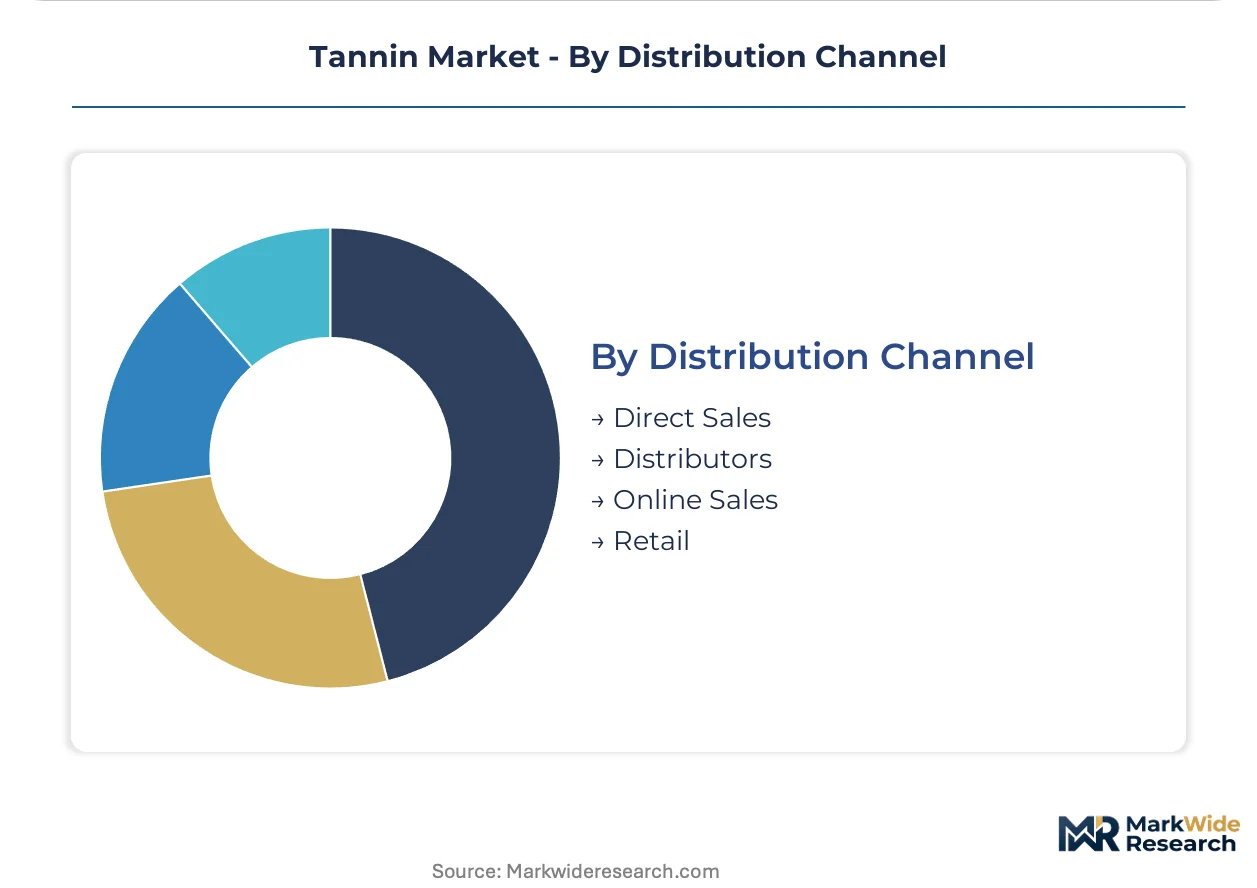
Distribution Channel:
Supply concentration shapes channel selection, with backward-integrated producers favoring direct contracting.
- Direct Sales:Bordeaux châteaux and chestnut forestry cooperatives in France's Dordogne basin lock volume commitments through harvest cycles. Controlled-origin designations command 15-20% premia over commodity grades.
- Distributors:Regional chemical and specialty ingredient wholesalers serve mid-scale leather processors and food manufacturers lacking technical specification expertise.
- Online Sales:E-commerce platforms penetrate small-batch cosmetic formulators and craft beverage producers seeking sample quantities.
- Retail:Consumer-facing channels supply home winemaking and artisanal leatherworking segments.
Distributors handle fragmented demand; Direct Sales deepens among premium enological and pharmaceutical buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France, Italy, and Spain concentrate enological tannin procurement through vineyard clusters and leather tannery networks. REACH compliance costs and chrome-free mandates are redrawing procurement geography across manufacturing basins.
France
Bordeaux châteaux and Burgundy négociants drive premium enological tannin offtake for color stabilization and mouthfeel layering. EFSA novel food evaluations govern dietary supplement-grade hydrolyzable tannin approvals. The Dordogne basin anchors chestnut forestry cooperatives supplying controlled-origin extracts with 15-20% price premia over commodity grades.
Italy
Tuscan vegetable tanneries in Santa Croce sull'Arno sustain condensed tannin volume for luxury leather goods. REACH chromium restrictions accelerate substitution toward quebracho-derived formulations. Piedmont enological specialists source galloyl-calibrated extracts for Barolo and Barbaresco aging protocols.
Spain
Igualada tannery clusters outside Barcelona process condensed tannins for automotive and upholstery leather segments. ECHA enforcement of SVHC thresholds tightens purity benchmarks for export-bound finished leather. Rioja and Ribera del Duero wineries expand tannin additive procurement for structured red wine portfolios.
Argentina
Mendoza wineries and Buenos Aires province tanneries split demand between enological and leather processing applications. Mimosa bark extraction from Entre Ríos and Corrientes provinces supplies regional condensed tannin feedstock. SAMR-equivalent export certifications lag, compressing pharmaceutical-grade market access.
United States
Napa Valley and Sonoma County vintners procure enological formulations for premium Cabernet and Pinot Noir programs. FDA GRAS determinations govern food-contact tannin inclusion thresholds. California-based natural ingredient distributors service craft beverage producers seeking clean-label preservative systems.
Tannin Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with backward-integrated forestry operators commanding premium tiers and toll processors serving standard-grade leather applications. The vendor base organizes around three archetypes: captive forestry owners controlling quebracho and chestnut supply, enological formulation houses with vintage-specific calibration capabilities, and synthetic phenolic producers competing on unit economics. Consolidation pressure concentrates among mid-scale extractors lacking purification infrastructure for pharmaceutical-grade certification. M&A activity targets South American bark supply control, while technology licensing spreads supercritical CO2 extraction capabilities.
Within the forestry-integrated tier, Silvateam S.p.A. and Tanac S.A. exemplify upstream control strategies through direct management of extraction feedstock. Laffort occupies a specialist position in enological formulation, representing the calibration-intensive segment serving premium wine producers. These three anchors illustrate how competitive positioning diverges between raw material security and application-specific technical service.
| Leading Market Players |
|---|
| Silvateam S.p.A. |
| Tanin Sevnica Ltd. |
| Laffort |
| Tanac S.A. |
| Polson Ltd. |
| UCL Company (Pty) Ltd. |
| Tannin Corporation |
| S.A. Ajinomoto OmniChem N.V. |
| Ever s.r.l. |
| Others |
Cost & Logistics Intelligence
Quebracho bark harvest costs cascade through three distinct pricing tiers, with South American forestry control separating pharmaceutical-grade hydrolyzable extracts from commodity condensed tannins destined for standard leather finishing. Energy-intensive aqueous extraction compresses margins at every node, forcing processors to choose between purification infrastructure investment and synthetic phenolic substitution.
Pricing Analysis
Volume throughput concentrates in condensed tannins for chrome-free leather processing, while margin capture tilts toward hydrolyzable grades with verified gallic acid potency for Swiss and German pharmaceutical corridors. Price differentiation rests on certification grade—EFSA novel food dossier completion commands 15-20% premia over commodity enological grades—and backward integration into chestnut or mimosa forestry. Pricing pressure stems from synthetic phenolic substitution in standard-grade leather segments, where cost minimization overrides natural-origin specifications. Small-batch cosmetic formulators and craft beverage producers exhibit highest price sensitivity, whereas Bordeaux châteaux and pharmaceutical buyers prioritize purity verification over unit economics.
Supply Chain Analysis
Dual-sourcing requirements from REACH-compliant tanneries and EFSA-regulated food manufacturers mandate multi-supplier qualification across Argentine, Brazilian, and Paraguayan quebracho bark clusters. Raw material dependencies center on mimosa bark from Entre Ríos province, chestnut wood from France's Dordogne basin, and gall nut extracts from Chinese and Turkish supply zones. Geographic concentration risk manifests in single-source vulnerability for condensed tannin feedstock, compounded by extraction energy intensity that amplifies margin exposure during thermal input price volatility. Distribution runs through direct contracting for premium enological and pharmaceutical grades, with regional chemical distributors serving fragmented mid-scale leather processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market has become a vertical-integration race, with upstream forestry control and downstream certification infrastructure representing the decisive levers separating premium-tier suppliers from toll processors.
For Market Incumbents: Cement raw material security through long-term offtake agreements with South American bark cooperatives, insulating against synthetic phenolic displacement in standard leather grades. Accelerate supercritical CO2 extraction capacity to capture pharmaceutical-grade gallic acid demand before Swiss and German competitors consolidate nutraceutical formulation partnerships. Defensive positioning requires simultaneous EFSA dossier preparation and SAMR GB compliance investment to maintain multi-jurisdiction market access.
For New Entrants and Emerging Players: Membrane filtration technology for molecular-weight-specific tannin fractionation offers entry into mid-scale enological customization previously reserved for integrated forestry operators. Target the clean-label food preservation segment in China, where SAMR enforcement lags create first-mover certification arbitrage for compliant exporters. A technology-licensing go-to-market model spreads capital requirements while establishing process credibility with regional craft wine producers.
For Investors and Strategic Acquirers: EFSA novel food approval timelines extending beyond 24 months is the leading indicator that analytical chemistry capabilities and regulatory affairs infrastructure will determine acquisition premiums. Five-to-ten-year viability favors processors with captive forestry supply and dual-certification pathways across food-contact and pharmaceutical grades. The signal to monitor is consolidation among mid-scale extractors lacking purification infrastructure, which will accelerate as REACH purity benchmarks tighten and multi-jurisdiction registration costs rise.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Forestry | Chestnut and quebracho supply control secures raw material continuity against geographic concentration risk. |
| Supercritical CO2 Extraction Deployment | Solvent-free pharmaceutical-grade output penetrates Swiss and German nutraceutical formulation corridors. |
| EFSA Novel Food Dossier Investment | Full constituent mapping ahead of submission compresses commercialization timelines for hydrolyzable derivatives. |
| Direct Contracting with Wine Producers | Bordeaux châteaux relationships transfer quality verification upstream and lock volume through harvest cycles. |
| SAMR GB Compliance Certification | First-mover advantage in China's domestic food manufacturing opens clean-label preservative substitution demand. |
Research Approach
Multi-period observation of quebracho bark harvest volumes, EFSA novel food approval timelines, and REACH enforcement patterns anchored the trend analysis, supplemented by interviews with tanning plant managers, enological formulation specialists, pharmaceutical procurement leads, and chestnut forestry cooperative directors. Secondary validation drew from customs trade data, ECHA SVHC threshold updates, SEC filings of listed specialty chemical producers, and Italian and French tannery association production surveys. Bottom-up extraction capacity modeling and top-down end-use demand estimation were triangulated against regional consumption patterns.
Input-output matrix framing connected raw material availability across South American forestry zones to downstream pricing tiers, with segmentation dimensions spanning tannin type, end-use industry, certification grade, and regional regulatory cluster. CAGRs were derived from regression analysis of historical procurement volumes against chrome-free leather mandate implementation and enological additive adoption curves. Forecast inputs incorporated energy price volatility coefficients and multi-jurisdiction registration lag effects.
Several conditions sit outside the modeled scope, including unannounced regulatory reclassifications of synthetic phenolic alternatives and abrupt shifts in vineyard acreage from climate-related vine replacement programs. Forecasts reflect documented assumptions regarding EFSA evaluation throughput rates and SAMR enforcement consistency. Deviation in quebracho bark supply from Argentine export restrictions or Corrientes province harvest disruptions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Borage Oil Market
Ingredients
Olive Oil Market
Ingredients
Global Arabinoxylan Fiber Market
Ingredients
Specialty Malt Market
Ingredients
United States Soy Protein Market
Ingredients
Soybean Meal Market
Ingredients
Immunity Support Ingredients Market
Ingredients
Global Pine Pollen Powder Market
Ingredients
Acetylated Starch Market
Ingredients
GCC Bakery Ingredients Market
Ingredients
Phytogenic Market
Ingredients
Bulk Food Ingredients Market
Ingredients
Vegan Baking Ingredients Market
Ingredients
Mineral Premix Market
Ingredients
Vegetable Fats Market
Ingredients
Algae-Based Ingredients Market