
 Global Malt Market | 2026-2036
Global Malt Market Size, Share, and Industry Trends Forecast 2026-2036
Global Malt Market Foresight
Precision malting technology is rewriting how barley transforms into consistent, specification-grade malt. Boortmalt leverages automated kiln controls across its European production network to reduce batch variability. Simpsons Malt anchors its competitiveness on heritage floor-malting expertise combined with modern moisture-management systems. Cargill extends its origination reach by integrating barley procurement directly with malting operations across multiple continents.
Malt is germinated cereal grain—typically barley—dried in controlled kilning to develop enzymatic activity, color, and flavor precursors for fermentation processes. The kilning temperature profile determines diastatic power, moisture content (typically 4-6% finished), and Lovibond color specifications that brewers match to recipe requirements. Pale Malt dominates volume as the base for most beer styles, while Crystal Malt commands margin premiums through specialized caramelization during roasting. Application demand concentrates in Brewing, where craft segment expansion outpaces mainstream lager stagnation, and Distilling, where single-malt whisky growth drives premium specialty malt procurement.
FDA food-safety standards govern malt imports into the United States, while REACH and EFSA frameworks in Europe regulate acrylamide limits and pesticide residue thresholds in food-grade production. These multi-jurisdictional compliance layers raise capital requirements for new market entrants and favor established operators with dedicated quality laboratories. Stakeholders must monitor how carbon-accounting rules under the EU Green Deal reshape energy-intensive kilning economics and sourcing decisions across supplier networks.
Market Dynamics
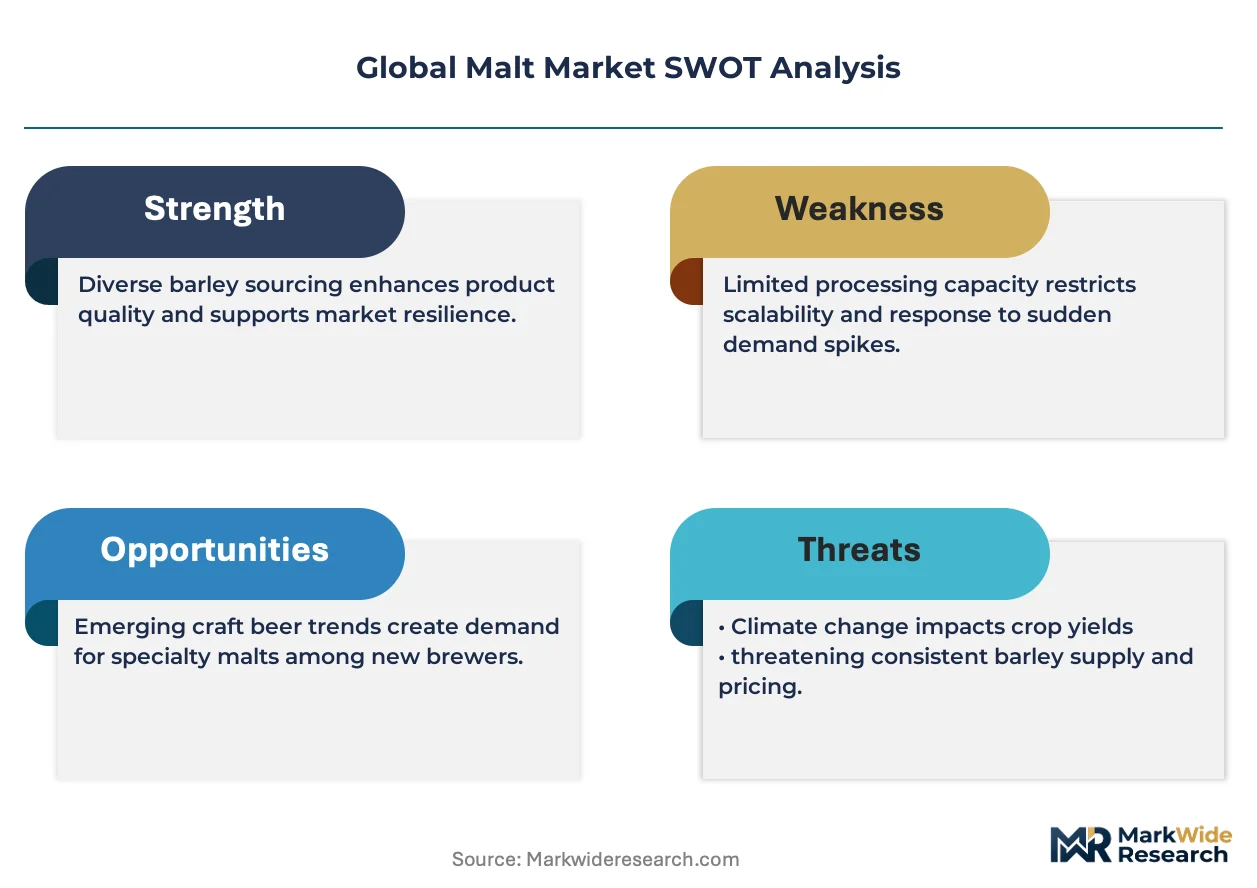
Precision malting technology is collapsing traditional batch-to-batch variation windows, forcing capital retooling across kiln operations while EFSA acrylamide limits tighten specification tolerances for food-grade output.
Growth Catalysts
- Craft brewing expansion:Microbreweries in Germany, Belgium, and the United States pull specialty malt volumes through specification-grade procurement contracts tied to heritage recipe requirements.
- REACH purity benchmarks:ECHA-mandated pesticide residue thresholds for food-grade malt create compliant-supplier premiums that reward quality-laboratory investments.
- Automated kiln control systems:Sensor-driven moisture management and temperature profiling reduce energy intensity per tonne while tightening Lovibond color consistency.
Market Restraints
- Barley input volatility:Weather-driven origination risk in Australia and Canada transmits directly to maltster margin compression during drought cycles.
- Supply concentration in Rhineland-Palatinate:German malting infrastructure clusters along Rhine logistics corridors, creating single-point disruption exposure.
- Acrylamide formation chemistry:Maillard reaction kinetics during high-temperature kilning impose hard technical limits on color development without exceeding EFSA thresholds.
Strategic Opportunities
- India brewing liberalization:State-level licensing reforms in Karnataka and Maharashtra open import channels for specialty caramel and roasted malts.
- EU Green Deal carbon accounting:Renewable thermal energy certificates for kilning operations create first-mover margin structures in low-carbon malt positioning.
- Direct-to-distillery contracting:Single-malt whisky producers in Scotland and Japan bypass merchant maltsters for bespoke peat-smoked and heritage varietal programs.
Industry Challenges
- Malting technologist scarcity:Germination biochemistry and kiln engineering expertise concentrates among retiring European specialists without structured apprenticeship pipelines.
- Multi-jurisdictional certification timelines:Parallel FDA, EFSA, and BIS food-safety approvals extend product launch cycles by 18-24 months for new specialty grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Malt Market |
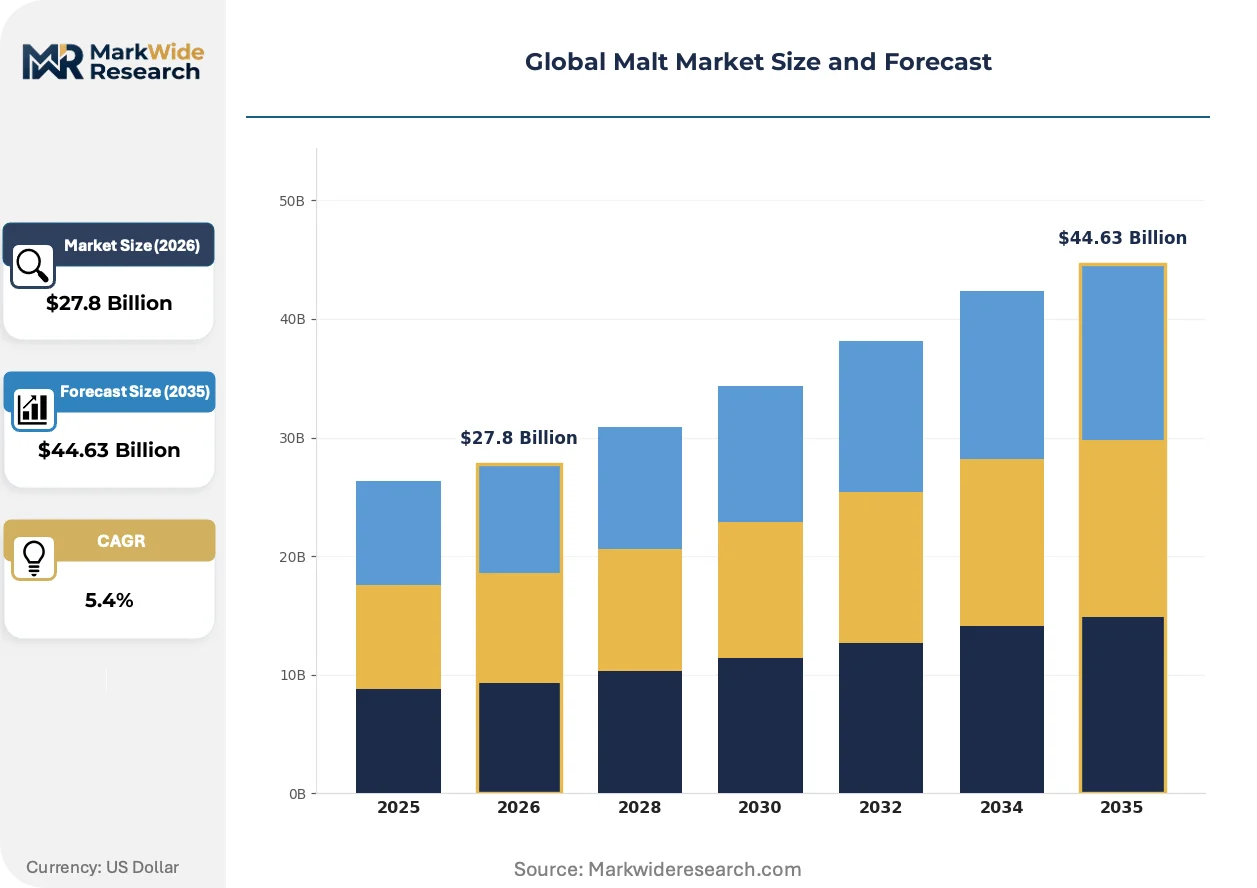
| Market Size in 2026 | $27.8 Billion |
| Market Size in 2035 | $44.63 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pale Malt, Crystal Malt, Chocolate Malt, Black Malt, Vienna Malt, Munich Malt Form: Whole Grain, Roasted, Flaked, Ground, Extract, Pellets Application: Brewing, Distilling, Food Additive, Animal Feed, Pharmaceuticals, Packaged Beverages End User: Microbreweries, Commercial Breweries, Distilleries, Food Manufacturers, Feed Producers, Pharma Companies |
| Companies Covered | Malteurop Groupe, Boortmalt, Simpsons Malt, Viking Malt, Muntons, Cargill, Axéréal, Crisp Malt, VIVESCIA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Malt Market Shifts & Advancements
Digital moisture sensing and AI-driven kiln profiles are compressing specification drift while regulatory carbon-accounting frameworks reshape energy sourcing decisions across malting networks.
Hyperspectral imaging is collapsing traditional laboratory analysis timelines for protein and moisture verification. Commercial breweries in Denmark and the Netherlands deploy inline spectroscopy for real-time batch acceptance, eliminating third-party assay delays and compressing supplier qualification cycles from months to days.
EU Green Deal carbon-border adjustment mechanisms are redirecting thermal energy procurement toward biogas and electrified kiln retrofits. German malting groups face margin pressure from embedded emissions accounting, while operators in Poland and the Czech Republic exploit grid-decarbonization timelines to position low-carbon malt for premium brewing contracts.
Distillers are consolidating procurement through long-term varietal contracts that bypass spot-market maltsters. Scotch whisky producers in Speyside and Islay lock multi-year supply for heritage barley strains, compressing merchant maltster volumes while rewarding backward-integrated distillery malting floors with traceability premiums.
Global Malt Market Segmentation
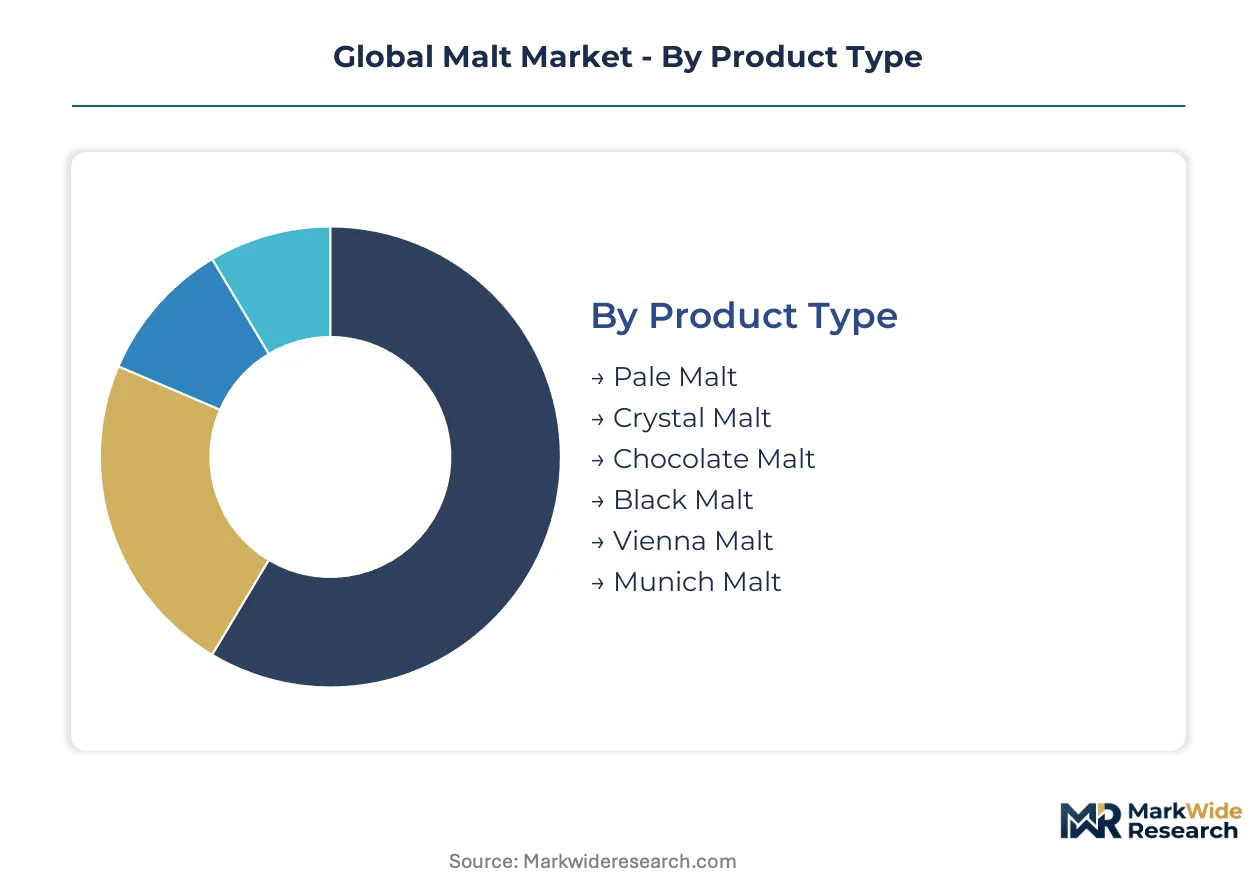
Malt segmentation reveals divergent margin structures across specification grades. Cycle times vary dramatically: base malts turn weekly through high-volume breweries, while specialty roasted variants sit in extended curing protocols for craft distillers.
Product Type:
Inventory velocity separates commodity base malts from extended-kiln specialty grades. Pale Malt rotates through supply chains in days; Black Malt and chocolate variants demand month-long curing cycles that tie up working capital.
- Pale Malt:Standard two-row barley germinated at controlled moisture levels produces the enzymatic backbone for lager and ale fermentation. German commercial breweries in Bavaria and North Rhine-Westphalia anchor procurement volumes through annual contracting that locks varietal specifications and diastatic power ranges.
- Crystal Malt:Stewed germination followed by rapid kiln roasting develops crystallized sugar structures that add caramel sweetness and amber coloration. Scottish distilleries in Speyside and Islay concentrate demand for premium grades that command specification premiums tied to Lovibond color precision.
- Chocolate Malt:High-temperature roasting of fully modified pale malt generates dark color and bitter cocoa notes for porters and stouts.
- Black Malt:Extended roasting near combustion thresholds produces de-bittered black colorant for stout recipes without astringency.
- Vienna Malt:Moderate kilning temperatures yield amber hues and subtle malt sweetness for Oktoberfest-style lagers.
- Munich Malt:Higher moisture retention during kilning develops melanoidin richness for bock and dunkel beer styles.
Pale Malt dominates installed base. Crystal Malt is where expansion concentrates.
Form:
Processing depth determines logistics economics and customer handling requirements. Whole grain shipments minimize transport costs but demand customer-side milling investment; extracts and pellets collapse handling complexity at premium pricing.
- Whole Grain:Intact malted barley kernels requiring customer-side milling and mashing equipment. German commercial breweries in Munich and Dortmund concentrate procurement through direct silo deliveries that minimize handling stages.
- Extract:Concentrated wort syrups and powders that bypass mashing entirely for beverage and food manufacturing. Japanese distilleries and ready-to-drink beverage formulators in Osaka and Tokyo drive demand for specification-grade extracts that compress production timelines.
- Roasted:Kiln-finished malt in kernel form for breweries with in-house milling capacity.
- Flaked:Pre-gelatinized rolled malt for direct addition to mash tuns without milling.
- Ground:Pre-milled grist for small-scale brewers lacking roller mill infrastructure.
- Pellets:Densified malt products for automated handling systems in large-scale brewing.
Whole Grain commands the largest volume footprint. Extract formats are climbing the fastest as beverage manufacturers seek processing simplification.
Application:
End-use specifications fragment procurement requirements across enzymatic, flavor, and nutritional functions. Brewing demands diastatic power consistency; distilling prioritizes fermentable extract yield; food applications impose microbiological purity standards.
- Brewing:Enzymatic conversion of starches to fermentable sugars for beer production. Craft microbreweries in Belgium, the United States, and Australia drive specialty malt diversification through recipe experimentation that pulls non-standard color and flavor variants.
- Distilling:High-extract malts for whisky, vodka, and spirit production. Scottish single-malt producers in the Highlands and Islay concentrate demand for heritage varietal programs that bypass commodity maltsters through direct farmer contracting.
- Food Additive:Malt extracts and powders for bakery, confectionery, and cereal applications.
- Animal Feed:Spent grain and lower-grade malt products for livestock nutrition.
- Pharmaceuticals:Pharmaceutical-grade malt extracts for tablet binding and nutritional supplements.
- Packaged Beverages:Malt-based ready-to-drink products and non-alcoholic malt beverages.
Brewing anchors volume demand. Distilling represents the steepest expansion trajectory as premium spirits consumption climbs.
End User:
Customer scale determines contract structures and technical service intensity. Microbreweries demand small-batch flexibility and recipe consultation; commercial breweries prioritize supply security and price stability through multi-year agreements.
- Microbreweries:Small-scale brewers typically below 15,000 hectoliters annual capacity. Independent craft operators in Portland, Oregon and Melbourne, Australia concentrate demand for experimental specialty malts that differentiate limited-release portfolios.
- Commercial Breweries:Large-scale producers with automated brewhouses and specification-driven procurement. Multinational brewing groups in Leuven, Belgium and São Paulo, Brazil anchor base malt volumes through origination contracts that span multiple growing seasons.
- Distilleries:Whisky, vodka, and spirit producers with specialized extract requirements.
- Food Manufacturers:Bakery, confectionery, and cereal companies using malt extracts and powders.
- Feed Producers:Livestock nutrition companies utilizing spent grain and by-product streams.
- Pharma Companies:Pharmaceutical manufacturers requiring compendial-grade malt ingredients.
Commercial Breweries dominate installed capacity. Microbreweries are gaining share fastest as craft segment penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German malting groups export specialty-grade output to craft breweries across Belgium, the United Kingdom, and Scandinavia through Rhine logistics corridors that minimize transit damage to enzymatic specifications.
Germany
Commercial breweries in Bavaria and North Rhine-Westphalia anchor base malt procurement through multi-season varietal contracts. EFSA acrylamide limits tighten kiln temperature tolerances for food-grade production. Malting infrastructure clusters along the Rhine corridor between Mainz and Mannheim, where automated kiln controls reduce batch-to-batch specification drift.
United States
Craft microbreweries in Portland, Oregon and Denver, Colorado drive specialty malt diversification through experimental recipe programs. FDA food-safety standards govern import certification timelines for European maltsters seeking market entry. Pacific Northwest brewing corridors concentrate demand for heritage floor-malted varieties that command specification premiums.
United Kingdom
Scottish single-malt distilleries in Speyside and Islay lock multi-year supply contracts for heritage barley strains. REACH pesticide residue thresholds create compliant-supplier premiums that reward dedicated quality laboratory investments. English craft breweries in Yorkshire and the Midlands pull caramel and roasted malt volumes through direct-to-distillery contracting models.
Belgium
Trappist and abbey breweries in West Flanders and Wallonia maintain heritage recipe requirements that specify traditional floor-malting techniques. EU Green Deal carbon-accounting frameworks redirect thermal energy procurement toward biogas retrofits. Antwerp logistics hubs serve as consolidation points for specialty malt redistribution to French and Dutch craft brewers.
India
State-level licensing reforms in Karnataka and Maharashtra open import channels for specialty caramel and roasted malts. FSSAI food-safety standards impose microbiological purity benchmarks that extend product qualification cycles. Microbreweries in Bangalore and Mumbai anchor demand growth as craft beer penetration deepens in urban consumption corridors.
Global Malt Market Competitive Landscape
On the supply side, the industry is consolidating around automated kiln technology investments while specialty-grade segments retain fragmentation among heritage floor-malting specialists. Three archetypes dominate: multinational agribusiness operators with integrated origination networks, regional specialists leveraging proximity to premium brewing clusters, and craft-focused maltsters emphasizing traditional production methods. Competitive moves concentrate on backward integration into barley procurement and capacity expansion in low-carbon kiln retrofits.
Among European heritage specialists, Boortmalt and Simpsons Malt exemplify contrasting technology strategies—automated kiln controls versus floor-malting expertise—while Cargill represents the integrated agribusiness archetype with origination reach across multiple continents. Malteurop Groupe and Viking Malt occupy positions within the continental European tier that emphasizes specification-grade consistency for industrial brewing contracts.
| Leading Market Players |
|---|
| Malteurop Groupe |
| Boortmalt |
| Simpsons Malt |
| Viking Malt |
| Muntons |
| Cargill |
| Axéréal |
| Crisp Malt |
| VIVESCIA |
| Others |
Supply & Pricing Matrix
Barley origination concentration in Australia and Canada funnels pricing power toward maltsters with multi-continent sourcing networks, while craft microbreweries absorb specification premiums that commodity lager producers refuse. Margin pools concentrate in specialty crystal and roasted grades where kilning expertise creates defendable differentiation.
Pricing Analysis
Legacy kiln technology versus precision-automated systems versus electrified retrofits stratifies pricing tiers across the installed base. Three-tier pricing structure across premium, standard, and economy levels reflects Lovibond color precision, EFSA acrylamide compliance certification, and volume scale. Pricing pressure stems from energy cost volatility in natural gas-dependent kilning operations. Microbreweries exhibit highest price sensitivity to base malt contracts; single-malt distilleries show lowest sensitivity for heritage varietal programs.
Supply Chain Analysis
REACH chemical safety registrations and EFSA food-grade purity thresholds function as de facto export controls limiting non-compliant malt flows into European brewing corridors. Geographic supply concentration centers on Germany, Belgium, and the United Kingdom for specialty-grade output. Raw material dependencies rest on Australian two-row barley, Canadian prairie wheat, and heritage Scottish varietals. Single-source vulnerability runs through Rhine logistics corridors between Mainz and Mannheim. Distribution runs through direct-to-brewery silo deliveries and merchant maltster redistribution networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Craft brewing fragmentation across Belgium, the United States, and Australia creates niche entry points for specialists who bypass volume-commodity economics. Microbrewery procurement decentralization rewards localized kilning operations with recipe-consultation capabilities.
For Market Incumbents: Build regulatory-compliance moats through dedicated EFSA and FDA quality laboratory investments that extend certification timelines for challengers. Anchor backward integration into barley origination across Australian and Canadian growing regions to compress input volatility exposure. Consolidate automated kiln control deployments that reduce batch-to-batch specification drift below competitor tolerance windows. For New Entrants and Emerging Players: Build out small-batch specialty malt capacity targeting Indian state-level licensing reforms in Karnataka and Maharashtra where import channels for caramel and roasted grades remain underdeveloped. Exploit malting technologist scarcity among retiring European specialists by recruiting from emerging brewing education programs. Lead go-to-market through direct-to-distillery contracting models that bypass established merchant maltster relationships. For Investors and Strategic Acquirers: Capital is best deployed toward automated kiln technology specialists with EU Green Deal carbon-accounting positioning for renewable thermal energy certificates. Long-term viability favors operators with demonstrated specification-grade consistency for industrial brewing contracts and heritage floor-malting credibility for craft segment premiums. Watch for inflection in electrified kiln retrofit adoption rates across German malting groups facing embedded emissions accounting pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Kiln Retrofit | Sensor-driven moisture management compresses Lovibond color variance for craft brewery contracts. |
| Backward Integration into Barley Origination | Captive supply from Australian and Canadian growing regions insulates margin from drought-driven input spikes. |
| EU Green Deal Carbon Certification | Renewable thermal energy certificates position low-carbon malt for premium brewing procurement in Belgium. |
| Direct-to-Distillery Contracting | Speyside and Islay single-malt producers lock multi-year heritage varietal supply bypassing merchant maltsters. |
| Heritage Floor-Malting Capacity Expansion | Traditional germination biochemistry expertise commands specification premiums from Trappist abbey breweries. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across malting technologists, craft brewery procurement managers, distillery supply chain directors, and barley origination specialists. Secondary validation drew from EFSA food-safety filings, REACH chemical registration databases, EU Green Deal policy documentation, and customs trade flows for malt and barley categories. Bottom-up segment sizing triangulated against top-down macroeconomic demand indicators across the projection horizon.
Calibration anchored volume and value outputs to observed procurement contract structures, kilning capacity utilization rates, and specialty-grade premium realizations. Segmentation dimensions modeled include product type tiers, form factor processing depth, brewing versus distilling application splits, and microbrewery versus commercial brewery end-user scale. CAGRs derived from trend extrapolation of craft segment penetration, regulatory compliance cost trajectories, and carbon-accounting framework adoption timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by electrified kiln retrofit specialists or heritage floor-malting consolidators would shift outcomes. Material shifts in EFSA acrylamide limit enforcement stringency or EU carbon-border adjustment mechanism scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Beer Mug Market
Alcoholic Beverages
Portable Keg System Market
Alcoholic Beverages
Guerbet Alcohols Market
Alcoholic Beverages
Absinthe Market
Alcoholic Beverages
Airport Duty-Free Liquor Market
Alcoholic Beverages
Drinkware, Beverageware, and Barware Market
Alcoholic Beverages
Wine Bottle Sterilizer Market
Alcoholic Beverages
South America Fermented Drinks Market
Alcoholic Beverages
Fruit Brandy Market
Alcoholic Beverages
Middle East and Africa Fermented Drinks Market
Alcoholic Beverages
CBD Wine Market
Alcoholic Beverages
Brandy Market
Alcoholic Beverages
United States Spirits Market
Alcoholic Beverages
Vodka Seltzer Market
Alcoholic Beverages
Orange Wine Market
Alcoholic Beverages
Pub Cellar Equipment Market