
 Potato Protein Market | 2026-2036
Potato Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Potato Protein Market Analysis
Buyer concentration among food manufacturers is hardening as large-scale processors consolidate supplier rosters to secure volume commitments. Royal Avebe leverages its cooperative structure to sustain long-term supply contracts with European food manufacturers. Roquette Freres anchors its position through deep specialization in plant-protein extrusion technologies. Emsland Group competes by controlling integrated potato starch and protein processing operations across Germany and the Netherlands.
Potato protein is the concentrated or isolated protein fraction extracted from potato tubers, typically containing 75-90% protein by dry weight with a well-balanced amino acid profile including high lysine content. Manufacturers recover this protein through acid precipitation or membrane filtration of potato fruit juice, a byproduct of starch extraction, yielding functional ingredients for emulsification and gelation in formulated foods. Isolates command the strongest margin pools due to their superior functionality in meat analogues and dairy alternatives, while concentrates retain broader volume traction in animal feed applications. Sports nutrition represents the fastest-growing application channel as endurance athletes and fitness consumers shift toward hypoallergenic, non-soy protein sources.
The European Food Safety Authority (EFSA) evaluates novel food applications for potato protein isolates, while REACH governs chemical safety in processing aids and extraction solvents. The EU Green Deal pressures processors to reduce water and energy intensity in protein recovery operations. Stakeholders must monitor how evolving EFSA guidance on protein digestibility claims reshapes product positioning and market access requirements.
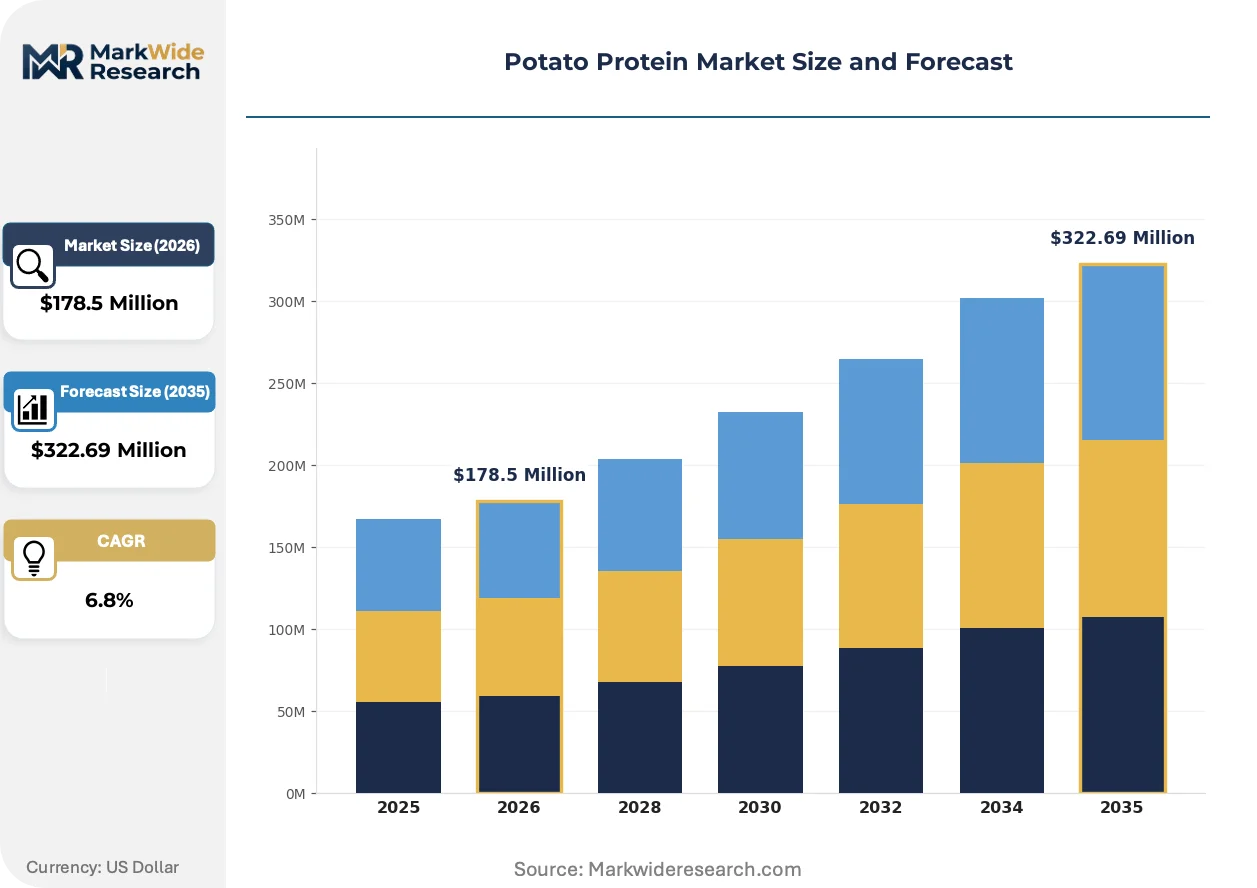
Market Dynamics
Processor consolidation among European starch cooperatives is concentrating supply-side leverage, while EFSA novel food assessments create asymmetric compliance burdens for new entrants versus incumbent operators with grandfathered approvals.
Growth Catalysts
- EU Green Deal water-intensity mandates:Processors investing in closed-loop membrane filtration systems qualify for green financing, accelerating capital deployment into high-purity isolate capacity.
- Sports nutrition formulation partnerships:Endurance nutrition brands in Germany and the Netherlands are locking in multi-year offtake agreements for hypoallergenic protein sources.
- Acid precipitation yield improvements:Dutch research clusters have optimized protein recovery rates from potato fruit juice, lowering unit costs for functional isolates.
Market Restraints
- Input cost volatility in potato tuber supply:Weather-driven starch potato harvest variability in Germany and the Netherlands creates margin compression for processors without backward integration into farming cooperatives.
- REACH solvent compliance burdens:Chemical safety registration requirements for extraction aids impose fixed compliance costs that disproportionately burden smaller isolate producers.
- Soy protein isolate substitution threat:Mature soy processing infrastructure in the US Midwest and Brazil delivers comparable functionality at scale-established price points.
Strategic Opportunities
- Underpenetrated precision fermentation integration:Dutch biotechnology clusters are exploring hybrid production models combining potato protein hydrolysates with microbial biomass for next-generation meat analogues.
- CSRD sustainability disclosure tailwinds:Large European food manufacturers facing mandatory Scope 3 reporting are sourcing traceable potato protein to meet regenerative agriculture claims in annual statements.
- Emerging pet nutrition applications:Premium companion animal food brands in France and the UK are formulating with potato protein to address canine soy and grain sensitivities.
Industry Challenges
- Membrane filtration engineering talent scarcity:Specialized process engineers with pilot-scale protein recovery experience command premium compensation in the Netherlands and Germany.
- Novel food authorization timeline uncertainty:EFSA evaluation periods for new isolate applications extend commercialization timelines by 18-36 months versus existing approved ingredients.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Potato Protein Market |
| Market Size in 2026 | $178.5 Million |
| Market Size in 2035 | $322.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isolates, Concentrates, Textured, Flour Application: Food & Beverage, Animal Feed, Nutraceuticals, Sports Nutrition Packaging Type: Bags, Boxes, Bulk Containers, Pouches End User: Food Manufacturers, Supplement Companies, Pet Food Producers, Bakeries |
| Companies Covered | Emsland Group, PEPEES Group, Royal Avebe, SudZucker, Kerry Group, Roquette Freres, KMC Ingredients, AKV Langholt, Tereos Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Potato Protein Market Emerging Trajectories
Protein recovery technology is converging with precision fermentation infrastructure, while regulatory disclosure mandates and shifting procurement criteria are redefining supplier qualification requirements across European food manufacturing.
Membrane filtration is integrating with enzymatic pre-treatment protocols to enhance protein yield from potato fruit juice. German and Dutch processors are retrofitting starch extraction lines with ceramic ultrafiltration modules. This convergence is integrating downstream purification capacity with upstream agricultural processing, compressing capital requirements for new isolate entrants.
REACH chemical safety registrations for novel extraction solvents are tightening process chemistry choices. The F-Gas Regulation is phasing out certain refrigerants used in protein precipitation cooling systems. Potato protein isolate producers are responding by investing in ammonia-based cooling infrastructure or aqueous two-phase extraction methods that bypass regulated solvents.
Food manufacturers are unbundling protein ingredient specifications from bundled starch-protein procurement contracts. Large European meat analogue producers are issuing separate tenders for functional isolates versus commodity concentrates. This disintermediation is most visible in Germany, where ingredient technology clusters enable direct supplier relationships bypassing traditional trading houses.
Potato Protein Market Segmentation
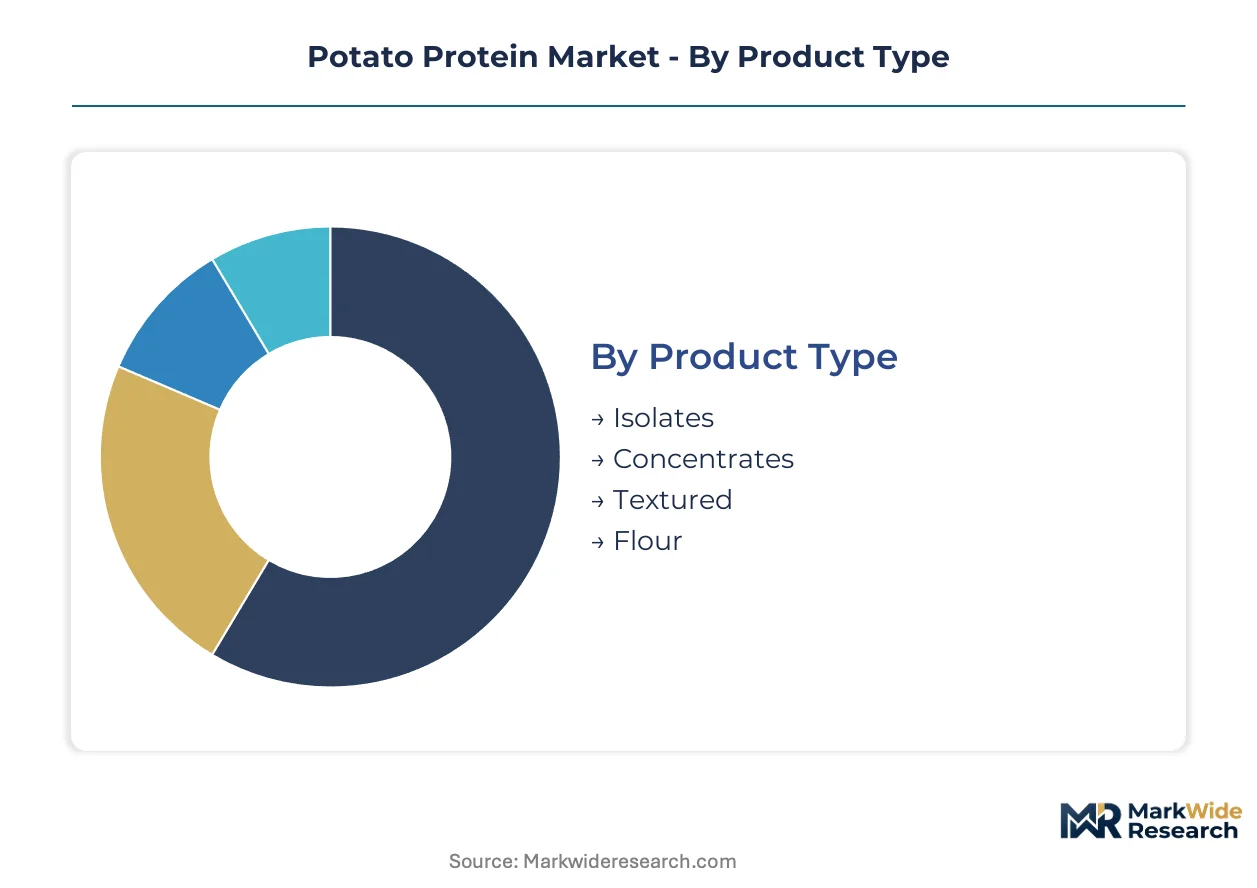
Potato protein segmentation reflects divergent regulatory pathways and functional specifications across product grades. EFSA novel food approvals concentrate in isolate categories, while feed-grade concentrates operate under less stringent feed additive frameworks.
Product Type:
EFSA novel food authorization requirements split sharply across this category, with isolates facing full safety assessments while concentrates leverage existing feed additive registrations.
- Isolates:Purified protein fractions containing 85-90% protein by dry weight, recovered through membrane filtration or acid precipitation of potato fruit juice. Demand concentrates in German meat analogue facilities seeking emulsification performance comparable to soy isolates, constrained by REACH registration burdens for extraction solvents that favor incumbent processors with grandfathered chemical approvals.
- Concentrates:Lower-purity fractions at 60-75% protein content, retaining more native starch and fiber. Volume concentrates in Dutch and German animal feed compounding, where backward integration into starch cooperatives secures supply stability against weather-driven tuber harvest variability.
- Textured:Extruded protein structures mimicking meat fiber organization, produced through high-moisture extrusion of isolate-concentrate blends. Dutch ingredient technology clusters dominate pilot-scale capacity.
- Flour:Whole potato protein-rich fractions with minimal processing, retaining native potato flavor and color profiles. Niche applications in European gluten-free bakery formulations.
Leading the category by volume: Concentrates. Growing fastest: Isolates.
Application:
Margin structures diverge sharply across this dimension, with sports nutrition commanding premium pricing against commodity feed applications.
- Food & Beverage:Dairy alternatives, meat analogues, and bakery applications requiring functional protein for gelation and emulsification. German formulators drive specification tightening around protein digestibility scores.
- Animal Feed:Aquaculture and livestock rations leveraging potato protein as a non-GMO, non-soy alternative. Dutch feed compounders anchor European volume offtake.
- Nutraceuticals:Capsule and tablet formulations targeting digestive health and amino acid supplementation. EFSA health claim restrictions limit positioning flexibility.
- Sports Nutrition:Hypoallergenic protein powders for endurance athletes with soy and dairy sensitivities. German and Dutch brands are locking in multi-year supply contracts, expanding most quickly within the application mix.
Highest margin capture: Sports Nutrition. Largest volume base: Animal Feed.
Packaging Type:
Supply chain configuration tracks customer scale and shelf-life requirements, with bulk formats dominating processor-processor transactions.
- Bags:Multi-wall paper or polyethylene sacks for 25-50kg industrial distribution. Standard for mid-volume food manufacturers without pneumatic handling systems.
- Boxes:Corrugated containers with inner liners for retail-ready ingredient shipments. French and UK distributors prefer this format for bakery sector deliveries.
- Bulk Containers:Flexible intermediate bulk containers and tanker shipments for high-volume meat analogue producers. German extrusion facilities receive isolate deliveries in this format.
- Pouches:Stand-up and flat pouches for sports nutrition brands requiring consumer-facing packaging. Premium positioning supports higher unit economics.
Dominant by tonnage: Bulk Containers. Steepest expansion trajectory: Pouches.
End User:
Procurement sophistication varies dramatically, with supplement companies conducting extensive supplier audits versus bakeries relying on distributor intermediation.
- Food Manufacturers:Meat analogue, dairy alternative, and processed food producers requiring functional protein with documented amino acid profiles. German and Dutch facilities issue separate tenders for isolates versus concentrates.
- Supplement Companies:Sports nutrition and nutraceutical brands demanding batch-level traceability and third-party testing. EFSA novel food documentation requirements extend qualification timelines.
- Pet Food Producers:Premium companion animal brands in France and the UK formulating for canine sensitivities. Growing segment seeking non-soy, non-grain protein sources.
- Bakeries:Gluten-free and allergen-free specialty producers using potato flour and protein for texture modification. Smaller scale, price-sensitive procurement.
Most stringent qualification requirements: Supplement Companies. Fastest-growing demand source: Pet Food Producers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for potato protein concentrates heavily in Germany and the Netherlands, where starch cooperative infrastructure supports scaled isolate production. Processing investments cluster along the Dutch-German border corridor, driven by EFSA novel food pathways and sports nutrition procurement.
Germany
Meat analogue manufacturers in Lower Saxony and Bavaria drive isolate procurement for emulsification performance. The EU Green Deal water-intensity mandates push processors toward closed-loop membrane filtration retrofits. Ingredient technology clusters around Hamburg and Frankfurt anchor pilot-scale textured protein capacity.
Netherlands
Dutch feed compounders and sports nutrition brands lock in multi-year offtake agreements for hypoallergenic protein. REACH solvent registration requirements favor incumbent processors with grandfathered chemical approvals. Wageningen-area research clusters optimize acid precipitation yields from potato fruit juice.
France
Premium pet food producers in Brittany and the Paris region formulate with potato protein for canine soy sensitivities. EFSA novel food documentation extends qualification timelines for isolate entrants. The country's national food safety regulator enforces strict batch-level traceability for nutraceutical applications.
United Kingdom
Gluten-free bakery specialists source potato flour and protein for texture modification in allergen-free formulations. CSRD sustainability disclosure mandates push large manufacturers toward traceable regenerative agriculture claims. Distribution concentrates through Midlands ingredient hubs serving retail-ready channels.
Poland
Starch potato cultivation expansion in Greater Poland and Masovia supports concentrate volume for animal feed compounding. Weather-driven harvest variability creates margin pressure for processors without cooperative backward integration. Emerging extrusion capacity targets Central European meat analogue demand.
Potato Protein Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue precision fermentation hybridization and pet nutrition specialization. The market exhibits cooperative-backed consolidation alongside specialized ingredient technology differentiation. Three archetypes dominate: starch cooperative incumbents with captive tuber supply, plant-protein extrusion specialists, and diversified nutrition ingredient platforms. Competitive moves concentrate on membrane filtration capacity expansion and EFSA novel food authorization racing.
Within the cooperative-incumbent tier, Royal Avebe and Emsland Group exemplify structures leveraging backward integration into farming operations to secure volume commitments. Roquette Freres occupies a position representing deep specialization in plant-protein extrusion technologies. These three entities anchor the competitive landscape through distinct supply chain control mechanisms rather than undifferentiated scale.
| Leading Market Players |
|---|
| Emsland Group |
| PEPEES Group |
| Royal Avebe |
| SudZucker |
| Kerry Group |
| Roquette Freres |
| KMC Ingredients |
| AKV Langholt |
| Tereos Group |
| Others |
Supply Flow & Price Mechanics
Isolate-concentrate bifurcation drives divergent margin structures across the potato protein value chain, with premium functional grades commanding contract-based offtake premiums while feed-grade concentrates trade on spot-indexed starch cooperative pricing. This tiered separation manifests in procurement patterns: meat analogue manufacturers in Germany negotiate multi-year isolate supply agreements with membrane filtration specialists, while Dutch animal feed compounders source concentrates through backward-integrated cooperative channels that internalize tuber harvest volatility.
Pricing Analysis
Volume-mass concentrates trade at commodity-indexed rates tied to starch cooperative output, while high-purity isolates capture substantial margin premiums through long-term formulation partnerships with sports nutrition brands. Price differentiation rests on EFSA novel food authorization status and protein digestibility scores, with REACH-compliant processors passing through solvent registration costs. Pricing pressure intensifies in the concentrate tier as weather-driven tuber harvest variability compresses margins for non-integrated processors. Supplement companies exhibit lowest price sensitivity, prioritizing batch traceability and hypoallergenic certification over unit economics.
Supply Chain Analysis
Direct-to-manufacturer channels handle high-volume isolate demand from German meat analogue extrusion facilities, while distributor-mediated flows serve smaller French and UK bakery formulators. Geographic concentration centers on the Netherlands and Germany, where Wageningen-area research clusters and Lower Saxony starch cooperatives anchor production. Raw material supply draws from contract potato cultivation in the Netherlands, Germany, and Poland, with protein recovery operations tethered to starch extraction byproduct streams. Single-source vulnerability runs through membrane filtration engineering talent scarcity in Dutch-German border regions. Distribution runs through flexible intermediate bulk containers for industrial processors and multi-wall sacks for mid-volume food manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure is hardening across the potato protein landscape as REACH solvent compliance burdens and EFSA novel food authorization timelines force sub-scale processors toward exit or acquisition. Cooperative-backed incumbents with grandfathered chemical approvals are capturing disproportionate margin pools.
For Market Incumbents: Acquire membrane filtration engineering capabilities to secure pilot-scale textured protein capacity ahead of precision fermentation hybridization threats. Expand closed-loop water recovery infrastructure to qualify for EU Green Deal green financing, locking in cost advantages against smaller isolate producers facing margin compression from weather-driven tuber harvest variability.
For New Entrants and Emerging Players: Sports nutrition distributors in Germany and the Netherlands represent the most accessible channel partners for hypoallergenic protein positioning, bypassing incumbent-dominated meat analogue tender processes. Target pet nutrition applications in France and the UK where canine sensitivity formulations command premium positioning with less stringent EFSA documentation requirements than human nutraceuticals.
For Investors and Strategic Acquirers: Exit pathways concentrate in cooperative-backed processors with captive tuber supply and grandfathered REACH registrations, as regulatory moats deepen against new entrants. Long-term viability favors assets with integrated starch-protein operations and established EFSA novel food dossiers. Monitor EFSA guidance evolution on protein digestibility claims as the critical inflection signal for isolate premium sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Capacity Expansion | Closed-loop systems qualify processors for EU Green Deal green financing instruments. |
| EFSA Novel Food Authorization Racing | Grandfathered approvals create asymmetric compliance burdens against new isolate entrants. |
| Backward Integration into Farming Cooperatives | Captive tuber supply insulates margin stability from weather-driven harvest variability. |
| Precision Fermentation Hybridization | Dutch biotechnology clusters explore microbial biomass integration for next-generation meat analogues. |
| CSRD-Aligned Sustainability Disclosure | Traceable regenerative agriculture claims support large European food manufacturer Scope 3 reporting. |
Methodological Framework
Document review covered EFSA novel food registers, REACH chemical safety filings, and EU starch cooperative annual disclosures, complemented by interviews with membrane filtration process engineers, sports nutrition procurement directors, Dutch feed compounder supply planners, and German meat analogue facility managers. Secondary validation drew from customs trade data, SEC filings of diversified nutrition ingredient platforms, and EU agricultural production statistics. Bottom-up capacity modeling and top-down demand segmentation were triangulated against primary field intelligence.
Segmentation outputs across product type, application, packaging format, and end-user category were projected across the analysis window using demand elasticity modeling calibrated to EFSA authorization timelines and sports nutrition contract disclosure patterns. CAGRs were derived from installed capacity expansion announcements, cooperative investment disclosures, and formulation partnership duration analysis. Forecast inputs incorporated EU Green Deal water-intensity mandate compliance trajectories and precision fermentation pilot-scale development indicators.
Several conditions sit outside the modeled scope, including unannounced regulatory shifts in extraction solvent classifications, disruptive precision fermentation scale-up timelines, and extreme weather events affecting starch potato cultivation. Forecasts reflect assumptions around EFSA evaluation period stability and cooperative infrastructure investment continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Soybean Oil Market
Ingredients
Mallow Glycolic Extract Market
Ingredients
Pomegranate Peel Polyphenol Complex Market
Ingredients
GCC Bakery Ingredients Market
Ingredients
Encapsulated Salt Market
Ingredients
Pea Fiber Market
Ingredients
African Brewing Enzymes Market
Ingredients
Middle East and Africa Lipids Market
Ingredients
Protein Hydrolysate Market
Ingredients
Freeze-Dried Pea Isolates Market
Ingredients
Functional Flours Market
Ingredients
Textured Wheat Protein Market
Ingredients
North America Rice Bran Oil Market
Ingredients
Fiber Rich Flours Market
Ingredients
Wheat Starch Market
Ingredients
Europe Vanilla Beans and Extract Market