
 Codonopsis Extract Market | 2026-2036
Codonopsis Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Codonopsis Extract Market Insights
Multi-source botanical procurement is expanding across Codonopsis extract supply chains as buyers diversify away from single-origin dependencies. Xi'an Lyphar Biotech anchors large-scale extraction capacity in Shaanxi Province. Shaanxi Jintai Biological Engineering leverages proprietary low-temperature processing to sustain higher active compound retention. Chengdu Biopurify Phytochemicals specializes in pharmaceutical-grade purification for regulated export markets.
Codonopsis extract comprises dried root-derived phytochemicals standardized for polysaccharide and saponin content, typically processed through aqueous or ethanol extraction followed by spray-drying or vacuum concentration into powder, liquid, or encapsulated formats. The extract serves primarily as an adaptogenic ingredient in immune-support and fatigue-reduction formulations across nutraceutical and traditional medicine applications. Powder formats dominate bulk ingredient procurement due to stability and blending flexibility, while capsule and softgel configurations capture premium positioning in direct-to-consumer channels. Dietary supplements represent the deepest application pool, though pharmaceutical-grade specifications command the highest margin tiers as quality certification requirements intensify.
China's NMPA and SAMR govern herbal extract registration, manufacturing licensing, and quality standards through GB protocols and pharmacopoeia monographs that determine domestic market access and export eligibility. The US FDA and DSHEA framework shape import requirements for botanical dietary ingredients, including New Dietary Ingredient notification obligations for novel extract specifications. Stakeholders must monitor evolving pharmacopeial harmonization between Chinese, European, and US standards to anticipate reformulation costs and qualification timelines.
Market Dynamics
Raw material procurement from Shaanxi Province extraction clusters is consolidating under vertically integrated processors, compressing spot-market availability and forcing downstream formulators into long-term offtake agreements with designated suppliers.
Growth Catalysts
- DSHEA NDI pathway:US dietary supplement brands are accelerating Codonopsis extract inclusion in adaptogenic formulations following clarified FDA notification procedures for established botanical ingredients.
- Pharmaceutical-grade purification:Contract manufacturers serving regulated European markets are expanding capacity for pharmacopeial-grade extract to meet EMA quality documentation requirements.
- Xi'an processing cluster:Concentrated extraction infrastructure in Shaanxi Province enables cost-efficient aqueous and ethanol processing at industrial scale.
Market Restraints
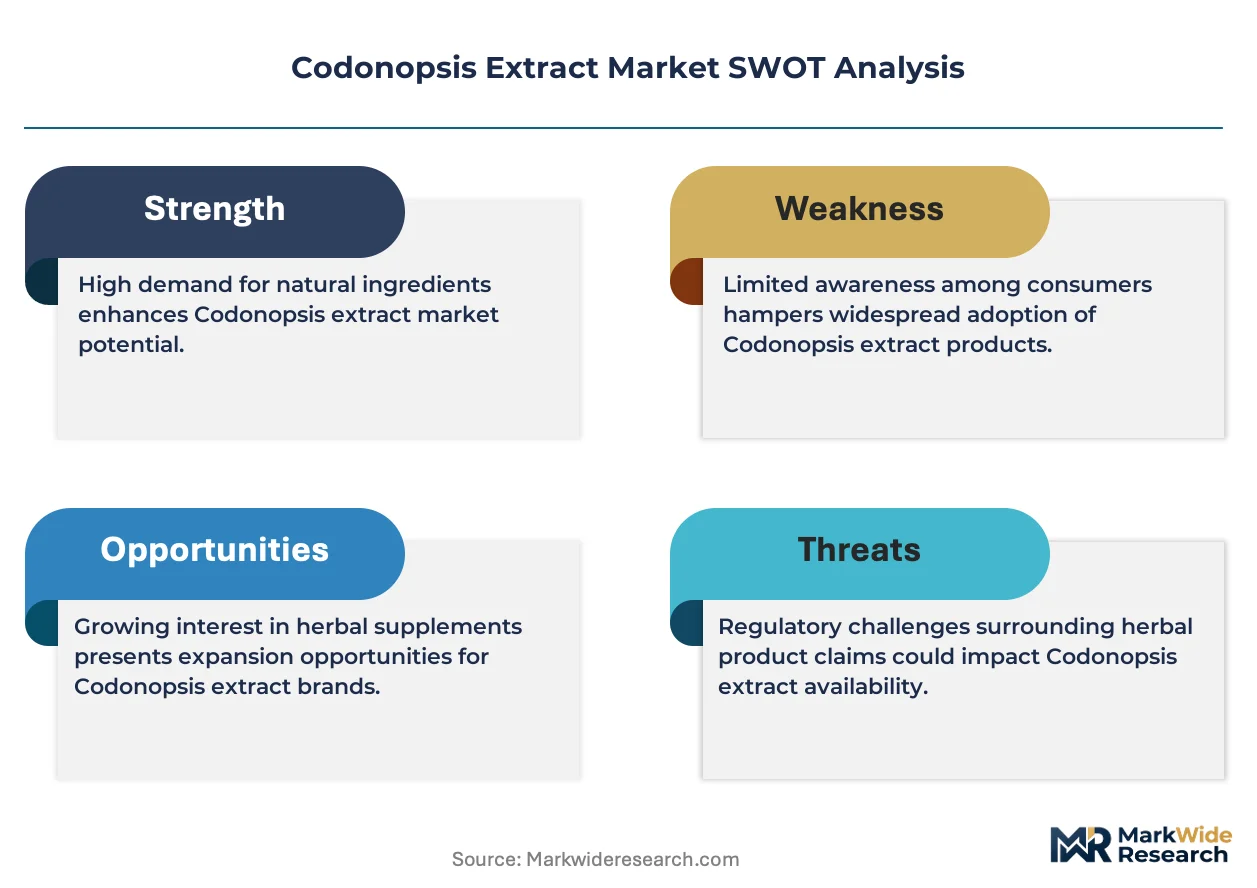
- Single-origin cultivation risk:Overdependence on Gansu and Shanxi province root supply exposes processors to climate-induced yield volatility and regional crop failure.
- Polysaccharide standardization costs:Achieving consistent saponin and polysaccharide content across batches requires advanced chromatographic verification, elevating quality control expenditure.
- Substitution by Panax ginseng:Established adaptogenic brands retain formulation preference for Korean and Chinese ginseng extracts with deeper clinical documentation and consumer recognition.
Strategic Opportunities
- SAMR functional food registration:China's streamlined health food filing system permits Codonopsis extract inclusion in beverages and fortified foods beyond traditional supplement formats.
- Direct-to-consumer capsule channels:E-commerce platforms and subscription wellness services are creating bypass routes around bulk ingredient distributors for branded finished products.
- Veterinary adaptogenic applications:Livestock stress-management formulations represent an emerging demand vertical with lower regulatory barriers than human pharmaceutical specifications.
Industry Challenges
- Pharmacopeial harmonization delays:Divergent monograph specifications between Chinese Pharmacopoeia, European Pharmacopoeia, and USP are forcing dual-standard production runs and extended qualification timelines for multi-market suppliers.
- Extraction technician scarcity:Specialized expertise in low-temperature vacuum concentration and spray-drying optimization for heat-sensitive saponins remains concentrated among senior operators at established Shaanxi facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Codonopsis Extract Market |
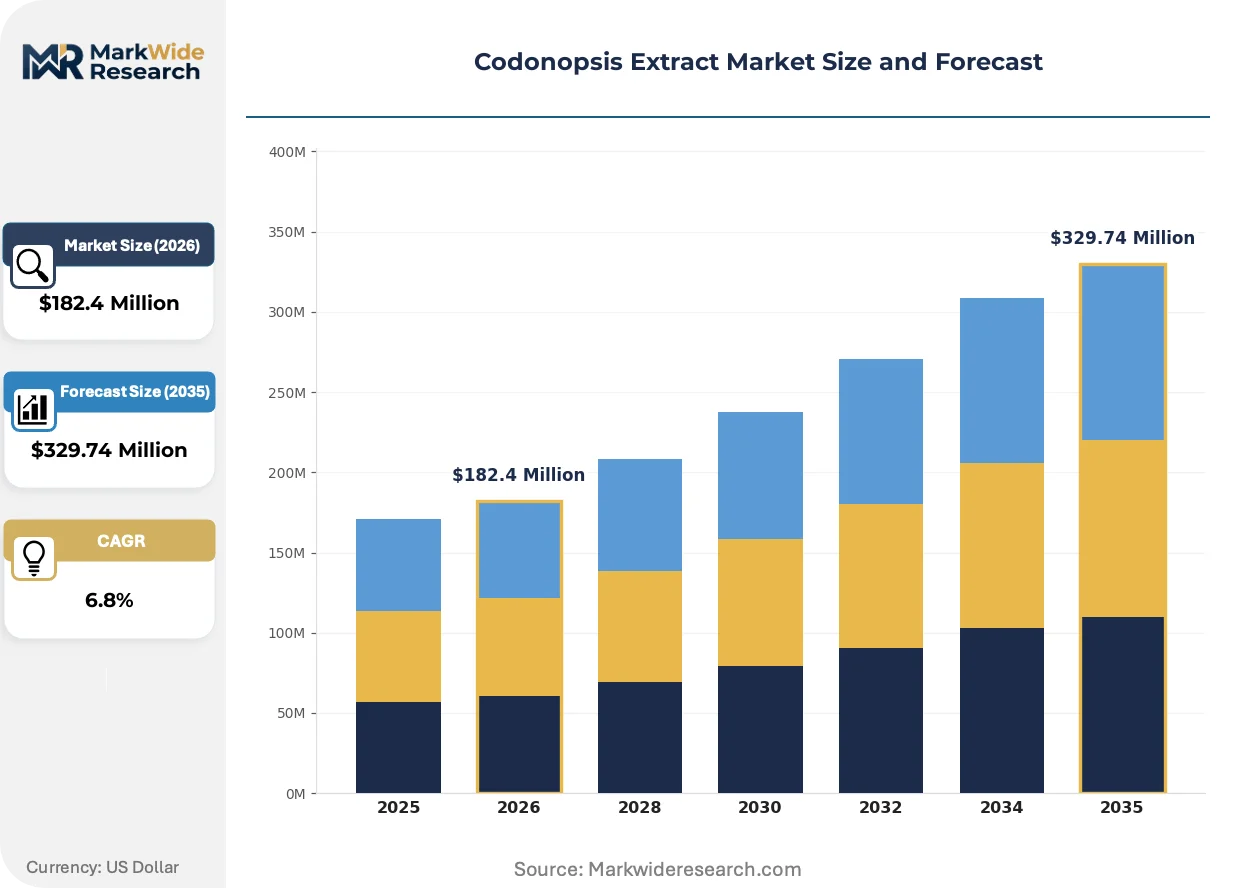
| Market Size in 2026 | $182.4 Million |
| Market Size in 2035 | $329.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Capsule, Softgel Application: Dietary Supplements, Herbal Remedies, Pharmaceuticals, Cosmetics Distribution Channel: Online Retail, Health Stores, Pharmacies, Supermarkets End User: Health-conscious Consumers, Athletes, Patients, Retailers |
| Companies Covered | Xi'an Lyphar Biotech, Shaanxi Jintai Biological Engineering, Chengdu Biopurify Phytochemicals, Hunan Nutramax, Xi'an Natural Field Bio-Technique, Shaanxi Undersun Biomedtech, Xi'an Le Sen Bio-Technology, Changsha Zhongren Biotechnology, Hubei Jusheng Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Codonopsis Extract Market Trends and Innovations
Processing technology and regulatory documentation standards are converging to reshape competitive positioning among Codonopsis extract suppliers, with quality verification capabilities becoming the primary differentiation mechanism.
Low-temperature vacuum concentration equipment is consolidating extraction efficiency gains among mid-scale processors seeking to minimize thermal degradation of bioactive polysaccharides. Dietary supplement contract manufacturers are adopting this technology to meet premium-tier procurement specifications from North American and European brands. The structural consequence is compressing margins for conventional spray-drying operators unable to demonstrate superior active compound retention.
REACH registration requirements for botanical extracts imported into the European Union are intensifying substance characterization obligations for Codonopsis-derived materials. Suppliers must now compile comprehensive safety data packages covering saponin fractions and heavy metal profiles to maintain market access. Pharmaceutical-grade specification holders are responding by investing in dedicated analytical laboratories to accelerate compliance documentation.
Formulation houses are consolidating purchase volumes through designated supplier programs rather than spot-market sourcing, compressing the viable vendor base for standardized extract. This behavioral shift is displacing traditional trading company intermediaries in favor of direct processor relationships with verified cultivation traceability. The transformation is most visible among US and German dietary supplement brands targeting adaptogenic positioning in immune support categories.
Codonopsis Extract Market Segmentation
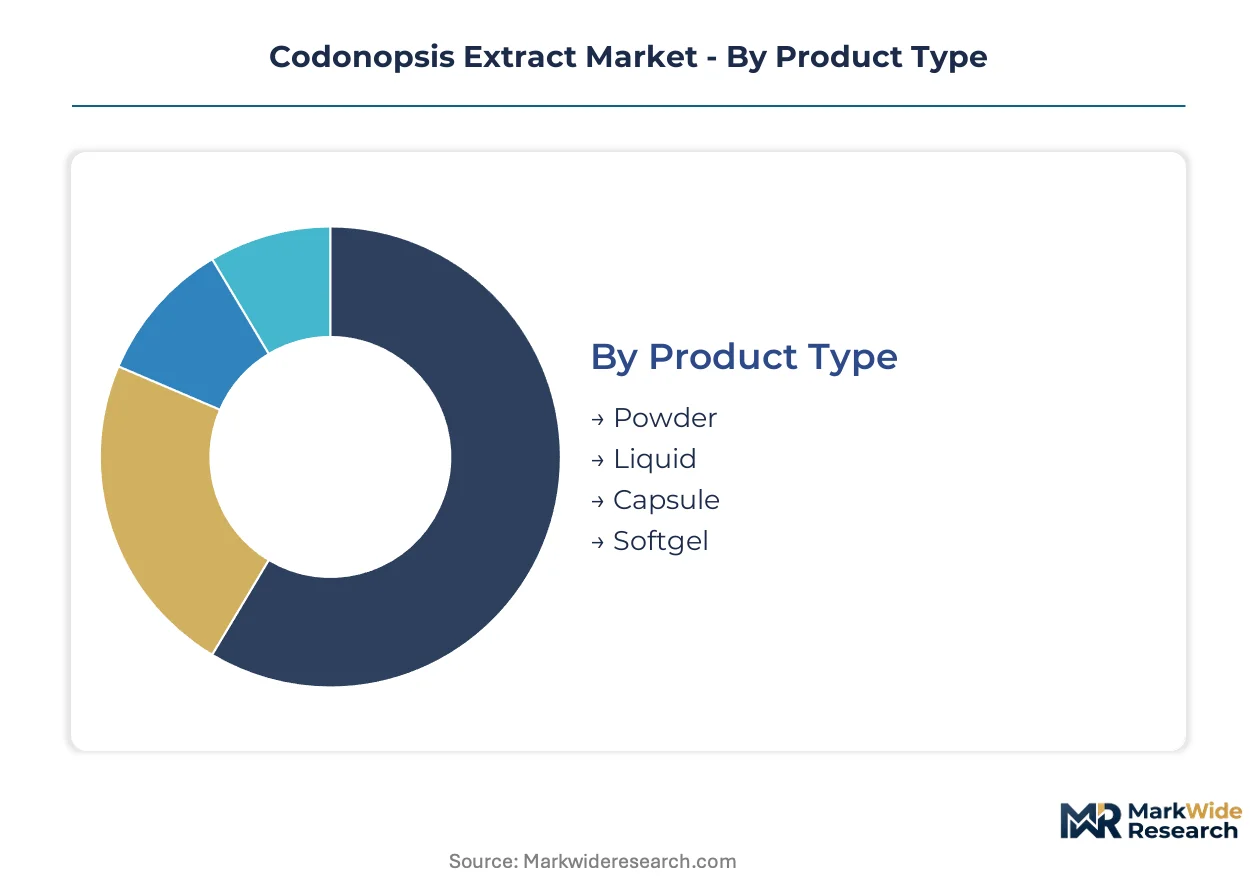
Codonopsis extract procurement patterns diverge sharply across format specifications and channel structures. Formulators select product types based on stability requirements and blending economics, while end-user segmentation reveals divergent quality tolerances and dosage preferences.
Product Type:
Upgrade cycles from conventional spray-dried powders to low-temperature processed alternatives are compressing margins for legacy processors unable to demonstrate superior polysaccharide retention.
- Powder:Spray-dried or vacuum-concentrated extracts standardized for polysaccharide content serve bulk ingredient procurement from dietary supplement contract manufacturers. Demand concentrates in Shaanxi Province extraction clusters serving North American adaptogenic brands, driven by blending flexibility and extended shelf stability requirements.
- Liquid:Aqueous or ethanol-based tinctures and concentrates target traditional medicine practitioners and functional beverage formulators seeking rapid dissolution characteristics. Tincture demand is climbing fastest among European herbal remedy distributors prioritizing dosage precision over transport efficiency.
- Capsule:Pre-measured gelatin or vegetable cellulose enclosures capture premium positioning in direct-to-consumer channels.
- Softgel:Oil-based suspensions in gelatin matrices serve lipid-soluble saponin formulations targeting enhanced bioavailability claims.
Volume placements concentrate in Powder; the faster expansion belongs to Liquid.
Application:
Cost tier stratification separates commodity-grade botanical inputs from pharmaceutical-grade specifications commanding intensive documentation burdens.
- Dietary Supplements:Adaptogenic and immune-support formulations represent the deepest application pool, with capsule and tablet configurations dominating finished product configurations. Procurement from US brands is accelerating following clarified DSHEA notification pathways for established botanical ingredients.
- Pharmaceuticals:Pharmacopeial-grade extracts meeting Chinese Pharmacopoeia, European Pharmacopoeia, or USP monograph requirements command the highest margin tiers. European contract manufacturers are expanding purification capacity to satisfy EMA quality documentation requirements.
- Herbal Remedies:Traditional medicine decoctions and practitioner-dispensed preparations sustain consistent demand in domestic Chinese and diaspora markets.
- Cosmetics:Topical adaptogenic claims in anti-fatigue and skin-brightening formulations represent an emerging specification tier with lower volume but premium positioning.
Revenue concentration sits with Dietary Supplements; steepest expansion trajectory belongs to Pharmaceuticals.
Distribution Channel:
Customer type fragmentation is forcing suppliers to maintain parallel certification portfolios for institutional procurement versus consumer-direct specifications.
- Online Retail:E-commerce platforms and subscription wellness services enable branded finished products to bypass traditional bulk ingredient distributors. Amazon and specialized botanical marketplaces are gaining share fastest among North American health-conscious consumers.
- Health Stores:Independent and chain natural product retailers sustain consistent placement for established adaptogenic brands with consumer recognition.
- Pharmacies:Regulated retail channels in Germany, France, and Italy require pharmacopeial-grade documentation for herbal remedy placement.
- Supermarkets:Mass-market grocery channels in China are expanding functional food and beverage placements following SAMR streamlined health food filing system expansions.
Volume leadership remains with Health Stores; channel share is climbing fastest at Online Retail.
End User:
Supply concentration around Xi'an processing infrastructure directly shapes service capabilities across divergent end-user quality requirements.
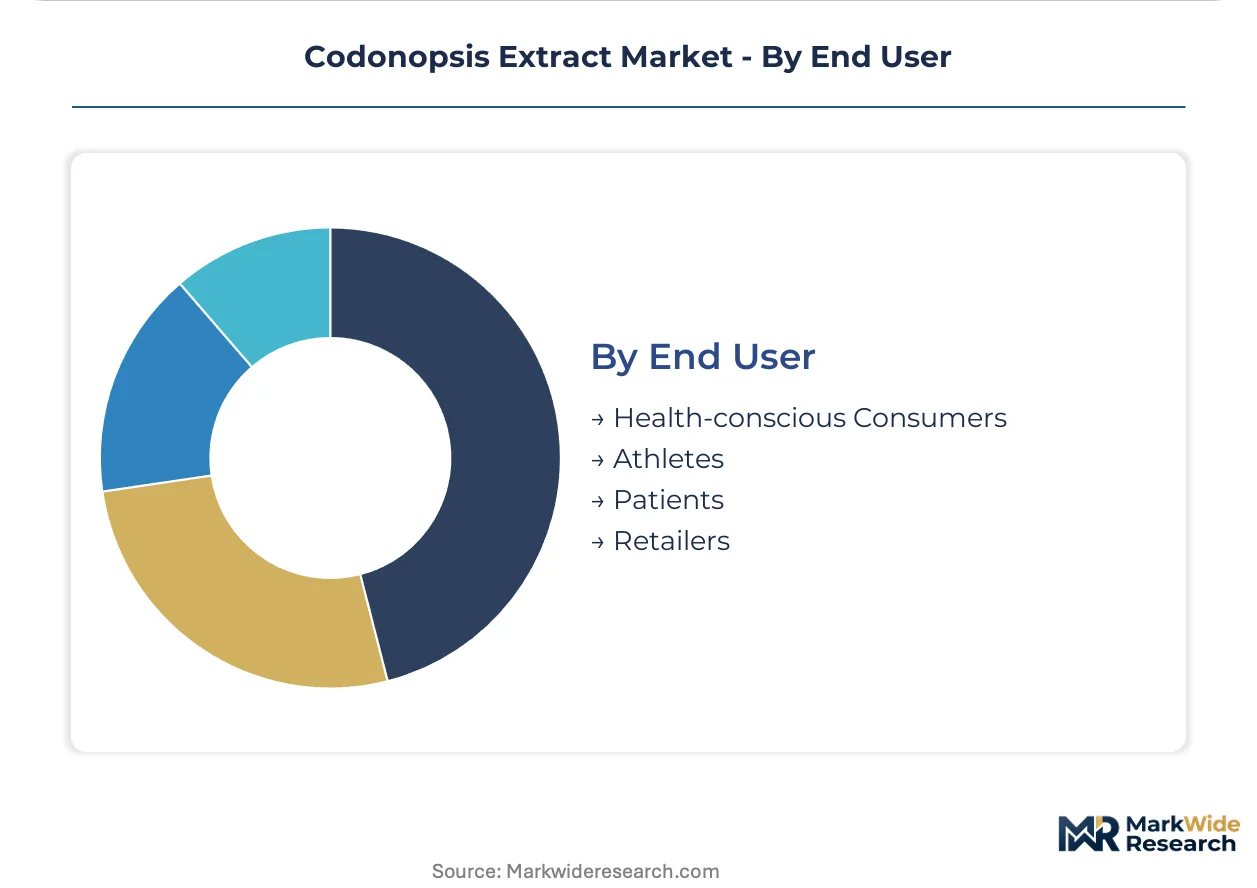
- Health-conscious Consumers:General wellness seekers purchasing adaptogenic supplements for immune support and fatigue management represent the broadest addressable base. Chinese urban consumers are expanding fastest following SAMR functional food registration expansions.
- Athletes:Sports nutrition formulators seeking adaptogenic recovery and endurance claims drive demand for standardized saponin content with batch-verified consistency.
- Patients:Traditional medicine practitioners and integrative health protocols prescribe Codonopsis for specific therapeutic indications requiring documented cultivation traceability.
- Retailers:Private-label and branded finished product companies procure bulk extracts for repackaging and formulation, consolidating purchase volumes through designated supplier programs.
Procurement scale concentrates with Retailers; patient-directed therapeutic applications are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shaanxi Province anchors Codonopsis extract processing capacity, with Xi'an-based extraction clusters supplying raw material refinement for international nutraceutical and pharmaceutical formulators across multiple continents.
United States
Dietary supplement brands are accelerating Codonopsis inclusion in adaptogenic formulations following clarified FDA notification procedures for established botanical ingredients. DSHEA NDI pathway clarifications reduced regulatory uncertainty for contract manufacturers. West Coast formulators in California and Oregon dominate procurement from Shaanxi suppliers for immune-support finished products.
China
Domestic health-conscious consumers are expanding fastest following SAMR functional food registration expansions beyond traditional supplement formats. NMPA herbal medicine registration pathways streamline market access for standardized botanical extracts. Shaanxi Province cultivation and extraction facilities cluster around Xi'an, consolidating vertically integrated processing capacity.
Germany
Pharmacopeial-grade extract demand concentrates among contract manufacturers serving regulated European markets with EMA quality documentation requirements. REACH registration intensifies substance characterization obligations for saponin fractions and heavy metal profiles. Bavaria-based pharmaceutical ingredient distributors anchor import consolidation for Central European formulators.
Japan
Traditional medicine practitioners sustain consistent demand for practitioner-dispensed preparations in domestic and diaspora markets. PMDA oversight of botanical ingredient quality standards shapes import specifications from Chinese processors. Tokyo-Osaka distribution corridors handle bulk extract refinement for finished Kampo formulations.
Australia
TGA regulatory frameworks for complementary medicines determine eligibility for Codonopsis extract inclusion in listed therapeutic goods. Sports nutrition formulators in Victoria and New South Wales drive demand for standardized saponin content with batch-verified consistency. Sydney-based ingredient distributors consolidate procurement from designated Shaanxi supplier programs.
Codonopsis Extract Market Competitive Landscape
Capacity expansion dominates the current landscape as extraction facilities scale low-temperature vacuum concentration capabilities to meet premium-tier procurement specifications. The vendor base organizes around three tiers: vertically integrated processors with captive cultivation, specialized pharmaceutical-grade purifiers, and trading intermediaries facing displacement. Strategic archetypes include scale-driven bulk extract suppliers, technology-differentiated quality specialists, and regulatory-compliance-focused documentation providers. Competitive moves concentrate on backward integration into raw material cultivation and geographic diversification of processing assets.
Within the technology-differentiated tier, Shaanxi Jintai Biological Engineering and Chengdu Biopurify Phytochemicals exemplify divergent specialization paths. Xi'an Lyphar Biotech anchors scale-driven supply consolidation among Shaanxi-based processors. These three entities represent the dominant competitive positioning vectors: proprietary processing retention, pharmaceutical-grade purification, and large-scale extraction infrastructure.
| Leading Market Players |
|---|
| Xi'an Lyphar Biotech |
| Shaanxi Jintai Biological Engineering |
| Chengdu Biopurify Phytochemicals |
| Hunan Nutramax |
| Xi'an Natural Field Bio-Technique |
| Shaanxi Undersun Biomedtech |
| Xi'an Le Sen Bio-Technology |
| Changsha Zhongren Biotechnology |
| Hubei Jusheng Technology |
| Others |
Pricing and Supply Chain Analysis
DSHEA NDI pathway clarifications for established botanical ingredients are compelling US dietary supplement brands to consolidate procurement through designated supplier programs, forcing extraction facilities to absorb certification costs and compress spot-market margins to retain volume commitments.
Pricing Analysis
Warranty and documentation bundling separates pharmaceutical-grade specifications from commodity tiers, with REACH registration packages and pharmacopeial certificates commanding substantial premiums over unverified bulk powder. Three-tier pricing structure across premium, standard, and economy levels reflects quality grade stratification and certification investment depth. Cost compression in standard-tier spray-dried powders is intensifying because low-temperature vacuum processors capture premium positioning. Contract manufacturers exhibit highest price sensitivity; pharmaceutical-grade buyers demonstrate lowest elasticity due to regulatory substitution barriers.
Supply Chain Analysis
Freight cost differentials between aqueous liquid concentrates and spray-dried powders are reshaping format preferences for European and North American importers sourcing from Shaanxi Province. Supply concentrates in China's Gansu and Shanxi cultivation belts for raw root material, with extraction and refinement clustering around Xi'an processing infrastructure. The chain draws from Codonopsis pilosula rootstock, ethanol and aqueous solvents, and gelatin or vegetable cellulose for encapsulation. Single-origin cultivation risk from climate-induced yield volatility represents the dominant structural vulnerability. Distribution runs through designated supplier programs and direct processor relationships displacing traditional trading intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Low-temperature vacuum concentration technology is displacing conventional spray-drying infrastructure, creating a capability divide between quality-tier processors and legacy operators unable to demonstrate superior polysaccharide retention.
For Market Incumbents: Deploy backward integration into captive cultivation in Gansu and Shanxi provinces to secure root supply against climate volatility and substitution by Panax ginseng formulations. Invest in dedicated analytical laboratories to accelerate REACH registration and pharmacopeial compliance documentation for European pharmaceutical contract manufacturers. Channel control through long-term offtake agreements with North American adaptogenic brands defends volume position against emerging low-temperature specialists. For New Entrants and Emerging Players: SAMR streamlined health food filing system in China opens a window for functional beverage and fortified food applications beyond traditional supplement formats. Target veterinary adaptogenic formulations for livestock stress management as the most penetrable application vertical with lower regulatory barriers than human pharmaceutical specifications. Pursue direct-to-consumer capsule channels through e-commerce platforms and subscription wellness services as the primary go-to-market angle bypassing bulk ingredient distributors. For Investors and Strategic Acquirers: Re-rating potential sits with technology-differentiated quality specialists given low-temperature processing retention capabilities becoming the primary procurement criterion for premium-tier North American and European brands. Acquisition focus should center on mid-scale processors with proven pharmacopeial-grade purification infrastructure and verified cultivation traceability systems. Watch for SAMR functional food registration expansion announcements as the inflection indicator signaling addressable market expansion beyond supplement formats.| Strategic Initiative | Industry Significance |
|---|---|
| Low-Temperature Processing Capacity Expansion | Xi'an-based facilities capturing premium-tier procurement from adaptogenic brands seeking superior polysaccharide retention. |
| Pharmacopeial-Grade Certification Investment | EMA and REACH compliance documentation enabling European pharmaceutical contract manufacturer supply relationships. |
| Backward Integration into Cultivation | Captive root supply from Gansu and Shanxi provinces mitigating single-origin climate risk exposure. |
| Direct-to-Consumer Channel Development | E-commerce platforms and subscription services bypassing traditional bulk ingredient distribution intermediaries. |
| Veterinary Application Formulation Development | Livestock stress-management products accessing lower regulatory barrier segments with emerging demand traction. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with extraction facility operators, dietary supplement contract manufacturing procurement leads, pharmaceutical-grade purification specialists, and SAMR registration consultants. Bottom-up volume modeling triangulated against top-down value estimates derived from NMPA herbal medicine registration databases, US FDA DSHEA NDI notification filings, and EMA quality documentation requirements for botanical extracts.
Granularity-level modeling operated at product type, application, and distribution channel dimensions, with additional segmentation by quality certification tier and processing technology type across the projection horizon. CAGRs were derived from trend extrapolation of procurement volume shifts between spray-dried and low-temperature processed formats, adjusted for SAMR functional food registration expansion scenarios and REACH registration compliance timelines.
The model assumes a particular technology adoption path; alternative pathways for low-temperature vacuum concentration would alter the outlook if spray-drying efficiency improvements close the polysaccharide retention gap. Forecasts reflect assumptions about pharmacopeial harmonization progress and climate stability in Gansu and Shanxi cultivation regions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Cocoa Butter Market
Ingredients
Aroma Ingredients Market
Ingredients
Cottonseed Oil Market
Ingredients
Coconut Oil Based Products Market
Ingredients
Buckwheat Groat Flour Market
Ingredients
Synephrine Market
Ingredients
Europe Potato Protein Market
Ingredients
India Olive Oil Market
Ingredients
Brazil Starch Derivatives Market
Ingredients
Black Seed Oil Market
Ingredients
Europe Phytosterols Market
Ingredients
Sunflower Protein Market
Ingredients
Cooking Coconut Milk Market
Ingredients
Sodium Reduction Ingredients Market
Ingredients
Soy Protein Ingredients Market
Ingredients
Europe Edible Oil Market