
 Europe Edible Oil Market | 2026-2036
Europe Edible Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Edible Oil Market Foresight
Precision blending and enzymatic interesterification is reconfiguring how European refiners achieve tailored lipid profiles for industrial bakery and confectionery clients. Bunge SA leverages its crush and refining footprint across the Netherlands and Germany to secure supply continuity for food manufacturers. AAK AB specializes in cocoa butter equivalents and specialty fats, anchoring its position in chocolate and dairy replacement formulations. Deoleo S.A. dominates Iberian olive oil distribution, extending its brand portfolio across private-label and premium retail channels in Southern Europe.
Europe edible oil comprises refined and unrefined vegetable lipids extracted from oilseeds, fruits, and nuts, with smoke points ranging from 160°C for unrefined flaxseed to 240°C for refined sunflower variants, serving as heat-transfer media, flavor carriers, and nutritional fat sources across food manufacturing and household preparation. Olive oil and sunflower oil command the largest volume shares, though canola oil is gaining traction in Northern European food processing for its favorable omega-3 profile and lower saturated fat content. Pouch and bulk container formats are expanding fastest among packaging types, particularly within food service and private-label retail, where cost efficiency and reduced packaging waste align with EU circular economy directives.
EMA food contact regulations, EFSA novel food assessments, and the EU Deforestation Regulation collectively reshape sourcing requirements, mandating traceability from plantation to refinery and restricting palm oil linked to land-use conversion. REACH compliance adds chemical safety layers to processing aids and refining catalysts, raising capital barriers for smaller operators. Stakeholders must monitor how the EU Deforestation Regulation's full enforcement affects palm and soy supply routes, and whether domestic oilseed expansion in Eastern Europe can offset import dependency for crush capacity.
Market Dynamics
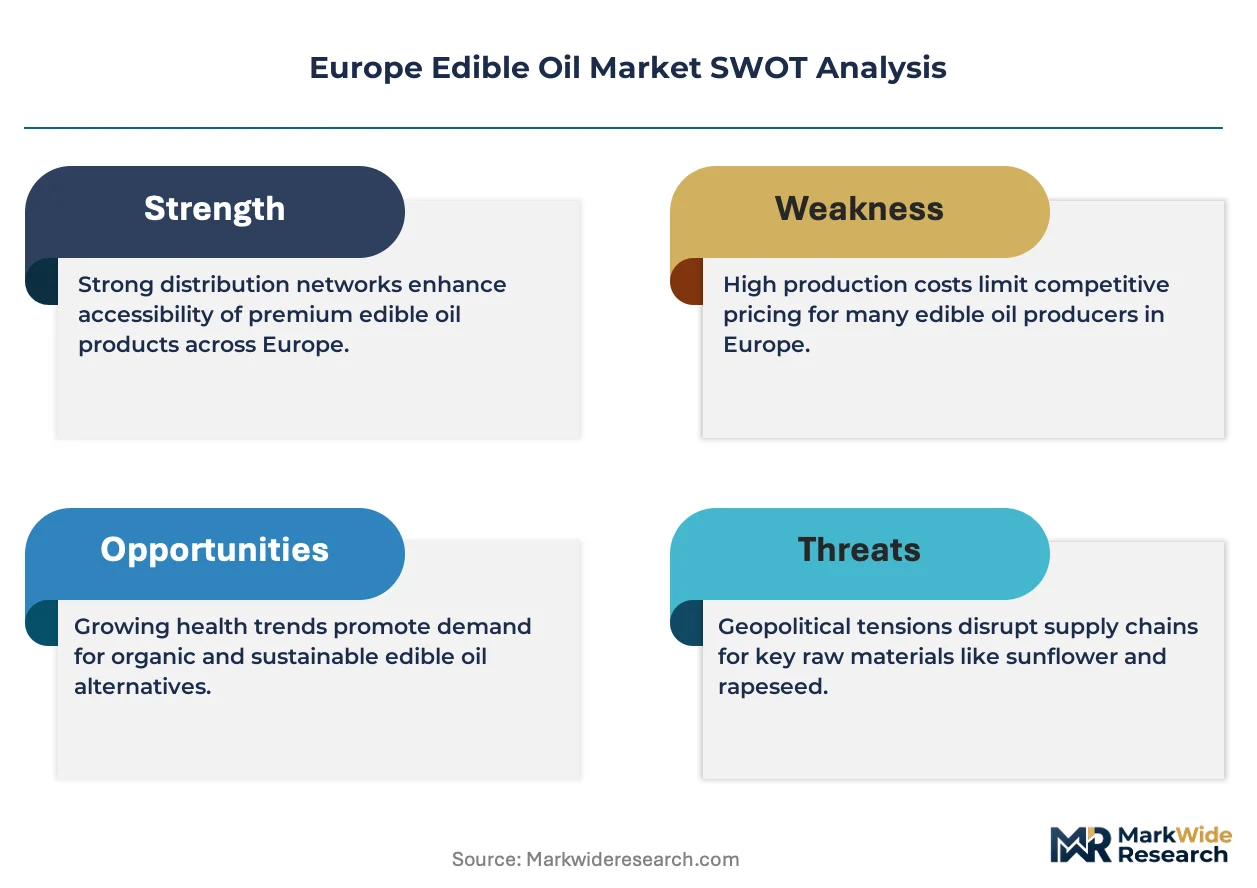
The EU Deforestation Regulation is compressing supply timelines for palm and soy imports while forcing refiners to rebuild traceability infrastructure from plantation to bottling line.
Growth Catalysts
- Clean-label processing:Food manufacturers in Germany and Spain are expanding cold-pressed oil sourcing to meet retailer clean-label requirements. This pulls volume toward unrefined variants with shorter ingredient declarations.
- Farm to Fork Strategy:The EU Green Deal tightens sustainability benchmarks across vegetable oil supply chains. Refiners must document carbon intensity and land-use practices to maintain access to food service contracts.
- High-oleic breeding programs:Sunflower and rapeseed varieties with elevated oleic acid content are displacing partially hydrogenated oils in industrial frying applications. Bakery and snack producers adopt these for extended fry life without trans fat formation.
Market Restraints
- Input cost volatility:Sunflower seed prices swing with Black Sea export disruptions. Crush margins compress when seed costs spike faster than refined oil contract prices can adjust.
- Supply concentration risk:Mediterranean olive oil production clusters in Andalusia and Apulia. Drought in either region triggers price spikes that ripple through private-label and premium retail channels simultaneously.
- Regulatory friction:REACH compliance adds chemical safety documentation layers to processing aids and refining catalysts. Smaller operators face capital barriers to upgrading analytical and reporting infrastructure.
Strategic Opportunities
- Eastern European crush expansion:Romania and Bulgaria offer untapped sunflower seed acreage with lower land costs than Western European alternatives. Investors can build greenfield crush capacity closer to origination.
- Pouch and bulk formats:Food service operators and private-label retailers are shifting from glass bottles to flexible pouches and intermediate bulk containers. This reduces packaging waste and aligns with EU circular economy directives.
- Cocoa butter equivalents:Specialty fat formulations using shea and palm fractions are capturing share in chocolate and dairy replacement applications. AAK AB and similar specialists can extend formulation services beyond commodity supply.
Industry Challenges
- Traceability system integration:Refiners must map supply chains from plantation to refinery under EU Deforestation Regulation requirements. Legacy ERP systems require expensive customization to capture geolocation data and mass balance documentation.
- Enzymatic interesterification scale-up:Commercial adoption of lipase-catalyzed processes for tailored lipid profiles demands capital for bioreactor infrastructure and enzyme stabilization. Technical talent for process optimization remains scarce in Central European refining clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Edible Oil Market |
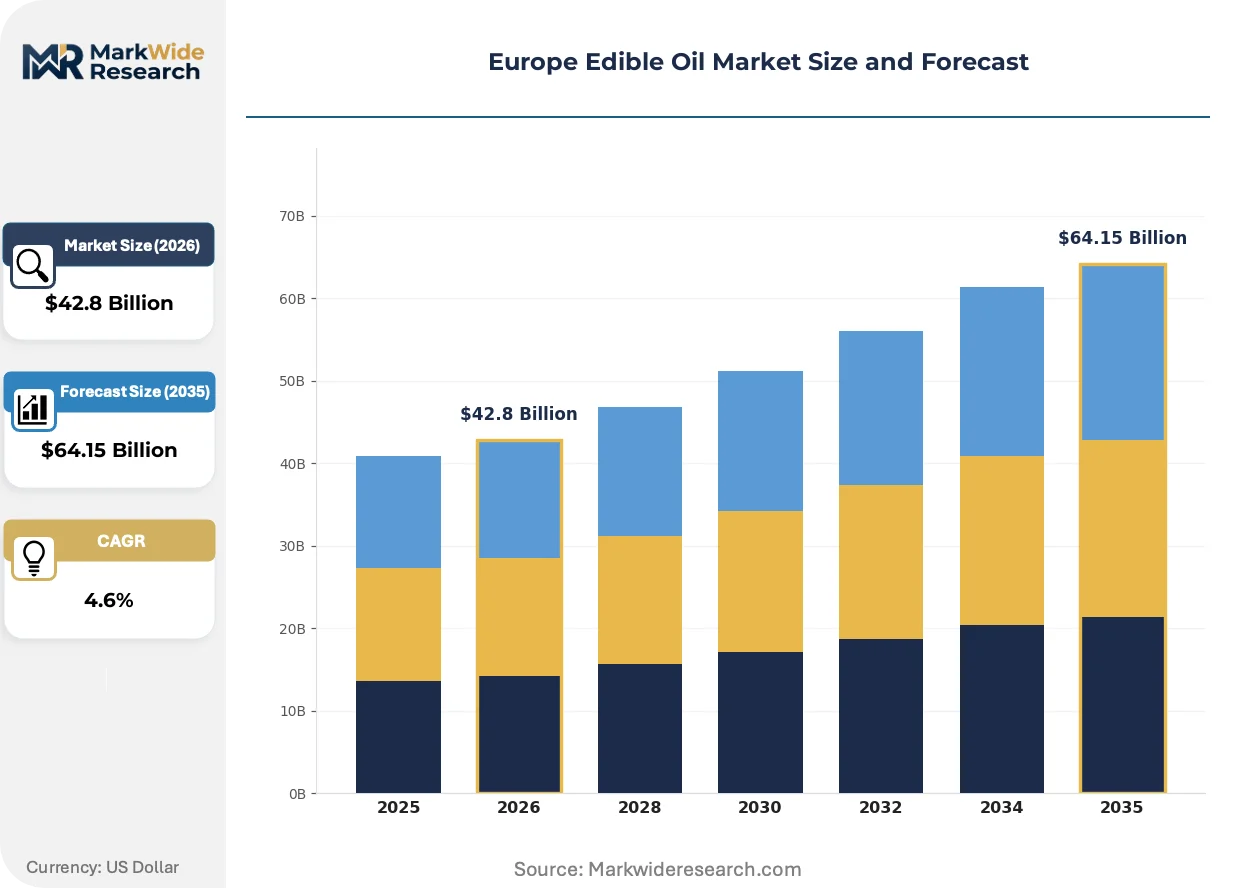
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $64.15 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Olive Oil, Sunflower Oil, Canola Oil, Palm Oil End User: Food Processing, Retail Consumers, Restaurants, Food Service Packaging Type: Bottles, Cans, Pouches, Bulk Containers Distribution Channel: Grocery Stores, Online Retail, Wholesale Distributors, Supermarkets |
| Companies Covered | Henry Lamotte OILS GmbH, Olympic Oils Ltd, Bunge SA, AAK AB, Deoleo S.A., Cargill, Incorporated, Olenex Sàrl, Sovena Group, Borges International Group, SL, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Edible Oil Market Shifts & Advancements
European edible oil processing is converging around precision lipid design, regulatory traceability mandates, and packaging format disruption that together reshape how refiners compete on margin and sustainability credentials.
Enzymatic interesterification is hybridizing traditional chemical interesterification with biological catalysis to produce cocoa butter equivalents and bakery shortenings with precise melting profiles. Industrial chocolate manufacturers in Belgium and Switzerland are piloting these processes at commercial scale. The technology is compressing the gap between commodity bulk fats and premium specialty formulations.
EMA food contact regulations and the EU Deforestation Regulation collectively mandate blockchain-enabled traceability from plantation to refinery. Oilseed crushers must now verify that palm and soy origins exclude land converted after 2020. Southern European olive oil bottlers are responding fastest, deploying QR-code lot tracking to preempt retailer compliance audits.
Food service procurement is consolidating around intermediate bulk containers and bag-in-box formats that reduce handling costs and packaging waste. Contract caterers in France and the Netherlands are displacing traditional 20-liter tins with reusable dispensing systems. This shift concentrates volume with refiners capable of bulk logistics and custom blending at regional distribution hubs.
Europe Edible Oil Market Segmentation
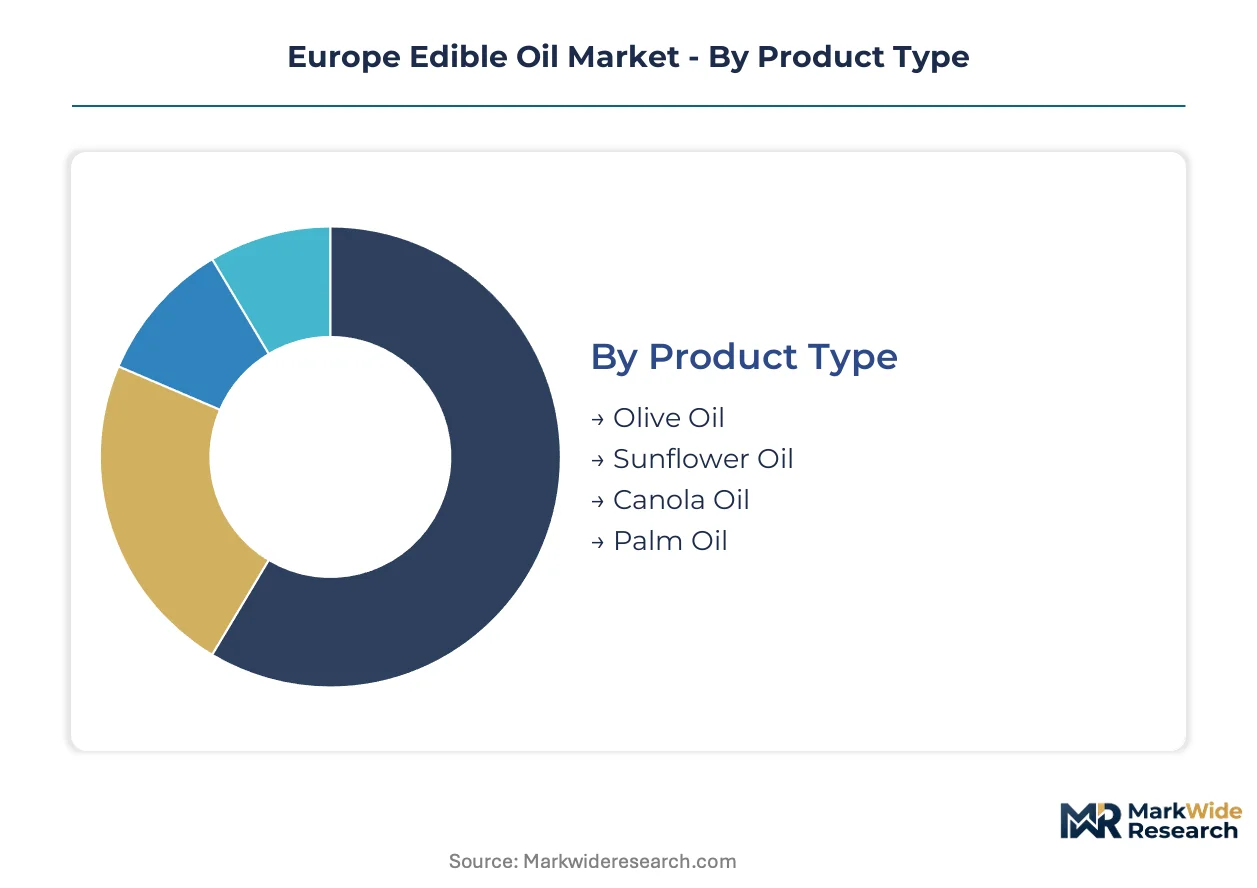
Segmentation in the Europe Edible Oil Market reveals how procurement cycles, packaging economics, and channel preferences fragment demand across distinct buyer profiles. Refiners must configure crush and blending assets to serve food manufacturers with six-month contracts alongside retailers requiring weekly replenishment.
Product Type:
Olive oil commands the longest inventory cycles due to single-harvest annual availability, while sunflower and canola oils turn faster through continuous crush operations.
- Olive Oil:Cold-pressed and extra-virgin grades dominate Mediterranean household consumption with smoke points of 160-190°C. Spanish and Italian bottlers in Andalusia and Apulia face drought-driven supply squeezes that compress margin structures during poor harvest years.
- Sunflower Oil:High-oleic variants with 80%+ oleic acid content displace partially hydrogenated oils in industrial frying across German snack manufacturers. Black Sea export disruptions inject price volatility that refiners hedge through Eastern European origination contracts.
- Canola Oil:Northern European food processors favor its omega-3 profile and sub-7% saturated fat content for clean-label formulations.
- Palm Oil:Fractionated palm olein serves confectionery and bakery applications under tightening EU Deforestation Regulation traceability requirements.
Olive oil anchors the volume base while high-oleic sunflower oil gains share at the steepest rate.
End User:
Food processing operations generate the steadiest demand through annual supply agreements, whereas restaurants and food service operators adjust procurement monthly based on traffic fluctuations.
- Food Processing:Industrial bakeries and confectionery manufacturers in Belgium and Switzerland specify tailored lipid profiles for texture and shelf-life control. Enzymatic interesterification adoption concentrates here as manufacturers seek cocoa butter equivalents without trans fat formation.
- Retail Consumers:Private-label penetration in German and French supermarkets drives volume, with premiumization strongest in Southern Europe where origin-protected olive oils command price premiums.
- Restaurants:Mid-tier dining chains in the Netherlands and France prioritize cost-stable refined oils with neutral flavor profiles for multi-purpose frying.
- Food Service:Contract caterers and institutional kitchens shift toward intermediate bulk containers to reduce handling labor and packaging waste.
Food processing anchors the volume base while food service gains share at the steepest rate.
Packaging Type:
Cost per liter and circular economy compliance separate premium formats from commodity packaging, with refillable systems penetrating food service fastest.
- Bottles:Glass and PET formats dominate retail shelves in Italy and Spain, where transparent packaging signals quality for extra-virgin olive oils. Ecodesign regulations under EU Green Deal directives pressure lightweighting and recycled content thresholds.
- Pouches:Flexible stand-up pouches with dispensing caps expand in French and Dutch food service, cutting packaging weight by 80% versus rigid alternatives.
- Cans:Tinplate and aluminum formats preserve oil quality in export markets with extended shelf-life requirements.
- Bulk Containers:Intermediate bulk containers and flexitanks serve industrial users in Germany with direct-to-factory logistics that bypass retail bottling costs.
Bottles anchor the volume base while pouches climb the fastest.
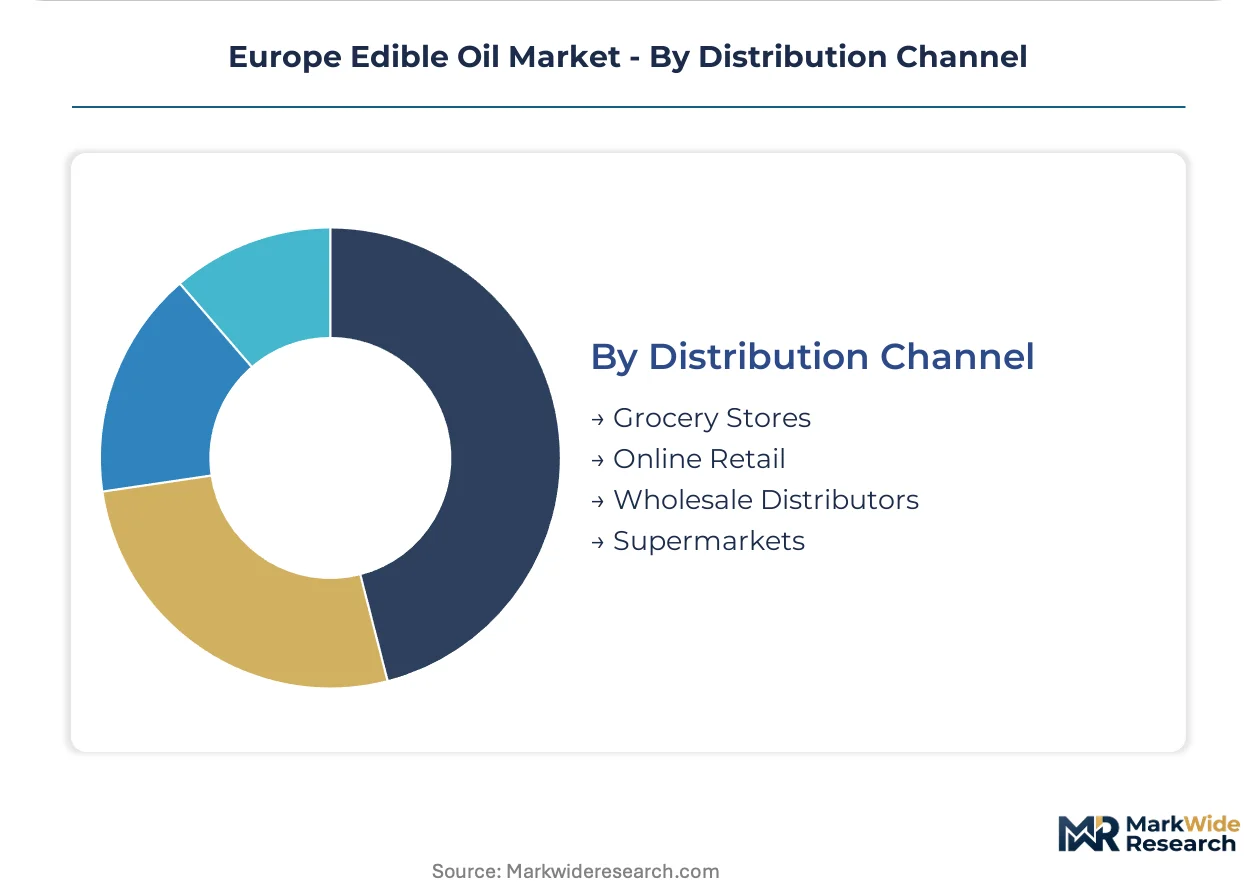
Distribution Channel:
Channel selection determines working capital intensity, with wholesale distributors demanding 60-90 day payment terms versus immediate settlement in online retail.
- Grocery Stores:Neighborhood and convenience formats in Portugal and Greece stock single-origin olive oils with short supply chains from regional mills. Shelf-space competition intensifies as private-label ranges expand.
- Supermarkets:Hypermarket chains in Germany and France consolidate procurement through centralized buying desks that negotiate annual volume contracts with crush facilities.
- Online Retail:Direct-to-consumer platforms gain traction for premium and organic certified oils, bypassing traditional wholesale markups.
- Wholesale Distributors:Specialized food service distributors in Belgium maintain regional blending facilities for custom fat formulations delivered to industrial bakeries.
Supermarkets anchor the volume base while online retail expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's edible oil trade balance tilts toward net imports for palm and soy, while Mediterranean producers dominate olive oil exports to global markets. Germany and the Netherlands function as crush and refining hubs for Northern European distribution. Southern bottlers concentrate on premium origin-protected olive oils.
Germany
Food manufacturers in Bavaria and North Rhine-Westphalia drive demand for high-oleic sunflower and canola oils in clean-label bakery applications. REACH compliance mandates chemical safety documentation for refining catalysts, raising capital barriers for smaller operators. Crush facilities in Hamburg and the Rhine-Ruhr corridor process Eastern European oilseeds for industrial supply chains.
Spain
Andalusian olive oil production anchors Mediterranean supply, with Jaén province supplying over one-third of national volume. The EU Deforestation Regulation forces bottlers to rebuild traceability infrastructure for palm fractions used in confectionery. Cold-pressed oil sourcing expands across Catalonia and Valencia as retailers demand shorter ingredient declarations.
Italy
Apulian and Sicilian olive groves face drought-driven supply squeezes that compress margins during poor harvest years. EFSA novel food assessments govern interesterified fat approvals for industrial chocolate applications. Turin and Milan house formulation specialists serving Swiss and Belgian confectionery manufacturers.
Netherlands
Rotterdam's port crush capacity positions the country as Northern Europe's oilseed processing gateway. EU Green Deal carbon intensity benchmarks pressure refiners to document land-use practices for food service contracts. Bunge SA leverages its Dutch refining footprint to secure supply continuity for German food manufacturers.
France
Brittany and Normandy rapeseed crush operations supply food processors seeking omega-3-rich formulations. EMA food contact regulations tighten packaging material standards for edible oil retail formats. Lyon-based contract caterers pioneer intermediate bulk container adoption to reduce handling labor and packaging waste.
Europe Edible Oil Market Competitive Landscape
On the supply side, the industry is consolidating around integrated crush-refine operators and specialty fat formulators with distinct technical capabilities. Three archetypes dominate: multinational agricultural processors with origination-to-bottling control, Nordic lipid technology specialists, and Iberian olive oil brand aggregators. Competitive moves center on Eastern European crush capacity expansion and enzymatic interesterification licensing.
Among integrated processors, Bunge SA exemplifies the multinational archetype with crush and refining assets spanning the Netherlands and Germany. AAK AB anchors the specialty fat tier, occupying a position in cocoa butter equivalent formulations. Deoleo S.A. represents the Mediterranean brand-aggregator model, sitting within Iberian olive oil distribution networks.
| Leading Market Players |
|---|
| Henry Lamotte OILS GmbH |
| Olympic Oils Ltd |
| Bunge SA |
| AAK AB |
| Deoleo S.A. |
| Cargill, Incorporated |
| Olenex Sàrl |
| Sovena Group |
| Borges International Group, SL |
| Others |
Supply & Pricing Matrix
Black Sea sunflower seed origination concentrates crushing margins in Eastern European supply basins, channeling value toward refiners with integrated origination assets while squeezing toll processors dependent on spot seed markets. German food manufacturers absorb premium pricing for high-oleic variants through annual contract structures that buffer spot volatility.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across Northern European food processing corridors. Three-tier pricing structure across premium, standard, and economy levels separates cold-pressed extra-virgin olive oils from refined commodity sunflower and private-label blends. Cost compression in standard-tier refined oils is intensifying because Black Sea export disruptions feed raw material volatility. Food service operators exhibit highest price sensitivity due to thin operating margins, while premium retail consumers demonstrate lowest sensitivity where origin-protected denominations command brand premiums.
Supply Chain Analysis
Tariff exposure between Southeast Asian palm origins and EU refining hubs dominates supply chain risk calculus under the EU Deforestation Regulation. Geographic supply concentration spans Ukraine and Romania for sunflower seed, Spain and Italy for olive oil, and Indonesia and Malaysia for palm fractions. Raw material dependencies rest on oilseed crush capacity, enzymatic catalyst supply, and specialty fat precursor availability. Single-source vulnerability concentrates in Mediterranean olive oil bottling where drought-driven harvest failures trigger simultaneous price spikes across private-label and premium channels. Distribution runs through Rotterdam port terminals for Northern European industrial supply, with regional blending hubs serving food manufacturers in Belgium and Switzerland.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe edible oil markets sit in early-cycle expansion as enzymatic interesterification adoption penetrates industrial chocolate and bakery applications at commercial scale. Clean-label processing requirements and EU Deforestation Regulation compliance investments accelerate consolidation around integrated operators with traceability infrastructure.
For Market Incumbents: Entrench origination-to-bottling control through Eastern European crush capacity expansion in Romania and Bulgaria. Secure mass balance documentation systems ahead of full EU Deforestation Regulation enforcement to defend food service contract access against specialty fat formulators with advanced traceability platforms.
For New Entrants and Emerging Players: Pursue white-space positioning in enzymatic interesterification licensing and cocoa butter equivalent formulation services for Belgian and Swiss confectionery manufacturers. Food service pouch and intermediate bulk container formats offer the most penetrable segment given incumbent inertia in flexible packaging logistics and custom blending at regional distribution hubs.
For Investors and Strategic Acquirers: Capital is best deployed toward integrated crush-refine operators with Eastern European origination assets and established EU Green Deal carbon intensity documentation systems. Long-term viability over a 5-10 year window favors specialists with enzymatic process capabilities and blockchain-enabled traceability infrastructure. The signal to watch is enforcement timing of EU Deforestation Regulation geolocation verification requirements for palm and soy supply routes.
| Strategic Initiative | Industry Significance |
|---|---|
| Eastern European Crush Expansion | Greenfield capacity in Romania and Bulgaria reduces origination distance for Black Sea sunflower seed supplies. |
| Enzymatic Interesterification Licensing | Bioreactor infrastructure deployment captures premium formulation contracts from Belgian chocolate manufacturers. |
| Blockchain Traceability Integration | Geolocation verification systems secure EU Deforestation Regulation compliance for palm and soy imports. |
| Flexible Packaging Format Shift | Pouch and bag-in-box systems align with EU circular economy directives for French contract caterers. |
| Specialty Fat Formulation Services | Cocoa butter equivalent R&D deepens relationships with Swiss confectionery and dairy replacement producers. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with crush facility managers, food processing procurement leads at German and Belgian manufacturers, olive oil mill operators in Andalusia and Apulia, and specialty fat formulation chemists at Nordic lipid technology firms. Secondary validation drew from EU customs trade databases, EFSA novel food assessment registers, ECHA REACH compliance filings, and industry association reports from Fediol and the International Olive Council. Bottom-up volume modeling triangulated against top-down market sizing across product type, end user, and packaging format segments.
Calibration against historical crush margin data and contract pricing disclosures from integrated processors anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include oil type, processing method, end-use industry, packaging format, and regional regulatory cluster. CAGRs were derived through trend extrapolation of adoption curves for high-oleic varieties and enzymatic processing technologies, cross-referenced with oilseed yield projections and EU policy implementation timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by integrated agricultural processors with upstream origination control would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Milk Mineral Concentrate Market
Ingredients
Cold Water Swelling Starch Market
Ingredients
Tannin Market
Ingredients
Smoked Yeast Market
Ingredients
Tuna and Algae Omega-3 Ingredient Market
Ingredients
Hydroxytyrosol Market
Ingredients
Fruit Powder Market
Ingredients
Specialty Starch Market
Ingredients
China Beer Adjuncts Market
Ingredients
Fig Ingredient Market
Ingredients
Oak Extract Market
Ingredients
Rice Starch Market
Ingredients
United Kingdom Gelatin Market
Ingredients
Specialty Flours Market
Ingredients
Custom Dry Ingredients Blends Market
Ingredients
PDO/PGI-Linked Mediterranean Ingredient Collections Market