
 Industrial Sugar Market | 2026-2036
Industrial Sugar Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Sugar Market Analysis
Premium-grade refined sugar specifications is bifurcating the industrial supply base as buyers enforce tighter color, moisture, and ash parameters for pharmaceutical and confectionery contracts. Südzucker AG leverages its beet-to-refinery integration across Central Europe to sustain consistent ICUMSA ratings. Cargill competes through ocean freight and port terminal control that anchors bulk delivery reliability to Asian beverage manufacturers. Tereos Group differentiates via simultaneous ethanol and crystalline output from French beet campaigns, occupying a dual-revenue position that buffers raw crop volatility.
Industrial sugar denotes sucrose refined to standardized purity levels, typically exceeding 99.85 percent sucrose content with controlled moisture below 0.05 percent and color ratings measured by ICUMSA units for batch consistency in manufacturing processes. It functions primarily as a bulking agent, preservative, and fermentation substrate across food, beverage, and pharmaceutical production lines where precise functional performance outweighs commodity pricing. Granulated sugar retains the dominant volume position in baking and confectionery applications where crystalline structure governs texture and shelf stability. Liquid sugar gains traction in beverage manufacturing and large-scale food processing as it eliminates dissolving steps and enables continuous-flow production economics. Powdered sugar commands premium positioning in pharmaceuticals and specialty confectionery where anti-caking additives and ultrafine particle distribution determine product performance.
The FDA enforces added-sugar disclosure on Nutrition Facts panels, compelling food processors to reformulate or source lower-sucrose alternatives that comply with updated serving-label rules. REACH and the EU Green Deal impose carbon-accounting obligations on European refiners, reshaping sourcing decisions toward verified lower-emission cane and beet supply chains. India's FSSAI mandates quantitative sugar declarations on packaged foods, tightening market access for imported refined products that lack compliant labeling documentation. Stakeholders must monitor how evolving sweetener taxes and carbon-border adjustments restructure procurement geography and product specification requirements across their customer portfolios.
Market Dynamics
Millers across Brazil's Center-South cane belt are recalibrating crush schedules in real time to arbitrage ethanol premiums against crystal sugar export windows, compressing the traditional campaign rhythm and forcing buyers into more volatile procurement cycles.
Growth Catalysts
- Carbon-border accounting:REACH and the EU Green Deal now require verified emission certificates for imported refined sugar, redirecting procurement toward certified low-carbon cane supply chains that command contract premiums.
- Functional beverage expansion:Formulators in Vietnam and Indonesia are scaling liquid sugar dosing systems for carbonated and isotonic drinks, eliminating dissolving stages and cutting batch cycle times.
- Pharmaceutical-grade demand:ICUMSA-45 specifications for parenteral solutions and tablet coatings are tightening purity thresholds, pulling ultrafine crystalline output away from commodity channels.
Market Restraints
- Input cost volatility:Natural gas and electricity tariffs for beet processing swing with European carbon allowance auctions, squeezing margin predictability for seasonal campaigns.
- Supply concentration risk:Crushing capacity clusters in São Paulo state and Mato Grosso do Sul, exposing buyers to weather-driven harvest disruptions and port congestion at Santos.
- Substitution pressure:Allulose and stevia glycoside blends are capturing clean-label reformulation budgets in North American beverage portfolios, displacing sucrose in mid-calorie segments.
Strategic Opportunities
- Underpenetrated African markets:Nigeria and Kenya lack domestic refining infrastructure, creating import substitution openings for toll-processed ICUMSA-100 bulk shipments.
- Regulatory tailwind:India's FSSAI quantitative labeling mandate is accelerating reformulation service contracts, rewarding suppliers with compliant documentation systems.
- Channel innovation:Direct-to-bakery liquid sugar tanker programs are bypassing distributor markups in Mexico's informal panadería sector.
Industry Challenges
- Calibration talent scarcity:ICUMSA colorimetry and polarimetry technicians are in short supply across beet processing facilities, delaying batch release timelines.
- Capex intensity:Vapor-compression evaporator upgrades for energy recovery require 18-24 month payback horizons that strain seasonal cash flows.
- Certification friction:FSSC 22000 and BRCGS Food Safety accreditation timelines stretch 8-14 months, gating access to pharmaceutical and infant nutrition contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Sugar Market |
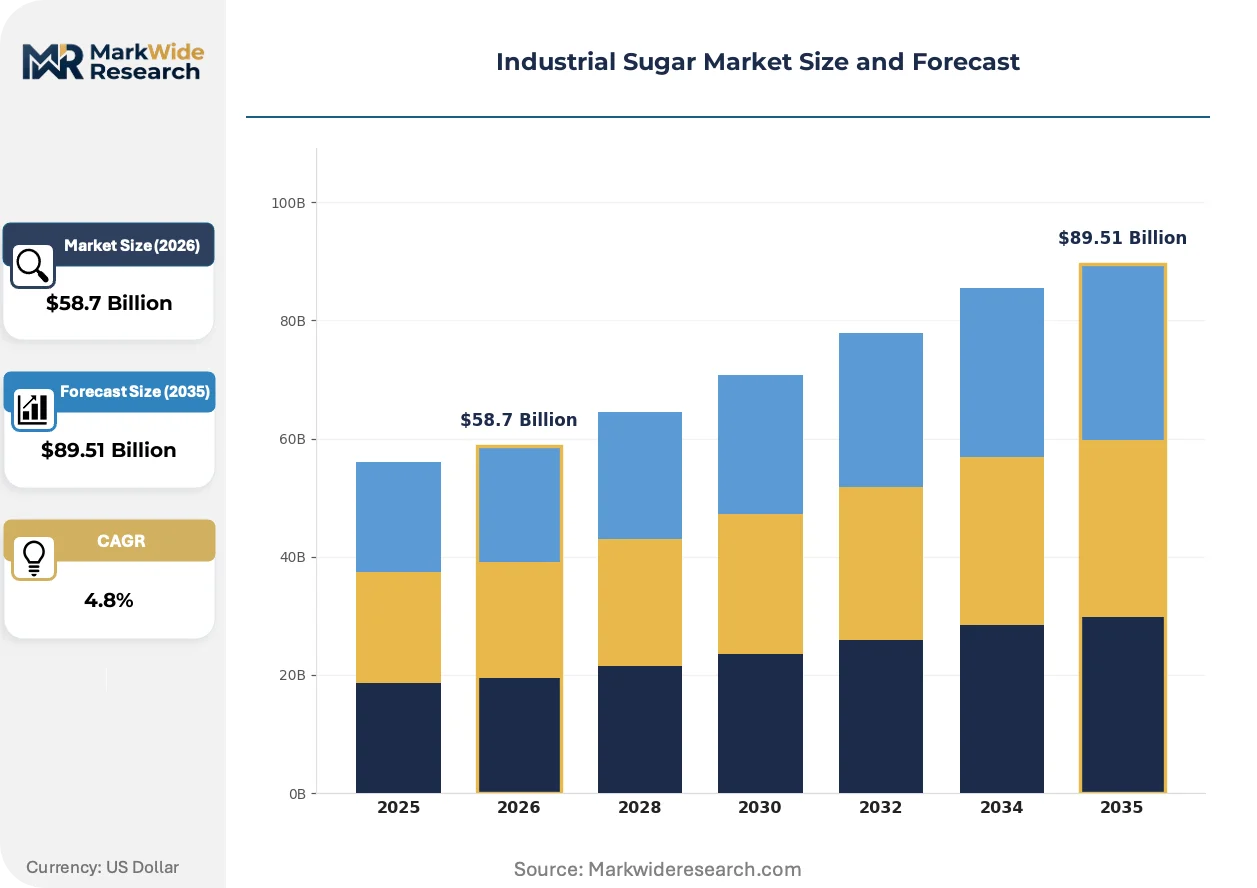
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $89.51 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granulated Sugar, Liquid Sugar, Powdered Sugar, Beet Sugar End User: Food Processing, Beverage Manufacturing, Pharmaceuticals, Confectionery Application: Baking, Preserves, Alcohol Production, Sweeteners Distribution Channel: Direct Sales, Wholesalers, Retailers, Online Sales |
| Companies Covered | Südzucker AG, Cargill, Nordzucker AG, Tate & Lyle, Tereos Group, Mitr Phol Group, Cosan S.A., Associated British Foods, Wilmar International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Sugar Market Emerging Trajectories
Membrane filtration and continuous pan boiling are compressing energy footprints while enabling tighter crystal size distribution, reshaping how refiners compete on specification consistency rather than tonnage throughput alone.
Continuous chromatographic separation is displacing traditional affination and carbonatation stages in beet refineries, stripping molasses impurities without lime or sulfur inputs. Südzucker and Nordzucker have retrofitted French and Polish facilities, cutting water use and waste salt volumes. The technology is displacing legacy refining assets in Central Europe, forcing smaller campaign processors into tolling arrangements or closure.
The FDA's updated Nutrition Facts panel enforcement compels added-sugar disclosure to the gram, pushing food processors toward lower-sucrose recipes or alternative sweetener blends. Compliance costs are diverting R&D budgets from line extensions toward reformulation chemistry. Confectionery and bakery segments in the United States are responding with reduced-sugar SKUs that trade on permissive portion claims rather than traditional taste profiles.
Beverage manufacturers are consolidating liquid sugar procurement through long-term tanker-service contracts that embed technical support and inventory management. This disintermediates traditional bagged-sugar distributors and transfers working capital burdens upstream. The model is most visible in Southeast Asia, where Coca-Cola and PepsiCo bottlers in Thailand and the Philippines have shifted 60-70 percent of sucrose intake to direct refinery relationships with dedicated logistics fleets.
Industrial Sugar Market Segmentation
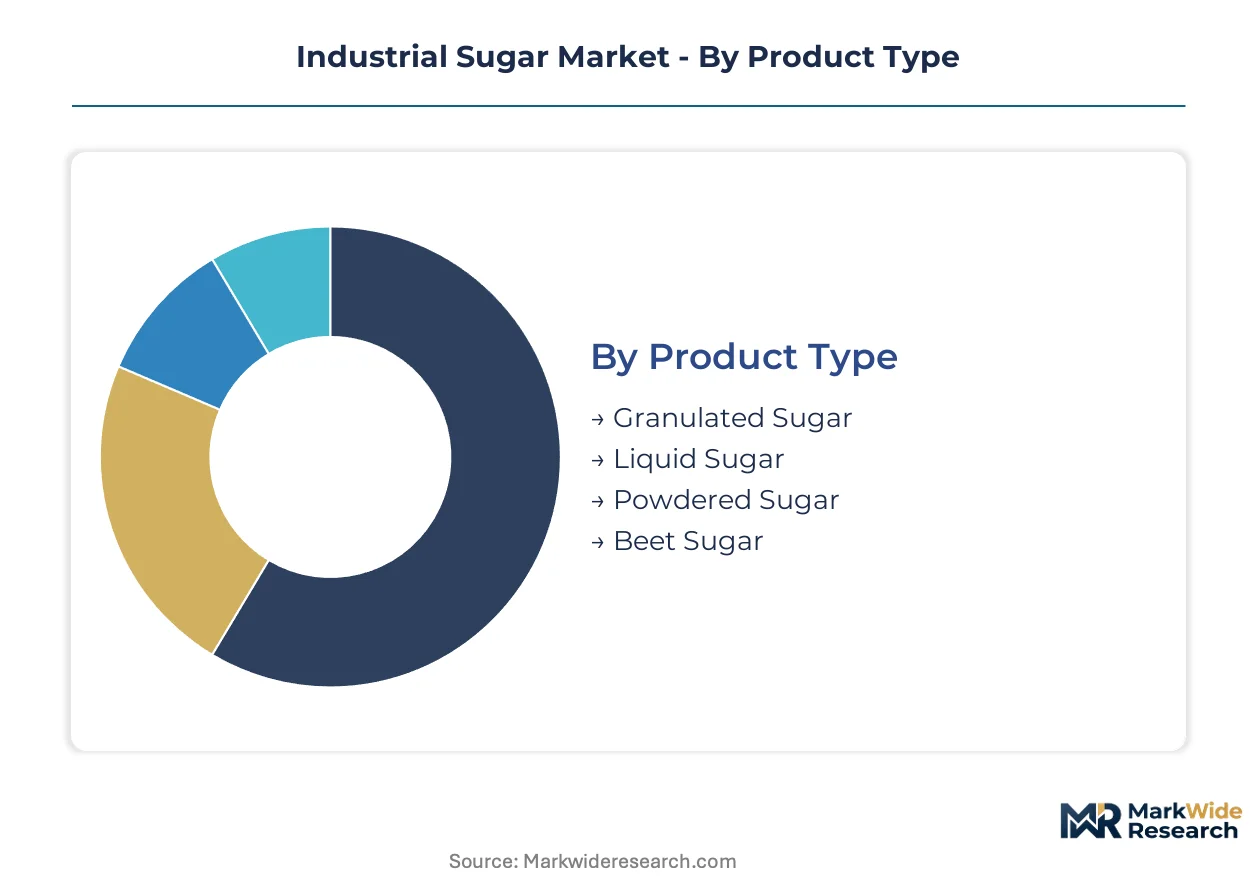
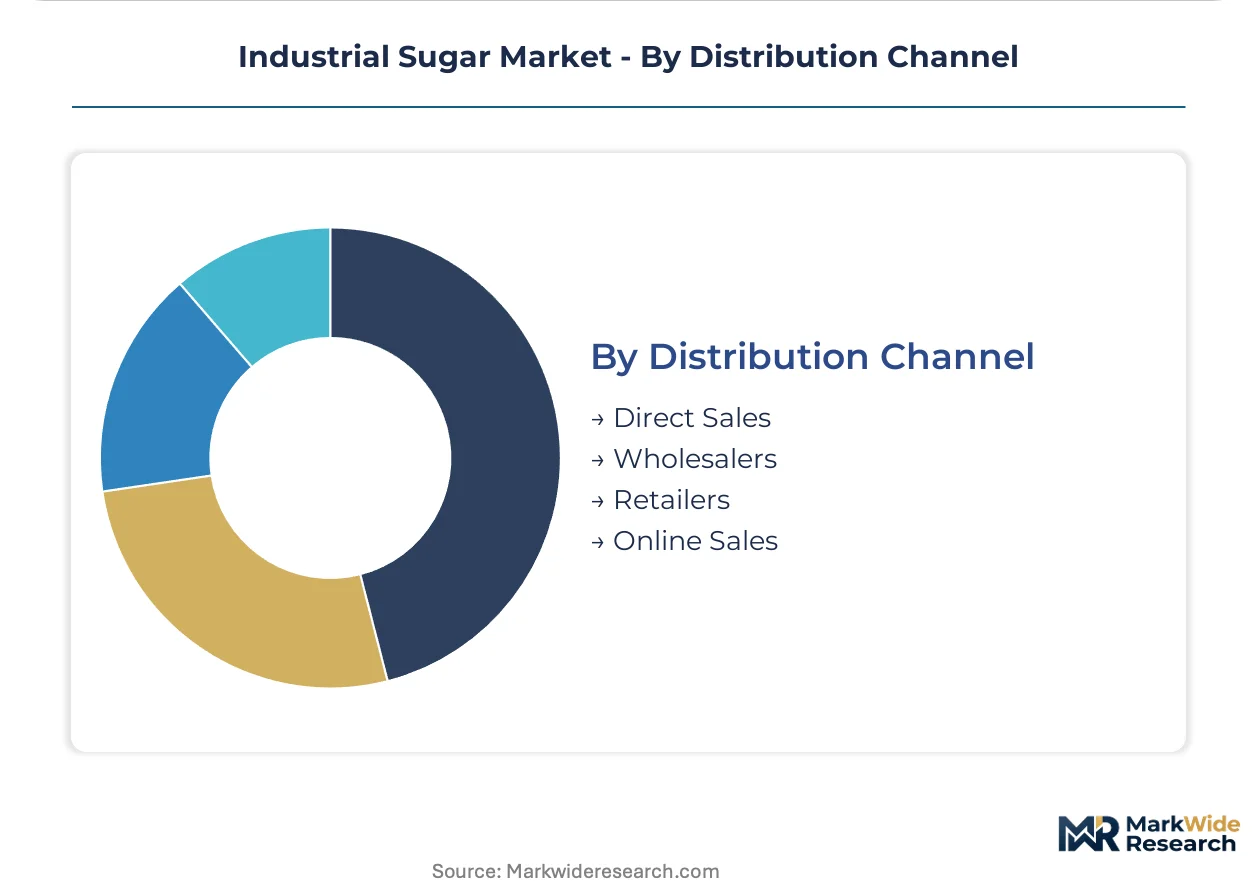
Industrial sugar procurement patterns diverge sharply across product formats and end-use channels. Specification requirements from beverage bottlers, pharmaceutical formulators, and confectionery manufacturers create distinct demand profiles that reshape refinery output allocation and distribution economics.
Product Type:
Liquid sugar flows through direct refinery-to-plant tanker contracts, while crystalline formats navigate layered wholesale networks before reaching manufacturing floors.
- Liquid Sugar:Invert syrup and liquid sucrose solutions eliminate dissolving stages in high-throughput beverage lines. Coca-Cola and PepsiCo bottlers in Thailand and the Philippines have shifted 60-70 percent of intake to dedicated tanker-service programs that embed technical support and inventory management.
- Granulated Sugar:Retains dominant volume position in baking and confectionery applications where crystalline structure governs texture and shelf stability. India's FSSAI labeling mandates are pushing reformulation toward lower-glycemic alternatives, compressing standard-grade volumes in packaged food channels.
- Powdered Sugar:Commands premium positioning in pharmaceuticals and specialty confectionery where anti-caking additives and ultrafine particle distribution determine product performance.
- Beet Sugar:Südzucker and Nordzucker campaign processors in Central Europe leverage beet-to-refinery integration to sustain consistent ICUMSA ratings for pharmaceutical and infant nutrition contracts.
Granulated sugar dominates installed base. Liquid sugar is where expansion concentrates.
End User:
Cost tier stratification separates commodity-scale buyers from specification-sensitive formulators willing to absorb purity premiums.
- Beverage Manufacturing:Carbonated and isotonic drink formulators in Vietnam and Indonesia are scaling liquid sugar dosing systems, cutting batch cycle times through continuous-flow production economics.
- Food Processing:FDA added-sugar disclosure rules compel reformulation toward lower-sucrose recipes or alternative sweetener blends, diverting R&D budgets from line extensions toward compliance chemistry.
- Pharmaceuticals:ICUMSA-45 specifications for parenteral solutions and tablet coatings tighten purity thresholds, pulling ultrafine crystalline output away from commodity channels.
- Confectionery:Reduced-sugar SKUs trade on permissive portion claims rather than traditional taste profiles as clean-label reformulation budgets capture allulose and stevia glycoside blends.
Food processing absorbs the largest tonnage. Pharmaceuticals extract the steepest purity premiums.
Application:
Volume concentration in mature applications contrasts with margin expansion in precision-dependent niches.
- Baking:Mexico's informal panadería sector is bypassing distributor markups through direct-to-bakery liquid sugar tanker programs that compress procurement costs.
- Sweeteners:Allulose and stevia glycoside blends are capturing clean-label reformulation budgets in North American beverage portfolios, displacing sucrose in mid-calorie segments.
- Preserves:Standard-grade granulated sugar retains cost advantage in high-acid, high-sugar shelf-stable products where water activity control dominates formulation.
- Alcohol Production:Brazilian millers recalibrate crush schedules to arbitrage ethanol premiums against crystal sugar export windows, compressing traditional campaign rhythms.
Baking commands raw volume throughput. Sweeteners are climbing the fastest on reformulation tailwinds.
Distribution Channel:
Customer type determines channel depth—multinational bottlers demand direct integration while regional processors tolerate wholesale intermediation.
- Direct Sales:Long-term tanker-service contracts disintermediate traditional bagged-sugar distributors and transfer working capital burdens upstream to refiners.
- Wholesalers:Remain entrenched in fragmented bakery and confectionery segments where order sizes fall below minimum thresholds for dedicated logistics fleets.
- Retailers:Capture residual demand from small-scale food processors and institutional kitchens lacking storage infrastructure for bulk procurement.
- Online Sales:Emerging channel for specialty-grade powdered sugar and pharmaceutical-lot documentation where traceability requirements exceed standard wholesale capabilities.
Direct sales anchor large-account relationships. Online channels are gaining share fastest in documentation-intensive niches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Brazil's Center-South cane belt display the lowest price elasticity as millers arbitrage ethanol premiums, while European pharmaceutical formulators absorb steep purity premiums with minimal volume response. India's beverage sector sits at the midpoint, reformulating under labeling pressure rather than switching suppliers.
Brazil
Cosan S.A. and other Center-South millers recalibrate crush schedules weekly to capture ethanol price spikes, compressing crystal sugar export windows into volatile procurement cycles. ANVISA maintains pharmaceutical-grade sucrose import documentation requirements that favor domestic ICUMSA-45 output. São Paulo state's Santos port corridor anchors bulk sugar logistics, though congestion periodically diverts shipments to Paranaguá.
India
FSSAI quantitative labeling mandates for added sugars are accelerating reformulation service contracts among beverage manufacturers seeking compliant documentation systems. The regulator's 2024 notification tightened disclosure thresholds for packaged foods, pushing processors toward lower-glycemic alternatives. Maharashtra's cooperative sugar mills dominate domestic supply, yet Uttar Pradesh's expanding ethanol-blending program is diverting cane juice from crystal production.
United States
FDA Nutrition Facts panel enforcement compels gram-level added-sugar disclosure, diverting R&D budgets from line extensions toward reformulation chemistry. The regulator's updated serving-size rules disproportionately impact confectionery and bakery segments. Florida's cane refineries and Michigan's beet processors serve distinct regional demand pools, with Gulf Coast facilities capturing Latin American re-export flows.
Germany
REACH carbon-accounting obligations and the EU Green Deal redirect procurement toward verified lower-emission beet supply chains that command contract premiums. Südzucker AG leverages beet-to-refinery integration across Saxony-Anhalt and Lower Saxony to sustain consistent ICUMSA ratings. The country's central European location enables toll-processing arbitrage between French beet campaigns and Polish cane refining.
Thailand
Mitr Phol Group scales liquid sugar dosing systems for Coca-Cola and PepsiCo bottlers, eliminating dissolving stages and cutting batch cycle times. The country's national food and drug administration aligns with ASEAN harmonization protocols for pharmaceutical-grade sucrose documentation. Bangkok's industrial corridor hosts dedicated tanker-service programs that have shifted 60-70 percent of beverage sector sucrose intake to direct refinery relationships.
Industrial Sugar Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with beet-campaign processors commanding specification consistency while cane-belt millers dominate volume throughput. The market structures around three strategic tiers: integrated agricultural-industrial conglomerates with captive feedstock, specialized pharmaceutical-grade refiners with certification depth, and toll processors serving regional beverage bottlers. Consolidation pressure concentrates among Central European beet processors facing carbon-border compliance costs, while fragmentation persists in Asian liquid sugar logistics. Competitive moves center on backward integration into agricultural supply and direct-to-plant tanker-service contracts that disintermediate wholesale distribution.
Among European beet processors, Südzucker AG and Nordzucker AG exemplify the integrated-campaign archetype with beet-to-refinery control sustaining consistent ICUMSA ratings. Tereos Group occupies a dual-revenue position across French beet and Brazilian cane assets, buffering raw crop volatility through simultaneous ethanol and crystalline output. These three represent contrasting geographic diversification strategies within the premium-specification tier.
| Leading Market Players |
|---|
| Südzucker AG |
| Cargill |
| Nordzucker AG |
| Tate & Lyle |
| Tereos Group |
| Mitr Phol Group |
| Cosan S.A. |
| Associated British Foods |
| Wilmar International |
| Others |
Supply Flow & Price Mechanics
Allulose and stevia glycoside substitution in North American beverage portfolios simultaneously redraws procurement geography toward alternative sweetener hubs and compresses sucrose pricing power in mid-calorie segments. Buyers now arbitrage between crystalline sucrose and clean-label alternatives based on gram-level disclosure compliance costs rather than commodity spot dynamics alone.
Pricing Analysis
After-sales technical service contracts for liquid sugar tanker programs capture lifetime value through embedded inventory management and dosing system calibration. Three-tier pricing structure across pharmaceutical-grade ICUMSA-45, standard food-grade, and bulk ethanol-adjacent crystal separates buyers by purity tolerance and documentation burden. Cost compression in standard-grade granulated sugar is intensifying because Brazilian millers prioritize ethanol premiums during crush season. Beverage bottlers exhibit highest price sensitivity due to volume scale and substitution readiness, while pharmaceutical formulators absorb steep premiums with minimal volume response.
Supply Chain Analysis
Inventory cycles compress to weekly recalibration as Brazilian Center-South millers arbitrage ethanol windows against crystal sugar export commitments. Supply concentrates in Brazil, India, and Thailand for cane-derived sucrose, with Germany and France anchoring beet sugar campaigns. Processing draws from natural gas, electricity, and lime inputs whose carbon-border accounting now gates EU market access. Single-source vulnerability clusters in São Paulo state's Santos port corridor, where congestion periodically diverts shipments. Distribution runs through direct refinery-to-plant tanker contracts for beverage majors, while fragmented bakery and confectionery segments tolerate wholesale intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service attach rates for liquid sugar dosing systems and calibration support are expanding faster than commodity crystal tonnage, reframing competitive advantage around operational partnership rather than extraction scale alone.
For Market Incumbents: Fortify backward integration into certified low-carbon cane supply chains ahead of EU carbon-border enforcement. Deepen captive beet processing capacity in Central Europe to sustain ICUMSA consistency for pharmaceutical contracts. Prioritize FSSC 22000 and BRCGS accreditation investments that gate infant nutrition and parenteral solution markets against emerging toll processors. For New Entrants and Emerging Players: FSSC 22000 fast-track programs unlock pharmaceutical-grade positioning without legacy campaign infrastructure. White-space concentrates in Nigeria and Kenya import substitution, where domestic refining gaps create toll-processing openings for ICUMSA-100 bulk shipments. Direct-to-bakery liquid sugar tanker programs in Mexico's informal panadería sector bypass entrenched distributor markups. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors dual-revenue processors with ethanol and crystalline flexibility. Long-term viability hinges on carbon-accounting compliance infrastructure and specification consistency rather than volume throughput alone. Watch for EU carbon-border adjustment mechanism enforcement as inflection indicator for procurement geography restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Low-Carbon Feedstock | REACH and EU Green Deal carbon-accounting obligations redirect procurement toward verified supply chains commanding contract premiums. |
| Liquid Sugar Tanker-Service Program Expansion | Coca-Cola and PepsiCo bottlers in Thailand and the Philippines have shifted 60-70 percent of intake to direct refinery relationships. |
| Pharmaceutical-Grade Certification Investment | FSSC 22000 and BRCGS accreditation timelines stretching 8-14 months gate access to parenteral solution and infant nutrition contracts. |
| Continuous Chromatographic Separation Retrofit | Südzucker and Nordzucker deployments in French and Polish facilities cut water use and waste salt volumes while displacing legacy assets. |
| Reformulation Service Contract Development | India's FSSAI quantitative labeling mandate accelerates compliant documentation system demand among beverage manufacturers. |
Methodological Framework
Initial hypotheses were tested against primary input from sugar mill operations directors, beverage procurement leads, pharmaceutical formulators, and refinery technical managers and refined through secondary validation. Trade data from customs authorities, FSSAI and FDA regulatory filings, EU ETS carbon allowance auction records, and industry association campaign reports anchored quantitative baselines. Bottom-up volume triangulation across product formats and end-use channels converged with top-down value estimates from refinery capacity and utilization disclosures.
Variance decomposition across the projection horizon isolates demand drivers by segment, regulatory shock impacts, and substitution elasticity parameters. Segmentation dimensions modeled include product type granularity, end-user specification tier, application functional requirements, and distribution channel depth. CAGRs were derived from trend extrapolation adjusted for policy inflection points and technology displacement curves. Crush schedule arbitrage behavior in Brazil and carbon-border compliance cost trajectories in Europe fed scenario-specific forecast paths.
Decision-makers should treat outputs as directional under sustained ethanol premium volatility and labeling regulation enforcement; material deviation would warrant model refresh. Forecasts assume continued clean-label substitution pressure and carbon-accounting compliance expansion. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Barley Malt Extract Market
Ingredients
Beetroot Powder Market
Ingredients
North America Fruit and Vegetable Ingredients Market
Ingredients
Sugar Beet Pectin Market
Ingredients
Soy Derivatives Market
Ingredients
Spray-Dried Isolate Market
Ingredients
Soy Hydrolysates Market
Ingredients
Lupine Peptides Market
Ingredients
Australia Sodium Reduction Ingredients Market
Ingredients
Quark Powder Market
Ingredients
Yeast Flakes Market
Ingredients
Encapsulated Salt Market
Ingredients
Tannin Market
Ingredients
North America Plant Protein Ingredients Market
Ingredients
Global Apricot Oil Market
Ingredients
Omega-3 Encapsulation Market