
 United States Whey Protein Ingredients Market | 2026-2036
United States Whey Protein Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
United States Whey Protein Ingredients Market Analytics
NSF Certified for Sport qualification is unwinding competitive access for whey protein suppliers serving collegiate and professional athletic programs. Glanbia PLC leverages its vertically integrated dairy processing network across Idaho and Wisconsin to secure raw whey supply. Hilmar Cheese Company dominates California's Central Valley production corridor with captive milk sourcing and advanced membrane filtration infrastructure. Leprino Foods Company positions its ingredient division to capture share in whey protein isolate grades demanded by premium sports nutrition brands.
Whey protein ingredients comprise the soluble protein fraction separated during cheese manufacture, typically processed through ultrafiltration and spray drying to achieve protein concentrations ranging from 34% to 90% depending on grade. These ingredients function as complete protein sources in formulated foods, delivering all nine essential amino acids with particular abundance in leucine for muscle protein synthesis. Whey protein isolate commands the highest margin pool among product type segments due to its superior purity and lower lactose content, while hydrolyzed whey protein represents the fastest-growing category as brands seek faster absorption claims. Within end user segments, sports nutrition anchors volume demand, though infant nutrition applications require the most stringent safety documentation and command premium pricing structures.
FDA enforcement of Current Good Manufacturing Practice regulations shapes whey protein facility compliance costs, while USDA organic certification creates a parallel supply chain with distinct sourcing and processing requirements. The Federal Trade Commission monitors protein content claims in dietary supplement marketing, influencing label precision and substantiation protocols. Stakeholders must track evolving positions from the Dietary Guidelines Advisory Committee regarding protein quality metrics, as these recommendations cascade into school nutrition procurement standards and influence long-term category demand.
Market Dynamics
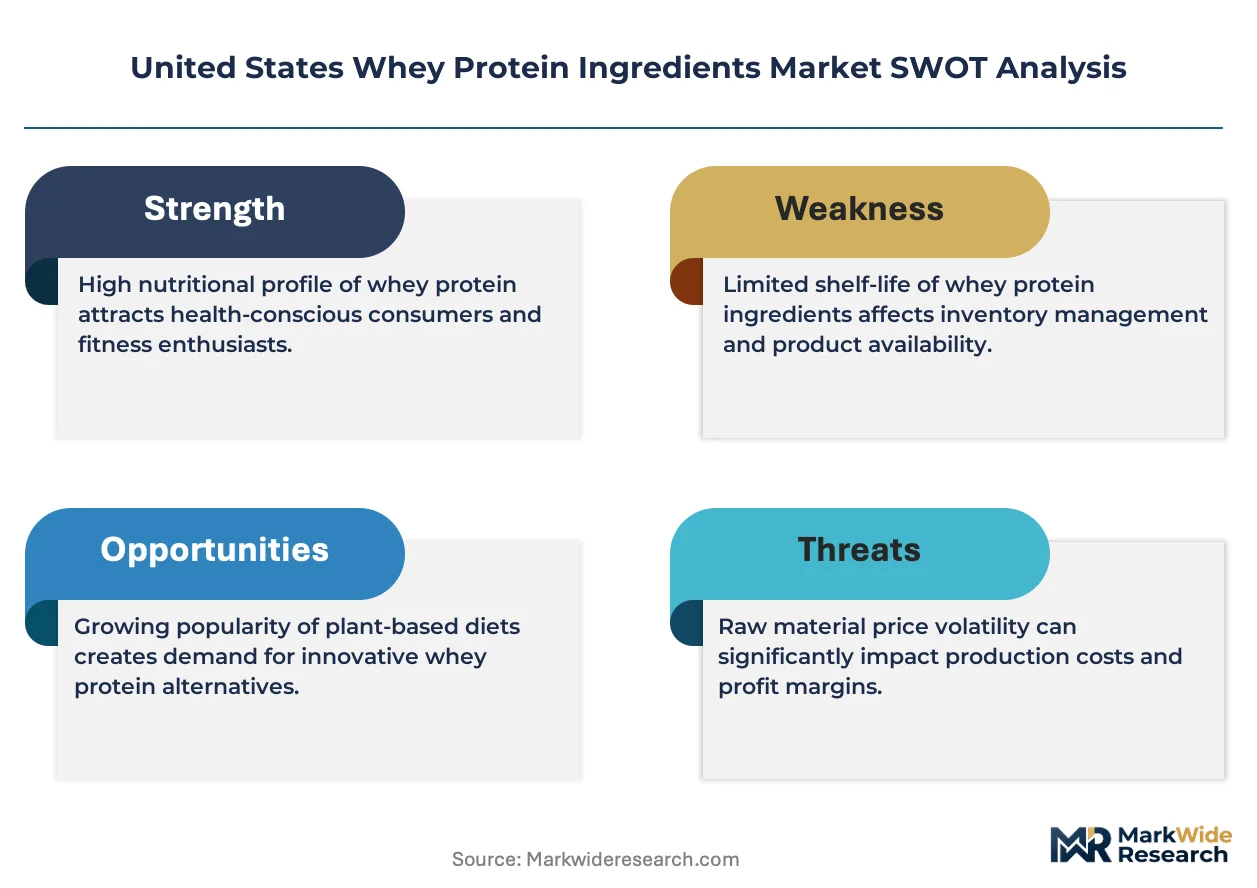
NSF Certified for Sport qualification is compressing supplier access for collegiate and professional athletic programs, creating tiered supply eligibility that favors processors with dedicated third-party audit infrastructure.
Growth Catalysts
- FDA Current Good Manufacturing Practice enforcement:Tighter facility compliance standards are filtering out subscale processors and consolidating volume among qualified suppliers serving sports nutrition brands.
- Texas and California fitness culture convergence:Food manufacturing clusters in these states are co-locating with protein formulation R&D centers, shortening development cycles for ready-to-drink applications.
- Membrane filtration advancement:Advanced ultrafiltration and diafiltration systems are enabling higher protein concentration yields from raw whey, improving isolate grade economics for premium positioning.
Market Restraints
- Captive milk supply concentration:California Central Valley dairy cooperatives control a disproportionate share of fluid milk access, limiting independent processor expansion.
- USDA organic certification parallel chain:Distinct sourcing and processing requirements for organic whey create duplicate infrastructure costs without commensurate volume scale.
- Plant protein substitution:Pea and rice protein isolates are capturing formulation share in mass-market protein bars where complete amino acid profiles are less critical.
Strategic Opportunities
- Infant nutrition safety documentation premium:Stringent microbial and heavy metal testing protocols required for pediatric applications command pricing multiples above sports nutrition grades.
- Hydrolyzed whey protein absorption claims:Pre-digested protein fractions enabling faster amino acid availability are opening positioning space in post-workout recovery segments.
- Dietary Guidelines Advisory Committee protein quality metrics:Evolving federal recommendations on protein quality assessment are cascading into school nutrition procurement standards.
Industry Challenges
- NSF Certified for Sport audit timelines:Third-party sport certification requires 12-18 month facility validation cycles that delay new supplier entry into collegiate athletic programs.
- Cross-functional formulation talent scarcity:Protein ingredient specialists with simultaneous expertise in dairy chemistry, sports nutrition physiology, and beverage emulsion stability command premium compensation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Whey Protein Ingredients Market |
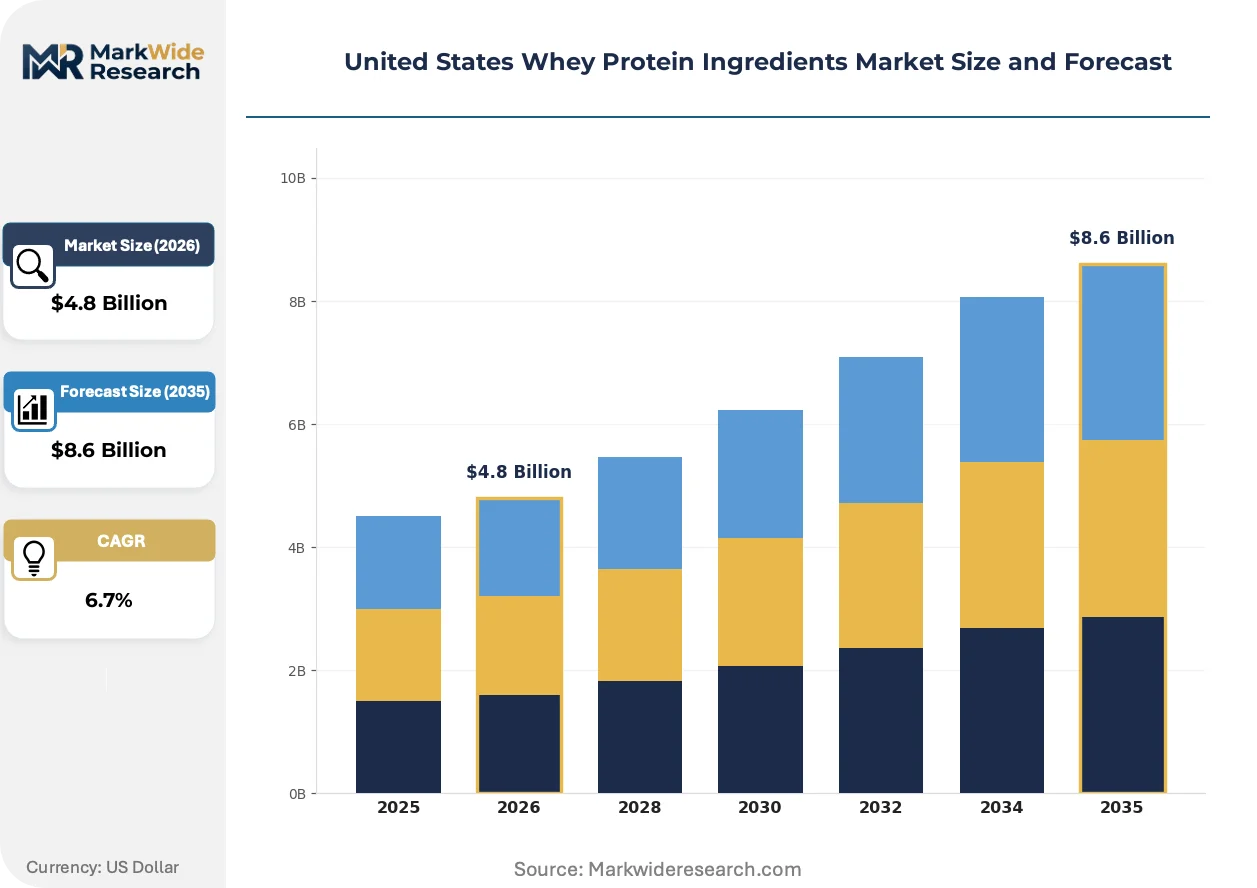
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whey Protein Concentrate, Whey Protein Isolate, Hydrolyzed Whey Protein, Native Whey Protein End User: Sports Nutrition, Dietary Supplements, Food & Beverage, Infant Nutrition Application: Protein Bars, Protein Powders, Ready-to-Drink, Bakery Products Distribution Channel: Online Retail, Health Stores, Supermarkets, Specialty Stores |
| Companies Covered | Glanbia PLC, Fonterra Co-operative Group Limited, Arla Foods amba, Koninklijke FrieslandCampina NV, Groupe Lactalis, Hilmar Cheese Company Inc., Agropur Dairy Cooperative, Leprino Foods Company, Carbery Food Ingredients Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Whey Protein Ingredients Market Evolving Landscape
Processing technology and certification standards are restructuring competitive access tiers, while demand patterns rotate toward faster-absorption formats and pediatric-grade safety documentation.
Microfiltration and ceramic membrane systems are decomposing traditional cheese whey recovery economics by enabling higher protein retention at lower thermal damage. Sports nutrition brands in Texas and California are adopting these systems at pilot scale. The technology is decomposing the historical advantage of large-scale commodity processors by allowing mid-size facilities to achieve isolate-grade purity.
FDA enforcement of Current Good Manufacturing Practice regulations for dietary supplements is elevating facility documentation burdens. Small and mid-size processors face disproportionate compliance cost absorption relative to revenue base. Sports nutrition contract manufacturers in California are consolidating supplier relationships to reduce audit duplication.
Direct-to-consumer subscription models for protein powders are fragmenting traditional distributor relationships that historically controlled shelf placement. Specialty e-commerce platforms are replacing broadline foodservice distribution for premium isolate grades. This pattern concentrates in fitness-dense metropolitan areas where brand discovery occurs through social channels rather than retail.
United States Whey Protein Ingredients Market Segmentation
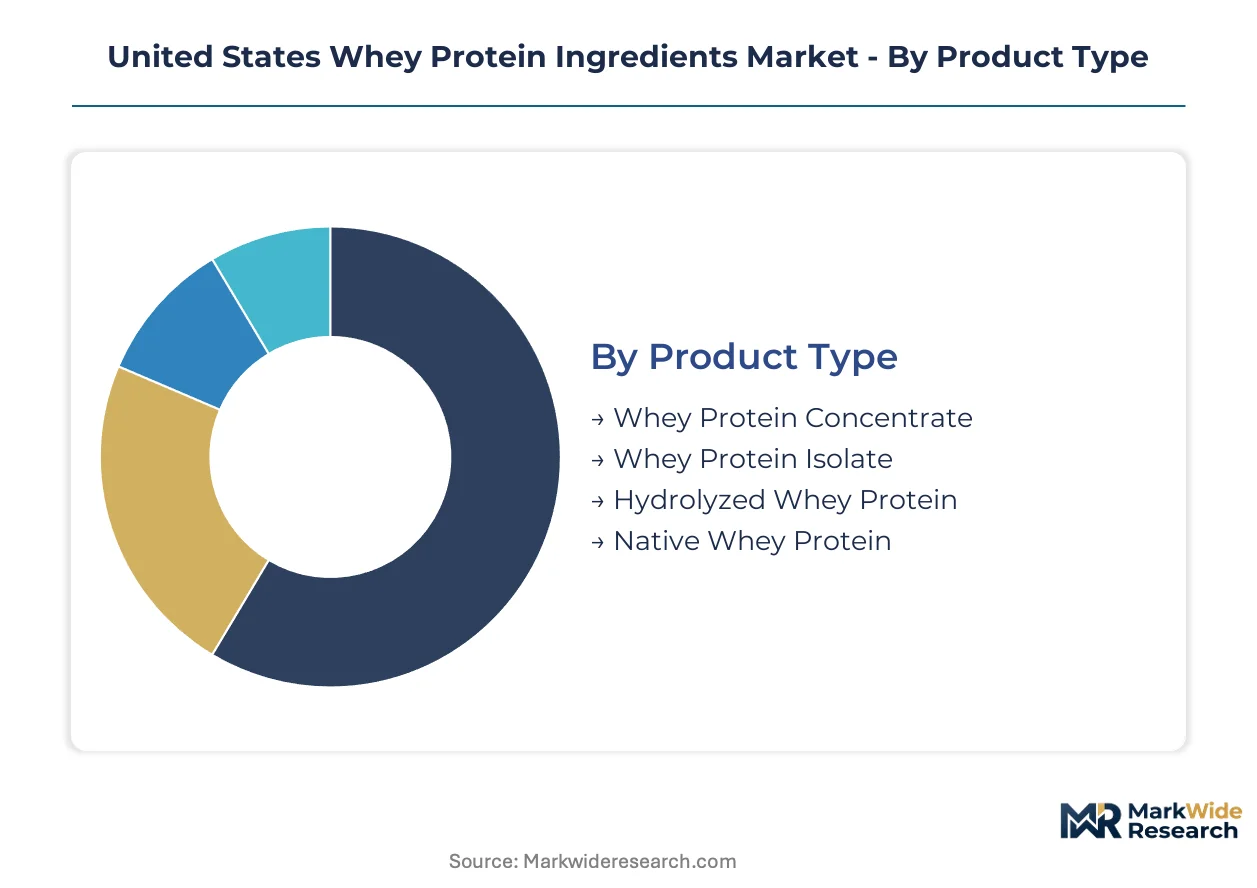
Product purity grades, end-use safety requirements, and absorption speed claims partition the United States whey protein ingredients market into distinct commercial tiers with divergent margin structures. Each segmentation dimension reveals where processors capture premium pricing versus commodity volume.
Product Type:
Margin pools concentrate in higher-purity grades where lactose reduction and leucine density justify price multiples over commodity concentrates.
- Whey Protein Concentrate:Protein content ranges from 34% to 80% with retained lactose and milk fats. Volume demand concentrates in mass-market protein powders and bakery applications where cost efficiency outweighs purity requirements.
- Whey Protein Isolate:Achieves 90%+ protein concentration through additional diafiltration steps that strip nearly all lactose and fat. Premium sports nutrition brands in California and Texas specify isolate grades for low-carb positioning and reduced digestive intolerance claims.
- Hydrolyzed Whey Protein:Enzymatic pre-digestion breaks peptide bonds for faster amino acid absorption. Post-workout recovery formulations drive demand where speed-to-muscle claims differentiate brand positioning.
- Native Whey Protein:Separated from fresh milk rather than cheese whey, preserving undenatured protein structures. Infant nutrition applications in the Northeast demand this grade for its superior digestibility profile and clean-label positioning.
The dominant share belongs to Whey Protein Concentrate, while Hydrolyzed Whey Protein is closing the gap fastest.
End User:
Volume scale and documentation burden diverge sharply across end-use categories, with pediatric applications imposing the steepest compliance costs.
- Sports Nutrition:Protein powders, bars, and ready-to-drink beverages for athletic performance and body composition goals. Demand clusters in fitness-dense metropolitan areas where NSF Certified for Sport qualification gates access to collegiate athletic programs.
- Dietary Supplements:Capsule and tablet formulations targeting general wellness consumers. FTC substantiation requirements for protein content claims shape label precision and marketing compliance costs.
- Food & Beverage:Functional fortification of yogurt, ice cream, and snack bars. Bakery applications in the Midwest leverage whey protein for moisture retention and Maillard browning control.
- Infant Nutrition:Pediatric formula applications requiring exhaustive microbial testing and heavy metal screening. FDA infant formula regulations and USDA organic certification create parallel supply chains with distinct sourcing protocols.
Sports Nutrition commands the largest volume position, though Infant Nutrition extracts the highest per-kilogram pricing.
Application:
Formulation complexity and thermal stability requirements determine which protein grades processors can specify.
- Protein Bars:Textural stability through shelf life demands precise water activity control and protein-hydrocolloid interactions. Texas and California contract manufacturers lead formulation R&D for clean-label binding systems.
- Protein Powders:The foundational application with lowest barrier to entry and highest private-label penetration. Direct-to-consumer subscription models are fragmenting traditional distributor control in fitness-dense urban markets.
- Ready-to-Drink:Beverage emulsion stability and aseptic processing requirements favor suppliers with beverage-specific technical service capabilities. Membrane filtration advancements enable higher protein loads without precipitation.
- Bakery Products:Whey protein replaces egg and gluten in high-protein bread and pastry applications. Thermal denaturation during baking limits functional performance, constraining inclusion rates.
Protein Powders retain the largest share, yet Ready-to-Drink formats are expanding most quickly.
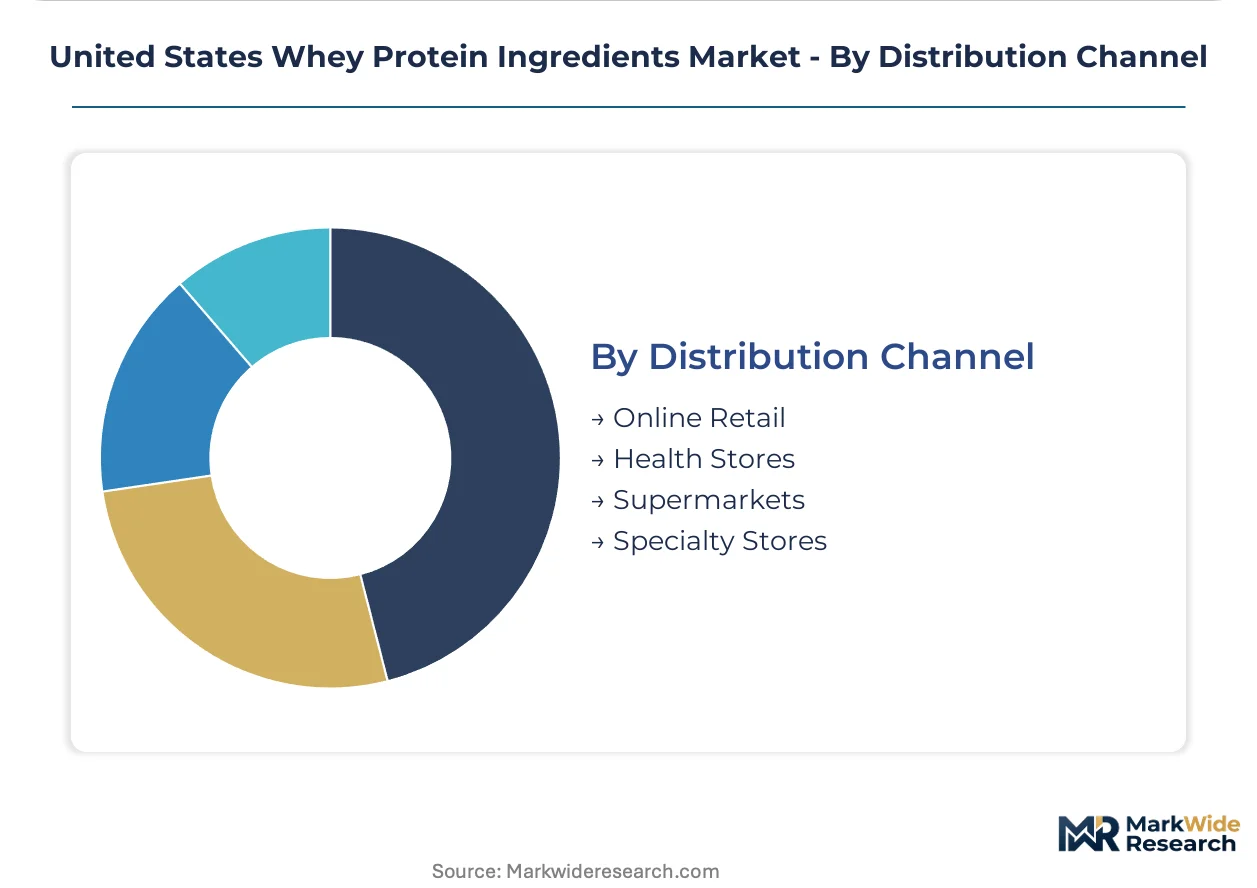
Distribution Channel:
Customer acquisition economics and brand discovery patterns are restructuring traditional wholesale relationships.
- Online Retail:Direct-to-consumer platforms bypass broadline distributors for premium isolate grades. Social media discovery in metropolitan fitness communities replaces retail shelf placement for brand building.
- Health Stores:GNC and Vitamin Shoppe locations provide tactile sampling and staff consultation for first-time buyers. NSF Certified for Sport visibility in these channels signals quality assurance to collegiate athletes.
- Supermarkets:Mass-market whey protein concentrates dominate club store and grocery placements. Price competition and private-label penetration compress margins for branded suppliers.
- Specialty Stores:Independent supplement retailers and CrossFit box pro-shops curate premium hydrolyzed and native whey selections. Personal trainer recommendations drive trial in these high-touch environments.
Online Retail has seized the dominant position, while Specialty Stores are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA enforcement of Current Good Manufacturing Practice regulations and USDA organic certification standards are reshaping facility compliance costs and sourcing requirements across domestic production corridors.
California
Central Valley dairy cooperatives control captive fluid milk access that limits independent processor expansion. FDA infant formula regulations impose exhaustive microbial testing protocols on pediatric-grade whey production. Hilmar Cheese Company anchors the Central Valley corridor with membrane filtration infrastructure serving sports nutrition brands in Los Angeles and San Diego metropolitan markets.
Texas
Fitness culture convergence with food manufacturing clusters is shortening ready-to-drink formulation development cycles. USDA organic certification creates parallel supply chains with distinct sourcing requirements for premium positioning. Dallas-Fort Worth and Austin metropolitan areas concentrate contract manufacturing R&D for clean-label protein bar binding systems.
Idaho
Vertically integrated dairy processing networks secure raw whey supply for isolate-grade production. EPA water discharge permits constrain expansion timelines for membrane filtration facilities. The Magic Valley region hosts processing infrastructure that supplies sports nutrition brands demanding NSF Certified for Sport qualification.
Wisconsin
Dairy cooperative density enables commodity whey concentrate volume production for mass-market applications. FDA dietary supplement labeling requirements shape protein content claim substantiation protocols. The Fox Valley and Madison metropolitan corridors concentrate private-label powder manufacturing for supermarket distribution channels.
New York Metro
Infant nutrition applications command premium pricing structures requiring heavy metal screening documentation. FTC monitoring of protein marketing claims influences label precision for direct-to-consumer subscription brands. Brooklyn and Queens warehouse districts anchor specialty e-commerce fulfillment for premium isolate grades targeting fitness-dense urban consumers.
United States Whey Protein Ingredients Market Competitive Landscape
Player mix skews toward integrated dairy processors with captive milk supply and dedicated third-party audit infrastructure. Tiered supply eligibility is compressing competitive access for collegiate athletic programs. Strategic archetypes include vertically integrated cheese manufacturers, cooperative-owned processing networks, and ingredient-specialist divisions of diversified food conglomerates. Dominant competitive moves center on membrane filtration capacity expansion and NSF sport certification acquisition.
Within the integrated processor tier, Glanbia PLC, Hilmar Cheese Company, and Leprino Foods Company exemplify archetypes defined by geographic concentration and certification positioning. Glanbia represents the multinational ingredient-specialist model with domestic processing infrastructure. Hilmar Cheese Company anchors the captive supply archetype through Central Valley dairy integration. Leprino Foods Company occupies a position bridging commodity cheese production and premium isolate-grade ingredient supply.
| Leading Market Players |
|---|
| Glanbia PLC |
| Fonterra Co-operative Group Limited |
| Arla Foods amba |
| Koninklijke FrieslandCampina NV |
| Groupe Lactalis |
| Hilmar Cheese Company Inc. |
| Agropur Dairy Cooperative |
| Leprino Foods Company |
| Carbery Food Ingredients Limited |
| Others |
Value Network & Pricing Analysis
Membrane filtration capacity utilization above eighty percent in California and Idaho processing corridors is compressing marginal production economics and elevating price floors for isolate-grade whey. This scale concentration grants captive-supply processors pricing power over independent brands while forcing commodity concentrate producers into volume-driven contract structures.
Pricing Analysis
Certification level creates the primary spread across whey protein tiers, with NSF Certified for Sport and USDA organic qualifications commanding thirty to fifty percent premiums over conventional grades. Three-tier pricing structure separates premium isolate from standard concentrate from economy-grade whey permeate, with hydrolyzed variants occupying a fast-growing mid-premium position. Cost compression in commodity concentrates is intensifying because private-label supermarket penetration erodes branded pricing power. Mass-market protein powder buyers exhibit highest price sensitivity, while infant nutrition formulators demonstrate lowest sensitivity due to documentation requirements.
Supply Chain Analysis
Inbound logistics costs from New Zealand and Irish dairy cooperatives through West Coast ports face chronic container availability constraints that inflate landed costs for imported whey fractions. Domestic supply concentrates in California, Idaho, and Wisconsin, with raw milk access controlled by Central Valley and Magic Valley dairy cooperatives. Processing infrastructure draws from ceramic membrane systems, spray drying towers, and aseptic packaging lines that represent billion-dollar sunk investments. Single-source vulnerability runs through California Central Valley fluid milk contracts that lock independent processors out of expansion. Distribution runs through specialty ingredient distributors, direct-to-consumer fulfillment centers, and broadline foodservice networks serving contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment story where FDA Current Good Manufacturing Practice compliance and NSF sport certification create switching costs that defend incumbent positions. Network effects concentrate in co-located R&D corridors where formulation expertise and processing infrastructure reinforce mutual dependence.
For Market Incumbents: Fortify membrane filtration capacity in Idaho and Texas corridors to capture ready-to-drink formulation demand before mid-scale competitors achieve isolate-grade yields. Deepen backward integration into captive milk supply through cooperative equity stakes that preempt independent processor expansion. Prioritize NSF Certified for Sport audit infrastructure investment to maintain tiered supply eligibility for collegiate athletic programs against emerging contract manufacturers.
For New Entrants and Emerging Players: Organic certification fast-track programs offer the most penetrable entry vector, as USDA parallel supply chains operate with less incumbent congestion than conventional whey corridors. Target hydrolyzed whey protein segments where enzymatic pre-digestion capabilities remain scarce among mid-tier processors. Pursue direct-to-consumer subscription models that bypass distributor gatekeeping in fitness-dense metropolitan markets.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among processors with infant nutrition safety documentation that locks formula manufacturers into multi-year supply agreements. Long-term viability across the analysis window favors vertically integrated dairy processors with captive raw whey access and established third-party audit infrastructure. Acquisition target archetype includes mid-scale membrane filtration facilities in underutilized dairy regions. Signal to monitor: FDA enforcement intensity shifts that accelerate subscale processor exit.
| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Capacity Expansion | Advanced ultrafiltration systems in Idaho enable isolate-grade purity that commands premium positioning in Texas sports nutrition corridors. |
| NSF Certified for Sport Acquisition | Third-party sport certification gates access to collegiate athletic procurement programs with twelve-to-eighteen month validation timelines. |
| Organic Certification Parallel Chain | USDA organic whey infrastructure captures premium positioning in clean-label infant nutrition applications with distinct sourcing protocols. |
| Direct-to-Consumer Channel Buildout | Subscription models fragment traditional distributor control in fitness-dense metropolitan markets where social discovery replaces retail placement. |
| Hydrolyzed Whey Protein R&D Investment | Enzymatic pre-digestion capabilities open post-workout recovery segments where absorption speed claims differentiate brand positioning. |
Research Methodology
Initial hypotheses were tested against primary input from sports nutrition brand formulators, dairy processing plant managers, infant nutrition regulatory affairs leads, and specialty ingredient distribution executives and refined through secondary validation. USDA organic certification databases, FDA dietary supplement inspection records, NSF Certified for Sport facility listings, and dairy cooperative production disclosures anchored quantitative triangulation. Bottom-up volume estimates from processor capacity utilization and top-down demand segmentation from end-use procurement patterns were reconciled to produce integrated market sizing.
Variance decomposition across product purity grades, end-use safety requirements, and absorption speed claims structured the analytical framework throughout the projection horizon. Modeled dimensions spanned whey protein concentrate, isolate, hydrolyzed, and native grades; sports nutrition, dietary supplement, food and beverage, and infant nutrition end users; protein powders, bars, ready-to-drink, and bakery applications; plus online retail, health stores, supermarkets, and specialty store channels. CAGRs were derived from segment-level growth rate distributions weighted by base-year revenue contributions. Forecast inputs incorporated membrane filtration yield improvements and FDA enforcement intensity scenarios.
Decision-makers should treat outputs as directional under assumptions of sustained fitness culture expansion in California and Texas and stable dairy cooperative supply structures; material deviation would warrant model refresh. Specific risk factors include plant protein substitution acceleration, captive milk supply consolidation, and regulatory enforcement volatility. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Shortening Powder Market
Ingredients
Cosmetic Ingredients Market
Ingredients
Wheat Protein Concentrates Market
Ingredients
Yeast Peptide Market
Ingredients
Ahiflower Oil Market
Ingredients
Waxy Maize Starch Market
Ingredients
Smoked Yeast Market
Ingredients
Cocoa Maker Market
Ingredients
Blackcurrant Concentrate Market
Ingredients
Cultured Non-Fat Dairy Ingredients Market
Ingredients
Bouillon Cubes Market
Ingredients
Rendered Products Market
Ingredients
Global Bioactive Ingredients Market
Ingredients
Global Natural Gum Market
Ingredients
Injection Grade Soybean Oil Market
Ingredients
Ground-Nut Oil Market