
 Europe Ostomy Care and Accessories Market | 2026-2036
Europe Ostomy Care and Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Ostomy Care and Accessories Market Analytics
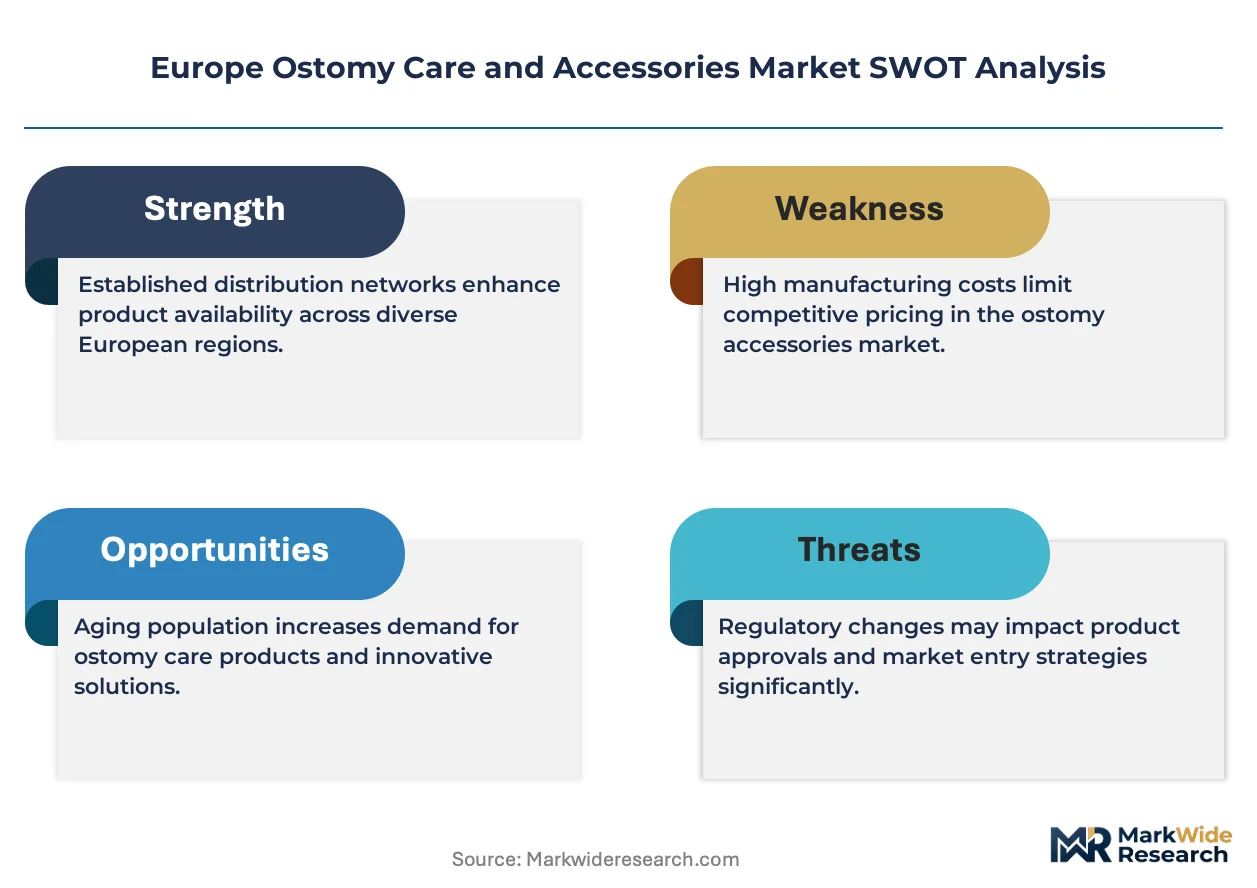
The capital-intensity divergence between integrated manufacturers and component suppliers is unwinding competitive stability in ostomy care. Coloplast Corp. leverages its polymer research infrastructure to control high-barrier film production in-house. ConvaTec Group Plc anchors its position through sustained investment in hydrocolloid adhesive platforms. Hollister Incorporated competes via geographic dominance across Nordic hospital systems.
Europe ostomy care and accessories encompass drainable and closed pouch systems, skin barriers with pH-buffering layers, and irrigation sets designed for stoma management after colectomy, ileostomy, or urostomy procedures. These products employ multilayer odor-barrier films—typically ethylene vinyl alcohol coextrusions—to prevent gas permeation while maintaining wear times exceeding three days. Ostomy bags command the largest revenue pool due to recurring replacement cycles, while skin barriers capture premium margins from patients with peristomal complications. Home care end users represent the fastest-growing channel as discharge protocols shift toward outpatient stoma management across EU health systems.
EMA oversight through the Medical Device Regulation framework and CE marking requirements under EU MDR govern biocompatibility testing and clinical evidence standards for ostomy appliances. France's ANSM and Germany's BfArM enforce additional post-market surveillance obligations that elevate compliance costs for non-EU entrants. Stakeholders must monitor reimbursement harmonization debates under the EU Health Technology Assessment framework to anticipate margin pressure from centralized procurement pilots.
Market Dynamics
The EU MDR framework is compressing certification timelines for ostomy appliances while simultaneously elevating clinical evidence thresholds, forcing manufacturers to restructure regulatory affairs teams and accelerate biocompatibility testing investments.
Growth Catalysts
- Home care discharge protocols:France's hospital-at-home programs and Germany's ambulatory surgery incentives are routing post-operative stoma patients directly to outpatient management, expanding the addressable user base for drainable pouch systems.
- EU MDR harmonization:Centralized CE marking pathways under the Medical Device Regulation framework reduce redundant national approvals, enabling faster cross-border distribution for hydrocolloid adhesive platforms.
- Polymer film innovation:Ethylene vinyl alcohol coextrusion advances are extending wear times beyond 72 hours, reducing replacement frequency and improving patient compliance across Nordic home care settings.
Market Restraints
- Ethylene vinyl alcohol feedstock concentration:Specialty polymer supply concentrates among three European petrochemical producers, exposing ostomy film manufacturers to input cost volatility and allocation risk.
- BfArM post-market surveillance:Germany's enhanced vigilance reporting requirements for Class IIa medical devices extend compliance timelines and elevate documentation burdens for non-EU market entrants.
- Skin barrier substitution:Generic hydrocolloid formulations from Eastern European contract manufacturers capture price-sensitive volume in public hospital tenders, compressing branded margin pools.
Strategic Opportunities
- Spain's underpenetrated home care infrastructure:Regional health system decentralization creates whitespace for direct-to-patient distribution models bypassing traditional hospital discharge channels.
- Digital stoma monitoring convergence:Integration of pH-sensing wearables with irrigation scheduling applications enables remote peristomal complication detection, opening subscription revenue streams.
- EU Health Technology Assessment alignment:Cross-border reimbursement pilot programs under centralized procurement frameworks favor manufacturers with health-economic evidence packages, rewarding early HTA investment.
Industry Challenges
- Polymer research talent scarcity:Specialized formulation chemists with multilayer film coextrusion expertise command premium compensation, constraining R&D expansion at mid-tier manufacturers.
- MDR technical documentation timelines:Clinical evaluation report preparation for novel skin barrier adhesives extends 18-24 months, delaying product launches beyond competitive windows.
- Legacy hospital procurement integration:ERP system compatibility with centralized EU purchasing platforms requires substantial middleware investment, disproportionately burdening smaller ostomy suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Ostomy Care and Accessories Market |
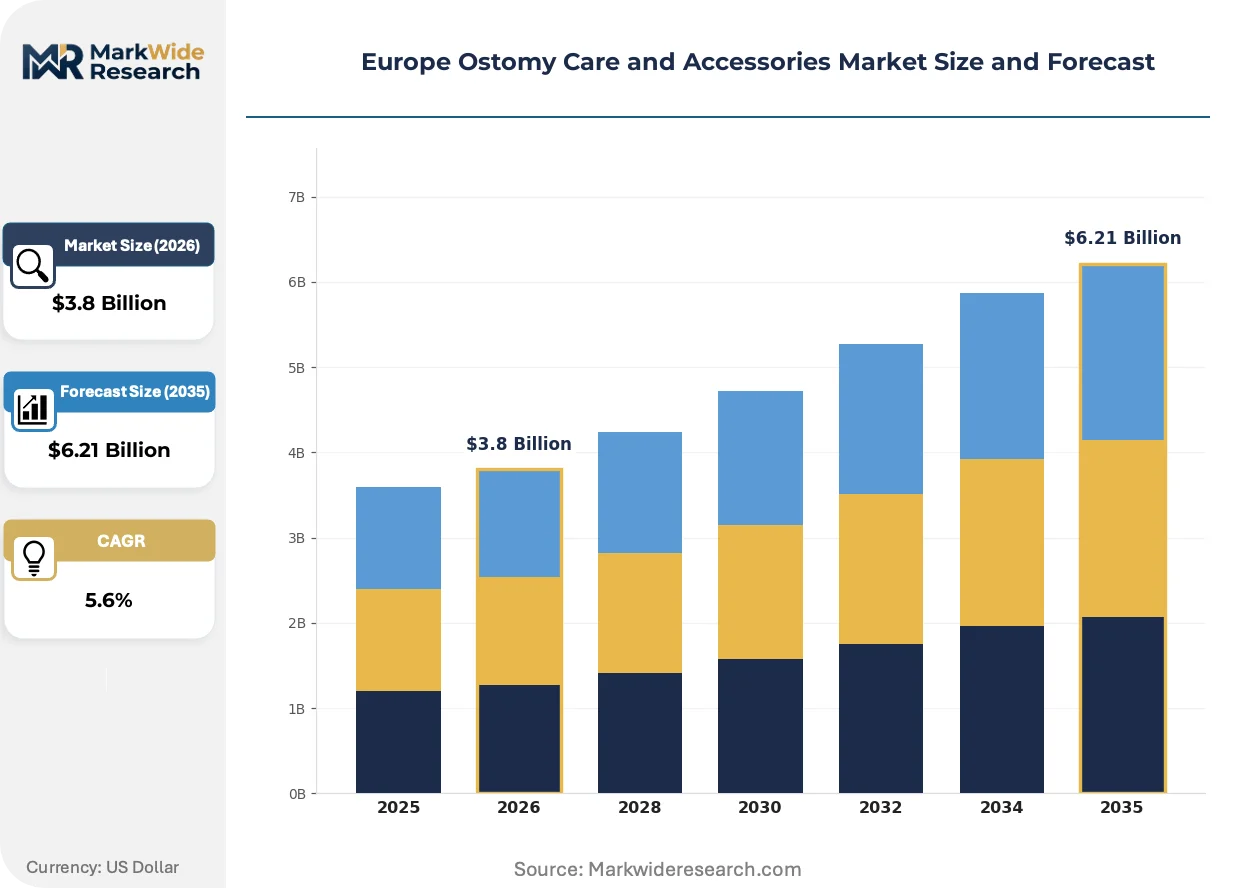
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ostomy Bags, Skin Barriers, Accessories, Adhesives Application: Colostomy, Ileostomy, Urostomy, Palliative Care End User: Hospitals, Home Care, Nursing Facilities, Clinics Distribution Channel: Online Retail, Pharmacies, Medical Supply Stores, Distributors |
| Companies Covered | Coloplast Corp., ConvaTec Group Plc, Hollister Incorporated, Salts Healthcare, B. Braun Melsungen AG, Welland Medical Limited, Marlen Manufacturing & Development Company, ALCARE Co., Ltd., Flexicare (Group) Limited, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Ostomy Care and Accessories Market Evolving Landscape
Active material science breakthroughs and regulatory digitization are compressing product development cycles while reshaping how stoma care products reach end users across European health systems.
Multilayer odor-barrier films incorporating nano-scale ethylene vinyl alcohol distributions are miniaturizing gas permeation pathways without sacrificing mechanical flexibility. German home care providers are adopting these platforms for high-activity patients requiring extended wear durability. The technology is miniaturizing the performance gap between premium and standard pouch tiers, eroding historical price stratification.
France's ANSM has implemented real-world evidence requirements for post-market surveillance of ostomy appliances under MDR Article 74, mandating systematic patient-reported outcome collection. Manufacturers must now integrate registry participation into commercial operations, elevating data infrastructure costs. Drainable pouch systems with novel closure mechanisms face the steepest documentation burdens as regulators scrutinize leakage-related adverse events.
Hospital procurement teams across the United Kingdom are consolidating stoma care purchasing through NHS Supply Chain framework agreements, compressing supplier rosters from twelve to four in several regions. Independent home care distributors are acquiring direct contracts with ostomy associations to bypass centralized tender processes. The behavioral shift is most pronounced in England's Integrated Care Systems, where patient choice policies create tension between volume aggregation and brand retention.
Europe Ostomy Care and Accessories Market Segmentation
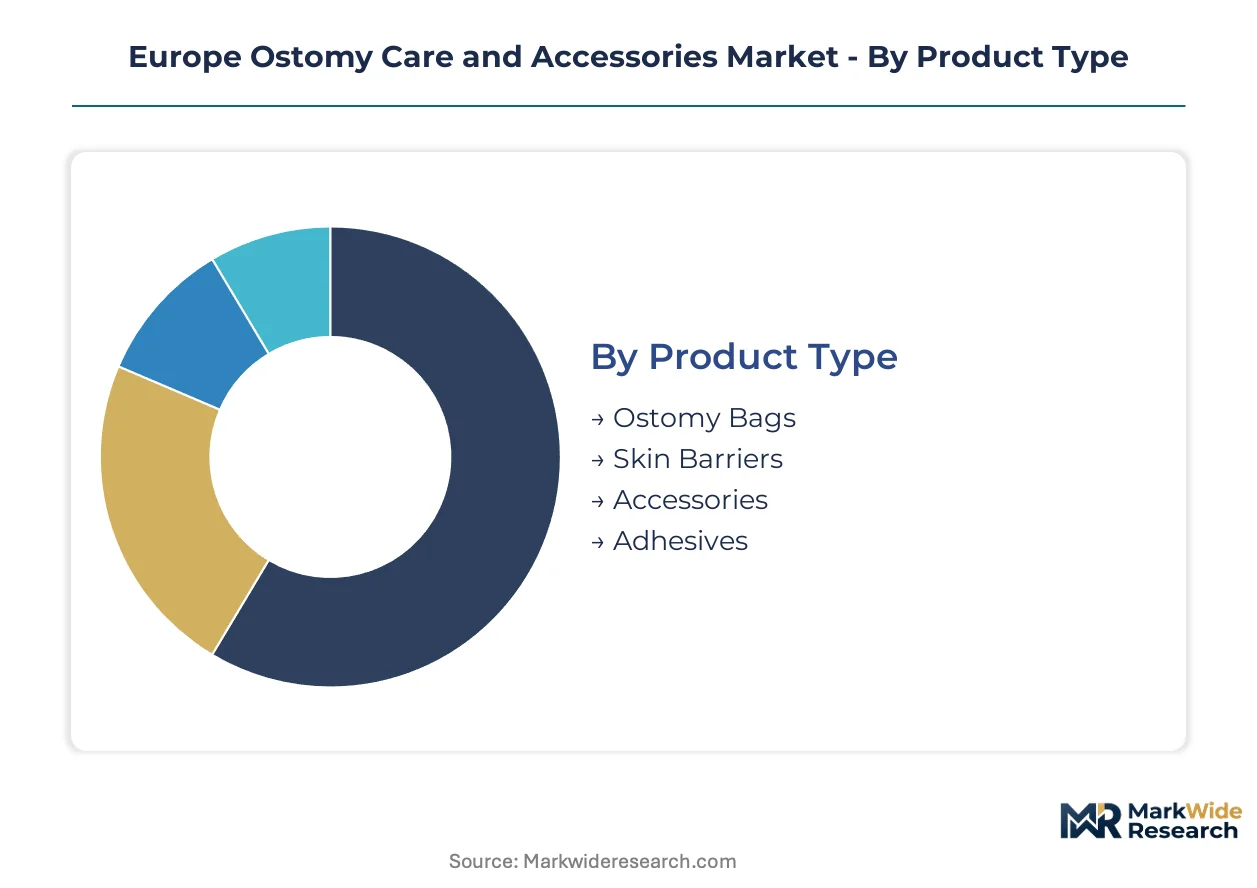
European ostomy care segmentation reflects divergent reimbursement pathways across national health systems. Product-level purchasing power concentrates in Germany and France, while distribution channel preferences fragment along urban-rural divides.
Product Type:
German and French manufacturers dominate ostomy bag production for domestic hospital contracts. Skin barrier sourcing from Nordic polymer specialists supplies export markets across the Baltic states.
- Ostomy Bags:Drainable and closed pouch systems employ multilayer ethylene vinyl alcohol films to achieve 72-hour wear times. German hospital-at-home programs are expanding recurring replacement volumes for two-piece systems with mechanical coupling mechanisms.
- Skin Barriers:Hydrocolloid adhesive platforms with pH-buffering layers prevent peristomal moisture-associated skin damage. French ANSM post-market surveillance requirements are elevating clinical documentation burdens for novel formulation launches.
- Accessories:Irrigation sets and pouch covers from Italian contract manufacturers serve price-sensitive Mediterranean markets.
- Adhesives:Acrylic and silicone-based medical-grade bonding agents from Dutch chemical suppliers enable extended wear compliance.
Ostomy bags command the established base. The steepest expansion runs through skin barriers.
Application:
Procedure volumes stratify across surgical oncology centers versus emergency intervention sites. Cost tier separation between curative and palliative pathways shapes procurement negotiations.
- Colostomy:Sigmoid and descending colon procedures generate the highest appliance replacement frequency due to semi-formed output consistency. United Kingdom NHS Supply Chain framework agreements aggregate purchasing for permanent colostomy patients discharged to community nursing.
- Ileostomy:Liquid effluent from small intestine diversion demands high-capacity drainable systems with advanced gas filtration. Nordic home care providers specify these platforms for Crohn's disease patients requiring intensive fluid management.
- Urostomy:Night drainage bags with anti-reflux valves from Spanish manufacturers address nocturnal incontinence requirements.
- Palliative Care:Simplified one-piece systems prioritize caregiver ease over extended wear performance in terminal patient populations.
Colostomy applications anchor revenue stability. Ileostomy systems are climbing the fastest as inflammatory bowel disease prevalence rises.
End User:
Customer-type concentration determines service intensity requirements. Hospital procurement teams negotiate volume contracts while home care patients demand direct-to-patient logistics.
- Hospitals:Acute surgical wards and stoma therapy nursing units drive initial appliance fitting and patient education. Germany's BfArM vigilance reporting obligations extend documentation timelines for hospital-supplied Class IIa devices.
- Home Care:Outpatient stoma management programs in France and Belgium route patients directly to reimbursed home delivery services. Regional health system decentralization in Spain creates whitespace for independent distributors.
- Nursing Facilities:Long-term care residences in Italy require simplified application systems for staff with limited specialized training.
- Clinics:Ambulatory surgery centers in the Netherlands perform increasing volumes of laparoscopic stoma formation procedures.
Hospital channels retain the volume base. Home care is gaining share fastest as discharge protocols accelerate across EU health systems.
Distribution Channel:
Supply concentration among three channel archetypes shapes margin capture. Online platforms displace traditional pharmacy relationships in urban corridors.
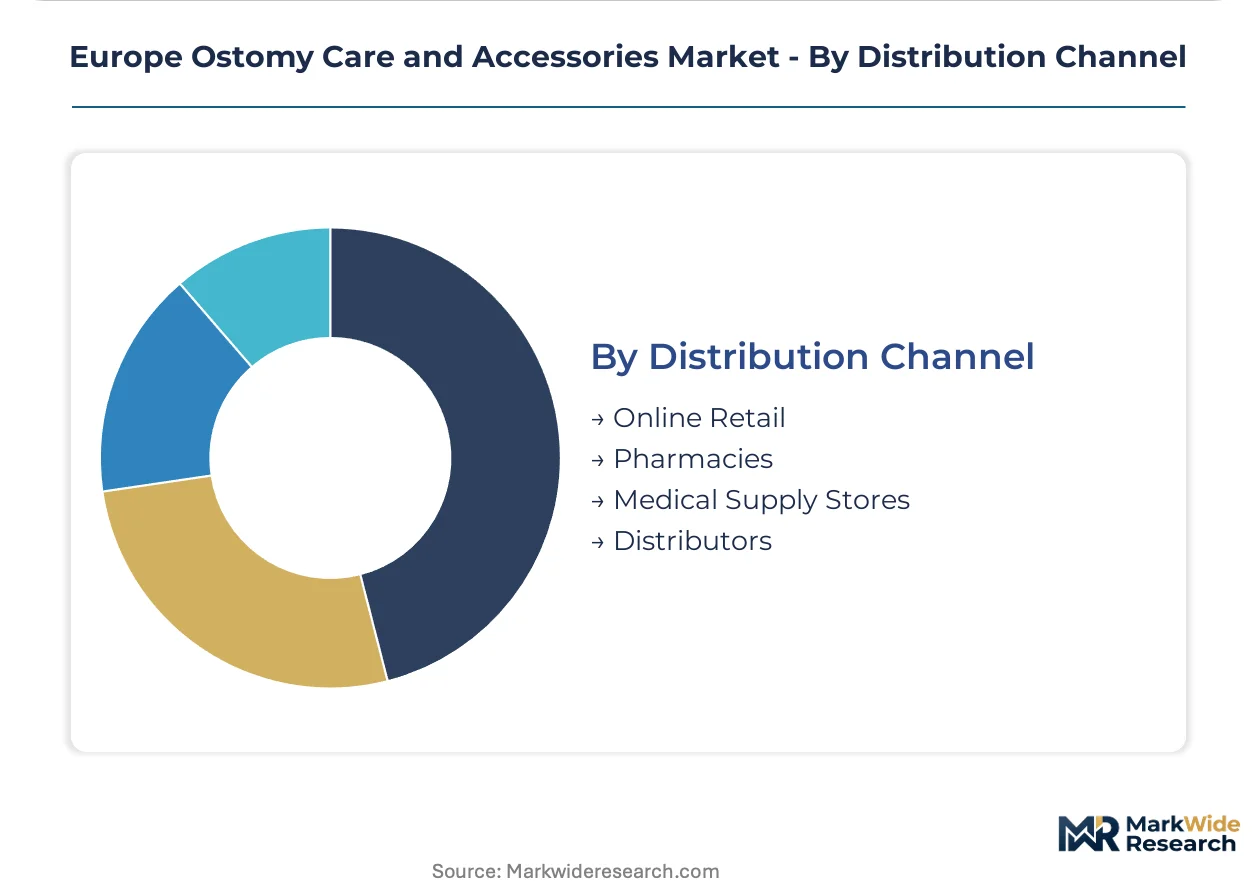
- Online Retail:Direct-to-patient e-commerce platforms bypass centralized tender processes through ostomy association partnerships. England's Integrated Care Systems patient choice policies enable digital channel penetration despite NHS Supply Chain aggregation.
- Pharmacies:Community pharmacy reimbursement in France and Germany maintains brick-and-mortar relevance for emergency appliance replacement.
- Medical Supply Stores:Specialized durable medical equipment retailers in Nordic regions provide fitting consultation services.
- Distributors:Wholesale intermediaries serving Eastern European markets face margin compression from generic hydrocolloid substitution.
Pharmacies hold the established position. Online retail is expanding most quickly as patient digital literacy improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German hospital-at-home programs command pricing premiums exceeding French ambulatory care tariffs by substantial margins, while Spanish regional decentralization fragments procurement power across autonomous communities.
Germany
Hospital-at-home discharge protocols for post-operative stoma patients expand recurring appliance volumes through reimbursed community nursing services. BfArM vigilance reporting obligations for Class IIa medical devices extend compliance timelines and documentation burdens for market entrants. The Rhine-Ruhr industrial corridor concentrates polymer film manufacturing for multilayer odor-barrier substrates.
France
ANSM real-world evidence requirements under MDR Article 74 mandate systematic patient-reported outcome collection for drainable pouch systems. Hospital-at-home programs route post-operative patients directly to outpatient stoma management, expanding addressable demand. The Paris-Saclay medical technology cluster anchors hydrocolloid adhesive research infrastructure.
United Kingdom
NHS Supply Chain framework agreements consolidate stoma care purchasing through regional aggregation, compressing supplier rosters from twelve to four in several Integrated Care Systems. Patient choice policies create channel tension between volume aggregation and brand retention. Greater Manchester's medical device distribution hub serves Northern England home care networks.
Spain
Regional health system decentralization creates whitespace for direct-to-patient distribution models bypassing traditional hospital discharge channels in autonomous communities with underpenetrated infrastructure. Catalonia's Barcelona medical technology corridor hosts contract manufacturers serving Mediterranean price-sensitive markets.
Netherlands
Ambulatory surgery centers perform increasing volumes of laparoscopic stoma formation procedures, routing patients to reimbursed home delivery services. Eindhoven's polymer research infrastructure supplies medical-grade bonding agents to Nordic ostomy film manufacturers.
Europe Ostomy Care and Accessories Market Competitive Landscape
Concentration sits with integrated polymer specialists controlling high-barrier film production in-house. The vendor base stratifies across three tiers: multinational medical device conglomerates with captive polymer research infrastructure, mid-tier European specialists leveraging regional adhesive formulation expertise, and contract manufacturers serving price-sensitive public tenders. Dominant competitive moves include backward integration into ethylene vinyl alcohol coextrusion capacity and geographic expansion through ostomy association partnerships bypassing centralized procurement.
Among Nordic hospital system specialists, Coloplast Corp. and Hollister Incorporated exemplify the integrated polymer research archetype, while ConvaTec Group Plc occupies a position emphasizing sustained platform investment in adhesive technologies. These three entities anchor the premium tier through differentiated wear-time performance and direct-to-patient service models.
| Leading Market Players |
|---|
| Coloplast Corp. |
| ConvaTec Group Plc |
| Hollister Incorporated |
| Salts Healthcare |
| B. Braun Melsungen AG |
| Welland Medical Limited |
| Marlen Manufacturing & Development Company |
| ALCARE Co., Ltd. |
| Flexicare (Group) Limited |
| Others |
Value Network & Pricing Analysis
Ninety-day ethylene vinyl alcohol film inventory cycles concentrate pricing power among German and Dutch polymer specialists, compressing margin capture for ostomy appliance assemblers dependent on spot-market resin procurement. This lead-time structure binds pricing tiers to feedstock allocation priority, with backward-integrated manufacturers commanding premium positioning against contract-manufacturing competitors.
Pricing Analysis
The customization-premium spread separates configured-to-order hydrocolloid skin barriers from standard drainable pouch systems by a substantial margin band. Three-tier pricing structure across premium, standard, and economy levels dominates, with differentiation resting on CE marking tier under EU MDR and volume scale in NHS Supply Chain tenders. Cost compression in the economy tier is intensifying because generic hydrocolloid formulations from Eastern European contract manufacturers capture public hospital volume. Public procurement teams exhibit highest price sensitivity, while home care patients prioritizing wear-time performance show lowest.
Supply Chain Analysis
Germany and the Netherlands anchor ethylene vinyl alcohol coextrusion capacity for multilayer odor-barrier films, while Italy hosts irrigation set contract manufacturing for Mediterranean markets. Raw material flows draw from Belgian petrochemical feedstock, Dutch medical-grade adhesive resins, and Nordic hydrocolloid gum bases. Single-source vulnerability concentrates in the three European producers of specialty EVOH resin, exposing film manufacturers to allocation risk during supply shocks. Distribution runs through hospital procurement frameworks in Northern Europe, direct-to-patient platforms in France, and pharmacy networks in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Generic hydrocolloid substitution from Eastern European contract manufacturers threatens branded margin pools, forcing incumbents to defend through differentiated wear-time performance and regulatory certification depth.
For Market Incumbents: Secure captive ethylene vinyl alcohol coextrusion capacity through backward integration or long-term offtake agreements with Rhine-Ruhr polymer specialists. Deepen EU MDR technical documentation investment to extend certification moats against generic entrants lacking clinical evaluation report infrastructure. For New Entrants and Emerging Players: Anchor in Spain's regionally decentralized health systems where direct-to-patient distribution models bypass NHS Supply Chain aggregation and hospital procurement consolidation. Target Catalonia and Andalusia autonomous communities with underpenetrated home care infrastructure, leveraging ostomy association partnerships for channel access. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because polymer research talent scarcity and MDR compliance cost escalation favor scaled manufacturers with captive R&D infrastructure. Target mid-tier European specialists with regional adhesive formulation expertise and incomplete CE marking portfolios. Watch for BfArM vigilance reporting obligation expansion as inflection signal for compliance cost acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR technical documentation investment compresses competitive windows for non-compliant entrants. |
| Hospital System Partnership | NHS Supply Chain framework agreements consolidate purchasing power across England's Integrated Care Systems. |
| Backward Integration | Captive ethylene vinyl alcohol film production insulates margin from petrochemical allocation volatility. |
| Software Companion Development | pH-sensing wearable integration enables subscription revenue streams for remote peristomal monitoring. |
| Reimbursement Strategy | EU Health Technology Assessment alignment rewards manufacturers with health-economic evidence packages. |
Research Methodology
Initial hypotheses were tested against primary input from stoma therapy nursing directors, hospital procurement committee members, biomedical engineers at GPOs, and regulatory affairs leads at polymer film manufacturers, and refined through secondary validation against EMA MDR guidance documents, BfArM vigilance reporting databases, NHS Supply Chain tender records, and EU Health Technology Assessment pilot program filings. Bottom-up demand modeling triangulated with top-down market sizing across product type, application, end user, and distribution channel dimensions.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects, with segmentation modeling covering product tier, reimbursement pathway, regional regulatory cluster, and patient discharge protocol. CAGRs were derived from fitted growth curves anchored to procedure volume trajectories and replacement frequency assumptions. Forecast inputs incorporate polymer film innovation cycles and EU MDR implementation pace.
Decision-makers should treat outputs as directional under assumptions of stable EVOH feedstock supply and continued EU MDR enforcement harmonization; material deviation in either would warrant model refresh. Recalibration cycles align with material shifts in reimbursement harmonization debates and polymer research breakthrough timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Nitrile Gloves Market
Medical Supplies
Latin America Incontinence Pads Market
Medical Supplies
Medical Plastics Market
Medical Supplies
Medical Procedure Tray Market
Medical Supplies
Butterfly Needle Sets Market
Medical Supplies
Ostomy Care Market
Medical Supplies
Blood Glucose Test Strip Packaging Market
Medical Supplies
Pressure Relief Mattress Market
Medical Supplies
Global Dialysis Concentrate Market
Medical Supplies
Push-In Plug Vials Market
Medical Supplies
Colostomy Bags Market
Medical Supplies
Global Lancets Market
Medical Supplies
Global Respiratory and Anesthesia Disposables Market
Medical Supplies
Global Surgical Masks Market
Medical Supplies
Intraosseous Infusion Kits Market
Medical Supplies
Europe Medical Clothing Market