
 Respiratory Masks Market | 2026-2036
Respiratory Masks Market Size, Share, and Industry Trends Forecast 2026-2036
Respiratory Masks Market Outlook
Southeast Asian manufacturing capacity is tilting toward melt-blown polypropylene output as regional governments prioritize medical supply autonomy. 3M leverages its integrated filter media production to sustain margin control across N95 and P100 lines. Honeywell International Inc. anchors North American distribution through industrial safety channels. MSA Safety Incorporated specializes in emergency responder configurations with integrated communications ports.
Respiratory masks are personal protective devices constructed from multi-layer nonwoven polypropylene media with electrostatically charged melt-blown cores designed to filter airborne particulates, pathogens, and industrial contaminants at specified efficiency thresholds. N95 masks dominate hospital procurement budgets while P100 filters command premium positioning in industrial and emergency response settings where oil-based aerosol protection is mandatory. Disposable usage types absorb the highest volume share across healthcare and industrial segments, though reusable frames with replaceable filter cartridges are gaining traction among emergency responders seeking operational cost reduction.
NIOSH certification protocols and OSHA respiratory protection standards govern product approval and workplace deployment in the United States, while the EU Medical Device Regulation and REACH chemical compliance frameworks shape European market access requirements. FDA emergency use authorizations during public health crises have permanently altered hospital procurement expectations for surge capacity. Stakeholders must monitor evolving filtration efficiency benchmarks and regional stockpiling mandates to align capacity planning with procurement cycles.
Market Dynamics
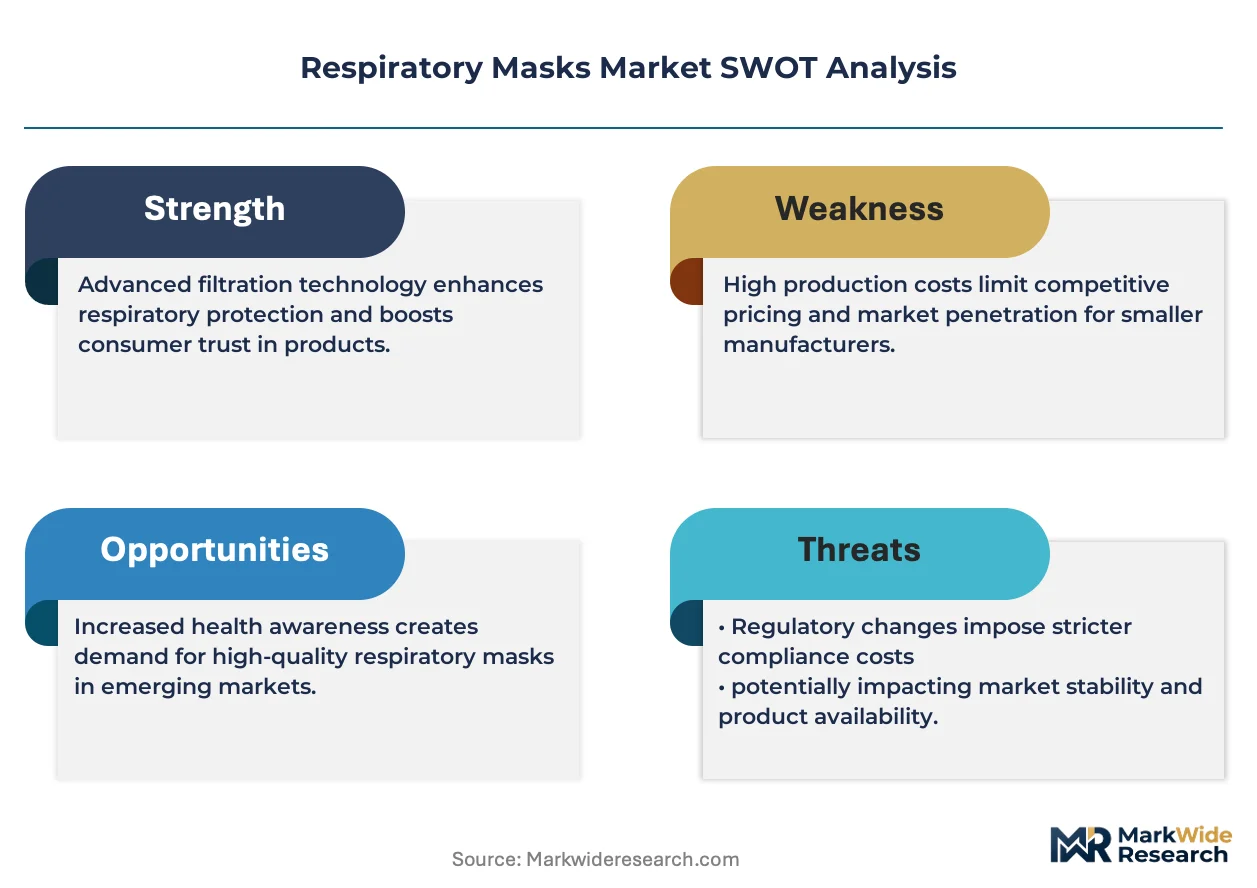
Hospital procurement consolidation and federal stockpiling mandates are compressing supplier margins while concentrating volume flows toward manufacturers with captive melt-blown polypropylene capacity and NIOSH-certified production lines.
Growth Catalysts
- NIOSH Certification Requirements:OSHA workplace exposure limits are tightening filtration performance standards across healthcare and industrial facilities, forcing equipment upgrades and replacement cycles.
- Federal Stockpiling Programs:United States government reserves are expanding strategic medical supply inventories, creating sustained demand for N95 and P100 respirators with surge capacity clauses.
- Melt-Blown Polypropylene:Southeast Asian manufacturing capacity expansion is reducing import dependency and shortening lead times for electrostatic filter media.
Market Restraints
- Raw Material Concentration:Polypropylene resin supply concentrates among petrochemical complexes in the US Gulf Coast and Middle East, exposing converters to feedstock volatility.
- Certification Bottlenecks:NIOSH approval timelines extend 12-18 months for new respirator designs, freezing product development pipelines and delaying market entry.
- Reusable Frame Substitution:Emergency responder agencies are shifting toward elastomeric half-masks with replaceable cartridges, eroding disposable N95 volume in professional segments.
Strategic Opportunities
- EU Medical Device Regulation:MDR compliance requirements are raising barriers for non-European suppliers, creating white space for certified manufacturers with notified body relationships.
- Integrated Communications Ports:Emergency responder configurations combining respiratory protection with radio integration command premium positioning and multi-year contract terms.
- India PLI Scheme:Production-linked incentives for medical device manufacturing are attracting filter media investments and regional supply chain localization.
Industry Challenges
- Electrostatic Charge Retention:Maintaining filtration efficiency across variable humidity conditions requires material science expertise that concentrates among legacy nonwoven specialists.
- Legacy ERP Integration:Hospital procurement systems demand EDI compliance and real-time inventory visibility that strain smaller manufacturers' IT infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Respiratory Masks Market |
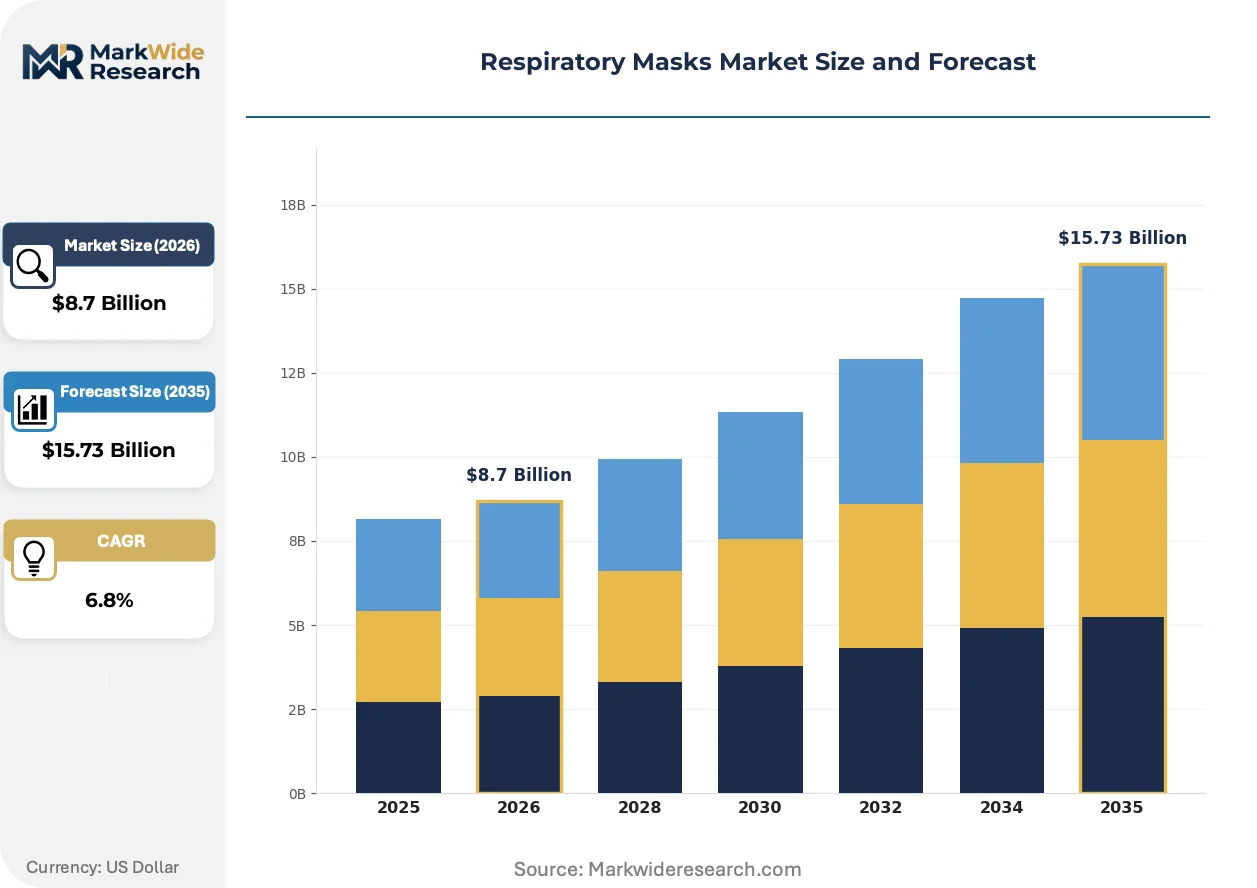
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: N95 Masks, Surgical Masks, P100 Filters, Face Shields End User: Healthcare Workers, General Public, Industrial Workers, Emergency Responders Usage Type: Disposable, Reusable, Single-Use, Multi-Use Material: Polypropylene, Cotton, Polyester, Activated Carbon |
| Companies Covered | 3M, Honeywell International Inc., Ansell Ltd., Medline Industries, Inc., Cardinal Health, Moldex-Metric, DuPont, MSA Safety Incorporated, Alpha Pro Tech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Respiratory Masks Market Strategic Shifts
Filter media manufacturing and mask assembly are converging through backward integration, while regulatory frameworks harden certification requirements and procurement patterns shift toward long-term supply agreements.
Electrospun nanofiber membranes are replacing conventional melt-blown layers in premium respirator lines. Industrial safety distributors and hospital systems with stringent fit-test protocols are adopting these materials at accelerating rates. The technology is collapsing the performance gap between disposable N95s and reusable elastomeric units in oil-based aerosol environments.
REACH chemical compliance frameworks in Europe are expanding substance restriction lists for skin-contact materials in respiratory devices. Manufacturers serving EU markets must reformulate elastomer components and validate alternative plasticizers through notified body assessment. This regulatory pressure is diverting R&D resources from performance innovation toward materials substitution.
Hospital systems are consolidating vendor rosters through multi-year sole-source agreements with surge capacity guarantees. Group purchasing organizations are displacing spot-market procurement and fragmenting residual volume among secondary suppliers. This behavioral shift is most visible in United States acute care networks where federal reimbursement policies reward supply chain redundancy investments.
Respiratory Masks Market Segmentation
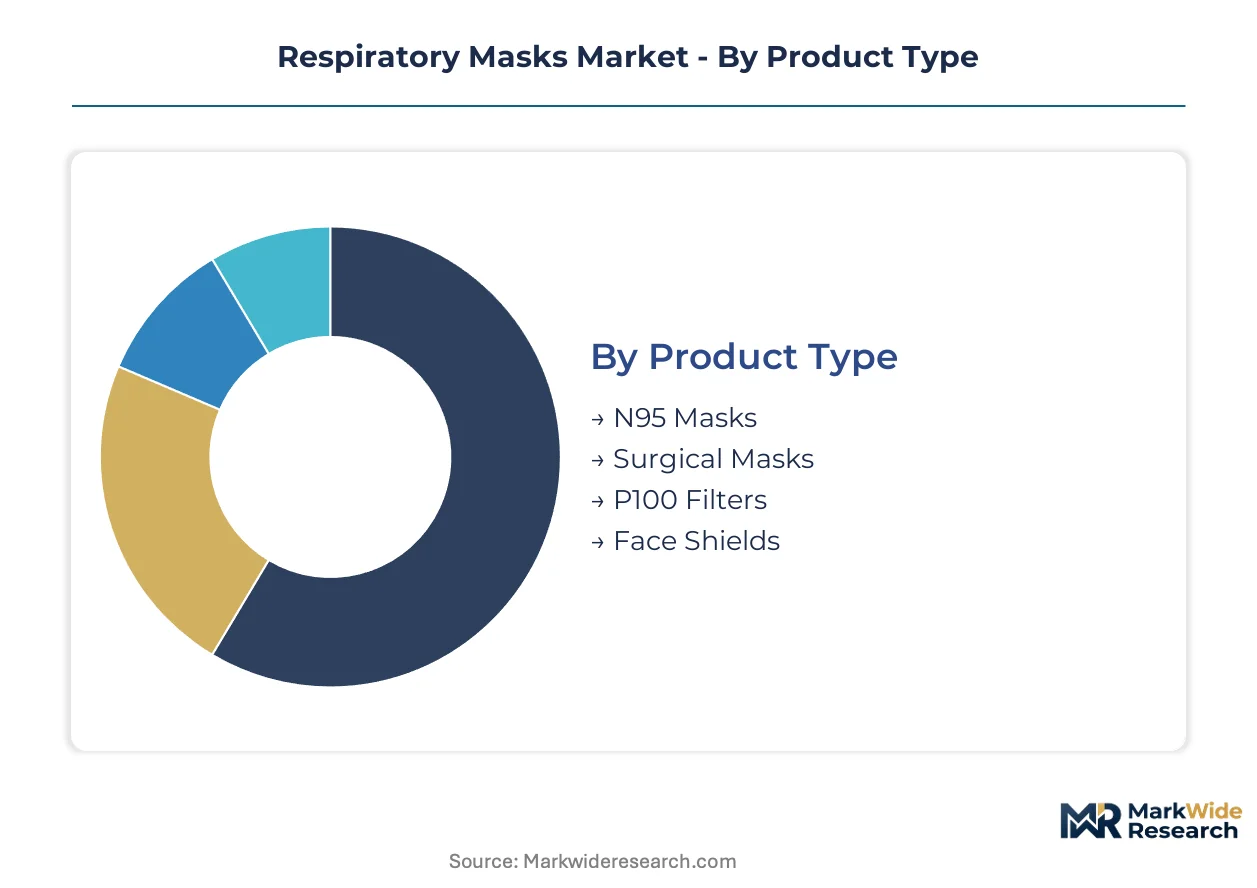
Respiratory mask procurement patterns diverge sharply across user environments, with hospital systems prioritizing NIOSH-certified disposables while industrial buyers weigh total cost of ownership against filtration longevity. Understanding these segment boundaries clarifies where margin pools concentrate and which technical specifications drive contract awards.
Product Type:
Mature filtration standards anchor hospital and industrial procurement, while emerging configurations reshape emergency response specifications.
- N95 Masks:Multi-layer nonwoven polypropylene construction with electrostatically charged melt-blown cores achieves 95% filtration efficiency against 0.3-micron particles. Hospital procurement consolidation in the United States is funneling volume toward manufacturers with captive melt-blown capacity and NIOSH-certified lines, compressing margins for secondary suppliers.
- P100 Filters:High-efficiency particulate air filtration rated at 99.97% with oil aerosol resistance mandatory for industrial and emergency response settings. Demand concentrates among MSA Safety and Honeywell distribution channels where integrated communications ports command premium positioning and multi-year sole-source agreements.
- Surgical Masks:Fluid-resistant barrier protection for sterile field maintenance during medical procedures.
- Face Shields:Secondary splash and spray protection deployed alongside primary respiratory devices in healthcare settings.
N95 masks retain volume leadership; P100 filters hold the steepest expansion curve among professional-grade categories.
End User:
Cost-tier stratification separates institutional buyers with compliance mandates from price-sensitive consumer segments.
- Healthcare Workers:OSHA respiratory protection standards and FDA emergency use authorization requirements govern hospital deployment protocols. Federal stockpiling programs and surge capacity clauses in United States acute care networks are reshaping procurement toward manufacturers with demonstrated supply continuity.
- Emergency Responders:Specialized configurations integrating radio communications and thermal imaging compatibility dominate fire service and hazardous materials team procurement. Elastomeric half-masks with replaceable cartridges are displacing disposable N95 volume as agencies pursue operational cost reduction.
- Industrial Workers:Fit-test protocols and exposure limit compliance drive replacement cycles in manufacturing and construction environments.
- General Public:Retail channel distribution with minimal regulatory oversight and price-driven purchasing behavior.
Healthcare workers retain volume leadership; emergency responders hold the steepest expansion curve.
Usage Type:
Volume concentration favors single-use disposables, though reusable frames are gaining traction in cost-sensitive professional segments.
- Disposable:Single-shift or single-patient use dominates hospital infection control protocols and industrial compliance programs. Southeast Asian manufacturing capacity expansion is shortening lead times for high-volume electrostatic filter media orders.
- Reusable:Elastomeric frames with replaceable filter cartridges reduce lifetime cost for emergency responder agencies and industrial maintenance departments. NIOSH approval timelines extending 12-18 months for new designs are freezing product development pipelines for specialized configurations.
- Single-Use:Identical functional specification to disposable with emphasis on patient-specific deployment in clinical settings.
- Multi-Use:Limited reuse protocols with decontamination validation requirements in resource-constrained environments.
Disposable usage retains volume leadership; reusable frames hold the steepest expansion curve.
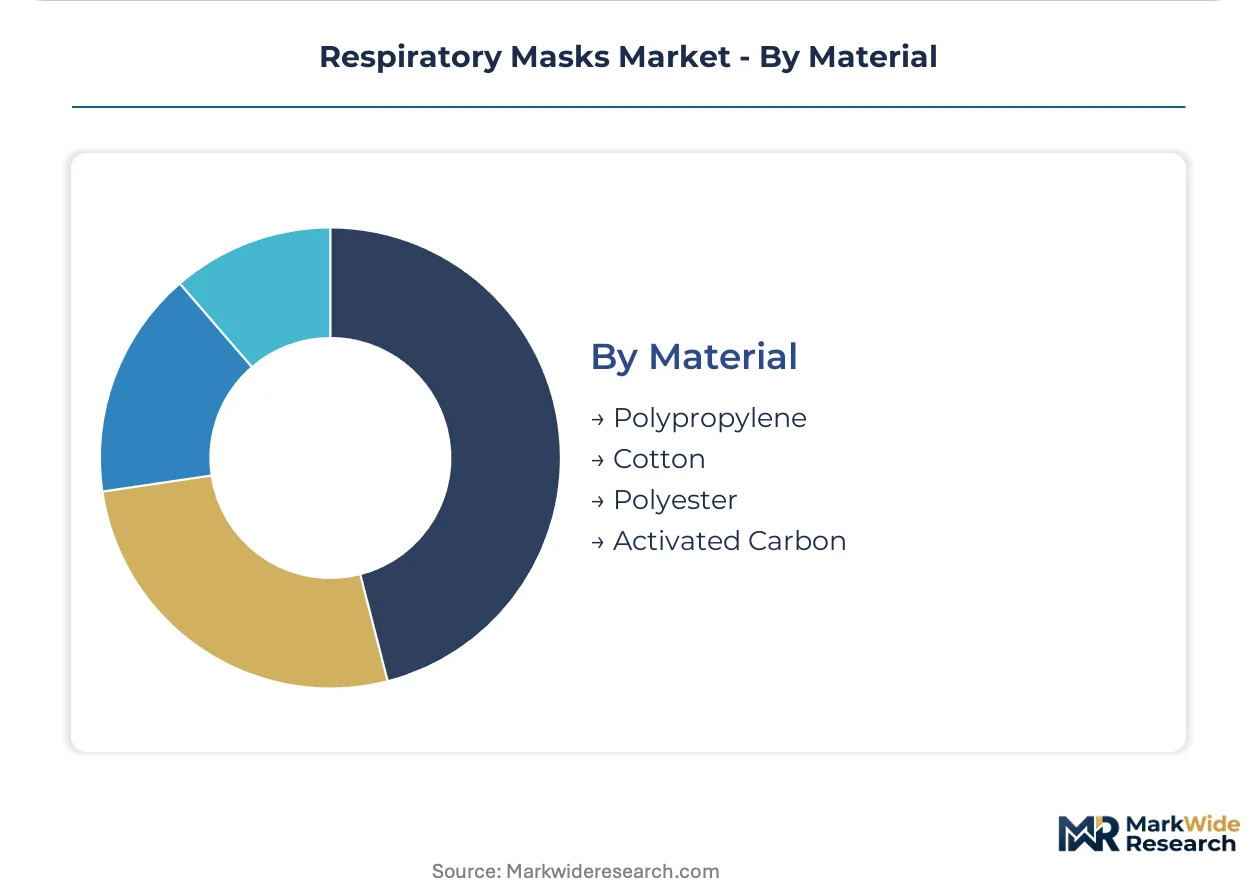
Material:
Supply concentration in petrochemical feedstocks dictates cost volatility and regional manufacturing strategies.
- Polypropylene:Melt-blown and spunbond nonwoven layers form the functional core of N95 and surgical mask construction. United States Gulf Coast and Middle East resin supply concentration exposes converters to feedstock price swings that compress margin predictability.
- Activated Carbon:Adsorptive media for organic vapor and nuisance odor protection in industrial and emergency response configurations. REACH chemical compliance frameworks in Europe are expanding substance restriction lists, forcing reformulation of skin-contact elastomer components.
- Cotton:Woven and nonwoven natural fiber barriers for consumer-grade comfort-oriented products.
- Polyester:Synthetic fiber reinforcement and outer shell durability in reusable frame construction.
Polypropylene retains volume leadership; activated carbon holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Melt-blown polypropylene capacity clusters in the United States Gulf Coast, Southeast Asia, and the Middle East, creating supply-side asymmetries that filter through to finished mask availability and procurement lead times. Hospital systems and industrial distributors calibrate inventory positions against these geographic production nodes. Regulatory divergence across national jurisdictions compounds sourcing complexity.
United States
Federal stockpiling programs and hospital procurement consolidation funnel volume toward domestic manufacturers with NIOSH-certified lines. OSHA respiratory protection standards and FDA emergency use authorization requirements govern workplace deployment protocols. Houston-Gulf Coast petrochemical complexes supply polypropylene resin to regional converters, though feedstock volatility compresses margin predictability for mask assemblers.
China
Domestic melt-blown capacity expansion accelerated following supply chain disruptions, with Yangtze River Delta manufacturers scaling electrostatic filter media output. NMPA medical device registration and GB standards compliance shape export market access. Zhejiang and Jiangsu provinces host integrated nonwoven clusters where backward integration into polypropylene spinning shortens production cycles for N95-equivalent respirators.
Germany
Industrial safety distributors anchor European demand for P100 and elastomeric configurations across manufacturing and chemical processing sectors. EU Medical Device Regulation and REACH chemical compliance frameworks raise barriers for non-European suppliers, creating white space for notified body-certified manufacturers. North Rhine-Westphalia's Ruhr industrial corridor sustains fit-test protocol adoption and replacement cycle discipline among plant safety officers.
India
Production-linked incentive schemes for medical device manufacturing attract filter media investments toward Gujarat and Maharashtra. CDSCO medical device rules and BIS certification requirements govern domestic market entry. Tamil Nadu's Sriperumbudur-Oragadam automotive belt generates parallel industrial safety demand as foreign component suppliers establish local assembly operations with mandated respiratory protection programs.
Japan
Hospital infection control protocols sustain premium disposable N95 procurement despite aging demographics compressing acute care bed expansion. PMDA medical device approval and JIS standards alignment shape product specifications for domestic distribution. Kansai region chemical companies supply specialized electrostatic additives to regional nonwoven converters serving both healthcare and semiconductor cleanroom applications.
Respiratory Masks Market Competitive Environment
Diversified industrial conglomerates and specialized safety equipment fabricators split the market along certification depth and channel access vectors. Consolidation pressures concentrate volume flows toward manufacturers with captive melt-blown capacity and multi-decade NIOSH relationships. Three archetypes dominate: integrated material-science conglomerates controlling upstream filter media, safety-focused specialists engineering application-specific configurations, and healthcare distributors leveraging procurement relationships. Competitive moves center on backward integration into polypropylene spinning and long-term sole-source agreements with hospital group purchasing organizations.
Within the integrated-materials tier, 3M and DuPont occupy positions exemplifying upstream control over electrostatic filter technology. Honeywell International Inc. and MSA Safety Incorporated represent the safety-specialist archetype, anchoring industrial and emergency responder channels where fit-test protocols and communications integration command premium positioning. Ansell Ltd. and Medline Industries, Inc. sit within the healthcare-distributor vector, consolidating hospital procurement relationships through multi-year contracts with surge capacity guarantees.
| Leading Market Players |
|---|
| 3M |
| Honeywell International Inc. |
| Ansell Ltd. |
| Medline Industries, Inc. |
| Cardinal Health |
| Moldex-Metric |
| DuPont |
| MSA Safety Incorporated |
| Alpha Pro Tech |
| Others |
Value Chain & Pricing Dynamics
Yangtze River Delta melt-blown capacity expansion is compressing export pricing for electrostatic filter media while concentrating procurement leverage among hospital systems with multi-year sole-source agreements. Polypropylene resin volatility at US Gulf Coast petrochemical complexes feeds directly into margin pressure for NIOSH-certified assemblers lacking backward integration into filter media production.
Pricing Analysis
NIOSH certification requirements dictate the pricing tier structure across healthcare and industrial procurement channels. Three-tier pricing structure across premium, standard, and economy levels separates P100 filters with integrated communications ports from baseline N95 disposables and unbranded surgical masks. Cost compression in standard-tier N95 supply is intensifying because hospital procurement consolidation funnels volume toward manufacturers with captive melt-blown capacity. Emergency responder agencies exhibit the lowest price sensitivity due to operational cost-reduction mandates, while general public retail channels demonstrate maximal elasticity.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for electrostatic filter media sourcing. Manufacturing concentrates in China, the United States, and Germany, with polypropylene resin, melt-blown nonwoven layers, and elastomer components as critical inputs. Single-source vulnerability concentrates in Southeast Asian melt-blown expansion projects still ramping toward qualified medical-grade output. Distribution runs through industrial safety distributors, hospital group purchasing organizations, and federal stockpiling programs with diverging lead time tolerances.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as emergency responder procurement shifts toward elastomeric configurations, creating niche openings for specialized manufacturers outside consolidated hospital supply chains.
For Market Incumbents: Insulate NIOSH-certified production lines through captive melt-blown capacity additions in the US Gulf Coast region. Secure multi-year sole-source agreements with hospital group purchasing organizations before federal stockpiling mandates further concentrate volume. Reusable frame substitution by emergency responder agencies threatens disposable N95 volume; counter through integrated communications port development for premium P100 lines. For New Entrants and Emerging Players: EU Medical Device Regulation compliance gaps among Asian exporters represent the most penetrable entry point for notified body-certified manufacturers. India's PLI scheme attracts filter media investments toward Gujarat and Maharashtra, creating regional supply chain localization opportunities. Target CDSCO-certified distribution partnerships with Tamil Nadu automotive suppliers establishing mandated respiratory protection programs. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-moat play because certification bottlenecks and NIOSH approval timelines freeze product development pipelines, concentrating value in legacy relationships. Acquisition target archetype: mid-cap specialists with existing notified body relationships in Europe and demonstrated surge capacity fulfillment. Watch NIOSH backlog clearance rates as inflection indicator for new entrant viability.| Strategic Initiative | Industry Significance |
|---|---|
| NIOSH Certification Investment | OSHA tightening exposure limits forces equipment upgrade cycles across hospital systems. |
| Backward Integration into Melt-Blown Media | |
| Emergency Responder Communications Integration | Radio-compatible P100 configurations command premium positioning and multi-year contracts. |
| EU MDR Notified Body Relationship | REACH compliance barriers create white space for certified manufacturers in European hospital procurement. |
| India PLI Scheme Localization | CDSCO-aligned production in Gujarat reduces import dependency for domestic medical device supply. |
Study Parameters
A standing panel of hospital procurement directors, industrial safety officers, NIOSH certification specialists, and melt-blown nonwoven converters provided ongoing calibration across the primary research phase. Primary interviews with group purchasing organization contract managers and emergency responder equipment chiefs combined with secondary validation from FDA emergency use authorization filings, OSHA respiratory protection standard updates, and EU Medical Device Regulation notified body registers. Bottom-up volume modeling triangulated against top-down healthcare expenditure flows and industrial safety equipment trade data.
Scenario-bracketing around federal stockpiling mandate intensity and NIOSH approval timeline variability shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type filtration efficiency tier, end-user compliance mandate level, usage type replacement cycle frequency, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to hospital bed expansion rates and industrial employment exposure statistics. Electrostatic charge retention benchmarks and fit-test protocol adoption curves served as industry-specific forecast inputs.
Stress conditions across polypropylene resin price volatility, NIOSH certification backlog duration, and emergency responder budget allocation shifts were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and hospital procurement consolidation velocity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Compression Socks Market
Medical Supplies
Plastic Medicine Spoons Market
Medical Supplies
Tracheostomy Securement Tapes Market
Medical Supplies
Casting and Splinting Market
Medical Supplies
Latex Medical Disposables Market
Medical Supplies
Petri Dishes Market
Medical Supplies
Global IV Tubing Sets and Accessories Market
Medical Supplies
North America Medical Clothing Market
Medical Supplies
Global Hot and Cold Therapy Packs Market
Medical Supplies
Abdominal Compression Garments Market
Medical Supplies
Global Synthetic Absorbable Sutures Market
Medical Supplies
Italy Ostomy Care and Accessories Market
Medical Supplies
Arthroscopy Fluid Management Disposables Market
Medical Supplies
Middle East and Africa Hospital Supplies Market
Medical Supplies
GCC Medical Gloves Market
Medical Supplies
Global Absorbent Dressings Market