
 Cryogenic Vials and Tubes Market | 2026-2036
Cryogenic Vials and Tubes Market Size, Share, and Industry Trends Forecast 2026-2036
Cryogenic Vials and Tubes Market Outlook
The EU Medical Device Regulation is repositioning the cost-of-entry calculus for cryogenic consumables manufacturers serving European biobanks. Thermo Fisher Scientific leverages its integrated cold-chain portfolio to sustain pricing power across temperature-controlled logistics. Greiner Bio-One anchors its position through specialized polypropylene formulations optimized for liquid nitrogen compatibility. Corning Incorporated competes by controlling distribution depth into academic research clusters.
Cryogenic vials and tubes are precision-manufactured containers engineered from polypropylene, polycarbonate, or fluoropolymer resins to maintain structural integrity at temperatures below minus 150 degrees Celsius, primarily serving the preservation of biological specimens for longitudinal research and therapeutic development. Polypropylene formulations dominate unit volume due to their balance of thermal shock resistance and cost efficiency, while fluoropolymer variants command premium positioning in cell therapy applications where extractable leachables must approach zero. Biobanking applications generate the most consistent demand cadence, though genomics workflows are expanding fastest as nucleic acid archive scales multiply.
The FDA enforces container-closure integrity standards for cryogenic storage systems used in cellular therapy manufacturing, while ISO 20387 establishes biobank quality management protocols that cascade into consumables procurement specifications. REACH compliance in Europe restricts certain plasticizers, compelling material reformulation investments that favor suppliers with captive polymer science capabilities. Stakeholders must monitor how evolving pharmacopoeial chapters on extractables and leachables will reshape qualification requirements for next-generation cryopreservation formats.
Market Dynamics
The EU Medical Device Regulation is compressing qualification timelines for cryogenic consumables while simultaneously elevating material traceability requirements, forcing manufacturers to restructure polymer sourcing and documentation systems.
Growth Catalysts
- Biobanking infrastructure:Centralized biobank networks across Germany, France, and the Netherlands are expanding liquid nitrogen storage capacity to serve pan-European clinical reference standards. Procurement volumes from these hubs cascade into sustained consumables demand.
- EMA cell therapy guidance:Regulatory clarity on cryopreserved starting materials is accelerating qualification protocols for GMP-grade vials. Cell therapy manufacturers now specify container-closure integrity at vapor-phase nitrogen temperatures.
- Polypropylene formulation advances:Specialized resin grades with enhanced thermal shock resistance are extending shelf-life claims. Material suppliers with captive polymer science capabilities are capturing preferential supply relationships.
Market Restraints
- Propylene monomer volatility:Feedstock price swings for polypropylene resin directly compress margin structures for molded consumables. Manufacturers without backward integration into polymer supply face earnings instability.
- REACH compliance costs:ECHA restrictions on certain plasticizers and stabilizers necessitate material reformulation. Qualification timelines for replacement chemistries extend 18-24 months.
- Glass cryovial substitution:Borosilicate alternatives retain share in analytical applications requiring optical clarity. Polypropylene dominance in cell therapy has not fully displaced glass in quality control workflows.
Strategic Opportunities
- Nordic biobank consolidation:Sweden and Denmark are integrating national sample archives into unified networks. Standardized procurement specifications across these systems favor suppliers with documented ISO 20387 alignment.
- Digital traceability integration:RFID-enabled vials are converging with laboratory information management systems. Biobanks in Switzerland are piloting automated inventory tracking at the primary container level.
- CSRD reporting requirements:Corporate sustainability disclosures are elevating scrutiny of consumables waste streams. Biodegradable and recyclable cryogenic formats command procurement preference in ESG-mandated tenders.
Industry Challenges
- Cleanroom molding capacity:ISO 14644-1 Class 7 production environments require capital-intensive facility investments. Qualified manufacturing square meters remain concentrated among established European processors.
- Extractables validation timelines:USP Chapter 1664 and ISO 10993-18 testing protocols extend product launch schedules. Analytical chemistry bottlenecks compound certification delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cryogenic Vials and Tubes Market |
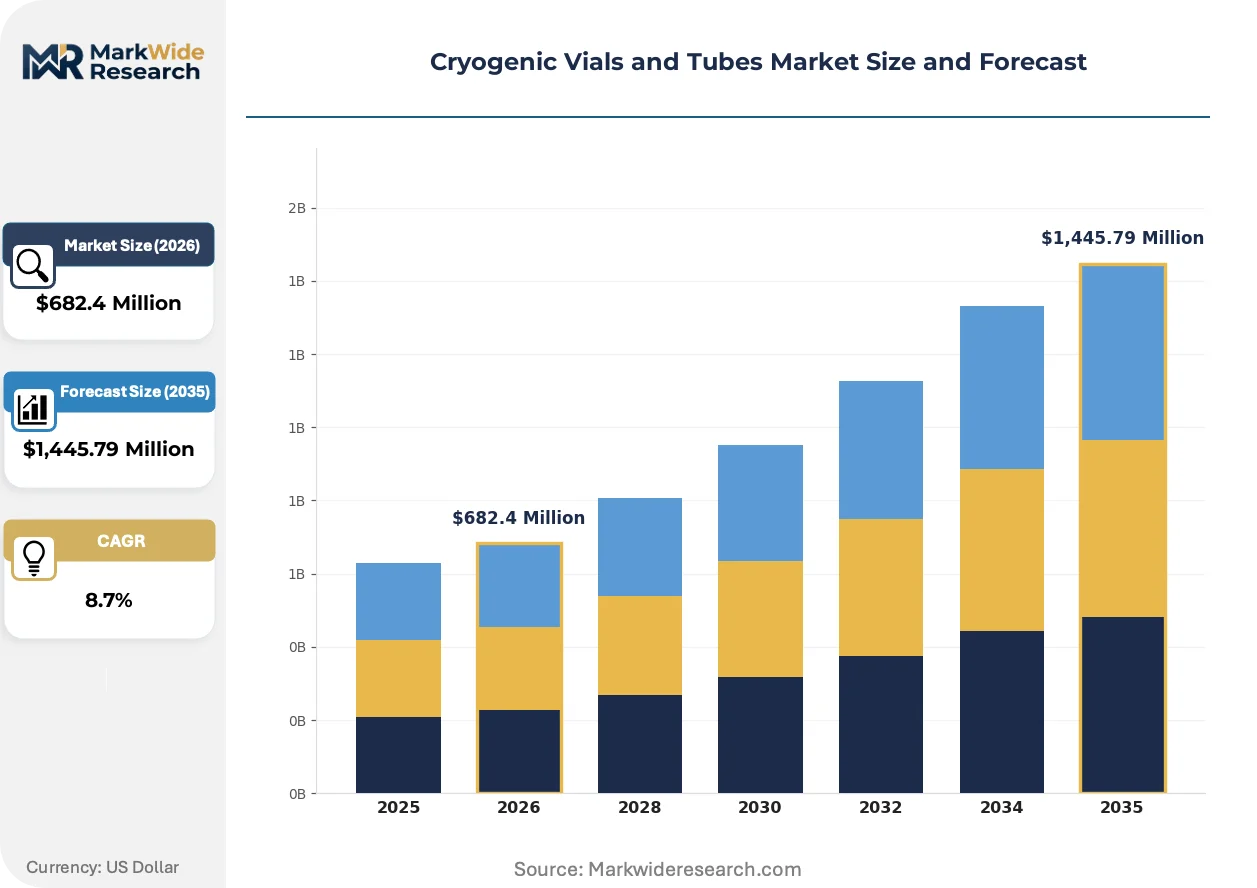
| Market Size in 2026 | $682.4 Million |
| Market Size in 2035 | $1,445.79 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
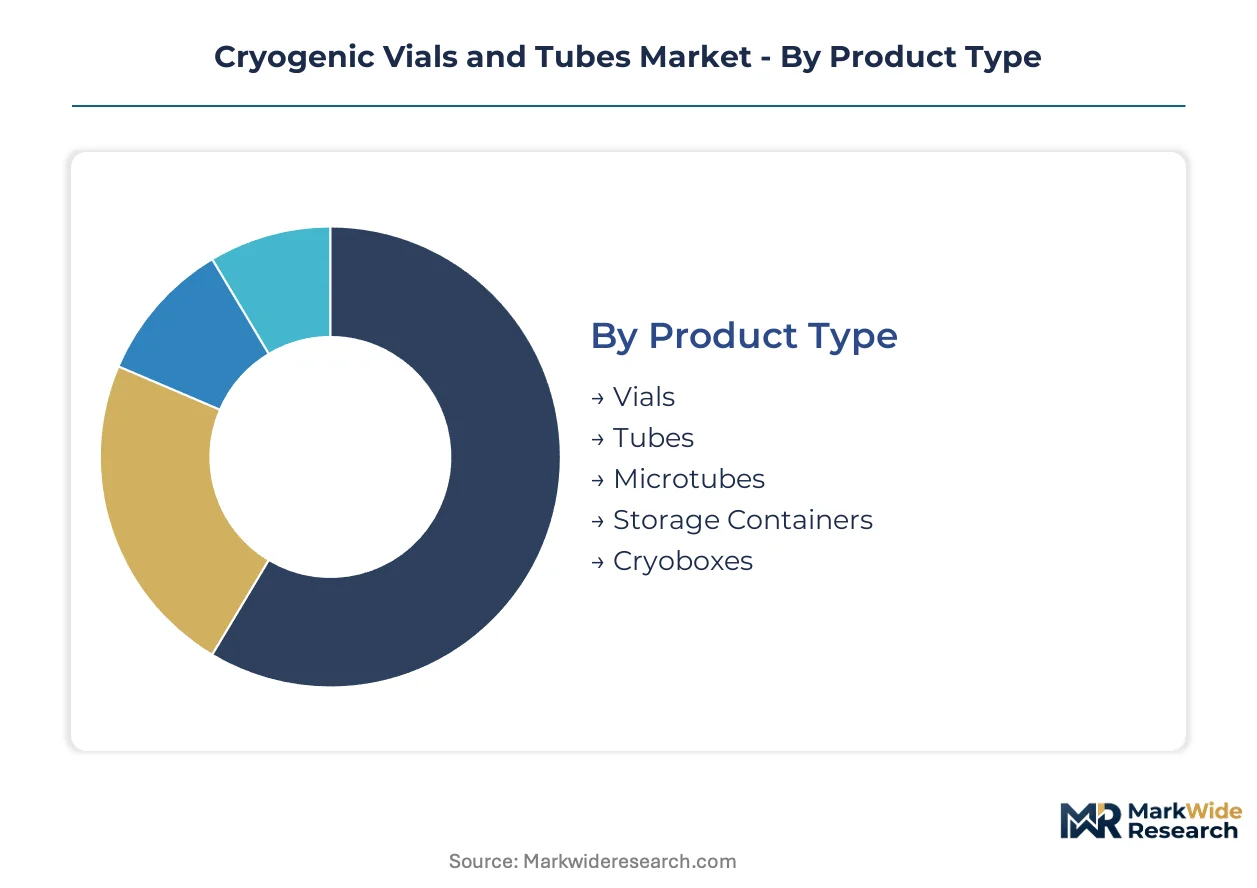
| Segmentation | Product Type: Vials, Tubes, Microtubes, Storage Containers, Cryoboxes Material: Polypropylene, Polycarbonate, Glass, Silicone, Fluoropolymer Application: Biobanking, Pharmaceutical Research, Diagnostics, Cellular Therapy, Genomics End User: Research Laboratories, Diagnostic Centers, Biopharmaceutical Firms, Academic Institutes |
| Companies Covered | Thermo Fisher Scientific, Corning Incorporated, Greiner Bio-One, DWK Life Sciences, Merck KGaA, Sumitomo Bakelite, Sigma-Aldrich, VWR International, CELLTREAT Scientific Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cryogenic Vials and Tubes Market Strategic Shifts
Automation, regulatory digitization, and procurement consolidation are restructuring how cryogenic consumables are specified, validated, and supplied across European research infrastructure.
Automated decapping and recapping systems are automating high-throughput biobank processing workflows. Facilities in Germany and the UK are deploying robotic liquid handling platforms that interface directly with standardized tube formats. This automation is compressing labor cost structures while demanding dimensional tolerances that exclude non-compliant suppliers.
REACH authorization procedures are tightening scrutiny of substances of very high concern in polymer formulations. ECHA's 2024-2026 rolling action plan targets specific plasticizers used in laboratory consumables. Cell therapy manufacturers are responding by mandating full material disclosure from their cryogenic vial suppliers.
Consolidated procurement through group purchasing organizations is displacing direct manufacturer relationships for academic and hospital biobanks. Centralized tenders in France and Italy now specify ISO 20387 quality management compliance as a mandatory qualification criterion. This concentration is visible most acutely in multi-site research networks seeking volume-based pricing structures.
Cryogenic Vials and Tubes Market Segmentation
Cryogenic consumables procurement varies sharply by performance tier and compliance burden. Material selection and application context reshape unit economics across customer segments.
Product Type:
Volume concentrates in standard formats while premium innovation targets automated handling systems.
- Vials:Polypropylene screw-cap containers engineered for vapor-phase nitrogen storage dominate biobank inventory systems. German centralized biobank networks specify external thread designs to minimize contamination risk during automated retrieval.
- Tubes:Larger-capacity formats with reinforced walls serve cell therapy manufacturing where container-closure integrity testing is mandatory. EMA guidance on cryopreserved starting materials is accelerating GMP-grade tube qualification timelines.
- Microtubes:0.5-2.0ml formats optimize freezer density for genomics archive expansion.
- Storage Containers:Rack-compatible systems integrate with liquid nitrogen dewar automation.
- Cryoboxes:Cardboard and polycarbonate grid systems complete cold-chain containment.
Today's leader: Vials. Tomorrow's challenger: Tubes.
Material:
Cost efficiency separates commodity resin grades from specialized formulations commanding qualification premiums.
- Polypropylene:Copolymer and homopolymer grades balance thermal shock resistance against extractables profiles. REACH compliance costs are forcing reformulation investments among European molders lacking captive polymer science capabilities.
- Fluoropolymer:Perfluoroalkoxy and polytetrafluoroethylene variants approach zero leachables for cell therapy applications. Swiss biobanks piloting automated inventory systems specify fluoropolymer for high-value therapeutic cell lines.
- Polycarbonate:Optical clarity retains share in quality control workflows requiring visual inspection.
- Glass:Borosilicate alternatives persist in analytical applications where chemical inertness exceeds thermal shock concerns.
- Silicone:Gasket and seal components complete container-closure systems.
Polypropylene commands current volume. Fluoropolymer captures margin expansion.
Application:
Regulatory clarity is redrawing segment boundaries between research-grade and GMP-specified demand.
- Biobanking:Longitudinal sample archives drive consistent procurement cadence across European reference networks. ISO 20387 quality management protocols cascade into consumables specifications that disqualify non-compliant suppliers.
- Cellular Therapy:Cryopreserved starting materials for CAR-T and stem cell products require validated container-closure integrity. FDA enforcement of container-closure standards is tightening qualification documentation requirements.
- Genomics:Nucleic acid archive scaling is expanding fastest among application segments.
- Pharmaceutical Research:Drug discovery biobanks maintain steady demand for standard-grade formats.
- Diagnostics:Clinical reference laboratories specify traceable lot documentation for regulatory submissions.
Biobanking anchors stability. Cellular therapy redefines premium tier requirements.
End User:
Procurement consolidation is compressing vendor counts across institutional categories.
- Biopharmaceutical Firms:Cell therapy manufacturers mandate full material disclosure and extractables validation. Group purchasing organization consolidation in France and Italy is displacing direct manufacturer relationships for multi-site research networks.
- Research Laboratories:Academic and government biobanks in the Netherlands prioritize ISO 20387 alignment in tender specifications. Automated decapping systems are filtering supplier pools to dimensionally compliant formats.
- Diagnostic Centers:Clinical laboratories balance cost containment against regulatory traceability.
- Academic Institutes:University biobanks face CSRD reporting pressure on consumables waste streams.
Biopharmaceutical firms set technical standards. Research laboratories drive volume consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cryogenic consumables manufacturing originated in post-war German polymer science clusters, where precision molding techniques developed for laboratory glassware transitioned to thermoplastics during the 1960s. This technical lineage established quality benchmarks that persist in current regulatory frameworks.
Germany
Centralized biobank networks in Heidelberg and Berlin drive standardized procurement volumes for polypropylene vials. The country's national pharmaceutical regulator enforces MDR traceability requirements that cascade into consumables documentation systems. Cleanroom molding facilities concentrate in Baden-Württemberg, where ISO 14644-1 Class 7 capacity serves pan-European cell therapy manufacturers.
United States
FDA container-closure integrity enforcement for cellular therapy manufacturing accelerates GMP-grade vial qualification timelines. Biopharmaceutical clusters in Massachusetts and California specify full material disclosure protocols from cryogenic consumables suppliers. The Boston-Cambridge corridor anchors demand for fluoropolymer variants in CAR-T production workflows.
Switzerland
Swissmedic oversight of therapeutic cell lines elevates procurement standards for zero-leachables storage formats. Biobanks in Basel and Zurich pilot RFID-enabled inventory tracking at the primary container level. The country's pharmaceutical manufacturing density supports premium-tier pricing for validated cryopreservation systems.
United Kingdom
Academic research clusters in Cambridge and Oxford maintain steady demand for standard-grade formats through consolidated university procurement frameworks. The Medicines and Healthcare products Regulatory Agency aligns with EMA guidance on cryopreserved starting materials. Automated decapping systems in the Crick Institute filter supplier pools to dimensionally compliant tube formats.
France
Group purchasing organization consolidation across hospital biobanks in Paris and Lyon displaces direct manufacturer relationships. The national health authority mandates ISO 20387 quality management compliance in centralized tenders for multi-site research networks. CSRD reporting requirements pressure academic institutes to specify biodegradable cryogenic formats in ESG-mandated procurement.
Cryogenic Vials and Tubes Market Competitive Environment
The competitive structure tilts toward diversified life science conglomerates with captive polymer science capabilities. Market concentration remains moderate, with tiered positioning separating GMP-validated suppliers from research-grade commodity producers. Three archetypes dominate: integrated cold-chain portfolio holders, specialized polypropylene formulators, and distribution-depth players serving academic clusters. Capacity expansion in cleanroom molding and strategic partnerships for digital traceability integration represent the dominant competitive moves.
Among integrated portfolio holders, Thermo Fisher Scientific occupies a position exemplifying cold-chain logistics leverage. Specialized formulators include Greiner Bio-One, which anchors the premium resin optimization segment. Distribution-focused competitors feature Corning Incorporated, representing the archetype of academic research cluster penetration. These three entities collectively illustrate the strategic segmentation between logistics integration, material science specialization, and channel depth.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Corning Incorporated |
| Greiner Bio-One |
| DWK Life Sciences |
| Merck KGaA |
| Sumitomo Bakelite |
| Sigma-Aldrich |
| VWR International |
| CELLTREAT Scientific Products |
| Others |
Value Chain & Pricing Dynamics
Centralized biobank procurement networks in Germany and France negotiate GMP-grade vial contracts through multi-year frameworks that compress spot-market volatility for qualified suppliers. This buyer concentration rewards ISO 20387-aligned manufacturers with pricing power while marginalizing non-certified competitors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates cryogenic consumables procurement. Price differentiation hinges on ISO 20387 certification tier and extractables validation depth, with GMP-grade fluoropolymer vials commanding substantial premiums over research-grade polypropylene. Cost compression in standard-grade segments is intensifying because REACH reformulation investments are transferring to buyers through volume rebates. Academic biobanks exhibit highest price sensitivity, whereas cell therapy manufacturers prioritize container-closure integrity over unit cost.
Supply Chain Analysis
Direct-to-biopharma channels handle GMP-grade demand, while distribution partners serve fragmented academic accounts. Manufacturing concentrates in Germany, Switzerland, and the United States, with cleanroom molding capacity anchored in Baden-Württemberg and Basel. Polypropylene resin supply draws from petrochemical complexes in Belgium and the Netherlands, with silicone gasket components sourced from specialized German compounders. Single-source vulnerability in ISO 14644-1 Class 7 production environments creates qualification bottlenecks that extend lead times for new market entrants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cryogenic vials and tubes market represents a late-cycle quality story where EMA cell therapy guidance is shifting procurement specifications toward validated container-closure systems with full material disclosure.
For Market Incumbents: Extend captive polymer science capabilities into fluoropolymer formulation to capture margin expansion in cell therapy applications. Backward integration into REACH-compliant resin grades defends against ECHA plasticizer restrictions while automated decapping compatibility requirements filter competitor pools. Capacity addition in Swiss cleanroom facilities secures proximity to high-value therapeutic cell line storage demand.
For New Entrants and Emerging Players: RFID-enabled inventory tracking systems offer a technology-first wedge into Swiss and Nordic biobank automation pilots. Nordic biobank consolidation presents the most penetrable geography, with standardized procurement specifications favoring documented ISO 20387 alignment. A go-to-market angle through laboratory information management system partnerships bypasses direct competition with established molders.
For Investors and Strategic Acquirers: Life science conglomerates with cold-chain logistics portfolios are the most active acquirers in this space, seeking captive consumables supply to complement temperature-controlled distribution networks. Acquisition targets include mid-cap European molders with qualified ISO 14644-1 capacity and documented extractables validation protocols. Watch EMA guidance expansion on cryopreserved starting materials as the signal for accelerated GMP-grade qualification demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Cleanroom Capacity Expansion | ISO 14644-1 Class 7 square meters in Baden-Württemberg serve pan-European cell therapy manufacturing demand. |
| Fluoropolymer Formulation Investment | Zero-leachables resin development captures premium pricing from Swiss therapeutic cell line biobanks. |
| RFID Traceability Integration | Automated inventory tracking at primary container level aligns with Swissmedic oversight requirements. |
| REACH Compliance Reformulation | ECHA plasticizer restrictions force material science investments that favor captive polymer capabilities. |
| Biobank Network Partnership | Centralized procurement through German reference hubs secures multi-year volume commitments. |
Study Parameters
Coverage spans Germany, Switzerland, the United States, the United Kingdom, and France, with primary inputs from each market cluster. The analysis combines structured interviews with biobank operations directors, cell therapy manufacturing executives, GPO contracts managers, and polymer science R&D leads with secondary validation from FDA container-closure guidance documents, EMA cryopreserved starting materials guidance, ISO 20387 biobank quality protocols, and REACH authorization procedure updates. Bottom-up demand modeling from biobank capacity expansion projects triangulates against top-down polymer consumption data.
Granularity-level modeling disaggregates volume and value across product type, material grade, application segment, and end-user category throughout the forecast period. The analytical framework incorporates treatment-line differentiation between research-grade and GMP-specified demand, regional regulatory cluster alignment with MDR and FDA enforcement patterns, and automation-readiness tier for robotic liquid handling compatibility. CAGRs derive from segment-specific demand elasticity coefficients applied to base-year procurement volumes.
The model holds under stable REACH authorization timelines and continued EMA cell therapy guidance enforcement; deviation in polymer feedstock volatility or cleanroom qualification delays would shift volume trajectories. Forecasts reflect documented assumptions regarding biobank infrastructure investment cadence and regulatory harmonization progress. Periodic stress-testing of base assumptions against ECHA rolling action plan updates and pharmacopoeial extractables chapter revisions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Tongue Depressors Market
Medical Supplies
Canada Hospital Supplies Market
Medical Supplies
Australia Hospital Supplies Market
Medical Supplies
Ostomy Care Market
Medical Supplies
Oral Syringes Market
Medical Supplies
Blood Collection Market
Medical Supplies
Bleeding Control Kit Market
Medical Supplies
Crutch Pads Market
Medical Supplies
Tracheostomy Tray Market
Medical Supplies
Respiratory Masks Market
Medical Supplies
Serological Pipettes Market
Medical Supplies
Global Adhesive Bandages Market
Medical Supplies
Sperm Processing Media Market
Medical Supplies
Oral Dosing Cups Market
Medical Supplies
Amniotic Membrane Market
Medical Supplies
Cryopreservation & Fertilization Media Market