
 Weather App Market | 2026-2036
Weather App Market Size, Share, and Industry Trends Forecast 2026-2036
Weather App Market Intelligence
App store distribution is fragmenting as platform fees and discovery algorithms force weather app developers toward direct-to-consumer web installations and OEM pre-load partnerships. The Weather Channel sustains brand recognition through broadcast-to-digital convergence and severe weather authority. Ventusky differentiates through high-resolution meteorological visualization layers that attract aviation and maritime professionals. Meteomatics anchors enterprise revenue with API-first architecture serving agricultural and energy trading clients.
A weather app constitutes a software application that ingests meteorological data from satellite, radar, ground station, and numerical weather prediction models to deliver location-specific forecasts, alerts, and visualizations through graphical interfaces with refresh intervals measured in minutes. These tools serve commercial and consumer purposes ranging from daily planning to critical operational decision-making in weather-exposed industries. Mobile deployment captures the largest user base given smartphone ubiquity, while cloud-based infrastructure enables the real-time data pipelines that power hyperlocal forecasting and push notification systems for severe weather alerts. Agriculture as an end-user segment represents the fastest-expanding margin pool as farm operators integrate precipitation and soil moisture analytics into automated irrigation and planting schedules.
Developers targeting the United States must navigate FCC requirements for emergency alert system integration alongside FDA-adjacent health advisories for heat and air quality indices. The EU AI Act imposes transparency obligations on machine learning models used for predictive weather analytics, while GDPR restricts granular location tracking essential for microclimate forecasting. Stakeholders must weigh regulatory compliance investments against the competitive advantage of proprietary data fusion algorithms as public meteorological APIs face usage restrictions and cost restructuring.
Market Dynamics
Precision agriculture is pulling weather apps into operational core systems as irrigation automation and planting algorithms demand sub-hourly precipitation data. Farm management platforms now embed meteorological APIs directly, bypassing standalone consumer interfaces.
Growth Catalysts
- EU AI Act transparency mandates:Algorithmic disclosure requirements for predictive models are accelerating investment in explainable forecasting architectures across European deployments.
- Agricultural digitization:Soil moisture sensors and automated irrigation systems require granular precipitation forecasts, embedding weather apps into farm operational technology stacks.
- Insurance-linked risk modeling:Parametric crop and property insurers in the United States subscribe to hyperlocal severe weather data for automated claims triggers.
Market Restraints
- GDPR location tracking restrictions:Granular geolocation consent requirements in Europe limit microclimate forecasting accuracy and user retention metrics.
- Public API cost restructuring:National meteorological services are imposing usage fees and rate limits on data feeds that independent developers historically accessed freely.
- Platform fee extraction:Apple and Google app store commissions consume 15-30% of subscription revenue, compressing margins for direct-to-consumer monetization models.
Strategic Opportunities
- OEM pre-load partnerships:Smartphone manufacturers and automotive infotainment systems represent undervalued distribution channels with embedded default status.
- Aviation and maritime specialization:High-resolution wind shear and wave height visualizations command premium subscriptions from professional transport operators.
- FCC emergency alert integration:Regulatory mandates for wireless emergency alerts create mandatory placement opportunities for certified severe weather notification services.
Industry Challenges
- Atmospheric data science talent scarcity:PhD-level meteorologists with machine learning expertise command compensation premiums that strain mid-size development teams.
- Legacy broadcast-to-digital integration:Television weather franchises struggle to port brand authority and audience retention into mobile-first notification environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Weather App Market |
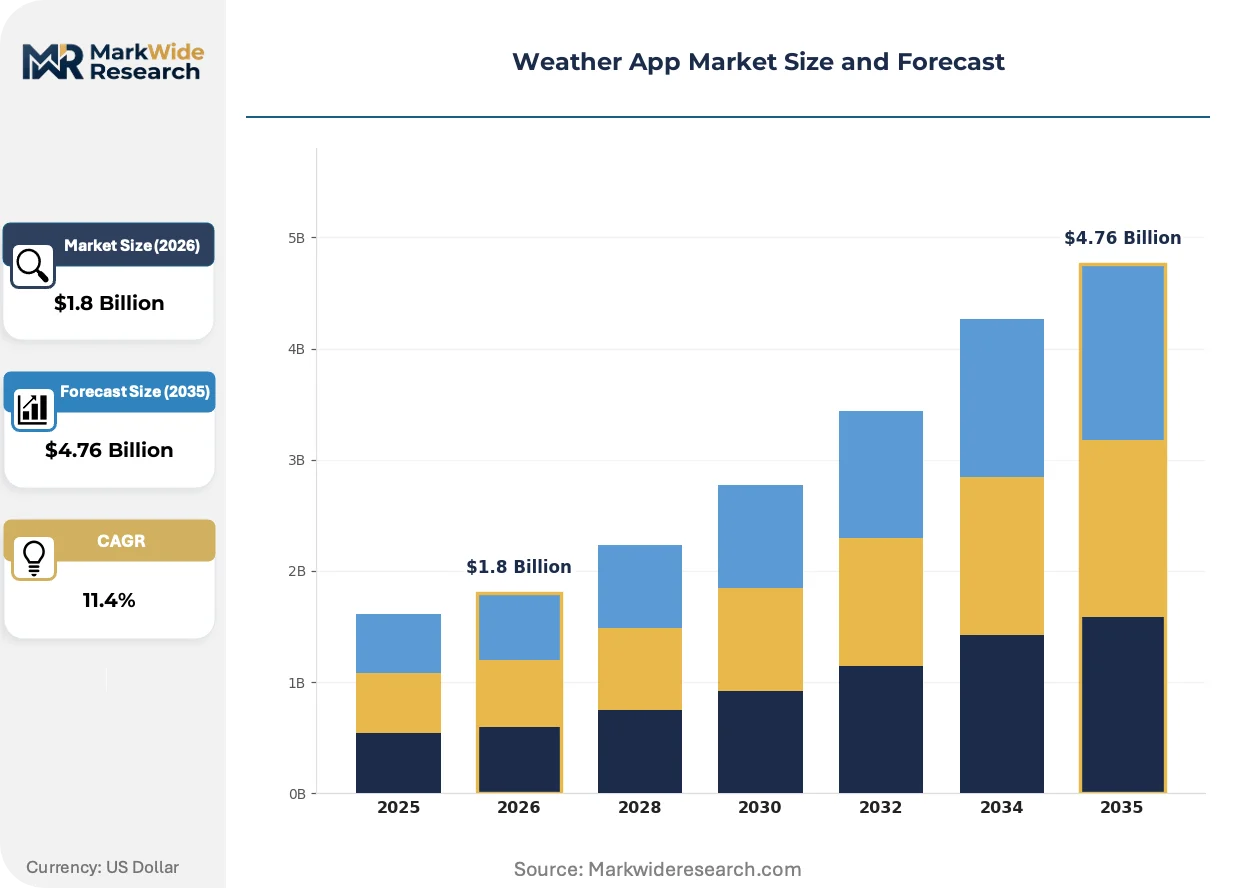
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Mobile, Desktop, Wearable, Smart Home End User: Individuals, Businesses, Agriculture, Government Deployment: Cloud-Based, On-Premise, Hybrid, SaaS Feature: Real-Time Updates, Forecasting, Alerts, Radar Maps |
| Companies Covered | Ventusky, Meteomatics, The Weather Channel, Sofar, PlanetIQ, Windy, ClimaCell, Understory, Sonuby Weather, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Weather App Market Strategic Shifts & Innovations
Machine learning is compressing forecast refresh intervals while multimodal data fusion—satellite, radar, IoT sensors—enables street-level microclimate prediction previously unattainable through public meteorological services alone.
Neural network ensembles trained on historical radar and satellite imagery are rendering obsolete traditional numerical weather prediction models for short-term precipitation nowcasting. Agricultural technology providers and logistics dispatchers adopt these systems within minutes of precipitation onset. The shift compresses competitive advantage to data latency rather than model sophistication.
The EU AI Act imposes documentation and human oversight requirements on automated forecasting systems deployed in European markets. Developers must maintain model cards explaining training data provenance and decision boundaries for regulatory inspection. Agricultural enterprise clients in Germany and France now require vendor compliance certification before API integration.
Enterprise procurement teams are unbundling weather data from bundled agricultural software suites, sourcing specialized meteorological APIs directly. Farm cooperatives and commodity trading desks negotiate standalone subscriptions with transparency into data lineage and update frequency. This pattern concentrates most visibly in the United States Corn Belt and Brazilian soybean regions where planting decisions carry million-dollar exposure.
Weather App Market Segmentation
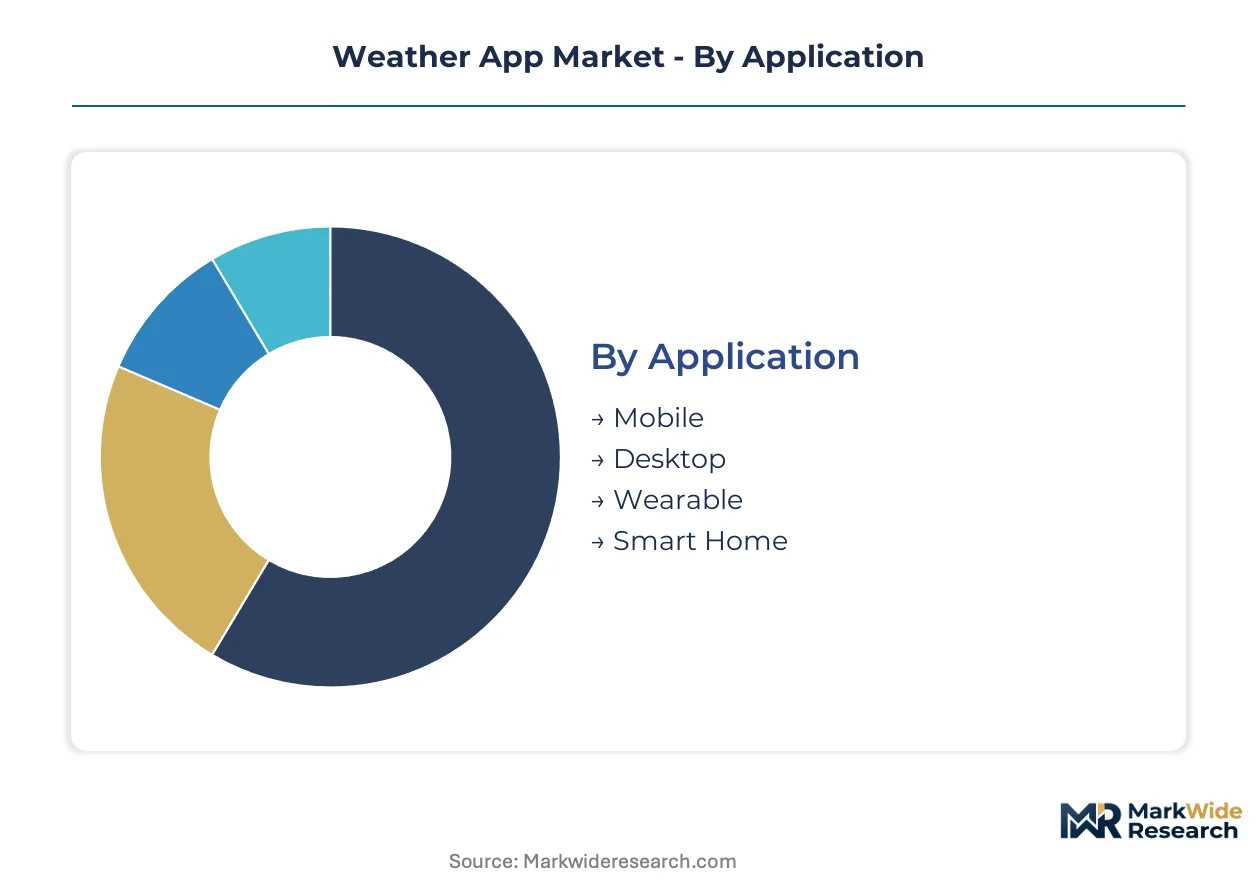
Weather app architectures diverge sharply across deployment contexts and user sophistication levels. The report maps four segmentation dimensions that determine pricing power, data infrastructure requirements, and regulatory exposure.
Application:
Mobile interfaces dominate daily consumer touchpoints, while specialized deployments command premium positioning in professional environments.
- Mobile:Native iOS and Android applications process push notifications through FCM and APNs infrastructure. United States carriers mandate wireless emergency alert integration for severe weather services, creating default placement advantages for certified providers.
- Desktop:Browser-based and native applications serve meteorologists, energy traders, and logistics dispatchers requiring multi-pane visualization. European enterprise procurement teams favor desktop deployments for GDPR-compliant data residency controls.
- Wearable:Apple Watch and Garmin integrations deliver glanceable precipitation alerts and UV index warnings. Battery constraints limit radar rendering, compressing functionality to notification-tier services.
- Smart Home:Alexa Skills and Google Assistant integrations vocalize morning briefings and severe weather warnings. Smart thermostat cross-selling generates ancillary revenue streams for HVAC-aligned providers.
The dominant share belongs to Mobile, while Smart Home is closing the gap fastest.
End User:
Customer archetypes span impulse-driven consumers to algorithm-dependent enterprise systems with divergent willingness-to-pay curves.
- Individuals:Freemium subscribers tolerate advertising in exchange for basic 7-day forecasts. Churn spikes during benign weather periods, compressing lifetime value calculations.
- Businesses:Logistics, construction, and event management operations subscribe to hourly precipitation probability feeds. United States parametric insurers embed these APIs into automated claims triggers.
- Agriculture:Precision farming platforms ingest sub-hourly soil moisture and evapotranspiration data. Farm cooperatives in Iowa and São Paulo states negotiate standalone API contracts bypassing bundled agritech suites.
- Government:National meteorological services and emergency management agencies procure redundant alert distribution channels. FCC certification requirements in the United States and EU AI Act transparency mandates in Europe reshape procurement specifications.
Agriculture claims the steepest expansion trajectory, while Government contracts deliver the most predictable renewal rates.
Deployment:
Infrastructure topology determines latency, compliance posture, and total cost of ownership for data-intensive forecasting workloads.
- Cloud-Based:AWS, Azure, and GCP deployments scale compute resources elastically during severe weather events. GDPR data residency requirements in Europe force regional instance provisioning.
- On-Premise:Defense and critical infrastructure operators air-gap meteorological systems from external networks. High capital expenditure limits adoption to classified and sovereign-sensitive applications.
- Hybrid:Edge nodes process radar interpolation locally while pushing archival data to centralized lakes. Maritime and aviation operators favor this architecture for connectivity-intermittent environments.
- SaaS:API-first vendors abstract infrastructure complexity behind per-call pricing. Agricultural technology providers and commodity trading desks in the United States Corn Belt dominate consumption volumes.
Cloud-Based architectures hold the installed base majority, though Hybrid deployments are gaining share fastest among industrial clients.
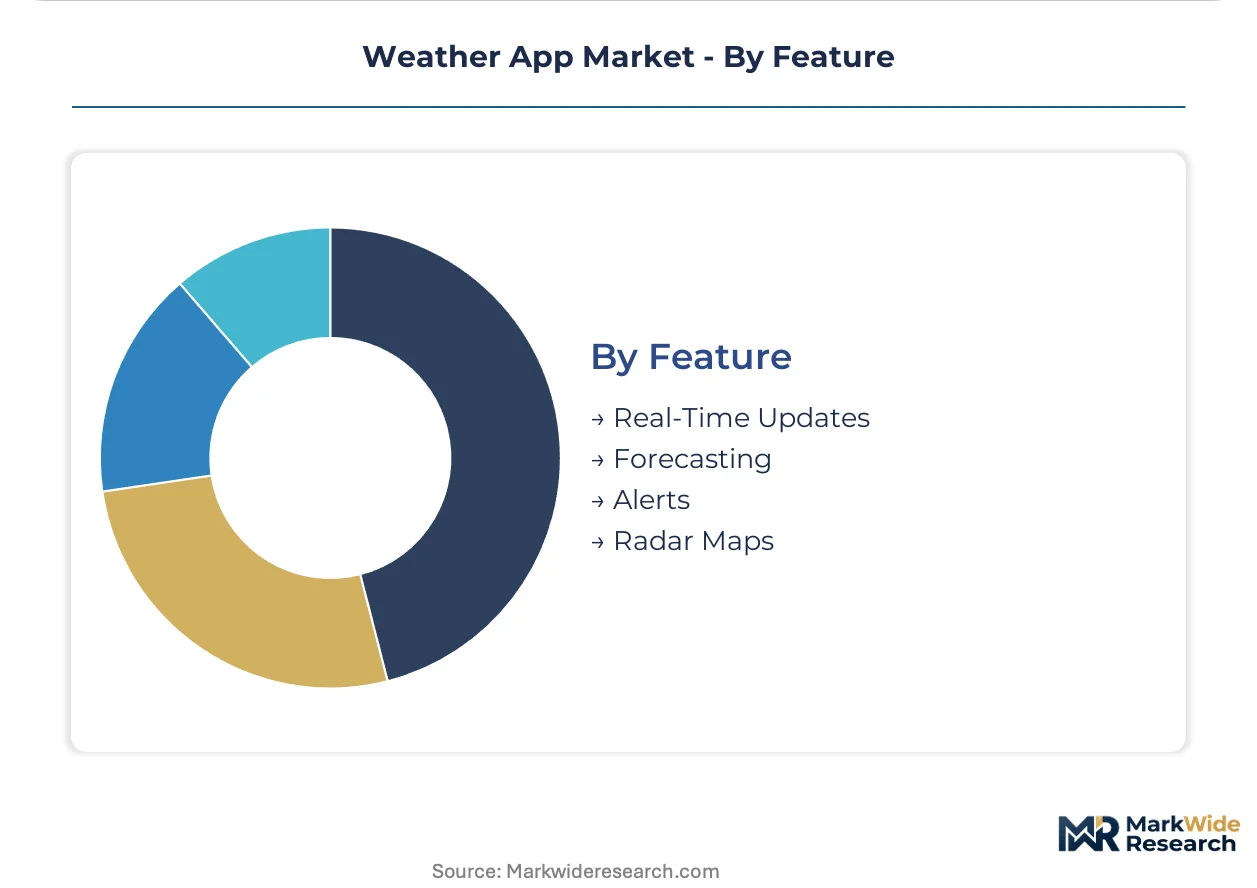
Feature:
Functional modules differentiate commodity forecasters from mission-critical decision support systems.
- Real-Time Updates:Sub-minute refresh intervals require WebSocket or MQTT streaming infrastructure. Severe weather authority services in the United States maintain FCC-mandated latency thresholds for tornado warnings.
- Forecasting:Neural network ensembles trained on historical radar nowcast precipitation 0-6 hours ahead. EU AI Act documentation requirements in Germany and France force model card maintenance for European deployments.
- Alerts:Push notification systems with location-based geofencing trigger evacuation advisories. Battery optimization tradeoffs on iOS and Android limit background location precision.
- Radar Maps:High-resolution Doppler visualization layers attract aviation and maritime professionals. Ventusky and similar specialists command 10-20x consumer pricing for these modules.
Forecasting capabilities anchor enterprise retention, while Radar Maps drive the fastest premium tier upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States wireless emergency alert infrastructure underwrites North American demand concentration, while European data residency requirements and Asian precision agriculture investments reshape regional deployment patterns.
United States
Severe weather alert infrastructure and parametric insurance-linked risk modeling drive enterprise subscription volumes. FCC mandates for wireless emergency alert integration create regulatory placement advantages for certified notification services. The Corn Belt spanning Iowa, Illinois, and Indiana concentrates agricultural API procurement as farm cooperatives negotiate standalone meteorological data contracts.
Germany
EU AI Act transparency obligations and GDPR-compliant data residency controls reshape enterprise procurement specifications for predictive forecasting models. The country's national meteorological regulator enforces strict documentation requirements for algorithmic weather systems. Bavaria anchors precision farming technology adoption with farm management platforms embedding sub-hourly precipitation analytics.
China
Dual carbon goals and renewable energy grid integration accelerate demand for hyperlocal wind and solar irradiance forecasting. The Ministry of Ecology and Environment imposes data localization requirements on meteorological services processing atmospheric information. The Yangtze River Delta clusters smart agriculture deployments where automated irrigation systems ingest soil moisture predictions.
Brazil
Soybean and sugarcane commodity trading desks subscribe to granular precipitation feeds for planting and harvest timing decisions. ANVISA-aligned health advisories for heat stress monitoring intersect with agricultural worker safety regulations. São Paulo state concentrates farm cooperative procurement as producers bypass bundled agritech suites for specialized API contracts.
India
Monsoon-dependent agricultural operations and expanding parametric crop insurance penetration drive API-first meteorological service adoption. The Central Electricity Authority mandates renewable energy forecasting accuracy standards for grid-connected solar and wind assets. Maharashtra and Gujarat cluster precision farming deployments where automated planting algorithms demand sub-hourly rainfall data.
Weather App Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream with raw data feeds and visualization engines. The vendor base stratifies across broadcast-to-digital franchises, API-first infrastructure providers, and specialized visualization layer developers. Three archetypes dominate: severe weather authority services leveraging regulatory certification, agricultural enterprise API vendors with embedded operational technology integration, and high-resolution visualization specialists serving aviation and maritime transport operators. Competitive moves concentrate on OEM pre-load partnerships for default placement status and direct-to-consumer web installations bypassing platform fee extraction.
Among broadcast-to-digital franchises, The Weather Channel occupies a position exemplifying severe weather authority convergence. Within the API-first infrastructure tier, Meteomatics and ClimaCell represent archetypes of embedded agricultural and energy trading service models. Ventusky anchors the specialized visualization segment with high-resolution meteorological layer offerings. These three entities collectively illustrate the competitive divergence between consumer-facing notification services and enterprise-grade operational data feeds.
| Leading Market Players |
|---|
| Ventusky |
| Meteomatics |
| The Weather Channel |
| Sofar |
| PlanetIQ |
| Windy |
| ClimaCell |
| Understory |
| Sonuby Weather |
| Others |
Cost & Logistics Intelligence
Silicon Valley cloud infrastructure clusters anchor the upstream compute capacity that weather app developers lease for real-time radar processing, concentrating pricing leverage among hyperscalers and compressing margin flexibility for API-first vendors downstream.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates the market. Enterprise agricultural subscriptions in the United States Corn Belt command the highest tier through sub-hourly soil moisture analytics and automated irrigation integration. Consumer freemium tiers face compression from platform fee extraction at Apple and Google app stores. Price differentiation rests on data refresh frequency and regulatory certification status, with EU AI Act-compliant vendors in Germany and France capturing premium positioning. Agricultural cooperatives exhibit lowest price sensitivity given million-dollar planting exposure, while individual consumers churn rapidly during benign weather periods.
Supply Chain Analysis
Tariff exposure between the United States and China for satellite componentry dominates supply chain risk assessment for hardware-dependent sensor networks. Meteorological data pipelines draw from United States National Oceanic and Atmospheric Administration feeds, European Centre for Medium-Range Weather Forecasts archives, and private satellite operators in Canada and Japan. Raw material dependencies include gallium arsenide for radar sensors, lithium for IoT ground station batteries, and specialized optical components for hyperspectral imaging. Single-source vulnerability concentrates in United States government satellite downlink infrastructure. Distribution runs through API gateways for enterprise clients and app store marketplaces for consumer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Native operating system weather widgets and voice assistant integrations threaten standalone app relevance, forcing incumbents to defend embedded utility through operational technology integration.
For Market Incumbents: Insulate core revenue by deepening API embedment into farm management platforms and energy trading systems. Pursue FCC emergency alert certification to secure default placement on United States carrier devices. Counter platform fee extraction through direct-to-consumer web installation campaigns and OEM pre-load negotiations with automotive infotainment suppliers. For New Entrants and Emerging Players: Pursue maritime and aviation specialization where high-resolution wind shear visualization commands 10-20x consumer pricing. Target Brazilian soybean cooperatives and Indian monsoon-dependent farm operations where bundled agritech suite unbundling creates white-space. Lead with hybrid edge-cloud architectures addressing connectivity-intermittent environments. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among API-first infrastructure providers serving agricultural and energy trading clients. Long-term viability favors vendors with explainable forecasting architectures compliant with EU AI Act transparency mandates. Acquisition target archetype: specialized visualization layer developers with aviation certification. Signal to watch: enterprise procurement teams unbundling weather data from bundled software suites.| Strategic Initiative | Industry Significance |
|---|---|
| OEM Pre-Load Partnership | Secures default placement status on Samsung and automotive infotainment systems bypassing app store discovery algorithms. |
| EU AI Act Compliance Certification | Enables German and French agricultural enterprise procurement requiring documented model cards for predictive forecasting systems. |
| Direct-to-Consumer Web Installation | Eliminates 15-30% platform fee extraction compressing margins on subscription revenue for standalone weather services. |
| Aviation Visualization Layer Development | Captures premium subscriptions from professional transport operators requiring high-resolution wind shear and turbulence data. |
| FCC Emergency Alert Integration | Mandates wireless emergency alert certification creating regulatory placement advantages for severe weather notification services. |
Research Approach
The analysis maps mobile deployment, desktop visualization, wearable integration, and smart home voice interfaces, each validated through meteorological data scientists, agricultural technology procurement officers, aviation dispatch operators, and emergency management officials. Primary interviews with API product managers at enterprise weather vendors and farm cooperative technology directors combined with secondary validation against FCC regulatory filings, EU AI Act implementation guidance, National Oceanic and Atmospheric Administration data service agreements, and app store revenue disclosure patterns. Bottom-up subscription volume estimates and top-down addressable market sizing triangulated through cross-reference.
Assumption sets held fixed the regulatory compliance cost trajectory for EU AI Act documentation requirements and GDPR data residency controls while varying agricultural digitization penetration rates and parametric insurance adoption curves across the projection horizon. Segmentation dimensions modeled include application interface type, end-user archetype from individual consumers to government agencies, deployment topology from cloud to hybrid edge, and feature module differentiation from basic forecasting to radar visualization. CAGRs derived through historical subscription growth pattern analysis and forward-looking API call volume projections. Industry-specific forecast inputs incorporated soil moisture sensor deployment densities and automated irrigation system adoption rates.
Macroeconomic conditions sit as an overlay; deviation in agricultural commodity price cycles and renewable energy investment flows would shift the trajectory for enterprise subscription demand. Forecasts reflect documented assumptions about regulatory enforcement intensity and public meteorological API cost restructuring. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Space and Workplace Management Software Market
Digital Solutions
Predictive Maintenance Software Market
Digital Solutions
Digital Workplace Technologies Market
Digital Solutions
Global BYOD and Enterprise Mobility Market
Digital Solutions
Returnless Refund Fraud Detection Market
Digital Solutions
APAC Digital Signage Market
Digital Solutions
Global Digital Workplace Software Market
Digital Solutions
Online Hyper-Local Services Market
Digital Solutions
Digital Assistant Market
Digital Solutions
Kubernetes Solutions Market
Digital Solutions
Enterprise Imaging Solutions Market
Digital Solutions
Mobile Collaboration Market
Digital Solutions
Voice Picking Headset Market
Digital Solutions
Global Computer Aided Dispatch Market
Digital Solutions
Global Digital Accessibility Software Market
Digital Solutions
Mobile Marketing Market