
 Global Digital Workplace Software Market | 2026-2036
Global Digital Workplace Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Digital Workplace Software Market Foresight
Subscription-based software-defined workspace orchestration is expanding as the primary commercial model, bundling virtual desktop delivery with automated lifecycle management. Citrix leverages its virtualization heritage to anchor enterprise deployments across regulated sectors. IBM competes through hybrid cloud integration, while NTT Data dominates managed workplace services across Asia-Pacific markets.
Digital workplace software encompasses integrated platforms that unify collaboration tools, identity management, and endpoint virtualization through API-driven architectures supporting zero-trust security frameworks. Its commercial purpose centers on decoupling employee productivity from physical infrastructure while enforcing governance policies. Cloud deployment leads solution delivery, though hybrid configurations capture the fastest expansion as organizations retain sensitive workloads on-premises. Workflow automation and virtual desktop segments concentrate margin pools where integration complexity creates vendor stickiness.
The EU AI Act, GDPR, and ISO 27001 standards collectively shape product roadmaps by mandating algorithmic transparency and data residency controls. The SEC's cybersecurity disclosure rules and Japan's METI data governance guidelines further constrain cross-border SaaS architectures. Stakeholders must monitor regulatory divergence between jurisdictions to avoid compliance-driven fragmentation of unified workspace strategies.
Market Dynamics
Zero-trust security architectures are compressing vendor consolidation timelines as enterprises abandon perimeter-based network models for identity-centric access controls. This structural shift rewards platform vendors with native security integration over point solutions requiring complex stitching.
Growth Catalysts
- EU AI Act compliance mandates:Algorithmic transparency requirements for automated decision-making systems are forcing financial services and healthcare institutions to upgrade workplace platforms with built-in audit trails.
- India's PLI scheme for IT hardware:Domestic manufacturing incentives are reducing endpoint device costs and accelerating virtual desktop infrastructure refresh cycles among mid-market enterprises.
- Endpoint virtualization:Decoupling compute from physical hardware is enabling bring-your-own-device policies that slash capital expenditure while maintaining centralized governance.
Market Restraints
- Cross-border data residency friction:GDPR's strict territoriality rules and China's data localization laws fragment cloud architectures, forcing vendors to maintain redundant regional infrastructure.
- Specialized identity management talent scarcity:Shortage of engineers certified in zero-trust implementation is extending deployment timelines and inflating professional services costs.
- Legacy application virtualization limits:Monolithic ERP systems lacking API surfaces resist containerization, trapping workloads on aging on-premises infrastructure.
Strategic Opportunities
- Germany's Industrie 4.0 workforce modernization:Manufacturing sector adoption of augmented reality-enabled digital workplaces for shop-floor technicians remains underpenetrated relative to white-collar deployments.
- Convergence of AI copilots with workflow automation:Natural language interfaces embedded directly into productivity suites are creating new pricing tiers and usage-based revenue models.
- Japan's METI data governance guidelines:Explicit vendor certification pathways for cross-border SaaS are reducing compliance uncertainty and accelerating procurement decisions.
Industry Challenges
- ISO 27001 certification backlog:Extended audit queues are delaying go-live dates for security-conscious buyers, compressing vendor revenue recognition timelines.
- Multi-cloud orchestration complexity:Enterprises distributing workloads across AWS, Azure, and Google Cloud require abstraction layers that increase integration testing overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Digital Workplace Software Market |
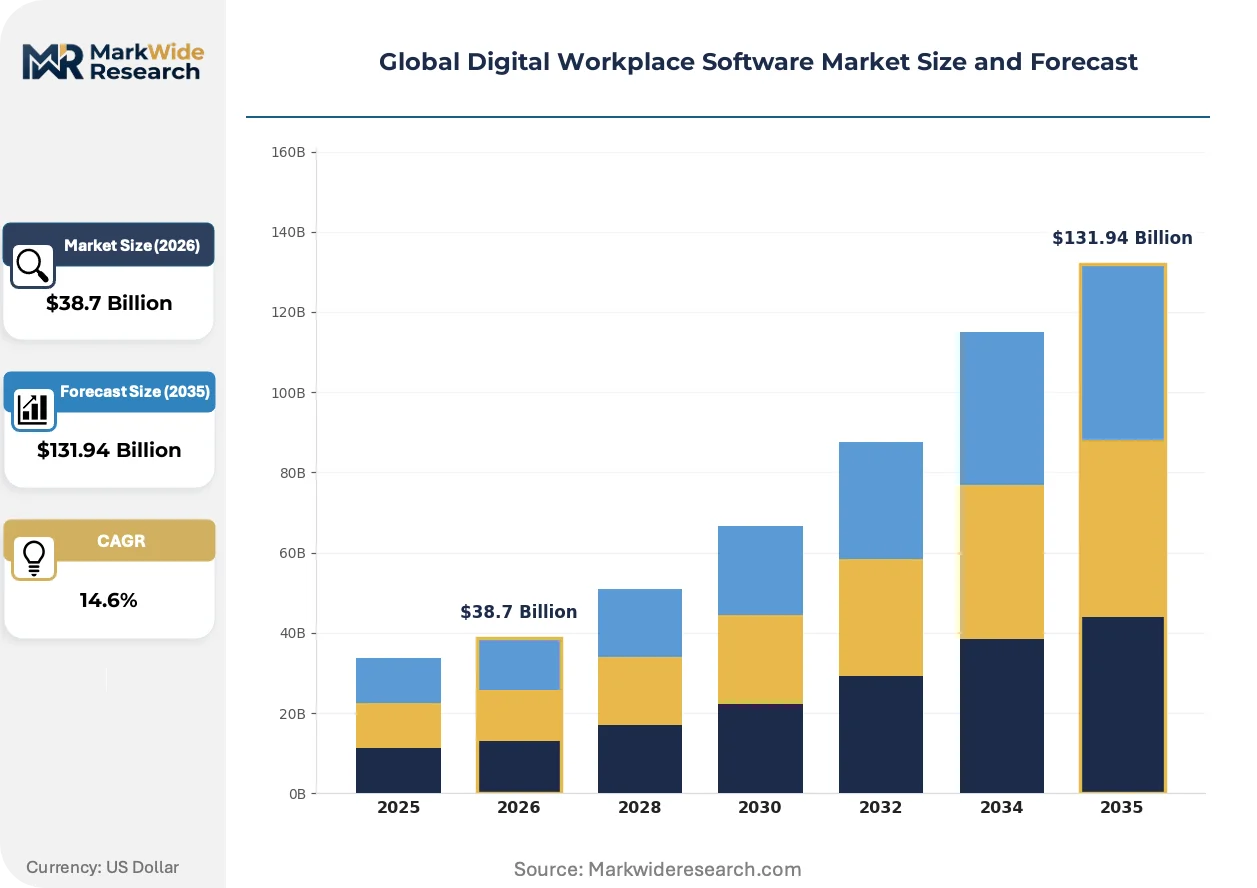
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $131.94 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud, On-Premises, Hybrid, Hosted Solution Type: Collaboration, Knowledge Management, Employee Engagement, Workflow Automation, Virtual Desktop Use Case: Remote Work Enablement, Project Management, Workforce Productivity, Internal Communication, IT Service Management End User: Small & Medium Enterprises, Large Corporations, Government Agencies, Educational Institutions, Non-Profit Organizations |
| Companies Covered | DXC Technology, Citrix, IBM, Capgemini, Unisys, Atos, NTT Data, Cognizant, Wipro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Digital Workplace Software Market Shifts & Advancements
Generative AI integration is electrifying user interface paradigms across workplace platforms, shifting interaction models from menu-driven navigation to conversational command structures. This transformation compresses training requirements while expanding addressable user bases.
Edge computing architectures are electrifying latency-sensitive workplace applications by processing voice and video streams closer to endpoints. Financial trading floors and healthcare emergency departments are deploying these configurations to eliminate round-trip delays to centralized clouds. The technology is electrifying competitive positioning for vendors with distributed infrastructure footprints versus hyperscale-only competitors.
The SEC's cybersecurity disclosure rules are mandating material incident reporting within four business days, forcing publicly traded buyers to prioritize platforms with native security information and event management integration. This regulatory pressure is accelerating replacement of legacy collaboration tools lacking audit-grade logging capabilities. Financial services and critical infrastructure operators face the steepest compliance burdens.
Consumption-based licensing is displacing seat-based contracts as the dominant commercial model, aligning vendor revenue with actual platform utilization. Mid-market enterprises in the United States and Germany are driving this shift, demanding granular metering of virtual desktop hours and automated workflow executions. Channel partners are restructuring compensation frameworks to accommodate recurring revenue recognition rather than upfront perpetual license recognition.
Global Digital Workplace Software Market Segmentation
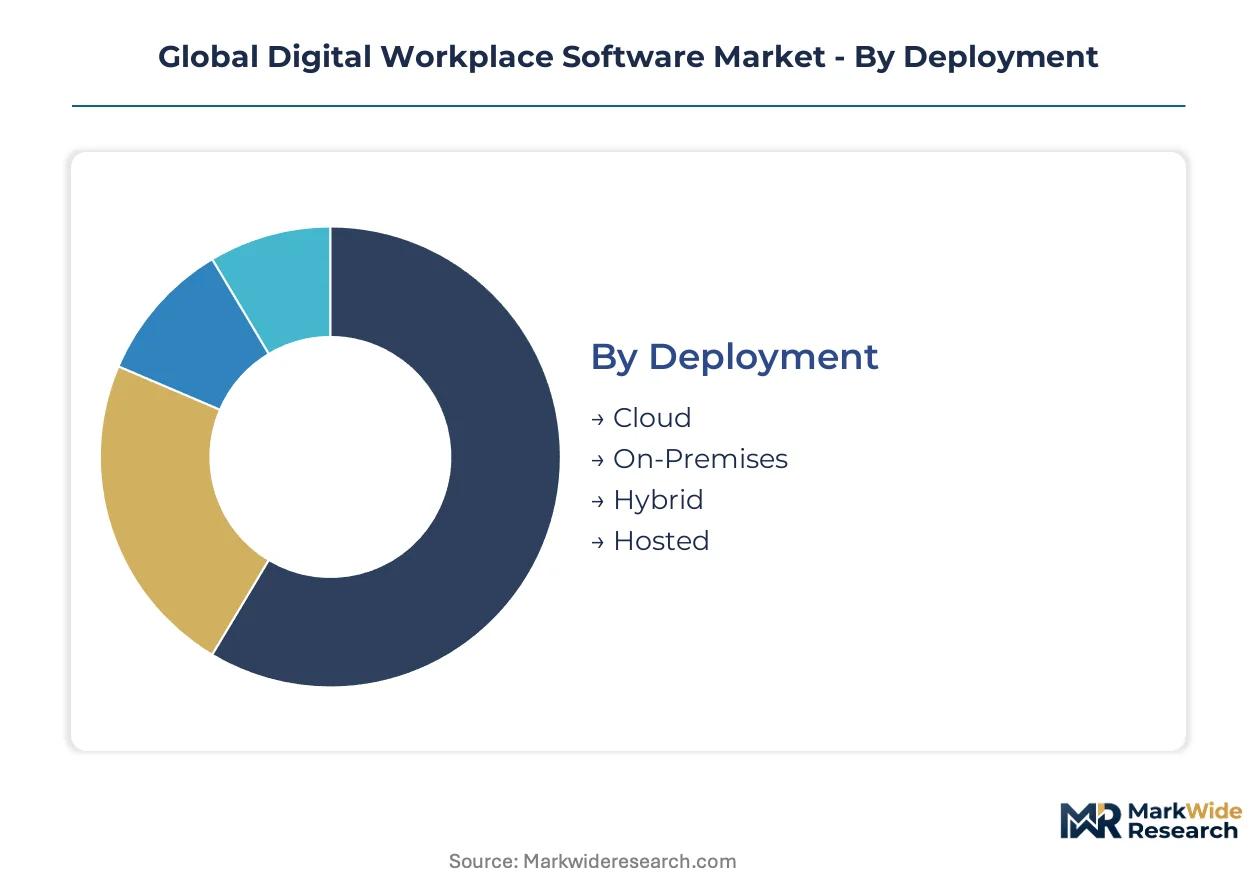
Digital workplace software procurement follows distinct technical and organizational logics that reshape vendor go-to-market strategies. Deployment architecture determines compliance posture and capital intensity, while solution type governs integration complexity and renewal economics.
Deployment:
Enterprise refresh cycles are compressing as zero-trust mandates force retirement of perimeter-dependent legacy stacks.
- Cloud:Multi-tenant SaaS delivery eliminates infrastructure ownership burdens. Financial services institutions in the United States and Germany are standardizing on cloud-native platforms to satisfy SEC cybersecurity disclosure rules and GDPR data residency requirements simultaneously.
- Hybrid:Sensitive workloads remain on-premises while collaboration tools shift to public cloud. India's mid-market enterprises favor this architecture to retain ERP systems locally while leveraging cloud-based virtual desktops, accelerated by PLI scheme hardware cost reductions.
- On-Premises:Complete infrastructure control for classified government environments and critical infrastructure operators.
- Hosted:Single-tenant managed deployments bridging compliance gaps for regulated healthcare providers.
Volume placements concentrate in Cloud; the faster expansion belongs to Hybrid.
Solution Type:
Margin pools align with integration depth, where workflow orchestration commands premium pricing over commoditized communication tools.
- Workflow Automation:Rules-based and AI-driven process orchestration connecting disparate enterprise applications. Manufacturing enterprises across Germany's Industrie 4.0 initiatives are deploying shop-floor automation layers that integrate with ERP and MES systems.
- Virtual Desktop:Centralized compute delivery decoupling endpoints from application hosting. India's IT services sector and United States healthcare systems are expanding VDI footprints to enable bring-your-own-device policies without sacrificing governance.
- Collaboration:Real-time messaging, video conferencing, and document co-authoring platforms.
- Knowledge Management:Enterprise search and institutional memory preservation systems.
- Employee Engagement:Pulse surveys, recognition platforms, and sentiment analytics tools.
Revenue concentration sits with Workflow Automation; Virtual Desktop is climbing the fastest as endpoint virtualization accelerates.
Use Case:
Application specificity determines implementation complexity and professional services attachment rates.
- Remote Work Enablement:Comprehensive platform stacks supporting distributed workforce productivity. Post-pandemic normalization has shifted procurement from emergency deployment to structured governance frameworks across United States and German enterprises.
- IT Service Management:Ticketing, asset management, and incident response automation. Japan's METI-certified vendors are capturing accelerated procurement cycles as explicit compliance pathways reduce vendor evaluation timelines.
- Project Management:Task allocation, resource scheduling, and milestone tracking systems.
- Workforce Productivity:Time tracking, output measurement, and performance analytics suites.
- Internal Communication:Corporate intranets, newsletters, and leadership broadcast channels.
Deployment scale favors Remote Work Enablement; IT Service Management is gaining share fastest on compliance tailwinds.
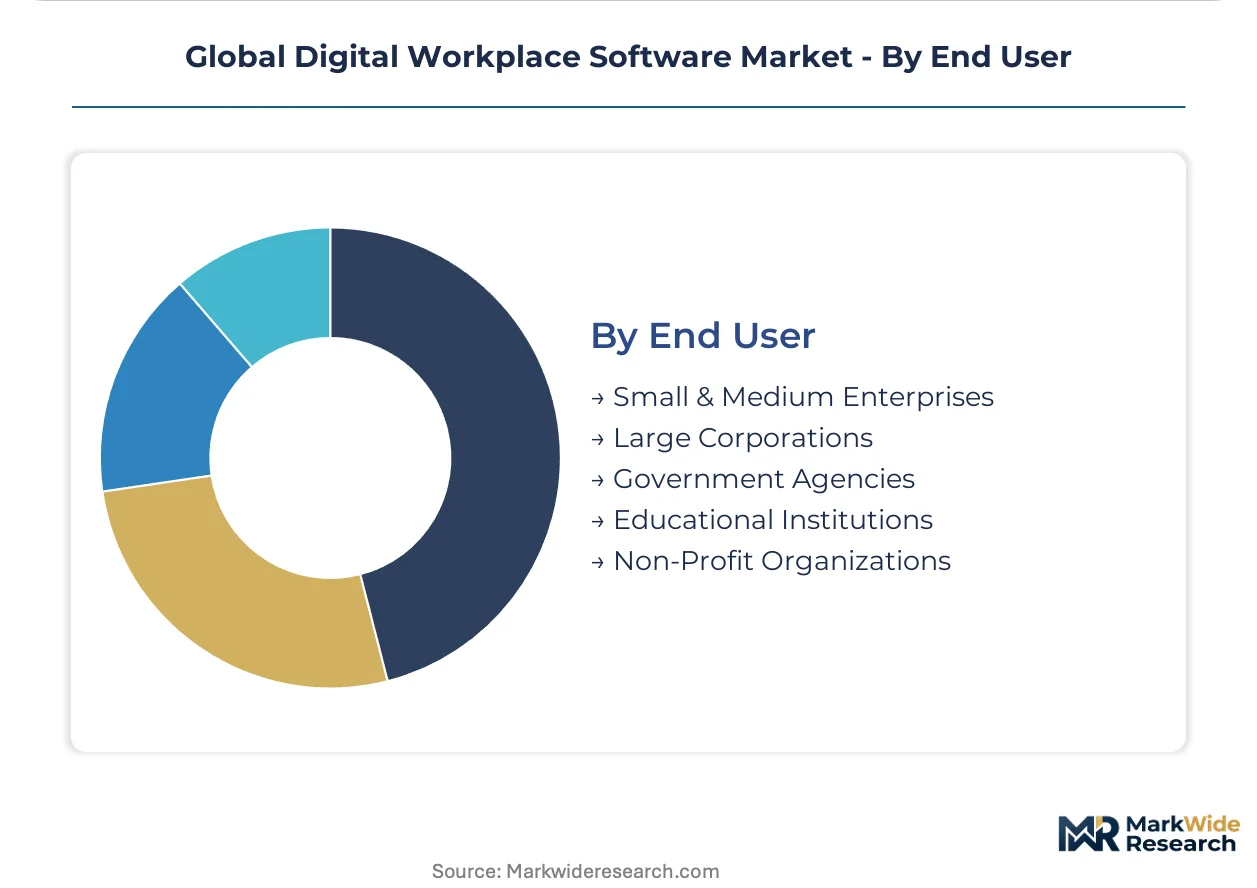
End User:
Customer scale dictates sales motion economics, from self-service provisioning to multi-year enterprise agreements.
- Large Corporations:Complex procurement involving security review boards and custom integration requirements. Multi-cloud orchestration demands across AWS, Azure, and Google Cloud environments are extending sales cycles while inflating annual contract values.
- Small & Medium Enterprises:Standardized packages with rapid deployment timelines. Consumption-based licensing adoption is most advanced here, with United States and German mid-market buyers driving granular metering of virtual desktop hours.
- Government Agencies:FedRAMP, ISO 27001, and jurisdiction-specific certification mandates.
- Educational Institutions:Semester-based procurement cycles with extreme price sensitivity.
- Non-Profit Organizations:Donation programs and grant-funded technology refresh initiatives.
Contract value concentrates in Large Corporations; Small & Medium Enterprises are expanding most quickly on consumption-model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software development concentrates in the United States, Germany, and India, while enterprise consumption spreads across financial services hubs in London, Singapore, and Dubai. Regulatory divergence between GDPR, SEC disclosure rules, and Japan's METI guidelines fragments vendor deployment architectures.
United States
Financial services institutions and healthcare systems drive cloud-native platform procurement. SEC cybersecurity disclosure rules mandate four-day incident reporting, forcing listed enterprises toward platforms with native SIEM integration. New York and Chicago trading floors deploy edge-computing workplace configurations to eliminate latency.
Germany
Manufacturing enterprises under Industrie 4.0 initiatives modernize shop-floor technician workspaces with augmented reality layers. GDPR data residency requirements and EU AI Act algorithmic transparency mandates shape vendor certification priorities. Bavarian automotive clusters and Ruhr industrial regions lead hybrid deployment adoption.
India
IT services sector expansion and mid-market enterprise modernization accelerate virtual desktop infrastructure refresh cycles. PLI scheme incentives for domestic hardware manufacturing reduce endpoint device costs. Bengaluru and Hyderabad technology corridors concentrate vendor delivery centers and managed workplace service operations.
Japan
Enterprise procurement accelerates under explicit METI data governance certification pathways for cross-border SaaS. Financial institutions and critical infrastructure operators prioritize vendors with pre-cleared compliance frameworks. Tokyo and Osaka metropolitan areas dominate IT service management platform deployment.
United Kingdom
Professional services firms and fintech clusters drive consumption-based licensing adoption for distributed workforce enablement. Post-Brexit regulatory divergence from EU frameworks creates dual compliance requirements for multinational enterprises. London financial district and Manchester technology hubs concentrate hybrid cloud workplace investments.
Global Digital Workplace Software Market Competitive Landscape
Capital-heavy systems integrators compete with asset-light pure-play software vendors for enterprise wallet share. Market structure tilts toward consolidation as zero-trust mandates compress vendor evaluation timelines. Three archetypes dominate: legacy virtualization specialists with installed-base leverage, hyperscale cloud integrators with managed service depth, and IT services conglomerates with geographic density. Competitive dynamics center on strategic partnerships for multi-cloud orchestration and vertical-specific compliance certifications.
Within the legacy virtualization tier, Citrix anchors enterprise deployments across regulated sectors through its heritage in application delivery infrastructure. IBM and NTT Data occupy distinct positions on the hybrid cloud spectrum—IBM through integration depth with enterprise middleware stacks, NTT Data through Asia-Pacific managed workplace service dominance. These three exemplify how vendor stickiness derives from integration complexity rather than point-solution functionality.
| Leading Market Players |
|---|
| DXC Technology |
| Citrix |
| IBM |
| Capgemini |
| Unisys |
| Atos |
| NTT Data |
| Cognizant |
| Wipro |
| Others |
Supply & Pricing Matrix
Consumption-based licensing adoption among United States and German mid-market buyers is compressing seat-based contract structures, forcing vendors to restructure channel compensation frameworks and invest in granular metering infrastructure to preserve margin capture.
Pricing Analysis
Margin tightening in virtual desktop infrastructure reflects hyperscaler compute cost pass-throughs and PLI scheme hardware subsidies in India. Pricing stratifies across premium zero-trust integrated tiers, standard cloud-native bundles, and economy hosted deployments. Cost compression accelerates in collaboration tools as Microsoft Teams and Slack commoditize real-time messaging. Small and medium enterprises exhibit highest price sensitivity, while large corporations absorbing multi-cloud orchestration complexity accept premium positioning.
Supply Chain Analysis
Cross-border data residency requirements are inflating regional infrastructure freight and redundancy costs as vendors replicate stacks across GDPR, China's data localization, and METI certification zones. Software development concentrates in the United States, Germany, and India, with delivery operations anchored in Bengaluru, Hyderabad, and Singapore hubs. Raw material dependencies center on hyperscaler compute capacity, endpoint device manufacturing, and specialized identity management engineering talent. Single-source vulnerability sits with AWS, Azure, and Google Cloud concentration. Distribution runs through systems integrators and managed service providers with vertical compliance expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Digital Workplace Software Market functions as a cost-of-compliance arena where EU AI Act algorithmic transparency mandates and GDPR data residency controls erect certification barriers that favor incumbents with pre-cleared audit frameworks.
For Market Incumbents: Deepen zero-trust native integration to defend against point-solution vendors requiring complex stitching. Invest in ISO 27001 certification pipeline acceleration to capture security-conscious buyers facing audit queue delays. Extend managed workplace service density across Asia-Pacific through NTT Data-style geographic footprint expansion. For New Entrants and Emerging Players: Launch via consumption-based metering models targeting German Industrie 4.0 manufacturing shop-floor deployments, the most underpenetrated segment relative to white-collar saturation. Target India's PLI-accelerated mid-market with virtual desktop bundles priced below hyperscaler direct offerings. Pursue METI pre-certification in Japan to compress procurement evaluation timelines. For Investors and Strategic Acquirers: The window for entry favors hybrid cloud integration specialists with existing enterprise middleware relationships and established FedRAMP or ISO 27001 credentials. Long-term viability hinges on workflow automation margin pools where API complexity creates vendor stickiness. Watch for SEC cybersecurity disclosure enforcement intensity as a signal for SIEM-integrated platform replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Zero-Trust Platform Integration | Consolidates identity-centric access controls into unified workspace stacks, displacing perimeter-dependent legacy vendors. |
| AI Copilot Workflow Embedding | Creates natural language command tiers that expand addressable user bases beyond technical specialists. |
| METI Certification Pre-Clearance | Accelerates Japanese enterprise procurement by eliminating cross-border SaaS compliance uncertainty. |
| Edge Computing Infrastructure Deployment | Eliminates latency for financial trading floors and healthcare emergency departments versus hyperscale-only competitors. |
| Consumption-Based Licensing Transition | Aligns vendor revenue with actual virtual desktop utilization, capturing mid-market price sensitivity. |
Research Methodology
Multi-period observation of vendor certification timelines, hyperscaler capex disclosures, and enterprise procurement cycle compression anchored the trend analysis, supplemented by interviews with CTOs, IT procurement officers, platform engineers, and channel partners across financial services, healthcare, and manufacturing verticals. Secondary validation drew from SEC filings, EU AI Act implementation guidance, METI certification databases, and ISO 27001 audit queue reports. Bottom-up deployment model sizing and top-down regulatory impact assessment were triangulated to cross-validate segment trajectories.
Input-output matrix modeling connected deployment architecture preferences, solution type margin structures, and end-user scale economics across the projection horizon. Segmentation dimensions spanned cloud-hybrid-on-premises deployment, workflow automation-virtual desktop-collaboration solution types, and large corporation-SME-government end-user tiers. CAGRs were derived from regression analysis against compliance mandate implementation schedules and PLI scheme hardware cost curves.
Regulatory divergence between GDPR, SEC disclosure rules, and China's data localization laws, alongside hyperscaler pricing volatility and identity management talent scarcity, are the dominant revision risks that could compress or extend vendor consolidation timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Agent-Oriented Enterprise Architecture Market
Digital Solutions
Harbor Management Software Market
Digital Solutions
Global Data Quality Tool Market
Digital Solutions
Europe Digital Marketing Software Market
Digital Solutions
Document Case Management (DCM) Market
Digital Solutions
End User Experience Monitoring (EUEM) Market
Digital Solutions
Digital Library Software Market
Digital Solutions
Real-Time (Graphics and Video) Rendering Solutions Market
Digital Solutions
Captioning and Subtitling Solutions Market
Digital Solutions
Europe Data Virtualization Market
Digital Solutions
Cloud Manufacturing Execution System (MES) Market
Digital Solutions
Data Integration Market
Digital Solutions
US Digital Signage Market
Digital Solutions
Enterprise Data Management Market
Digital Solutions
Mobile Resource Management Solutions Market
Digital Solutions
Remote Integration Solutions Market