
 Online Hyper-Local Services Market | 2026-2036
Online Hyper-Local Services Market Size, Share, and Industry Trends Forecast 2026-2036
Online Hyper-Local Services Market Analytics
Last-mile delivery networks is reconfiguring competitive economics across urban corridors. DoorDash Inc. dominates North American suburban penetration with algorithmic batching that sustains driver utilization rates. Grab Holdings Ltd. anchors Southeast Asian operations through super-app integration of transport, payments, and food delivery. Uber Technologies Inc. leverages its rideshare driver base to compete on variable cost structure across multiple continents.
Online hyper-local services coordinate geographically constrained service fulfillment through digital platforms matching decentralized labor supply with immediate consumer demand, typically executing delivery or service completion within a one-to-five kilometer radius using GPS tracking, dynamic pricing engines, and automated dispatch protocols. Food delivery commands the largest transaction volume among service type segments, though personal shopping exhibits faster growth as grocery and retail partnerships deepen. AI dispatching is displacing manual routing across technology segments, while subscription pricing models capture higher lifetime value from individual consumers and families compared to pay-per-service alternatives.
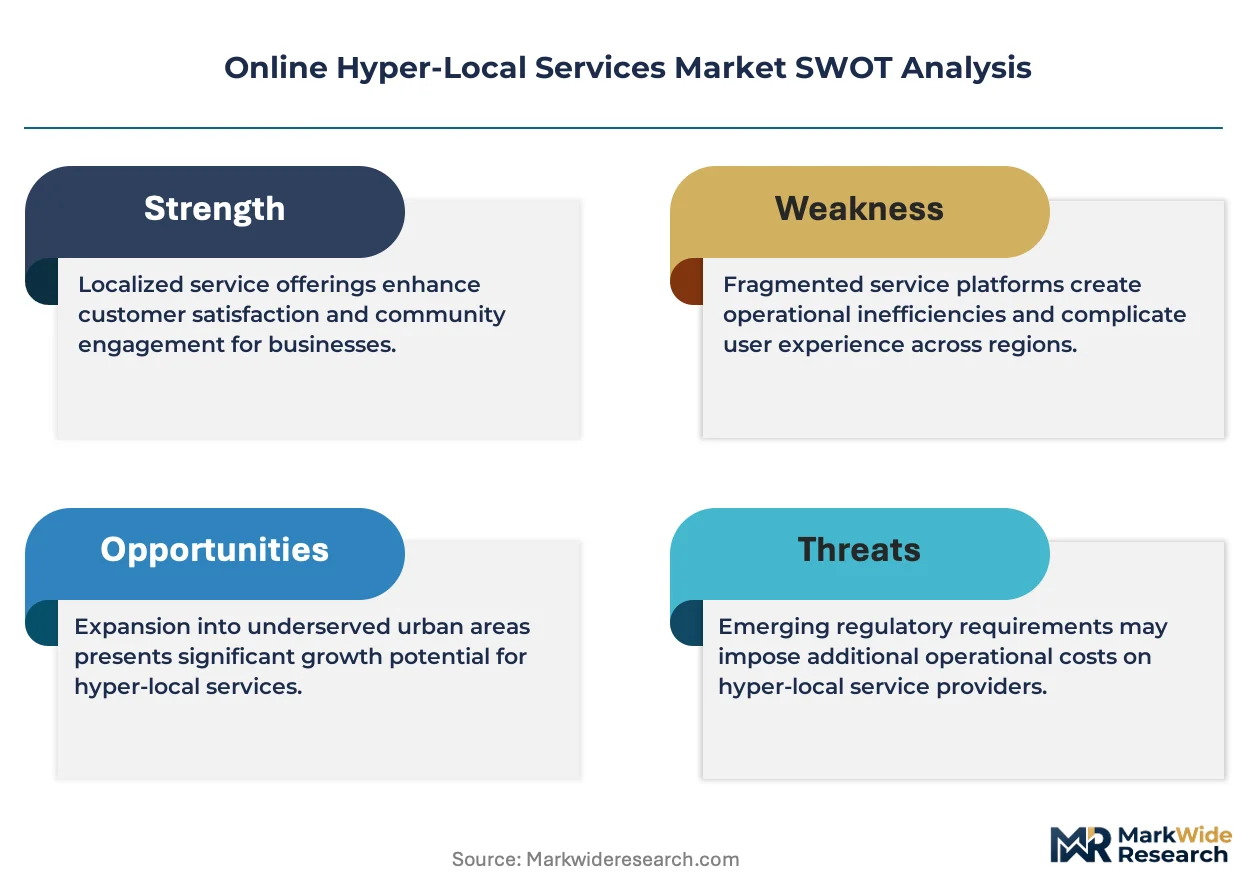
FDA food safety guidelines, EU GDPR data protection frameworks, and India's FSSAI hygiene certification requirements shape operational compliance burdens and platform liability exposure across key jurisdictions. OSHA delivery worker classification standards in the United States and emerging gig-economy labor regulations in Europe are forcing platform restructuring of contractor relationships and benefit obligations. Stakeholders must monitor regulatory divergence on worker classification and data localization mandates when allocating capital across geographic expansion priorities.
Market Dynamics
AI dispatching algorithms are compressing delivery windows below thirty minutes in dense metropolitan zones, forcing platforms to reconfigure labor economics and route density thresholds to sustain unit economics.
Growth Catalysts
- Smartphone penetration:India, Brazil, and Indonesia are concentrating demand as digital payment infrastructure expands and first-time users convert to platform adoption.
- FSSAI hygiene certification:India's food safety mandates are professionalizing kitchen operations and elevating consumer trust in digital food ordering.
- Real-time route optimization:GPS tracking and dynamic pricing engines are matching decentralized labor supply with immediate consumer demand across urban corridors.
Market Restraints
- OSHA delivery worker classification:United States regulatory standards are forcing platform restructuring of contractor relationships and benefit obligations.
- Input cost volatility:Fuel price fluctuations directly impact driver earnings and platform subsidy requirements in last-mile networks.
- EU GDPR data protection:European frameworks are imposing operational compliance burdens and platform liability exposure across cross-border data flows.
Strategic Opportunities
- Personal shopping expansion:Grocery and retail partnerships are deepening as platforms extend beyond food delivery into broader retail fulfillment.
- Subscription pricing models:Higher lifetime value capture from individual consumers and families is displacing pay-per-service alternatives.
- Brazilian digital payment growth:Expanding PIX infrastructure and smartphone adoption are opening underpenetrated urban service corridors.
Industry Challenges
- Gig-economy labor regulations:European emerging mandates are forcing operational reconfiguration of contractor benefit structures and employment classification.
- Data localization mandates:Divergent jurisdictional requirements on cross-border data storage are complicating platform architecture and capital allocation decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Online Hyper-Local Services Market |
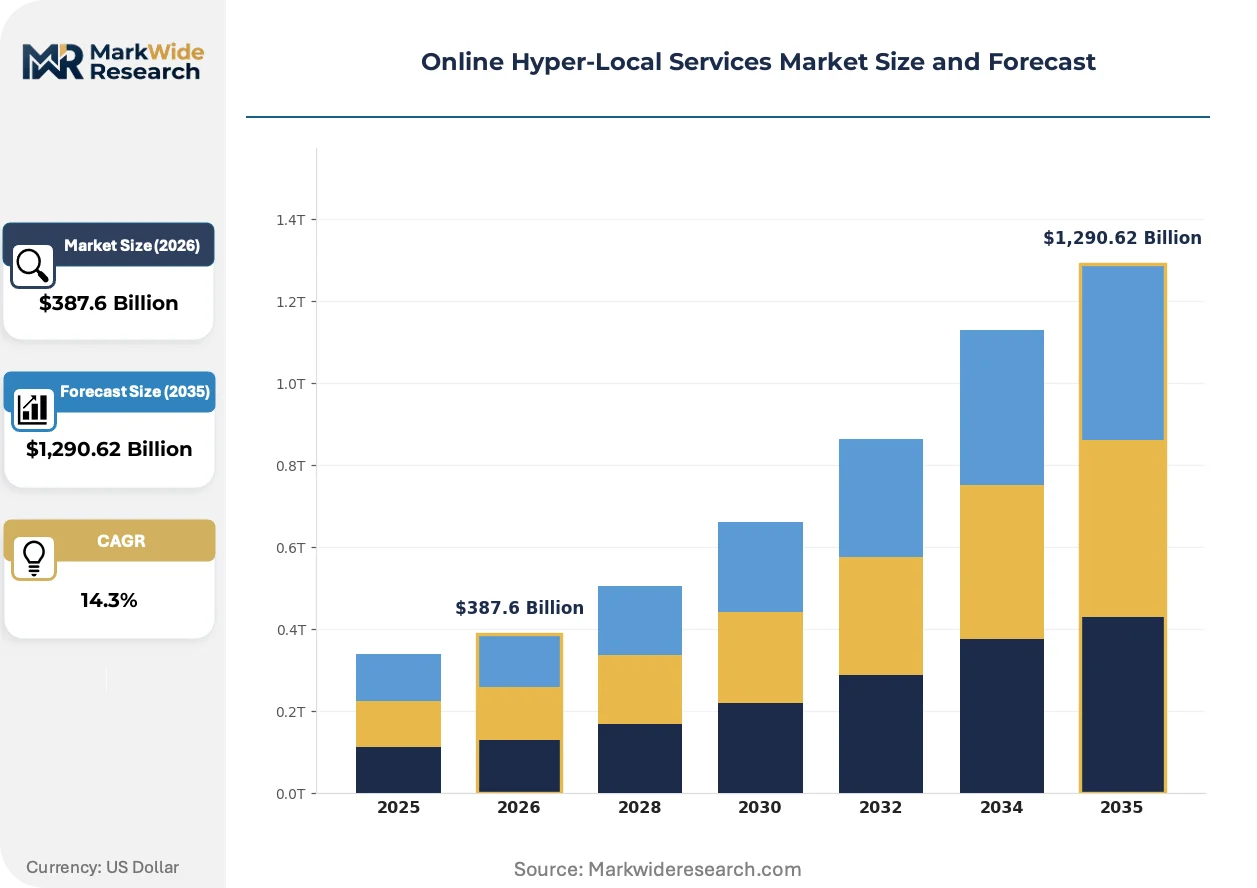
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $1,290.62 Billion |
| CAGR (2026 – 2036) | 14.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Food Delivery, Home Cleaning, Pet Care, Personal Shopping Technology: Mobile Apps, Web Platforms, Delivery Drones, AI Dispatching Customer Type: Individual Consumers, Small Businesses, Enterprises, Families Pricing Model: Subscription, Pay-per-Service, Tiered Pricing, Freemium |
| Companies Covered | Grab Holdings Ltd., Instacart Inc., DoorDash Inc., Rappi Inc., Grubhub Inc., Uber Technologies Inc., Zomato, Swiggy, Delivery Hero SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Online Hyper-Local Services Market Evolving Landscape
Algorithmic coordination of decentralized labor supply is compressing fulfillment windows and enabling new service categories beyond traditional food delivery.
Automated dispatch protocols are digitizing the matching of driver capacity with real-time demand spikes. Urban platforms are deploying these systems to sustain utilization rates during off-peak hours. The technology is digitizing route density economics and enabling sub-thirty-minute service guarantees in metropolitan cores.
GDPR data protection frameworks are reshaping platform liability for consumer location tracking and payment data storage. European operators face heightened compliance costs for cross-border data transfers. Food delivery segments with multi-jurisdiction operations are responding through localized server infrastructure and consent-management systems.
Subscription pricing is displacing transactional pay-per-service models among family households and high-frequency users. Platforms are bundling delivery fee waivers with priority service tiers to lock in recurring revenue. This shift is most visible in dense Indian and Southeast Asian metros where monthly order frequency exceeds fifteen transactions.
Online Hyper-Local Services Market Segmentation
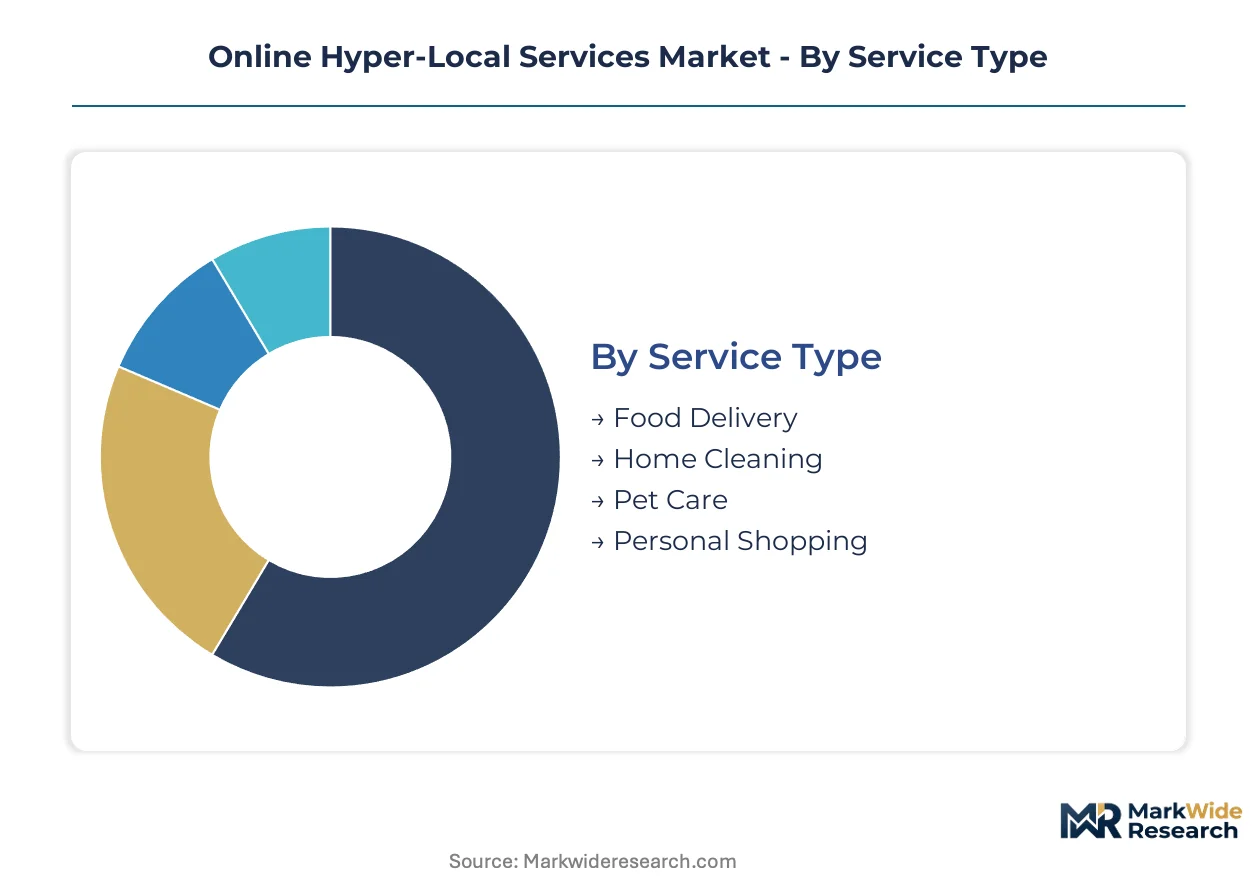
Hyper-local service platforms segment demand across multiple dimensions to optimize labor allocation, technology deployment, and pricing elasticity. Each segmentation axis reveals distinct margin profiles and capital intensity requirements that shape platform strategy.
Service Type:
Mature categories dominate transaction volume while emerging segments reshape platform economics through higher frequency and subscription attach rates.
- Food Delivery:Restaurant order aggregation with real-time kitchen coordination and driver batching algorithms. Dense Indian metros and Southeast Asian urban corridors generate the highest order frequency, though driver subsidy requirements compress margins during peak demand windows.
- Personal Shopping:Grocery and retail fulfillment extending platform infrastructure beyond prepared meals. Brazilian PIX-enabled corridors and Indonesian smartphone penetration clusters are accelerating adoption as inventory integration with supermarket chains deepens.
- Home Cleaning:Scheduled domestic services matching verified labor with residential demand. Background-check protocols and insurance requirements elevate operational overhead relative to delivery categories.
- Pet Care:Veterinary transport, grooming, and boarding coordination. Premium pricing tolerance among urban professional households supports higher service fees per transaction.
Food Delivery handles the majority of throughput; Personal Shopping is gaining share fastest as grocery partnerships mature.
Technology:
Customer-facing interfaces differentiate by acquisition cost while backend systems determine fulfillment speed and labor utilization.
- Mobile Apps:Native smartphone applications with push notification systems and biometric payment authentication. First-time user conversion in India, Brazil, and Indonesia concentrates here as smartphone penetration outpaces desktop access.
- AI Dispatching:Machine learning algorithms optimizing driver-job matching and route sequencing in real time. Dense metropolitan zones deploy these systems to sustain sub-thirty-minute guarantees and off-peak utilization rates.
- Web Platforms:Browser-based ordering portals retaining enterprise and small business customers with complex procurement workflows.
- Delivery Drones:Autonomous aerial systems for lightweight payloads in regulatory-permissive jurisdictions. FAA operational waivers and EU aviation frameworks constrain deployment scale.
Mobile Apps capture the largest user base; AI Dispatching shows the steepest expansion trajectory as platforms compete on speed guarantees.
Customer Type:
Volume concentration and pricing power diverge sharply between individual transaction seekers and contracted organizational accounts.
- Individual Consumers:Single-user accounts with variable frequency and high price sensitivity. Subscription pricing models target this segment to reduce churn and elevate lifetime value.
- Families:Multi-user household accounts with higher monthly order thresholds and stronger subscription conversion. Dense Indian and Southeast Asian metros with fifteen-plus monthly transactions anchor this segment.
- Small Businesses:Local retailers and offices procuring recurring delivery and maintenance services. Contracted relationships reduce per-transaction acquisition costs.
- Enterprises:Corporate accounts with centralized billing and service-level agreements. Catering and facilities management contracts extend platform revenue stability.
Individual Consumers generate the highest transaction count; Families exhibit the strongest subscription attach rates and retention metrics.
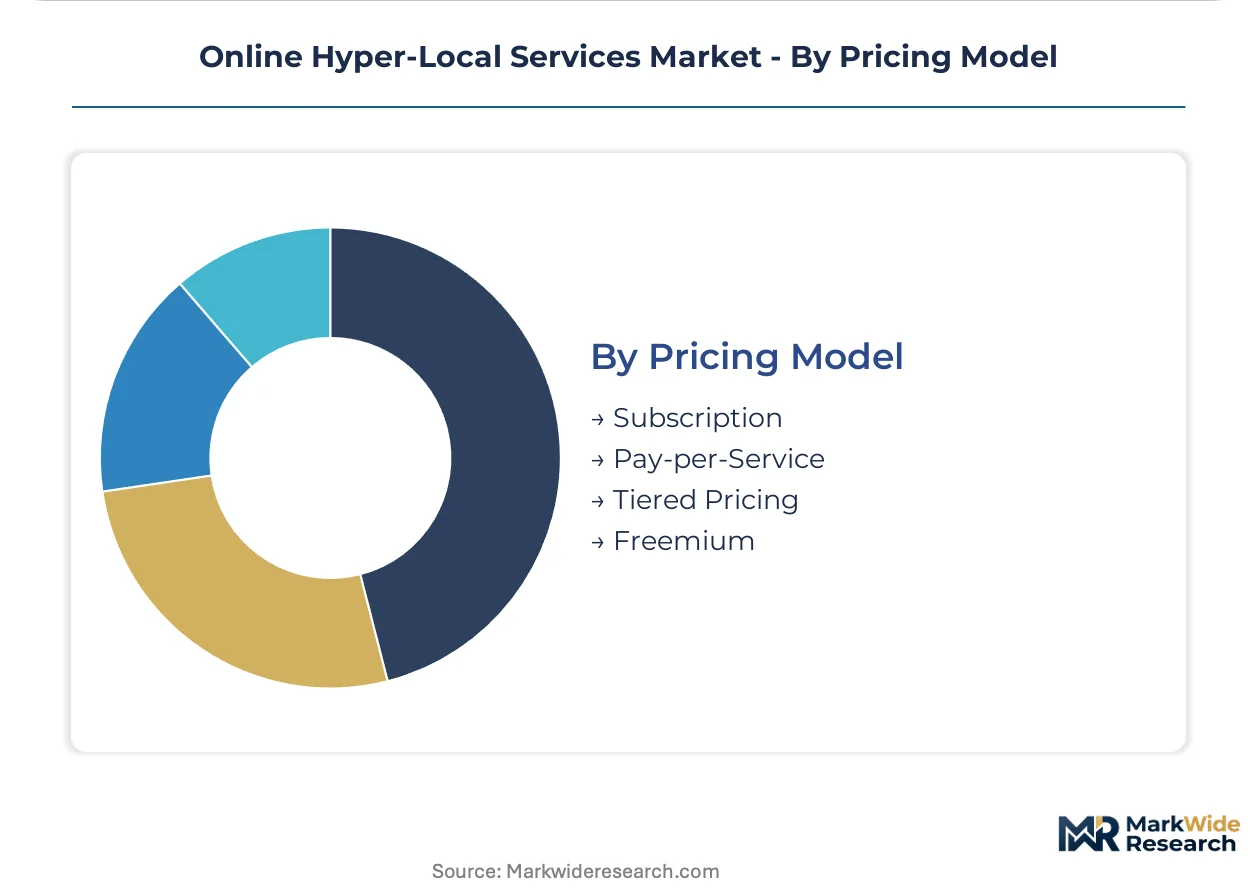
Pricing Model:
Revenue predictability and customer lifetime value trade off against acquisition friction and competitive flexibility.
- Subscription:Recurring monthly fees bundling delivery waivers and priority service tiers. High-frequency users in dense urban corridors convert most readily, displacing pay-per-service alternatives.
- Pay-per-Service:Transactional fees per order without commitment. Price-sensitive occasional users and trial adopters cluster here, elevating churn risk.
- Tiered Pricing:Premium-mid-economy differentiation based on delivery speed and service quality. Platforms deploy this structure to capture willingness-to-pay variation across income segments.
- Freemium:Basic service access with fee-based upgrades for expedited fulfillment or enhanced features. Conversion rates to paid tiers determine unit economics viability.
Subscription models secure the most predictable revenue streams; Tiered Pricing expands most quickly as platforms segment urban markets by service priority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FSSAI hygiene certification requirements in India anchor operational compliance frameworks across the dominant geography. Brazil's expanding PIX infrastructure and Indonesia's deepening smartphone penetration are accelerating platform adoption in high-growth corridors. Regulatory divergence on worker classification and data localization mandates complicates capital allocation decisions.
United States
OSHA delivery worker classification standards and state-level gig economy legislation are forcing platform restructuring of contractor relationships. FDA food safety guidelines shape operational compliance for prepared meal logistics. Dense metropolitan zones in California and New York deploy AI dispatching to sustain sub-thirty-minute delivery guarantees.
India
FSSAI hygiene certification mandates professionalize cloud kitchen operations and elevate consumer trust in digital food ordering. RBI digital payment infrastructure expansion accelerates first-time user conversion across tier-two cities. Mumbai and Bengaluru corridors generate the highest order frequency, though driver subsidy requirements compress margins during peak windows.
Brazil
Central Bank PIX instant payment infrastructure expansion opens underpenetrated urban service corridors for platform penetration. ANVISA food safety protocols govern prepared meal logistics compliance requirements. São Paulo and Rio de Janeiro metropolitan areas concentrate demand as smartphone adoption outpaces legacy banking access.
Indonesia
Bank Indonesia digital payment interoperability standards accelerate platform onboarding for first-time smartphone users. National food and drug regulatory frameworks impose hygiene certification burdens on restaurant partners. Jakarta and Surabaya urban corridors exhibit fastest personal shopping adoption as grocery retail partnerships deepen.
Germany
EU GDPR data protection frameworks impose operational compliance costs for cross-border consumer location tracking and payment data storage. KBA and federal labor authority gig economy regulations are emerging around contractor benefit structures. Berlin and Munich metropolitan zones deploy localized server infrastructure to satisfy data localization mandates.
Online Hyper-Local Services Market Competitive Landscape
Super-app integrators and specialized delivery platforms split the market across divergent geographic and service-type vectors. Consolidation pressures intensify as capital-intensive last-mile networks demand scale thresholds for unit economic viability. Three archetypes dominate: rideshare-anchored multi-service platforms, food-delivery-native specialists, and regional super-app operators. Competitive moves concentrate on algorithmic dispatch technology licensing and backward integration into captive logistics infrastructure.
Within the super-app tier, Grab Holdings Ltd. and Rappi Inc. exemplify geographic specialization strategies. Among food-delivery-native specialists, DoorDash Inc. and Swiggy occupy positions defined by suburban density penetration and subscription model innovation respectively. Uber Technologies Inc. represents the rideshare-anchored archetype leveraging driver base fungibility across service categories.
| Leading Market Players |
|---|
| Grab Holdings Ltd. |
| Instacart Inc. |
| DoorDash Inc. |
| Rappi Inc. |
| Grubhub Inc. |
| Uber Technologies Inc. |
| Zomato |
| Swiggy |
| Delivery Hero SE |
| Others |
Value Network & Pricing Analysis
Fuel price volatility in last-mile networks determines both margin compression thresholds and platform decisions on captive fleet investment versus contractor dependency. This risk vector widens the spread between subscription-backed pricing tiers and transactional pay-per-service rates while forcing geographic concentration in dense urban corridors where route density offsets per-mile cost exposure.
Pricing Analysis
Configured-to-order pricing for enterprise catering contracts commands premium spreads over standard consumer delivery fees. Subscription models stratify across premium, standard, and economy tiers based on order frequency thresholds and priority dispatch guarantees. Pricing pressure stems from driver subsidy requirements during peak demand windows, compressing margins in Indian and Southeast Asian metros. Small businesses exhibit highest price sensitivity due to volume concentration risks, while family households with fifteen-plus monthly transactions show lowest elasticity.
Supply Chain Analysis
Tariff exposure between US and Chinese technology hardware disrupts AI dispatching infrastructure procurement for platform operators. Supply draws from Taiwan for semiconductor components, China for electric vehicle fleet hardware, and India for cloud kitchen equipment manufacturing. GPS tracking devices and route optimization software rest on single-source licensing vulnerabilities from dominant algorithm providers. Distribution runs through third-party logistics aggregators in emerging markets and captive last-mile networks in mature metropolitan zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of real-time demand forecasting talent and proprietary routing algorithm IP defines competitive moats in this market. Platforms that secure these capabilities command pricing power and utilization efficiency that generalized competitors cannot replicate.
For Market Incumbents: Pre-empt algorithmic talent poaching through equity-heavy compensation structures and captive R&D centers in Bengaluru and Singapore. Consolidate backward integration into cloud kitchen real estate to defend margin position against rising commercial rent inflation in dense urban corridors. Lock in exclusive partnerships with municipal authorities for curb access permits before regulatory fragmentation hardens. For New Entrants and Emerging Players: Build out personal shopping infrastructure in Brazilian tier-two cities where PIX penetration outpaces incumbent platform coverage. Target Indonesian grocery retail partnerships as the most penetrable white-space segment given deepening smartphone adoption and underdeveloped supermarket digital integration. Pursue white-label logistics-as-a-service positioning to enterprise clients rather than direct consumer acquisition. For Investors and Strategic Acquirers: Regional super-app operators with integrated payment and transport stacks represent the priority acquisition archetype for platform consolidation plays. Long-term viability hinges on subscription attach rates above thirty percent and off-peak utilization efficiency. Watch regulatory reclassification of delivery workers as employees in European jurisdictions as the inflection signal for margin structure disruption.| Strategic Initiative | Industry Significance |
|---|---|
| AI Dispatching Infrastructure Investment | Machine learning talent acquisition in Bengaluru and Singapore compresses fulfillment windows below thirty minutes. |
| Subscription Model Migration | Recurring revenue capture from family households in Indian metros displaces transactional pay-per-service alternatives. |
| Cloud Kitchen Real Estate Backward Integration | Captive supply of FSSAI-compliant kitchen infrastructure reduces third-party rent exposure and quality variance. |
| PIX-Enabled Payment Partnership | Brazilian instant payment infrastructure integration opens underpenetrated urban corridors for first-time user conversion. |
| Gig Worker Classification Compliance | Proactive benefit structure redesign ahead of OSHA and emerging European mandates limits regulatory liability exposure. |
Research Methodology
Desk research of SEC filings, hyperscaler capex disclosures, and food safety regulatory databases preceded structured interviews with platform operations executives, municipal transport planners, cloud kitchen operators, and gig worker advocacy representatives. Primary fieldwork across Mumbai, São Paulo, Jakarta, and Berlin validated demand density assumptions and driver earnings structures. Secondary triangulation drew from RBI payment system reports, ANVISA compliance filings, and EU labor authority consultation documents. Bottom-up order frequency modeling and top-down addressable market sizing were reconciled through iterative stakeholder feedback.
Assumption sets held smartphone penetration curves and fuel price bands fixed while varying regulatory reclassification timelines and AI deployment cost trajectories across the projection horizon. Segmentation dimensions modeled include service type, technology deployment tier, customer household structure, and pricing commitment level. CAGRs derived from logistic diffusion curves fitted to historical adoption patterns in comparable digital service categories. Forecast inputs incorporated driver supply elasticity estimates and kitchen capacity expansion pipelines from municipal permitting records.
Stress conditions across fuel price spikes, worker reclassification court rulings, and data localization mandate enforcement were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on technology cost decline rates and regulatory enforcement intensity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Managed File Transfer (MFT) Market
Digital Solutions
Global Metadata Management Tools Market
Digital Solutions
Australia System Integration Market
Digital Solutions
Email Deliverability Tools Market
Digital Solutions
Australia Digital Twin Market
Digital Solutions
Smart Recording Pen Market
Digital Solutions
Electrical Digital Twins Market
Digital Solutions
Manufacturing Execution System Market
Digital Solutions
Middle East and Africa Digital Scent Technology Market
Digital Solutions
South Korea Digital Twin Market
Digital Solutions
Asia-Pacific Route Optimization Software Market
Digital Solutions
North America Online Dating Services Market
Digital Solutions
Europe Warranty Management System Market
Digital Solutions
UAE Digital Twin Market
Digital Solutions
Service Orchestration Market
Digital Solutions
Mock Interview Platforms Market