
 Global Agriculture Robots Market | 2026-2036
Global Agriculture Robots Market Size, Share, and Industry Trends Forecast 2026-2036
Global Agriculture Robots Market Analysis
China's Yangtze River Delta is reshaping component supply chains for precision agriculture hardware. Deere & Company leverages its embedded software ecosystem to lock in fleet replacement cycles across North American row-crop operations. DJI anchors consumer drone manufacturing scale but competes in agricultural spraying through RTK-GPS integration. AGCO Corporation differentiates via its Fendt brand's autonomous tractor validation programs across German test farms.
Agriculture robots encompass mobile autonomous platforms, aerial unmanned systems, and stationary robotic implements engineered to execute crop cultivation, animal husbandry, and post-harvest tasks with minimal human intervention. These systems integrate machine vision arrays, LiDAR terrain mapping, and sub-inch GPS correction to navigate unstructured field environments while performing seeding, spraying, or selective harvesting operations. Autonomous tractors and robotic weeders currently command the largest installed base, though drone-based crop scouting captures disproportionate R&D investment due to faster payback cycles on variable-rate input prescriptions. Indoor farming deployment remains nascent but attracts venture funding as vertical farm operators seek labor arbitrage through robotic transplanting and harvesting modules.
The EPA governs aerial application drift standards that constrain drone payload configurations and flight altitude protocols in US airspace. ECHA's REACH framework governs battery chemistry disposal pathways for European-deployed units, while China's MIIT enforces GB standard certification for wireless telemetry frequencies used in autonomous navigation. Japan's METI subsidizes precision agriculture equipment through its Smart Agriculture program, directly influencing procurement timelines for sensor-integrated platforms. Stakeholders must monitor evolving FAA beyond-visual-line-of-sight rulemakings and EU AI Act risk classifications for autonomous decision systems that determine chemical application rates without human confirmation loops.
Market Dynamics
Autonomous navigation stacks are compressing equipment replacement cycles as growers face simultaneous labor scarcity and chemical input cost volatility. The convergence of RTK-GPS correction networks with edge-computing vision systems is virtualizing traditional operator-in-the-loop workflows across row-crop and specialty operations.
Growth Catalysts
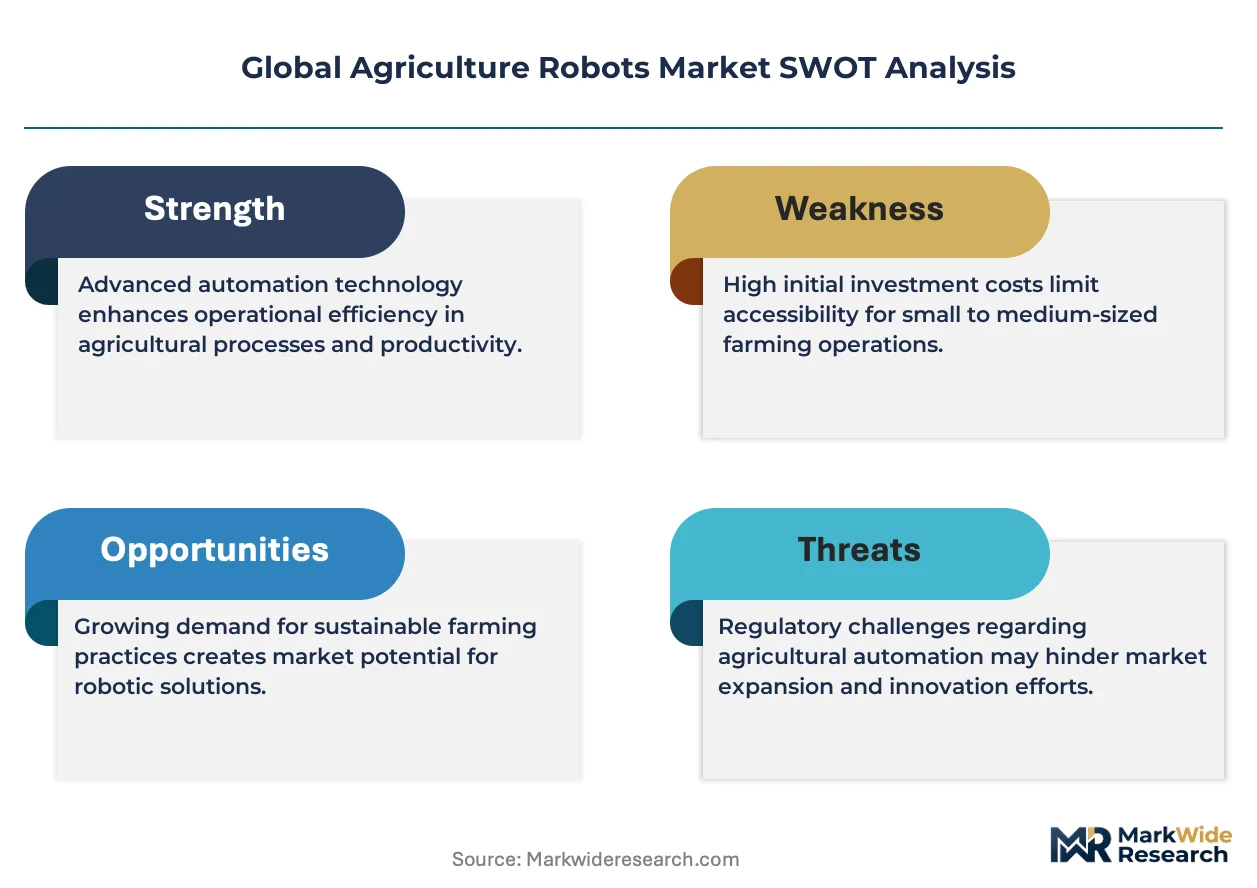
- EU Farm to Fork pesticide reduction mandates:Brussels' 50% chemical reduction targets by 2030 are accelerating mechanical weeding robot deployment across German and French arable farms.
- Labor arbitrage in controlled-environment agriculture:Vertical farm operators in the Netherlands are integrating robotic transplanting modules to offset seasonal workforce gaps.
- Sub-inch GPS correction infrastructure:Commercial RTK network expansion across Australia's wheat belt is enabling autonomous tractor guidance without base station ownership.
Market Restraints
- Lithium-ion cell supply concentration:Battery pack procurement depends on Chinese cathode material processing, exposing European OEMs to export quota volatility.
- FAA beyond-visual-line-of-sight rulemaking delays:Restricted flight envelopes for agricultural drones cap payload efficiency in US cotton and corn applications.
- Machine vision training data scarcity:Crop-weed classification accuracy remains constrained by limited labeled datasets for niche vegetable varieties.
Strategic Opportunities
- Japan METI Smart Agriculture subsidies:Tokyo's direct equipment procurement incentives create favorable financing terms for sensor-integrated platforms in rice paddy operations.
- Robotic selective harvesting convergence:Integration of soft robotics grippers with hyperspectral sorting is opening fresh-market strawberry automation in California's Salinas Valley.
- India BIS agricultural machinery certification streamlining:Harmonized testing protocols for autonomous implements are reducing market entry friction for foreign OEMs.
Industry Challenges
- Mechatronics technician scarcity:Maintenance of hydraulic-electric hybrid drive systems requires skills absent in traditional farm equipment service networks.
- ISO 12100 machinery safety compliance timelines:Validation of autonomous emergency stop systems extends product development cycles by 8-14 months.
- Legacy fleet CAN bus incompatibility:Retrofit of autonomy kits onto 5-10 year old tractors demands proprietary gateway hardware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Agriculture Robots Market |
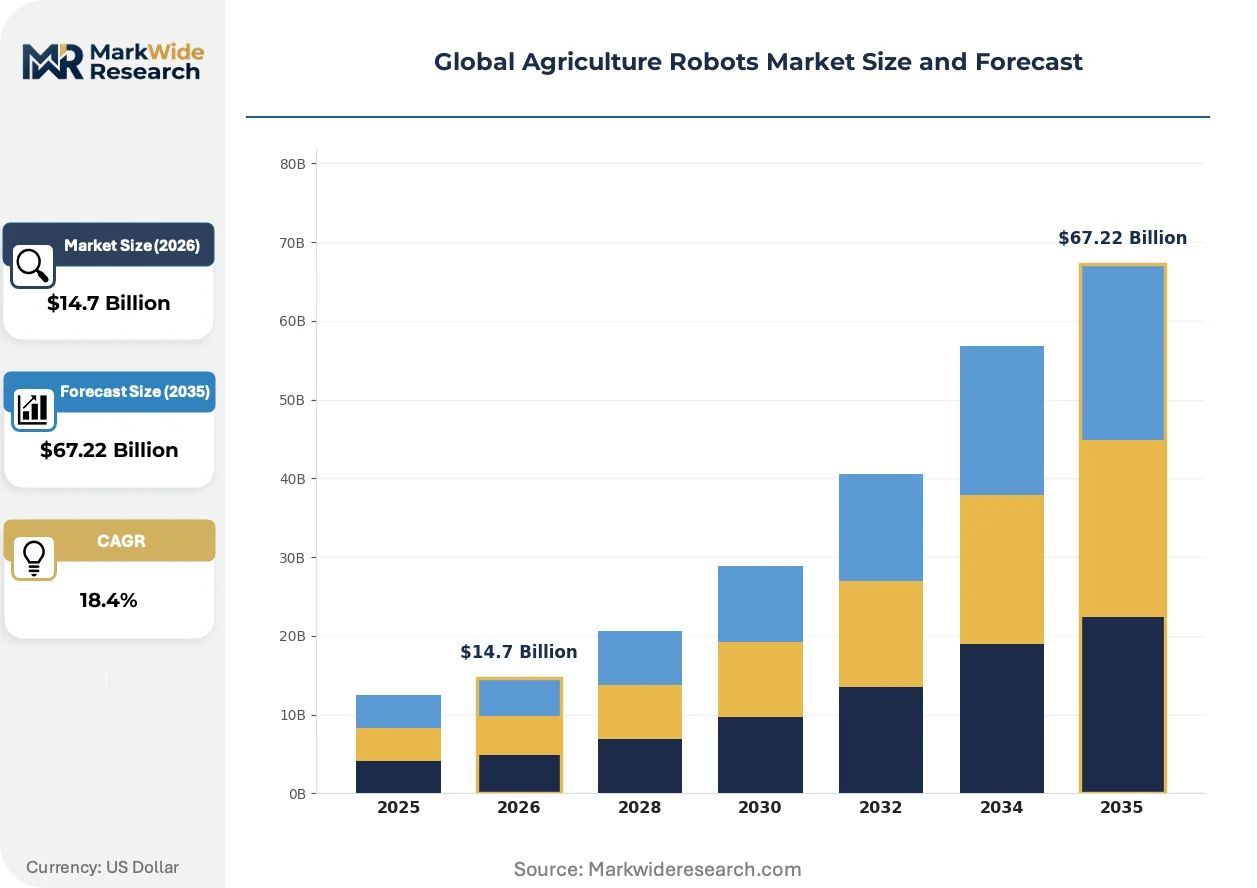
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $67.22 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Autonomous Tractors, Drones, Harvesters, Robotic Weeders End Use Industry: Crop Production, Livestock Management, Aquaculture, Horticulture Technology: AI, Machine Learning, Sensors, GPS Deployment: Indoor Farming, Outdoor Farming, Greenhouses, Vertical Farming |
| Companies Covered | Deere & Company, AGCO Corporation, CNH Industrial N.V., Kubota Corporation, DJI, Lely, Trimble Inc., CLAAS KGaA mbH, Autonomous Solutions, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Agriculture Robots Market Emerging Trajectories
Digital twin architectures are compressing field testing requirements while edge AI inference is displacing cloud-dependent decision loops. These shifts are reconfiguring R&D expenditure patterns and supplier relationships across the value chain.
Machine vision-based crop monitoring is virtualizing traditional scouting labor. Large specialty crop growers in California's Central Valley are deploying multispectral camera arrays on autonomous ground platforms at scale. This virtualization is collapsing the feedback loop between anomaly detection and variable-rate input application from days to hours.
REACH battery chemistry disclosure requirements are reshaping European equipment design cycles. ECHA's extended producer responsibility mandates now govern lithium pack end-of-life pathways for field robots. German OEMs are responding by modularizing battery architectures to accelerate cell replacement and recycling logistics.
Equipment-as-a-service contracting is displacing traditional ownership models among mid-scale row-crop operators. Dealer networks in Brazil's Mato Grosso soybean belt are unbundling hardware from per-acre autonomy subscriptions. This shift concentrates most visibly among 500-2,000 hectare farms seeking to convert capex to opex without sacrificing precision capability.
Global Agriculture Robots Market Segmentation
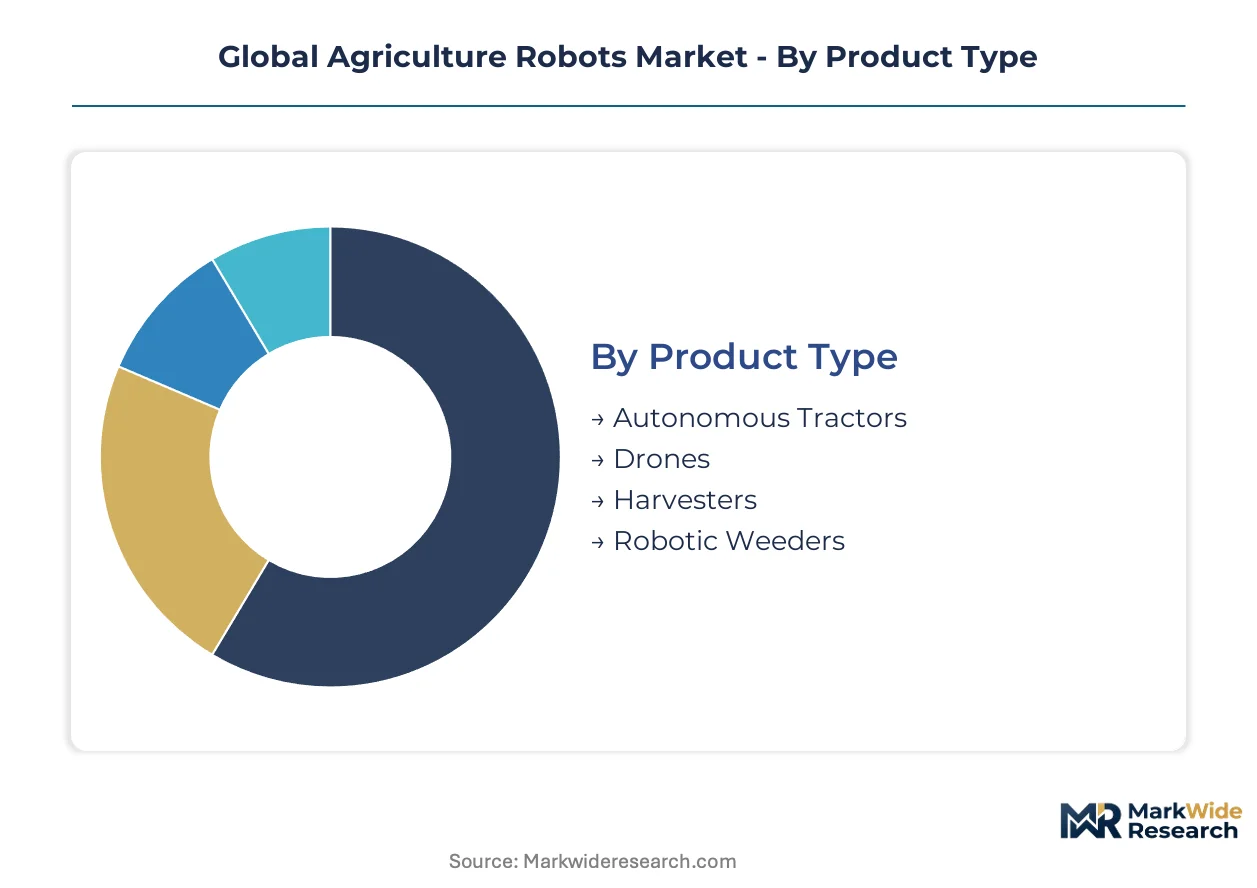
Equipment complexity varies sharply across agriculture robot categories, driving divergent service contract structures and spare parts logistics. Segmentation reveals where technical support intensity clusters and how procurement cycles align with operational criticality.
Product Type:
After-sales service intensity peaks with hydraulic-electric hybrid drive systems requiring specialized mechatronics technicians.
- Autonomous Tractors:These platforms integrate RTK-GPS correction with electro-hydraulic steering architectures for sub-inch row guidance. Demand concentrates across Australia's wheat belt where commercial network expansion eliminates base station ownership burdens. Preventive maintenance contracts now bundle telemetry monitoring with seasonal calibration services.
- Drones:Aerial systems combine multispectral imaging arrays with variable-rate spray payloads for crop scouting operations. California's Central Valley specialty growers deploy these at scale to collapse anomaly-to-application feedback loops from days to hours. Payload efficiency remains capped by FAA beyond-visual-line-of-sight rulemaking delays.
- Harvesters:Selective picking platforms employ soft robotics grippers with hyperspectral sorting for fresh-market produce.
- Robotic Weeders:Mechanical weeding robots deploy machine vision arrays for crop-weed classification in chemical reduction compliance scenarios.
Autonomous tractors hold the largest share; momentum sits with robotic weeders.
End Use Industry:
Application environments dictate sensor configuration durability and software validation protocols.
- Crop Production:Row-crop and specialty operations deploy autonomous platforms for seeding, spraying, and cultivation tasks across unstructured field environments. German and French arable farms accelerate mechanical weeding deployment under EU Farm to Fork pesticide reduction mandates.
- Livestock Management:Autonomous systems monitor animal health metrics and automate feeding protocols in dairy and cattle operations.
- Aquaculture:Underwater robotic platforms execute net cleaning and biomass estimation in offshore farming installations.
- Horticulture:Robotic transplanting and harvesting modules address labor arbitrage requirements in controlled-environment operations.
Crop production dominates installed base; horticulture is climbing the fastest as vertical farm operators scale automation.
Technology:
Component integration depth determines field reliability and firmware update complexity.
- AI:Edge AI inference engines process machine vision data for real-time crop-weed classification and selective harvesting decisions. Training data scarcity for niche vegetable varieties constrains accuracy thresholds in specialty applications.
- Machine Learning:Predictive algorithms optimize input application rates based on historical yield maps and real-time sensor fusion.
- Sensors:LiDAR terrain mapping arrays and multispectral camera systems enable navigation and crop monitoring across variable field conditions.
- GPS:Sub-inch correction networks from commercial RTK providers enable autonomous guidance without producer-owned base stations.
Sensor hardware commands current procurement volume; AI software layers are gaining share fastest through subscription monetization.
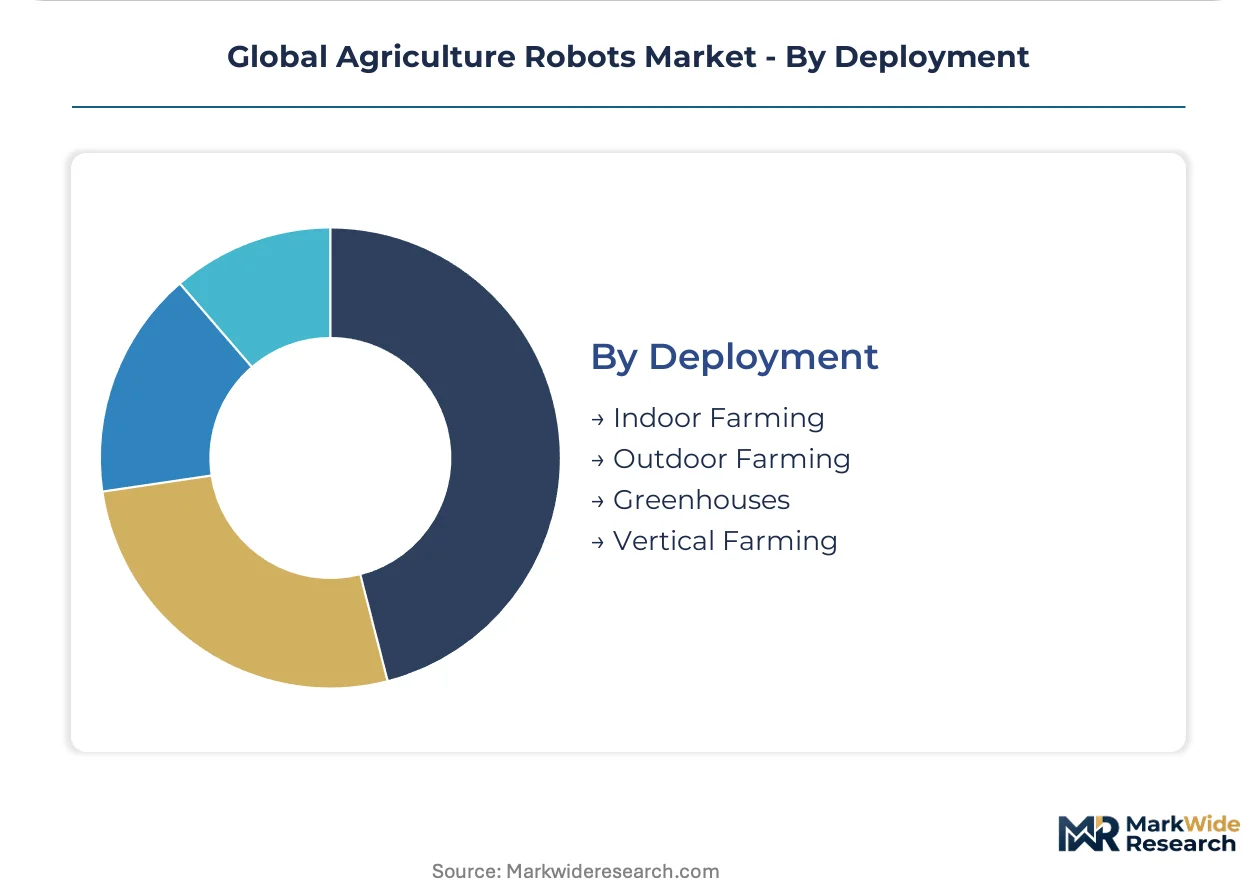
Deployment:
Environmental control precision shapes capital intensity and payback period calculations.
- Indoor Farming:Fully enclosed environments enable tightly controlled robotic workflows with minimal weather disruption exposure.
- Outdoor Farming:Open-field deployment demands ruggedized chassis and adaptive navigation for unstructured terrain.
- Greenhouses:The Netherlands' automation cluster near Wageningen concentrates robotic transplanting and harvesting R&D for protected cultivation.
- Vertical Farming:Stacked production architectures require specialized robotic modules for tiered access and space-constrained operations.
Outdoor farming retains the largest installed base; vertical farming shows the steepest expansion trajectory as labor arbitrage drives venture funding.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese component suppliers dominate upstream battery and sensor manufacturing, while German and Dutch engineering clusters concentrate autonomous system integration. Equipment procurement patterns diverge sharply across regulatory environments and subsidy regimes.
United States
California's Central Valley specialty growers deploy multispectral drone arrays for real-time crop monitoring. FAA beyond-visual-line-of-sight rulemaking delays constrain aerial spray payload efficiency in cotton and corn belts. The Salinas Valley cluster anchors robotic selective harvesting R&D for fresh-market strawberry automation.
Germany
German arable farms accelerate mechanical weeding robot deployment under EU Farm to Fork pesticide reduction mandates. ECHA's REACH framework governs lithium pack end-of-life pathways for field robots. The Fendt brand's autonomous tractor validation programs operate across Lower Saxony test farms.
China
The Yangtze River Delta reshapes component supply chains for precision agriculture hardware through concentrated cathode material processing. MIIT enforces GB standard certification for wireless telemetry frequencies in autonomous navigation. DJI anchors consumer drone manufacturing scale while competing in agricultural spraying through RTK-GPS integration.
Netherlands
Vertical farm operators near Wageningen integrate robotic transplanting modules to offset seasonal workforce gaps. EU AI Act risk classifications for autonomous chemical application systems influence validation timelines. The greenhouse automation cluster concentrates protected cultivation R&D for tiered robotic access systems.
Japan
Tokyo's METI Smart Agriculture subsidies create favorable financing terms for sensor-integrated platforms in rice paddy operations. Aging agricultural workforce demographics drive autonomous equipment procurement. Hokkaido test fields host predictive algorithm optimization for input application rates.
Global Agriculture Robots Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in sensor and powertrain supply. The vendor base organizes around three archetypes: legacy agricultural equipment manufacturers with embedded software ecosystems, consumer drone scale players extending into spraying applications, and pure-play autonomy startups focused on selective harvesting. Consolidation pressure runs highest where fleet replacement cycles intersect with subscription monetization models. Strategic moves cluster on M&A for machine vision capabilities and partnerships for RTK-GPS network access.
Within the legacy equipment tier, Deere & Company and AGCO Corporation exemplify platform integrators leveraging embedded software ecosystems to lock in North American and European fleet replacement cycles. DJI occupies a distinct position as a consumer-scale manufacturer extending RTK-GPS integration into agricultural spraying applications.
| Leading Market Players |
|---|
| Deere & Company |
| AGCO Corporation |
| CNH Industrial N.V. |
| Kubota Corporation |
| DJI |
| Lely |
| Trimble Inc. |
| CLAAS KGaA mbH |
| Autonomous Solutions, Inc. |
| Others |
Supply Flow & Price Mechanics
Overcapacity in China's Yangtze River Delta cathode processing facilities is compressing battery pack procurement costs while simultaneously eroding supplier margins, creating asymmetric pricing power that favors large-volume OEMs with forward-contract leverage over smaller autonomy startups.
Pricing Analysis
ECHA's REACH framework dictates the pricing tier structure for European-deployed agriculture robots by imposing extended producer responsibility costs on lithium pack end-of-life pathways. Three-tier pricing structure across premium, standard, and economy levels separates Fendt-branded autonomous tractors with full telemetry bundles from mid-market guidance systems and entry-level retrofit kits. Cost compression in the economy tier is intensifying because Chinese component oversupply is forcing margin concessions from cathode processors. Mid-scale row-crop operators in Brazil's Mato Grosso soybean belt exhibit the highest price sensitivity as they convert capex to opex through equipment-as-a-service contracting.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard practice among European OEMs sourcing from Chinese lithium-ion cell suppliers, reflecting working capital strain upstream. Geographic supply concentration centers on China for cathode material processing, South Korea for electrolyte formulation, and Japan for precision sensor components. Raw material dependencies rest on cobalt sulfate, lithium carbonate, and rare-earth magnet alloys for drive systems. Single-source vulnerability in Chinese cathode processing exposes European OEMs to export quota volatility. Distribution runs through dealer networks that unbundle hardware from per-acre autonomy subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The agriculture robots market functions as a defensive-moat arena where embedded software ecosystems and fleet data network effects create switching costs that lock in multi-year replacement cycles.
For Market Incumbents: Harden embedded software ecosystem lock-in by expanding RTK-GPS correction network partnerships that tether fleet telemetry to proprietary guidance architectures. Deepen backward integration into LiDAR sensor modules to reduce exposure to Chinese component volatility. The priority threat is pure-play autonomy startups commercializing retrofit kits that bypass traditional dealer channels. For New Entrants and Emerging Players: Build out selective harvesting capabilities for fresh-market strawberries in California's Salinas Valley, where soft robotics grippers with hyperspectral sorting remain underpenetrated relative to row-crop automation. Target 500-2,000 hectare mid-scale operations seeking opex conversion through equipment-as-a-service models. The most penetrable entry point is robotic weeding for EU Farm to Fork compliance scenarios. For Investors and Strategic Acquirers: Capital is best deployed toward pure-play machine vision specialists with labeled crop-weed datasets for niche vegetable varieties, as training data scarcity constrains accuracy thresholds and creates acquisition scarcity value. Long-term viability hinges on regulatory entrenchment through EU AI Act risk classification validation for autonomous chemical application systems. The signal to watch is FAA beyond-visual-line-of-sight rulemaking finalization, which would unlock aerial spray payload efficiency and revalue drone platform portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Machine Vision Capability Acquisition | Labeled crop-weed datasets for specialty vegetables overcome accuracy constraints constraining robotic weeder deployment. |
| RTK-GPS Network Partnership | Commercial correction infrastructure eliminates base station ownership burdens across Australia's wheat belt expansion. |
| Equipment-as-a-Service Launch | Per-acre autonomy subscriptions convert capex to opex for mid-scale Brazilian soybean operators. |
| Modular Battery Architecture Redesign | Cell replacement acceleration responds to ECHA REACH end-of-life pathway mandates for European markets. |
| Selective Harvesting R&D Expansion | Soft robotics grippers with hyperspectral sorting open fresh-market strawberry automation in California's Salinas Valley. |
Methodological Framework
Operator-level perspectives from fleet managers at large specialty crop growers, precision agriculture dealers, OEM platform engineers, and vertical farm operations directors anchored the qualitative base. Primary interview data combined with secondary validation from SEC equipment manufacturer filings, FAA rulemaking dockets, EU Farm to Fork strategy documents, and ECHA REACH guidance notices. Bottom-up triangulation across installed base estimates and top-down cross-checks against regional subsidy program allocations ensured methodological rigor.
Scenario-bracketing across regulatory acceleration and delay cases bounded the projection horizon. Segmentation dimensions modeled include equipment type, deployment environment, technology layer, and end-use application intensity. CAGRs were derived from weighted average growth trajectories across these segments. Industry-specific forecast inputs incorporated METI Smart Agriculture subsidy disbursement timelines and EU AI Act risk classification implementation pacing.
Stress conditions across lithium cell export quota volatility, FAA beyond-visual-line-of-sight rulemaking delays, and EU pesticide reduction mandate enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about subsidy continuity and regulatory implementation pacing. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Exoskeleton Systems Market
Robotics and Automation
Case and Box Handling Robots Market
Robotics and Automation
Latin America Warehouse Robotics Market
Robotics and Automation
AGV & AMR in Logistics Market
Robotics and Automation
Robot As a Service Market
Robotics and Automation
Europe Underwater Robotics Market
Robotics and Automation
Asia-Pacific Robotics Technology Market
Robotics and Automation
Intelligent Parcel Delivery Lockers Market
Robotics and Automation
Household Cleaning Robotics Market
Robotics and Automation
Global Robot Kitchen Market
Robotics and Automation
Industrial Robots Market
Robotics and Automation
Smart Remote Control Market
Robotics and Automation
Drone Package Delivery Market
Robotics and Automation
Mobile Robotics Market
Robotics and Automation
China Industrial Robots Market
Robotics and Automation
Global Medical Telepresence Robot Market