
 Global BYOD and Enterprise Mobility Market | 2026-2036
Global BYOD and Enterprise Mobility Market Size, Share, and Industry Trends Forecast 2026-2036
Global BYOD and Enterprise Mobility Market Foresight
Containerization technology is shifting how enterprises secure personal devices without full device control, collapsing the cost of BYOD program deployment. Microsoft Corporation leverages its Entra and Intune ecosystem to anchor enterprise identity across hybrid work environments. VMware Inc. competes through workspace virtualization that extends corporate data boundaries onto unmanaged endpoints. BlackBerry Limited specializes in government-grade containerization, occupying a defensible niche in regulated industries where data sovereignty mandates strict separation.
BYOD and enterprise mobility encompasses the policies, software platforms, and security frameworks that enable employees to use personal smartphones, tablets, and laptops for work tasks while maintaining corporate data integrity through encrypted containers, network access control, and centralized policy enforcement. Cloud-based deployment leads solution delivery by eliminating on-premise infrastructure overhead and enabling real-time policy synchronization across distributed workforces. Mobile device management retains the largest solution offering share as organizations prioritize endpoint visibility, though identity and access management is accelerating fastest as zero-trust architectures replace perimeter-based security models. Remote workforce enablement dominates application demand, while field service management represents an emerging margin pool for vendors targeting deskless worker populations.
The U.S. FCC and NIST cybersecurity frameworks shape product standards for domestic enterprise mobility deployments, while the EU GDPR and AI Act compel multinationals to embed data residency and algorithmic transparency into cross-border device management. India's TRAI guidelines and BIS data-localization mandates are forcing platform vendors to establish in-country infrastructure or cede public-sector contracts to compliant rivals. Stakeholders must monitor how fragmented regulatory requirements across Washington, Brussels, and New Delhi reshape vendor certification burdens and customer procurement criteria.
Market Dynamics
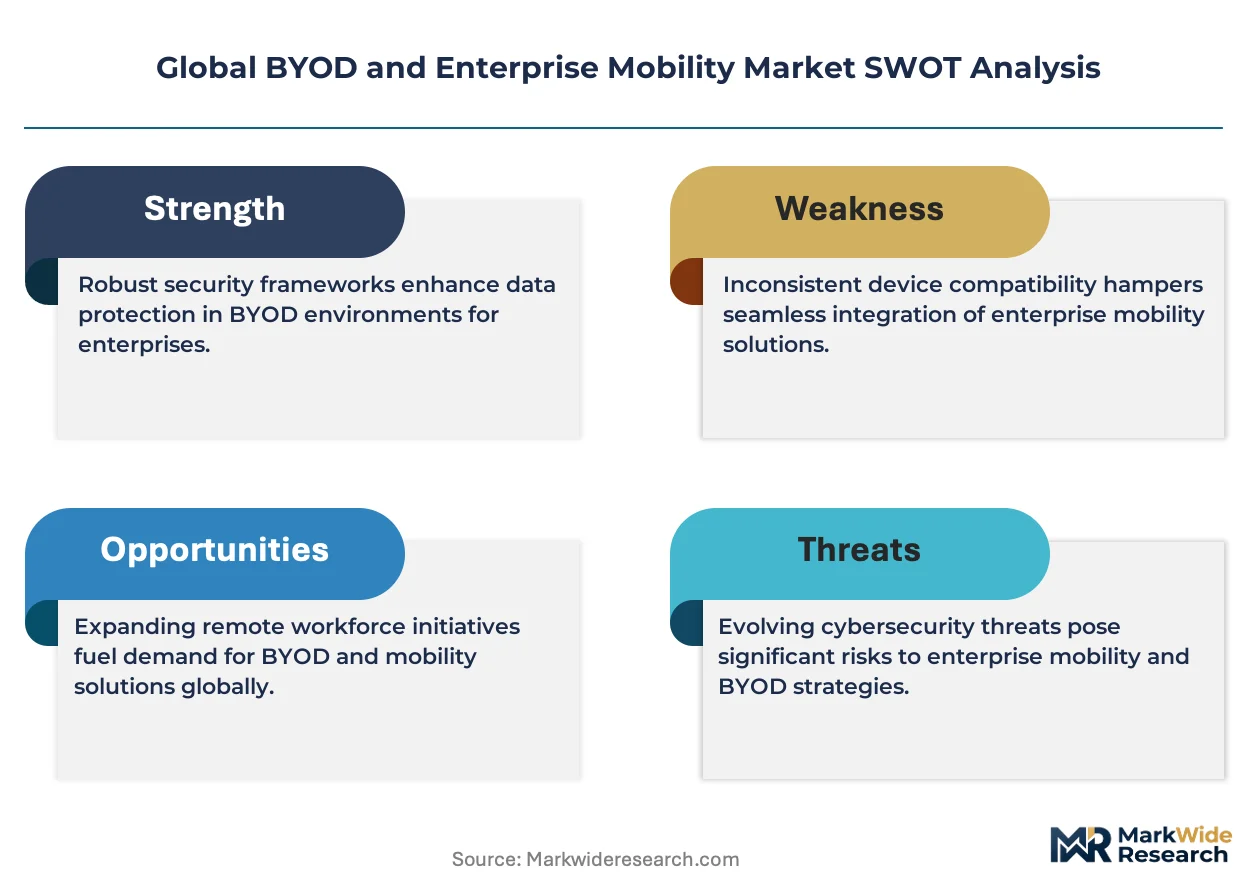
Zero-trust security architectures are collapsing the traditional network perimeter, forcing enterprises to reconstitute data protection around identity-centric access controls and device-agnostic policy enforcement rather than location-based trust assumptions.
Growth Catalysts
- EU AI Act compliance mandates:Multinationals deploying algorithmic decision tools on employee devices must embed audit trails and transparency controls, accelerating demand for governed mobility platforms with embedded governance layers.
- Financial services talent retention:Investment banks and insurers are expanding BYOD eligibility to differentiate compensation packages without expanding fixed hardware budgets, converting capital expenditure to operational flexibility.
- Containerization cost compression:Virtualized workspace delivery slashes per-device deployment costs by eliminating full mobile device management licensing for personal smartphones, opening BYOD to mid-market enterprises previously priced out.
Market Restraints
- Data localization infrastructure requirements:India's BIS mandates and TRAI guidelines compel foreign platform vendors to establish in-country server farms or forfeit public-sector contracts, raising fixed-cost barriers to market entry.
- Cross-border regulatory fragmentation:Simultaneous compliance with NIST cybersecurity frameworks, GDPR data residency rules, and sector-specific financial regulations creates architectural complexity that prolongs procurement cycles.
- Legacy perimeter security sunk costs:Enterprises with substantial investments in VPN concentrators and network access control appliances face write-down pressure that slows zero-trust migration timelines.
Strategic Opportunities
- Field service deskless worker populations:Utilities, logistics, and healthcare home-service organizations represent underpenetrated demand for ruggedized containerized access to work order systems on personally owned tablets.
- Convergence of identity and endpoint management:Integration of biometric authentication with continuous device posture assessment enables passwordless access that satisfies both security teams and end-user convenience expectations.
- German industrial Mittelstand expansion:Mid-sized manufacturers in Baden-Württemberg and Bavaria are consolidating previously siloed contractor access, supplier portals, and employee mobility into unified platforms.
Industry Challenges
- Zero-trust architecture skill scarcity:Implementation of continuous authentication and microsegmentation requires scarce identity engineering expertise that outstrips supply in enterprise IT organizations.
- Privacy-versus-security tension:Employee resistance to employer visibility into personal device location, application usage, and browsing patterns complicates policy enforcement and generates legal exposure under GDPR and emerging US state privacy laws.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global BYOD and Enterprise Mobility Market |
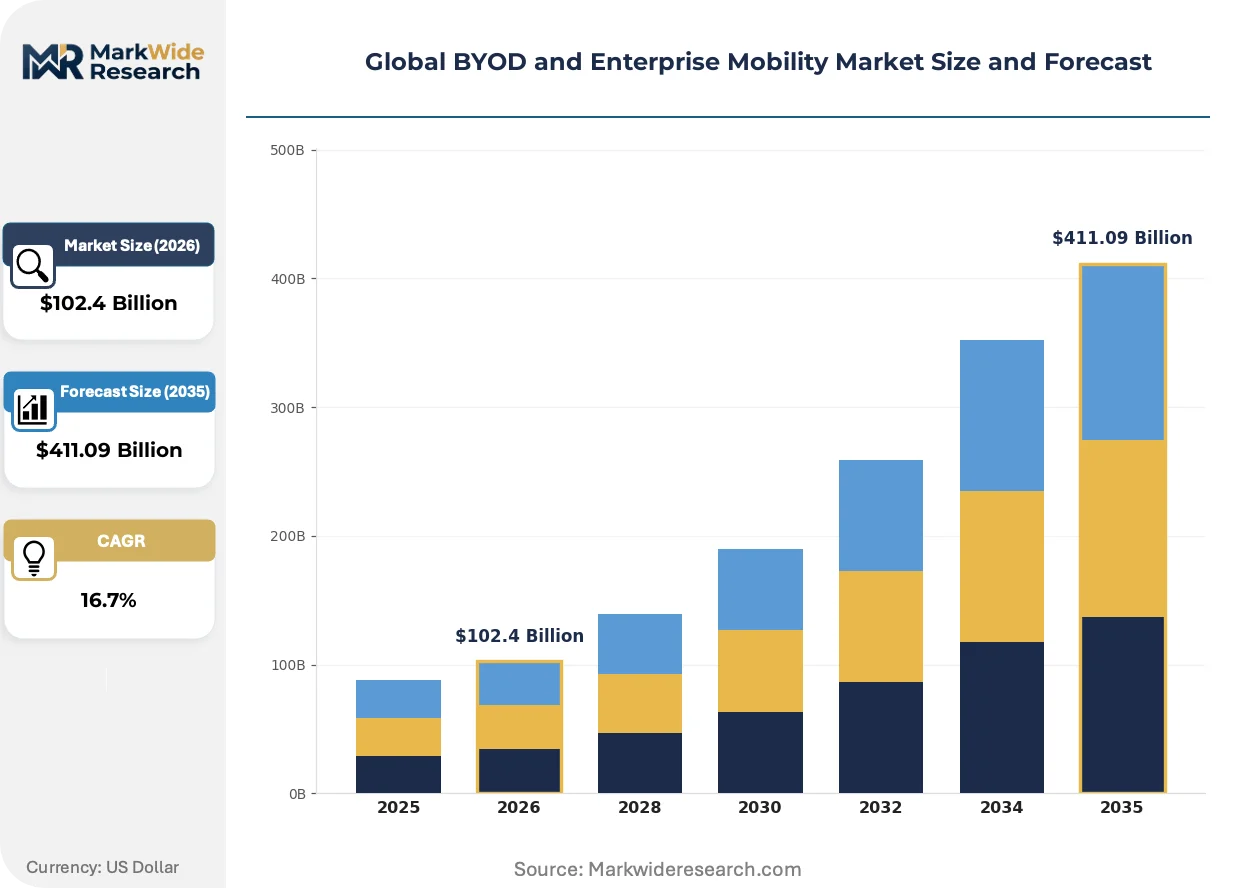
| Market Size in 2026 | $102.4 Billion |
| Market Size in 2035 | $411.09 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Type: Cloud-Based, On-Premise, Hybrid, Hosted Solution Offering: Mobile Device Management, Mobile Application Management, Enterprise Messaging, Identity & Access Management, Security Management Application: Remote Workforce Enablement, Secure BYOD Access, Field Service Management, Sales Force Automation, Virtual Desktop Infrastructure End User: Information Technology Firms, Financial Services, Government Agencies, Manufacturing Companies, Telecommunications Providers |
| Companies Covered | Microsoft Corporation, Cisco Systems, BlackBerry Limited, IBM Corporation, SAP SE, Infosys Limited, VMware Inc., Citrix Systems, Oracle Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global BYOD and Enterprise Mobility Market Shifts & Advancements
Enterprise mobility is pivoting from device-centric management to data-centric protection, with architectural innovations dissolving the boundary between corporate and personal computing environments through software-defined containment.
Secure enclave technology is modularizing how enterprises provision isolated execution environments on heterogeneous consumer hardware. Automotive suppliers and pharmaceutical field forces are deploying confidential computing containers that process sensitive CAD files and clinical trial data without exposing decryption keys to the host operating system. This modularization enables BYOD programs in previously excluded regulated sectors by satisfying data sovereignty requirements without mandating specific device models.
The EU AI Act's risk-classification framework is compelling platform vendors to embed algorithmic impact assessments into mobility management dashboards. Enterprises deploying AI-driven productivity assistants on employee devices must now document training data provenance and decision logic for high-risk applications. German automotive manufacturers and French financial institutions are most affected, with procurement teams requiring vendor attestations of conformity before contract execution.
Consumption-based licensing is displacing perpetual seat models as the dominant commercial structure for endpoint management platforms. Mid-market enterprises in India and the United States are prioritizing vendors offering monthly active user pricing that aligns costs with actual deployment rather than licensed capacity. This shift compresses vendor revenue recognition cycles while lowering customer switching costs, intensifying competitive pressure on incumbents with entrenched enterprise agreements.
Global BYOD and Enterprise Mobility Market Segmentation
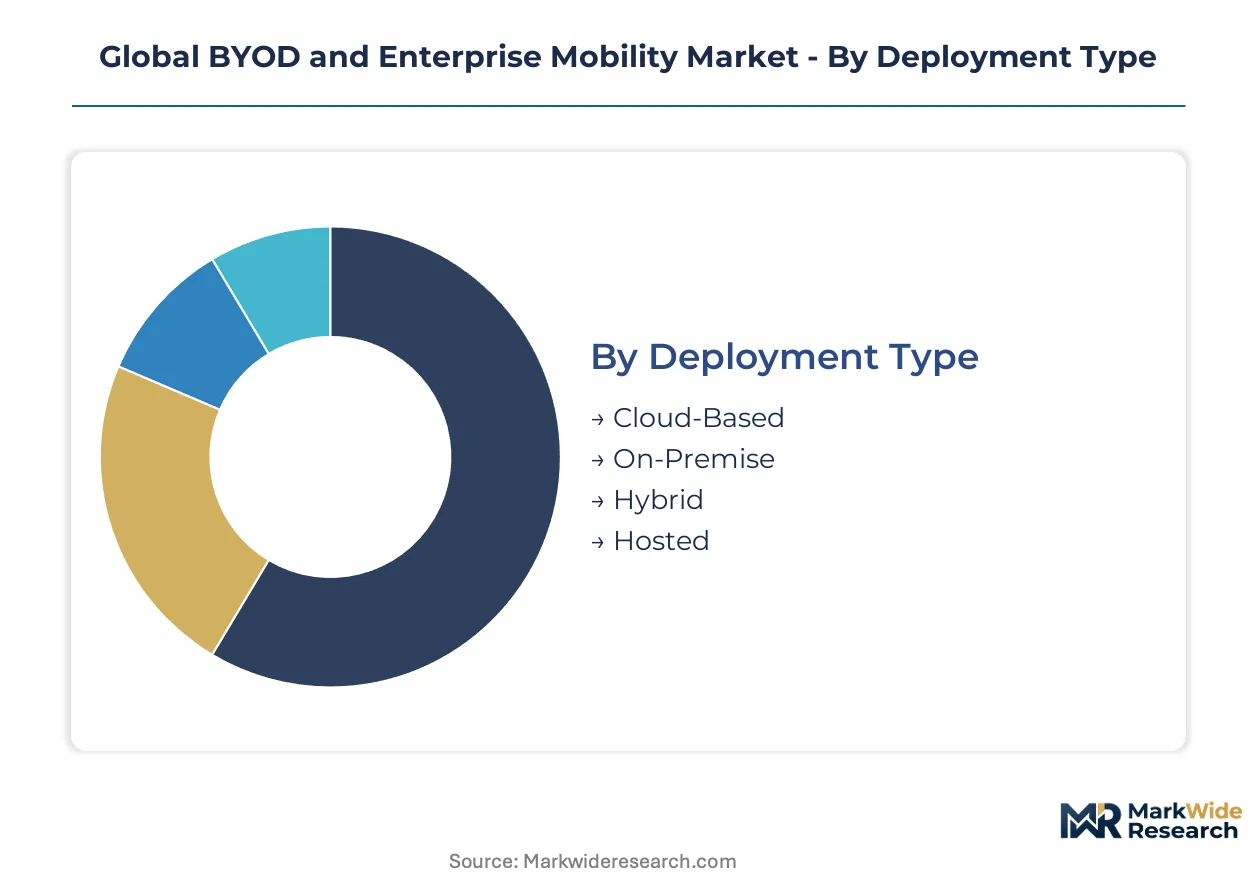
Enterprise mobility segmentation reveals how deployment architecture, security layering, and workforce topology intersect to determine vendor selection criteria and pricing power. Understanding these divides exposes where platform consolidation will accelerate versus where specialized point solutions retain defensible margins.
Deployment Type:
Cloud-based delivery commands volume leadership through operational simplicity, while hybrid architectures capture premium pricing from regulated enterprises requiring data residency controls.
- Cloud-Based:Multi-tenant SaaS platforms eliminate infrastructure overhead and enable real-time policy synchronization across distributed workforces. Demand concentrates among mid-market enterprises in the United States and Germany seeking rapid BYOD program deployment without capital expenditure. Financial services firms favor this model for contractor and seasonal worker access.
- On-Premise:Dedicated infrastructure deployments satisfy air-gapped security requirements and legacy integration needs in defense and intelligence sectors. Government agencies in India and classified research facilities in Germany sustain this segment despite higher total cost of ownership.
- Hybrid:Split architectures partition sensitive identity data on-premise while pushing device management workloads to cloud edge nodes. German automotive manufacturers and French healthcare networks deploy this model to satisfy GDPR data residency without sacrificing scalability.
- Hosted:Single-tenant managed services in third-party data centers serve enterprises lacking internal security operations centers. Regional banks in India and specialized manufacturing clusters in Bavaria represent concentrated demand.
Mature deployment sits with on-premise installations in defense and critical infrastructure. Newer deployment is concentrated in cloud-native architectures among technology-enabled services firms.
Solution Offering:
Endpoint visibility tools anchor current spending, while identity-centric platforms are climbing the fastest as zero-trust architectures displace perimeter-based security models.
- Mobile Device Management:Core platform functionality delivering inventory visibility, remote wipe capabilities, and OS-level policy enforcement across heterogeneous device fleets. Manufacturing companies in Germany and logistics operators in India represent the largest installed base, driven by field workforce expansion and contractor access requirements.
- Identity & Access Management:Continuous authentication and biometric verification systems that bind data access to verified user identity regardless of device ownership. Financial services firms in the United States and Germany are expanding fastest here, compelled by SEC cybersecurity disclosure rules and EU DORA operational resilience mandates.
- Mobile Application Management:Containerized workspace delivery that isolates corporate data within encrypted application sandboxes without full device control. Healthcare providers and professional services firms favor this lighter-touch approach for physician and partner BYOD programs.
- Enterprise Messaging:Secure communication platforms with message retention, e-discovery, and compliance archiving for regulated industries. Government agencies and legal services firms sustain demand despite competition from consumer messaging platforms.
- Security Management:Unified threat detection and response across endpoints, networks, and cloud workloads. Telecommunications providers and managed security service operators integrate these capabilities into bundled offerings for enterprise clients.
Revenue concentration remains with mobile device management in industrial and logistics applications. Steepest expansion trajectory belongs to identity and access management as passwordless authentication becomes procurement-mandatory in financial services.
Application:
Remote work enablement saturates knowledge-worker deployments, while field service management represents the largest untapped expansion opportunity for platform vendors.
- Remote Workforce Enablement:Comprehensive virtual workspace provisioning for distributed employees accessing corporate applications from personal devices. Information technology firms and financial services companies in the United States and Germany have achieved near-universal coverage, compressing growth potential in these geographies.
- Field Service Management:Ruggedized mobile access to work order systems, asset databases, and customer records for deskless technicians and inspectors. Utilities in Germany, healthcare home services in India, and agricultural equipment dealers in the United States are expanding fastest as these sectors digitize previously paper-based workflows.
- Secure BYOD Access:Policy frameworks and technical controls enabling personal device use for corporate email, calendars, and approved applications. Mid-market enterprises across all geographies represent the remaining expansion pool as large enterprises complete initial deployments.
- Sales Force Automation:Mobile CRM access, quote generation, and order entry tools for distributed sales personnel. Pharmaceutical and industrial equipment sectors sustain demand despite consolidation into broader platform suites.
- Virtual Desktop Infrastructure:Centralized desktop delivery to personal tablets and laptops, preserving data residency in corporate data centers. Government agencies and regulated financial institutions favor this model for high-sensitivity workloads.
Procurement maturity clusters in remote workforce enablement among technology and financial services firms. Emerging demand is concentrating in field service management as utilities, healthcare networks, and logistics operators mobilize deskless workforces.
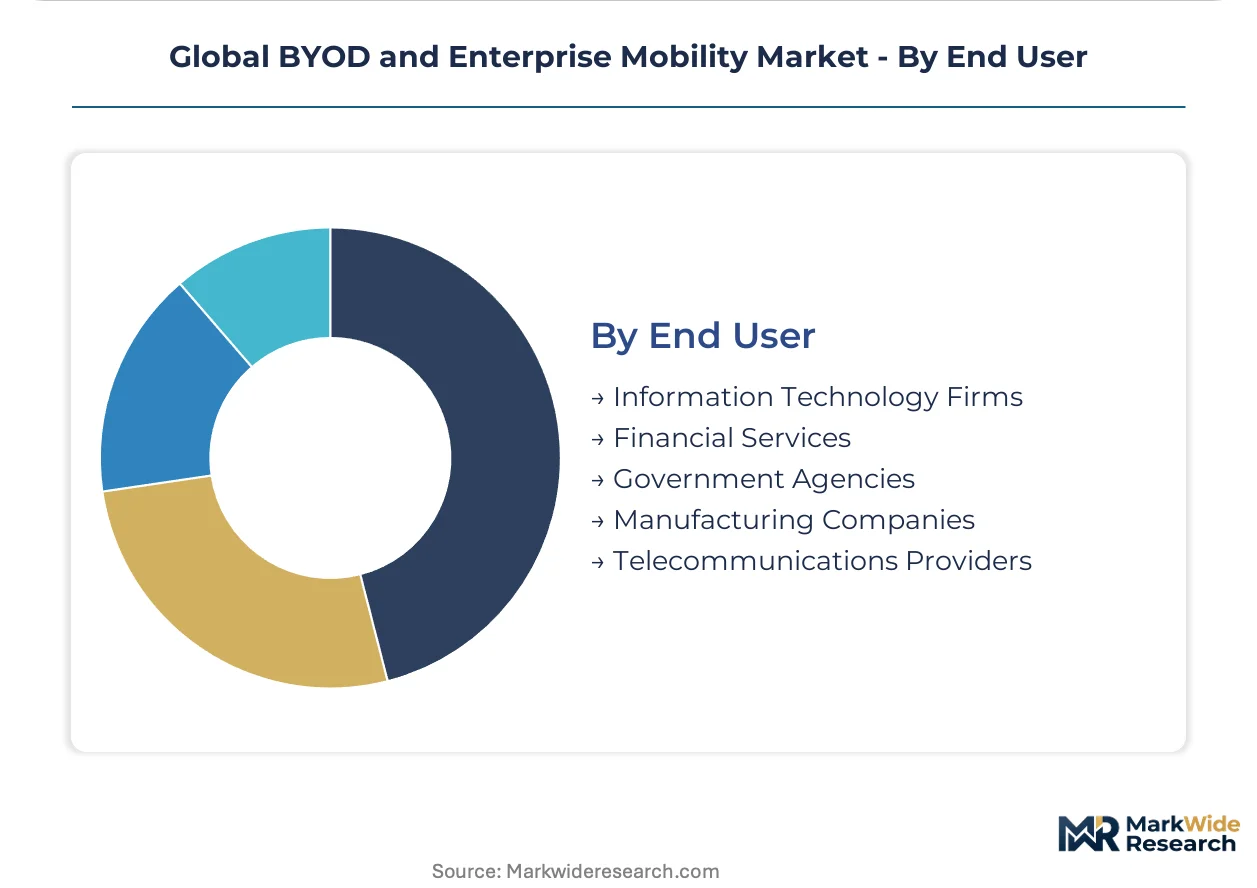
End User:
Financial services and technology firms drive premium solution adoption, while government procurement creates certification barriers that favor established vendors with compliance infrastructure.
- Financial Services:Investment banks, insurers, and payment processors deploying governed mobility to satisfy SEC, FINRA, and ECB operational resilience requirements while differentiating talent compensation through BYOD flexibility. New York, London, and Frankfurt represent the largest metropolitan demand concentrations.
- Information Technology Firms:Technology companies and software vendors with sophisticated internal security operations seeking advanced containerization and zero-trust architectures. These buyers function as reference customers and technology partners for platform vendors.
- Government Agencies:Federal, state, and municipal entities with stringent data classification, sovereignty, and audit requirements. India's public sector mandates BIS-certified domestic infrastructure, while German agencies require Common Criteria certification for classified workloads.
- Manufacturing Companies:Industrial enterprises mobilizing quality assurance, maintenance, and supply chain personnel across factory floors and supplier networks. German Mittelstand manufacturers and Indian automotive suppliers represent contrasting procurement patterns between integrated platform and point solution preferences.
- Telecommunications Providers:Mobile network operators and cable companies bundling endpoint management into enterprise connectivity offerings. These vendors function as channel partners and competitive threats to independent platform providers.
Contract value concentration sits with financial services procurement of integrated identity and endpoint platforms. Fastest-growing engagement volume is emerging in manufacturing as industrial digitization extends mobility programs from office staff to operational technology environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise mobility demand concentrates in the United States, Germany, and India as these markets advance zero-trust architectures and cloud-native endpoint management. Financial services firms across these geographies are expanding BYOD programs to retain talent while navigating divergent regulatory mandates.
United States
Financial services and technology sectors drive premium solution adoption, with investment banks in New York and San Francisco deploying governed mobility to satisfy SEC cybersecurity disclosure rules. The FCC and NIST frameworks shape product standards for domestic deployments. Silicon Valley technology firms function as reference customers for advanced containerization architectures.
Germany
Automotive manufacturers and the industrial Mittelstand consolidate previously siloed contractor access into unified platforms, particularly in Baden-Württemberg and Bavaria. GDPR data residency rules and the EU AI Act compel embedded governance controls and algorithmic transparency attestations. Frankfurt financial institutions require vendor conformity documentation before contract execution.
India
Telecommunications providers and IT services firms anchor demand, with field service management emerging fastest among healthcare home services and logistics operators. TRAI guidelines and BIS data-localization mandates force platform vendors to establish in-country server farms or forfeit public-sector contracts. Bangalore and Hyderabad technology clusters drive cloud-native deployment preferences.
United Kingdom
Professional services firms and fintech startups prioritize identity-centric access management as zero-trust architectures displace legacy VPN models. The Information Commissioner's Office enforces GDPR compliance through substantial penalties, accelerating demand for managed mobility solutions with embedded audit capabilities. London's financial district concentrates procurement of integrated endpoint and identity platforms.
Japan
Manufacturing conglomerates and telecommunications providers sustain demand for hybrid deployment architectures that preserve data residency controls. METI guidelines on operational technology security influence endpoint management requirements for factory floor mobility. Tokyo and Osaka industrial corridors mobilize quality assurance and maintenance personnel across supplier networks.
Global BYOD and Enterprise Mobility Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with platform consolidation accelerating in endpoint management while containerization retains specialized margins. The vendor landscape organizes around three archetypes: cloud-native platform providers with identity ecosystems, virtualization specialists extending corporate data boundaries, and government-grade security vendors serving regulated industries. Dominant competitive moves include strategic partnerships to embed mobility controls within productivity suites, and geographic expansion through in-country infrastructure investments to satisfy data localization mandates.
Within the cloud-native platform tier, Microsoft Corporation and VMware Inc. anchor contrasting approaches to hybrid work enablement. Microsoft leverages its Entra and Intune ecosystem to bind enterprise identity across distributed endpoints, while VMware competes through workspace virtualization that extends corporate data boundaries onto unmanaged devices. BlackBerry Limited occupies a defensible niche in government-grade containerization, serving regulated industries where data sovereignty mandates strict separation between personal and corporate execution environments.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Cisco Systems |
| BlackBerry Limited |
| IBM Corporation |
| SAP SE |
| Infosys Limited |
| VMware Inc. |
| Citrix Systems |
| Oracle Corporation |
| Others |
Supply & Pricing Matrix
Horizontal platform consolidation across cloud-native endpoint management anchors both supply positioning and pricing power for dominant vendors, compressing margins for point-solution specialists while enabling volume-tiered SaaS economics that favor incumbents with identity-ecosystem breadth.
Pricing Analysis
Volume leadership concentrates in consumption-based SaaS tiers while premium pricing attaches to hybrid deployments with data-residency controls. Three-tier pricing structure across premium, standard, and economy levels separates identity-integrated suites from standalone MDM and freemium entry points. Cost compression in mid-market cloud tiers is intensifying because containerization eliminates per-device licensing overhead. Financial services procurement teams exhibit lowest price sensitivity, prioritizing compliance attestations over per-seat economics.
Supply Chain Analysis
Reverse-logistics flows for device refurbishment and secure data destruction create secondary value pools for certified IT asset disposition vendors serving regulated enterprise mobility programs. Core platform development concentrates in the United States, Germany, and India, with cloud infrastructure provisioning drawing from hyperscaler data center networks across Singapore, Ireland, and Virginia. Semiconductor components for secure enclave processors and biometric sensors hinge on Taiwan and South Korea fabrication capacity. Single-source vulnerability in confidential computing chipsets threatens supply continuity for government-grade containerization deployments. Distribution runs through direct enterprise sales teams, telecommunications provider bundles, and managed security service operator channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Identity engineering talent scarcity props pricing for zero-trust architecture implementations, constraining supply-side delivery capacity across financial services and government verticals.
For Market Incumbents: Acquire specialized containerization engineering teams to close capability gaps in confidential computing and secure enclave provisioning. Consolidate channel partnerships with telecommunications providers bundling endpoint management into enterprise connectivity offerings. Defensive positioning requires preemptive certification investment for India's BIS mandates and Germany's Common Criteria evaluation before compliance deadlines harden procurement criteria.
For New Entrants and Emerging Players: Capture field service management white space among German utilities and Indian healthcare home services, where deskless worker mobilization lags knowledge-worker saturation. Target mid-market manufacturing clusters in Bavaria and Baden-Württemberg seeking unified contractor access platforms. Go-to-market leverage rests on consumption-based pricing that aligns vendor revenue with actual monthly active deployment rather than licensed capacity commitments.
For Investors and Strategic Acquirers: Exit pathways concentrate in platform consolidation plays by hyperscalers seeking identity-ecosystem completeness. Long-term viability favors vendors with embedded governance layers satisfying EU AI Act algorithmic transparency requirements. Acquisition target archetypes include government-grade containerization specialists with Common Criteria certification infrastructure. Monitor BIS compliance deadline enforcement in Indian public-sector procurement as inflection indicator for vendor market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Identity Ecosystem Integration | Microsoft Entra and Intune convergence binds enterprise access across hybrid endpoints, displacing standalone MDM vendors. |
| Confidential Computing Certification | Secure enclave attestation enables BYOD expansion into pharmaceutical and automotive supplier networks under data sovereignty mandates. |
| In-Country Infrastructure Deployment | Domestic server farms satisfy India's TRAI guidelines and BIS data-localization requirements for public-sector contracts. |
| Algorithmic Governance Embedding | EU AI Act risk-classification dashboards differentiate platforms for Frankfurt financial institutions and German automotive manufacturers. |
| Field Service Platform Extension | Ruggedized containerized access captures utilities and healthcare home services in underpenetrated deskless worker populations. |
Research Methodology
Multi-period observation of vendor pricing disclosures, certification timelines, and procurement contract values anchored the trend analysis, supplemented by interviews with chief information security officers, enterprise mobility platform engineers, IT procurement directors at financial services firms, and channel sales leads at telecommunications providers. Secondary validation drew from SEC cybersecurity disclosure filings, EU AI Act implementation guidance, BIS certification registries, and hyperscaler capex disclosures. Bottom-up deployment estimates across organization size tiers triangulated against top-down market sizing from platform vendor revenue reporting.
Input-output matrix modeling connected identity management adoption rates, zero-trust architecture penetration, and regulatory compliance spending to endpoint management revenue pools across the projection horizon. Segmentation dimensions included deployment architecture, solution offering type, application use case, and end-user vertical with regional regulatory cluster overlay. CAGRs were derived from fitted trend extrapolation moderated by technology substitution elasticity estimates and compliance deadline acceleration effects.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU AI Act enforcement severity, India BIS mandate expansion, and zero-trust skill scarcity resolution. Practitioners should monitor certification backlog queues at German BSI and Indian STQC facilities, hyperscaler data center localization announcements, and financial services SEC cybersecurity disclosure violation penalties for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Data Collection and Labeling Market
Digital Solutions
Online Home Service Market
Digital Solutions
Global Connected Workplace Market
Digital Solutions
Digital Signage Systems Market
Digital Solutions
Affiliate Marketing Platform Market
Digital Solutions
Revenue Management Software Market
Digital Solutions
Multicarrier Parcel Management Solutions Software Market
Digital Solutions
Global Interactive Voice Response Market
Digital Solutions
India ICT Market
Digital Solutions
Digital Certificates Market
Digital Solutions
GCC and Africa ICT Market
Digital Solutions
Canada Digital Twin Market
Digital Solutions
Global Unified Endpoint Management Market
Digital Solutions
Governed Enterprise Architecture Scenario Sandbox Market
Digital Solutions
Life Science Multichannel Campaign Management Market
Digital Solutions
Document Management System Market