
 Global Digital Accessibility Software Market | 2026-2036
Global Digital Accessibility Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Digital Accessibility Software Market Foresight
Buyer concentration among large private enterprises is realigning how accessibility software vendors structure enterprise sales teams. Level Access leverages deep federal sector relationships to sustain multi-year government contracts. Deque Systems, Inc. anchors its position through specialized developer tooling that integrates into CI/CD pipelines. AudioEye, Inc. competes by controlling automated remediation at scale for e-commerce platforms with high transaction volumes.
Digital accessibility software encompasses automated testing engines, manual audit workflows, and remediation overlays that detect WCAG violations against perceptibility, operability, understandability, and robustness criteria. These systems scan HTML structures, color contrast ratios, keyboard navigation paths, and ARIA labeling to prevent exclusion of users with visual, auditory, motor, or cognitive impairments. Cloud-based deployment leads adoption as organizations prioritize elastic scaling across distributed web estates, while screen readers and captioning software capture concentrated R&D investment due to persistent gaps in multimedia accessibility. Web accessibility dominates use-case revenue, though mobile accessibility accelerates fastest as native application compliance litigation expands.
The U.S. Department of Justice ADA enforcement, the EU Web Accessibility Directive transposed across member states, and the W3C WCAG 2.2 technical standard collectively reshape product roadmaps and procurement specifications. Vendors must now engineer for Section 508 federal conformance, EN 301 549 European harmonization, and evolving national requirements in Australia and Canada. Stakeholders should monitor how regulatory divergence between jurisdictions forces platform architects to maintain multiple compliance rule engines rather than unified global configurations.
Market Dynamics
Enterprise procurement consolidation is compressing vendor ecosystems as Fortune 500 retailers demand unified accessibility platforms spanning automated testing, manual audit workflows, and remediation overlays under single contracts.
Growth Catalysts
- WCAG 2.2 technical standard:The W3C's updated perceptibility, operability, understandability, and robustness criteria force platform refreshes across federal and commercial deployments, expanding addressable scope for compliance software vendors.
- Native application litigation:Mobile accessibility lawsuits against e-commerce and financial services apps accelerate demand for automated scanning of iOS and Android codebases beyond traditional web estates.
- CI/CD pipeline integration:Developer tooling that embeds accessibility testing into continuous deployment workflows captures budget allocations previously directed toward post-launch manual audits.
Market Restraints
- Cloud infrastructure concentration:Elastic scaling requirements tether accessibility platforms to hyperscaler ecosystems, creating dependency on AWS, Azure, and Google Cloud pricing and availability.
- ARIA implementation complexity:Inconsistent browser and assistive technology support for dynamic web content markup forces vendors to maintain multiple testing rule engines, elevating engineering overhead.
- Overlay remediation skepticism:Disability advocacy organizations dispute the efficacy of automated widget-based fixes, generating reputational risk for vendors emphasizing rapid deployment over structural code repair.
Strategic Opportunities
- EN 301 549 harmonization gaps:European member states diverge in transposition timelines and procurement enforcement, creating openings for vendors offering jurisdiction-specific compliance modules.
- Immersive content accessibility:Virtual and augmented reality training platforms in enterprise and education sectors lack established captioning, audio description, and haptic feedback standards.
- Embedded finance compliance:Banking-as-a-service and buy-now-pay-later integrations into retail checkout flows trigger ADA Title III exposure for non-financial merchants requiring accessibility overlays.
Industry Challenges
- WCAG auditor certification scarcity:The International Association of Accessibility Professionals credential pipeline fails to match enterprise demand for qualified manual testers, extending audit backlogs.
- Legacy content remediation:Decades of archived PDF documents, multimedia libraries, and third-party embedded widgets resist automated scanning, forcing labor-intensive manual remediation at scale.
- Multi-jurisdiction rule maintenance:Vendors must simultaneously engineer for Section 508 federal conformance, European harmonization, and emerging national requirements in Australia and Canada without fragmenting codebase architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Digital Accessibility Software Market |
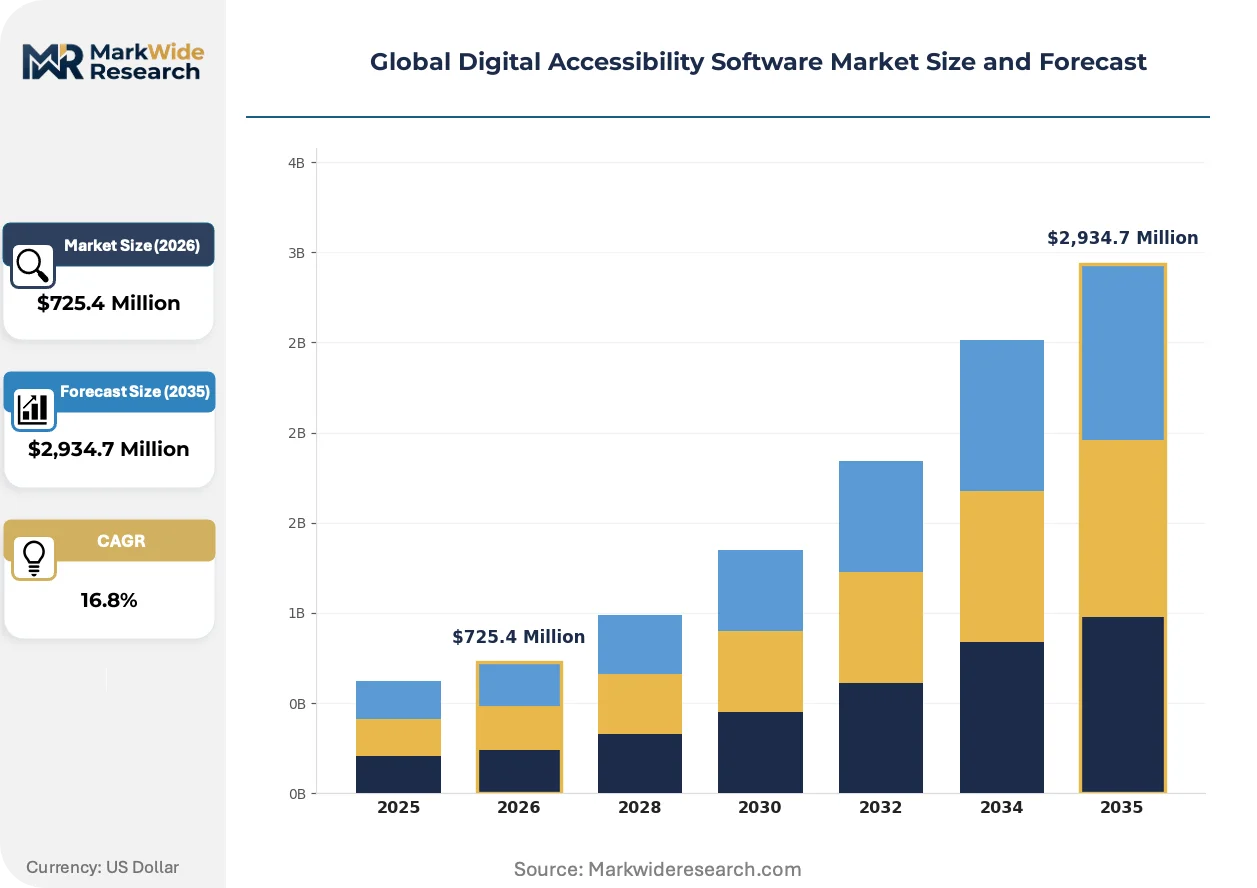
| Market Size in 2026 | $725.4 Million |
| Market Size in 2035 | $2,934.7 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing Solution Offering: Screen Readers, Voice Recognition, Text Enlargement, Captioning Software, Keyboard Navigation Tools Use Case: Web Accessibility, Mobile Accessibility, Document Accessibility, Software Accessibility, E-Learning Platforms End User: Educational Institutions, Government Agencies, Non-Profit Organizations, Private Enterprises |
| Companies Covered | Level Access, AudioEye, Inc., Deque Systems, Inc., Siteimprove, UsableNet Inc., accessiBe Inc., Silktide Ltd, UserWay, AccessibilityChecker.org INC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Digital Accessibility Software Market Shifts & Advancements
Machine learning inference engines are displacing rules-based accessibility scanners, compressing false-positive rates while expanding coverage of dynamic single-page applications and complex interaction patterns.
Computer vision algorithms paired with natural language processing are automating image description generation and video captioning at throughput levels impossible under manual transcription workflows. Media publishers and streaming platforms deploy these systems to clear backlogs of un-described visual assets ahead of litigation exposure. The structural consequence is a collapse in per-asset remediation cost curves, enabling accessibility compliance for long-tail content previously deemed uneconomical.
Regulators in Brussels have sharpened enforcement of the EU Web Accessibility Directive through public sector procurement disqualification mechanisms, compelling government contractors to demonstrate EN 301 549 conformance in bid submissions. Member state digital ministries now embed accessibility clauses into framework agreements for web development and SaaS procurement. Germany and France lead implementation stringency, with federal agencies publishing violation remediation timelines under freedom-of-information pressure.
Enterprise buyers increasingly unbundle accessibility testing from bundled digital agency contracts, establishing direct vendor relationships with specialized platform providers. Retail and hospitality sectors drive this disintermediation, separating pre-launch compliance verification from creative and development services. Australia exhibits the most pronounced unbundling pattern, where federal and state procurement frameworks mandate standalone accessibility supplier certification.
Global Digital Accessibility Software Market Segmentation
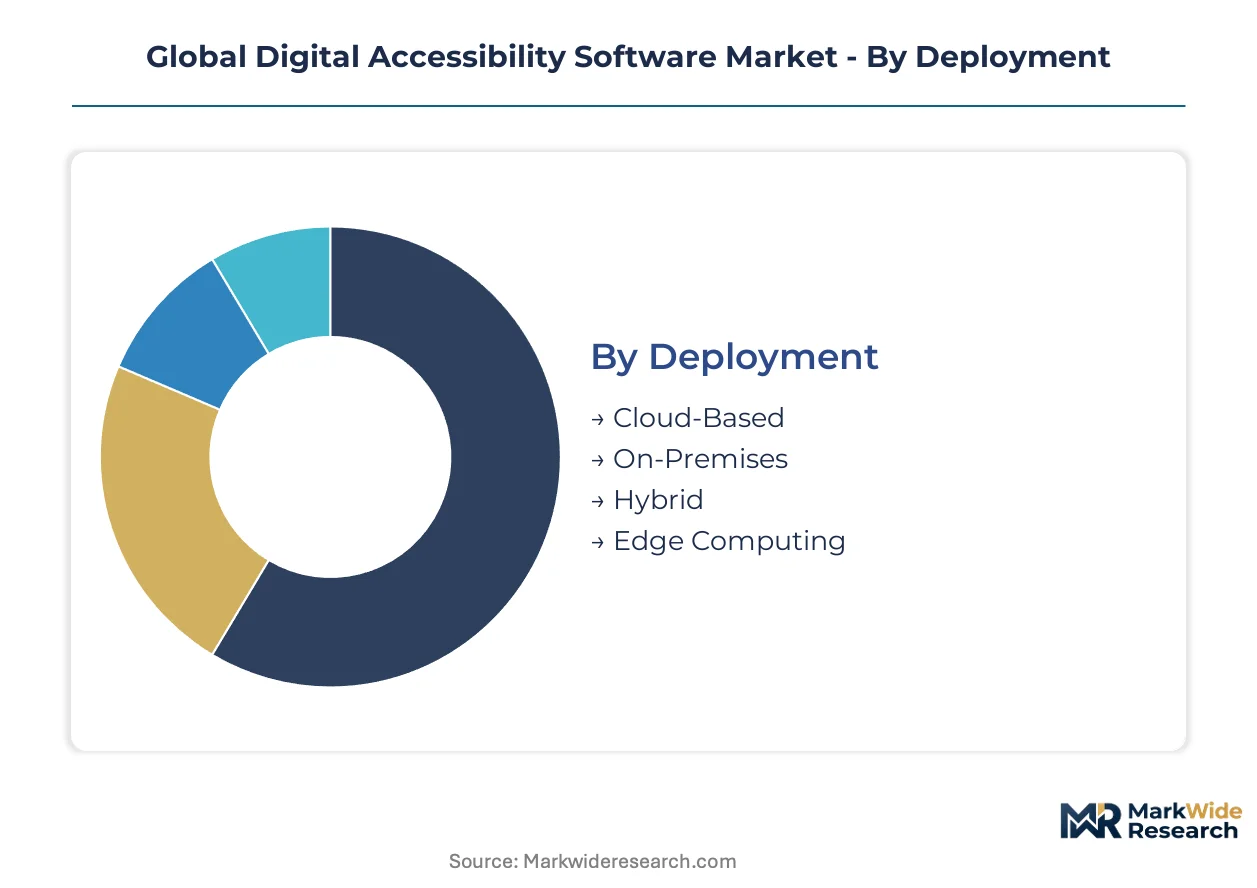
Segmentation in digital accessibility software reflects how procurement priorities diverge across infrastructure constraints, compliance mandates, and user impairment profiles. Buyers select deployment architectures based on data sovereignty requirements, while solution portfolios map directly to WCAG conformance obligations and litigation exposure patterns.
Deployment:
Elastic scaling requirements versus data residency mandates create a customization-to-standardization spectrum across infrastructure choices.
- Cloud-Based:Elastic scaling across distributed web estates enables Fortune 500 retailers to consolidate vendor relationships onto unified platforms. Procurement teams in the United States and Germany prioritize this model for rapid deployment across multi-brand portfolios without capital expenditure cycles.
- On-Premises:Federal agencies and defense contractors maintain air-gapped installations to satisfy Section 508 audit trails and classified environment restrictions. The U.S. Department of Veterans Affairs and comparable European security services drive residual demand despite higher total cost of ownership.
- Hybrid:Financial services institutions segment sensitive customer data on-premises while pushing public-facing content through cloud accessibility overlays.
- Edge Computing:Retail kiosks and point-of-sale terminals in Australia deploy localized processing to minimize latency for real-time captioning and voice navigation.
Leading the category by volume: Cloud-Based. Expanding most quickly: Edge Computing.
Solution Offering:
Functional specialization versus integrated platform bundling determines how procurement budgets fragment across assistive technology categories.
- Screen Readers:Software synthesizing text-to-speech output for visual impairment access, with JAWS and NVDA compatibility requirements dominating federal procurement specifications. Demand concentrates in educational institutions and government agencies across the United States and Australia where Section 508 and Disability Discrimination Act enforcement mandates comprehensive non-visual access.
- Captioning Software:Automated and human-in-the-loop transcription systems for multimedia content, now essential for streaming platforms and e-learning publishers facing ADA Title III exposure. Media publishers deploy machine learning inference engines to clear backlogs of un-described video assets ahead of litigation timelines.
- Voice Recognition:Motor impairment accommodation through speech-to-text input control, penetrating legal and healthcare documentation workflows.
- Text Enlargement:Browser-based magnification and reflow utilities for low-vision users, standard in public sector kiosk deployments.
- Keyboard Navigation Tools:Focus management and skip-link utilities ensuring operability without pointer devices, embedded in CI/CD pipelines by developer tooling vendors.
Capturing dominant procurement share: Captioning Software. Gaining share fastest: Voice Recognition.
Use Case:
Channel-specific compliance exposure shapes how organizations prioritize remediation investment across digital touchpoints.
- Web Accessibility:HTML structure scanning, color contrast validation, and ARIA labeling for browser-based experiences, commanding the largest addressable spend. E-commerce platforms with high transaction volumes in the United States and Germany drive automated testing engine procurement to preempt serial plaintiff litigation.
- Mobile Accessibility:Native iOS and Android codebase scanning for screen reader compatibility and gesture operability, accelerating as plaintiffs target financial services and retail applications. The shift reflects enforcement expansion beyond traditional web estates into smartphone-native commerce.
- Document Accessibility:PDF remediation and structured document tagging for archival compliance, labor-intensive due to decades of legacy content backlogs.
- Software Accessibility:Desktop application conformance for enterprise productivity tools, relevant to federal contractor supply chains.
- E-Learning Platforms:Multimedia courseware accessibility for educational institutions receiving federal funding, triggering ADA Title II and Section 504 obligations.
Highest current procurement intensity: Web Accessibility. Steepest expansion trajectory: Mobile Accessibility.
End User:
Budget authority and compliance timeline pressure vary sharply across institutional categories with differing litigation exposure and funding mechanisms.
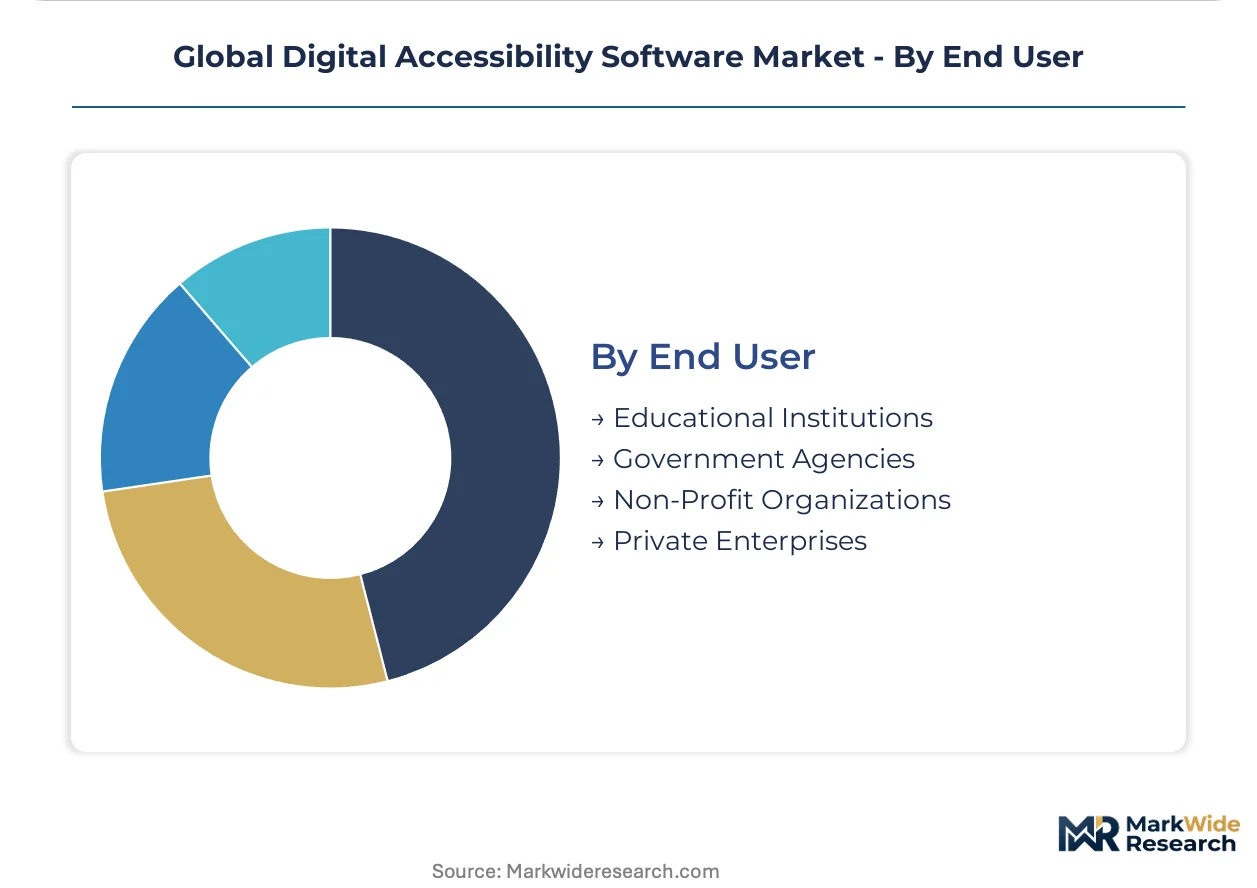
- Private Enterprises:Fortune 500 retailers and hospitality chains with direct ADA Title III exposure, consolidating vendor relationships onto unified platforms under procurement team centralization. Risk management departments in the United States prioritize rapid remediation overlay deployment to dismiss serial plaintiff claims.
- Government Agencies:Federal, state, and municipal entities bound by Section 508, EN 301 549, and procurement disqualification mechanisms, sustaining multi-year contracts through formal RFP processes. Germany and France lead European implementation stringency with published violation remediation timelines.
- Educational Institutions:Universities and K-12 districts managing ADA Title II and Section 504 obligations alongside Office for Civil Rights complaint resolution.
- Non-Profit Organizations:Disability advocacy groups and service providers with mission-driven accessibility requirements but constrained procurement budgets.
Commanding largest absolute spend: Private Enterprises. Procurement formalization advancing fastest: Government Agencies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's venture capital concentration anchors North American accessibility software development, while Stuttgart's automotive engineering cluster and Sydney's government procurement frameworks shape demand patterns across distinct regulatory environments.
United States
Federal contractor supply chains and serial plaintiff litigation drive enterprise procurement of automated testing platforms. The Department of Justice ADA enforcement surge tightens compliance timelines for digital publishers and e-commerce platforms. Washington D.C. hosts Level Access's federal sector relationships, sustaining multi-year government contracts through Section 508 conformance requirements.
Germany
Automotive OEM digital showrooms and industrial machinery human-machine interfaces generate specialized accessibility engineering demand. The EU Web Accessibility Directive transposition through EN 301 549 mandates public sector procurement disqualification for non-compliant vendors. Munich and Stuttgart clusters concentrate developer tooling vendors integrating accessibility into manufacturing software supply chains.
Australia
Banking and retail sectors face Disability Discrimination Act exposure accelerating native application compliance investment. Federal and state procurement frameworks mandate standalone accessibility supplier certification ahead of European implementation timelines. Sydney anchors the most pronounced procurement unbundling pattern, separating compliance verification from creative agency contracts.
United Kingdom
Financial services regulatory technology budgets and public sector digital transformation programs expand addressable market scope. The Equality Act 2010 and Public Sector Bodies Accessibility Regulations enforce WCAG 2.1 AA conformance across government digital services. London's fintech concentration drives demand for embedded finance accessibility overlays in banking-as-a-service integrations.
Canada
Provincial accessibility legislation harmonization and federal contractor supply chain requirements create procurement complexity for cross-border vendors. The Accessible Canada Act establishes 2040 compliance deadlines for federally regulated industries including banking and telecommunications. Toronto's technology corridor concentrates enterprise sales teams serving Fortune 500 North American headquarters.
Global Digital Accessibility Software Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue AI-powered remediation and immersive content accessibility modules. The vendor ecosystem compresses as enterprise procurement teams demand unified platforms spanning testing, audit, and remediation under single contracts. Three archetypes dominate: federal sector specialists leveraging long-term government relationships, developer tooling vendors embedding into CI/CD pipelines, and automated remediation providers targeting high-volume e-commerce transaction environments. Consolidation pressure manifests through strategic partnership formations and technology licensing arrangements rather than outright acquisition activity.
Within the federal specialist archetype, Level Access anchors multi-year contracting relationships through deep Section 508 expertise. Deque Systems, Inc. exemplifies the developer tooling tier, with its incorporation structure signaling enterprise software heritage. AudioEye, Inc. occupies the automated remediation position, its naming convention indicating sensory accessibility specialization. These three entities collectively represent the strategic positioning vectors—government, engineering workflow, and rapid deployment—that vendors must navigate as procurement centralization accelerates.
| Leading Market Players |
|---|
| Level Access |
| AudioEye, Inc. |
| Deque Systems, Inc. |
| Siteimprove |
| UsableNet Inc. |
| accessiBe Inc. |
| Silktide Ltd |
| UserWay |
| AccessibilityChecker.org INC |
| Others |
Supply & Pricing Matrix
Enterprise procurement consolidation onto unified accessibility platforms is forcing vendors to unbundle automated testing engines from manual audit services, compressing margins on standalone tooling while elevating premium pricing for integrated remediation overlays that satisfy Fortune 500 single-contract mandates.
Pricing Analysis
Warranty and service bundling separates premium-tier vendors from economy competitors, with three-tier pricing structure across premium, standard, and economy levels anchored by certification grade and after-sales support intensity. Price differentiation hinges on WCAG 2.2 conformance validation depth and jurisdiction-specific compliance module availability. Cost compression in standard-tier SaaS subscriptions is intensifying because hyperscaler infrastructure fees consume recurring revenue. Government agencies exhibit lowest price sensitivity due to multi-year appropriation cycles, while mid-market retailers demonstrate acute sensitivity to per-seat licensing costs.
Supply Chain Analysis
Certification and qualification gating through IAAP credential requirements constrains qualified manual auditor availability, creating supply bottlenecks that propagate into audit backlog pricing premiums. Engineering talent concentrates in the United States, Germany, and India, with machine learning inference engine development drawing from hyperscaler cloud infrastructure and open-source accessibility testing libraries. Single-source vulnerability in AWS, Azure, and Google Cloud hosting creates concentration risk for elastic scaling-dependent vendors. Distribution runs through direct enterprise sales teams and digital agency partnership channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as vendors pursue backward integration into proprietary machine learning training datasets to differentiate inference engine accuracy and reduce dependency on third-party computer vision APIs.
For Market Incumbents: To counter emerging AI-native entrants with superior dynamic single-page application scanning, Level Access and Deque Systems should deepen upstream control over WCAG auditor certification pipelines and expand in-house captioning transcription capacity. Federal sector specialists must secure EN 301 549 jurisdiction-specific module development ahead of European harmonization gaps closing. For New Entrants and Emerging Players: Enter via immersive content accessibility modules for enterprise VR training platforms, where captioning and haptic feedback standards remain undefined. The most penetrable white-space sits in banking-as-a-service embedded finance compliance for non-financial merchants. A channel partnership strategy with retail SaaS checkout providers accelerates customer acquisition without direct enterprise sales infrastructure. For Investors and Strategic Acquirers: The window for entry favors developer tooling vendors with established CI/CD pipeline integration and recurring revenue visibility. Acquisition targets should demonstrate machine learning inference engine differentiation rather than rules-based legacy architectures. Watch for ADA Title III litigation expansion into native mobile applications as the inflection signal triggering platform consolidation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified testing-audit-remediation bundles capture Fortune 500 procurement centralization mandates. |
| Machine Learning Engine Development | Proprietary inference datasets displace rules-based scanners in dynamic application coverage. |
| Jurisdiction-Specific Compliance Module | EN 301 549 and Section 508 rule engines address multi-jurisdiction procurement requirements. |
| CI/CD Pipeline Embedding | Developer workflow integration captures budget allocations from post-launch manual audits. |
| Strategic Partnership | Hyperscaler alliances secure elastic scaling capacity and co-selling into cloud-native enterprises. |
Research Methodology
SEC filings, hyperscaler capex disclosures, and federal procurement databases formed the secondary backbone, supplemented by primary interviews with CTOs, IT procurement officers, platform engineers, and integration specialists across the United States, Germany, and Australia. Bottom-up deployment model sizing and top-down enterprise software spend allocation were triangulated against WCAG litigation filing trends and public sector accessibility framework documentation.
Historical trendline analysis of cloud accessibility platform adoption informed elasticity assumptions across the projection horizon. Segmentation dimensions modeled include deployment architecture, solution offering category, use case channel, and end-user institutional type. CAGRs were derived from regression analysis against regulatory enforcement intensity indices and enterprise procurement centralization metrics, with machine learning inference engine penetration and native application litigation velocity as key forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ADA Title III enforcement acceleration or EU Web Accessibility Directive transposition delays. Model outputs reflect assumptions regarding auditor certification pipeline expansion and hyperscaler pricing trajectory. A model refresh is warranted upon material change in federal accessibility procurement appropriation levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Assortment and Space Optimization (ASO) Market
Digital Solutions
IT Asset Management (ITAM) Software Market
Digital Solutions
Premium Messaging Market
Digital Solutions
Route Optimization Software Market
Digital Solutions
Media Asset Management (MAM) Solutions Market
Digital Solutions
Tail Spend Management Solutions Market
Digital Solutions
Data Monetization Solutions for Life Science Companies Market
Digital Solutions
Demand Signal Repository Solutions Market
Digital Solutions
Digital Check Scanning Solutions Market
Digital Solutions
Location As a Service Market
Digital Solutions
Enterprise Information Management (EIM) Solution Market
Digital Solutions
Global Digital Workplace Software Market
Digital Solutions
Global Surface Computing Market
Digital Solutions
Cloud Based Simulation Application Market
Digital Solutions
Decision Support System Market
Digital Solutions
Asia Pacific B2C Legal Services Market