
 Space and Workplace Management Software Market | 2026-2036
Space and Workplace Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Space and Workplace Management Software Market Analysis
Enterprise real estate teams is rotating demand toward integrated workplace experience platforms, displacing standalone point solutions. Eptura leverages its combined heritage in asset and space management to anchor mid-market expansion. Envoy differentiates through visitor management workflows that extend into broader security ecosystems. Robin competes aggressively on mobile-first desk booking interfaces that appeal to technology sector buyers.
Space and workplace management software encompasses integrated digital platforms that orchestrate physical resource allocation through real-time occupancy sensors, API-connected calendar systems, and automated booking engines. These systems primarily enable organizations to reduce underutilized square footage while supporting employee flexibility policies. Cloud-based deployment leads absolute revenue contribution due to faster implementation cycles and lower capital barriers, though hybrid architectures are gaining traction among financial services buyers with segmented data requirements. Room booking functionality remains the most mature product category, while space optimization modules command premium pricing due to their dependence on IoT sensor integration and advanced analytics pipelines.
EU GDPR and the EU AI Act impose strict constraints on biometric occupancy tracking and automated space allocation algorithms, compelling vendors to architect privacy-by-design features. The US Securities and Exchange Commission climate disclosure rules indirectly elevate demand for carbon footprint analytics embedded in workplace platforms. Stakeholders must evaluate whether their vendor roadmaps incorporate ambient intelligence capabilities without triggering cross-border data transfer complications.
Market Dynamics
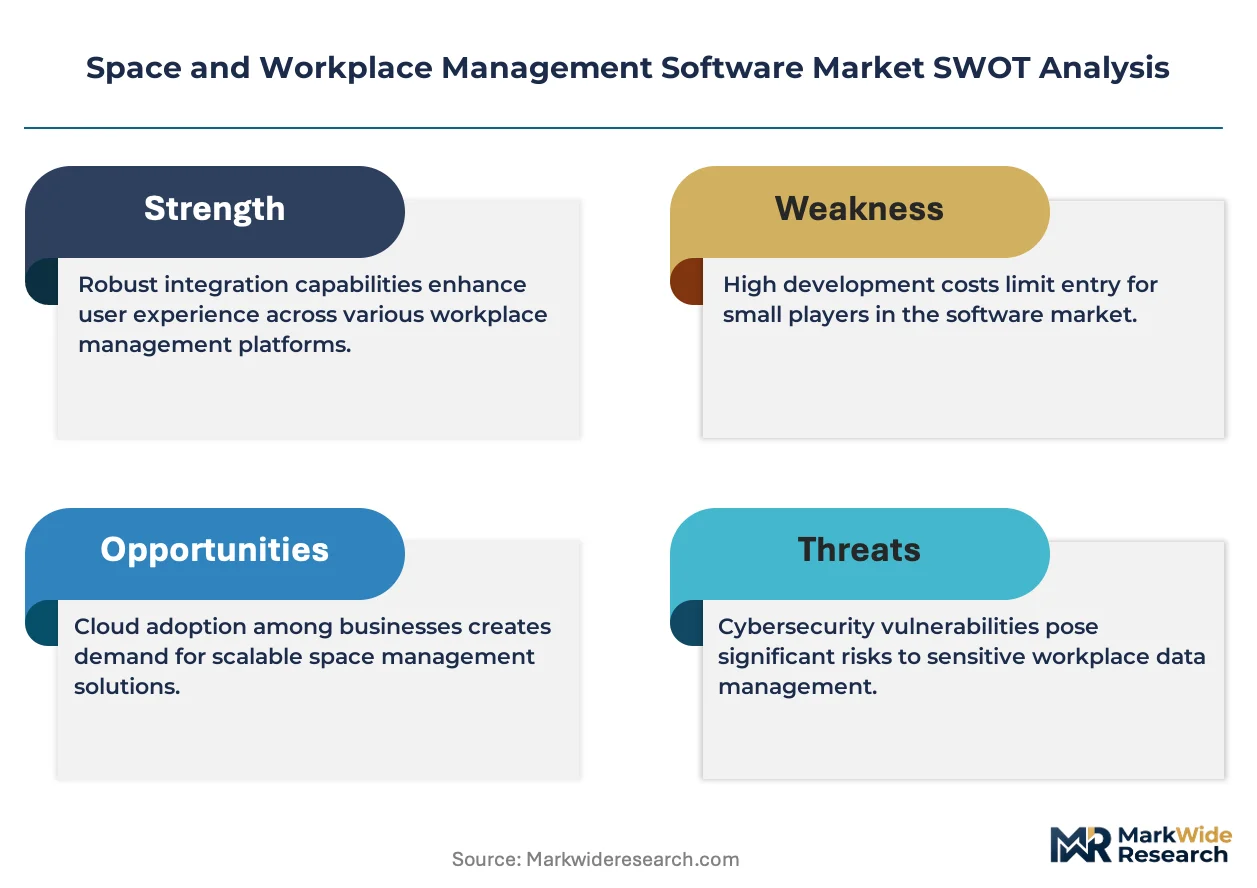
Enterprise real estate teams are consolidating vendor relationships around unified workplace experience platforms, compressing procurement cycles for standalone point solutions while elevating demand for API-native architectures that integrate occupancy sensing, carbon analytics, and employee-facing mobile interfaces into single contracts.
Growth Catalysts
- EU AI Act compliance mandates:Biometric occupancy tracking restrictions are accelerating vendor investment in privacy-preserving computer vision alternatives. Financial services and healthcare buyers in Germany and France now require these capabilities.
- Hybrid work policy stabilization:Technology sector employers in the United States and Japan are formalizing desk-sharing ratios above 1.5:1, driving recurring license expansion for dynamic booking engines.
- IoT sensor cost curves:Passive infrared and time-of-flight occupancy sensors have crossed price thresholds enabling mass deployment across mid-market office portfolios.
Market Restraints
- Cloud data sovereignty requirements:EU GDPR and emerging national data localization laws fragment vendor infrastructure strategies. Providers must maintain region-specific instances, elevating operational complexity.
- Legacy building management system integration:BACnet and Modbus protocol heterogeneity in installed building automation creates technical friction that extends implementation timelines.
- Biometric data litigation exposure:Illinois BIPA and comparable state privacy statutes in the United States impose statutory damages that deter aggressive facial recognition deployment.
Strategic Opportunities
- Carbon footprint analytics embedding:US SEC climate disclosure rules and EU CSRD extend compliance obligations to Scope 2 and Scope 3 emissions. Workplace platforms that automate utility data ingestion and emission factor calculation capture premium positioning.
- Healthcare and life sciences vertical expansion:Hospital systems require hot-desking for clinical staff with stringent credentialing and zone-access controls. This segment remains underpenetrated relative to technology and financial services.
- Ambient intelligence convergence:Integration of occupancy sensing with HVAC and lighting control systems enables autonomous building optimization. Early deployments in Singapore and Netherlands commercial towers demonstrate technical viability.
Industry Challenges
- Cross-functional implementation coordination:Successful deployment requires synchronization between IT security, facilities management, and human resources functions. Misaligned stakeholder priorities stall pilot-to-production transitions.
- Sensor calibration and drift maintenance:Physical occupancy sensors require periodic recalibration to maintain accuracy. Portfolio-scale maintenance programs strain vendor service organization capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Space and Workplace Management Software Market |
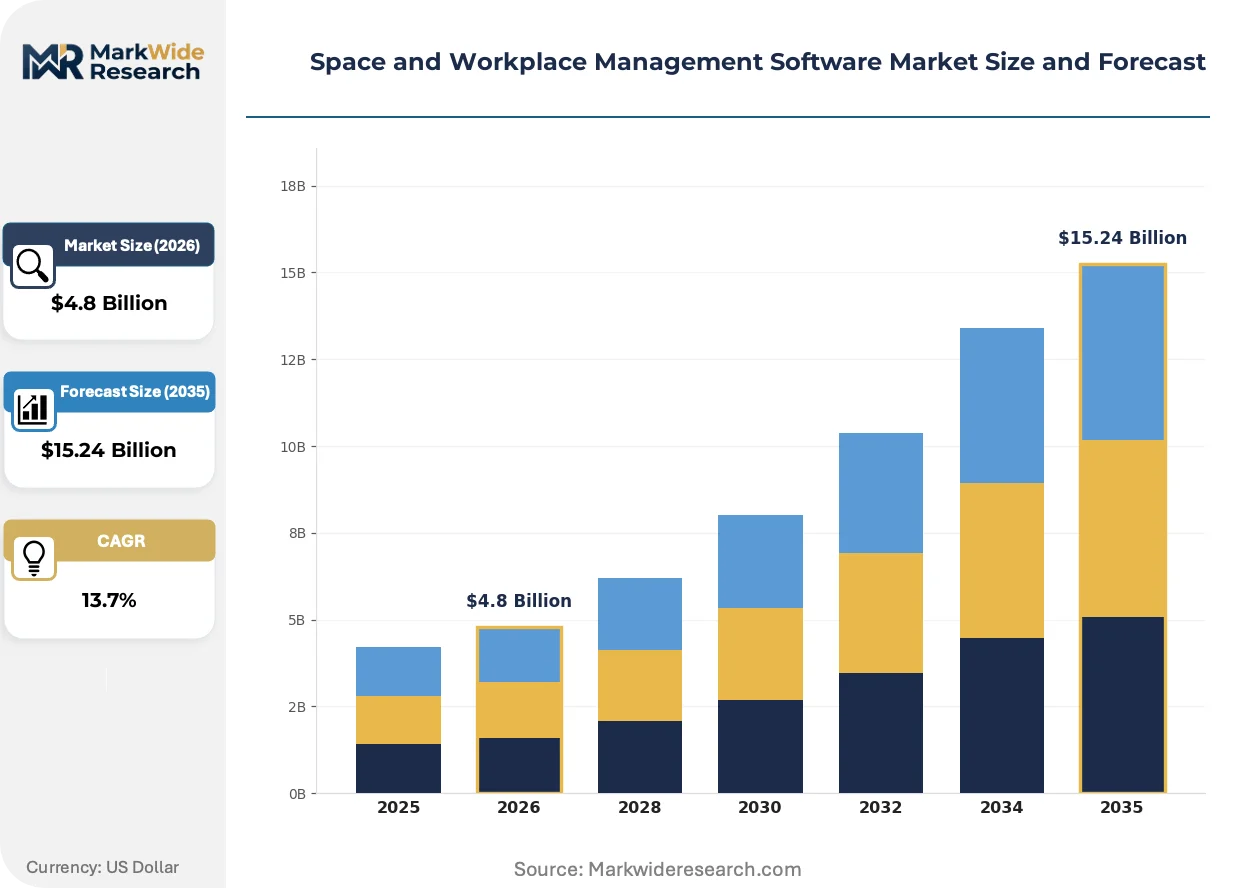
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.24 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, SaaS End User: Corporations, Educational Institutions, Government Agencies, Healthcare Facilities Product Type: Room Booking, Space Optimization, Visitor Management, Asset Tracking Feature: Analytics, Mobile Access, Integration Capabilities, Customization |
| Companies Covered | Skedda, Archie, OfficeSpace Software, Condeco, Envoy, Robin, Nexudus, FM:Systems, Eptura, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Space and Workplace Management Software Market Emerging Trajectories
Ambient intelligence capabilities are migrating from experimental building pilots to standard procurement requirements, compressing the competitive window for vendors that lack real-time environmental sensing and autonomous control integration.
Computer vision-based occupancy detection is fragmenting across multiple technical approaches including edge-based processing, on-device inference, and cloud-analyzed video streams. Large technology employers in California and Washington are piloting privacy-preserving depth cameras that eliminate biometric capture. This fragmentation is creating vendor specialization around latency-sensitive versus accuracy-optimized deployment profiles.
The EU AI Act's risk classification framework for biometric identification systems is forcing architectural redesigns of space allocation algorithms. Automated desk assignment based on inferred employee attributes now triggers enhanced conformity assessment obligations. German and French enterprise buyers are prioritizing vendors with documented algorithmic impact assessments and human-in-the-loop override mechanisms.
Subscription pricing for workplace platforms is displacing perpetual license models across buyer segments below ten thousand seats. Facilities management outsourcing firms in the United Kingdom and Australia are consolidating vendor relationships to capture volume discounts and unified service level agreements. This shift compresses vendor margins while extending customer lifetime value through automatic feature updates.
Space and Workplace Management Software Market Segmentation
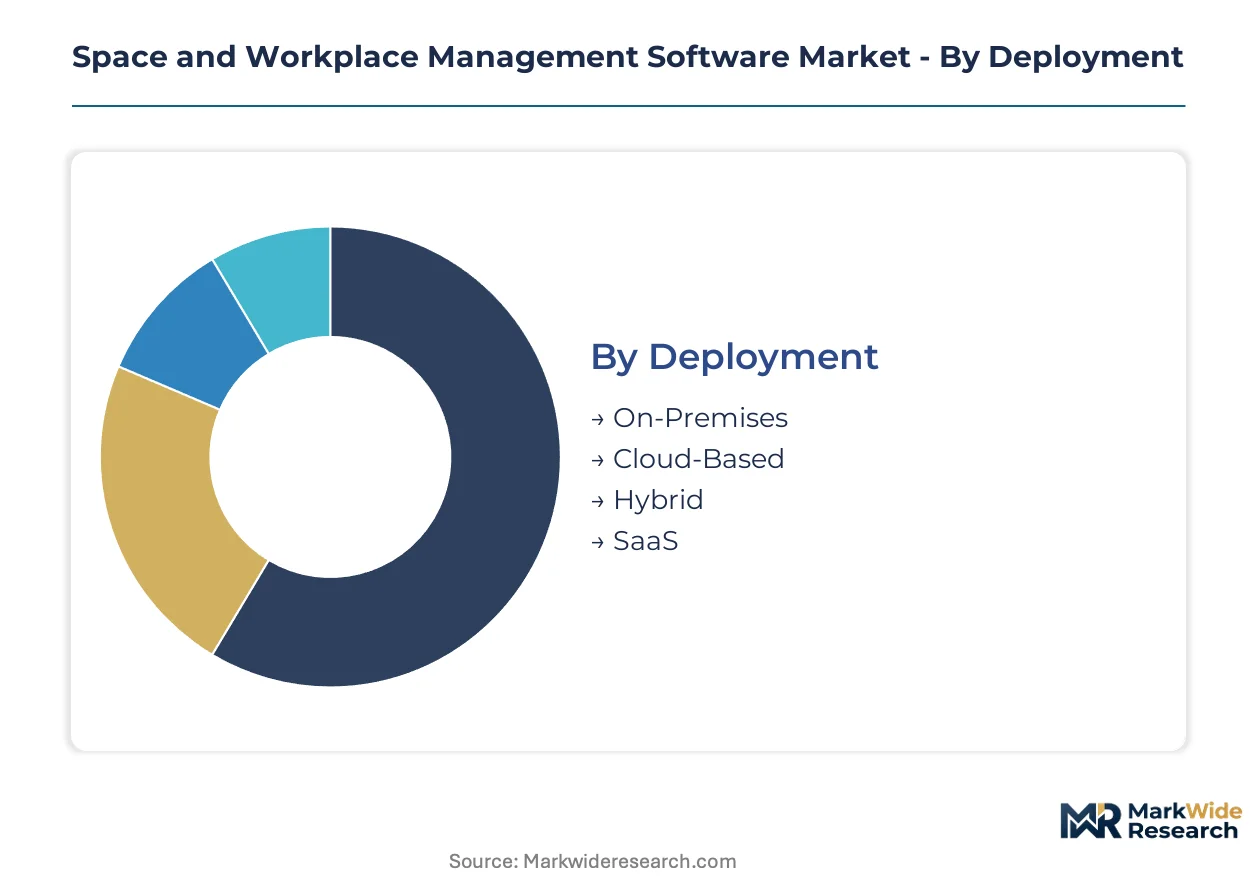
Segmentation in the space and workplace management software market reveals distinct procurement patterns across deployment architectures and user verticals. Each dimension carries specific compliance burdens and integration requirements that reshape vendor prioritization.
Deployment:
Cloud-based and SaaS offerings dominate export-oriented sales into data-sovereignty-conscious jurisdictions, while on-premises and hybrid deployments concentrate in domestic financial services and defense contracting.
- Cloud-Based:Multi-tenant architectures enable rapid provisioning across distributed office portfolios. Demand concentrates in United States technology employers formalizing desk-sharing ratios above 1.5:1, with procurement cycles compressed by pre-configured API integrations.
- Hybrid:Segmented data architectures separate employee-facing booking layers from sensitive occupancy analytics. German and French financial services buyers require these configurations to satisfy EU GDPR residency mandates without sacrificing real-time environmental sensing.
- On-Premises:Single-tenant installations persist in government and classified contracting where air-gapped networks are mandatory.
- SaaS:Subscription models displace perpetual licenses below ten thousand seats, with facilities management outsourcing firms in the United Kingdom and Australia consolidating vendor relationships for volume discounts.
Cloud-based deployments command the established base. The steepest expansion runs through hybrid architectures as data localization requirements proliferate.
End User:
Corporations drive volume procurement through centralized real estate functions, while healthcare and government segments impose specialized credentialing and zone-access requirements that elevate solution complexity.
- Corporations:Enterprise real estate teams consolidate vendor relationships around unified workplace experience platforms. Technology sector buyers in the United States and Japan prioritize mobile-first desk booking interfaces.
- Healthcare Facilities:Hospital systems require hot-desking for clinical staff with stringent credentialing and zone-access controls. This segment remains underpenetrated relative to technology and financial services.
- Government Agencies:Public sector procurement emphasizes FedRAMP and comparable security certifications, extending sales cycles.
- Educational Institutions:Campus-wide implementations coordinate classroom scheduling, research lab allocation, and administrative space.
Corporations anchor current revenue concentration. Healthcare facilities present the steepest expansion trajectory as clinical workforce mobility policies formalize.
Product Type:
Room booking functionality represents the most mature category with standardized procurement, while space optimization modules command premium pricing through IoT sensor dependencies.
- Room Booking:Calendar-integrated reservation engines with automated conflict resolution. Demand concentrates in United States and Japanese technology employers stabilizing hybrid work policies.
- Space Optimization:Real-time occupancy analytics pipelines processing sensor feeds for density recommendations. German and French buyers require privacy-preserving computer vision alternatives to satisfy EU AI Act biometric restrictions.
- Visitor Management:Credentialing workflows extending into broader security ecosystems with pre-registration and host notification.
- Asset Tracking:Indoor positioning for mobile equipment and furniture inventory across multi-floor facilities.
Room booking commands the established base. Space optimization gains share fastest as carbon footprint analytics embed into compliance reporting.
Feature:
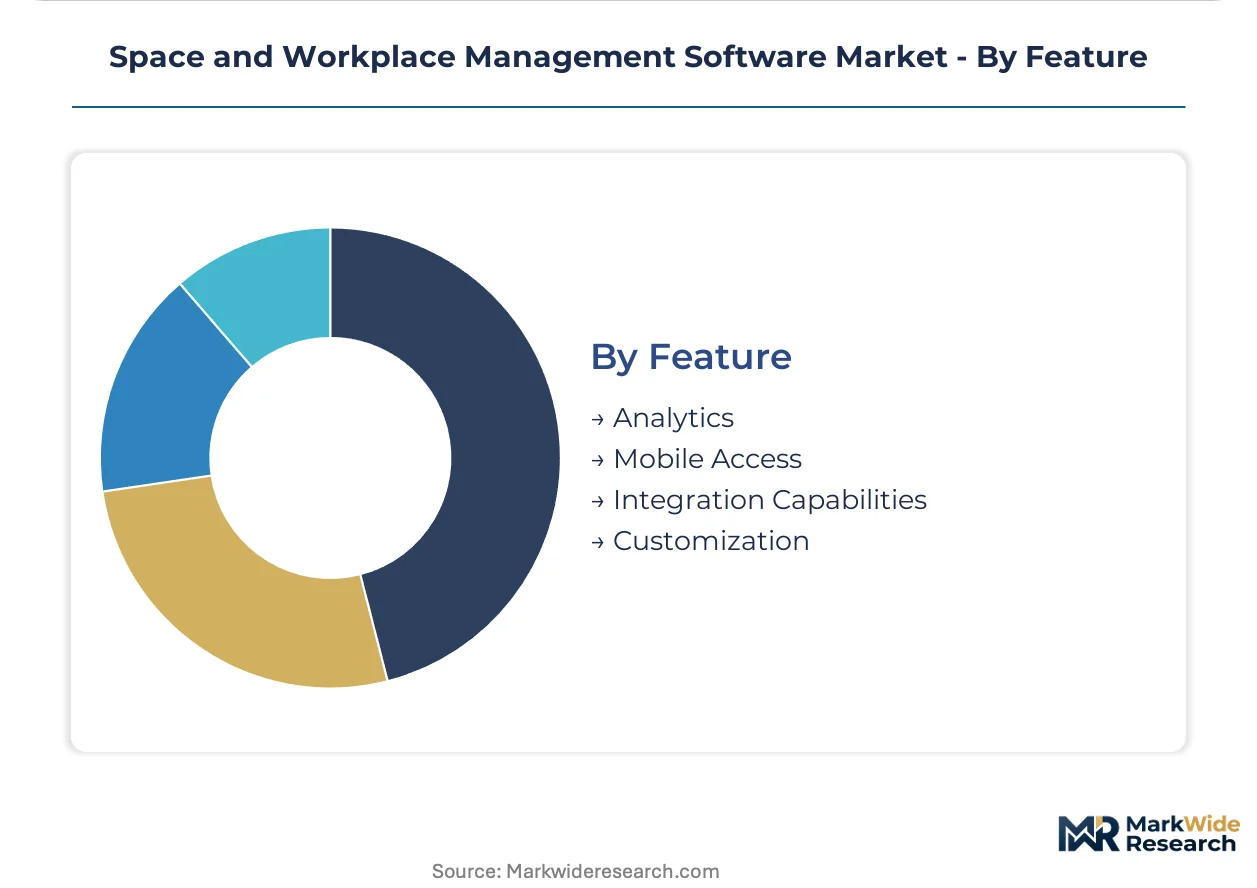
Analytics capabilities differentiate premium tiers through automated utility ingestion and emission factor calculation, while mobile access has become table stakes for competitive positioning.
- Analytics:Scope 2 and Scope 3 emissions calculation with automated utility data ingestion. United States SEC climate disclosure rules and EU CSRD elevate demand for these capabilities.
- Mobile Access:Native iOS and Android interfaces for desk booking, room reservation, and service requests. Technology sector buyers treat this as a non-negotiable requirement.
- Integration Capabilities:API-native architectures connecting to HR systems, building automation, and identity providers.
- Customization:White-labeling and workflow configuration for multi-brand corporate portfolios.
Mobile access commands the established base. Analytics capabilities expand most quickly as environmental disclosure obligations extend to workplace operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German workplace management vendors export integrated compliance platforms to French and Dutch enterprise buyers navigating EU AI Act biometric restrictions. This trade corridor channels privacy-preserving occupancy analytics northward while carbon disclosure tools flow west into London financial services procurement.
United States
Technology sector employers in San Francisco and Seattle formalize desk-sharing ratios above 1.5:1, expanding recurring license demand for dynamic booking engines. SEC climate disclosure rules elevate procurement priority for carbon footprint analytics modules. New York Metro financial services firms anchor hybrid architecture adoption to satisfy segmented data requirements.
Germany
Industrial Mittelstand employers in Bavaria and Baden-Württemberg consolidate vendor relationships around unified workplace platforms with API-native architectures. EU AI Act risk classification frameworks for biometric identification trigger enhanced conformity assessment obligations for space allocation algorithms. Frankfurt financial services procurement prioritizes vendors with documented algorithmic impact assessments.
Japan
Tokyo technology sector employers stabilize hybrid work policies with mobile-first desk booking interfaces as standard procurement requirements. METI building efficiency standards accelerate ambient intelligence pilot programs in Osaka commercial towers. Nagoya manufacturing headquarters deploy hot-desking for engineering staff with stringent zone-access controls.
United Kingdom
London facilities management outsourcing firms consolidate vendor relationships to capture volume discounts and unified service level agreements. UK GDPR enforcement actions against biometric data processing elevate demand for privacy-preserving computer vision alternatives. Manchester and Birmingham corporate portfolios drive subscription pricing displacement of perpetual licenses.
Singapore
Commercial tower developers in the Central Business District demonstrate technical viability for autonomous building optimization integrating occupancy sensing with HVAC control. National sustainability disclosure requirements elevate procurement priority for automated utility data ingestion. Government technology procurement mandates API-native architectures for smart nation infrastructure.
Space and Workplace Management Software Market Vendor Landscape
Player mix skews toward cloud-native workplace experience platforms displacing legacy on-premises installations. Market structure concentrates around vendors with integrated IoT sensor pipelines and carbon analytics capabilities. Two strategic archetypes dominate: unified platform consolidators bundling room booking, visitor management, and space optimization; and mobile-first specialists competing on employee-facing interface design. Competitive moves center on API ecosystem expansion and privacy-preserving computer vision development.
Within the unified platform tier, Eptura leverages combined heritage in asset and space management, while FM:Systems anchors enterprise real estate consolidation. Envoy occupies a distinct position extending visitor management workflows into broader security ecosystems. These three exemplify how vendor specialization around latency-sensitive versus accuracy-optimized deployment profiles fragments computer vision-based occupancy detection approaches.
| Leading Market Players |
|---|
| Skedda |
| Archie |
| OfficeSpace Software |
| Condeco |
| Envoy |
| Robin |
| Nexudus |
| FM:Systems |
| Eptura |
| Others |
Supply Flow & Price Mechanics
Subscription-based SaaS contracts with automatic renewal clauses lock in recurring revenue visibility while binding mid-market buyers to multi-year terms that suppress churn. These structures concentrate pricing power with vendors that embed IoT sensor pipelines and carbon analytics into unified platforms, compressing margins for standalone point solutions.
Pricing Analysis
Cloud-native deployment pricing gaps separate incumbent SaaS tiers from legacy on-premises perpetual licenses and emerging ambient intelligence bundles. Three-tier pricing structure across premium, standard, and economy levels stratifies by integration complexity and sensor density, with premium tiers commanding attach rates for carbon footprint modules. Cost compression in standard tiers stems from facilities management outsourcing firms consolidating vendor relationships for volume discounts. Mid-market technology employers in the United States exhibit highest price sensitivity, while German financial services buyers prioritize compliance-certified configurations regardless of premium positioning.
Supply Chain Analysis
China and Taiwan anchor passive infrared and time-of-flight sensor fabrication, while the United States and Germany concentrate cloud infrastructure and edge computing hardware. Software supply chains draw from open-source analytics frameworks, proprietary computer vision algorithms, and API middleware libraries. Single-source vulnerability concentrates in sensor semiconductor foundries, where geopolitical friction threatens component availability. Distribution runs through direct enterprise sales teams for large deployments, supplemented by channel partners serving mid-market portfolios in the United Kingdom and Australia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Recurring service revenue from sensor maintenance, calibration programs, and carbon analytics subscriptions expands faster than perpetual license recognition, transforming vendor economics toward lifetime value capture.
For Market Incumbents: Compound platform stickiness by embedding ambient intelligence capabilities that fuse occupancy sensing with HVAC control, displacing standalone building automation vendors. Prioritize backward integration into edge hardware to reduce sensor cost exposure and accelerate deployment velocity. Defend against mobile-first specialists by anchoring enterprise real estate consolidation around API-native architectures that span room booking, visitor management, and space optimization. For New Entrants and Emerging Players: Differentiate on privacy-preserving computer vision alternatives that satisfy EU AI Act biometric restrictions without triggering enhanced conformity assessments. Target healthcare facilities in Germany and Japan, where clinical workforce hot-desking policies remain underpenetrated relative to technology and financial services. Pursue white-label partnerships with facilities management outsourcing firms seeking unified service level agreements across multi-brand corporate portfolios. For Investors and Strategic Acquirers: Cloud-native workplace experience platforms with demonstrated algorithmic impact assessments and human-in-the-loop override mechanisms represent priority acquisition archetypes. Long-term viability hinges on vendor capacity to navigate fragmented data sovereignty requirements without sacrificing real-time environmental sensing capabilities. Watch for inflection signals in German and French procurement patterns, where EU AI Act enforcement actions are elevating compliance documentation to disqualification thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Privacy-Preserving Computer Vision Development | EU AI Act biometric restrictions in Germany and France mandate architectural redesigns for occupancy detection. |
| Carbon Analytics Module Integration | US SEC climate disclosure rules and EU CSRD extend compliance obligations to Scope 2 and Scope 3 emissions tracking. |
| API Ecosystem Expansion | Enterprise real estate teams consolidate vendor relationships around unified platforms connecting HR systems and building automation. |
| Healthcare Vertical Penetration | Hospital systems require hot-desking with stringent credentialing and zone-access controls in underpenetrated segments. |
| Sensor Maintenance Service Programs | Portfolio-scale calibration and drift management strain vendor service organization capacity, creating attach revenue opportunities. |
Methodological Framework
Cross-validation between primary interviews with enterprise real estate directors, facilities management executives, IT procurement officers, and building automation engineers anchors the qualitative findings. Secondary validation draws from SEC filings, EU regulatory impact assessments, hyperscaler workplace platform disclosures, and commercial real estate investment trust reports. Bottom-up deployment estimates triangulate against top-down market sizing derived from cloud infrastructure spending patterns and IoT sensor shipment data.
Sensitivity analysis frameworks test forecast robustness across deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern dimensions. CAGRs derive from segmented growth rate assumptions calibrated to hybrid work policy stabilization timelines and IoT sensor cost curve trajectories. Input variables include desk-sharing ratio formalization rates, EU AI Act implementation enforcement intensity, and carbon disclosure regulatory expansion scope.
Material uncertainties — regulatory enforcement variance, sensor semiconductor supply disruptions, and cross-functional implementation coordination failures — sit outside the modeled envelope. Forecasts reflect assumptions about hybrid work policy permanence and data sovereignty requirement proliferation. Recalibration cycles align with material shifts in EU AI Act risk classification interpretations and US SEC climate disclosure rule finalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Quality Process Management Application Market
Digital Solutions
Content Moderation Services Market
Digital Solutions
Data As a Service (Daas) Market
Digital Solutions
United States Contract Manufacturing Services Market
Digital Solutions
Mexico Digital Showers Market
Digital Solutions
North America Digital Signage Market
Digital Solutions
Healthcare Computerized Maintenance Management System Market
Digital Solutions
Mexico ICT Market
Digital Solutions
Audio Over IP Solutions Market
Digital Solutions
Global Transport Management Software Market
Digital Solutions
Saudi Arabia Digital Twin Market
Digital Solutions
Database Management Platform Market
Digital Solutions
Revenue Management Solutions Market
Digital Solutions
Commercial P2P CDN Market
Digital Solutions
UK High Performance Computing Market
Digital Solutions
Real-Time Temperature and Location Monitoring Platforms for Cold Chain Market