
 Enterprise Imaging Solutions Market | 2026-2036
Enterprise Imaging Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Enterprise Imaging Solutions Market Analysis
Radiologist workforce shortages across developed health systems is bifurcating vendor strategies between automation-heavy platforms and workflow-consolidation suites. Siemens Healthineers leverages its embedded AI diagnostics to sustain premium positioning in academic medical centers. GE HealthCare competes through deep hardware-software integration across its imaging install base. Philips anchors its enterprise imaging portfolio on interoperable cloud architectures that span hospital networks.
Enterprise Imaging Solutions integrate picture archiving and communication systems (PACS), vendor-neutral archives (VNA), and clinical viewers into unified platforms that manage DICOM and non-DICOM imaging data across departments. These systems centralize storage, retrieval, and distribution of diagnostic images to eliminate siloed departmental archives and enable enterprise-wide clinical collaboration. Cloud-based deployments are capturing the fastest expansion as health systems prioritize capital-light subscription models and remote accessibility. Radiology maintains the largest revenue share given scan volumes and regulatory complexity, while cardiology imaging represents a concentrated margin pool due to structured reporting requirements and integration with hemodynamic systems.
The FDA enforces interoperability standards under the 21st Century Cures Act that mandate API-enabled data exchange, while HIPAA governs patient data security across cloud and hybrid deployments. The EU Medical Device Regulation (MDR) reclassifies software with diagnostic functions, extending conformity assessment burdens for vendors serving European hospitals. Stakeholders must monitor how FDA artificial-intelligence guidance for radiological devices reshapes algorithm validation requirements and market access timelines for AI-enhanced imaging platforms.
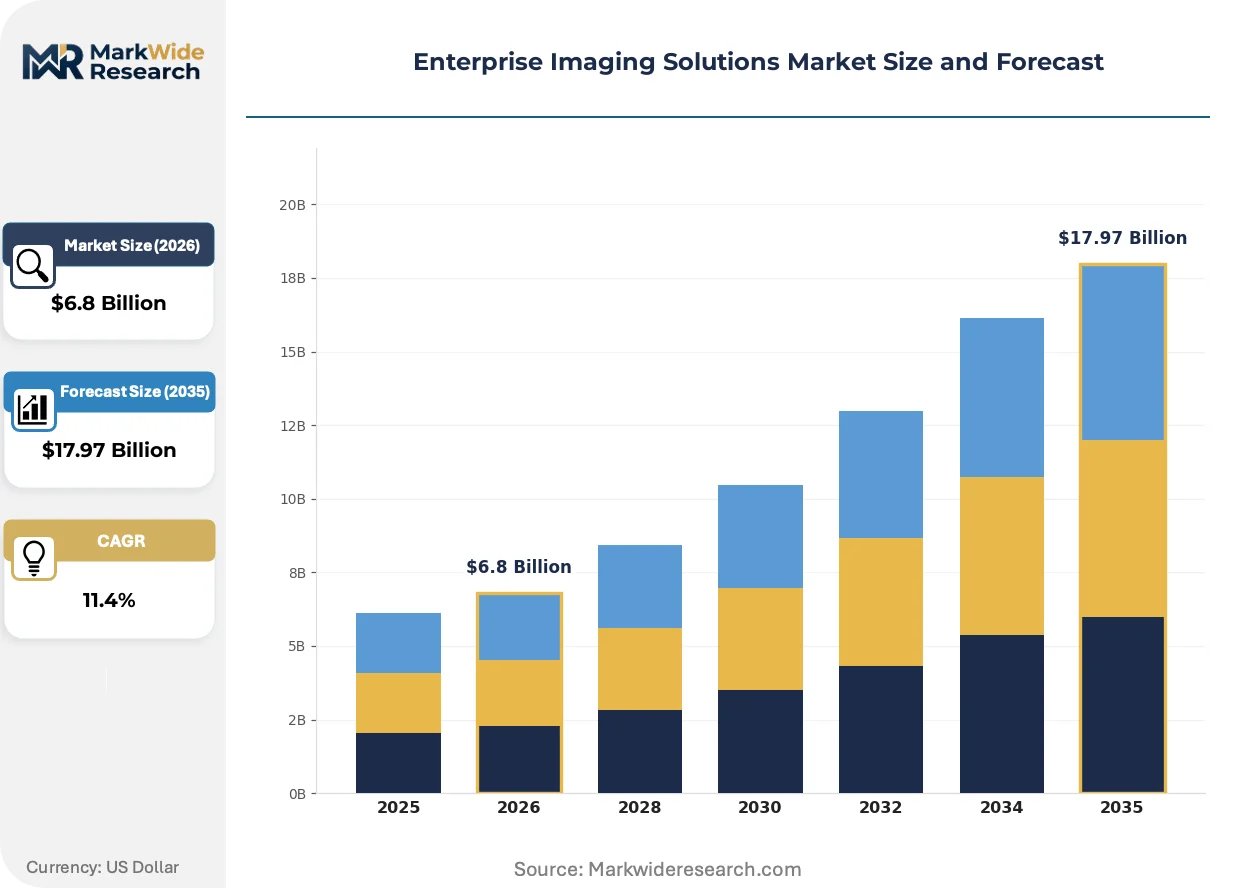
Market Dynamics
Cloud-native architectures are decomposing legacy PACS hierarchies as health systems abandon capital-intensive on-premise infrastructure for subscription-based platforms that unify radiology, cardiology, and pathology workflows.
Growth Catalysts
- FDA 21st Century Cures Act:API interoperability mandates force vendors to replace siloed departmental archives with open-data architectures. Hospital networks accelerate procurement cycles to meet compliance deadlines.
- Germany's Hospital Future Act:Federal digitization frameworks consolidate imaging infrastructure across university hospitals, creating concentrated demand for vendor-neutral archives.
- AI-augmented diagnostic workflows:Embedded machine learning algorithms in radiology platforms reduce interpretation time and address workforce shortages in academic medical centers.
Market Restraints
- Data migration complexity:Decades of DICOM and non-DICOM archives in proprietary formats impose technical debt that slows cloud transitions.
- EU MDR conformity burdens:Reclassification of diagnostic software extends validation timelines and certification costs for vendors serving European hospitals.
- Radiologist workforce scarcity:Developed health systems face structural shortages that limit adoption velocity regardless of platform sophistication.
Strategic Opportunities
- Cardiology imaging integration:Structured reporting requirements and hemodynamic system connectivity create margin-rich expansion beyond radiology.
- India's Ayushman Bharat digitization:National health stack initiatives open public hospital procurement for cloud-native imaging platforms.
- Edge computing convergence:Hybrid architectures combining central cloud storage with on-premise inference nodes address latency-sensitive emergency workflows.
Industry Challenges
- HIPAA compliance engineering:Cloud deployments require continuous security architecture validation across multi-tenant environments.
- Interoperability standardization:Competing FHIR implementation guides create integration friction between vendor platforms.
- Legacy system coexistence:Hybrid deployments demand specialized talent for bridging on-premise archives with cloud-native viewers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enterprise Imaging Solutions Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radiology, Cardiology, Oncology, Orthopedics Technology: Cloud-Based, On-Premises, Hybrid, Mobile End User: Hospitals, Clinics, Imaging Centers, Research Laboratories Application: Diagnostic Imaging, Radiotherapy Planning, Image Archiving, Research & Development |
| Companies Covered | Optum, Inc., Siemens Healthineers AG, Agfa-Gevaert Group, Intelerad, Pro Medicus, Ltd., GE HealthCare, Koninklijke Philips N.V., Sectra AB, FUJIFILM Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enterprise Imaging Solutions Market Emerging Trajectories
Containerized microservices architectures are reshaping how imaging platforms scale, enabling modular deployment of AI inference engines and viewer components without monolithic system overhauls.
Serverless computing is decomposing traditional PACS architectures into discrete functions for routing, storage, and display. Academic medical centers in the United States pilot these architectures for research imaging pipelines. The structural consequence is decomposing vendor lock-in by enabling substitution of individual components rather than full-platform replacement.
The EU Medical Device Regulation reclassifies software with diagnostic functions, extending conformity assessment burdens for algorithms that interpret radiological images. Vendors serving European hospitals must maintain technical documentation and clinical evidence packages that satisfy notified body scrutiny. Germany's university hospital networks delay procurement decisions pending MDR certification clarity.
Subscription pricing models displace perpetual license structures as health systems prioritize operational expenditure over capital allocation. Hospital procurement committees now evaluate total cost of ownership across five-year horizons rather than upfront acquisition costs. This shift concentrates most visibly in North American integrated delivery networks negotiating enterprise-wide platform contracts.
Enterprise Imaging Solutions Market Segmentation
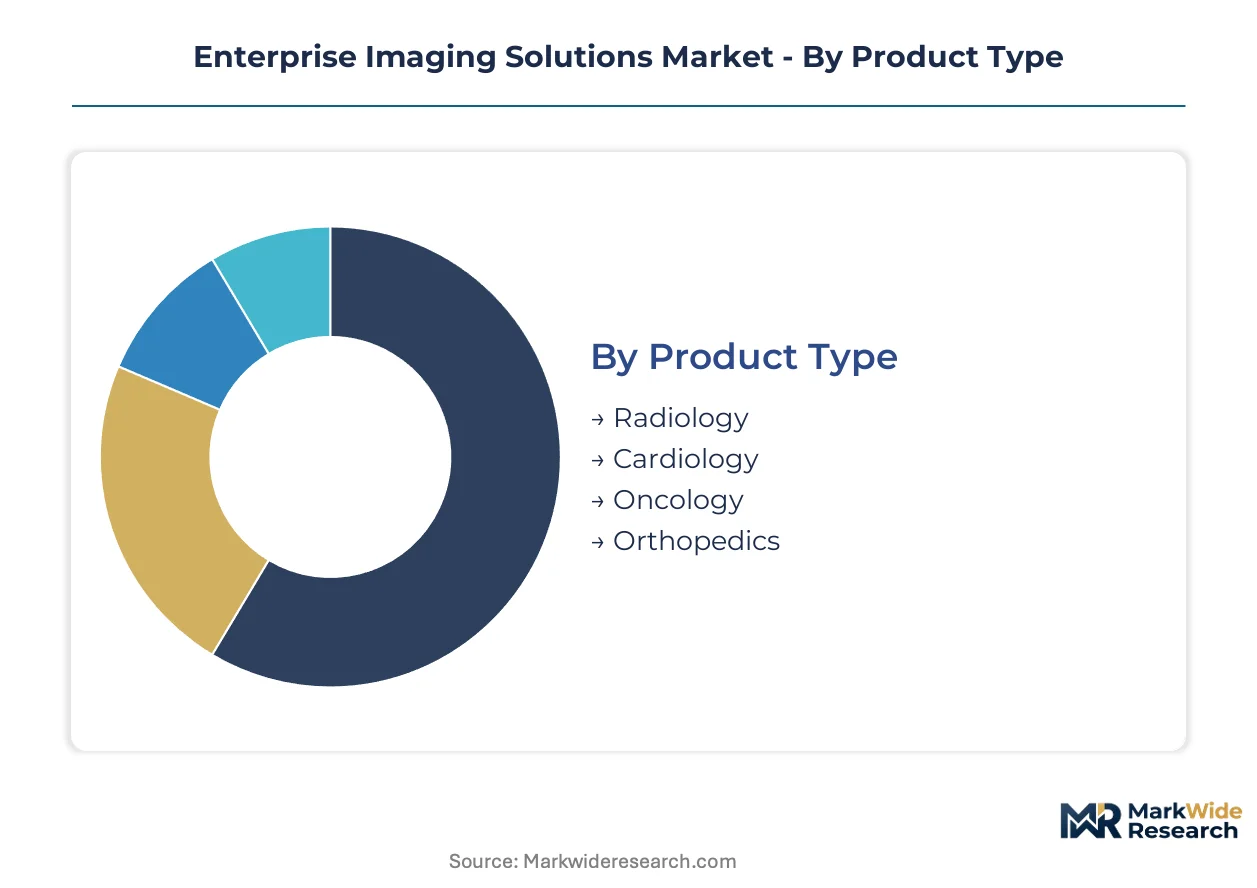
Segmentation in enterprise imaging reveals where capital deployment concentrates across clinical workflows and infrastructure architectures. Vendors calibrate platform development to margin-differentiated segments rather than uniform market coverage.
Product Type:
Margins pool in segments with structured reporting requirements and AI-augmented diagnostic complexity.
- Radiology:Platforms manage DICOM workflows across CT, MRI, and X-ray modalities with embedded machine learning for lesion detection. Academic medical centers in Germany consolidate procurement under federal digitization mandates, prioritizing vendor-neutral archives that unify multi-site operations.
- Cardiology:Systems integrate echocardiography, catheterization imaging, and hemodynamic data with structured reporting for procedural documentation. Hospital networks in the United States accelerate replacement of departmental PACS to meet FDA interoperability deadlines.
- Oncology:Multi-modality fusion platforms support tumor board workflows and longitudinal tracking.
- Orthopedics:3D surgical planning and implant templating modules address elective procedure volumes.
Radiology holds installed capacity. Cardiology is rotating up the share rankings.
Technology:
Deployment architecture determines total cost of ownership and procurement committee evaluation criteria.
- Cloud-Based:Subscription models eliminate capital expenditure for storage infrastructure while enabling remote access across distributed hospital networks. North American integrated delivery networks negotiate enterprise-wide contracts spanning radiology and cardiology workflows.
- Hybrid:Architectures combine central cloud repositories with on-premise inference nodes for latency-sensitive emergency reads. University hospitals pilot these configurations to balance accessibility with sub-second response requirements.
- On-Premises:Legacy installations persist where data residency requirements block external hosting.
- Mobile:Tablet-optimized viewers extend diagnostic access to point-of-care settings and teleradiology services.
Cloud-Based commands procurement momentum. Hybrid is climbing the fastest as a transitional architecture.
End User:
Customer scale dictates platform complexity and integration service requirements.
- Hospitals:Enterprise deployments unify imaging across radiology, cardiology, and pathology with single-vendor accountability. Germany's university hospital networks consolidate infrastructure under national digitization frameworks.
- Imaging Centers:High-volume outpatient facilities prioritize workflow efficiency and rapid report turnaround for referring physician relationships.
- Clinics:Smaller deployments favor lightweight cloud subscriptions with minimal IT overhead.
- Research Laboratories:Academic institutions require scalable storage for multi-terabyte research datasets and AI training pipelines.
Hospitals anchor revenue concentration. Imaging Centers are gaining share fastest among outpatient migration trends.
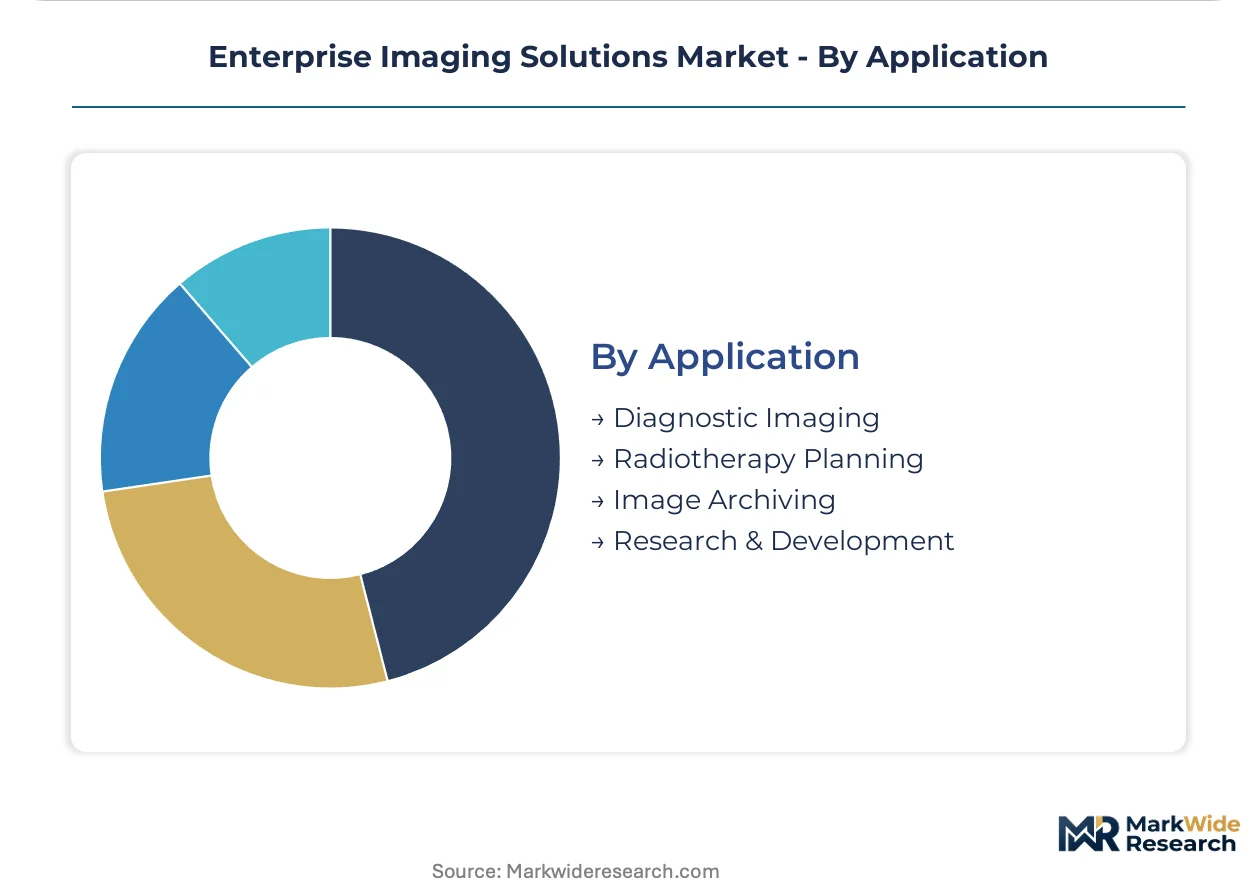
Application:
Use case specificity determines regulatory pathway and validation burden.
- Diagnostic Imaging:Primary interpretation workflows generate the core revenue base with embedded AI algorithms reducing radiologist reading time. FDA guidance on machine learning-based radiological devices reshapes validation requirements for algorithm vendors.
- Image Archiving:Long-term retention systems must reconcile decades of proprietary DICOM formats with modern interoperability standards.
- Radiotherapy Planning:Integration with treatment planning systems requires sub-millimeter spatial accuracy and contouring validation.
- Research & Development:Imaging biobanks and clinical trial data management demand anonymization pipelines and multi-site governance frameworks.
Diagnostic Imaging holds installed capacity. Image Archiving is rotating up the share rankings as migration projects accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA interoperability mandates anchor United States procurement cycles, while Germany's federal digitization frameworks and India's national health stack initiatives create concentrated demand pockets across three continents.
United States
Hospital networks accelerate cloud-native platform procurement to unify radiology and cardiology workflows. The FDA's 21st Century Cures Act API mandates force replacement of legacy PACS architectures by compliance deadlines. Academic medical centers in Boston and the Research Triangle pilot serverless computing architectures for research imaging pipelines.
Germany
University hospitals consolidate imaging infrastructure under the Hospital Future Act digitization frameworks. The EU Medical Device Regulation reclassification of diagnostic software extends conformity assessment burdens for algorithm vendors. Berlin and Munich hospital networks delay procurement decisions pending MDR certification clarity for AI-enhanced platforms.
India
Public hospital procurement opens for cloud-native imaging platforms through Ayushman Bharat national health stack initiatives. The country's central pharmaceutical regulator maintains oversight of software with diagnostic functions. Hyderabad and Bangalore health tech clusters attract enterprise imaging vendors targeting tier-two city hospital networks.
Japan
Aging demographics intensify radiologist workforce shortages, driving automation-heavy platform demand in academic medical centers. The PMDA governs software classification for diagnostic algorithms under revised medical device frameworks. Tokyo and Osaka metropolitan hospital systems prioritize vendor-neutral archives for multi-site imaging consolidation.
Australia
State health departments negotiate enterprise-wide imaging contracts spanning public hospital networks. The TGA oversees software-based medical device registration including AI-augmented diagnostic platforms. Melbourne and Sydney medical research institutes drive demand for scalable storage architectures supporting multi-terabyte imaging biobanks.
Enterprise Imaging Solutions Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with premium positioning concentrated among hardware-software integrated conglomerates and cloud-native platform specialists. Siemens Healthineers leverages embedded AI diagnostics to sustain positioning in academic medical centers. GE HealthCare competes through deep hardware-software integration across imaging install bases. Philips anchors portfolios on interoperable cloud architectures spanning hospital networks. Strategic moves concentrate on M&A for AI algorithm portfolios and strategic partnerships for cloud infrastructure scale.
Within the integrated diagnostics tier, Siemens Healthineers AG and Koninklijke Philips N.V. exemplify contrasting architectural philosophies—one emphasizing embedded AI within hardware ecosystems, the other prioritizing vendor-neutral cloud interoperability. GE HealthCare occupies a position bridging these approaches through install base leverage. Among imaging-centric specialists, Sectra AB and Intelerad represent the cloud-native and workflow-consolidation archetypes respectively. Agfa-Gevaert Group and FUJIFILM Corporation anchor the legacy-to-cloud transition segment, while Pro Medicus, Ltd. exemplifies the high-performance visualization specialist tier. Optum, Inc. represents the health services conglomerate vector, integrating imaging platforms within broader care delivery ecosystems.
| Leading Market Players |
|---|
| Optum, Inc. |
| Siemens Healthineers AG |
| Agfa-Gevaert Group |
| Intelerad |
| Pro Medicus, Ltd. |
| GE HealthCare |
| Koninklijke Philips N.V. |
| Sectra AB |
| FUJIFILM Corporation |
| Others |
Supply Flow & Price Mechanics
Cloud infrastructure scale economies in North American hyperscaler regions compress storage costs for enterprise imaging vendors, concentrating supply-side bargaining power among three dominant platform providers while establishing subscription price floors that undercut perpetual license alternatives.
Pricing Analysis
North American hospital networks pay 15-25% subscription premiums over Western European academic centers for equivalent cloud-native platform tiers, reflecting higher FDA compliance engineering costs embedded in US-facing deployments. Pricing stratifies across premium, standard, and economy tiers according to AI module depth and multi-site deployment scale. Cost compression in standard-tier subscriptions is intensifying because hyperscaler storage commoditization erodes vendor differentiation. Imaging centers exhibit highest price sensitivity due to thin outpatient margins, while university hospital networks demonstrate lowest sensitivity given federal digitization grant offsets.
Supply Chain Analysis
The United States and Germany anchor enterprise imaging software development, with India supplying engineering talent pools for cloud-native platform construction. Component dependencies include GPU clusters for AI inference, object storage architectures, and FHIR-compliant middleware layers. Single-source vulnerability concentrates in NVIDIA-dominated AI accelerator supply, exposing vendors to allocation constraints during semiconductor cycles. Distribution runs through direct enterprise sales teams for hospital network contracts, supplemented by GPO aggregation for mid-tier imaging center procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
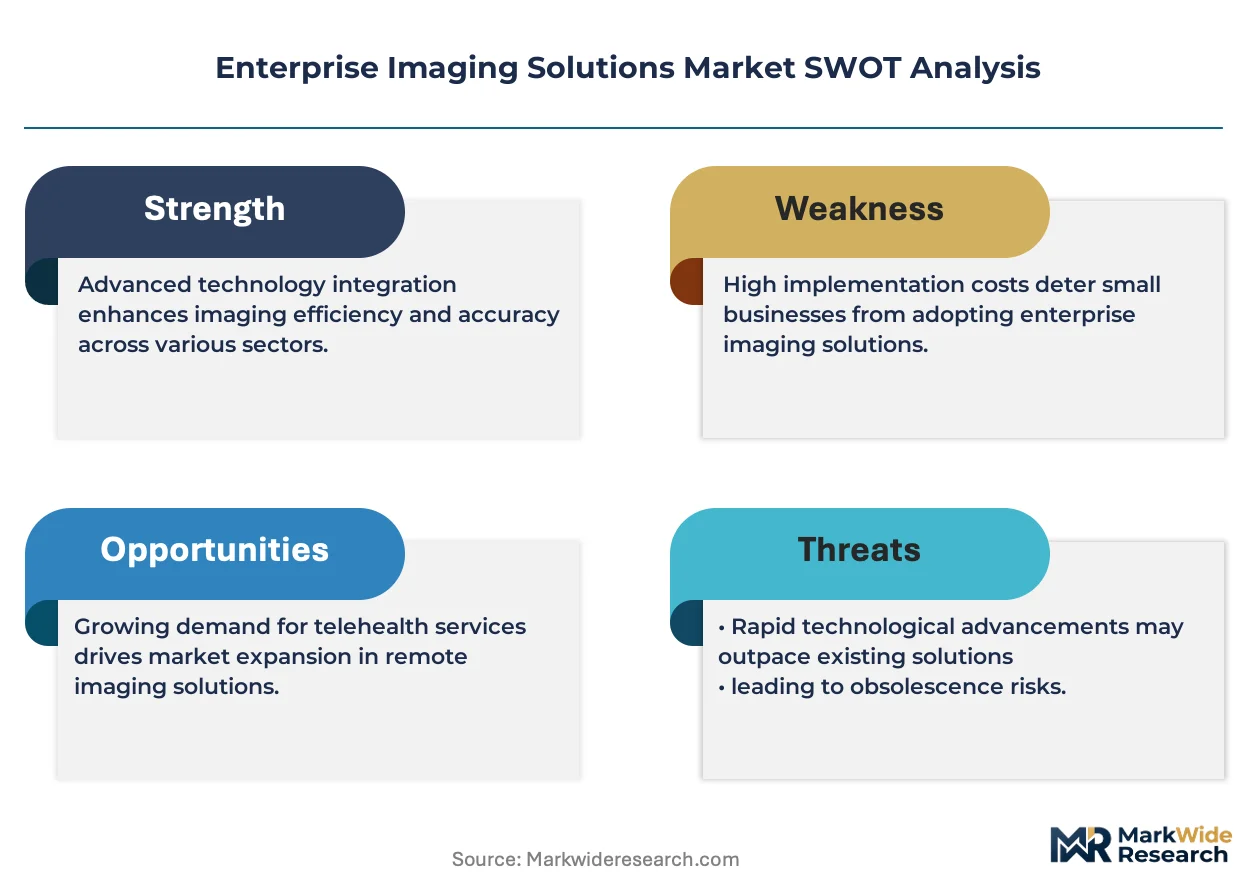
Enterprise imaging platforms represent a service-attach opportunity where AI algorithm subscriptions and managed cloud operations expand faster than core PACS licensing, with recurring revenue components approaching 60% of vendor bookings in North American deployments.
For Market Incumbents: Shield installed base retention by embedding proprietary AI diagnostics that increase switching costs for academic medical centers. Accelerate backward integration into cloud infrastructure through hyperscaler partnerships that reduce third-party storage dependency. Prioritize MDR certification investment for European market access before competitor algorithms secure notified body approval.
For New Entrants and Emerging Players: FDA 510(k) fast-track pathways for AI-augmented radiology devices offer expedited market entry against incumbent validation timelines. Target India's Ayushman Bharat public hospital digitization as the most penetrable geography, where cloud-native architectures bypass legacy PACS displacement complexity. Pursue channel partnerships with regional health tech integrators rather than direct hospital sales.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors cloud-native platform specialists with containerized microservices architectures over legacy PACS vendors requiring full-stack replacement. Five-to-ten year viability hinges on AI algorithm portfolio depth and FHIR-native interoperability. Monitor FDA artificial intelligence guidance publication as the critical inflection signal for algorithm validation cost trajectories.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Algorithm Portfolio Acquisition | Embedded machine learning capabilities differentiate platform tiers for academic medical center procurement. |
| Hyperscaler Cloud Partnership | AWS and Azure infrastructure agreements reduce storage costs and accelerate multi-tenant deployment scalability. |
| FHIR-Native Architecture Development | API-first interoperability satisfies FDA 21st Century Cures Act mandates and accelerates hospital network sales cycles. |
| MDR Certification Investment | European notified body approval unlocks Germany's university hospital procurement under federal digitization frameworks. |
| Cardiology Workflow Integration | Structured reporting modules capture margin-rich expansion beyond radiology into hemodynamic system connectivity. |
Methodological Framework
A standing panel of hospital CIOs, radiology department chairs, GPO contracts managers, and biomedical engineers provided ongoing calibration for demand assumptions and procurement timeline validation. Primary interviews with enterprise imaging vendors and cloud infrastructure providers combined with secondary analysis of FDA 510(k) filings, hospital procurement databases, and hyperscaler healthcare vertical disclosures. Bottom-up deployment estimates triangulated against top-down health system IT spending benchmarks.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation across deployment architecture, clinical workflow type, organization scale, AI integration depth, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to installed base replacement cycles and greenfield procurement identified through federal digitization program tracking.
Decision-makers should treat outputs as directional under assumptions of continued FDA interoperability enforcement and stable hyperscaler pricing; material deviation in AI regulatory timelines or cloud storage cost trajectories would warrant model refresh. Recalibration cycles align with material shifts in federal digitization funding authorization and notified body certification capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Spain Digital Twin Market
Digital Solutions
Global Digital Asset Management Software Market
Digital Solutions
OTA Transmission Platform Market
Digital Solutions
Load Balancer Market
Digital Solutions
E-Ink E-Reader Market
Digital Solutions
IT Operations Management Market
Digital Solutions
Smart Signage Market
Digital Solutions
Fuel Management Software Market
Digital Solutions
Global Work Order Management Systems Market
Digital Solutions
Legal Technology Market
Digital Solutions
Email Deliverability Tools Market
Digital Solutions
Messaging Platform Market
Digital Solutions
Workflow Management System Market
Digital Solutions
Voice Remote Control Market
Digital Solutions
APAC Digital Signage Market
Digital Solutions
Enterprise Mobility Market