
 Mobile Marketing Market | 2026-2036
Mobile Marketing Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Marketing Market Intelligence
Market Context
Retail banking is decoupling from generic display budgets and redirecting spend toward personalized push notification ecosystems. Moburst leverages proprietary creative testing protocols to sustain performance marketing margins across fintech app-install campaigns. InMobi anchors demand in emerging markets through its supply-side platform dominance and localized ad-serving infrastructure. Publicis Groupe competes via consolidated data assets that bridge media planning with first-party identity resolution.
Technical Definition and Segment Structure
Mobile marketing encompasses programmatic delivery of promotional content through wireless handheld devices, operating across real-time bidding exchanges, SDK-mediated in-app inventories, and carrier-grade SMS gateways with sub-100-millisecond latency requirements. The discipline serves commercial objectives spanning acquisition, retention, and location-triggered conversion optimization. In-app advertising and push notifications command expanding budget share as ATT-constrained advertisers seek deterministic engagement channels, while location-based services remain margin-diluted due to iOS geoprivacy restrictions. Campaign objectives cluster around retention and engagement where lifetime-value modeling justifies premium CPMs, whereas brand awareness placements face commoditization.
Regulatory Framework and Outlook
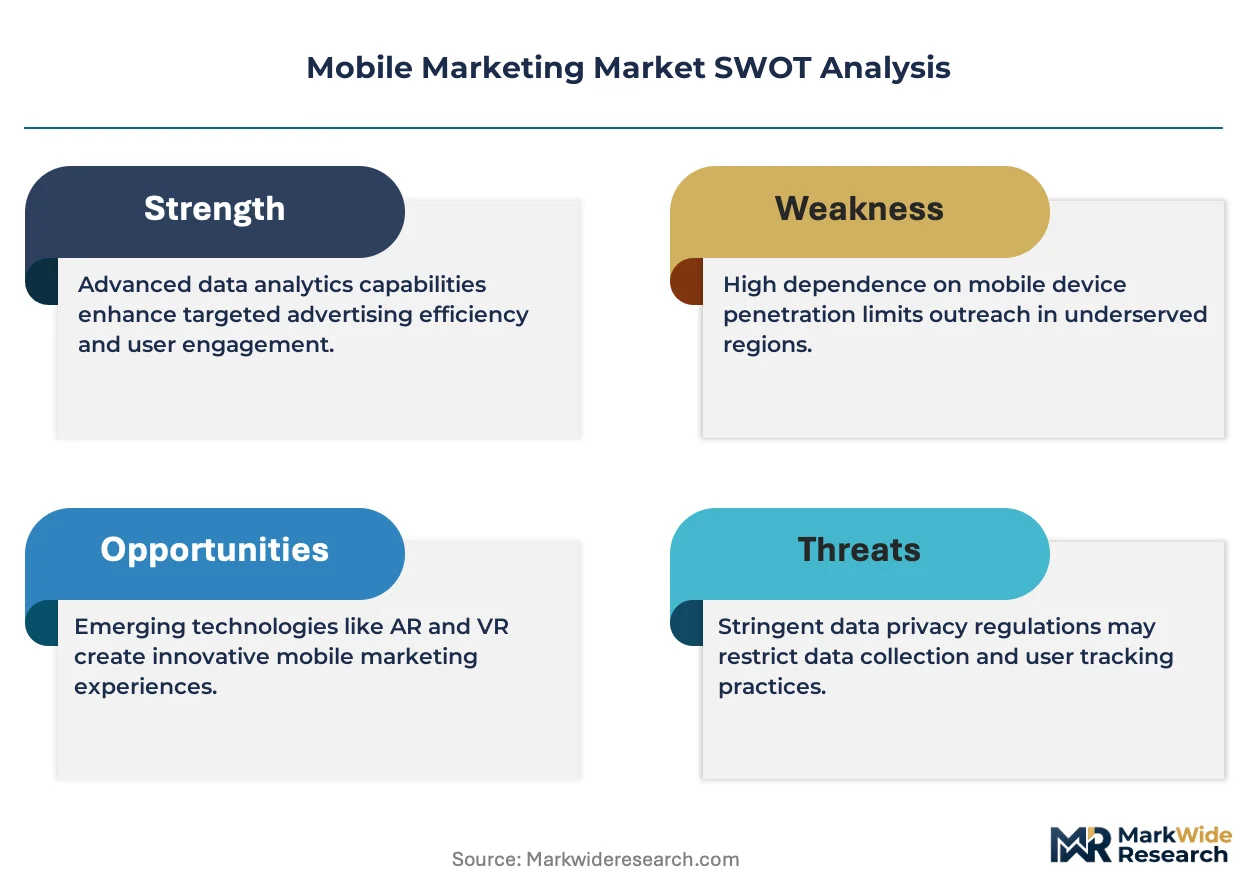
The EU Digital Markets Act and GDPR impose interoperability and consent-layer obligations on gatekeeper platforms, while the US FTC scrutinizes dark-pattern design in subscription flows and California's CPPA extends opt-out rights to cross-context behavioral advertising. India's TRAI mandates granular consent frameworks for promotional SMS, and the RBI's data-localization directives constrain cloud-based campaign orchestration for financial services advertisers. Stakeholders must monitor enforcement divergence between Brussels-mandated interoperability and Washington's sectoral privacy fragmentation.
Market Dynamics
Apple's App Tracking Transparency framework has severed deterministic attribution pipelines, forcing advertisers to rebuild measurement infrastructure around first-party data lakes and probabilistic modeling. This single technical intervention has compressed CPM efficiency curves and redirected budget flows toward owned-channel engagement mechanics.
Growth Catalysts
- UPI-enabled commerce convergence:India's tier-two urban corridors are generating install velocity for fintech apps as smartphone penetration crosses critical mass in secondary cities.
- GDPR consent-layer maturation:European advertisers have operationalized granular opt-in frameworks that now yield higher-quality first-party data pools than pre-regulation baselines.
- Push notification infrastructure:Retail banking apps are migrating spend from display networks toward deterministic messaging channels with direct wallet integration.
Market Restraints
- iOS geoprivacy architecture:Location-based services face margin compression as precise geofencing requires explicit user permissions that suppress inventory scale.
- Cloud localization mandates:India's RBI data-localization directives constrain campaign orchestration for financial services advertisers using offshore server infrastructure.
- ATT attribution fragmentation:Cross-platform measurement now requires probabilistic stitching that increases media planning complexity and agency overhead.
Strategic Opportunities
- SDK-mediated inventory expansion:In-app advertising formats are capturing budget share as ATT-constrained buyers prioritize deterministic engagement channels over mobile web.
- EU Digital Markets Act interoperability:Gatekeeper platform obligations will force data portability mechanisms that reduce advertiser switching costs between walled gardens.
- Consent-native creative formats:Rewarded video and value-exchange placements are emerging as privacy-compliant alternatives to interruptive ad units.
Industry Challenges
- Probabilistic modeling talent scarcity:The shift from deterministic attribution to incrementality testing requires data science capabilities that outstrip current agency staffing.
- Cross-context behavioral opt-out mechanics:California's CPPA extension creates compliance engineering burdens for national campaign architectures.
- Carrier-grade SMS latency requirements:Promotional messaging infrastructure must maintain sub-100-millisecond delivery windows while scaling across heterogeneous network conditions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Marketing Market |
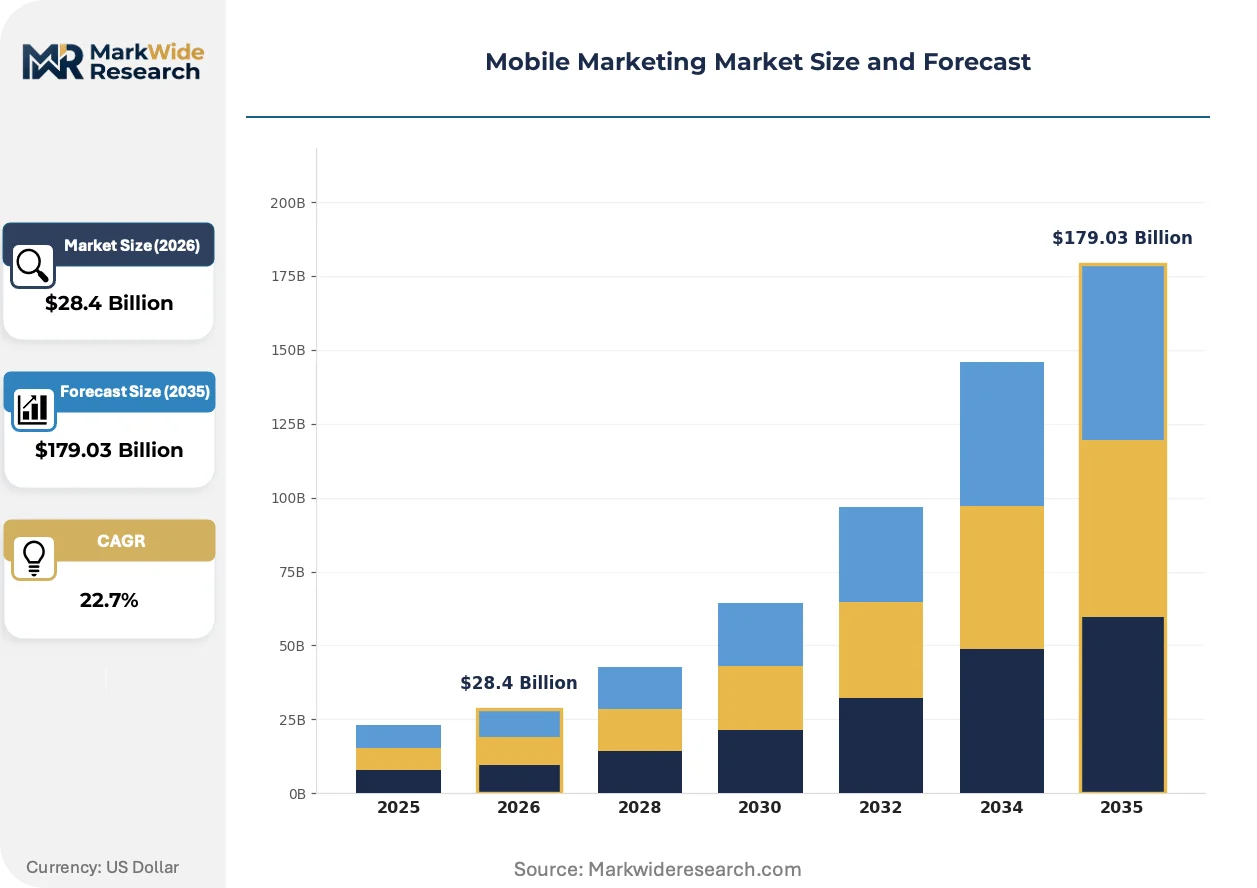
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $179.03 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Channel Type: SMS, Push Notifications, In-App Advertising, Mobile Wallet, Location-Based Services, QR Codes Industry Application: E-commerce, Hospitality, Entertainment, Telecommunications, Education, Real Estate Campaign Objective: Brand Awareness, Customer Acquisition, Retention, Lead Generation, Sales Promotion, Engagement Device Platform: Android, iOS, Windows Mobile, Feature Phones, Tablets, Wearables |
| Companies Covered | Digitas, Moburst, Merkle, InMobi, Liftoff Mobile, Ogilvy, Publicis Groupe, Phiture, Wunderman Thompson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Marketing Market Strategic Shifts & Innovations
Privacy-preserving measurement architectures are displacing legacy attribution stacks, compressing the technical half-life of established campaign analytics. Three concurrent developments are restructuring competitive positioning across the ecosystem.
Clean room infrastructure is unifying advertiser and publisher data assets without raw data commingling. Retail banking and fintech app-install buyers are adopting these environments at accelerated pace to salvage audience segmentation capabilities. The technology is unifying media planning with first-party identity resolution while maintaining regulatory distance from personal data exposure.
Brussels-mandated interoperability obligations under the EU Digital Markets Act are forcing platform gatekeepers to expose advertising interfaces and performance data to third-party verification. Industrial consequence includes reduced information asymmetry between advertisers and dominant platforms. Financial services verticals operating across European markets are most affected, with compliance teams rebuilding API integration roadmaps to capture newly portable campaign insights.
Agency compensation structures are rotating from commission-based media buying toward outcome-indexed performance fees. The traditional media planning function is being disrupted by in-house programmatic desks and direct platform relationships. This pattern is most visible in North American and European markets where procurement functions have consolidated vendor rosters and demanded transparent cost-plus pricing.
Mobile Marketing Market Segmentation
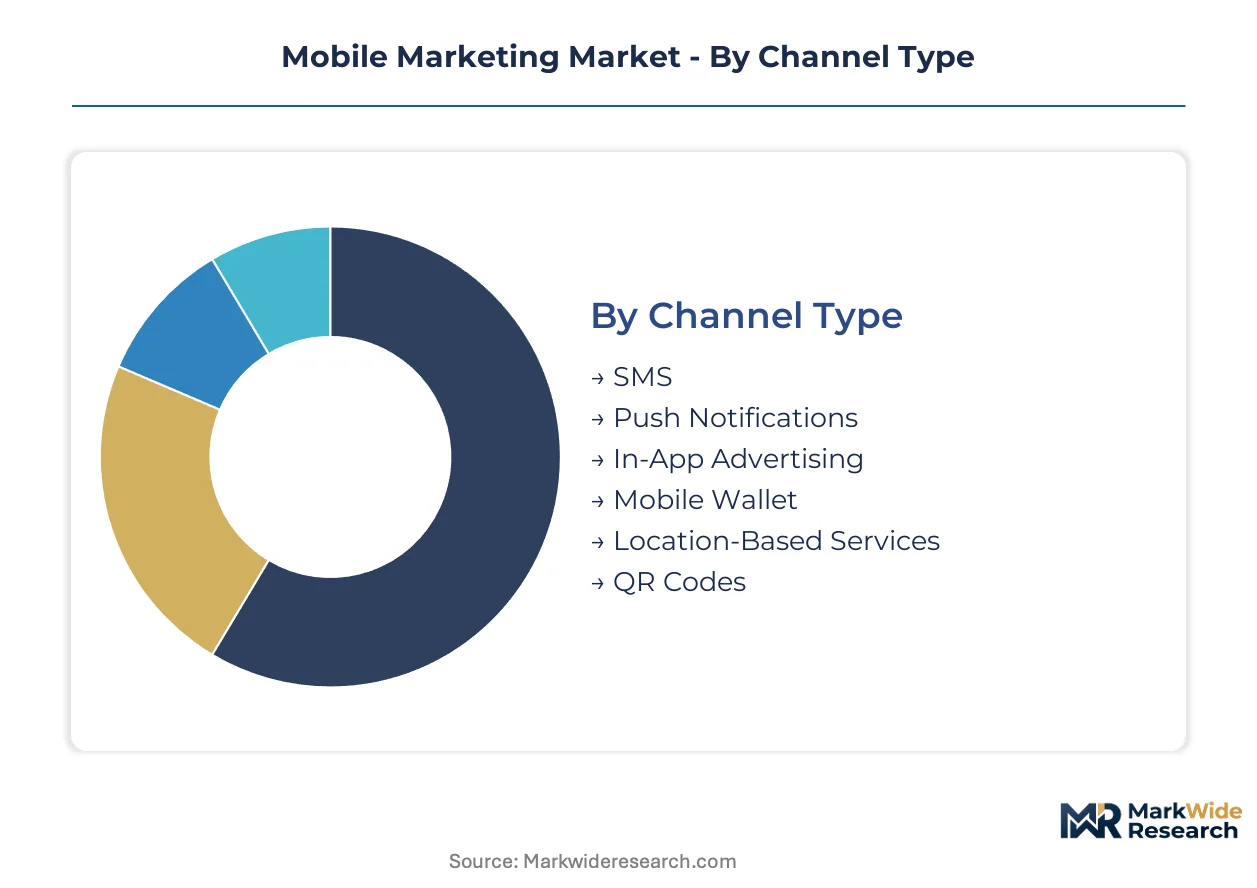
Channel diversity in mobile marketing demands granular segmentation as ATT-constrained advertisers redirect budgets toward deterministic engagement mechanics. Each axis reveals distinct technical requirements, regulatory exposure, and margin profiles that reshape vendor positioning across the ecosystem.
Channel Type:
Technical infrastructure and latency specifications differentiate channel economics, with SDK-mediated formats commanding premium inventory access.
- SMS:Carrier-grade gateways deliver promotional content with sub-100-millisecond latency requirements across heterogeneous network conditions. India's TRAI mandates granular consent frameworks that operationalize opt-in mechanics for financial services promotional messaging in tier-two urban corridors.
- Push Notifications:Deterministic messaging channels bypass attribution fragmentation by leveraging first-party device identifiers with direct wallet integration. Retail banking apps are migrating display budgets toward these owned-channel ecosystems as ATT severs cross-platform tracking pipelines.
- In-App Advertising:SDK-mediated inventory captures budget share through real-time bidding exchanges with deterministic engagement metrics.
- Mobile Wallet:Payment-integrated promotional surfaces enable conversion optimization at point-of-transaction.
- Location-Based Services:Geofencing infrastructure faces margin compression from iOS geoprivacy restrictions requiring explicit user permissions.
- QR Codes:Offline-to-online bridging format with minimal technical infrastructure requirements.
Push notifications lead on scale; SMS leads on momentum as UPI-enabled commerce accelerates promotional messaging adoption.
Industry Application:
End-use verticals exhibit divergent privacy sensitivity and creative format preferences that reshape campaign architecture.
- E-commerce:Transaction-heavy vertical demands attribution precision for ROAS optimization across fragmented device platforms. Indian fintech app-install campaigns concentrate in tier-two corridors where smartphone penetration and UPI infrastructure converge.
- Hospitality:Location-triggered booking flows rely on geofencing capabilities constrained by iOS permission architectures.
- Entertainment:Streaming and gaming apps prioritize rewarded video formats with value-exchange consent mechanics.
- Telecommunications:Carrier-owned inventory benefits from first-party data lakes and deterministic subscriber identifiers.
- Education:Subscription-based models face FTC scrutiny of dark-pattern design in enrollment flows.
- Real Estate:High-consideration purchase cycles require extended attribution windows and incrementality testing capabilities.
E-commerce dominates volume concentration; entertainment climbs the fastest on privacy-compliant creative adoption.
Campaign Objective:
Objective tiering determines measurement methodology, with retention and engagement justifying premium CPMs through lifetime-value modeling.
- Brand Awareness:Upper-funnel placements face commoditization as probabilistic modeling replaces deterministic reach metrics. European advertisers leveraging GDPR-matured consent frameworks yield higher-quality first-party data pools than pre-regulation baselines.
- Customer Acquisition:App-install campaigns require probabilistic attribution stitching that increases agency overhead and data science staffing demands.
- Retention:Owned-channel engagement mechanics command expanding budget share with direct platform relationships displacing traditional media planning.
- Lead Generation:Form-fill optimization depends on consent-layer design compliant with California's CPPA cross-context behavioral opt-out extensions.
- Sales Promotion:Time-bound conversion acceleration leverages mobile wallet integration for frictionless redemption.
- Engagement:Session-depth metrics prioritize in-app advertising formats over mobile web inventory.
Retention leads on scale; acquisition gains share fastest on clean room infrastructure adoption for audience segmentation.
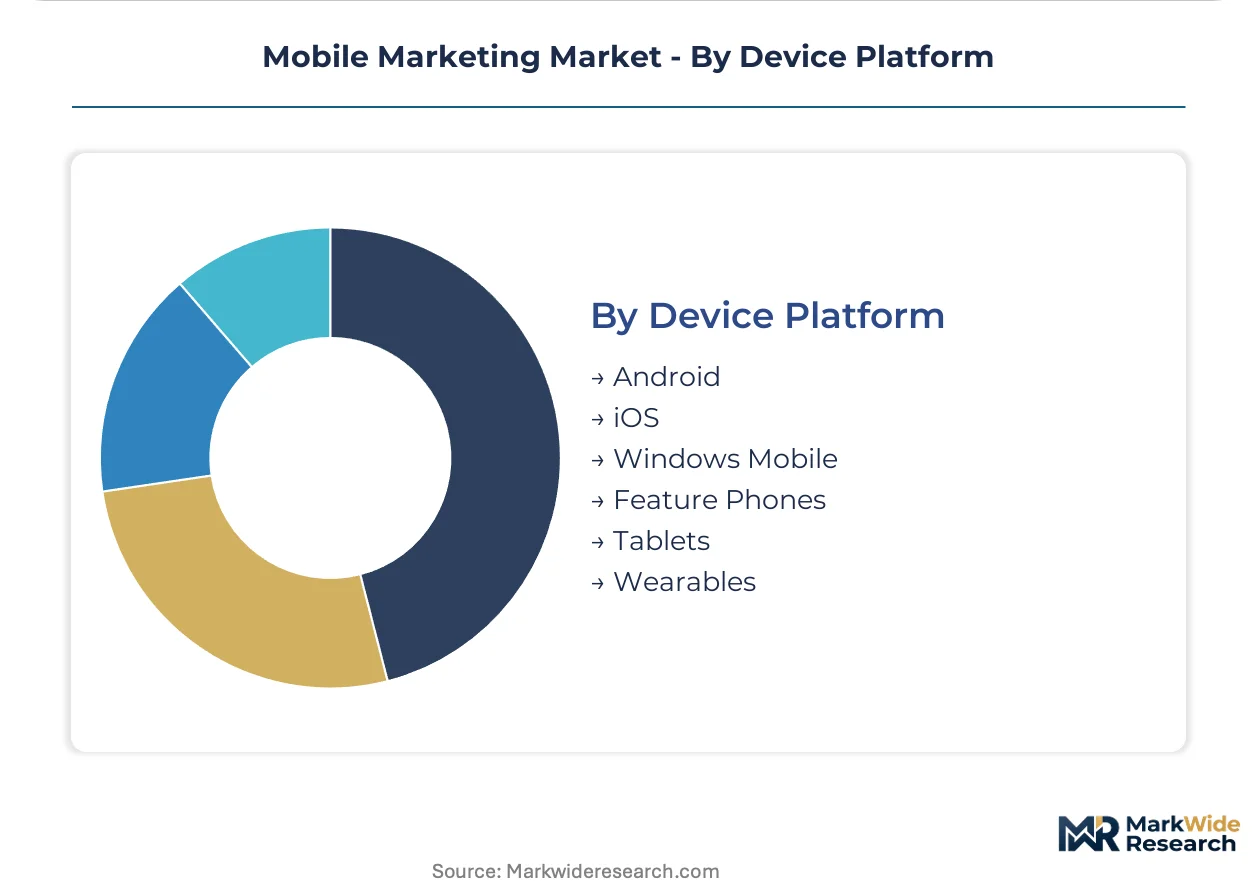
Device Platform:
Operating system fragmentation creates divergent privacy architectures that reshape measurement infrastructure investment.
- Android:Google's Privacy Sandbox and alternative identifier frameworks preserve more granular attribution capabilities than iOS counterparts. India's device ecosystem skews heavily toward Android, concentrating fintech app-install demand in Google's advertising infrastructure.
- iOS:Apple's ATT framework has severed deterministic attribution pipelines, compressing CPM efficiency curves and forcing first-party data lake reconstruction. The EU Digital Markets Act interoperability obligations will expose advertising interfaces to third-party verification, reducing information asymmetry for financial services verticals.
- Windows Mobile:Enterprise-focused niche with limited consumer advertising inventory scale.
- Feature Phones:SMS-dependent reach in emerging market segments with constrained smartphone penetration.
- Tablets:Larger-format creative inventory with distinct engagement patterns from smartphone usage.
- Wearables:Notification-surface constraints require ultra-concise messaging formats with limited attribution visibility.
Android leads on scale; wearables represent the steepest expansion trajectory on notification-surface innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting mobile marketing infrastructure investment toward jurisdictions with clearer consent-framework cost structures. India's data-localization mandates and the EU's interoperability obligations create divergent compliance burdens that reshape platform architecture decisions.
United States
California's CPPA extension of cross-context behavioral opt-out rights is forcing national campaign architectures to rebuild consent-layer engineering. The FTC scrutinizes dark-pattern design in subscription flows, particularly for education and fintech app enrollments. New York and San Francisco metro areas concentrate demand for probabilistic attribution talent as ATT-constrained advertisers rebuild measurement stacks.
India
Tier-two urban corridors including Pune, Jaipur, and Lucknow generate install velocity for fintech apps as UPI-enabled commerce converges with smartphone penetration crossing critical mass. TRAI mandates granular consent frameworks for promotional SMS that operationalize opt-in mechanics for financial services messaging. Mumbai and Bangalore anchor supply-side platform development for localized ad-serving infrastructure.
Germany
GDPR-matured consent frameworks yield higher-quality first-party data pools than pre-regulation baselines for European advertisers. The EU Digital Markets Act interoperability obligations force gatekeeper platforms to expose advertising interfaces to third-party verification. Berlin and Hamburg host compliance engineering teams rebuilding API integration roadmaps for financial services verticals.
United Kingdom
Post-Brexit regulatory divergence creates friction for cross-border campaign orchestration between UK and EU data environments. The Information Commissioner's Office enforces granular consent requirements that parallel GDPR stringency. London's fintech corridor drives demand for clean room infrastructure unifying advertiser and publisher data assets without raw data commingling.
Japan
METI guidelines on data portability influence advertiser platform-switching behaviors in a market historically characterized by walled-garden dominance. Feature phone segments persist in rural prefectures, sustaining SMS-dependent reach strategies alongside smartphone-centric in-app campaigns. Tokyo and Osaka concentrate mobile wallet integration development for payment-embedded promotional surfaces.
Mobile Marketing Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with full-service agency networks commanding consolidated data assets while performance marketing boutiques capture ATT-constrained app-install demand. The vendor base stratifies into three tiers: global holding companies with media planning integration, mobile-native specialists with SDK-mediated inventory access, and regional boutiques with localized creative testing protocols. Dominant competitive moves include clean room infrastructure partnerships and outcome-indexed compensation structure adoption.
Within the performance marketing tier, Moburst and Liftoff Mobile exemplify mobile-native specialists with deterministic engagement channel expertise. Publicis Groupe anchors the global holding company archetype with consolidated data assets bridging media planning and first-party identity resolution. InMobi occupies a position as an emerging market infrastructure provider through supply-side platform dominance.
| Leading Market Players |
|---|
| Digitas |
| Moburst |
| Merkle |
| InMobi |
| Liftoff Mobile |
| Ogilvy |
| Publicis Groupe |
| Phiture |
| Wunderman Thompson |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up performance marketing specialists concentrate inventory access through SDK-mediated platform acquisitions, compressing intermediary margins while extracting pricing discipline from ATT-constrained advertisers rebuilding first-party data infrastructure. This ownership pattern feeds supply consolidation into fewer holding structures and amplifies rate-card uniformity across programmatic exchanges.
Pricing Analysis
Direct-to-OEM discount structures dominate enterprise app-install campaigns, with agency markups compressing as in-house programmatic desks disintermediate traditional media planning. Price differentiation hinges on deterministic attribution capabilities and creative testing velocity, with privacy-compliant channels commanding premium placement. Pricing pressure stems from probabilistic modeling talent scarcity that inflates agency overhead. Mid-market fintech advertisers exhibit highest price sensitivity; tier-one retail banking apps show lowest, prioritizing wallet-integrated engagement mechanics.
Supply Chain Analysis
Certification gating through MMP accreditation and clean room compliance frameworks restricts viable inventory aggregation to a narrowing vendor tier. Supply concentrates in the United States, India, and Germany, where data-localization mandates and interoperability obligations reshape infrastructure deployment. Raw material dependencies span first-party data lakes, probabilistic attribution SDKs, and carrier-grade SMS gateways. Single-source vulnerability runs through dominant supply-side platforms in emerging markets. Distribution runs through API-integrated demand-side platforms with real-time bidding exchange connectivity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's tier-two urban corridors offer regulatory-arbitrage advantages against Brussels-mandated consent-layer costs, as TRAI's granular opt-in frameworks impose lighter engineering burdens than GDPR-matured European baselines while capturing equivalent UPI-enabled commerce velocity.
For Market Incumbents: Deepen clean room infrastructure partnerships to salvage audience segmentation capabilities as ATT fragments deterministic attribution. Consolidate SDK-mediated inventory access through selective platform acquisitions. Threat substitution from in-house programmatic desks demands faster creative testing protocols. Vertical integration into first-party data lake architecture is the critical lever. For New Entrants and Emerging Players: Regional boutique agencies with localized creative testing protocols offer the most penetrable entry wedge. Target India's tier-two fintech app-install corridor where UPI infrastructure and smartphone penetration converge with lighter compliance burdens. A consent-native creative format specialization—rewarded video and value-exchange placements—provides differentiated go-to-market positioning against interruptive ad unit incumbents. For Investors and Strategic Acquirers: Cloud infrastructure providers and retail banking technology arms are the most active acquirers in this space, seeking deterministic engagement channel capabilities. Long-term viability centers on privacy-preserving measurement architecture ownership. Acquisition targets should demonstrate probabilistic modeling talent depth and clean room operational readiness. The signal to watch is enforcement divergence between Brussels-mandated interoperability and Washington's sectoral privacy fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| Clean Room Infrastructure Partnership | Unifies advertiser-publisher data assets without raw commingling, satisfying RBI and GDPR localization requirements. |
| SDK-Mediated Inventory Expansion | Captures ATT-constrained budget flows toward deterministic in-app engagement channels over mobile web. |
| Consent-Native Creative Format Development | Positions rewarded video and value-exchange units as privacy-compliant alternatives to interruptive advertising. |
| Outcome-Indexed Compensation Restructure | Replaces commission-based media buying with performance fees aligned to retention and engagement metrics. |
| Regional Supply-Side Platform Acquisition | Secures localized ad-serving infrastructure in India's tier-two corridors where UPI-enabled commerce accelerates. |
Research Approach
Bottom-up campaign-objective modeling reconciled against top-down supply-side platform tracking forms the analytical core of this study. Primary interviews with programmatic traders, mobile marketing executives, privacy compliance officers, and fintech growth leads combine with secondary validation from SEC filings, App Annie engagement data, TRAI regulatory circulars, and RBI data-localization directives. This triangulation anchors volume and value estimates across the projection horizon.
Input-output matrices map channel-type deployment against device-platform fragmentation and industry-application concentration. Segmentation dimensions include campaign objective tiering, channel technical specifications, end-use vertical privacy sensitivity, and regional regulatory framework clusters. CAGRs derive from install velocity trajectories in India's tier-two corridors and consent-framework maturation curves in European markets. Probabilistic attribution adoption rates and clean room infrastructure penetration serve as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to enforcement divergence between Brussels-mandated interoperability and Washington's sectoral privacy fragmentation, plus cloud-localization mandate expansion. Forecasts reflect documented assumptions on ATT constraint persistence and UPI infrastructure rollout velocity. A model refresh is warranted upon material change in iOS geoprivacy architecture or EU Digital Markets Act implementation timing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Distributed Order Orchestration Market
Digital Solutions
Global Asset Reliability Software Market
Digital Solutions
Digital Shelf Market
Digital Solutions
Managed File Transfer (MFT) Market
Digital Solutions
Tablet Based E-Detailing Market
Digital Solutions
Government Open Data Management Platform Market
Digital Solutions
Asia-Pacific Route Optimization Software Market
Digital Solutions
Workflow Management System Market
Digital Solutions
Europe Smart Card Market
Digital Solutions
File Sharing Market
Digital Solutions
Warranty Management System Market
Digital Solutions
Product Prototyping Market
Digital Solutions
Online Classified Ad Platform Market
Digital Solutions
Latin America and Europe Digital Signature Market
Digital Solutions
Data Governance Market
Digital Solutions
Load Balancer Market