
 Global Wireless Health Market | 2026-2036
Global Wireless Health Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wireless Health Market Foresight
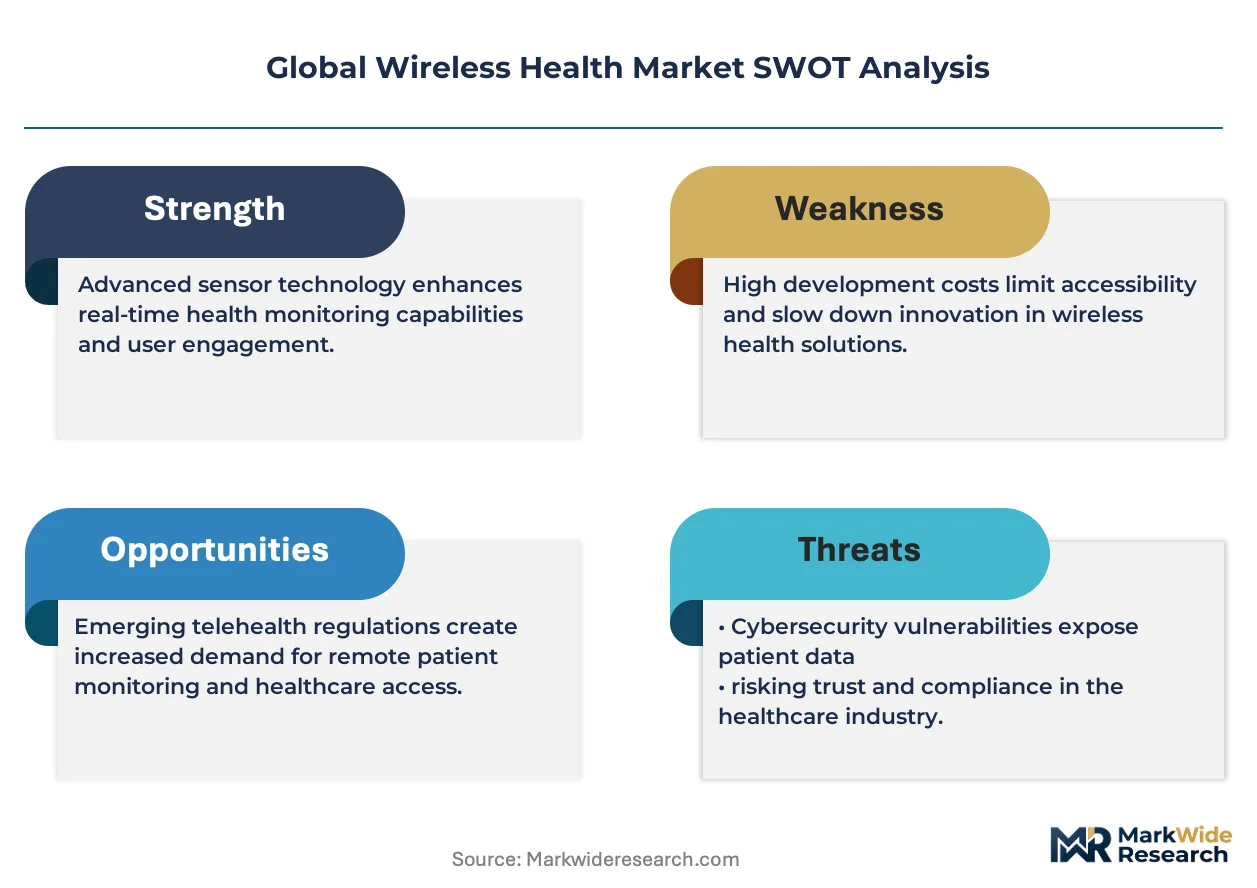
Project finance and leasing arrangements for connected device fleets is tilting competitive dynamics toward asset-light operators. Qualcomm Technologies leverages its semiconductor leadership to dominate cellular-enabled medical chipsets. Koninklijke Philips anchors its position through integrated remote patient monitoring ecosystems spanning hardware and cloud analytics. AT&T competes by controlling private 5G network deployments for hospital campuses.
Wireless health encompasses medical data transmission, remote physiological monitoring, and software-driven care coordination through radio-frequency protocols including Bluetooth Low Energy 5.3 and ultra-wideband positioning. Its primary purpose is to decouple clinical observation from physical proximity, enabling continuous vital sign streaming and algorithm-triggered interventions. Wearable sensors lead hardware shipment volumes while telehealth platforms capture disproportionate margin pools through recurring SaaS structures. Mobile health apps occupy the fastest-expansion tier among consumer-facing segments, though chronic disease management generates the highest per-user revenue concentration among application categories.
FDA pre-certification, EU MDR Class IIa rules for connected devices, and Japan's PMDA software-as-medical-device guidance collectively shape product development timelines and market access conditions. HIPAA encryption mandates in the United States and GDPR health data provisions in Europe directly influence cloud architecture decisions and cross-border data routing. Stakeholders must monitor evolving interoperability standards and reimbursement code expansions that determine which modalities achieve sustainable clinical adoption.
Market Dynamics
Private 5G network deployments are compressing latency thresholds for continuous vital sign streaming, forcing hospital systems to restructure their device procurement around real-time clinical decision support rather than episodic data capture.
Growth Catalysts
- FDA Pre-Certification Pathway:Software-based medical devices now navigate abbreviated approval timelines, accelerating commercialization for algorithm-driven diagnostics and remote monitoring platforms.
- Bluetooth Low Energy 5.3:Extended range and reduced power consumption enable multi-day wearable operation, expanding addressable populations for chronic disease management programs.
- Germany's Hospital Digitization Mandates:Federal reimbursement incentives for remote patient monitoring infrastructure are driving fleet-scale sensor deployments across integrated provider networks.
Market Restraints
- Semiconductor Supply Concentration:Cellular-enabled medical chipsets depend on concentrated foundry capacity in East Asia, exposing device manufacturers to allocation volatility and extended lead times.
- GDPR Cross-Border Routing Complexity:European health data localization requirements fragment cloud architecture decisions, forcing redundant infrastructure investments that inflate operational overhead.
- Legacy EHR Integration Friction:Proprietary data formats in incumbent hospital information systems resist standardized API connectivity, delaying algorithm-triggered intervention deployment.
Strategic Opportunities
- India's Tier-2 City Penetration:Mobile-first health delivery models are scaling beyond metropolitan boundaries, creating first-mover advantages for localized platform adaptation.
- Ultra-Wideband Positioning Convergence:Spatial tracking accuracy is enabling fall detection and mobility analytics in elderly care facilities, opening hardware-software bundled revenue streams.
- Japan's PMDA Software-as-Medical-Device Guidance:Clearer classification pathways for AI diagnostics reduce regulatory uncertainty, attracting venture deployment into predictive analytics engines.
Industry Challenges
- Interoperability Standards Fragmentation:Competing connectivity protocols across device ecosystems force engineering teams to maintain multiple certification tracks simultaneously.
- Clinical Validation Timeline Compression:Algorithm developers face pressure to demonstrate real-world evidence for reimbursement codes before rival platforms capture prescriber mindshare.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wireless Health Market |
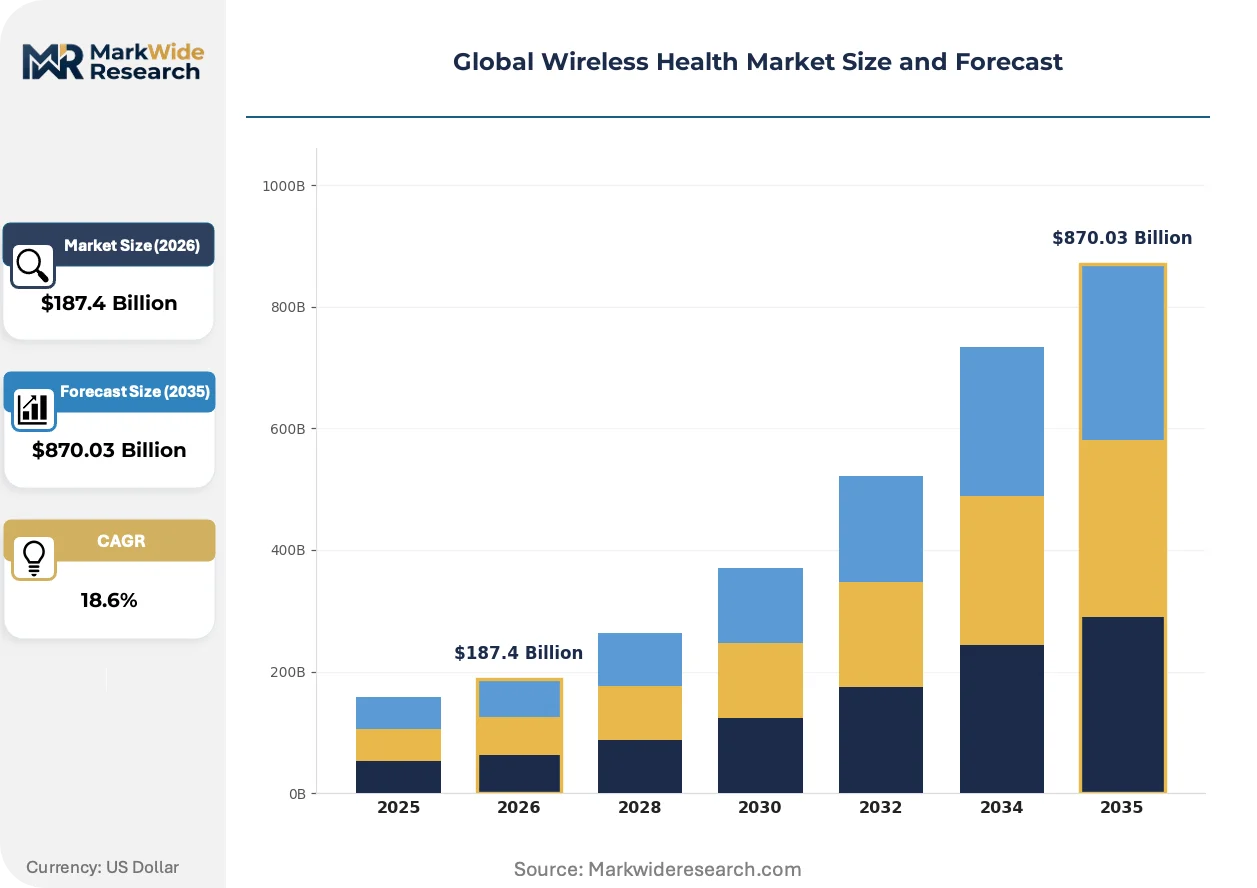
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $870.03 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Connected Medical Devices, Remote Patient Monitoring, Mobile Health Apps, Wearable Sensors, Telehealth Platforms Technology: Bluetooth, Wi-Fi, NFC, Cellular, Zigbee Application: Chronic Disease Management, Fitness & Wellness, Remote Diagnostics, Elder Care Monitoring, Mental Health Support End User: Clinics, Health Insurance Providers, Research Institutions, Rehabilitation Centers, Home Care Services |
| Companies Covered | Qualcomm Technologies, Koninklijke Philips, Omron Corporation, Allscripts Healthcare Solutions, AT&T, Verizon Communications, Epic Systems Corporation, Cerner Corporation, IBM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wireless Health Market Shifts & Advancements
Edge computing architectures are redistributing analytical workloads from centralized clouds to bedside processors, enabling sub-second clinical alerts while reducing transmission bandwidth requirements.
Continuous glucose monitoring systems with factory-calibrated sensors are digitizing diabetes management by eliminating fingerstick calibration requirements. Endocrinology practices across the United States are adopting these devices at accelerating replacement cycles for legacy intermittent monitors. The technology is digitizing patient-generated data volumes while compressing HbA1c testing frequency in value-based care contracts.
The EU MDR Class IIa rules for connected devices impose post-market surveillance obligations that extend liability across software update lifecycles. Manufacturers must maintain clinical evidence registries that track algorithm performance degradation over time. Cardiovascular monitoring wearables face the steepest compliance burden, driving consolidation among smaller notified body clients toward established registrars.
Subscription-based device provisioning is displacing capital purchase models in US hospital procurement departments. Health systems in Texas and Florida are piloting per-patient-per-month arrangements that bundle hardware, connectivity, and analytics into single vendor relationships. This restructuring concentrates supplier selection authority within value analysis committees rather than individual department budgets.
Global Wireless Health Market Segmentation
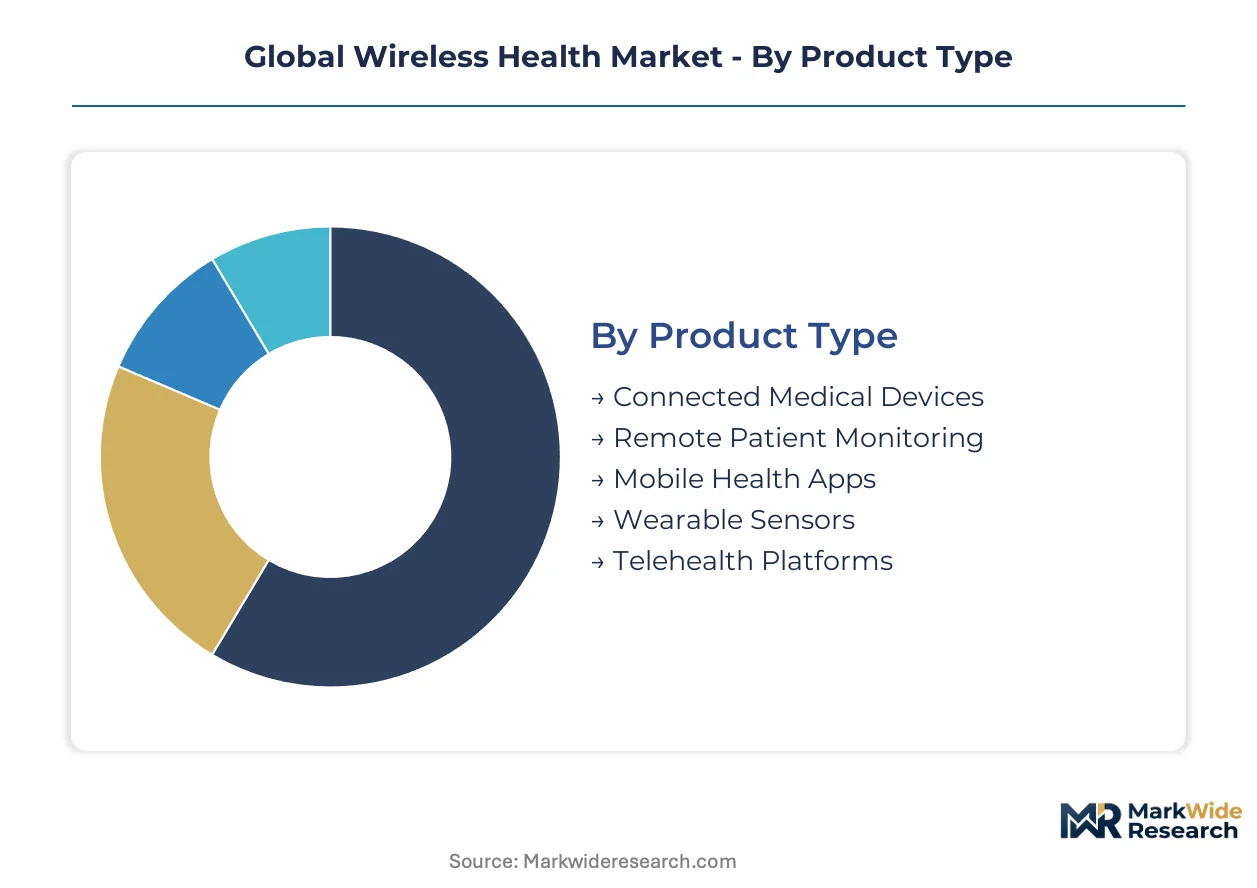
Segmentation in wireless health reveals how technology maturity, reimbursement pathways, and clinical validation requirements create divergent commercial trajectories across hardware and software categories. Understanding these divisions enables stakeholders to align R&D investment with segments offering sustainable margin structures rather than commoditized volume plays.
Product Type:
Mature connected hardware segments compete on cost efficiency while emerging software platforms capture recurring revenue through SaaS structures.
- Wearable Sensors:Factory-calibrated biosensors eliminate fingerstick requirements for glucose monitoring while enabling multi-day continuous operation through Bluetooth Low Energy 5.3 protocols. Hospital systems in Germany are deploying fleet-scale sensor arrays for post-discharge cardiac monitoring under federal digitization mandates.
- Telehealth Platforms:Cloud-native architectures integrate video consultation, asynchronous messaging, and EHR connectivity into unified care coordination hubs. Texas and Florida health systems are piloting per-patient-per-month subscription models that bundle hardware, connectivity, and analytics into single vendor relationships.
- Connected Medical Devices:Cellular-enabled diagnostic hardware with embedded SIM capabilities supports ambulatory ECG and pulse oximetry in rural coverage zones.
- Remote Patient Monitoring:Integrated ecosystems spanning hardware deployment, cellular connectivity, and clinical workflow integration for chronic condition oversight.
- Mobile Health Apps:Consumer-facing software delivering medication adherence prompts, symptom tracking, and wellness coaching through smartphone interfaces.
Wearable sensors retain volume leadership; mobile health apps hold the steepest expansion curve.
Technology:
Cost tier stratification separates premium low-latency protocols from economy connectivity options in device specification decisions.
- Cellular:LTE-M and NB-IoT modems enable wide-area coverage for ambulatory patients without smartphone tethering, with Qualcomm dominating medical chipset supply. Private 5G network deployments in US hospital campuses are compressing latency thresholds for real-time clinical decision support.
- Bluetooth:Version 5.3 delivers extended range and reduced power consumption for multi-day wearable operation, expanding addressable populations for chronic disease management programs in India's tier-1 cities.
- Wi-Fi:High-bandwidth protocol supporting video-intensive telehealth consultations and large-file diagnostic imaging transmission.
- NFC:Short-range contactless pairing for medication authentication and clinician device provisioning in acute care settings.
- Zigbee:Mesh networking standard for in-facility sensor arrays requiring low-power, multi-hop connectivity across elderly care environments.
Bluetooth dominates shipment volumes through wearable integration; cellular protocols are climbing the fastest as remote monitoring programs expand beyond smartphone-dependent populations.
Application:
Customer type differentiation separates clinically validated therapeutic segments from discretionary wellness purchases with divergent reimbursement pathways.
- Chronic Disease Management:FDA-cleared algorithms for diabetes, hypertension, and heart failure generate the highest per-user revenue concentration through recurring monitoring fees and value-based care contract performance bonuses. Endocrinology practices across the United States are adopting continuous glucose monitoring at accelerating replacement cycles.
- Elder Care Monitoring:Ultra-wideband positioning convergence enables fall detection and mobility analytics in assisted living facilities, opening hardware-software bundled revenue streams. Spatial tracking accuracy supports aging-in-place strategies while reducing emergency department utilization.
- Remote Diagnostics:Asynchronous store-and-forward imaging and algorithm-interpreted ECG readings for specialist consultation without physical proximity.
- Fitness & Wellness:Consumer-grade activity tracking and biometric feedback without clinical validation or insurance reimbursement eligibility.
- Mental Health Support:Digital therapeutic platforms delivering cognitive behavioral therapy protocols and mood monitoring through smartphone interfaces.
Chronic disease management captures premium pricing through reimbursement codes; elder care monitoring is expanding most quickly as demographic shifts accelerate institutional demand.
End User:
Volume concentration clusters around institutional purchasers with procurement authority while margin opportunities emerge in fragmented direct-to-patient channels.
- Home Care Services:Distributed nursing organizations managing post-acute patients through cellular-connected device fleets and cloud-based care coordination dashboards. Germany's hospital digitization mandates are accelerating sensor deployment across integrated provider networks.
- Clinics:Ambulatory practices adopting subscription-based device provisioning models that displace capital purchase structures and concentrate supplier selection authority within value analysis committees.
- Health Insurance Providers:Payers deploying remote monitoring as risk stratification tools to reduce emergency utilization and institutional readmission penalties.
- Rehabilitation Centers:Post-surgical and injury recovery facilities tracking patient adherence to prescribed mobility protocols.
- Research Institutions:Academic medical centers conducting real-world evidence generation for algorithm validation and regulatory submission support.
Home care services retain volume leadership through federal reimbursement tailwinds; health insurance providers are gaining share fastest as value-based contracting expands risk-bearing arrangements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal digitization mandates and reimbursement incentives are accelerating wireless health infrastructure deployment across hospital systems in Germany, the United States, and India. Regulatory pathways in Japan and the United Kingdom are clarifying software-as-medical-device classifications, reducing market entry friction for algorithm developers. These policy frameworks are concentrating investment in metropolitan clusters with integrated provider networks and established technology ecosystems.
United States
Texas and Florida health systems are piloting subscription-based device provisioning models that bundle hardware, connectivity, and analytics into single vendor relationships. FDA's digital health pre-certification pathway compresses approval timelines for software-based medical devices, enabling faster commercialization of remote monitoring platforms. The Greater Boston corridor hosts dense concentrations of EHR integration specialists and algorithm developers serving academic medical centers.
Germany
Hospital digitization mandates are driving fleet-scale sensor deployments across integrated provider networks in North Rhine-Westphalia and Bavaria. Federal reimbursement incentives for remote patient monitoring infrastructure have created procurement urgency among regional hospital associations. The Rhine-Ruhr metropolitan region anchors manufacturing and cloud infrastructure investments serving Central European markets.
India
Mobile-first health delivery models are scaling fastest in Mumbai, Delhi-NCR, and Bangalore, where smartphone penetration enables direct-to-patient platform deployment. CDSCO regulatory frameworks for connected devices are evolving to accommodate software-driven diagnostics from domestic developers. Hyderabad and Chennai are emerging as hubs for telehealth platform engineering and clinical workflow integration services.
Japan
PMDA software-as-medical-device guidance is reducing regulatory uncertainty for AI diagnostic developers in Tokyo and Osaka metropolitan areas. METI-funded initiatives are accelerating private 5G network deployments in elderly care facilities to support fall detection and mobility analytics. The Kansai region concentrates medical device manufacturing expertise with embedded connectivity capabilities.
United Kingdom
NHS Long Term Plan commitments to digital-first primary care are expanding remote monitoring procurement frameworks across integrated care systems in England. MHRA recognition of FDA-cleared devices streamlines market access for US-developed platforms targeting chronic disease management. The Cambridge-London corridor hosts venture-backed startups specializing in algorithm-triggered intervention protocols.
Global Wireless Health Market Competitive Landscape
On the supply side, the industry is consolidating around integrated platform providers capable of spanning hardware, connectivity, and cloud analytics within unified vendor relationships. Semiconductor specialists, medical device incumbents, and telecommunications operators occupy distinct competitive tiers with limited overlap in core capabilities. Three strategic archetypes dominate: chipset designers controlling radio-frequency protocols, hospital technology integrators managing EHR connectivity, and network operators deploying private cellular infrastructure. M&A activity concentrates on care coordination software acquisitions, while capacity expansion focuses on edge computing deployments for sub-second clinical alerts.
Within the semiconductor tier, Qualcomm Technologies anchors cellular-enabled medical chipset supply through foundry partnerships and protocol licensing structures. Koninklijke Philips exemplifies the integrated device-and-analytics archetype, bundling wearable sensors with cloud-based care coordination dashboards for hospital system procurement committees. AT&T occupies the network-operator position, controlling private 5G deployments for campus-level latency compression in acute care settings.
| Leading Market Players |
|---|
| Qualcomm Technologies |
| Koninklijke Philips |
| Omron Corporation |
| Allscripts Healthcare Solutions |
| AT&T |
| Verizon Communications |
| Epic Systems Corporation |
| Cerner Corporation |
| IBM |
| Others |
Supply & Pricing Matrix
East Asian foundry concentration for cellular-enabled medical chipsets concentrates margin capture upstream with Qualcomm Technologies and TSMC-dependent suppliers, while downstream pricing power aggregates with hospital procurement committees managing subscription-based device fleets. This structural asymmetry forces device manufacturers to absorb component volatility while competing for multi-year SaaS contracts that lock in recurring revenue streams.
Pricing Analysis
Certification level creates the primary spread between premium FDA-cleared platforms and economy-tier wellness devices. Three-tier pricing structure across premium, standard, and economy levels stratifies by clinical validation depth, with chronic disease management commanding subscription premiums and fitness trackers competing on unit economics. Cost compression in the wearable sensor tier is intensifying because Bluetooth Low Energy 5.3 commoditizes basic connectivity, while hospital systems remain least price-sensitive due to federal reimbursement tailwinds and value-based care performance bonuses.
Supply Chain Analysis
Silicon wafer supply feeds from Taiwan, South Korea, and Japan, with medical-grade chipset fabrication resting on TSMC's specialty nodes and Samsung Foundry's LTE-M capacity. Raw material dependencies span gallium arsenide for RF components, lithium polymer for multi-day wearable batteries, and medical-grade plastics for biocompatible housings. Single-source vulnerability concentrates in 5G modem intellectual property held by Qualcomm, while distribution runs through hospital GPO contracts and direct-to-provider SaaS platforms rather than traditional device wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wireless health market functions as a service-attach opportunity where cloud analytics and clinical workflow integration expand faster than hardware shipment volumes. Recurring SaaS revenue from care coordination dashboards now exceeds one-time device margins for integrated platform providers.
For Market Incumbents: Harden regulatory moats by accelerating FDA pre-certification for algorithm-driven diagnostics before emerging AI-native entrants capture prescriber mindshare. Deepen backward integration into edge computing silicon to secure sub-second alert latency capabilities that differentiate against commodity sensor competitors. Lock hospital systems into multi-year subscription arrangements that bundle hardware refreshes with analytics upgrades, concentrating procurement authority within value analysis committees. For New Entrants and Emerging Players: Pursue India's tier-2 city penetration where mobile-first health delivery models face limited incumbent saturation and CDSCO regulatory pathways favor domestic software developers. Target elder care monitoring applications where ultra-wideband positioning convergence enables fall detection hardware-software bundles with limited established competition. Deploy localized platform adaptation through regional clinical workflow partnerships rather than direct hospital system sales. For Investors and Strategic Acquirers: Capital is best deployed toward care coordination software specialists with proven EHR integration capabilities and existing hospital system procurement relationships. The long-term viability window favors platforms demonstrating real-world evidence generation for reimbursement code expansion over pure hardware manufacturers facing semiconductor cost volatility. Watch for algorithm-triggered intervention protocols achieving CMS recognition as the signal for sustainable clinical adoption inflection.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Pre-Certification Pathway | Abbreviated approval timelines accelerate commercialization for algorithm-driven remote monitoring platforms. |
| Hospital System Partnership | Texas and Florida health systems pilot subscription models bundling hardware, connectivity, and analytics. |
| CE Marking Pathway | EU MDR Class IIa compliance enables post-market surveillance registries tracking algorithm performance degradation. |
| Software Companion Development | Bluetooth Low Energy 5.3 integration extends wearable operation for multi-day chronic disease programs. |
| Reimbursement Strategy | Germany's federal digitization mandates drive fleet-scale sensor deployment across integrated provider networks. |
Research Methodology
The analysis maps wearable sensors, telehealth platforms, connected medical devices, and remote patient monitoring ecosystems, each validated through hospital purchasing committees, biomedical engineers, GPO contracts managers, and clinical workflow specialists. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and CDSCO device registrations. Bottom-up shipment estimates triangulate against top-down addressable population models across the analysis window.
Assumptions held reimbursement code expansion and regulatory pathway clarity fixed at observed trajectories, while semiconductor supply concentration and interoperability standard adoption were varied across sensitivity scenarios. Segmentation dimensions modeled include product type, connectivity protocol, application category, and end-user procurement structure. CAGRs derive from fitted adoption curves incorporating hospital digitization mandate timelines and chronic disease prevalence projections, with private 5G deployment pace and edge computing infrastructure buildout as key industry-specific inputs.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by telecommunications operators into care coordination software would shift outcomes substantially. Cross-checking against hospital capital expenditure surveys and GPO contract value disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Global Gi Fi Technology Market
Wireless Technologies
Public Safety Wireless Communication and Municipal Wireless Communication Market
Wireless Technologies
Global Bluetooth Beacon and Ibeacon Market
Wireless Technologies
5G Mmwave Technology Market
Wireless Technologies
Public Wi-Fi Market
Wireless Technologies
USA Li-Fi Market
Wireless Technologies
North America Wireless Microphone Market
Wireless Technologies
Cellular Repeater Market
Wireless Technologies
Global Massive MIMO Market
Wireless Technologies
Distributed Antenna System Market
Wireless Technologies
5G Wireless Equipment Market
Wireless Technologies
Wireless Smart Home Market
Wireless Technologies
5G Wireless Ecosystem Market
Wireless Technologies
Wireless Mesh Networking Market
Wireless Technologies
Wi-Fi Hotspot (Dongle) Market
Wireless Technologies
Industrial Wireless Solution Market