
 Mobile Collaboration Market | 2026-2036
Mobile Collaboration Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Collaboration Market Foresight
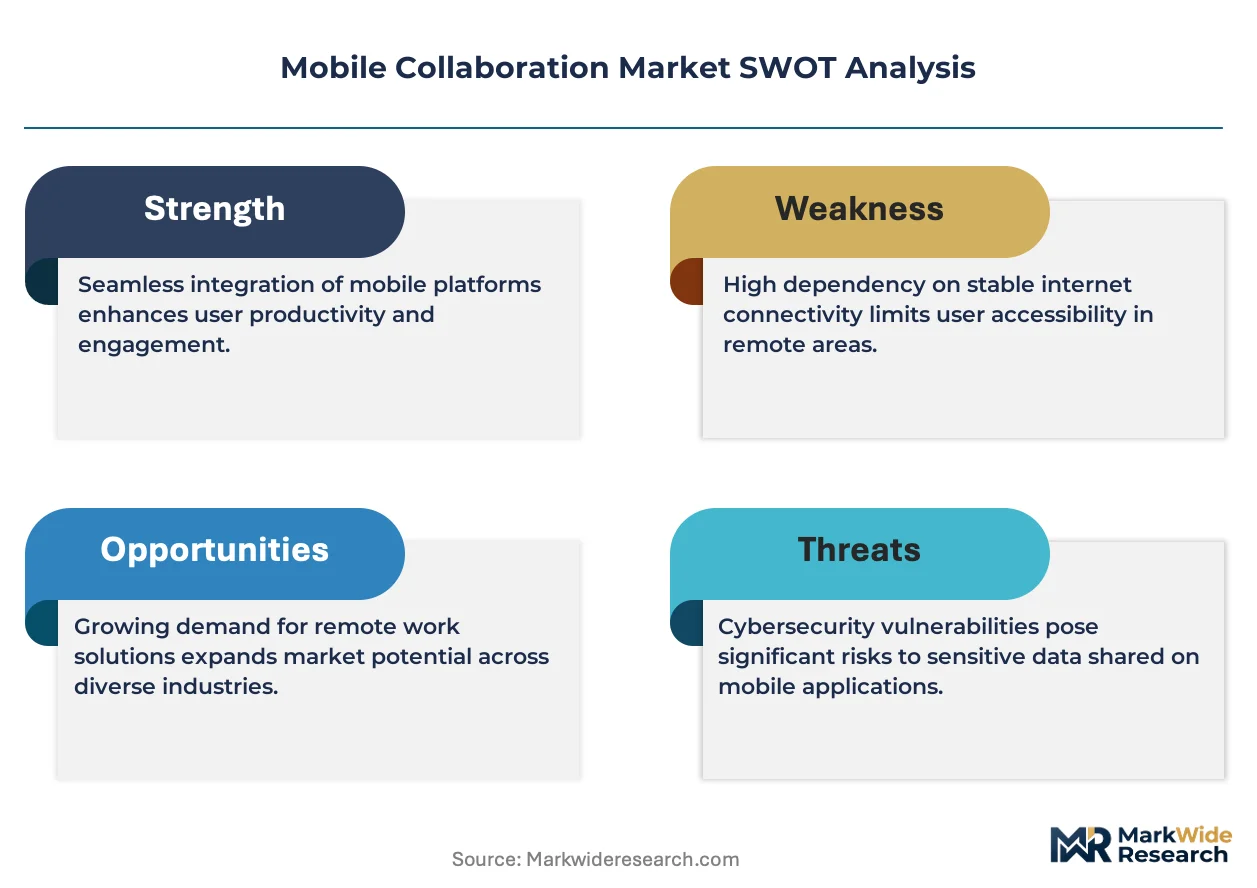
ISO/IEC 27001 certification is collapsing as a baseline market-access requirement, forcing smaller vendors to absorb compliance costs or exit enterprise procurement cycles. Microsoft Teams leverages its Office 365 integration to dominate corporate deployments. Slack competes through channel-based workflow specialization and extensive third-party app connectivity. Zoom anchors its position in video-centric collaboration, though it navigates pressure to diversify beyond meetings into persistent team workspaces.
Mobile collaboration encompasses real-time communication, content co-creation, and task coordination delivered through smartphones, tablets, and wearable devices, typically requiring sub-150ms latency for synchronous editing and AES-256 encryption for enterprise data protection. Its primary commercial purpose is sustaining workforce productivity across distributed locations without tethering employees to desktop environments. Cloud-based solutions lead deployment preferences due to elastic scaling and reduced capital overhead, while AI-powered tools represent the fastest-expanding technology segment as automated transcription, sentiment analysis, and predictive scheduling embed into core workflows. Hybrid solutions capture growing interest from regulated industries requiring on-premises data sovereignty with cloud accessibility.
FCC net-neutrality rulings and HIPAA security standards shape US market access by mandating minimum encryption protocols and audit trails for healthcare communications. The EU AI Act and GDPR impose algorithmic transparency and data-localization requirements that increase compliance costs for cross-border SaaS providers. Stakeholders must monitor whether emerging national data-sovereignty laws fragment platform architectures into incompatible regional instances or drive consolidation around vendors with multi-tenant geographic distribution.
Market Dynamics
Zero-trust security mandates from federal agencies are compressing vendor qualification cycles and consolidating procurement around platforms with pre-certified FedRAMP authorization.
Growth Catalysts
- FedRAMP Authorization:Federal agencies now require FedRAMP Moderate or High authorization for cloud collaboration tools, accelerating platform consolidation among compliant vendors.
- Healthcare Coordination:HIPAA-covered entities demand encrypted messaging with audit trails, expanding deployment of clinical communication platforms across hospital systems.
- AI-Enhanced Workflows:Automated transcription and sentiment analysis tools embed into core collaboration suites, reducing manual documentation burden for distributed teams.
Market Restraints
- Compliance Cost Burden:ISO/IEC 27001 certification and SOC 2 Type II audits impose six-figure annual costs that exclude smaller vendors from enterprise RFPs.
- Data Residency Requirements:GDPR and emerging national data-sovereignty laws force multi-tenant architecture fragmentation, increasing operational complexity for cross-border SaaS providers.
- Latency Constraints:Sub-150ms synchronous editing requirements demand edge computing infrastructure that raises capital intensity for real-time collaboration features.
Strategic Opportunities
- Regulated Industry Hybrid Cloud:Financial services and healthcare organizations seek on-premises data sovereignty with cloud accessibility, creating demand for hybrid deployment models.
- Wearable Integration:Smart glasses and haptic wearables converge with mobile collaboration platforms, enabling hands-free field service coordination in manufacturing and logistics.
- EU AI Act Certification:Algorithmic transparency requirements create first-mover advantage for vendors publishing model cards and bias audit documentation.
Industry Challenges
- Legacy System Integration:Enterprise IT teams struggle to bridge on-premises PBX and document management systems with cloud-native collaboration platforms.
- Zero-Trust Architecture Deployment:Continuous verification models require identity and access management reconfiguration that strains mid-market IT resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Collaboration Market |
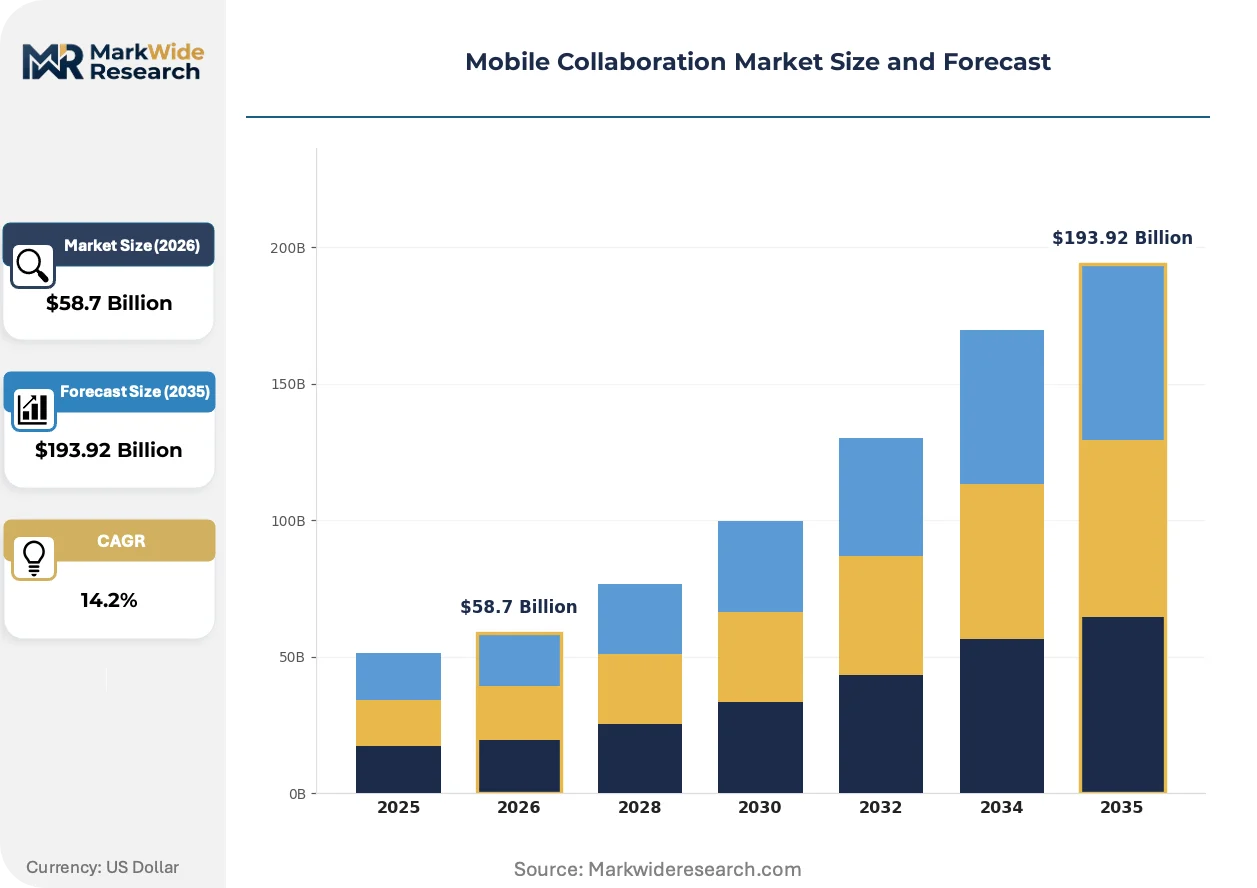
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $193.92 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Messaging Apps, Video Conferencing Tools, Document Sharing Platforms, Collaborative Whiteboards End User: Healthcare Providers, Educational Institutions, Corporate Firms, Remote Teams Deployment: Cloud-Based Solutions, On-Premises Solutions, Hybrid Solutions, SaaS Platforms Technology: AI-Powered Tools, Real-Time Collaboration, 5G Connectivity, Cross-Platform Solutions |
| Companies Covered | Google Workspace, Notion, Slack, Zapier, Miro, Microsoft Teams, Asana, Fireflies, Zoom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Collaboration Market Shifts & Advancements
Artificial intelligence capabilities are embedding into core collaboration workflows faster than standalone productivity tools can maintain relevance. Vendors race to automate routine coordination tasks before competitors capture user preference lock-in.
Edge-resident AI inference is displacing cloud-only processing for real-time transcription and translation features. Healthcare systems and financial trading floors adopt on-device speech recognition to minimize data transit latency. This architecture shift compresses vendor differentiation around model efficiency rather than raw cloud compute scale.
The EU AI Act's risk-based classification system imposes documentation burdens on high-risk workplace monitoring applications. Vendors must publish technical documentation and human oversight protocols for emotion recognition and productivity scoring features. German works councils and French labor inspectors lead enforcement, forcing product managers to strip functionality from European deployments.
Enterprise buying committees now require security certification proof points before pilot authorization, extending sales cycles but reducing post-deployment churn. Channel partners and systems integrators capture margin by pre-validating compliance documentation for mid-market buyers. United States federal contractors exhibit this pattern most acutely, with FedRAMP authorization serving as table stakes for vendor consideration.
Mobile Collaboration Market Segmentation
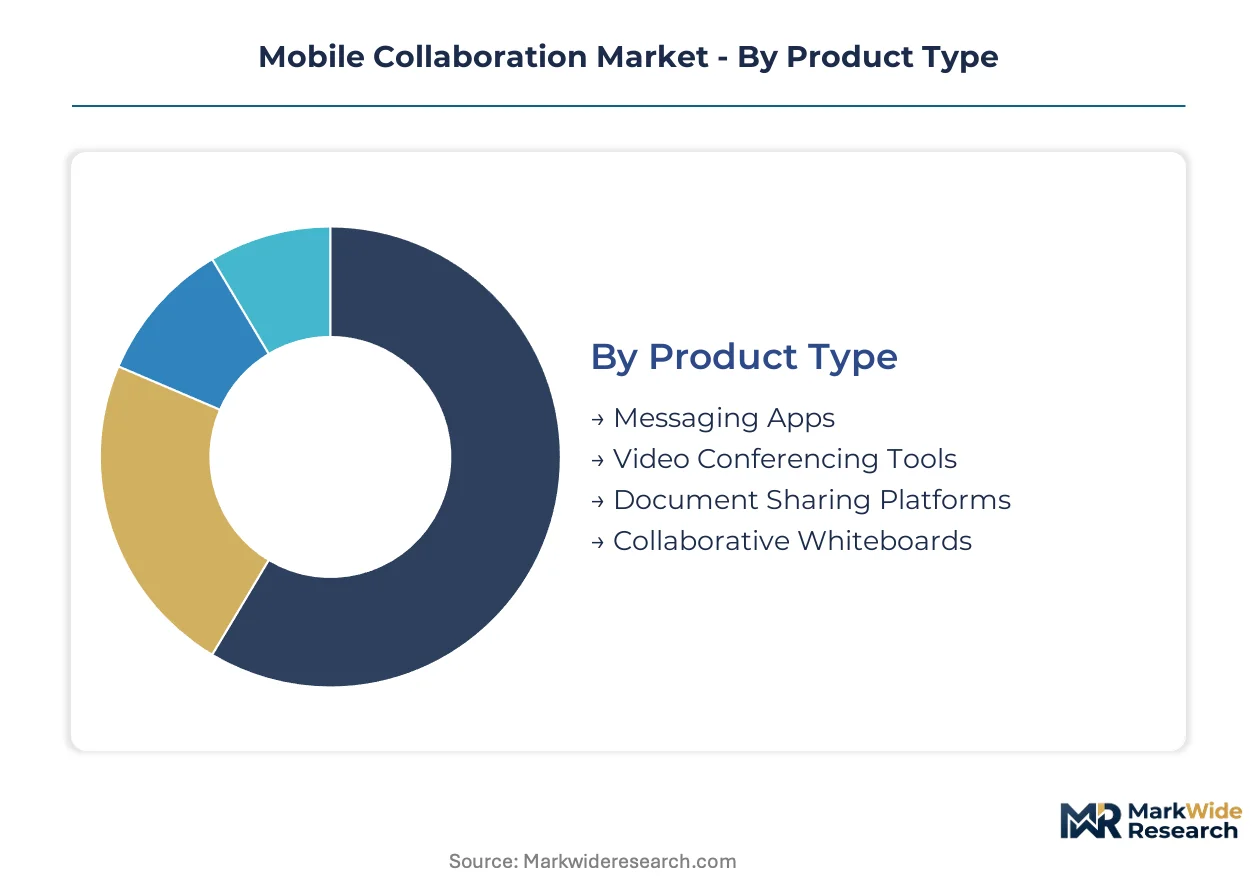
Mobile collaboration platforms fragment across four distinct axes that determine procurement priorities and vendor positioning. Deployment architecture and end-user verticals exert the strongest influence on pricing and compliance requirements.
Product Type:
Messaging apps and video conferencing tools concentrate demand in North American enterprise procurement, while document sharing platforms and collaborative whiteboards see stronger traction in European regulated industries.
- Messaging Apps:Deliver encrypted text, voice, and file exchange with sub-second delivery confirmation. Healthcare systems in the United States prioritize these for HIPAA-compliant clinical coordination, driving integration with electronic health record systems.
- Video Conferencing Tools:Enable synchronous audio-visual communication with screen sharing and recording capabilities. Corporate headquarters and federal contractors dominate procurement, with FedRAMP authorization serving as a non-negotiable qualifier for vendor consideration.
- Document Sharing Platforms:Support version-controlled file synchronization with granular access permissions. Financial services firms in Germany and France adopt these under GDPR and EU AI Act constraints.
- Collaborative Whiteboards:Provide infinite canvas interfaces for visual brainstorming and diagramming. Design agencies and product teams in the United Kingdom and Netherlands represent the core user base.
Video conferencing tools hold the largest share; momentum sits with collaborative whiteboards.
End User:
Cost tier separation distinguishes enterprise buyers with dedicated compliance budgets from mid-market adopters seeking freemium entry points.
- Healthcare Providers:Require audit trails, encryption at rest and in transit, and integration with clinical workflows. Hospital systems across the United States, Germany, and Japan drive premium pricing for certified platforms.
- Corporate Firms:Demand scalable seat licensing with single sign-on and advanced analytics dashboards. Multinational headquarters in New York, London, and Singapore anchor volume procurement.
- Educational Institutions:Prioritize accessibility compliance and learning management system integration. Public universities in California and Texas represent the largest North American contracts.
- Remote Teams:Favor lightweight, mobile-first interfaces with low per-seat costs. Freelance collectives and startup incubators in Berlin and Bangalore expand most quickly.
Corporate firms command the highest average contract values; remote teams are climbing the fastest.
Deployment:
Application criticality determines architecture choice, with regulated workloads demanding data sovereignty and latency-sensitive operations requiring edge proximity.
- Cloud-Based Solutions:Deliver multi-tenant elasticity with automatic updates and consumption-based pricing. SaaS-native startups and mid-market firms across the United States and United Kingdom default to this model.
- Hybrid Solutions:Combine on-premises data residency with cloud accessibility for burst capacity. Swiss banks and German automotive manufacturers lead adoption for intellectual property protection.
- On-Premises Solutions:Provide complete infrastructure control within organizational firewalls. Defense contractors and intelligence agencies in the United States mandate this architecture.
- SaaS Platforms:Offer standardized feature sets with rapid deployment timelines. Professional services firms in Australia and Canada favor this for operational simplicity.
Cloud-based solutions dominate seat count; hybrid solutions gain share fastest.
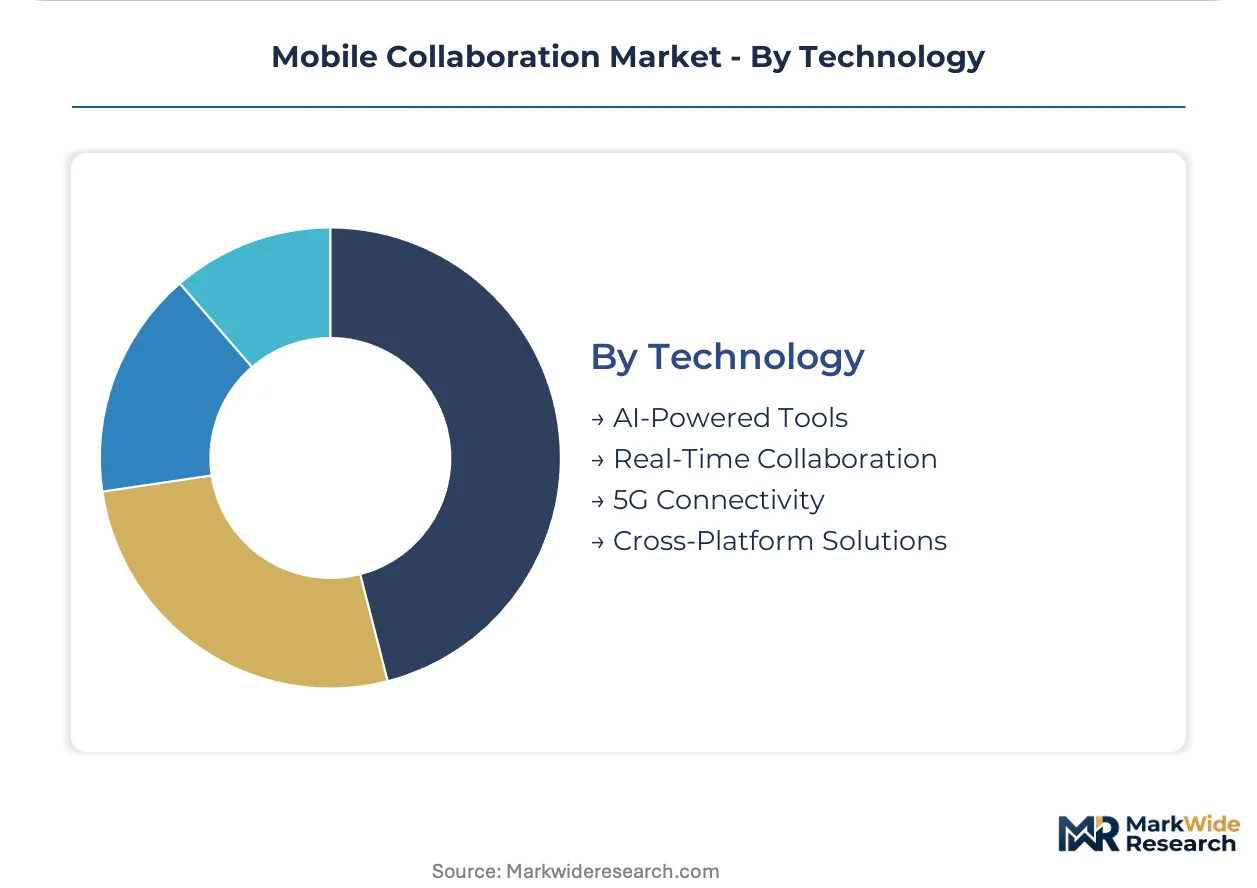
Technology:
Customer maturity separates early AI adopters seeking workflow automation from conservative buyers prioritizing proven interoperability.
- AI-Powered Tools:Embed automated transcription, sentiment analysis, and predictive scheduling into core workflows. Technology companies in Silicon Valley and Shenzhen pilot these capabilities most aggressively.
- 5G Connectivity:Enables sub-50ms latency for high-definition mobile video and augmented reality overlays. South Korean manufacturing floors and Japanese logistics hubs deploy these for field service coordination.
- Real-Time Collaboration:Synchronizes document edits and cursor movements across distributed users. Legal and financial advisory firms in New York and London require this for time-sensitive deal execution.
- Cross-Platform Solutions:Ensure functional parity across iOS, Android, Windows, and macOS endpoints. Government agencies with mixed device fleets in Canada and Australia mandate this compatibility.
Real-time collaboration holds the largest installed base; AI-powered tools show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FedRAMP authorization requirements and GDPR compliance mandates are fragmenting procurement patterns across major economies, with each jurisdiction imposing distinct certification burdens on platform vendors seeking market access.
United States
Federal zero-trust mandates and healthcare HIPAA compliance drive enterprise platform consolidation. FCC net-neutrality rulings shape minimum encryption protocols for cross-state communications. Hospital systems in Boston and federal contractors in Washington D.C. anchor demand for FedRAMP-authorized clinical coordination tools.
Germany
Industrial manufacturing clusters and automotive supply chains demand hybrid cloud architectures for intellectual property protection. The EU AI Act and GDPR impose algorithmic transparency requirements that increase compliance documentation burdens. Works councils in Stuttgart and Munich enforce strict workplace monitoring restrictions on emotion recognition features.
United Kingdom
Financial services firms in London require sub-150ms latency for real-time trading floor coordination. Post-Brexit data adequacy negotiations create uncertainty for cross-border SaaS data flows. Design agencies and product teams in Manchester and Bristol represent core adopters of collaborative whiteboard platforms.
Japan
Manufacturing floors and logistics hubs deploy 5G-enabled mobile collaboration for field service coordination. METI industrial digitization programs subsidize SME adoption of cloud-based productivity tools. Technology companies in Tokyo and Osaka pilot AI-powered transcription and predictive scheduling capabilities most aggressively.
Switzerland
Private banking and pharmaceutical headquarters demand on-premises data sovereignty with selective cloud burst capacity. Swissmedic and FINMA regulations mandate audit trails for clinical and financial communications. Zurich and Geneva-based wealth managers anchor premium pricing for certified hybrid deployment models.
Mobile Collaboration Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and integration breadth. The vendor base clusters around three strategic tiers: hyperscale platforms with pre-certified federal authorization, workflow specialists with deep third-party connectivity, and vertical-specific tools for regulated industries. Competitive moves concentrate on FedRAMP certification acquisition and AI feature embedding to capture enterprise buying committee preference.
Within the hyperscale platform tier, Microsoft Teams and Google Workspace exemplify archetypes competing through ecosystem lock-in and cross-application integration density. Slack occupies a position representing workflow specialization through channel-based coordination and extensive app marketplace connectivity. Zoom anchors the video-centric archetype, though competitive pressure forces diversification beyond synchronous meetings into persistent team workspaces.
| Leading Market Players |
|---|
| Google Workspace |
| Notion |
| Slack |
| Zapier |
| Miro |
| Microsoft Teams |
| Asana |
| Fireflies |
| Zoom |
| Others |
Supply & Pricing Matrix
Edge computing infrastructure substitution for centralized cloud data centers is redrawing procurement geography and compressing margin structures across vendor tiers simultaneously.
Pricing Analysis
Certification level creates the primary spread between FedRAMP-authorized premium tiers and uncertified economy offerings. SaaS subscription models dominate with seat-based tiers, while HIPAA and ISO/IEC 27001 compliance premiums separate healthcare-grade deployments from standard enterprise licenses. Cost compression in the mid-market intensifies as freemium entrants force incumbent discounting. Remote teams and freelance collectives exhibit the highest price sensitivity; federal contractors and Swiss private banking clients show the least.
Supply Chain Analysis
Inventory lead times for AI inference chips and edge server hardware have extended from semiconductor foundry constraints in Taiwan, South Korea, and the United States. Cloud infrastructure draws from hyperscaler data center networks, 5G spectrum allocations, and encryption module supply chains concentrated in Germany and Japan. Single-source vulnerability sits with NVIDIA GPU dependencies for real-time transcription workloads. Distribution runs through direct enterprise sales teams, systems integrator channel partners, and hyperscaler marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Federal procurement cycles are recovering from pandemic-era backlog clearance, with zero-trust mandate deadlines compressing vendor qualification windows and accelerating replacement demand.
For Market Incumbents: Secure FedRAMP High authorization before fiscal year-end procurement waves to lock out uncertified competitors. Deepen backward integration into edge computing hardware partnerships to control latency-critical infrastructure costs. Channel partner pre-certification programs represent the priority lever for mid-market expansion. For New Entrants and Emerging Players: Anchor in hybrid deployment architectures for German automotive and Swiss pharmaceutical verticals where data sovereignty requirements exclude pure-cloud incumbents. Target clinical communication platform gaps in Japanese hospital systems with 5G-enabled field service coordination tools. Go-to-market through METI-subsidized SME digitization programs accelerates initial traction. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors workflow specialists with deep third-party connectivity and pre-certified federal authorization. Long-term viability over the next decade hinges on AI feature embedding speed rather than raw user scale. Acquisition targets should demonstrate algorithmic transparency documentation readiness for EU AI Act compliance. Watch for FedRAMP authorization backlog clearance velocity as the inflection signal for platform consolidation pace.| Strategic Initiative | Industry Significance |
|---|---|
| FedRAMP Authorization Acquisition | Federal contractors in Washington D.C. mandate this qualification for vendor consideration. |
| Edge AI Inference Deployment | Healthcare systems in Boston adopt on-device speech recognition to minimize data transit latency. |
| Hybrid Cloud Architecture Launch | Swiss banks in Zurich demand on-premises data sovereignty with selective cloud burst capacity. |
| EU AI Act Certification Program | German works councils enforce algorithmic transparency requirements on workplace monitoring features. |
| Channel Partner Pre-Validation Network | Systems integrators capture margin by pre-validating compliance documentation for mid-market buyers. |
Research Methodology
A spread of perspectives from platform engineering directors, healthcare IT procurement officers, federal contracting specialists, and channel partner principals converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against SEC filings, hyperscaler capex disclosures, App Annie mobile collaboration adoption metrics, and FedRAMP authorization databases. Bottom-up seat deployment estimates and top-down enterprise IT spending triangulation anchored value projections.
Segmentation dimensions modeled include deployment architecture, end-user vertical, organization size tier, and integration complexity level across the projection horizon. CAGRs emerged from fitting logistic adoption curves to historical penetration data and stress-testing against regulatory mandate timelines. AI feature embedding velocity and 5G infrastructure rollout pace served as industry-specific forecast sensitivity inputs.
Decision-makers should treat outputs as directional under assumptions of sustained federal zero-trust compliance deadlines and stable EU-U.S. data adequacy frameworks; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Service Virtualization Market
Digital Solutions
Indonesia Digital Software Solutions Market
Digital Solutions
Laser Page-Turning Pen Market
Digital Solutions
Deviation Management and CAPA Platforms for Cold Chain Logistics Market
Digital Solutions
Correspondence Management Solution Market
Digital Solutions
US Digital Twin Market
Digital Solutions
Demand Planning Solutions Market
Digital Solutions
Digital Workplace Market
Digital Solutions
Email Deliverability Tools Market
Digital Solutions
Data Pipeline Tools Market
Digital Solutions
Next Generation Search Engines Market
Digital Solutions
Global Sharing Economy Market
Digital Solutions
Digital Manufacturing Software Market
Digital Solutions
Data As a Service (Daas) Market
Digital Solutions
Kuwait ICT Market
Digital Solutions
Graph Technology Market