
 Weather Data Services Market | 2026-2036
Weather Data Services Market Size, Share, and Industry Trends Forecast 2026-2036
Weather Data Services Market Outlook
High-resolution satellite imagery is rebalancing cost structures across weather data provisioning, compressing the economics of ground-station-only networks. DTN leverages proprietary mesoscale modeling to anchor its position in agricultural risk management. AccuWeather, Inc. competes through broadcast and digital channel control that extends its data monetization beyond core meteorological subscriptions. The Weather Company dominates enterprise API delivery, sustaining renewal rates through deep integration with cloud infrastructure providers.
Weather data services encompass the collection, processing, and distribution of atmospheric observations and model outputs through digital platforms, typically delivered via REST APIs with sub-hourly update frequencies and spatial resolutions reaching one kilometer. These services enable operational decision-making across sectors exposed to meteorological variability, from aviation routing to crop protection protocols. Forecasting solutions command the largest revenue share within service type segmentation, while predictive analytics represents the fastest-expanding category as machine learning training sets deepen. API delivery mode leads in enterprise uptake, though mobile application growth accelerates among smallholder agriculture users in emerging economies.
The National Oceanic and Atmospheric Administration's open data policies shape competitive dynamics by providing foundational observational inputs that private providers refine and repackage. The European Commission's Destination Earth initiative and the UK Met Office's public-private partnership frameworks influence market access conditions and data quality benchmarks across North Atlantic markets. Stakeholders must monitor how national meteorological services reposition their commercial licensing terms as fiscal pressures mount and satellite constellation operators pursue direct-to-enterprise distribution channels.
Market Dynamics
High-resolution satellite constellations are compressing the cost economics of ground-station-only networks, forcing established providers to rebalance capital allocation between proprietary sensor arrays and third-party imagery licensing.
Growth Catalysts
- EU Green Deal climate adaptation mandates:These requirements accelerate deployment of hyperlocal monitoring networks across member states, creating sustained procurement pipelines for meteorological analytics platforms.
- Offshore wind development:Germany's North Sea and Baltic Sea expansion drives subscription growth for precision forecasting services that optimize turbine dispatch and maintenance scheduling.
- Machine learning training sets:Deepening historical atmospheric databases enable predictive analytics applications that command premium pricing in agricultural risk management.
Market Restraints
- Ground-station capital intensity:Dense sensor networks require substantial fixed investment in hardware, site acquisition, and telemetry infrastructure that limits geographic coverage expansion.
- NOAA open data dependency:Foundational observational inputs from US federal sources create vulnerability to policy shifts or budget reallocations that could disrupt upstream data supply.
- API commoditization pressure:Standardized REST delivery formats reduce differentiation barriers, compressing margins for providers lacking proprietary modeling or vertical integration.
Strategic Opportunities
- Smallholder agriculture in emerging economies:Mobile application penetration creates addressable demand among farmers previously excluded from subscription meteorological services.
- Destination Earth initiative:The European Commission's digital twin program funds high-fidelity simulation infrastructure that private providers can leverage for enhanced forecast accuracy.
- Aviation routing optimization:Turbulence prediction and contrail avoidance algorithms represent underpenetrated use cases with measurable fuel savings justifying enterprise licensing.
Industry Challenges
- Atmospheric data science talent scarcity:The intersection of meteorology, machine learning, and distributed systems engineering constrains product development velocity across the vendor base.
- Legacy system integration friction:Enterprise customers in utilities and aviation maintain decades-old operational platforms that resist seamless API connectivity without costly middleware development.
- Cross-border data sovereignty compliance:Divergent national regulations on atmospheric observation sharing create jurisdictional complexity for global platform operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Weather Data Services Market |
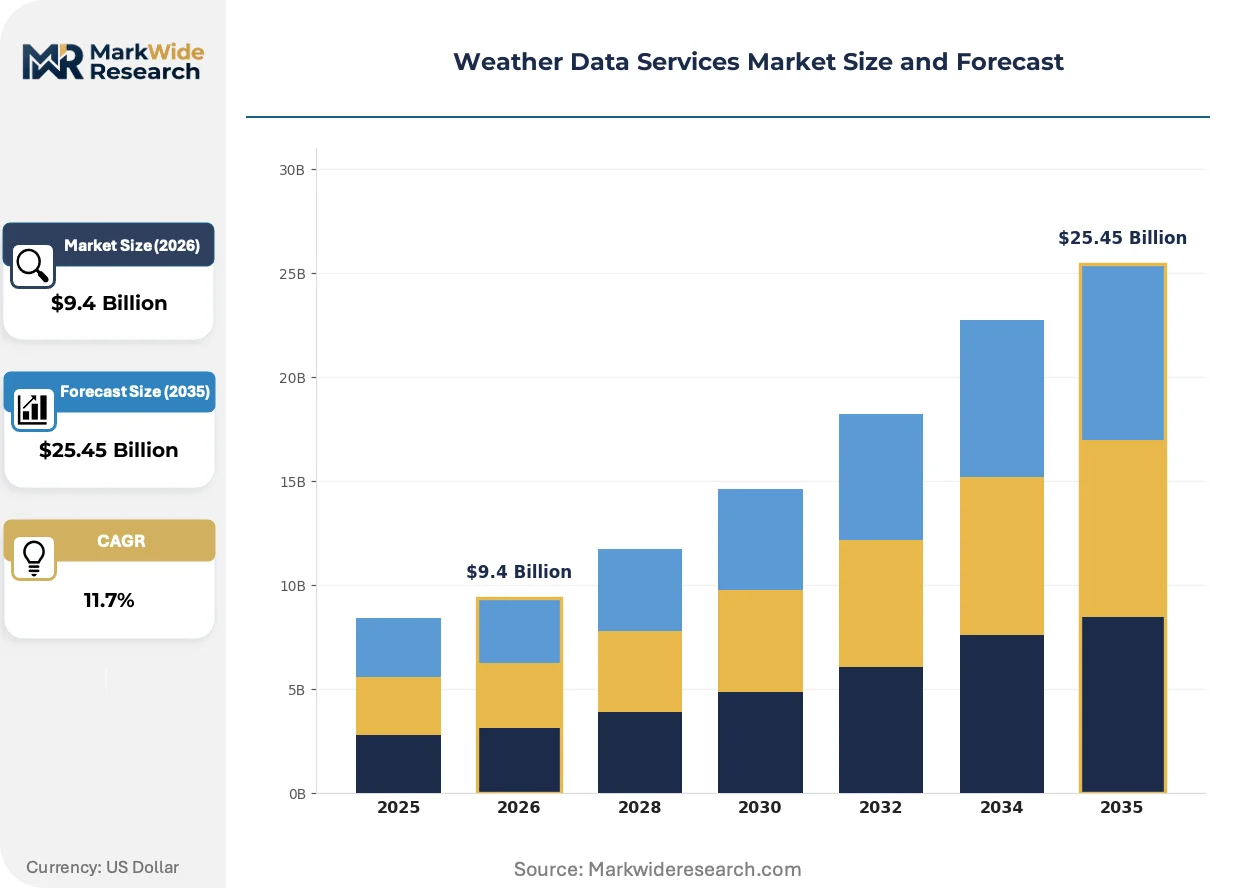
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $25.45 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Forecasting, Monitoring, Analytics, Alerts End User: Agriculture, Transportation, Energy, Retail Delivery Mode: API, Web Application, Mobile Application, On-premises Solution: Climate Modeling, Real-time Data, Historical Data, Predictive Analytics |
| Companies Covered | The Weather Company, AccuWeather, Inc., DTN, OpenWeather, Meteomatics, Meteoblue, Weather Underground, StormGeo, Fugro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Weather Data Services Market Strategic Shifts
Synthetic aperture radar and hyperspectral imaging are expanding the observable atmospheric variables beyond traditional visible and infrared spectra, enabling new monetizable forecast products.
CubeSat constellations delivering sub-hourly revisit frequencies are expanding into agricultural monitoring applications, with Brazilian soybean cooperatives and Australian wheat belt operators adopting subscription services that replace government bulletin dependency. The compression of imagery economics is enabling tiered service models that previously required dedicated government procurement.
The EU AI Act's risk classification framework for automated decision systems is imposing documentation and audit requirements on predictive analytics providers serving critical infrastructure operators. Weather data platforms supplying algorithmic inputs to aviation dispatch and grid management must now maintain explainability trails. German transmission system operators are requiring enhanced model transparency as a procurement qualification criterion.
Subscription billing is displacing per-call API pricing among enterprise accounts seeking cost predictability for operational budgeting. Utilities and agricultural conglomerates in the US Great Plains and Canadian prairies are consolidating vendor relationships under multi-year enterprise agreements with service-level guarantees. This concentration of purchasing authority favors providers with dedicated customer success infrastructure and vertical-specific application layers.
Weather Data Services Market Segmentation
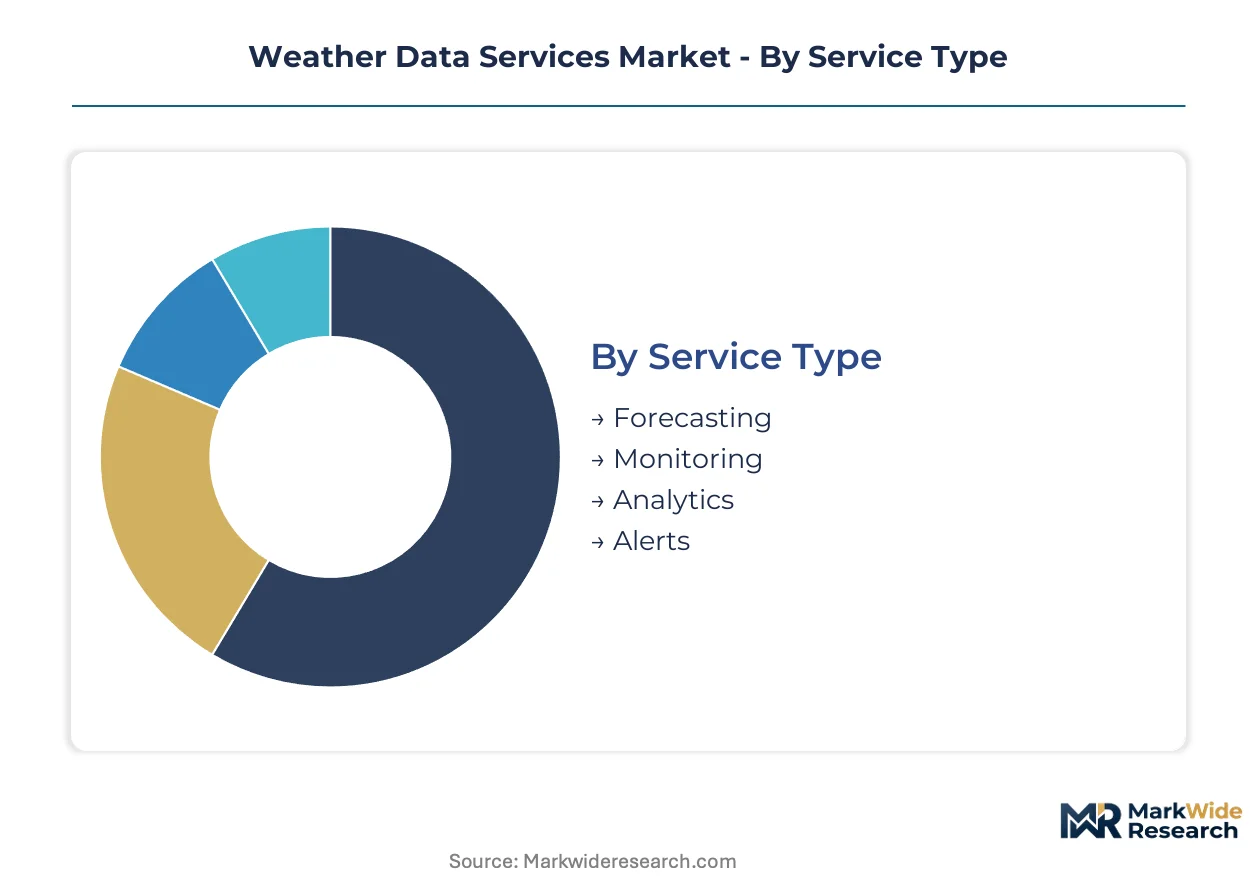
Weather data services fragment across multiple technical and commercial dimensions, each shaping procurement patterns and vendor specialization. The four primary segmentation axes—service type, end user, delivery mode, and solution—determine pricing architecture, integration complexity, and renewal economics across customer accounts.
Service Type:
Standardized meteorological outputs compete against bespoke advisory services across this spectrum, with automation driving cost compression at the base and human expertise commanding premiums at the top.
- Forecasting:Numerical weather prediction outputs delivered through deterministic and ensemble model suites form the revenue foundation. Grid operators in Germany and aviation dispatch centers in the United States anchor procurement volume through operational dependency on 15-minute to 6-hour horizon updates.
- Analytics:Machine learning-derived insights transform raw atmospheric observations into actionable risk metrics for crop protection and energy trading. Brazilian soybean cooperatives and Australian wheat belt operators are expanding subscriptions fastest as government bulletin dependency fades.
- Monitoring:Real-time observational feeds from satellite constellations and ground sensor networks support continuous environmental surveillance.
- Alerts:Threshold-triggered notification systems deliver critical weather warnings through SMS, email, and push channels for emergency response coordination.
Most installed capacity flows through Forecasting. Expansion is steepest in Analytics.
End User:
Customer sophistication and data integration depth vary dramatically across sectors, from precision agriculture's mobile-first consumption to energy utilities' enterprise system embedding.
- Energy:Transmission system operators and renewable asset managers consume hyperlocal forecasting for turbine dispatch and solar irradiance optimization. EU Green Deal mandates are accelerating procurement pipelines across member states.
- Agriculture:Large-scale cooperatives and individual smallholders represent bifurcated demand profiles, with mobile application penetration unlocking previously excluded farmers in emerging economies.
- Transportation:Aviation routing and maritime logistics drive requirements for turbulence prediction and contrail avoidance algorithms with measurable fuel savings justification.
- Retail:Demand forecasting and supply chain optimization applications leverage weather correlation models for inventory positioning and promotional timing.
Energy commands the largest contract values. Agriculture is gaining share fastest through mobile penetration.
Delivery Mode:
Enterprise infrastructure constraints and user mobility requirements create distinct technical specifications across consumption channels.
- API:RESTful endpoints with sub-hourly update frequencies and one-kilometer spatial resolution dominate enterprise uptake. Deep integration with cloud infrastructure providers sustains renewal rates among platform-native customers.
- Mobile Application:Smartphone-delivered services are accelerating fastest among smallholder agriculture users in emerging economies where desktop infrastructure remains limited.
- Web Application:Browser-based dashboards serve mid-market customers seeking visualization without integration overhead.
- On-premises:Air-gapped deployments satisfy defense, critical infrastructure, and data sovereignty requirements in regulated jurisdictions.
API delivery carries the highest revenue concentration. Mobile Application is climbing the fastest as emerging market access expands.
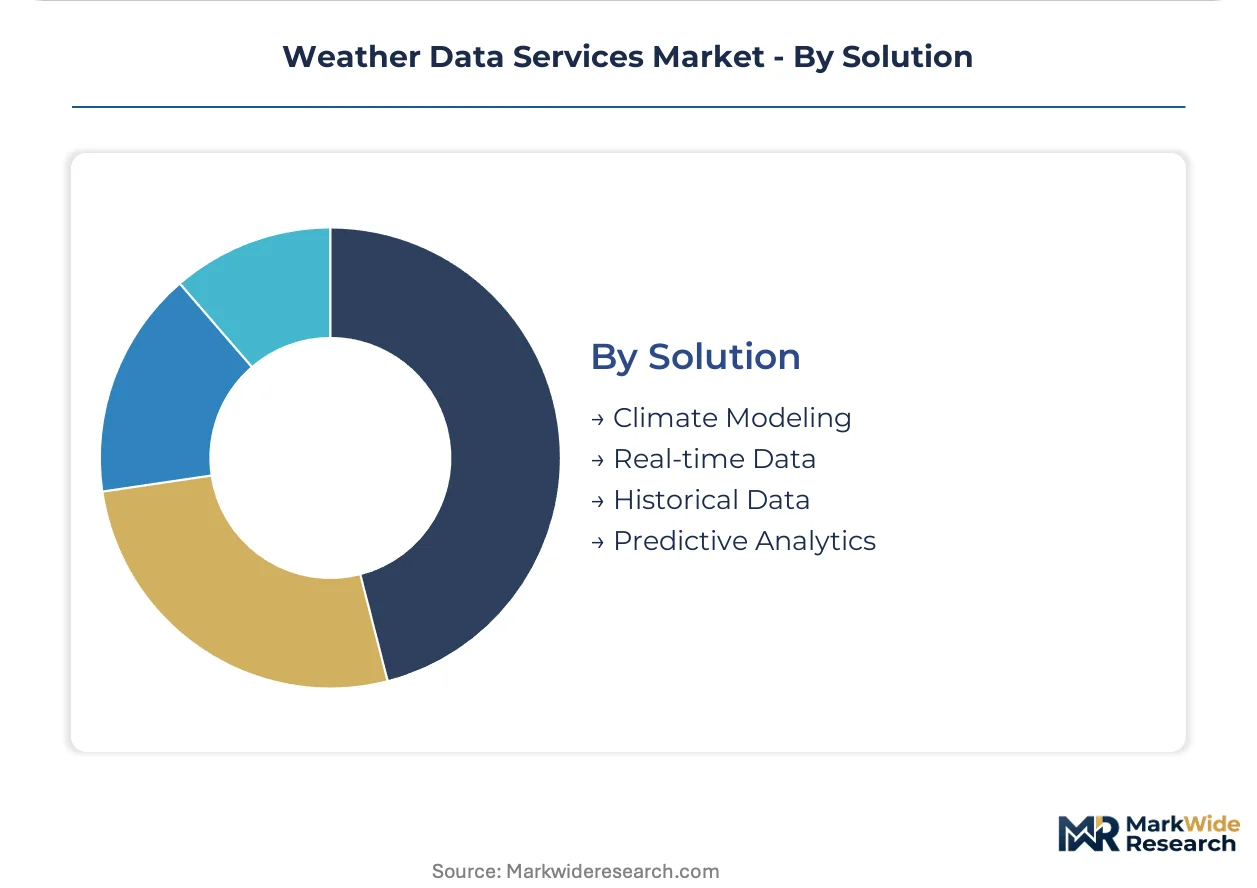
Solution:
Temporal orientation and computational intensity differentiate offerings across historical reconstruction, present observation, and future simulation.
- Predictive Analytics:Machine learning training sets applied to historical atmospheric databases enable risk scoring and probabilistic scenario generation. Agricultural risk management platforms command premium pricing for yield prediction and crop protection timing.
- Climate Modeling:Long-range simulation infrastructure supports strategic planning for infrastructure resilience and agricultural adaptation. The European Commission's Destination Earth initiative funds high-fidelity capabilities that private providers leverage.
- Real-time Data:Sub-hourly observational streams from satellite constellations and sensor networks support operational decision-making with minimal latency.
- Historical Data:Archived atmospheric records enable backtesting, trend analysis, and machine learning model training for retrospective insight generation.
Climate Modeling absorbs the most capital investment. Predictive Analytics is expanding most quickly through machine learning adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German transmission system operators anchor procurement volume for hyperlocal forecasting platforms as North Sea offshore wind expansion accelerates. EU Green Deal mandates are reshaping meteorological infrastructure investment patterns across member states.
Germany
Offshore wind developers in the North Sea and Baltic Sea drive subscription growth for turbine dispatch optimization and maintenance scheduling services. The EU Green Deal's climate adaptation requirements accelerate hyperlocal monitoring network deployment across federal states. Hamburg-based energy traders and Bavarian precision agriculture cooperatives represent concentrated demand clusters for meteorological analytics platforms.
United States
Aviation dispatch centers and Great Plains utilities consume high-frequency forecasting outputs for operational routing and renewable asset management. NOAA's open data policies provide foundational observational inputs that private providers refine and repackage. The Dallas-Fort Worth metroplex and California's Central Valley host dense concentrations of agricultural risk management subscribers.
United Kingdom
Maritime logistics operators and North Sea energy infrastructure managers require precision forecasting for vessel routing and platform safety protocols. The UK Met Office's public-private partnership frameworks influence data quality benchmarks and market access conditions. Aberdeen's offshore engineering cluster and London's insurance underwriting district sustain specialized meteorological service demand.
Brazil
Soybean cooperatives in Mato Grosso and São Paulo are adopting satellite-based subscription services that replace government bulletin dependency. CubeSat constellation operators target agricultural monitoring applications with sub-hourly revisit frequencies. The Campinas technology corridor hosts emerging domestic meteorological analytics ventures serving South American commodity markets.
Australia
Wheat belt operators and mining logistics coordinators purchase real-time observational feeds for crop protection timing and supply chain optimization. The Bureau of Meteorology's data licensing terms shape competitive conditions for private forecast providers. Perth's resources sector and Queensland's agricultural regions represent high-value subscription account concentrations.
Weather Data Services Market Competitive Environment
Strategic partnerships dominate the current landscape as providers rebalance capital allocation between proprietary sensor arrays and third-party imagery licensing. The vendor base fragments across specialized meteorological modeling firms, broadcast media extensions, and enterprise API platforms. Three archetypes prevail: agricultural risk specialists leveraging mesoscale modeling, broadcast-derived data monetizers controlling digital channel distribution, and cloud-native API providers embedding through infrastructure partnerships. Technology licensing agreements and geographic expansion into emerging economy agricultural markets represent the dominant competitive moves.
Within the agricultural risk specialist tier, DTN exemplifies proprietary modeling capabilities that anchor subscription pricing power. AccuWeather, Inc. occupies a position as the broadcast-media-derived archetype, extending data monetization beyond core meteorological subscriptions through digital channel control. The Weather Company sits within the enterprise API tier, sustaining renewal rates through deep integration with cloud infrastructure providers.
| Leading Market Players |
|---|
| The Weather Company |
| AccuWeather, Inc. |
| DTN |
| OpenWeather |
| Meteomatics |
| Meteoblue |
| Weather Underground |
| StormGeo |
| Fugro |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal climate adaptation mandates function as procurement qualification gates, restricting qualified supply to providers with hyperlocal monitoring networks and certified model transparency while enabling premium-tier pricing for compliant meteorological analytics platforms serving German transmission system operators and North Sea offshore wind developers.
Pricing Analysis
Input-cost pass-through from satellite constellation licensing and proprietary mesoscale modeling development anchors subscription pricing architecture. Three-tier pricing structure across premium, standard, and economy levels segments by spatial resolution, update frequency, and vertical-specific application layers. Cost compression in the API tier is intensifying because standardized REST delivery formats reduce differentiation barriers. Smallholder agriculture users in emerging economies exhibit highest price sensitivity, while German utilities and aviation dispatch centers demonstrate lowest sensitivity due to operational dependency and measurable fuel savings justification.
Supply Chain Analysis
Single-source vulnerability sits with NOAA's open data policies for foundational observational inputs that private providers refine and repackage. Raw material dependencies center on satellite imagery licensing from constellation operators, proprietary sensor array hardware, and machine learning training infrastructure. Supply chain risk manifests as policy-shift vulnerability to US federal budget reallocations that could disrupt upstream data supply. Distribution runs through cloud infrastructure partnerships for enterprise API delivery, mobile application stores for emerging market agriculture penetration, and direct licensing agreements for on-premises air-gapped deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in predictive analytics applications where deepening machine learning training sets enable premium pricing, while satellite imagery economics compress input costs for tiered service models.
For Market Incumbents: To counter API commoditization pressure from standardized REST delivery formats, anchor renewal rates through deep integration with cloud infrastructure providers and invest in proprietary mesoscale modeling capabilities that resist price erosion. DTN's agricultural risk management positioning demonstrates how vertical-specific application layers sustain pricing power against generic forecast providers. For New Entrants and Emerging Players: Mobile application penetration in emerging economies represents the most addressable white-space expansion route. Target Brazilian soybean cooperatives and Australian wheat belt operators with subscription services that replace government bulletin dependency, leveraging CubeSat constellation sub-hourly revisit frequencies as a technical differentiation angle against established ground-station networks. For Investors and Strategic Acquirers: Valuations sit cheapest among broadcast-media-derived data monetizers lacking cloud-native API infrastructure or proprietary modeling depth. Long-term viability favors providers with atmospheric data science talent pipelines and EU AI Act compliance documentation for critical infrastructure algorithmic inputs. Watch German transmission system operator procurement criteria for explainability trail requirements as an inflection indicator for market access conditions.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Mesoscale Modeling Investment | DTN anchors agricultural risk management pricing power against commodity forecast providers. |
| Cloud Infrastructure Partnership Deepening | The Weather Company sustains enterprise renewal rates through AWS, Azure, and GCP embedding. |
| CubeSat Constellation Licensing Agreement | Sub-hourly revisit frequencies unlock smallholder agriculture subscriptions in Mato Grosso cooperatives. |
| EU AI Act Compliance Certification | German TSO procurement criteria now require explainability trails for algorithmic grid inputs. |
| Mobile Application Geographic Expansion | Smartphone penetration displaces government bulletin dependency among emerging market farmers. |
Study Parameters
Multiple input streams — structured interviews with meteorological platform executives, grid operator procurement officers, and agricultural cooperative managers; regulatory filings from the European Commission and UK Met Office; and satellite operator licensing disclosures — were reconciled against NOAA open data policy documentation and hyperscaler partnership announcements. Bottom-up account triangulation across German transmission system operators, Brazilian soybean cooperatives, and US aviation dispatch centers was validated against top-down market sizing from service type segmentation.
Data-stream reconciliation across forecasting, analytics, monitoring, and alerts service categories enabled projection modeling across the analysis window. Segmentation dimensions included delivery mode differentiation between API and mobile application channels, end-user verticals spanning energy and agriculture, and solution types from predictive analytics to climate modeling. CAGRs were derived from subscription renewal rate analysis and procurement pipeline tracking across EU Green Deal mandated deployments.
The model assumes a particular technology adoption path; alternative pathways for synthetic aperture radar and hyperspectral imaging expansion would alter the outlook for ground-station-only network displacement. Forecasts reflect assumptions about NOAA data policy continuity and EU AI Act implementation timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Canada Geospatial Imagery Analytics Market
Analytics
FMCG Spending on Analytics Market
Analytics
Iraq ICT Market
Analytics
Global Customer Analytics Market
Analytics
Germany Geospatial Analytics Market
Analytics
Manufacturing Analytics Market
Analytics
Europe Supply Chain Analytics Market
Analytics
Global Digital Intelligence Platform Market
Analytics
Europe Predictive Analytics Market
Analytics
Global System Monitoring Market
Analytics
Application Analytics Market
Analytics
Regression Analysis Tool Market
Analytics
Supply Chain Big Data Analytics Market
Analytics
Big Data Analytics in Automotive Market
Analytics
Connected Device Analytics Market
Analytics
Identity Analytics Market