
 Global Nebuliser Market | 2026-2036
Global Nebuliser Market Size, Share, and Industry Trends Forecast 2026-2036
Global Nebuliser Market Foresight
Multi-source component procurement is broadening across nebuliser supply chains as manufacturers diversify beyond single-source pneumatic parts. Omron Corporation leverages its sensor technology heritage to sustain precision manufacturing advantages in Asia-Pacific production hubs. Koninklijke Philips N.V. anchors its position through integrated respiratory care ecosystems that pair nebulisers with diagnostic platforms. PARI Respiratory Equipment, Inc. differentiates through specialized pediatric and cystic fibrosis applications that command clinical loyalty.
A nebuliser converts liquid medication into aerosol droplets for inhalation therapy, typically generating particle sizes between one and five micrometers to optimize deep lung deposition via jet, ultrasonic, or mesh vibration mechanisms. The device serves primarily to deliver bronchodilators, corticosteroids, and antibiotics to patients with obstructive or infectious respiratory conditions. Mesh nebulisers, particularly vibrating mesh variants, are capturing margin pools through portable battery-powered designs that serve home care settings and ambulatory care centers. Jet nebulisers remain entrenched in hospital procurement channels where cost sensitivity and established clinical protocols limit displacement, while ultrasonic nebulisers occupy a narrowing niche in specific cystic fibrosis treatment protocols.
The FDA's 510(k) premarket notification framework governs device clearance in the United States, while the EU Medical Device Regulation (MDR) imposes stricter clinical evidence requirements and post-market surveillance obligations across European markets. Japan's PMDA maintains distinct pharmaceutical-medical device combination product rules that shape nebuliser-drug pairing strategies for manufacturers. Stakeholders must monitor evolving reimbursement classifications for home-use mesh devices as payors recalibrate coverage between durable medical equipment and disposable pharmacy benefits.
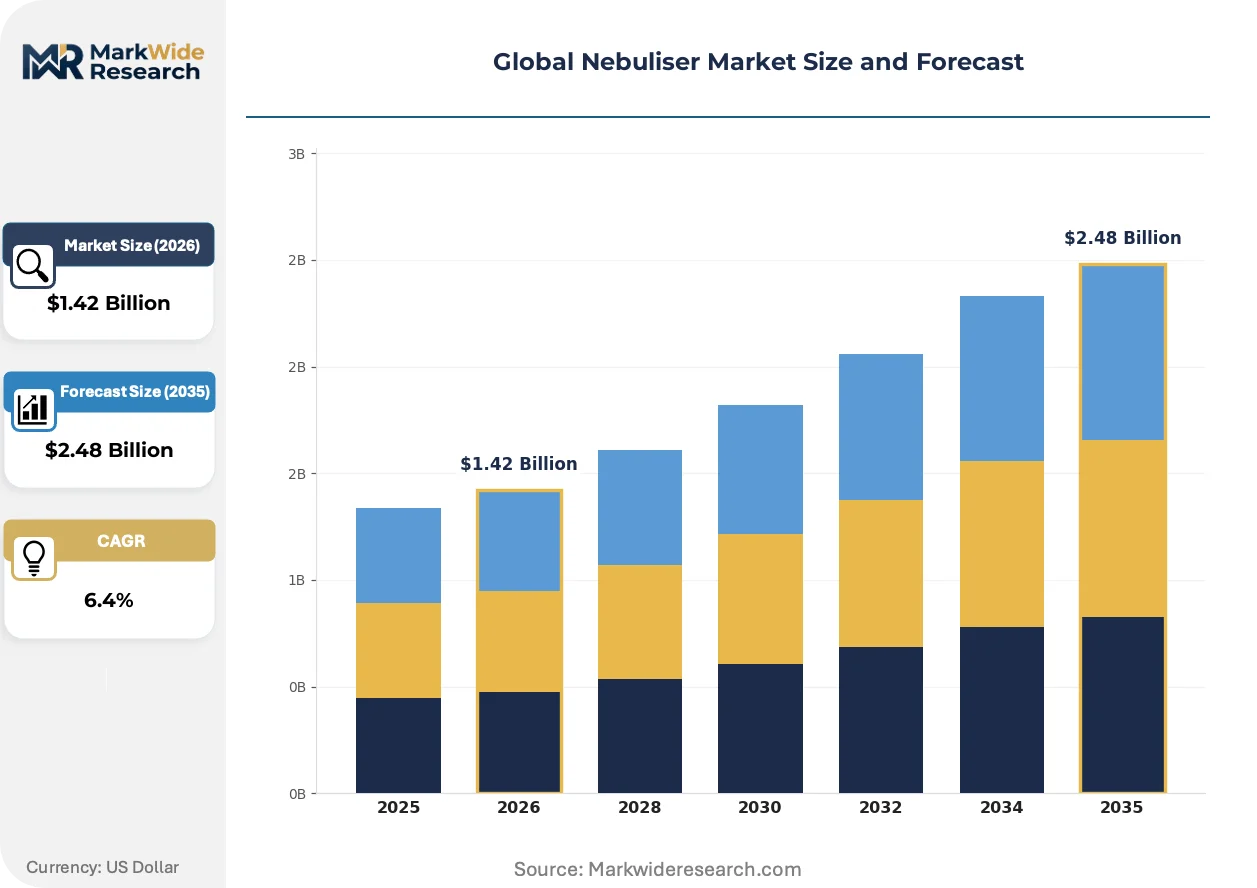
Market Dynamics
Mesh nebuliser technology is compressing hospital procurement cycles as portable battery-powered devices enable patient-managed respiratory therapy outside clinical settings. This shift fragments demand across home care, ambulatory centers, and traditional inpatient channels.
Growth Catalysts
- FDA 510(k) clearance pathway:The streamlined premarket notification framework accelerates portable mesh nebuliser introductions in the United States, reducing time-to-market for manufacturers targeting home care expansion.
- Home care settings:Patients with chronic obstructive pulmonary disease and asthma seek alternatives to hospital-based respiratory therapy, driving device adoption in domestic environments across Germany, Japan, and the United States.
- Vibrating mesh mechanisms:Battery-powered designs optimize particle size distribution for deep lung deposition, enabling effective bronchodilator delivery without compressed gas infrastructure.
Market Restraints
- Jet nebuliser cost entrenchment:Hospital procurement channels retain pneumatic devices due to established clinical protocols and lower per-unit acquisition costs, limiting mesh displacement in institutional settings.
- EU MDR clinical evidence requirements:Stricter post-market surveillance obligations and expanded clinical data mandates lengthen approval timelines and elevate compliance expenditures for European market entry.
- Ultrasonic heat generation:Thermal degradation of protein-based medications constrains ultrasonic nebuliser applicability, restricting this technology to narrow cystic fibrosis protocols.
Strategic Opportunities
- Pediatric specialization:Cystic fibrosis and asthma management in children represents underpenetrated demand, with mask interface designs and flow rate calibration creating differentiated value propositions.
- Japan PMDA combination product rules:Pharmaceutical-medical device pairing frameworks enable nebuliser-drug integrated submissions, opening reimbursement pathways for manufacturer partnerships with respiratory drug developers.
- Reimbursement recalibration:Payor reclassification of home-use mesh devices between durable medical equipment and pharmacy benefits creates channel arbitrage opportunities for direct-to-patient distribution models.
Industry Challenges
- Biocompatibility certification timelines:ISO 10993 testing for patient-contact materials extends product development cycles, particularly for novel mesh alloys and polymer formulations.
- Legacy system integration:Electronic health record connectivity and remote monitoring platform interoperability require substantial firmware development resources for hospital procurement compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Nebuliser Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Jet Nebuliser, Ultrasonic Nebuliser, Mesh Nebuliser, Vibrating Mesh Nebuliser Therapy Area: Chronic Obstructive Pulmonary Disease, Asthma, Cystic Fibrosis, Bronchiectasis, Respiratory Infections End User: Hospitals, Home Care Settings, Clinics, Ambulatory Care Centers, Rehabilitation Centers Distribution Channel: Pharmacies, Online Retailers, Medical Equipment Suppliers, Direct Hospital Procurement, Specialty Stores |
| Companies Covered | Omron Corporation, Koninklijke Philips N.V., PARI Respiratory Equipment, Inc., Drive DeVilbiss Healthcare, GE Healthcare, Aerogen, GF Health Products, Inc., Allied Healthcare Products, Inc., Vectura Group Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Nebuliser Market Shifts & Advancements
Connected respiratory ecosystems are redefining competitive boundaries as nebuliser hardware converges with digital therapeutics and remote patient monitoring platforms. This integration demands new capabilities across sensor miniaturization, cloud architecture, and clinical workflow software.
Vibrating mesh technology is overtaking pneumatic mechanisms in ambulatory care segments. These devices generate consistent one-to-five micrometer particle sizes through electroformed aperture plates, enabling efficient corticosteroid and antibiotic deposition. Home care providers and outpatient clinics in Germany and the United States are standardizing on battery-operated mesh units, compressing jet nebuliser margins in non-acute settings.
EU Medical Device Regulation enforcement is restructuring European market access protocols. Clinical evaluation reports now require systematic literature reviews and post-market clinical follow-up plans for all nebuliser classifications. Manufacturers targeting France, Germany, and Italy must rebuild technical documentation to satisfy notified body scrutiny, delaying product launches by twelve to eighteen months relative to pre-MDR timelines.
Hospital purchasing consortia are consolidating procurement authority across integrated delivery networks. Group purchasing organizations now negotiate multi-year nebuliser supply agreements covering entire health systems, displacing individual facility purchasing autonomy. This concentration is most visible in the United States, where IDN-managed spend accounts for the majority of acute care respiratory device procurement.
Global Nebuliser Market Segmentation
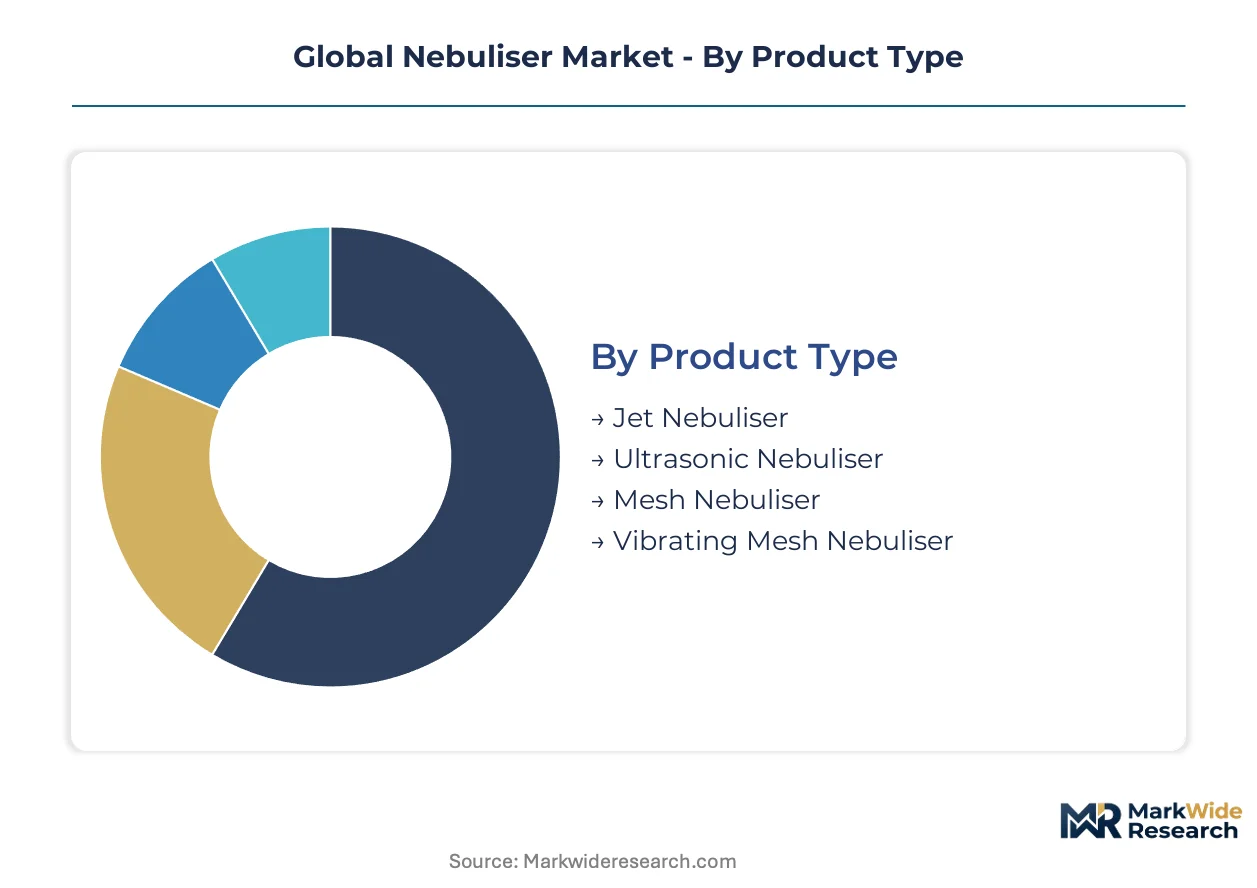
Nebuliser market segmentation reveals how technology, clinical application, and care setting intersect to shape procurement patterns. Manufacturers align R&D investments and distribution strategies against these dimensions to capture margin pools across institutional and patient-managed environments.
Product Type:
Supply concentration in vibrating mesh manufacturing is reshaping competitive positioning as electroformed aperture plate production gravitates toward precision electronics hubs in Japan and Germany.
- Vibrating Mesh Nebuliser:Electroformed aperture plates with 1-3 micrometer precision apertures generate consistent aerosol particle sizes for deep lung deposition. Demand concentrates in German home care settings where PARI Respiratory Equipment validates clinical protocols for COPD and asthma management.
- Mesh Nebuliser:Piezoelectric crystal-driven mechanisms convert liquid medication without compressed gas infrastructure. Battery-powered designs are gaining share fastest in United States ambulatory care centers seeking portable alternatives to pneumatic systems.
- Jet Nebuliser:Pneumatic compressor technology dominates hospital procurement channels through lower per-unit acquisition costs and established clinical familiarity.
- Ultrasonic Nebuliser:High-frequency piezoelectric transducers generate thermal energy that restricts application to heat-stable medications in narrow cystic fibrosis protocols.
Today's leader: Jet Nebuliser. Tomorrow's challenger: Vibrating Mesh Nebuliser.
Therapy Area:
Cost tier stratification across therapy areas mirrors reimbursement intensity, with cystic fibrosis commanding premium device specifications and COPD driving volume scale.
- Chronic Obstructive Pulmonary Disease:Progressive airway obstruction requires daily bronchodilator delivery through devices optimized for elderly patient dexterity. United States Medicare reimbursement for durable medical equipment sustains demand concentration in home care channels.
- Cystic Fibrosis:Genetic mucus clearance dysfunction demands specialized nebuliser-drug pairings with precise flow rate calibration. German clinical centers anchor validation standards for pediatric mask interfaces and antibiotic deposition efficiency.
- Asthma:Reversible airway inflammation drives seasonal demand spikes aligned with allergen exposure patterns across temperate climates.
- Bronchiectasis:Permanent bronchial dilation requires chronic airway clearance therapy with mucolytic agent compatibility.
- Respiratory Infections:Acute antibiotic and antiviral delivery concentrates in hospital settings with infection control protocols.
COPD anchors current volume. Cystic Fibrosis commands premium positioning.
End User:
Customer type fragmentation is forcing manufacturers to maintain parallel product portfolios serving divergent technical and economic specifications.
- Home Care Settings:Patient-managed therapy environments demand intuitive interfaces, battery portability, and quiet operation for domestic acceptance. Japanese regulatory frameworks for self-medication devices shape design requirements for export markets.
- Hospitals:Acute care institutions prioritize device durability, multi-patient disinfection protocols, and electronic health record connectivity for clinical workflow integration.
- Ambulatory Care Centers:Outpatient facilities balance portability with clinical-grade performance for same-day respiratory procedures.
- Clinics:Primary and specialty care offices require cost-effective solutions for episodic respiratory treatment.
- Rehabilitation Centers:Post-acute facilities focus on patient education and transition-to-home device training.
Hospitals retain procurement authority. Home Care Settings are expanding most quickly.
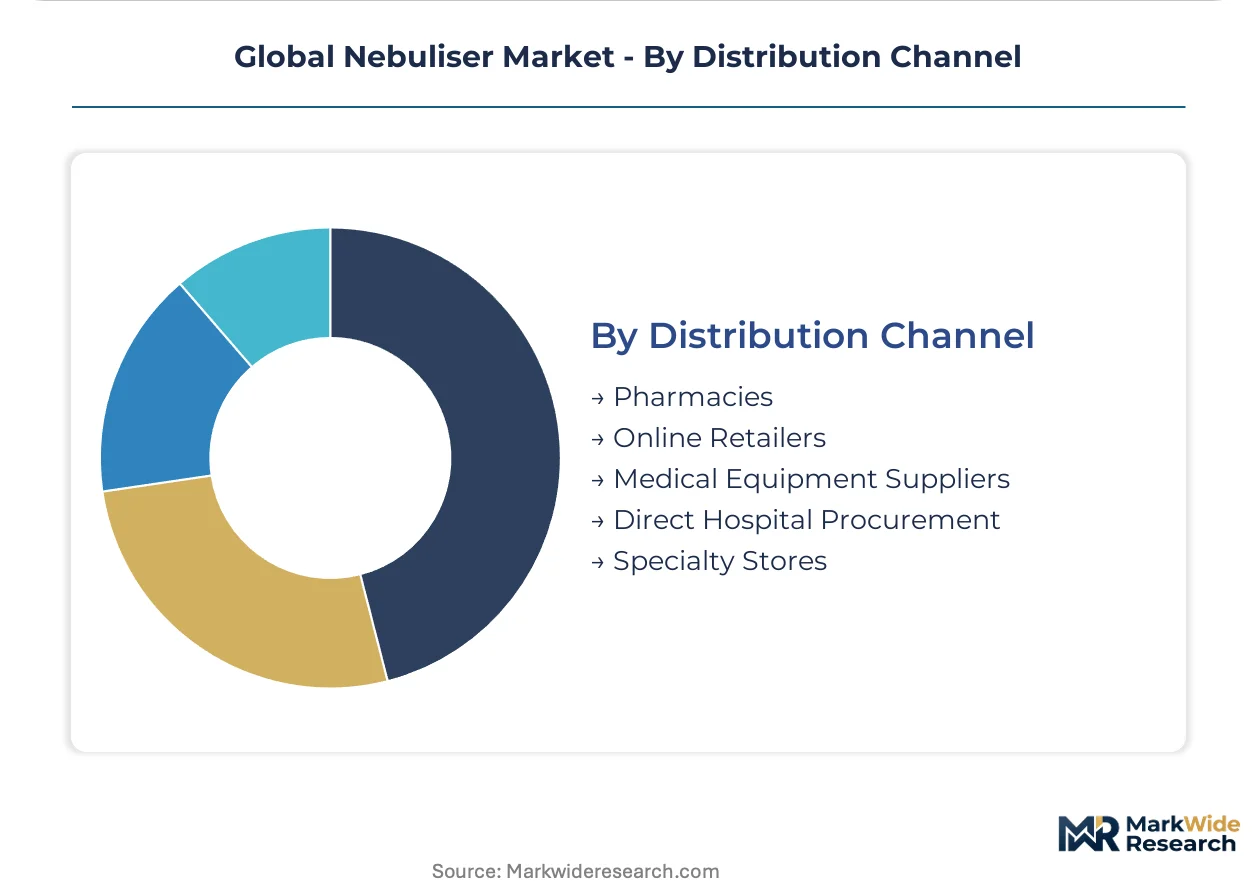
Distribution Channel:
Channel maturity varies by geography, with direct hospital procurement entrenched in Germany and online retail gaining traction in United States consumer-directed healthcare spending.
- Direct Hospital Procurement:Integrated delivery network purchasing consortia negotiate multi-year supply agreements covering entire health systems, displacing individual facility autonomy in United States acute care markets.
- Medical Equipment Suppliers:Specialized distributors provide clinical training, technical service, and regulatory documentation support for institutional customers.
- Pharmacies:Community and specialty pharmacies serve prescription-integrated nebuliser dispensing with pharmacist counseling on medication-device pairing.
- Online Retailers:E-commerce platforms enable direct-to-patient sales of portable mesh devices, challenging traditional durable medical equipment channels.
- Specialty Stores:Respiratory-focused retailers offer personalized fitting and education for complex pediatric and cystic fibrosis applications.
Direct Hospital Procurement dominates institutional volume. Online Retailers present the steepest expansion trajectory in patient-directed segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Starnberg anchors precision nebuliser manufacturing through PARI Respiratory Equipment's clinical validation laboratories and pediatric therapy development centers. Device demand concentrates in respiratory disease clusters across Germany, Japan, and the United States where aging populations and cystic fibrosis prevalence sustain procurement volumes.
United States
Medicare durable medical equipment reimbursement sustains home care channel expansion for portable mesh devices. FDA 510(k) premarket notifications govern device clearance timelines for manufacturers targeting patient-managed respiratory therapy. Minneapolis-St. Paul clusters medical device engineering talent that supports connected nebuliser platform development.
Germany
COPD prevalence among elderly populations drives institutional procurement of jet nebulisers in acute care settings. EU Medical Device Regulation clinical evidence requirements lengthen approval timelines for vibrating mesh introductions. Starnberg's concentration of respiratory therapy specialists anchors European clinical protocol standards.
Japan
Self-medication device regulations shape design requirements for export-oriented manufacturers. PMDA pharmaceutical-medical device combination product rules enable integrated nebuliser-drug submission pathways. Tokyo-Osaka industrial corridors concentrate precision electronics manufacturing for electroformed aperture plate production.
China
Domestic respiratory disease burden expands hospital procurement volumes for cost-sensitive pneumatic devices. NMPA medical device registration requirements govern import substitution strategies for local manufacturers. Shanghai-Suzhou precision manufacturing clusters support component supply for multinational assembly operations.
India
CDSCO medical device rules increasingly align with international standards for nebuliser quality certification. Asthma prevalence in urban centers drives pharmacy channel dispensing of basic jet units. Mumbai-Pune pharmaceutical corridors concentrate respiratory drug manufacturing that shapes device pairing strategies.
Global Nebuliser Market Competitive Landscape
Global majors compete with regional champions across regulatory compliance capabilities and clinical validation depth. Market structure shows moderate consolidation with tiered positioning between premium device specialists and volume-scale pneumatic manufacturers. Three archetypes dominate: precision mesh technology leaders, integrated respiratory ecosystem providers, and cost-optimized hospital suppliers. Competitive moves center on M&A for digital health platform integration and capacity expansion in Asia-Pacific assembly hubs.
Within the integrated ecosystem tier, Koninklijke Philips N.V. and Omron Corporation exemplify divergent strategic positioning. PARI Respiratory Equipment, Inc. anchors the specialized clinical validation segment. These three entities occupy distinct competitive spaces based on geographic origin, corporate structure, and archetype alignment rather than direct product confrontation.
| Leading Market Players |
|---|
| Omron Corporation |
| Koninklijke Philips N.V. |
| PARI Respiratory Equipment, Inc. |
| Drive DeVilbiss Healthcare |
| GE Healthcare |
| Aerogen |
| GF Health Products, Inc. |
| Allied Healthcare Products, Inc. |
| Vectura Group Plc |
| Others |
Supply & Pricing Matrix
Electroformed nickel price indices cascade through vibrating mesh nebuliser manufacturing, compressing margins for precision aperture plate producers while amplifying cost advantages for pneumatic jet device assemblers sourcing commodity aluminum and polymer housings.
Pricing Analysis
Input-cost pass-through from precision electronics components and medical-grade polymers stratifies pricing across certification tiers. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared vibrating mesh devices from CE-marked mid-tier units and basic pneumatic compressors. Cost compression in economy jet nebulisers is intensifying because Chinese manufacturers are expanding NMPA-registered production capacity. Hospital procurement committees exhibit lowest price sensitivity due to bundled GPO contracts, while direct-to-patient online buyers drive hardest bargain comparisons.
Supply Chain Analysis
Single-source vulnerability sits with Japanese electroformed aperture plate suppliers serving precision mesh manufacturers. Component sourcing draws from Germany for clinical validation equipment, China for pneumatic compressor assemblies, and Japan for piezoelectric crystal elements. Raw material dependencies span nickel alloys for mesh fabrication, medical-grade polycarbonates for housings, and lithium-ion cells for portable power. Tariff exposure on Chinese-manufactured compressors elevates landed costs for US hospital distributors. Distribution runs through integrated delivery network purchasing consortia in the United States and specialized respiratory equipment distributors in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory complexity into competitive moats, with EU MDR enforcement and FDA 510(k) pathways accelerating consolidation around compliant manufacturers.
For Market Incumbents: To counter margin erosion from Chinese pneumatic device exporters, Omron Corporation and Koninklijke Philips N.V. should deepen backward integration into piezoelectric crystal production and expand electroformed mesh capacity in Japan. Securing notified body pre-certification for EU MDR technical documentation rebuilds creates twelve-to-eighteen month lead times that strand non-compliant competitors.
For New Entrants and Emerging Players: The price-point gap between PARI Respiratory Equipment's premium pediatric cystic fibrosis devices and economy Chinese jet nebulisers opens white-space at mid-tier ambulatory care specifications. Target United States Medicare reimbursement-eligible portable mesh devices for COPD home therapy. Pursue partnership pathways with respiratory drug developers under Japan PMDA combination product rules to bypass standalone device reimbursement barriers.
For Investors and Strategic Acquirers: Asymmetric upside sits with precision mesh technology specialists possessing ISO 10993 biocompatibility certification and pediatric mask interface IP. Five-to-ten year viability hinges on FDA clearance velocity and EU MDR notified body relationships. Watch for inflection where home care reimbursement recalibration shifts durable medical equipment classification toward pharmacy benefit channels, collapsing traditional distributor margins and enabling direct-to-patient capture.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Streamlined premarket notifications compress time-to-market for portable mesh devices targeting US home care expansion. |
| EU MDR Technical Documentation Rebuild | Systematic literature reviews and post-market clinical follow-up plans satisfy notified body scrutiny for German market access. |
| Hospital System Partnership | Integrated delivery network supply agreements displace individual facility purchasing autonomy across United States acute care. |
| Software Companion Development | Electronic health record connectivity and remote monitoring platform interoperability satisfy procurement compliance requirements. |
| Reimbursement Strategy Reclassification | Payor recalibration of home-use mesh devices between durable medical equipment and pharmacy benefits creates channel arbitrage. |
Research Methodology
Multiple input streams — primary interviews with respiratory therapy clinicians, hospital GPO contracts managers, and biomedical engineers; secondary validation against FDA 510(k) filings, EU MDR notified body documentation, and CMS Medicare reimbursement databases; plus customs trade data for pneumatic compressor imports — were reconciled through bottom-up device shipment modeling and top-down therapy area demand estimation.
Data-stream reconciliation anchored volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, therapy area, end user, and distribution channel, with regional regulatory cluster effects layered across country-level forecasts. CAGRs were derived from therapy-area-specific prevalence trends and device replacement cycle analysis, calibrated against electroformed mesh manufacturing capacity expansion and pneumatic compressor production data.
Caveats apply where FDA guidance document revisions, EU MDR enforcement intensity variations, or Medicare reimbursement category recalibrations could materially shift the outlook. Forecasts reflect documented assumptions about regulatory pathway stability and payor classification continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Gastric Bands Market
Medical Devices
Asia-Pacific Manual Resuscitators Market
Medical Devices
Global Medical Tricorder Device Market
Medical Devices
Peripheral Interventions Market
Medical Devices
Reusable Medical Battery Market
Medical Devices
Surgical Smart Glasses Market
Medical Devices
Hysterectomy Devices Market
Medical Devices
Global Pulse Oximetry Market
Medical Devices
Blood Warmer Devices/Sample Warmer Market
Medical Devices
Blood Thawing System Market
Medical Devices
Europe Micro Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Global Artificial Tendons and Ligaments Market
Medical Devices
Mexico Aesthetic Devices Market
Medical Devices
Hearing Aids Market
Medical Devices
3D Medical Imaging Devices Market
Medical Devices
Handheld Ultrasound Devices Market